
 Vehicle Conversion Market | 2026-2036
Vehicle Conversion Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Conversion Market Analytics
Commercial fleet operators are rebalancing conversion demand away from passenger cars toward vans and light trucks as last-mile electrification accelerates. Braun Ability anchors the accessibility segment with specialized wheelchair lift manufacturing that sustains premium positioning across North American channels. Vantage Mobility International (VMI) dominates dealer network coverage for modified minivans, while Ford Motor Company leverages OEM-backed conversion certification to control fleet retrofit volume.
Vehicle conversion encompasses the modification of existing internal combustion engine platforms through powertrain replacement, structural adaptation, or accessibility retrofit to achieve altered propulsion, utility, or occupant function. Electric conversion typically involves battery pack integration rated between 40 kWh and 100 kWh, motor mount fabrication, and thermal management system recalibration to preserve chassis dynamics. Conversion type splits reveal electric conversion outpacing accessibility upgrades in absolute growth as battery cost curves improve fleet economics, while performance enhancements occupy a mature niche with concentrated margin pools in motorsport and luxury applications. End user dynamics show commercial fleet operators driving volume through centralized procurement, whereas personal users sustain higher per-unit customization spend.
Federal EPA tailpipe standards, California Air Resources Board zero-emission mandates, and NHTSA Federal Motor Vehicle Safety Standards collectively shape conversion eligibility, certification pathways, and interstate commerce legibility for modified vehicles. The EU Green Deal and REACH chemical compliance protocols add material sourcing constraints for battery system integrators serving European markets. Stakeholders must monitor evolving crash-test equivalency rulings and battery recycling mandates as these frameworks determine which conversion architectures qualify for fleet incentives and resale channel access.
Market Dynamics
Commercial fleet operators are consolidating conversion procurement around centralized powertrain swap programs as California Air Resources Board zero-emission mandates compress diesel vehicle operating windows. This structural pressure is reallocating capital from incremental retrofits toward full platform electrification.
Growth Catalysts
- EPA tailpipe standards:Federal emission ceilings are eliminating older diesel chassis from interstate commerce, forcing fleet operators toward certified conversion architectures that preserve vehicle registration eligibility.
- Last-mile delivery electrification:E-commerce logistics networks are standardizing electric van specifications across depots, creating volume demand for modular battery pack integration between 40 kWh and 100 kWh.
- Battery cost curves:Lithium-ion cell pricing compression is narrowing total cost of ownership gaps against internal combustion platforms, accelerating payback calculations for commercial operators.
Market Restraints
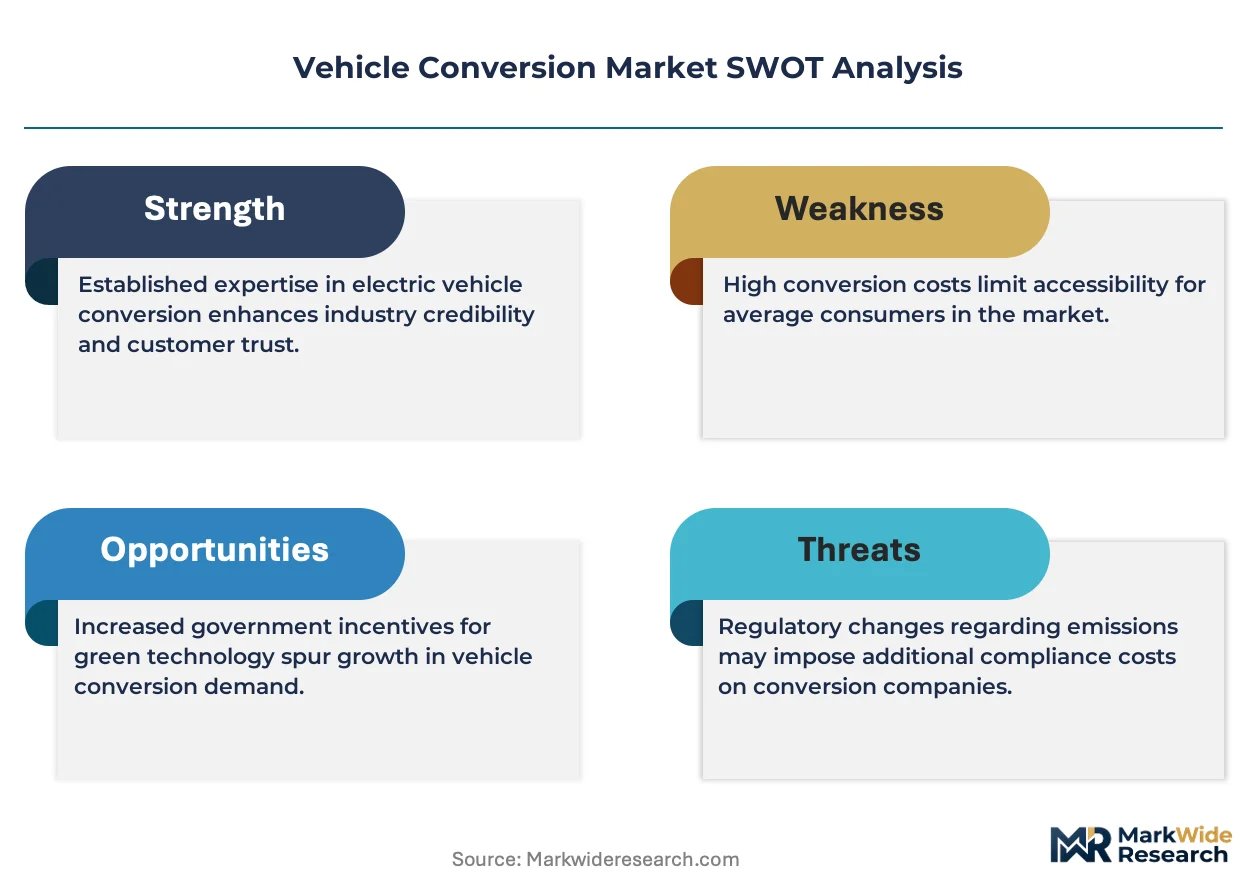
- Crash-test equivalency uncertainty:NHTSA Federal Motor Vehicle Safety Standards lack clear retrofit certification pathways, creating resale risk for converted vehicles and freezing secondary market liquidity.
- Cell supply concentration:Cathode active material refining clusters in China are exposing conversion integrators to input cost volatility and geopolitical supply disruption.
- Thermal management complexity:Battery thermal runaway containment requirements are adding engineering overhead that slows conversion throughput and extends workshop occupancy.
Strategic Opportunities
- EU Green Deal battery passports:European material traceability mandates are creating first-mover advantage for conversion shops with verified recycled-content supply chains.
- Light truck electrification:Medium-duty pickup platforms remain underpenetrated relative to vans, offering margin expansion for integrators mastering higher-torque motor mounting.
- Direct fleet contracting:Bypassing dealer networks through OEM-backed conversion certification is compressing channel costs and capturing lifetime service revenue.
Industry Challenges
- High-voltage technician scarcity:Certified electric vehicle conversion specialists command wage premiums that erode workshop economics outside major metropolitan clusters.
- Interstate commerce legibility:Inconsistent state-level registration treatment of modified vehicles creates compliance fragmentation for national fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Conversion Market |
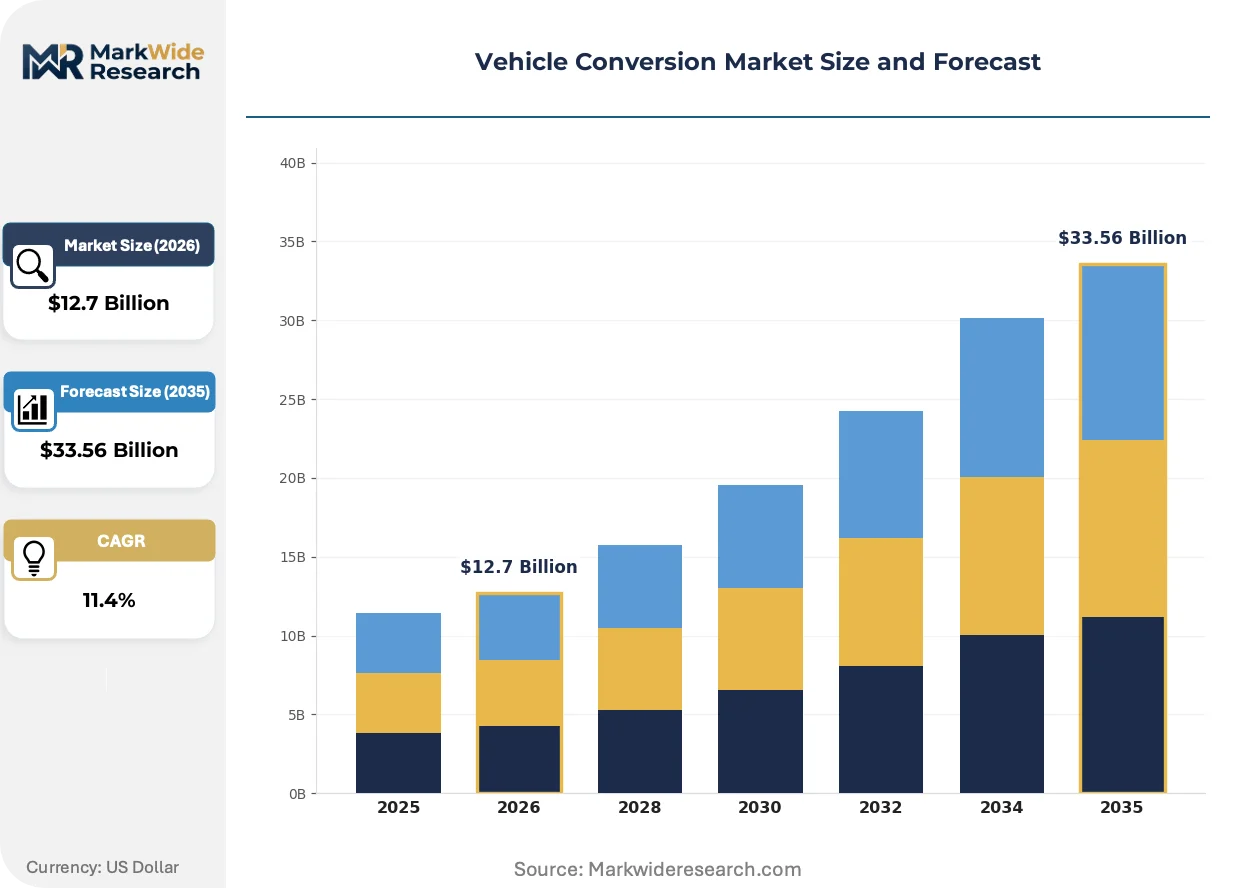
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $33.56 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Trucks, Vans, Buses Conversion Type: Electric Conversion, Accessibility Upgrades, Performance Enhancements, Fuel Efficiency Modifications End User: Personal Users, Commercial Fleet Operators, Government Agencies, Nonprofit Organizations Technology: Hybrid Systems, Battery Systems, Alternative Fuels, Custom Modifications |
| Companies Covered | VAN Adventure Van Custom Conversions, Green Shed Conversions, Braun Ability, Ford Motor Company, DIYEV, Vantage Mobility International (VMI), Becker Automotive Design, General Motors, Autogroup International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Conversion Market Evolving Landscape
Modular battery architecture is displacing custom fabrication as the dominant conversion methodology, compressing project timelines from months to weeks. This standardization is enabling new service models that separate hardware procurement from installation labor.
Swappable battery pack designs are converging with fleet telematics platforms to enable state-of-health monitoring and predictive degradation management. Logistics operators are adopting these integrated systems to optimize charging scheduling across multi-depot networks. The structural consequence is that conversion value is migrating from hardware margin toward software-enabled energy management services.
California Air Resources Board zero-emission mandates are tightening diesel vehicle phase-out timelines and accelerating powertrain swap demand among Class 3-5 commercial operators. Fleets are responding by pre-positioning conversion capacity ahead of 2027 model-year restrictions. The segment most affected is urban last-mile delivery, where operators are consolidating vehicle specifications to simplify maintenance training.
Centralized procurement by national fleet operators is displacing fragmented owner-operator decision-making and compressing conversion supplier margins. Large buyers are unbundling battery supply from installation service, pressuring integrators toward pure-play assembly models. This concentration is most visible in the United States, where top-ten logistics accounts now represent the majority of electric conversion volume.
Vehicle Conversion Market Segmentation
Vehicle conversion markets fragment sharply across buyer priorities—fleet operators chase total cost of ownership, personal users demand customization depth, and regulators impose divergent certification burdens. Understanding these fault lines clarifies where margin pools concentrate and which technology bets align with procurement trajectories.
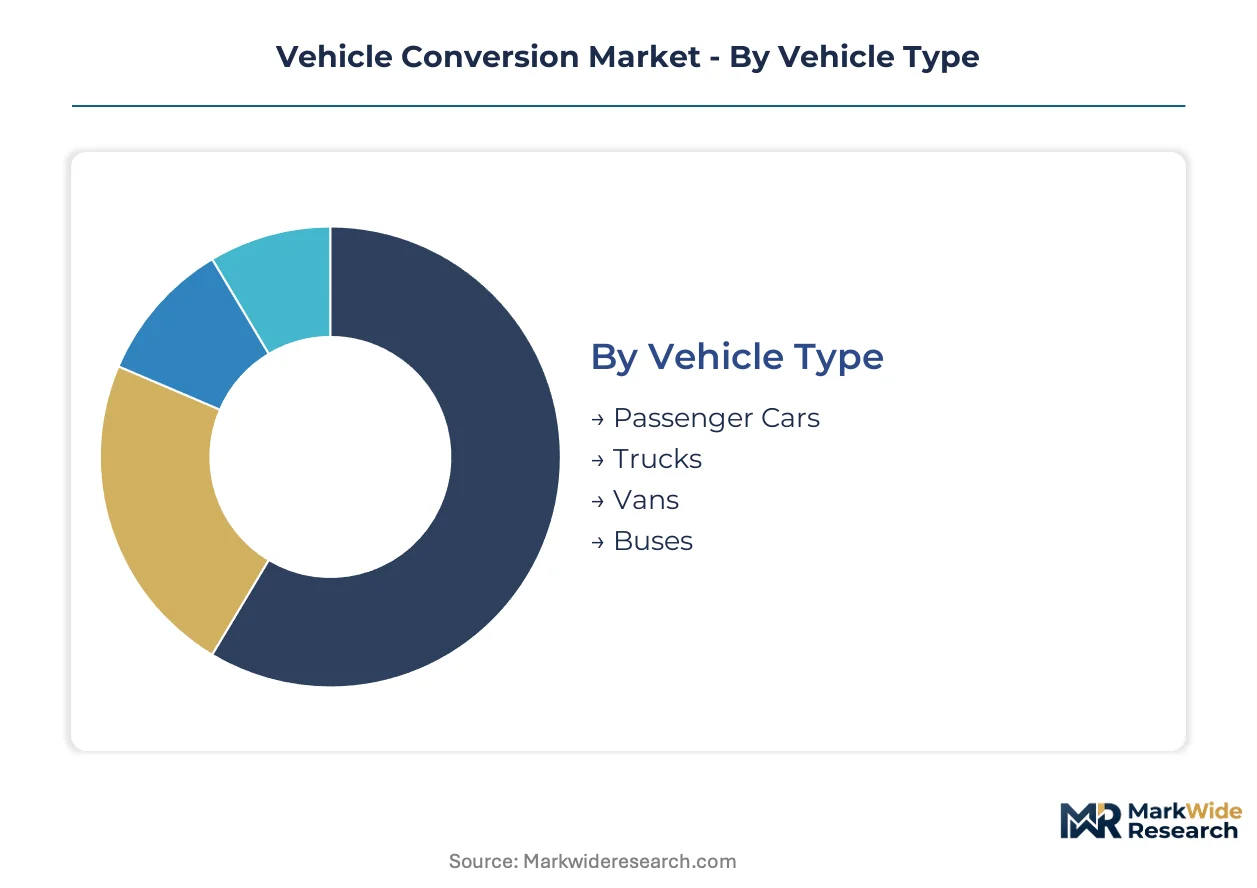
Vehicle Type:
Commercial operators and private owners diverge fundamentally on payload requirements, duty cycles, and regulatory exposure.
- Passenger Cars:Electric powertrain swaps dominate this segment, typically involving 40-80 kWh battery architectures and motor mount fabrication for compact chassis. Demand clusters among individual owners in Germany and California seeking to preserve vintage vehicle registration while meeting local zero-emission mandates.
- Vans:Last-mile delivery fleets drive volume here, with standardized 60-100 kWh modular packs enabling depot-charging optimization across multi-vehicle operations. United States logistics networks are consolidating procurement around single specifications to simplify maintenance training.
- Trucks:Medium-duty platforms remain underpenetrated relative to vans, with higher-torque motor mounting requirements slowing conversion throughput.
- Buses:Transit agency retrofits emphasize passenger capacity preservation and thermal management for high-cycle operations.
Volume sits with vans; growth tilts toward trucks as torque-optimized motor designs mature.
Conversion Type:
Margin profiles diverge based on engineering complexity, certification pathway clarity, and aftermarket service attach rates.
- Electric Conversion:Full powertrain replacement integrates battery packs, electric motors, and thermal management systems calibrated to preserve chassis dynamics. Fleet operators in the United States and China are accelerating procurement as battery cost curves compress payback periods against diesel platforms.
- Accessibility Upgrades:Wheelchair lift installation, ramp modification, and interior reconfiguration serve mobility-impaired users through specialized manufacturing. North American demand concentrates around OEM-certified dealer networks serving Medicaid-funded vehicle programs.
- Performance Enhancements:Engine tuning, suspension modification, and drivetrain upgrades occupy a mature niche with concentrated margin pools in motorsport and luxury applications.
- Fuel Efficiency Modifications:Aerodynamic retrofit and engine management recalibration deliver marginal gains for owner-operators seeking operating cost relief.
Revenue concentrates in electric conversion; accessibility upgrades retain the most stable pricing power.
End User:
Procurement scale and decision velocity separate institutional buyers from fragmented personal demand.
- Commercial Fleet Operators:Centralized procurement across national logistics networks enables volume pricing and standardized specifications. These buyers are unbundling battery supply from installation service, pressuring integrators toward pure-play assembly models.
- Personal Users:Hobbyist and commuter conversions sustain higher per-unit customization spend but demand extended consultation cycles and bespoke engineering.
- Government Agencies:Transit authorities and municipal fleets drive bus electrification through RFP-based contracting with crash-test equivalency requirements.
- Nonprofit Organizations:Disability service providers anchor accessibility upgrade demand through grant-funded vehicle modification programs.
Procurement volume flows through fleet operators; customization value per unit peaks with personal users.
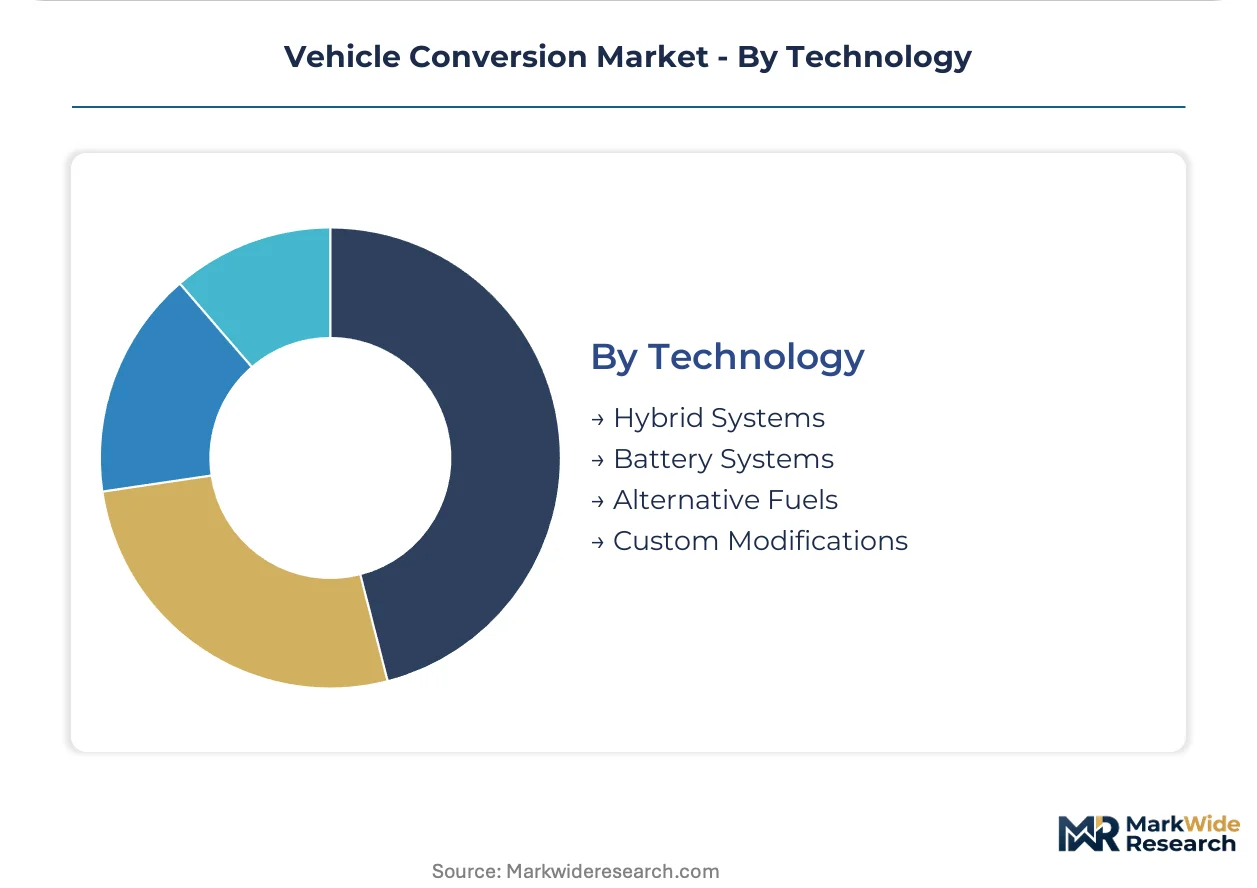
Technology:
System architecture choices determine supply chain exposure, technician certification requirements, and regulatory compliance burden.
- Battery Systems:Lithium-ion pack integration rated 40-100 kWh dominates electric conversion, with cell supply concentration in China creating input cost volatility for integrators. NHTSA Federal Motor Vehicle Safety Standards and EU battery passport mandates are reshaping sourcing requirements.
- Hybrid Systems:Parallel and series hybrid architectures preserve range flexibility for operators in regions with charging infrastructure gaps.
- Alternative Fuels:Compressed natural gas and hydrogen retrofit serve niche applications with established fueling infrastructure.
- Custom Modifications:Bespoke fabrication addresses specialized accessibility and performance requirements outside standardized product lines.
Investment intensity clusters around battery systems; hybrid architectures gain share fastest in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Advanced Clean Trucks regulation and Germany's KBA certification pathways have concentrated vehicle conversion investment in jurisdictions with clear retrofit-to-electric pathways. These incentive zones attract battery system integrators seeking regulatory certainty for fleet electrification programs.
United States
Commercial fleet operators dominate procurement through centralized powertrain swap programs. EPA tailpipe standards and California Air Resources Board zero-emission mandates compress diesel operating windows. Detroit and Los Angeles anchor conversion workshop clusters serving last-mile delivery networks.
Germany
Individual owners preserve vintage passenger car registration through compact chassis electrification. KBA type-approval requirements and EU Green Deal battery passport mandates shape certification pathways. Stuttgart and Munich concentrate engineering talent for thermal management system recalibration.
China
Cathode active material refining clusters expose conversion integrators to input cost volatility. MIIT vehicle modification regulations and dual carbon goals accelerate commercial fleet electrification. Shenzhen and Shanghai host battery pack integration facilities serving domestic logistics operators.
United Kingdom
Accessibility upgrade demand concentrates through OEM-certified dealer networks serving grant-funded vehicle programs. DVSA Individual Vehicle Approval requirements govern structural modifications. Birmingham and Manchester sustain specialized manufacturing for wheelchair lift installations.
Japan
Hybrid architectures gain share in regions with charging infrastructure gaps. METI energy transition policies support alternative fuel retrofits for established fueling networks. Nagoya and Osaka house fabrication shops mastering motor mount adaptation for compact commercial platforms.
Vehicle Conversion Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fleet procurement favoring scale-capable integrators while personal users sustain boutique fabrication shops. The vendor base concentrates around three strategic archetypes: OEM-backed certification programs, accessibility-focused specialists, and electric powertrain pure-plays. M&A activity targets battery system integrators with verified supply chains, while strategic partnerships between cell suppliers and installation networks reshape channel economics.
Among North American accessibility specialists, Braun Ability and Vantage Mobility International (VMI) exemplify dealer network coverage models for modified minivan distribution. Ford Motor Company occupies a position representing OEM-backed conversion certification for fleet retrofit volume. These three anchors illustrate how regulatory compliance capabilities and certification pathway access determine competitive positioning across distinct procurement channels.
| Leading Market Players |
|---|
| VAN Adventure Van Custom Conversions |
| Green Shed Conversions |
| Braun Ability |
| Ford Motor Company |
| DIYEV |
| Vantage Mobility International (VMI) |
| Becker Automotive Design |
| General Motors |
| Autogroup International |
| Others |
Value Network & Pricing Analysis
Modular battery architecture standardization is compressing project timelines from months to weeks while simultaneously redrawing cost economics and concentrating procurement power among fleet operators with volume scale. This production-method transition enables unbundling of hardware supply from installation labor, reshaping margin distribution across the value chain.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory commands discounts. Project-based pricing dominates, with differentiation hinging on NHTSA certification tier and customization depth. Cost compression in standardized van conversions is intensifying because national fleet operators are consolidating procurement around single specifications. Commercial fleet operators exhibit highest price sensitivity; personal users seeking vintage passenger car preservation show lowest.
Supply Chain Analysis
Single-source vulnerability sits with cathode active material refining clusters in China. Battery cell production draws from China, South Korea, and Japan, with lithium carbonate, nickel sulfate, and cobalt hydroxide anchoring input dependencies. Geopolitical supply disruption poses structural risk. Distribution runs through OEM-certified dealer networks and direct fleet contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vehicle conversion is consolidating around scale-capable integrators as centralized fleet procurement eliminates fragmented owner-operator demand. California Air Resources Board zero-emission mandates are accelerating this consolidation by compressing diesel operating windows for weaker players.
For Market Incumbents: Cement certification pathway dominance by deepening NHTSA Federal Motor Vehicle Safety Standards compliance investment ahead of evolving crash-test equivalency rulings. Secure backward integration into battery pack assembly to defend margin position against unbundling pressure from fleet procurement teams.
For New Entrants and Emerging Players: Capture white-space opportunity in medium-duty truck electrification, where torque-optimized motor mounting requirements have slowed incumbent throughput. Target municipal transit agencies through RFP-based contracting with government-grade crash-test documentation.
For Investors and Strategic Acquirers: Exit pathways concentrate in battery system integrators with verified recycled-content supply chains positioned for EU Green Deal battery passport compliance. Five-to-ten-year viability favors shops with OEM-backed conversion certification. Watch NHTSA retrofit certification pathway clarity as the decisive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Adoption | Compresses conversion timelines and enables unbundled service models for fleet operators. |
| OEM-Backed Certification Investment | Ford Motor Company leverages factory authorization to control fleet retrofit volume. |
| Verified Recycled-Content Supply Chain | Positions integrators for EU battery passport mandates and first-mover advantage. |
| Direct Fleet Contracting Bypass | Eliminates dealer network costs and captures lifetime service revenue streams. |
| Thermal Management System Recalibration | Stuttgart and Munich engineering talent preserves chassis dynamics for German vintage conversions. |
Research Methodology
Document review covered SEC filings from automotive OEMs and conversion specialists, EPA regulatory dockets, and NHTSA safety standard updates, complemented by interviews with fleet procurement directors, conversion workshop owners, battery system integrators, and thermal management engineers. Secondary validation drew from California Air Resources Board mandate documentation, EU Green Deal implementation guidance, and IHS Markit vehicle registration databases. Bottom-up project pipeline assessment triangulated against top-down market sizing.
Market value and volume outputs across the projection horizon reflect segmentation by vehicle type, conversion category, end-user archetype, and battery system architecture. CAGRs were derived from regression analysis against battery cost curve trajectories and regulatory mandate phase-in schedules. Forecast inputs incorporated fleet operator payback period calculations and state-level zero-emission compliance timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NHTSA crash-test equivalency rulings, cathode material supply disruption, and interstate commerce registration fragmentation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
United States Automotive Dealership Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Car Wash Services Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Car Wash System Market
Automotive Services
US Car Wash Services Market
Automotive Services
Europe Car Wash Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Brushless Car Wash Machine Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Car Vending Machine Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Global Car Wash Market
Automotive Services
North America Car Wash Market