
 United States White Glove Delivery Service Market | 2026-2036
United States White Glove Delivery Service Market Size, Share, and Industry Trends Forecast 2026-2036
United States White Glove Delivery Service Market Insights
California's Advanced Clean Trucks regulation is shifting fleet investment toward electric and low-emission vehicles across white glove operations. XPO leverages its dedicated last-mile infrastructure to sustain service density in major metropolitan corridors. FedEx Corporation anchors its white glove portfolio through specialized handling networks for high-value goods. SEKO Logistics differentiates via technology leadership in real-time shipment visibility and appointment scheduling.
White glove delivery service encompasses premium logistics solutions involving inside placement, unpacking, assembly, debris removal, and room-of-choice positioning, typically requiring two-person crews and appointment-based scheduling with narrow delivery windows. The service targets bulky, fragile, or high-value items where standard curbside delivery fails to meet customer expectations. Residential delivery occupies the largest volume pool, though assembly service captures disproportionate margin due to labor specialization and extended customer touchpoints. E-commerce retailers dominate end-user demand, while third-party logistics providers compete against in-house delivery arms for enterprise contracts. Subscription-based pricing models are gaining traction among furniture retailers seeking predictable fulfillment costs.
The Department of Transportation's hours-of-service rules and the Federal Motor Carrier Safety Administration's compliance standards shape crew scheduling, driver availability, and operational cost structures. OSHA workplace safety requirements influence two-person team protocols and equipment handling procedures during in-home deliveries. Stakeholders must monitor evolving emissions mandates and labor classification rulings that could restructure contractor-employee ratios across the industry.
Market Dynamics
California's Advanced Clean Trucks regulation is compressing fleet replacement cycles and forcing capital reallocation toward electric powertrains across white glove operations nationwide.
Growth Catalysts
- Medical Equipment Logistics:Hospital networks and home healthcare providers now mandate inside delivery with assembly for imaging equipment and patient beds.
- EPA Phase 2 Standards:Greenhouse gas rules for medium- and heavy-duty vehicles are accelerating fleet modernization investments.
- Urban Corridor Density:Last-mile complexity in California's metropolitan clusters is generating premium service premiums.
Market Restraints
- Two-Person Crew Economics:Labor costs for specialized handling teams exceed standard delivery models by significant multiples.
- Appointment Window Compression:Narrow delivery windows reduce route density and increase per-stop fulfillment costs.
- OSHA Compliance Burden:Workplace safety requirements for in-home deliveries add procedural overhead and training cycles.
Strategic Opportunities
- Subscription Pricing Models:Furniture retailers seek predictable fulfillment costs through flat-rate service agreements.
- Assembly Service Expansion:Extended customer touchpoints in product installation capture disproportionate margin pools.
- Real-Time Visibility Platforms:Appointment scheduling and shipment tracking technologies differentiate carrier offerings.
Industry Challenges
- Driver Classification Rulings:Evolving contractor-employee ratios threaten operating model structures.
- Hours-of-Service Constraints:DOT rules limit crew scheduling flexibility and compress available delivery windows.
- Emissions Mandate Timing:Multi-state regulatory divergence complicates national fleet standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States White Glove Delivery Service Market |
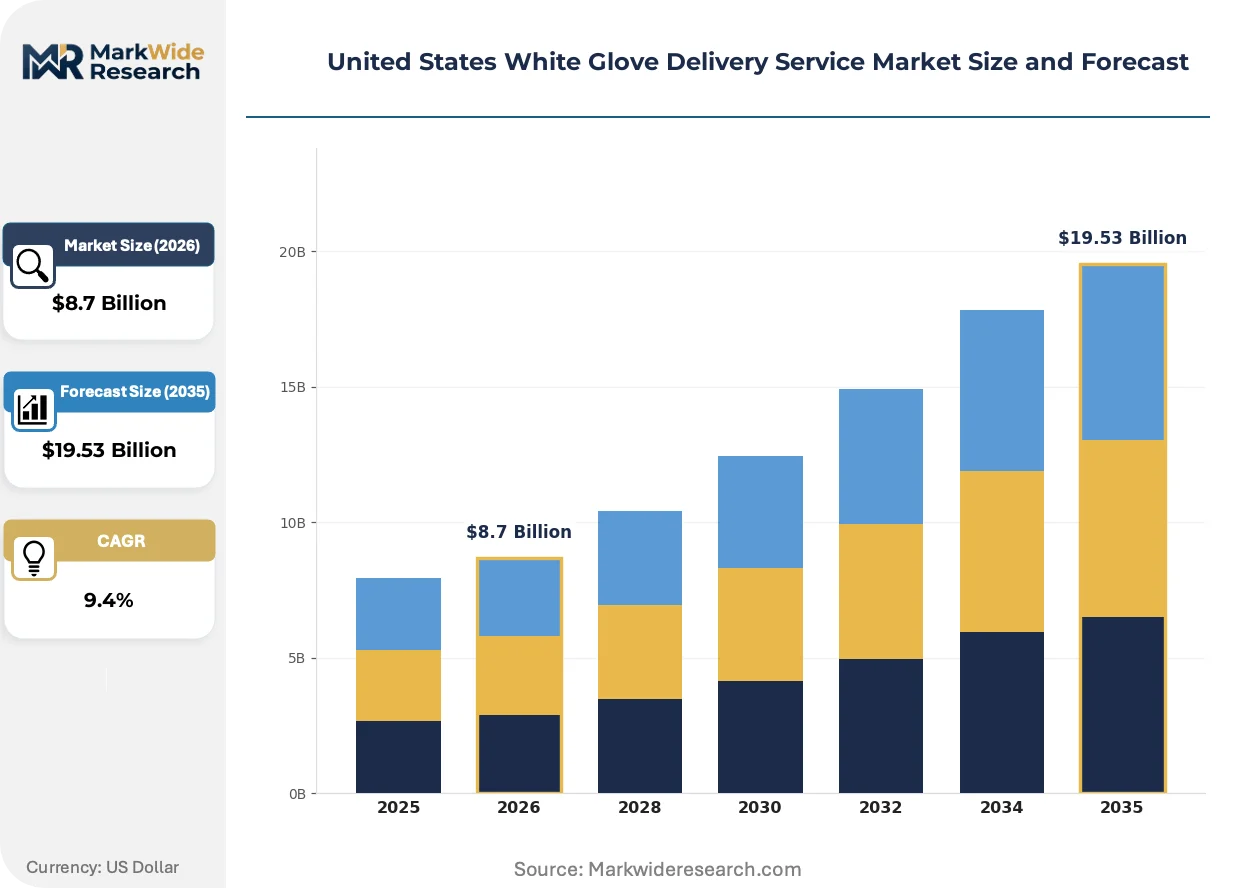
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Delivery, Commercial Delivery, Assembly Service, Specialized Handling End User: E-commerce Retailers, Furniture Stores, Electronics Retailers, Healthcare Providers Delivery Mode: In-House, Third-Party Logistics, Scheduled Delivery, Same-Day Delivery Pricing Model: Flat Rate, Per Item, Subscription-Based, Tiered Pricing |
| Companies Covered | XPO, SEKO Logistics, United Parcel Service (UPS), Ryder, J.B. Hunt Transport, Werner Enterprise, Fidelitone Last Mile Inc, FedEx Corporation, Hub Group, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States White Glove Delivery Service Market Trends and Innovations
Electric vehicle adoption is restructuring fleet economics while regulatory pressure intensifies and buyer expectations for premium service harden.
Medium-duty electric step vans with extended range batteries are electrifying last-mile operations in California's dense urban corridors. Furniture retailers and appliance distributors are piloting these platforms in Los Angeles and San Francisco metropolitan zones. The technology is electrifying total cost of ownership calculations and compressing diesel fleet replacement timelines.
California's Advanced Clean Trucks regulation mandates escalating zero-emission vehicle sales percentages through 2035. Fleet operators must now integrate electric vehicle procurement into capital planning or face market access restrictions. The rule most affects multi-state carriers serving California's white glove corridors, forcing compliance investments that ripple through national network designs.
Room-of-choice positioning with debris removal is displacing threshold delivery as the baseline expectation among e-commerce furniture buyers. Retailers are unbundling premium service tiers and charging explicit fees for assembly and packaging removal. This behavioral shift concentrates in California and New York metropolitan markets where consumer willingness to pay for white glove treatment exceeds national averages.
United States White Glove Delivery Service Market Segmentation
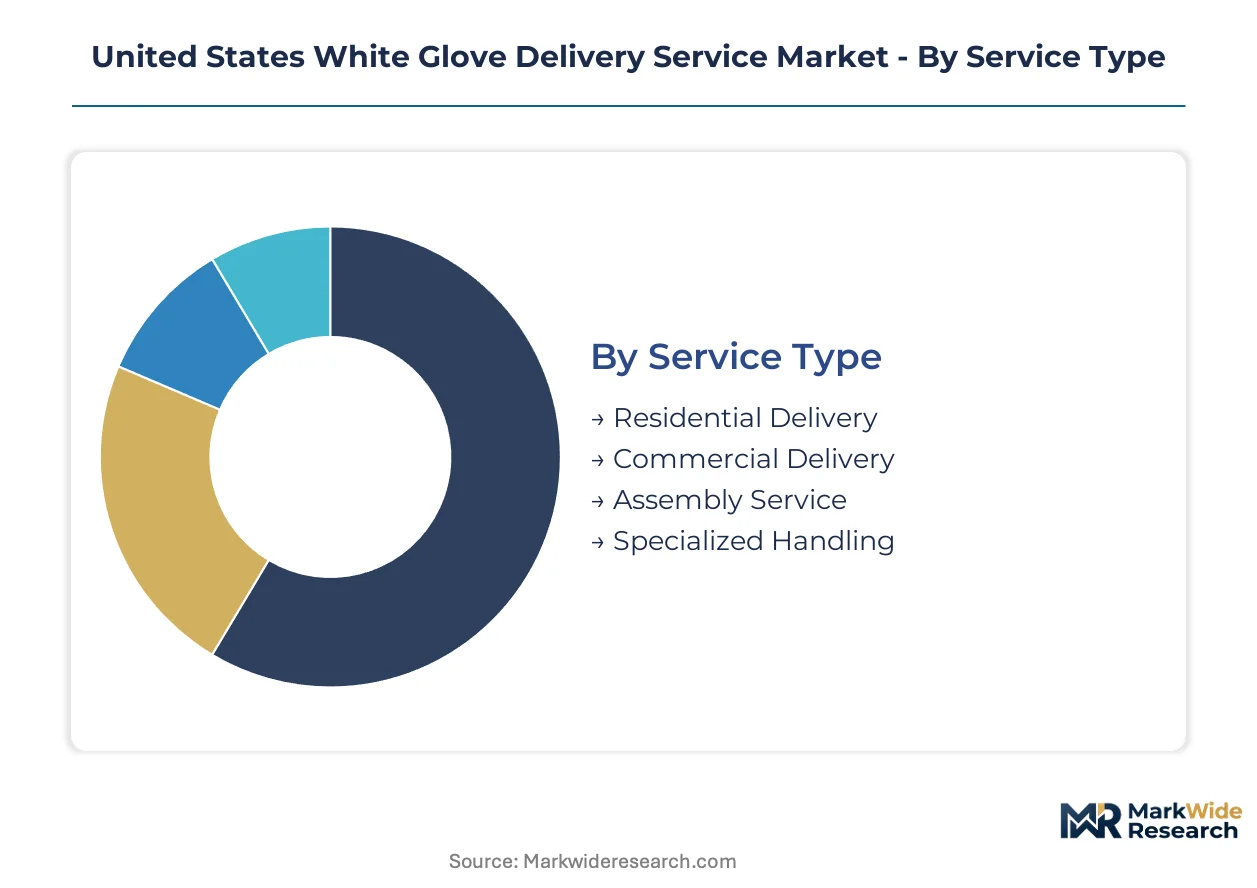
White glove delivery service segmentation reveals how operational complexity and customer willingness to pay fragment the market into distinct service tiers. Each dimension—service type, end user, delivery mode, and pricing model—creates strategic positioning opportunities that separate premium providers from commoditized competitors.
Service Type:
Standalone white glove services operate as discrete purchase options, while embedded variants bundle into larger product transactions.
- Residential Delivery:Inside placement and room-of-choice positioning for bulky home goods. Demand concentrates in California's dense urban corridors where apartment buildings and narrow street access complicate standard freight operations. The EPA's Phase 2 greenhouse gas standards are accelerating electric fleet investments for these high-frequency routes.
- Assembly Service:Product installation requiring specialized labor and extended customer touchpoints. Furniture retailers in Los Angeles and San Francisco metropolitan zones capture disproportionate margins through this add-on. OSHA workplace safety requirements shape two-person crew protocols and equipment handling procedures during in-home installations.
- Commercial Delivery:White glove handling for business locations including offices and retail showrooms.
- Specialized Handling:Climate-controlled transport and custom crating for fragile or high-value items.
Residential delivery leads volumes today; assembly service is gaining share fastest.
End User:
Cost tier separation distinguishes mass-market retailers from premium channel partners with distinct service expectations.
- E-commerce Retailers:Online-first merchants driving volume through subscription-based fulfillment agreements. National furniture platforms mandate white glove as standard for competitive parity. The Department of Transportation's hours-of-service rules constrain crew scheduling flexibility across their distributed warehouse networks.
- Healthcare Providers:Hospital networks and home healthcare operators requiring inside delivery with assembly for imaging equipment and patient beds. California's Advanced Clean Trucks regulation forces fleet modernization for carriers serving medical corridors. Demand is climbing fastest among home healthcare providers expanding remote patient monitoring infrastructure.
- Furniture Stores:Traditional brick-and-mortar retailers leveraging white glove as differentiation against online competitors.
- Electronics Retailers:High-value consumer technology merchants requiring anti-static handling and installation support.
E-commerce retailers anchor volume concentration; healthcare providers show steepest expansion trajectory.
Delivery Mode:
Volume concentration separates high-frequency scheduled operations from premium same-day positioning.
- Third-Party Logistics:Specialized carriers providing outsourced white glove capacity to enterprise clients. XPO and FedEx Corporation anchor this segment through dedicated last-mile infrastructure. The Federal Motor Carrier Safety Administration's compliance standards shape driver availability and operational cost structures across multi-state networks.
- In-House:Retailers maintaining captive delivery fleets for brand control and customer data capture. Major furniture chains in California's metropolitan clusters invest here to differentiate service quality. Capital intensity limits expansion to largest volume operators with density economics.
- Scheduled Delivery:Appointment-based routing with narrow delivery windows reducing per-stop efficiency.
- Same-Day Delivery:Expedited white glove service commanding premium pricing for urgent fulfillment needs.
Third-party logistics dominates transaction volume; in-house operations are expanding most quickly among top-tier retailers.
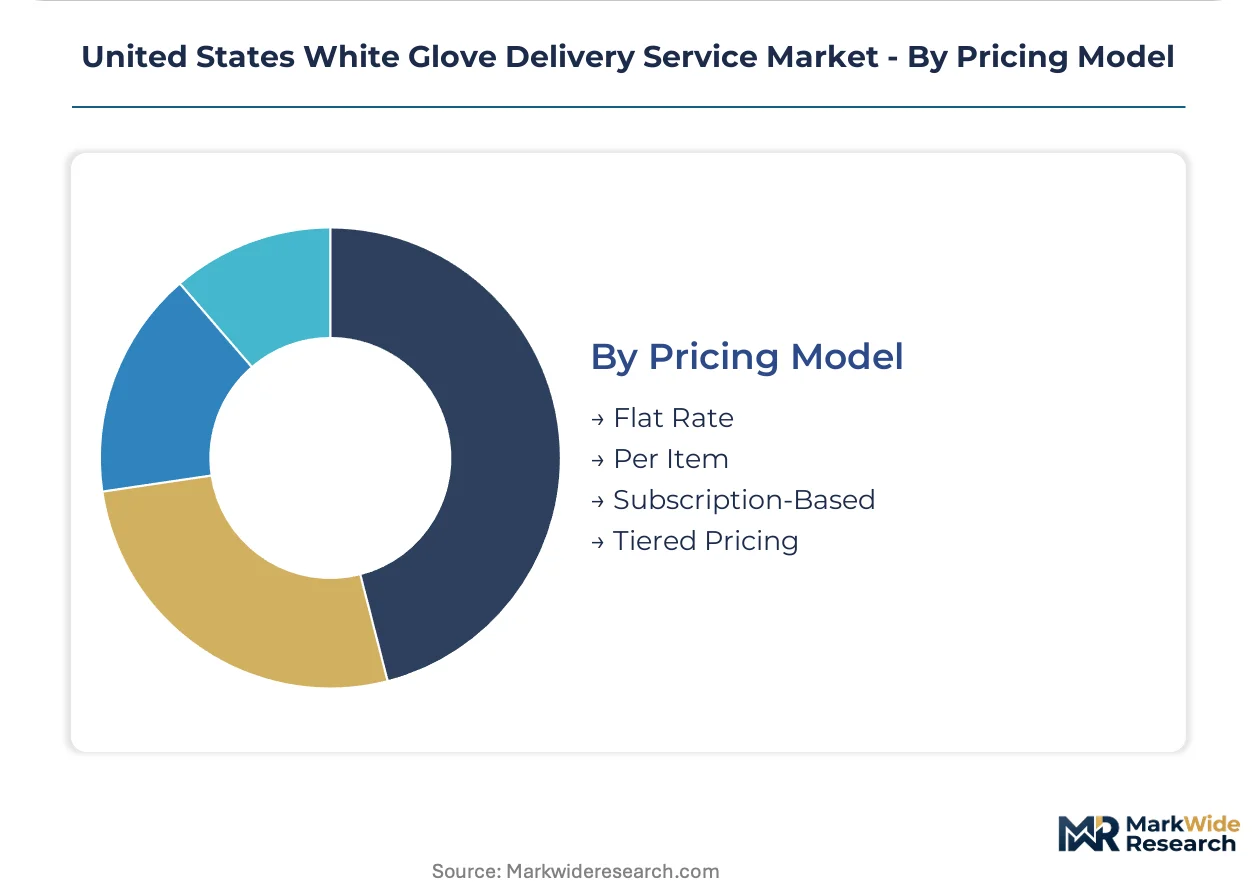
Pricing Model:
Customer type segmentation separates predictable subscription relationships from transactional spot purchasing.
- Subscription-Based:Flat-rate service agreements furnishing predictable fulfillment costs for high-volume furniture retailers. SEKO Logistics differentiates here through technology leadership in real-time shipment visibility. California-based merchants pilot these structures to stabilize seasonal demand fluctuations.
- Tiered Pricing:Explicit unbundling of premium service levels including assembly and debris removal. E-commerce furniture buyers in New York and California metropolitan markets show willingness to pay for graduated service tiers. This model is displacing threshold delivery as baseline expectation.
- Flat Rate:Simplified per-delivery pricing for standardized service configurations.
- Per Item:Variable pricing scaled to product dimensions, weight, and handling complexity.
Subscription-based models lead enterprise adoption; tiered pricing is climbing fastest among direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled two-person delivery crews concentrate in California's dense metropolitan corridors, where last-mile complexity and consumer willingness to pay for premium service converge. The EPA's Phase 2 greenhouse gas standards and state-level emissions mandates are reshaping fleet procurement decisions across major logistics hubs.
California
Los Angeles and San Francisco metropolitan zones anchor white glove volume concentration, driven by e-commerce furniture retailers and home healthcare providers requiring inside delivery with assembly. The California Air Resources Board's Advanced Clean Trucks regulation mandates escalating zero-emission vehicle sales percentages through 2035. Fleet operators serving these urban corridors must now integrate electric powertrains into capital planning or face market access restrictions.
Texas
Dallas-Fort Worth and Houston logistics clusters support medical equipment distribution networks requiring specialized handling for imaging systems and patient beds. The Texas Commission on Environmental Quality oversees regional air quality initiatives affecting fleet composition decisions. Major third-party logistics providers maintain dedicated last-mile infrastructure in these metropolitan areas to serve hospital networks expanding remote patient monitoring.
New York Metro
The five-borough region and surrounding counties generate premium service demand from apartment dwellers lacking freight elevator access. New York State's Department of Environmental Conservation administers vehicle emissions programs influencing medium-duty fleet procurement. Last-mile carriers navigate narrow street access and parking constraints while meeting appointment-based scheduling requirements for room-of-choice positioning.
Illinois
Chicago's central location supports distribution hub operations feeding Midwest white glove corridors with medical and furniture freight. The Illinois Environmental Protection Agency implements diesel emissions reduction programs affecting regional carrier fleets. Two-person crew operations concentrate in the metropolitan area to address high-rise residential delivery complexity and commercial installation requirements.
Florida
Miami and Tampa metropolitan areas serve retirement community demand for patient bed delivery and home healthcare equipment installation. The Florida Department of Environmental Protection oversees transportation emissions standards shaping fleet modernization timelines. Carriers serving these markets balance seasonal volume fluctuations with year-round medical logistics contracts requiring specialized handling protocols.
United States White Glove Delivery Service Market Competitive Landscape
Capital-heavy fleet operators compete with asset-light technology platforms for control of customer relationships and delivery density. The market structure separates integrated logistics networks owning dedicated last-mile infrastructure from specialized regional carriers and in-house retail delivery arms. Three archetypes dominate: national multi-modal operators with dedicated white glove divisions, technology-enabled third-party logistics specialists, and captive retail fleets maintained by high-volume furniture and appliance merchants. Competitive intensity centers on route density optimization and real-time visibility platform deployment.
Within the integrated logistics tier, XPO and FedEx Corporation anchor service density through owned infrastructure and specialized handling networks. SEKO Logistics occupies a position among technology-enabled specialists, differentiating through real-time shipment visibility and appointment scheduling capabilities. These three entities exemplify the strategic divergence between asset-heavy scale operations and platform-driven service differentiation reshaping competitive positioning across premium delivery corridors.
| Leading Market Players |
|---|
| XPO |
| SEKO Logistics |
| United Parcel Service (UPS) |
| Ryder |
| J.B. Hunt Transport |
| Werner Enterprise |
| Fidelitone Last Mile Inc |
| FedEx Corporation |
| Hub Group, Inc. |
| Others |
Pricing and Supply Chain Analysis
Medium-duty electric step vans with extended range batteries are restructuring fleet economics while simultaneously compressing diesel procurement timelines and concentrating supplier relationships around battery-electric powertrain specialists. This technology transition feeds directly into pricing power dynamics as carriers with early electrification commitments secure preferential access to constrained zero-emission vehicle allocations.
Pricing Analysis
Subscription-based flat-rate service agreements dominate enterprise furniture retailer contracts, with pricing stratifying across premium assembly-inclusive tiers, standard room-of-choice positioning, and economy threshold delivery levels. Price differentiation rests on crew specialization depth and real-time visibility platform integration. Cost compression in standard tiers is intensifying because route density constraints from narrow appointment windows erode per-stop economics. Mass-market e-commerce retailers exhibit highest price sensitivity, while hospital networks and home healthcare providers demonstrate lowest sensitivity due to compliance mandates and patient safety requirements.
Supply Chain Analysis
Direct-to-retailer channels handle high-volume scheduled delivery demand, while third-party logistics networks manage outsourced enterprise capacity. Distribution runs through domestic final-mile depots concentrated in California, Texas, and New York metropolitan clusters. Vehicle procurement draws from specialized medium-duty chassis manufacturers and electric powertrain conversion specialists. Single-source vulnerability around battery supply agreements with limited qualified electric step van providers represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
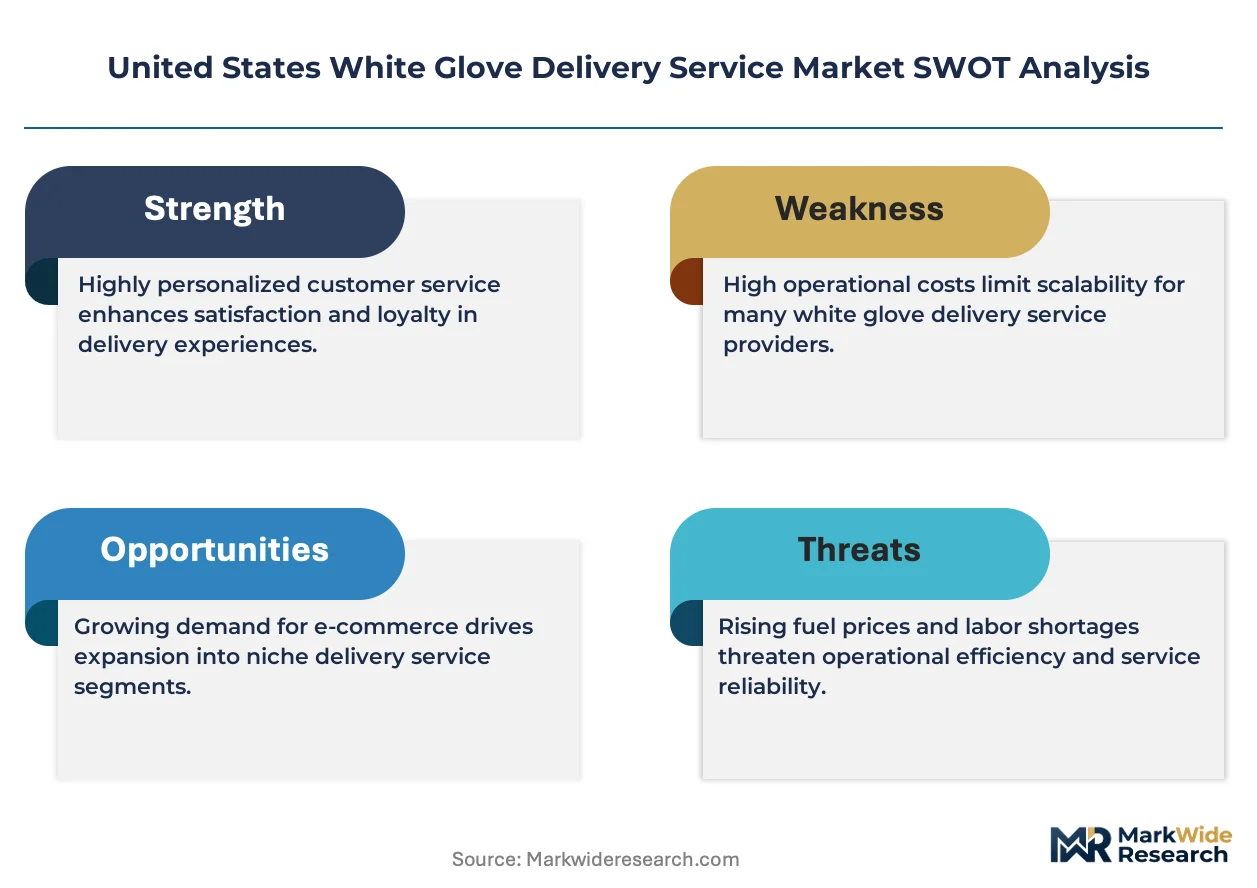
Margin expansion in white glove delivery hinges on assembly service penetration and electric fleet operating cost advantages displacing diesel maintenance burdens.
For Market Incumbents: Anchor service density in California's Advanced Clean Trucks corridors through accelerated electric fleet commitments that lock in zero-emission vehicle allocation priority. Defend against technology-enabled entrants by deepening proprietary real-time visibility platform capabilities. Vertical integration into captive assembly technician training programs protects margin pools from labor arbitrage by specialized staffing platforms.
For New Entrants and Emerging Players: Rural home healthcare providers represent an underserved buyer archetype with escalating medical equipment logistics requirements and limited incumbent coverage density. Wedge into this white space through targeted partnerships with regional hospital networks expanding remote patient monitoring infrastructure. Emphasize OSHA-compliant two-person crew protocols as a differentiated safety credential against asset-light competitors.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional third-party logistics specialists with concentrated exposure to California metropolitan corridors and pending electric fleet conversion liabilities. Long-term viability over the five-to-ten year horizon favors carriers with demonstrated route density economics and established healthcare provider relationships. Monitor EPA Phase 2 compliance timeline acceleration as the critical inflection signal for stranded diesel asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | California Air Resources Board mandates force zero-emission vehicle procurement into capital planning cycles. |
| Assembly Service Expansion | Furniture retailers capture disproportionate margins through extended customer touchpoints and specialized labor. |
| Real-Time Visibility Platform Deployment | Appointment scheduling and shipment tracking technologies differentiate carrier offerings in competitive bids. |
| Healthcare Provider Partnership | Hospital networks mandate inside delivery with assembly for imaging equipment and patient bed installations. |
| Subscription Pricing Model Adoption | Flat-rate service agreements stabilize seasonal demand fluctuations for high-volume furniture merchants. |
Research Methodology
Coverage spans California, Texas, New York, Illinois, and Florida metropolitan corridors, with primary inputs from each region combined with secondary validation. Interviews with fleet operations directors, furniture retailer logistics managers, healthcare procurement officers, and last-mile technology vendors anchored demand-side perspectives. Secondary sources included DOT hours-of-service regulatory filings, EPA Phase 2 compliance documentation, California Air Resources Board rulemaking records, and OSHA workplace safety guidance. Bottom-up route density modeling and top-down market sizing triangulated volume estimates across the analysis window.
Granularity-level modeling addressed service type, end user category, delivery mode, and pricing model dimensions at the metropolitan statistical area level. CAGRs were derived from segment-level growth rate reconciliation against aggregate market trajectory. Electric vehicle adoption curves and labor cost inflation assumptions shaped fleet economics projections throughout the forecast period.
Underlying measurement precision varies by segment; subscription-based pricing and third-party logistics transaction volumes carry tighter precision than emerging same-day delivery tiers. Forecasts reflect assumptions regarding regulatory compliance timeline adherence and consumer willingness-to-pay evolution for premium service tiers. Periodic stress-testing of base assumptions is recommended given driver classification ruling uncertainty and multi-state emissions mandate divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Middle East Car Rental Market
Transportation Services
Bird Carriers Market
Transportation Services
On Street Vehicle Parking Meter Market
Transportation Services
Malaysia Car Rental Market
Transportation Services
Drayage Services Market
Transportation Services
Fleet Management Consulting Service Market
Transportation Services
Full-Service Carrier Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Enclosed Car Transportation Service Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Taxi and Ride-Hailing Services Market
Transportation Services
Benchmarking Services for Transportation Rates Market
Transportation Services
Refrigerated Truck Rental Market
Transportation Services
Corporate Employee Transportation Service Market
Transportation Services
Bulk Transportation Services Market