
 Car Breakdown Recovery Services Market | 2026-2036
Car Breakdown Recovery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Car Breakdown Recovery Services Market Analysis
European roadside assistance fleets is consolidating around networked dispatch platforms and centralized fleet ownership. RAC Motoring Services leverages its patrol density across the United Kingdom to sustain sub-30-minute response commitments. Agero Inc. anchors North American insurer partnerships through proprietary telematics integration. AA plc competes on membership retention via bundled home and motor coverage.
Car breakdown recovery services encompass emergency roadside intervention, vehicle relocation, and on-site minor repair performed by trained technicians using mobile workshop units equipped with diagnostic scanners, jump-start packs, and flatbed carriers. The primary commercial purpose is minimizing driver downtime and preventing secondary accidents on high-speed corridors. Roadside Assistance commands the largest revenue share among service types due to recurring subscription structures, while Towing generates the highest per-incident margins especially for heavy vehicle recoveries. Fleet Operators represent the fastest-growing end user category as logistics firms internalize uptime guarantees into service level agreements.
The United States Department of Transportation governs commercial vehicle recovery safety standards through FMCSA regulations, while the EU F-Gas Regulation shapes mobile air conditioning recharge protocols during roadside interventions. Germany's KBA enforces periodic vehicle inspection rules that indirectly generate breakdown events from deferred maintenance. Stakeholders must monitor embedded telematics penetration rates to determine whether manufacturer-integrated recovery systems displace independent service contracts.
Market Dynamics
Fleet electrification timelines are compressing service contract durations as logistics operators demand predictive uptime guarantees rather than reactive recovery dispatch. This shift forces incumbents to reconfigure patrol density models around charging infrastructure corridors rather than traditional fuel station networks.
Growth Catalysts
- EU F-Gas Regulation:Mobile air conditioning recharge mandates during roadside interventions create recurring service touchpoints. Recovery operators bundle refrigerant handling into standard contracts.
- Fleet telematics penetration:Logistics firms integrate breakdown prediction into route optimization. Service providers capture data feeds to pre-position patrol assets before failure alerts trigger.
- German autobahn density:High-speed corridor concentration generates consistent call volumes. Recovery fleets achieve utilization rates unavailable in dispersed rural networks elsewhere.
Market Restraints
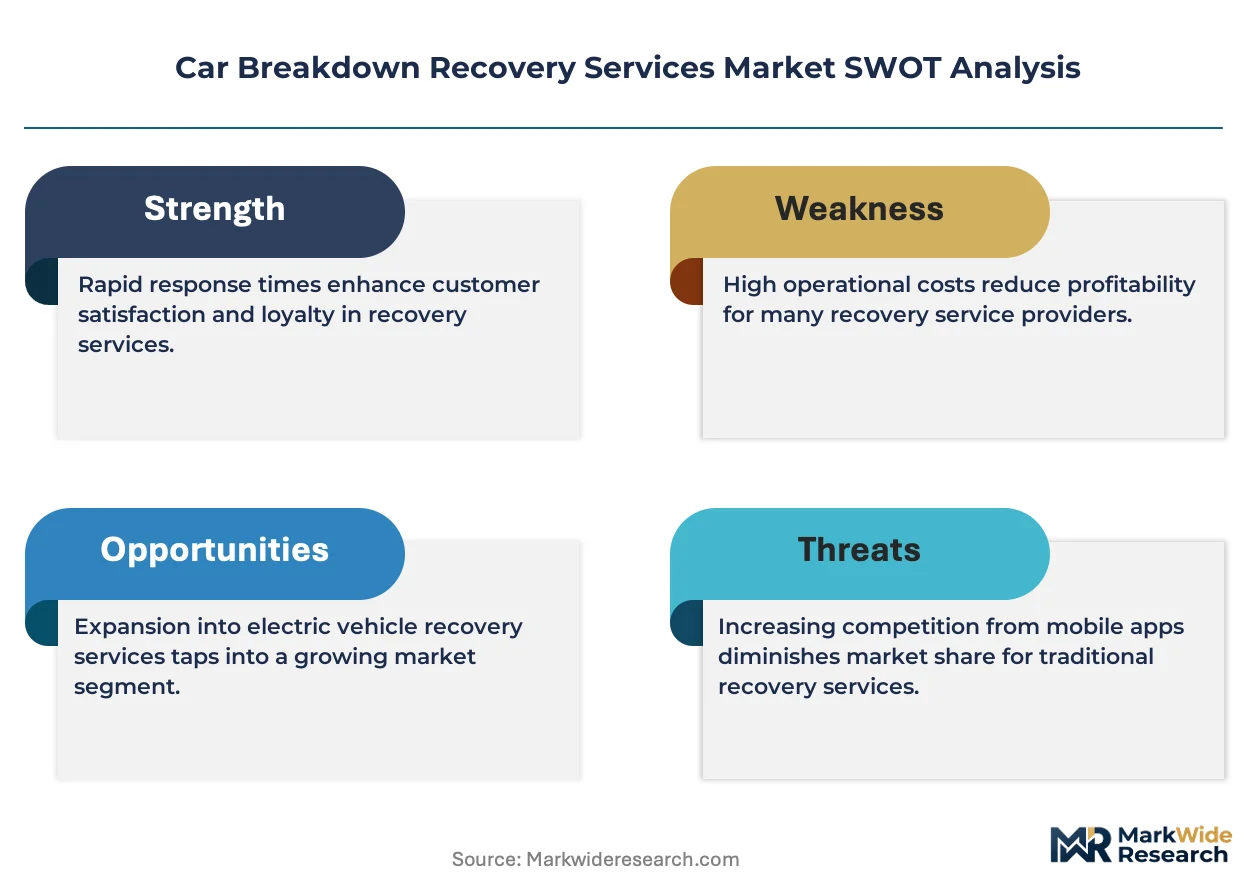
- Technician labor pool constraints:EV high-voltage certification requirements exceed current training pipeline capacity. Recovery operators compete with dealerships for qualified personnel.
- Specialized equipment capex:Flatbed carriers rated for electric vehicle battery protection cost substantially more than conventional tow rigs. Smaller operators delay fleet refresh cycles.
- Insurer direct integration:Telematics-enabled first notice of loss systems bypass traditional roadside assistance dispatch. Independent service providers lose policyholder access.
Strategic Opportunities
- Polish and Romanian highway expansion:EU infrastructure funds are extending motorway networks eastward. Recovery operators can establish patrol nodes ahead of mature market saturation.
- CSRD reporting alignment:Fleet operators must document supply chain emissions. Recovery services offering carbon-neutral dispatch options capture sustainability-driven contract renewals.
- Vehicle-to-grid integration:Stranded EVs with bidirectional charging capability represent mobile power assets. Recovery technicians trained in grid connection protocols unlock new revenue streams.
Industry Challenges
- Multi-voltage platform complexity:Patrol technicians must safely handle 400V and 800V architectures across competing OEM designs. Training standardization lags vehicle launch cycles.
- Legacy dispatch system integration:Insurer back-end platforms rely on decades-old protocols. Real-time telematics data feeds require expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Breakdown Recovery Services Market |
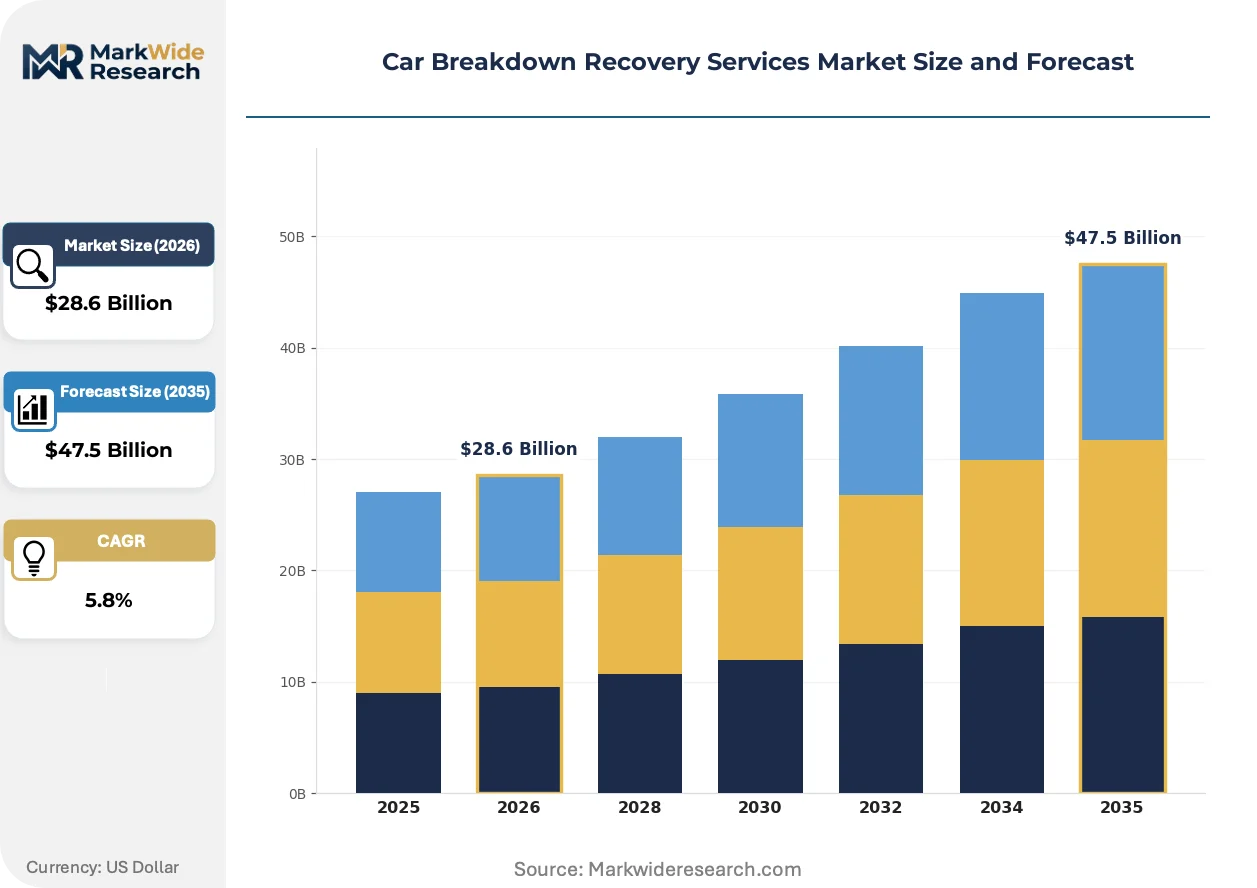
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Roadside Assistance, Towing, Fuel Delivery, Tire Change End User: Individual Drivers, Fleet Operators, Insurance Companies, Commercial Vehicles Vehicle Type: Passenger Cars, Motorcycles, Light Trucks, Heavy Vehicles Coverage Area: Urban Areas, Rural Areas, Highways, National Reach |
| Companies Covered | RAC Motoring Services, Allstate Insurance Company, AAA, Paragon Motor Club, Good Sam Enterprise LLC, Agero Inc., AA plc, Falck A/S, Allianz Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Breakdown Recovery Services Market Emerging Trajectories
Diagnostic capability migration from fixed garages to mobile patrol units is redefining technician skill requirements and equipment payloads. The sector is pivoting from mechanical recovery toward software-enabled intervention.
AI-powered fault prediction is automating dispatch decisions before drivers recognize symptoms. Fleet operators in Germany and the Netherlands deploy machine learning models trained on CAN bus data streams to trigger proactive patrol deployment. This compression of response initiation is automating the traditional emergency call center role and shifting value toward predictive platform providers.
The EU Green Deal's embedded carbon reporting requirements are mandating service vehicle fleet decarbonization. Recovery operators face compressed timelines to transition patrol vans to electric or hydrogen propulsion. Heavy recovery segments in France and Italy resist this shift due to torque requirements for commercial vehicle winching, creating regulatory friction between mandate and operational feasibility.
Subscription unbundling is fragmenting buyer relationships as fleet procurement teams separate breakdown coverage from motor insurance. Large logistics operators in the United Kingdom negotiate direct service level agreements with recovery specialists. This disintermediation of traditional insurance intermediaries concentrates purchasing power among fewer buyers with customized uptime specifications.
Car Breakdown Recovery Services Market Segmentation
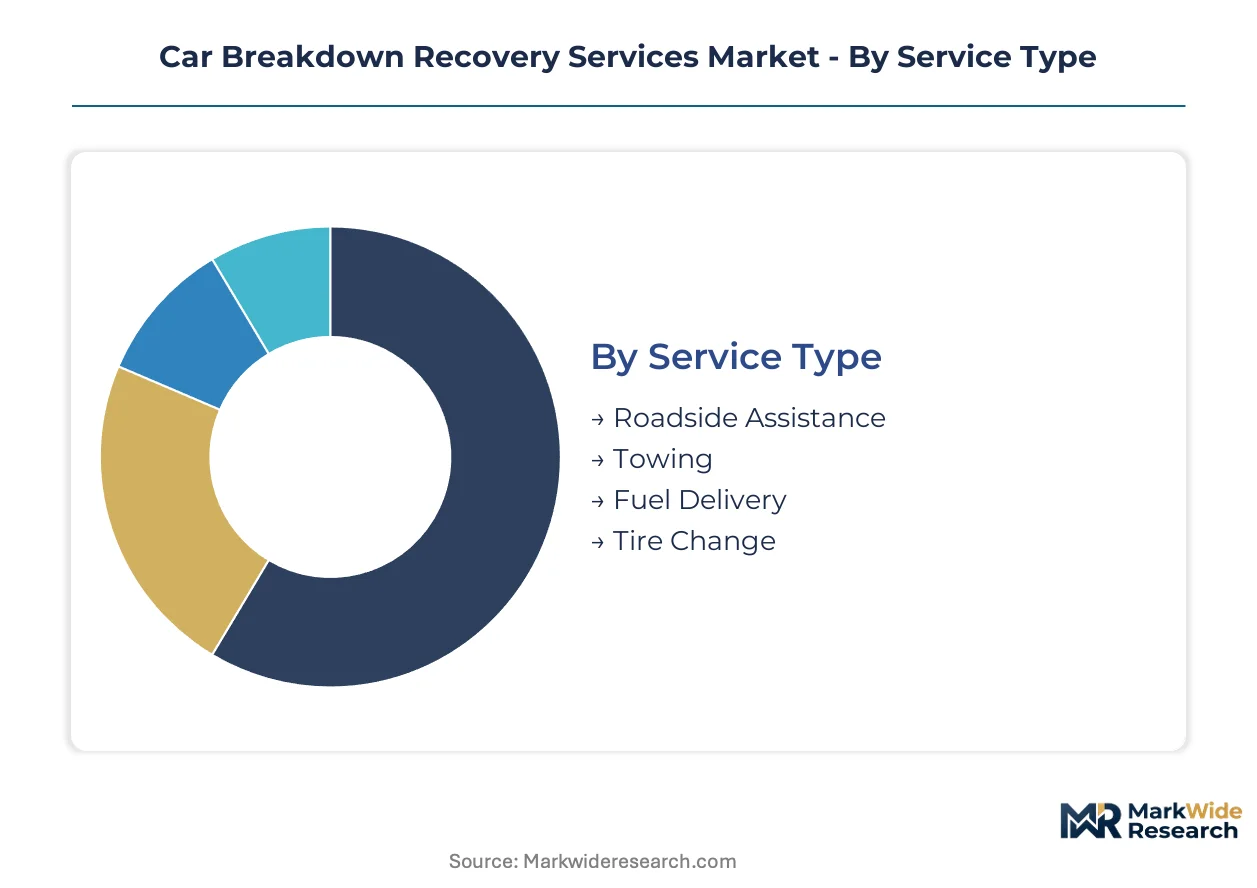
Recovery operators configure service portfolios around response time guarantees and vehicle specialization. Segmentation decisions determine patrol density investments, technician certification requirements, and equipment procurement priorities across geographic footprints.
Service Type:
Standardization dominates commodity interventions while premium tiers bundle predictive capabilities and specialized handling protocols.
- Roadside Assistance:On-site minor repairs, battery jump-starts, and lockout services performed by mobile technicians carrying diagnostic scanners and portable power units. German autobahn networks and Netherlands corridor density sustain sub-20-minute response commitments through predictive pre-positioning. Subscription structures generate recurring revenue streams with 12-month contract cycles.
- Towing:Vehicle relocation using flatbed carriers, wheel-lift rigs, and heavy-duty rotators rated for electric vehicle battery protection. Per-incident pricing scales with distance and vehicle weight class. French and Italian commercial vehicle corridors command premium rates for heavy recovery involving cargo transfer and specialized winching.
- Fuel Delivery:Emergency diesel, gasoline, and AdBlue dispensing to stranded vehicles lacking station access. Rural UK networks and Spanish coastal routes maintain higher call frequency due to infrastructure gaps.
- Tire Change:Mobile fitting of spare wheels or temporary repairs using sealant injection systems. Seasonal demand spikes correlate with winter tire transition periods in Nordic markets.
Leading the category by volume: Roadside Assistance. Expanding most quickly: Towing.
End User:
Procurement complexity escalates from individual discretionary purchases to enterprise-level uptime specifications with penalty clauses.
- Fleet Operators:Logistics firms, delivery services, and rental companies negotiating service level agreements with guaranteed response windows and alternative vehicle provision. EU CSRD reporting requirements increasingly mandate carbon-neutral dispatch options in contract terms. Telematics integration enables predictive intervention before driver awareness of failure symptoms.
- Insurance Companies:Motor underwriters bundling recovery access into comprehensive policies or selling standalone roadside assistance riders. Direct telematics integration threatens traditional dispatch relationships as first notice of loss systems automate incident reporting.
- Individual Drivers:Retail subscribers purchasing annual membership through automobile clubs or direct-to-consumer platforms. UK and German markets show highest penetration rates due to motorway density and high vehicle age profiles.
- Commercial Vehicles:Operators of buses, coaches, and specialist transport requiring heavy recovery capability and cargo continuity protocols. French regulatory frameworks mandate specific equipment ratings for passenger vehicle recovery.
Steepest expansion trajectory: Fleet Operators. Largest contract value concentration: Insurance Companies.
Vehicle Type:
Equipment specialization requirements fragment service capability across voltage architectures and weight classifications.
- Passenger Cars:Standard patrol units handle battery failures, tire damage, and minor mechanical faults across internal combustion and electric platforms. German KBA inspection rules indirectly generate call volume from deferred maintenance accumulation.
- Heavy Vehicles:Commercial trucks, buses, and construction equipment requiring rotator-equipped recovery rigs and cargo transfer coordination. Italian mountain corridors and Alpine tunnel networks demand specialized heavy recovery staging points.
- Light Trucks:Delivery vans and utility vehicles occupying intermediate weight classes with mixed drivetrain configurations. Urban last-mile logistics concentration in Netherlands and Belgian distribution hubs drives service demand.
- Motorcycles:Two-wheel recovery using specialized trailers and securement systems. Mediterranean coastal tourism routes and Alpine motorcycle touring corridors generate seasonal demand clustering.
Highest service frequency: Passenger Cars. Fastest capability investment: Heavy Vehicles.
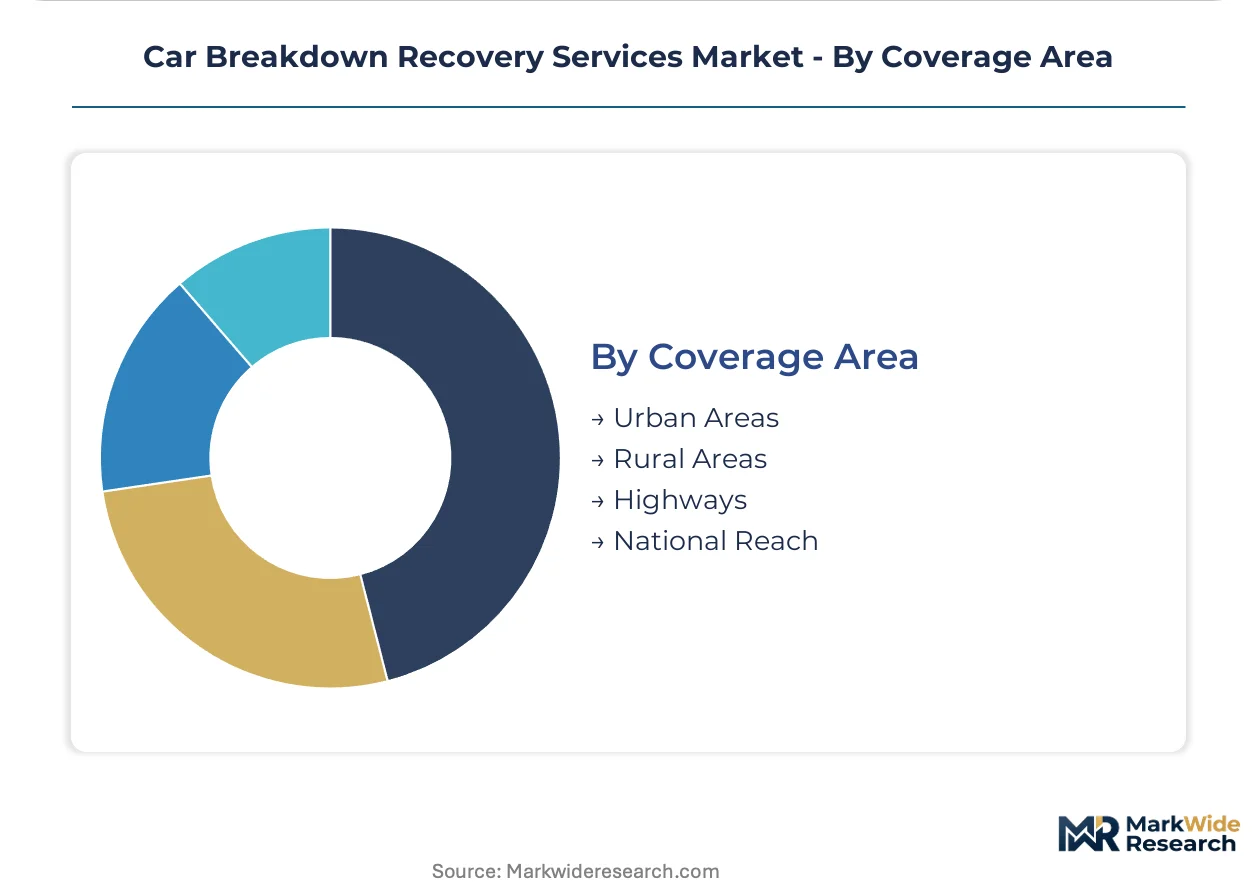
Coverage Area:
Patrol economics invert between dense urban networks with utilization efficiency and dispersed rural territories requiring premium pricing.
- Highways:High-speed corridor patrols achieving fastest response times through dedicated service lanes and emergency refuge areas. German autobahn density enables utilization rates unavailable in dispersed networks elsewhere.
- Urban Areas:Metropolitan patrol grids with congestion-adjusted response algorithms and parking restriction navigation. London congestion charging zones and Paris low-emission boundaries shape dispatch routing.
- National Reach:Cross-border service networks covering multiple jurisdictions with harmonized response protocols. EU single market facilitation enables seamless coverage across member state boundaries.
- Rural Areas:Low-density territories requiring extended response windows and higher per-incident pricing. Scottish Highlands and Spanish interior regions maintain limited patrol presence with contractor augmentation.
Maximum patrol utilization: Highways. Fastest network expansion: National Reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diesel particulate filter regulations and high-speed corridor density anchor geographic demand concentration across mature automotive markets.
Germany
Autobahn network density and KBA inspection rules generate persistent recovery call volumes from deferred maintenance accumulation. The EU F-Gas Regulation mandates mobile air conditioning recharge protocols during roadside interventions. Recovery fleets cluster around Frankfurt-Rhine-Main and Munich-Stuttgart corridors where utilization rates exceed dispersed rural networks.
United States
FMCSA commercial vehicle safety standards and insurer telematics integration drive service contract standardization. NHTSA regulations shape heavy recovery equipment ratings for battery-protected electric vehicle transport. Texas and California logistics corridors concentrate fleet operator demand with predictive uptime specifications.
United Kingdom
Subscription unbundling trends separate breakdown coverage from motor insurance among fleet procurement teams. London congestion charging zones and low-emission boundaries reshape urban dispatch routing algorithms. Midlands and North England distribution hubs anchor patrol density investments for last-mile logistics coverage.
France
Heavy recovery segments resist EU Green Deal fleet decarbonization mandates due to torque requirements for commercial vehicle winching. ANSM-equivalent transport safety frameworks mandate specific equipment ratings for passenger vehicle recovery. Alpine tunnel networks and Italian border corridors demand specialized heavy recovery staging points.
Netherlands
Urban last-mile logistics concentration drives service demand for light truck and delivery van recovery. Predictive patrol pre-positioning using CAN bus data streams compresses response initiation below driver awareness thresholds. Randstad metropolitan grids achieve sub-20-minute response commitments through congestion-adjusted dispatch algorithms.
Car Breakdown Recovery Services Market Vendor Landscape
Global majors compete with regional champions across telematics integration depth and patrol density economics. Market structure consolidates around networked dispatch platforms with centralized fleet ownership displacing fragmented contractor models. Three archetypes dominate: insurer-anchored platforms, automobile club membership networks, and fleet-direct service specialists. Competitive moves concentrate on predictive capability acquisition and charging infrastructure corridor pre-positioning.
Within the insurer-anchored tier, Agero Inc. and Allstate Insurance Company represent platform-based dispatch integration. AA plc and RAC Motoring Services occupy positions within membership-retention-focused automobile club networks. These five entities exemplify contrasting geographic footprints and partnership structures across North American and European markets.
| Leading Market Players |
|---|
| RAC Motoring Services |
| Allstate Insurance Company |
| AAA |
| Paragon Motor Club |
| Good Sam Enterprise LLC |
| Agero Inc. |
| AA plc |
| Falck A/S |
| Allianz Partners |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement concentration in Germany and the Netherlands anchors contract-based pricing with embedded uptime guarantees. Insurance bundling in the United Kingdom and North America creates divergent pricing power between direct fleet negotiations and intermediary-mediated subscriptions.
Pricing Analysis
Warranty unbundling separates breakdown coverage from comprehensive motor policies. Three-tier pricing structure across premium, standard, and economy levels reflects response time guarantees and vehicle specialization. Price differentiation hinges on telematics integration depth and technician certification tier. Cost compression in the economy tier is intensifying because insurer direct integration bypasses traditional dispatch margins. Individual retail subscribers exhibit highest price sensitivity; fleet operators with SLA penalty clauses show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, the United Kingdom, and Poland anchor hub-and-spoke patrol deployment. Equipment manufacturing draws from China for diagnostic scanners, Italy for flatbed carriers, and Germany for mobile workshop vehicles. Single-source vulnerability concentrates in EV high-voltage safety component supply. Distribution runs through centralized fleet ownership networks displacing fragmented contractor models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician certification bottlenecks and specialized equipment capex are forcing consolidation among sub-scale operators. Surviving players must secure predictive capability advantages before telematics-enabled insurers capture policyholder relationships.
For Market Incumbents: Deepen telematics platform integration to pre-position patrol assets before failure alerts trigger. Secure EV high-voltage technician pipelines through dealership partnerships before labor competition intensifies. Acquire regional specialists in Polish and Romanian highway corridors ahead of infrastructure maturity. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for refrigerant-handling specialists to embed into standard recovery contracts. Target fleet operator direct procurement teams in the Netherlands negotiating CSRD-aligned carbon-neutral dispatch options. Lead with predictive maintenance software rather than asset-heavy patrol networks. For Investors and Strategic Acquirers: The window for entry favors vertically integrated regional champions with charging corridor positioning. Five-to-ten year viability hinges on electrification transition pacing and manufacturer-integrated recovery system displacement risk. Monitor embedded OEM telematics penetration rates as inflection indicator for independent service contract displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Platform Development | AI-powered fault prediction using CAN bus data compresses response initiation below driver awareness in German corridors. |
| EV High-Voltage Certification Investment | 400V and 800V architecture training standardization lags vehicle launch cycles, creating technician scarcity premiums. |
| Charging Infrastructure Corridor Pre-Positioning | Patrol density reconfiguration around charging networks displaces traditional fuel station-based dispatch economics. |
| CSRD Reporting Alignment | Carbon-neutral dispatch options capture sustainability-driven contract renewals from EU fleet operators. |
| Regional Network Expansion | Polish and Romanian motorway extensions enable patrol node establishment ahead of mature market saturation. |
Methodological Framework
Document review covered EU F-Gas Regulation implementation guidance, FMCSA commercial vehicle safety standards, and KBA inspection rule amendments, complemented by interviews with fleet operations directors, roadside assistance dispatch platform engineers, recovery equipment procurement managers, and insurer telematics integration specialists. Secondary validation drew from customs trade data on recovery vehicle imports, SEC filings of listed automobile clubs, and vehicle registration databases. Bottom-up service call volume modeling triangulated against top-down fleet contract value estimates.
Segmentation outputs across service type, end user archetype, vehicle classification, and coverage area geography were calibrated against patrol utilization rates and response time commitments. CAGRs were derived from contract renewal velocity and fleet electrification timeline assumptions. Key inputs included embedded telematics penetration trajectories and EU infrastructure fund disbursement schedules for highway expansion.
The model assumes a particular technology adoption path; alternative pathways for bidirectional vehicle-to-grid integration would alter the outlook for stranded EV recovery revenue streams. Forecasts reflect documented assumptions around technician training pipeline expansion and equipment refresh cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
Parking Services Market
Automotive Services
United States Automotive Dealership Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Car Subscription Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Car Washing Service Market
Automotive Services
Vehicle Conversion Market
Automotive Services
France Car Rental Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Motorsports Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Driverless Sweeper Market
Automotive Services
United States Automotive Service Market