
 UK Electric Bus Battery Pack Market | 2026-2036
UK Electric Bus Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
UK Electric Bus Battery Pack Market Insights
Aftermarket service revenue is reshaping margin distribution across the UK electric bus battery pack value chain. CATL leverages its integrated cell-to-pack manufacturing scale to dominate supply contracts with British bus OEMs. BYD Company anchors its UK position through backward integration into cell production and captive service networks. Hyperbat specializes in modular pack assembly tailored to European bus platform specifications, competing on customization speed rather than volume.
A UK electric bus battery pack is a rechargeable electrochemical energy storage system engineered to deliver sustained high-current discharge for heavy-duty urban transit duty cycles, typically incorporating lithium-ion cells with capacities exceeding 300 kWh and thermal management architectures rated for ambient temperatures. Its primary commercial purpose is to replace diesel propulsion with zero-emission electric drivetrains while maintaining route operational range and depot turnaround schedules. LFP chemistry leads procurement volumes among UK operators prioritizing thermal stability and extended cycle life over energy density, while fast charging technology captures the fastest growth trajectory as operators deploy opportunity charging infrastructure at route termini. The public transport end user segment concentrates the majority of installed base value, though private fleet operators are emerging as a secondary demand channel for airport and campus shuttle applications.
The UK Department for Transport's ZEBRA funding framework and the Office for Low Emission Vehicles' grant structures directly shape procurement timelines and minimum technical specifications for battery capacity and warranty terms. BSI standards for electric vehicle battery safety, combined with emerging UKCA marking requirements post-Brexit, create compliance thresholds that filter non-European suppliers from certain tender categories. Stakeholders must monitor how the UK's developing battery passport regulations and anticipated carbon border adjustments will reshape supplier qualification criteria and total cost of ownership calculations for fleet procurement decisions.
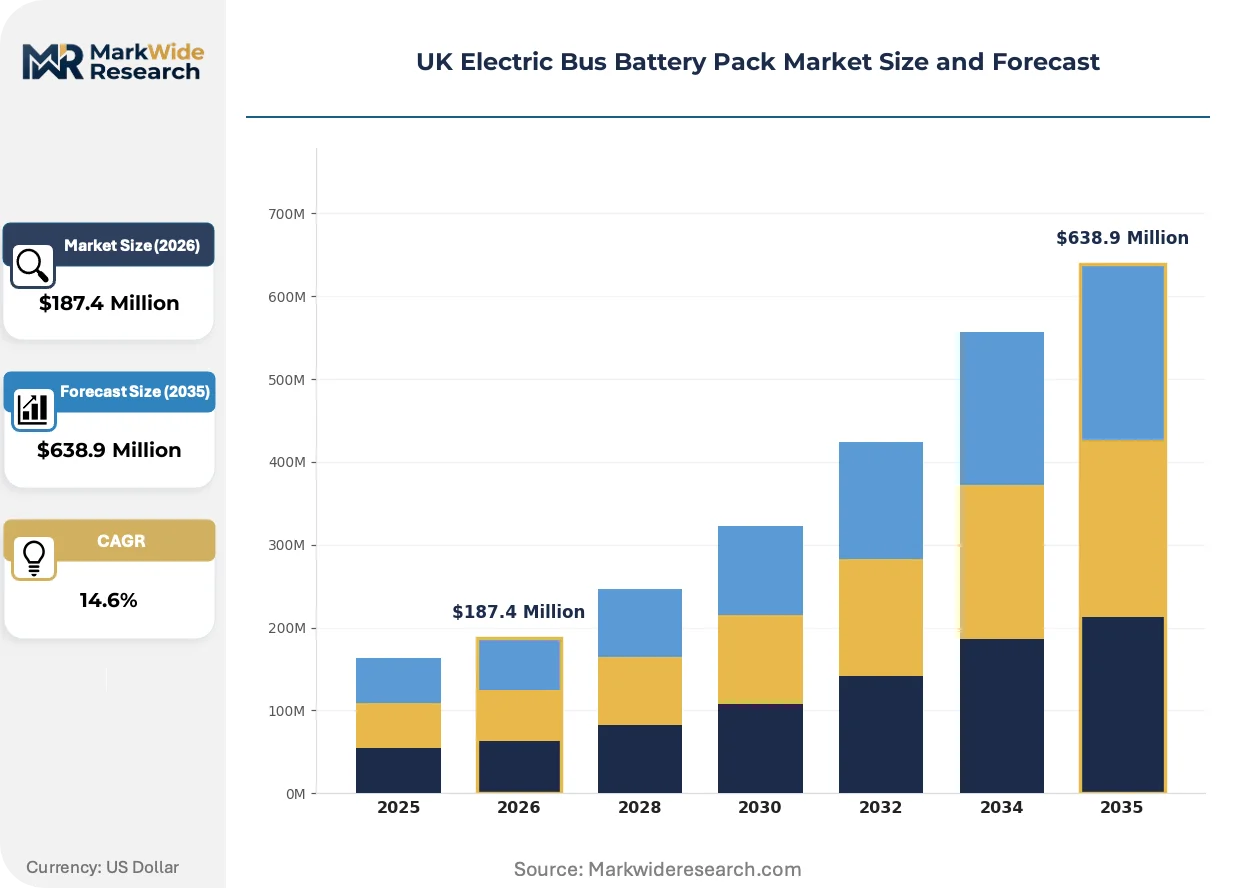
Market Dynamics
The UK government's ZEBRA funding framework and Clean Air Zone mandates are compressing procurement timelines for high-capacity battery systems, forcing transport authorities to accelerate fleet electrification schedules while navigating post-Brexit certification requirements.
Growth Catalysts
- Zero Emission Bus Regional Areas (ZEBRA) programme:The Department for Transport's funding mechanism directly subsidizes battery procurement for municipal operators in England, Scotland, Wales, and Northern Ireland.
- Clean Air Zone mandates:Birmingham, Manchester, and London's tightening emissions regulations penalize diesel bus operations, redirecting capital toward electric alternatives.
- LFP chemistry dominance:Lithium iron phosphate cell technology delivers the thermal stability and cycle life specifications that UK fleet operators prioritize for heavy-duty urban duty cycles.
Market Restraints
- Cell supply concentration:Asian cell manufacturers control upstream lithium-ion production, exposing UK pack assemblers to raw material volatility and shipping cost swings.
- UKCA marking friction:Post-Brexit conformity assessment requirements create compliance delays for European suppliers unfamiliar with British certification pathways.
- Depot infrastructure capex:Grid connection upgrades and high-power charging hardware demand capital commitments that strain municipal transport authority budgets.
Strategic Opportunities
- Northern Ireland fleet gap:Belfast and Derry transport authorities lag English electrification rates, creating first-mover positioning for battery suppliers with localized service networks.
- Airport shuttle electrification:Private operators at Heathrow, Gatwick, and Manchester airports are emerging as a secondary demand channel for mid-capacity battery packs.
- Battery passport regulations:Anticipated UK carbon border adjustments and traceability mandates will favor suppliers with established lifecycle documentation systems.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance departments lack sufficient trained personnel for battery pack diagnostics and module replacement procedures.
- Integration complexity with legacy depot systems:Existing electrical infrastructure at Victorian-era bus depots requires costly retrofitting to accommodate megawatt-scale charging equipment.
- Warranty liability compression:Extended cycle-life guarantees demanded by ZEBRA-funded tenders strain pack assembler balance sheets against cell supplier back-to-back terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Electric Bus Battery Pack Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, NCA, Others Technology: Fast Charging, Wireless Charging, Modular, Standard Charging End User: Public Transport, Private Fleet, Logistics, Ride-sharing Size: Small, Medium, Large, X-Large |
| Companies Covered | BYD Company, CATL, LG Energy Solution, Samsung SDI, SK Innovation, LEAPENERGY, Hyperbat, Alexander Battery Technologies, Connected Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Electric Bus Battery Pack Market Trends and Innovations
Cell-to-pack architectures and opportunity charging infrastructure are restructuring how UK bus operators specify energy storage systems, compressing the traditional trade-off between battery capacity and depot dwell time.
Solid-state battery research is hybridizing with conventional liquid electrolyte designs as British pack assemblers trial semi-solid cell configurations for next-generation double-decker applications. Transport for London's technical specifications now accommodate these intermediate chemistries, enabling earlier commercialization than full solid-state timelines would permit. The structural consequence is a tiered supply base where established LFP suppliers defend municipal contracts while semi-solid specialists target premium rapid-charge deployments.
The UK's developing battery passport regulations under the Office for Product Safety and Standards are mandating digital product traceability from cell origin through end-of-life recycling. This policy infrastructure compels pack manufacturers to invest in blockchain-enabled supply chain documentation systems ahead of mandatory compliance deadlines. Northern Irish and Scottish operators face accelerated implementation timelines due to devolved administration procurement rules.
Service unbundling is fragmenting traditional battery supply agreements as West Midlands and Greater Manchester authorities separate pack procurement from long-term maintenance contracts. Third-party asset managers are inserting themselves between cell suppliers and fleet operators, absorbing warranty risk in exchange for guaranteed service revenue streams. This behavioral shift concentrates most visibly among English transport authorities with ZEBRA-funded deployments exceeding fifty vehicles.
UK Electric Bus Battery Pack Market Segmentation
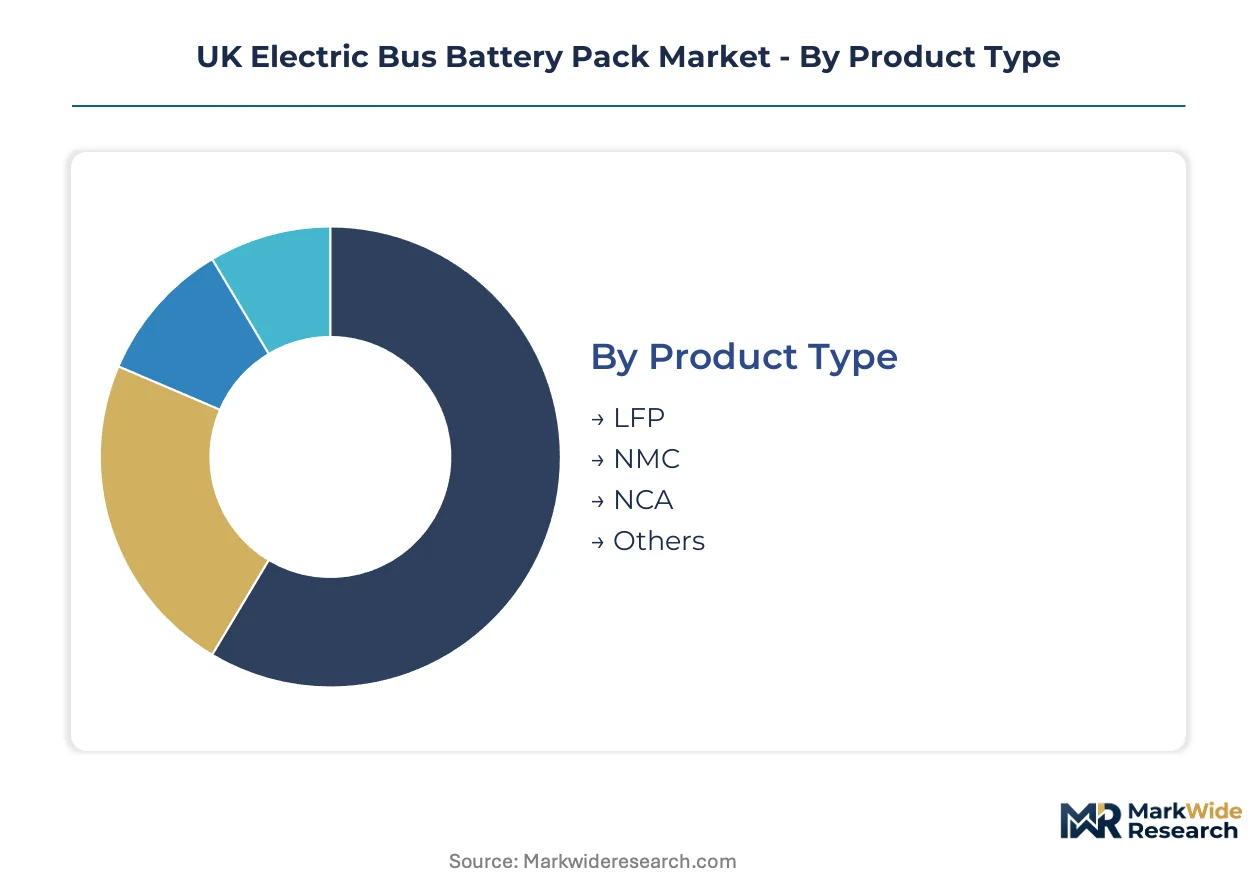
UK electric bus battery pack segmentation reveals how procurement specifications diverge across municipal duty cycles, charging infrastructure constraints, and fleet ownership models. Transport authorities in Greater London and the West Midlands are driving specification fragmentation through divergent route requirements and depot retrofit capabilities.
Product Type:
Lithium iron phosphate chemistry dominates municipal procurement due to thermal stability demands, while nickel-based alternatives serve niche applications requiring higher energy density.
- LFP:Lithium iron phosphate cells deliver superior thermal stability and cycle life exceeding 4,000 cycles under heavy-duty urban duty cycles. Transport for London specifications prioritize LFP for double-decker fleets operating intensive stop-start routes across Greater London, with ZEBRA-funded tenders mandating extended warranty terms that favor this chemistry's degradation profile.
- NMC:Nickel manganese cobalt configurations achieve higher volumetric energy density for single-decker applications with extended range requirements. West Midlands transport authorities specify NMC for inter-urban routes connecting Birmingham with surrounding authorities, where depot spacing exceeds opportunity charging intervals.
- NCA:Nickel cobalt aluminum formulations target premium rapid-charge deployments at Heathrow and Gatwick airport shuttles.
- Others:Emerging sodium-ion and solid-state prototypes are undergoing trial deployments with Scottish transport consortiums.
The dominant share belongs to LFP, while NMC is closing the gap fastest among English regional authorities with longer average route lengths.
Technology:
Charging infrastructure investment patterns are forcing technology selection trade-offs between capital-intensive depot upgrades and operational flexibility.
- Fast Charging:Pantograph and plug-in systems delivering 350-450 kW enable opportunity charging at route termini, compressing battery capacity requirements. Manchester's transport authority is deploying fast charging infrastructure across 12 corridor endpoints, reducing required pack sizes by 30-40% compared to overnight-only fleets.
- Modular:Swappable pack architectures allow capacity scaling across single-decker and double-decker platforms from common cell inventories. Northern Irish operators favor modular systems due to constrained depot footprints in Belfast and Derry, where phased electrification demands flexible capacity reconfiguration.
- Wireless Charging:Inductive systems are undergoing pilot deployment at select West Midlands bus stations.
- Standard Charging:Overnight depot charging remains prevalent among Welsh authorities with lower daily mileage requirements.
Fast charging infrastructure is expanding most quickly in English metropolitan areas, though modular architectures retain preference where capital constraints limit grid upgrade feasibility.
End User:
Fleet ownership structure determines procurement volume scale, warranty negotiation leverage, and service contract bundling preferences.
- Public Transport:Municipal operators in England, Scotland, Wales, and Northern Ireland concentrate the majority of installed base value through ZEBRA-funded procurement frameworks. Transport authorities in Greater London, West Midlands, and Greater Manchester issue consolidated tenders exceeding 50 vehicles, extracting extended cycle-life guarantees and captive service commitments from pack assemblers.
- Private Fleet:Airport shuttle operators at Heathrow, Gatwick, and Manchester are emerging as a secondary demand channel with distinct mid-capacity specifications. These operators prioritize rapid turnaround compatibility over maximum range, accepting shorter cycle-life ratings in exchange for lower capital expenditure.
- Logistics:Parcel delivery fleet electrification is generating pilot demand around distribution hubs.
- Ride-sharing:Microtransit operators are testing small-format packs for on-demand shuttle services.
Public transport commands the dominant procurement volume, while private fleet electrification is gaining share fastest among airport and campus shuttle applications.
Size:
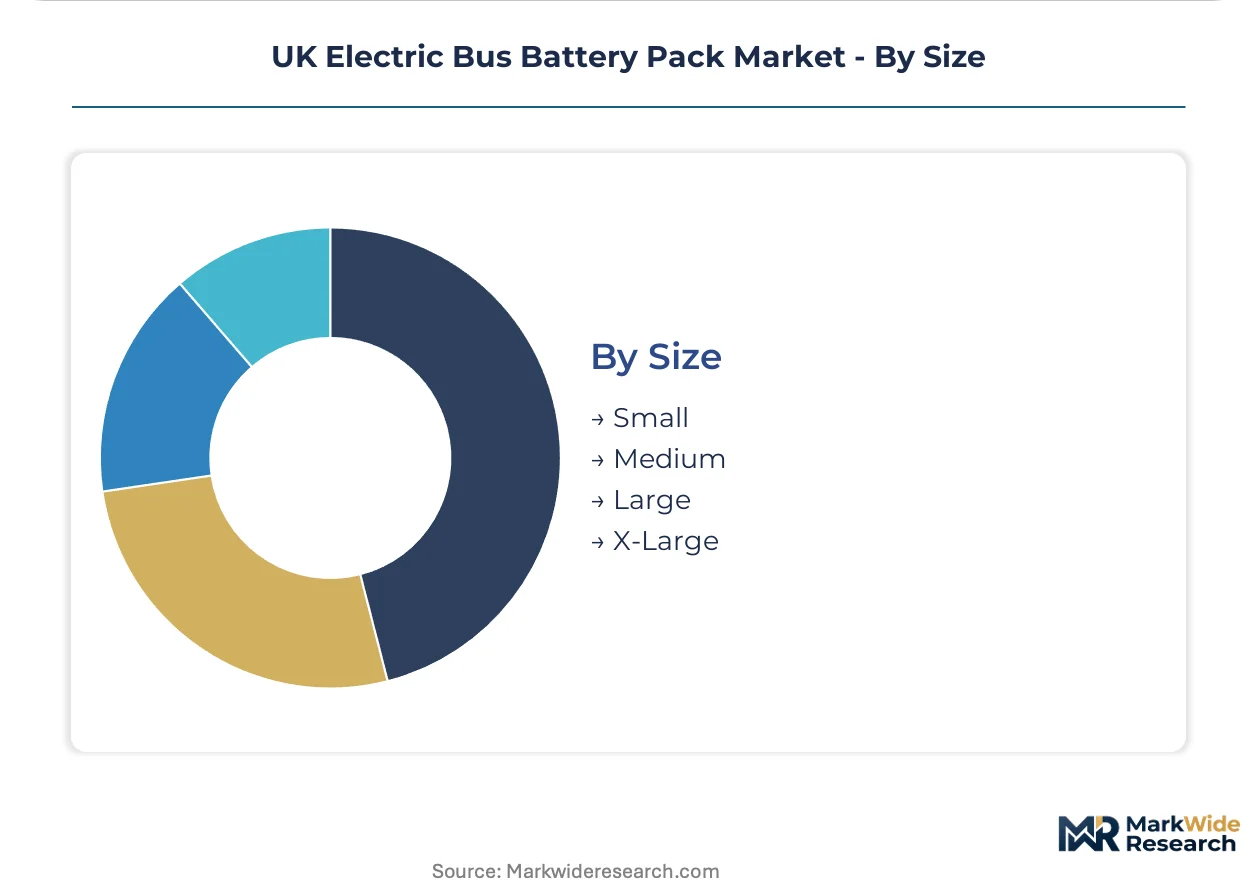
Pack capacity scaling reflects route length distribution, topography, and heating load requirements across UK operating environments.
- Large:Systems exceeding 400 kWh serve double-decker applications and northern routes with elevated heating demands. Scottish operators in Glasgow and Edinburgh specify large packs to accommodate winter climate loads without range degradation, while maintaining schedule adherence on hilly terrain.
- Medium:250-400 kWh configurations balance capital efficiency with operational flexibility for standard single-decker duty cycles. English regional authorities outside London favor medium packs paired with opportunity charging infrastructure, optimizing total cost of ownership across 15-20 year asset lifecycles.
- Small:Sub-250 kWh systems target airport shuttle and campus circulation routes.
- X-Large:Prototype 500+ kWh configurations are under evaluation for rural Scottish inter-urban services.
Large packs hold the dominant installed position, though medium formats are climbing fastest as opportunity charging infrastructure proliferates across English transport authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell production concentrates among Asian manufacturers, forcing UK pack assemblers to navigate import dependencies and post-Brexit certification friction. Transport authorities across England, Scotland, Wales, and Northern Ireland are compressing procurement timelines under ZEBRA funding pressure.
England
Transport for London operates the UK's largest electric bus fleet, driving demand for high-capacity LFP systems across Greater London's double-decker routes. The Department for Transport's ZEBRA programme channels funding toward municipal operators in Birmingham, Manchester, and Leeds. West Midlands transport authorities are deploying opportunity charging infrastructure at 12 corridor endpoints.
Scotland
Glasgow and Edinburgh transport authorities specify large-format battery packs exceeding 400 kWh to accommodate winter heating loads and hilly terrain. Transport Scotland's decarbonisation targets accelerate fleet replacement schedules beyond English timelines. Scottish transport consortiums are trialing sodium-ion and solid-state prototypes with local pack assemblers.
Wales
Cardiff and Swansea operators favor medium-capacity packs paired with standard overnight charging due to lower daily mileage requirements. Welsh Government funding supplements ZEBRA allocations for valley authority fleets serving dispersed populations. Depot infrastructure constraints in former mining regions limit fast charging deployment feasibility.
Northern Ireland
Belfast and Derry transport authorities lag English electrification rates, creating positioning opportunities for suppliers with localized service networks. Translink's procurement framework prioritizes modular pack architectures to accommodate constrained depot footprints. The Department for Infrastructure's sustainable transport programme is unlocking capital for phased fleet conversion.
UK Electric Bus Battery Pack Market Competitive Landscape
Integrated cell-to-pack manufacturers and regional pack assemblers split the market between scale-driven supply contracts and customization-focused service relationships. Consolidation pressures favor players with captive cell supply or established UK service networks. Two archetypes dominate: Asian cell producers with backward integration into pack assembly, and European specialists competing on modular configuration speed. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for ZEBRA-funded tender waves.
Among Asian-integrated manufacturers, BYD Company and CATL anchor the supply base for British bus OEMs, representing the scale-driven archetype with in-house cell production. Hyperbat occupies a position within the European specialist tier, exemplifying modular pack assembly tailored to platform-specific requirements. These three entities illustrate the structural divide between volume-focused supply relationships and customization-oriented competitive positioning.
| Leading Market Players |
|---|
| BYD Company |
| CATL |
| LG Energy Solution |
| Samsung SDI |
| SK Innovation |
| LEAPENERGY |
| Hyperbat |
| Alexander Battery Technologies |
| Connected Energy |
| Others |
Pricing and Supply Chain Analysis
Fujian province's cell manufacturing clusters anchor global lithium iron phosphate capacity, concentrating pricing leverage among Chinese producers who supply UK pack assemblers facing post-Brexit certification friction and volatile shipping costs. This geographic concentration compresses margins for British integrators while amplifying buyer power among transport authorities consolidating ZEBRA-funded tenders.
Pricing Analysis
Aftermarket service revenue drives lifetime value across UK electric bus battery deployments, with extended warranty contracts and module replacement programs generating recurring income streams that offset compressed pack margins. Three-tier pricing structure across premium, standard, and economy levels separates CATL's volume-tier cell supply from Hyperbat's customization services and BYD's integrated service bundles. Cost compression in standard LFP configurations is intensifying because ZEBRA-funded tenders extract extended cycle-life guarantees. Municipal transport authorities exhibit highest price sensitivity, while airport shuttle operators accept premium pricing for rapid-charge compatibility.
Supply Chain Analysis
Extended payment terms from UK pack assemblers to cell suppliers are restructuring working capital requirements across the value chain, with supply-chain finance facilities bridging cash flow gaps for European integrators. China, South Korea, and Japan concentrate upstream lithium-ion cell production, while UK pack assembly draws from German and domestic module integration. Lithium carbonate, nickel sulfate, and copper foil anchor raw material dependencies. Single-source vulnerability from CATL and BYD's market dominance creates procurement risk. Distribution runs through OEM direct supply contracts and third-party asset managers unbundling service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrogen fuel cell propulsion systems, which threaten to displace battery-electric architectures on extended-range inter-urban routes if electrolyzer costs decline and refueling infrastructure scales.
For Market Incumbents: Entrench position through captive cell supply agreements with Chinese producers and accelerated UKCA certification investment to preempt compliance delays. BYD's backward integration into cell production demonstrates defensible positioning against margin compression from ZEBRA warranty terms. Prioritize service network density in Northern Ireland and Scotland where electrification lags create retention risk. For New Entrants and Emerging Players: Pursue modular pack assembly specialization targeting Belfast and Derry transport authorities, where constrained depot footprints favor flexible capacity reconfiguration. Northern Ireland's lagging electrification rate offers most penetrable geographic entry point. Lead with rapid customization turnaround rather than volume scale, mirroring Hyperbat's European specialist archetype. For Investors and Strategic Acquirers: Long-term, this sits as a regulated infrastructure play because ZEBRA funding frameworks and Clean Air Zone mandates create procurement visibility that de-risks capital deployment. Acquisition targets should combine UK service network density with established cell supplier relationships. Monitor Transport Scotland's sodium-ion prototype trials as signal for chemistry diversification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Production | BYD's captive supply secures margin control against Asian producer pricing leverage. |
| UKCA Certification Pre-Investment | Early compliance clears procurement pathways for ZEBRA-funded English tenders. |
| Service Network Localization | Dedicated technicians in Belfast and Glasgow reduce warranty fulfillment costs. |
| Opportunity Charging Infrastructure Partnership | Manchester's corridor endpoint deployment reduces required pack capacity by 30-40%. |
| Battery Passport Documentation System | Blockchain-enabled traceability satisfies Office for Product Safety and Standards mandates. |
Research Methodology
The analysis maps LFP and NMC chemistry tiers, fast charging and modular technology configurations, and public versus private fleet ownership models, each validated through fleet procurement directors at Transport for London and West Midlands transport authorities, pack engineering leads at Hyperbat and Alexander Battery Technologies, and ZEBRA program administrators at the Department for Transport. Secondary validation sources include UK Department for Transport funding disclosures, Office for Low Emission Vehicles grant allocation records, and BSI electric vehicle battery safety standards. Bottom-up cell shipment estimates triangulate against top-down transport authority electrification commitments.
Assumptions held fixed include ZEBRA funding continuity and Clean Air Zone enforcement timelines, while cell chemistry cost curves and charging infrastructure deployment rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass chemistry type, charging technology, end user ownership structure, and pack capacity tier across the projection horizon. CAGRs derive from fleet replacement schedules correlated with battery degradation curves and warranty obligation periods. Forecast inputs incorporate depot infrastructure capex constraints and high-voltage technician availability.
Sensitivities concentrate around ZEBRA funding renewal decisions, UKCA marking implementation delays, and solid-state battery commercialization timelines. Forecasts reflect documented assumptions regarding transport authority procurement behavior and cell supplier capacity allocation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Automotive Battery Thermal Management System Market
Electric Vehicles
Mexico E-Bike Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
Japan E-Bike Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Electric Vehicle on Board Charger Market