
 Electric Commercial Vehicle MRO Market | 2026-2036
Electric Commercial Vehicle MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Commercial Vehicle MRO Market Foresight
ISO 6469-1 high-voltage safety certification is collapsing the pool of qualified independent workshops eligible to service battery-electric trucks and buses. Robert Bosch leverages its diagnostic equipment portfolio to sustain technician training programs across European service networks. Continental AG anchors its position through in-house production of specialized high-voltage testing tools that OEMs specify in warranty contracts. ZF Friedrichshafen AG competes by extending its e-mobility service footprint into captive fleet maintenance agreements with logistics operators.
Electric Commercial Vehicle MRO encompasses the technical servicing, repair, overhaul, and upgrade of battery-electric trucks, vans, and buses operating in commercial freight and passenger applications, requiring specialized handling of lithium-ion battery packs operating at 400-800V DC and thermal management systems using dielectric coolants. The primary commercial purpose centers on maximizing vehicle uptime while ensuring technician safety and preserving battery state-of-health across demanding duty cycles. Battery Systems maintenance commands the deepest margin pools as cell degradation assessment requires proprietary diagnostic algorithms and controlled-environment disassembly capabilities. Telematics-enabled predictive maintenance is displacing scheduled interval servicing as fleet operators demand real-time state-of-health monitoring to optimize total cost of ownership. Fleet Operators represent the most concentrated demand segment as centralized procurement of maintenance contracts drives volume consolidation toward national service agreements.
FCC equipment authorization rules govern diagnostic tool connectivity standards for connected commercial vehicles operating in US territories, while EU Green Deal emissions targets and REACH chemical handling protocols shape workshop infrastructure investments across European member states. Germany's KBA enforces periodic technical inspection standards that now incorporate high-voltage system integrity verification for electric trucks. Stakeholders must decide whether to build captive high-voltage service capability or outsource to certified third-party networks before technician scarcity hardens into a structural bottleneck.
Market Dynamics
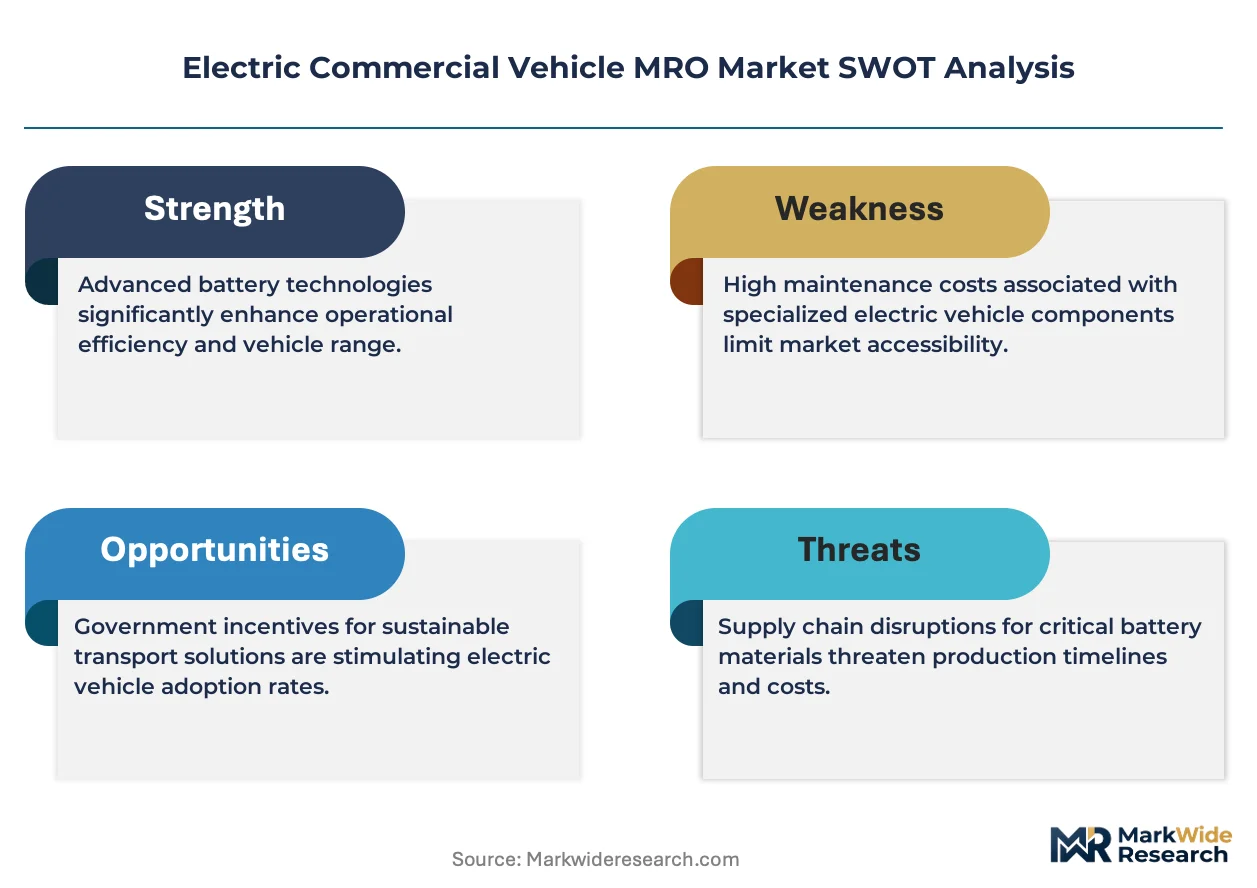
The Electric Commercial Vehicle MRO market faces a technician qualification bottleneck as ISO 6469-1 high-voltage safety certification requirements proliferate across European service networks. Fleet operators now demand predictive maintenance capabilities that legacy workshop infrastructure cannot support without capital-intensive retrofitting.
Growth Catalysts
- EU Green Deal Battery Management System mandates:Certification requirements under EU protocols are tightening technician qualification standards and consolidating service demand toward certified providers.
- Last-mile delivery fleet electrification:Urban logistics operators are expanding electrified truck servicing commitments as municipal zero-emission zones proliferate across German commercial corridors.
- Telematics-enabled predictive maintenance:Real-time battery state-of-health monitoring is displacing scheduled interval servicing and generating recurring software subscription revenue streams.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack replacement parts depend on Asian cell manufacturers, exposing European MRO networks to input cost volatility and extended lead times.
- High-voltage infrastructure capex requirements:Workshop retrofitting for 400-800V DC handling demands specialized lifting equipment and controlled-environment disassembly bays that independents cannot finance.
- REACH dielectric coolant handling protocols:Chemical safety regulations impose costly waste disposal and technician protective equipment mandates that compress margin pools on thermal system servicing.
Strategic Opportunities
- Captive fleet maintenance agreements:Long-term service contracts with logistics operators offer predictable revenue and lock out competing independent workshops.
- Battery remanufacturing and second-life applications:Cell degradation assessment capabilities position certified providers to capture value from end-of-first-life packs in stationary storage redeployment.
- Stuttgart-Mannheim hub specialization:Germany's commercial vehicle manufacturing cluster concentrates OEM technical support resources and trained technician labor pools.
Industry Challenges
- ISO 6469-1 certification scarcity:The collapsing pool of qualified independent technicians is creating structural service capacity constraints that OEM-affiliated networks are exploiting.
- Proprietary diagnostic algorithm lock-in:Battery state-of-health assessment depends on OEM-controlled software tools that restrict third-party service providers from performing warranty-compliant repairs.
- Legacy thermal management system incompatibility:Conventional coolant handling infrastructure cannot accommodate dielectric fluid properties, forcing complete workshop re-equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Commercial Vehicle MRO Market |
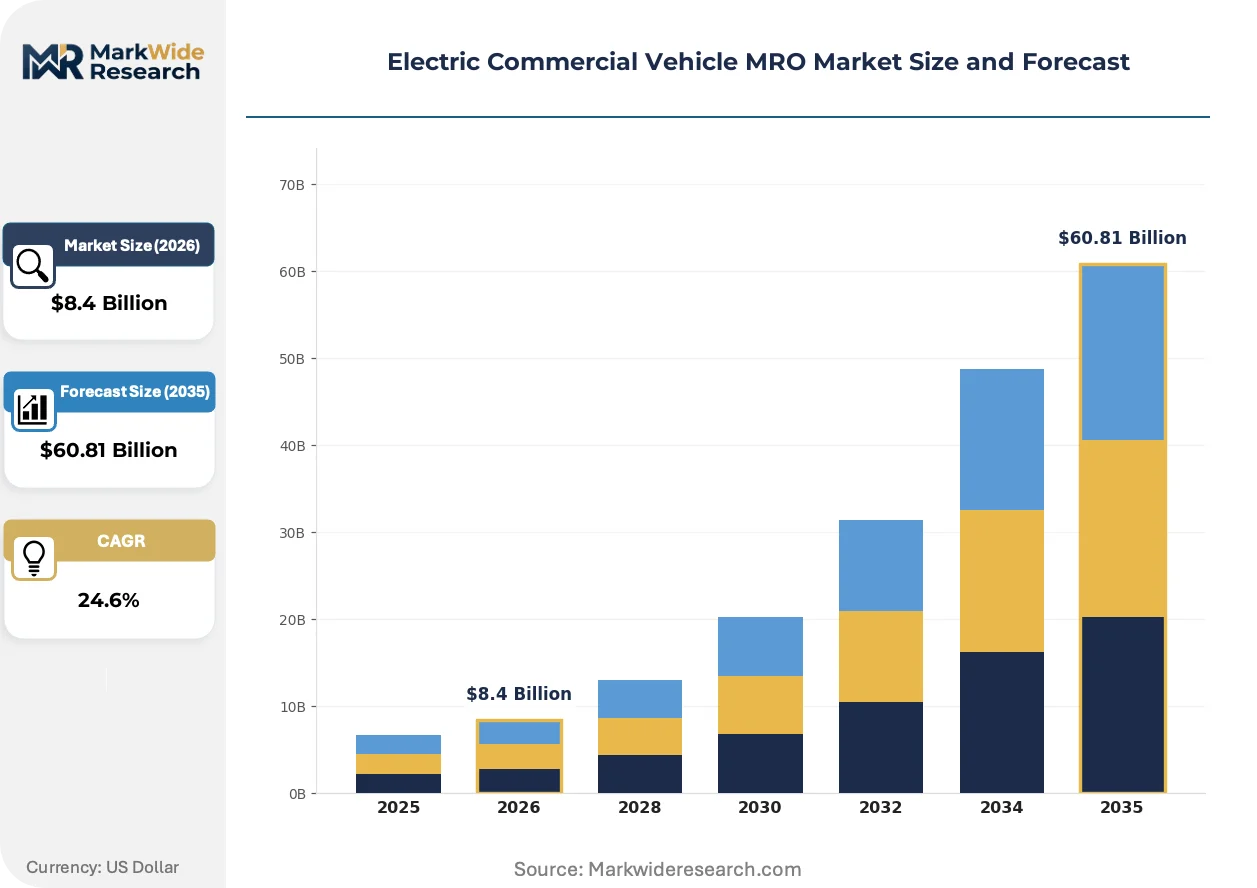
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $60.81 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repairs, Upgrades, Inspections Component: Battery Systems, Electric Motors, Charging Stations, Control Units Market Segment: Fleet Operators, Trucking Companies, Logistics Providers, Delivery Services Technology: Telematics, Battery Management Systems, Software Tools, Diagnostic Equipment |
| Companies Covered | Robert Bosch, Continental AG, ZF Friedrichshafen AG, Schaeffler Technologies, Daimler, Volvo, MAN Global, Allison Transmission, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Commercial Vehicle MRO Market Shifts & Advancements
Telematics integration is actively reshaping how fleet operators procure commercial vehicle maintenance, shifting value capture from labor hours to data-driven uptime guarantees. Three interconnected developments are restructuring competitive positioning in electric commercial vehicle servicing.
Cloud-connected battery diagnostics is bifurcating the MRO value chain between software-enabled predictive platforms and traditional reactive repair services. Fleet operators with centralized procurement functions are adopting subscription-based monitoring tools at accelerated pace. The technology is bifurcating margin pools toward algorithm developers and compressing commoditized mechanical labor returns.
Germany's KBA has incorporated high-voltage system integrity verification into periodic technical inspection standards for electric trucks operating on federal road networks. The regulation forces independent workshops to obtain OEM-recognized certification or cede inspection revenue to authorized service networks. Battery-electric bus operators in North Rhine-Westphalia and Bavaria are consolidating maintenance contracts toward KBA-certified providers with proprietary testing equipment.
Centralized national service agreements are displacing regional workshop relationships as procurement departments demand unified uptime SLAs across distributed fleet footprints. Logistics operators with pan-European coverage are unbundling maintenance from vehicle acquisition and awarding multi-year contracts to certified network providers. This concentration is most visible in German last-mile delivery operations where fleet standardization on single OEM platforms simplifies service procurement.
Electric Commercial Vehicle MRO Market Segmentation
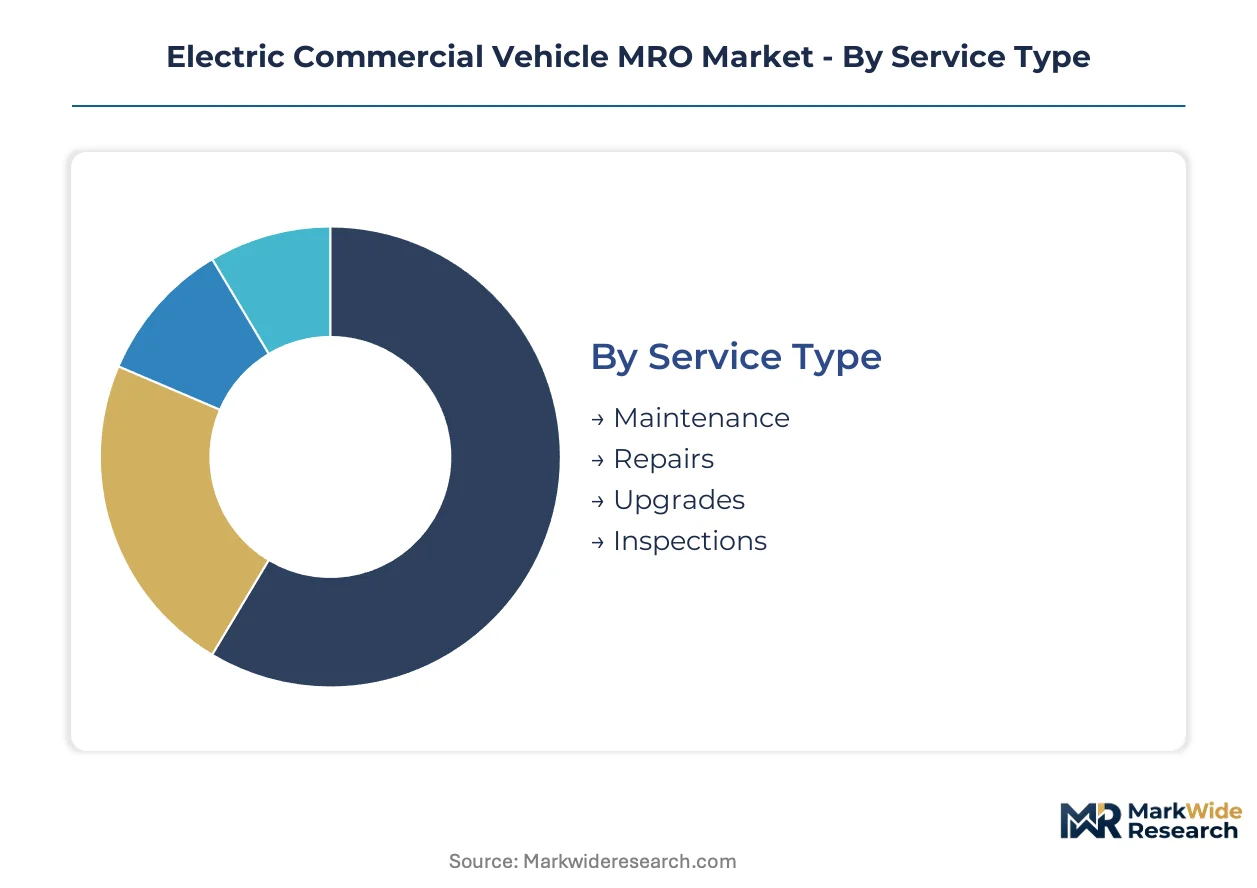
Electric commercial vehicle MRO segmentation reveals how regulatory compliance tiers concentrate purchasing power toward certified service providers. Fleet procurement departments structure maintenance contracts around component criticality and technician qualification requirements rather than traditional hourly labor rates.
Service Type:
EU Green Deal protocols and KBA inspection mandates differentiate service value based on voltage handling certification rather than mechanical complexity alone.
- Maintenance:Scheduled servicing of battery thermal management systems and high-voltage connection integrity checks requires ISO 6469-1 certified technicians. Demand clusters around Stuttgart-Mannheim logistics corridors where fleet operators centralize electrified van servicing under predictive uptime contracts.
- Repairs:Cell-level battery pack remediation and inverter replacement demand controlled-environment disassembly bays. REACH coolant handling protocols compress margins on thermal system repairs while concentrating revenue toward providers with proprietary diagnostic algorithms.
- Upgrades:Firmware updates and battery capacity expansion retrofits.
- Inspections:KBA-mandated high-voltage integrity verification for federal roadworthiness certification.
Established volume favors Maintenance; emerging adoption favors Inspections as regulatory deadlines tighten.
Component:
Margin pools stratify sharply between proprietary battery diagnostics and commoditized mechanical assemblies.
- Battery Systems:Lithium-ion pack state-of-health assessment and cell balancing operations command premium pricing through OEM-controlled software tools. Fleet operators in German last-mile delivery consolidate procurement toward providers with controlled-environment disassembly capabilities and remanufacturing partnerships.
- Electric Motors:Permanent magnet motor rewinding and bearing replacement services.
- Charging Stations:Onboard charger module diagnostics and DC fast-charging port servicing.
- Control Units:Power electronics and vehicle control module reprogramming.
Revenue concentration sits with Battery Systems; capability expansion targets Control Units as software-defined vehicle architectures mature.
Market Segment:
Procurement centralization patterns separate national fleet agreements from fragmented owner-operator relationships.
- Fleet Operators:Pan-European logistics providers with standardized electrified truck platforms award multi-year captive maintenance contracts. These agreements lock out independent workshops through proprietary telematics integration and unified SLA structures across distributed depot networks.
- Trucking Companies:Long-haul freight operators with mixed diesel-electric fleets.
- Logistics Providers:Third-party fulfillment operators managing shipper-owned vehicle pools.
- Delivery Services:Urban parcel distributors operating municipal zero-emission zone compliance fleets.
Contract value concentrates with Fleet Operators; volume growth accelerates fastest among Delivery Services responding to municipal access restrictions.
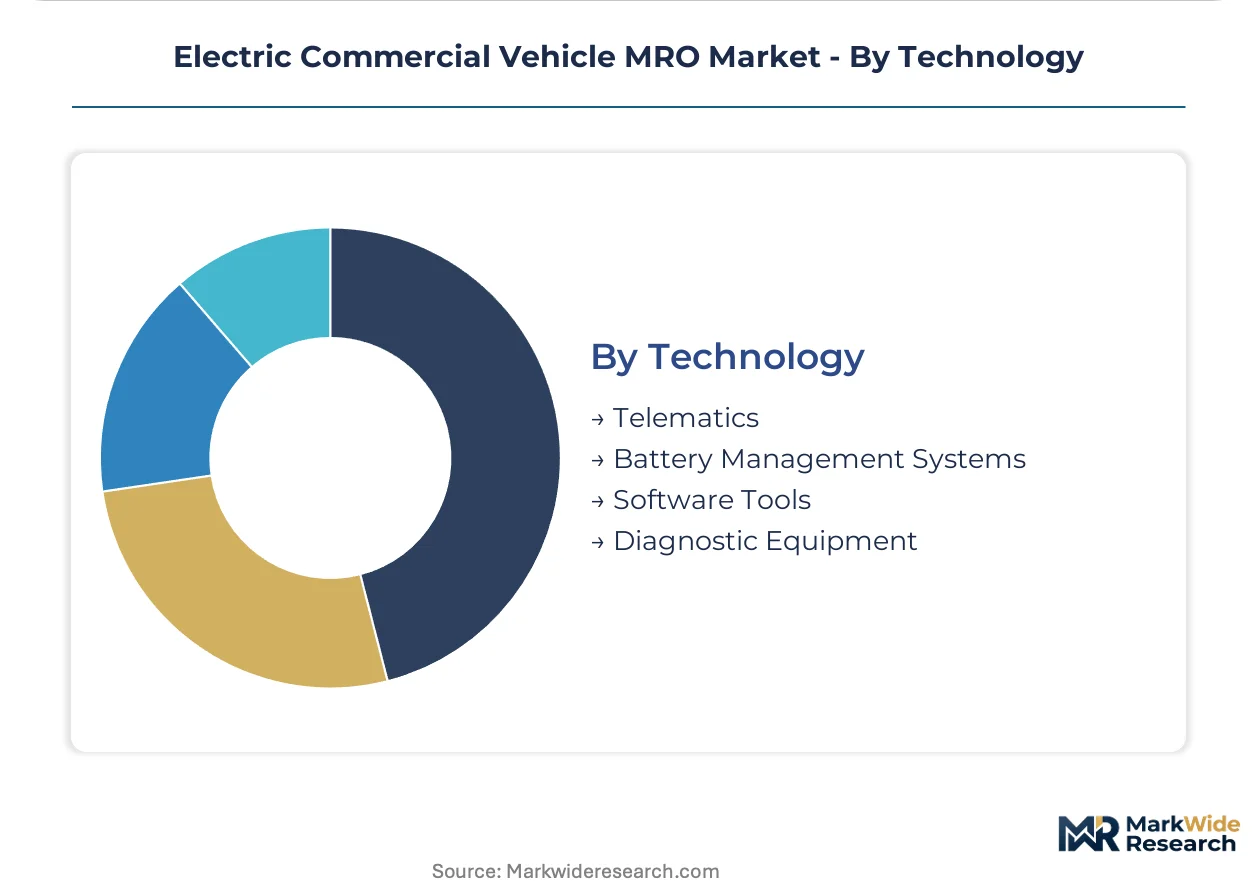
Technology:
Software-enabled predictive platforms are displacing reactive repair revenue toward recurring subscription models.
- Telematics:Cloud-connected battery state-of-health monitoring enables fleet operators to optimize charging cycles and preempt cell degradation failures. Real-time data streams from German commercial corridors support centralized procurement decisions that bypass regional workshop relationships.
- Battery Management Systems:OEM-controlled diagnostic algorithms restricting third-party warranty compliance.
- Software Tools:Predictive maintenance platforms and fleet management integration suites.
- Diagnostic Equipment:High-voltage testing tools specified in OEM warranty contracts.
Margin capture shifts toward Telematics; equipment sales concentrate with Diagnostic Equipment as workshop certification requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal emissions targets are accelerating workshop certification mandates across major commercial vehicle corridors, concentrating service demand toward high-voltage qualified providers in manufacturing clusters.
Germany
KBA inspection mandates now require high-voltage integrity verification for electric trucks on federal roads. The EU Green Deal Battery Management System protocols tighten technician qualification standards nationwide. Stuttgart-Mannheim logistics corridors concentrate OEM technical support resources and trained labor pools for last-mile fleet servicing.
United States
FCC equipment authorization rules govern diagnostic tool connectivity standards for connected commercial vehicles operating across US territories. Fleet operators in California and Texas are expanding electrified truck servicing commitments as state-level zero-emission regulations tighten. The Pacific Northwest and Midwest manufacturing belts host concentrated depot networks for predictive maintenance contract consolidation.
China
MIIT new energy vehicle standards mandate specialized high-voltage handling protocols for commercial EV servicing. GB standards for battery system safety shape workshop infrastructure investments across eastern manufacturing provinces. The Yangtze River Delta and Pearl River Delta clusters concentrate lithium-ion cell supply chains and remanufacturing capabilities for second-life applications.
France
ANSM and CNIL oversight intersects with EU REACH chemical handling protocols for dielectric coolant waste disposal in thermal system servicing. Paris-based fleet operators are consolidating maintenance contracts toward certified providers with proprietary diagnostic algorithms. The Île-de-France and Auvergne-Rhône-Alpes corridors anchor logistics electrification programs serving municipal zero-emission zones.
United Kingdom
Post-Brexit regulatory alignment with EU Green Deal emissions targets maintains pressure on technician certification standards. London's ultra-low emission zone expansion drives delivery fleet electrification and captive maintenance agreement demand. The Midlands and Southeast England manufacturing clusters concentrate high-voltage testing equipment distribution networks.
Electric Commercial Vehicle MRO Market Competitive Landscape
Player mix skews toward diversified automotive suppliers with established diagnostic equipment portfolios. Tiered competitive structure separates OEM-affiliated networks with proprietary software tools from independent workshops facing certification barriers. Strategic archetypes include integrated system suppliers, specialized high-voltage testing equipment fabricators, and telematics-enabled predictive maintenance platforms. Dominant competitive moves center on technician training program expansion and captive fleet maintenance contract capture.
Within the integrated supplier tier, Robert Bosch leverages its diagnostic equipment portfolio across European service networks, while Continental AG anchors its position through in-house production of specialized high-voltage testing tools. ZF Friedrichshafen AG occupies a position exemplifying the predictive maintenance archetype through fleet maintenance agreement extension. These three entities represent how established automotive suppliers are repositioning existing capabilities toward electrified commercial vehicle servicing requirements.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental AG |
| ZF Friedrichshafen AG |
| Schaeffler Technologies |
| Daimler |
| Volvo |
| MAN Global |
| Allison Transmission |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Dielectric coolant substitution for conventional thermal fluids is simultaneously relocating workshop equipment sourcing toward German and Chinese manufacturing clusters and compressing margin pools on thermal system servicing as REACH compliance costs accumulate.
Pricing Analysis
Certification level creates the primary spread between ISO 6469-1 qualified providers and uncertified independents. Three-tier pricing structure across OEM-authorized premium networks, certified third-party standard providers, and non-compliant economy workshops dominates the market. Cost compression in the economy tier is intensifying because KBA inspection mandates force fleet operators toward verified providers. Fleet operators with centralized procurement show lowest price sensitivity; independent owner-operators face acute margin pressure.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production for battery pack replacements. European MRO networks draw from Asian cell manufacturers, German diagnostic equipment fabricators, and domestic coolant chemical suppliers. Single-source vulnerability in high-voltage testing equipment creates procurement bottlenecks when OEMs restrict spare parts availability. Distribution runs through authorized dealer networks and direct fleet service agreements rather than open aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician credential scarcity now governs competitive access more than equipment scale, as ISO 6469-1 certification bottlenecks lock out two-thirds of legacy workshops from warranty-compliant revenue pools.
For Market Incumbents: Shield proprietary diagnostic algorithm access through OEM warranty contract exclusivity and accelerate technician training program expansion in Stuttgart-Mannheim corridors before labor scarcity hardens. Lock in captive fleet maintenance agreements with logistics operators to preempt third-party network penetration. Vertical integration into battery remanufacturing capabilities secures end-of-first-life pack value capture. For New Entrants and Emerging Players: EU Green Deal fast-track certification pathways for ISO 6469-1 compliance offer the most penetrable entry wedge. Target delivery services operators in municipal zero-emission zones where fleet electrification timelines outrun incumbent service capacity. Deploy telematics-enabled predictive maintenance platforms as the primary go-to-market angle to bypass capital-intensive workshop infrastructure requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive supplier portfolios seeking electrification pivot capital. Five-to-ten year viability hinges on software-defined vehicle architecture capture rather than mechanical servicing scale. Monitor KBA certification expansion timelines as the critical inflection signal for independent network consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Program Expansion | Robert Bosch and Continental AG are scaling ISO 6469-1 certification pipelines to capture qualified labor scarcity premiums. |
| Captive Fleet Maintenance Agreement | ZF Friedrichshafen AG secures multi-year contracts with pan-European logistics operators that lock out competing independents. |
| Battery Remanufacturing Capability Buildout | Certified providers with controlled-environment disassembly bays capture second-life stationary storage redeployment value. |
| Telematics Platform Integration | Cloud-connected battery state-of-health monitoring shifts revenue from labor hours to recurring software subscriptions. |
| High-Voltage Testing Equipment Production | In-house fabrication of specialized diagnostic tools specified in OEM warranty contracts anchors supplier positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fleet procurement departments, OEM aftermarket service heads, independent workshop owners, and diagnostic equipment manufacturers. Secondary validation drew from KBA inspection protocols, EU Green Deal regulatory filings, REACH chemical handling directives, and commercial vehicle production databases. Bottom-up service revenue estimates triangulated against top-down fleet electrification penetration models.
Across the analysis window, forecasts segmented by service type, component criticality, fleet operator scale, and technology adoption phase generated volume and value outputs. CAGRs derived from technician capacity expansion curves, regulatory deadline clustering, and predictive maintenance software penetration rates. Battery state-of-health degradation models and thermal system service interval compression informed segment-specific trajectory assumptions.
Decision-makers should treat outputs as directional under stable EU Green Deal implementation timelines and lithium-ion cell supply continuity; material deviation in either would warrant model refresh. Recalibration cycles align with KBA certification mandate expansions and fleet electrification program accelerations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Americas MAP Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
US Car Wash Services Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Automotive Retail Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Auto Leasing Services Market
Automotive Services
GCC Car Rental Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Car Wash Services Market