
 Driver's License Market | 2026-2036
Driver's License Market Size, Share, and Industry Trends Forecast 2026-2036
Driver's License Market Foresight
Public-private partnership financing for DMV infrastructure modernization is reshaping competitive dynamics in driver credentialing. J.J. Keller & Associates leverages its compliance management platform to anchor commercial driver qualification services across state lines. Foley Services sustains market presence through specialized driver file management and drug testing administration for fleet operators. DISA Global Solutions differentiates via integrated background screening and compliance monitoring tools that extend beyond traditional licensing functions.
A driver's license constitutes a government-issued credential certifying operator authorization for motorized vehicles, typically incorporating machine-readable zones, holographic security features, and embedded RFID or barcode elements for identity verification. The credential serves as both a traffic safety control mechanism and a de facto national identification document for commercial and civic transactions. Commercial and digital format segments command attention as commercial licensing ties directly to freight economy compliance burdens, while digital formats gain structural momentum from smartphone-based credential pilots in multiple states. Department of Motor Vehicles issuance retains dominant volume share, though automated renewal channels erode in-person dependency and shift operational cost structures.
The National Highway Traffic Safety Administration and Department of Homeland Security enforce REAL ID standards that dictate document authentication protocols and minimum issuance security requirements. State DMV regulators administer practical examination standards and medical certification rules that determine commercial driver eligibility and renewal frequency. Stakeholders must monitor federal-state coordination on digital identity interoperability standards and assess infrastructure investments against shifting credential format preferences.
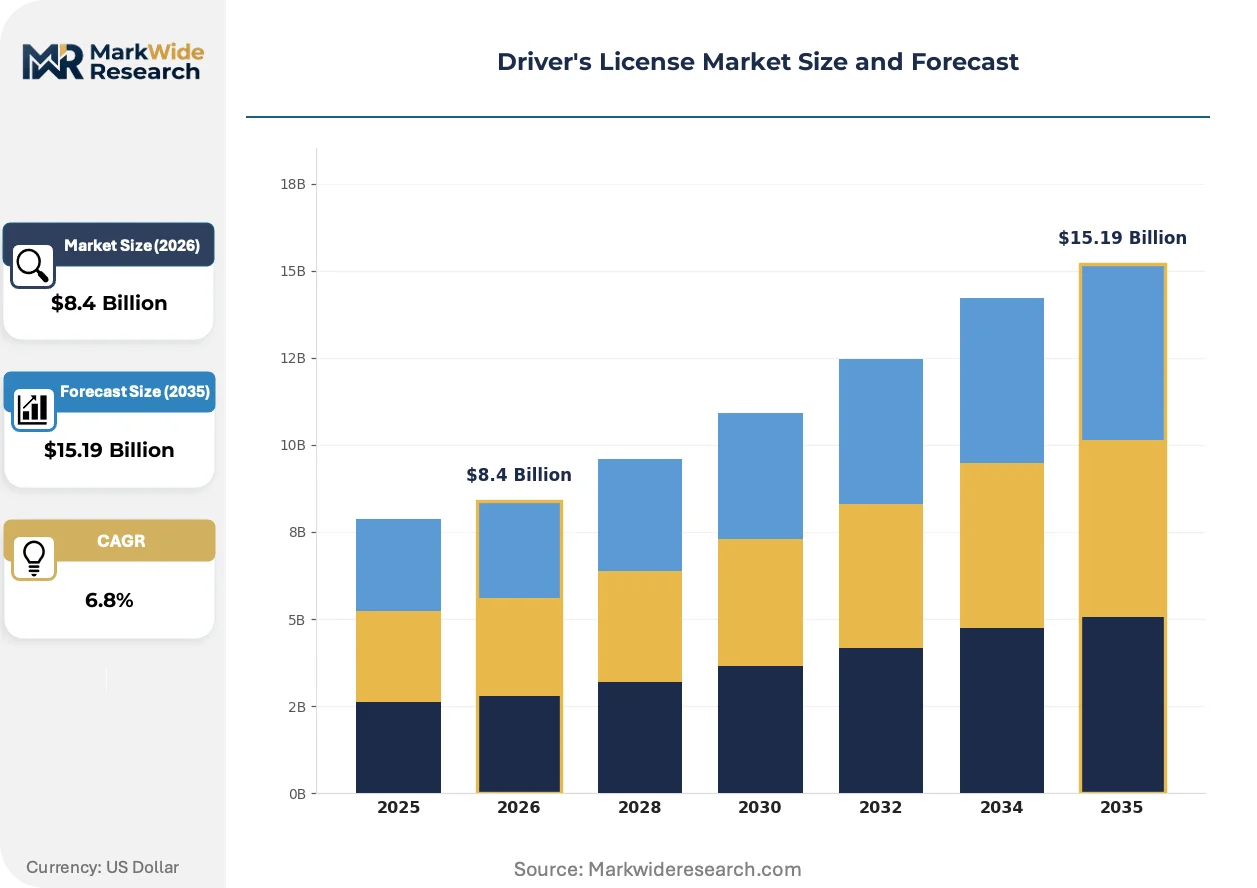
Market Dynamics
REAL ID enforcement deadlines are compressing state DMV procurement cycles and forcing simultaneous upgrades to physical card security, digital credential infrastructure, and backend identity verification systems.
Growth Catalysts
- REAL ID Act compliance mandates:The Department of Homeland Security's phased enforcement timeline compels state transportation agencies to replace legacy card production systems with federally certified equipment and document authentication protocols.
- Mobile wallet integration pilots:Smartphone-based digital driver's licenses in Arizona, Colorado, and Maryland demonstrate consumer acceptance and reduce in-person renewal burdens for state agencies.
- Commercial driver medical certification automation:Fleet operators demand integrated drug testing, background screening, and credential monitoring to satisfy Federal Motor Carrier Safety Administration compliance requirements.
Market Restraints
- Polycarbonate substrate supply concentration:Secure card material production clusters in Western Europe and East Asia expose state issuers to freight cost volatility and extended lead times for holographic overlay films.
- Legacy mainframe system dependency:Decades-old DMV database architectures impose integration friction with modern identity verification APIs and real-time credential status querying.
- Interstate digital credential interoperability gaps:Absence of unified technical standards between state motor vehicle agencies limits cross-border recognition of mobile driver's licenses for law enforcement verification.
Strategic Opportunities
- Underpenetrated rural DMV digitization:County-level motor vehicle offices in Montana, Wyoming, and North Dakota lack automated renewal kiosks and remote identity proofing capabilities that urban jurisdictions have deployed.
- Convergence of biometric enrollment and liveness detection:Facial recognition matching against centralized state databases enables remote renewal without physical office visits while satisfying NIST presentation attack detection standards.
- Commercial driver qualification file consolidation:Third-party administrators can bundle medical examiner certificate tracking, safety performance history, and substance abuse program participation into unified subscription services for trucking fleets.
Industry Challenges
- Skilled credential production technician shortages:Secure card manufacturing requires specialized expertise in laser engraving, holographic lamination, and quality control that vocational programs have not scaled to meet state procurement timelines.
- Multi-vendor system integration complexity:DMV modernization projects must synchronize card personalization hardware, identity proofing software, and legacy database middleware without disrupting daily issuance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver's License Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Commercial, Non-Commercial, Learner's, International Issuing Authority: Department of Motor Vehicles, State Agencies, Local Government, Federal Agencies Renewal Type: Online, In-Person, Automated, Mail Format: Card, Digital, Combined, Temporary |
| Companies Covered | J.J. Keller & Associates, Foley Services, Texas Department of Public Safety, Smart Way Driving School, Evilsizor & Associates, Texas Department of Motor Vehicles, DISA Global Solutions, ProDrivers, Driver iQ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver's License Market Shifts & Advancements
Credential format diversification is fragmenting procurement patterns as states pilot smartphone-based alternatives while maintaining physical card obligations, creating dual-track infrastructure demands.
Polycarbonate laser-engraved cards with tactile surface relief are replacing PVC substrates with printed overlays. State issuers in California, Texas, and New York have completed substrate conversions to meet REAL ID durability standards. This migration is rendering obsolete thermal retransfer printing equipment that dominated DMV procurement for two decades.
The Department of Homeland Security's REAL ID enforcement schedule mandates document authentication upgrades at every issuance point. State agencies must install front-office verification hardware capable of detecting fraudulent breeder documents. Commercial driver's license operations face the most compressed compliance timelines due to federal motor carrier credentialing requirements.
Fleet procurement departments are consolidating driver qualification services under single-vendor contracts that bundle licensing, medical certification, and compliance monitoring. Third-party administrators displace fragmented point solutions. Trucking operators in the Southeast and Midwest show the strongest preference for integrated subscription models over transactional service arrangements.
Driver's License Market Segmentation
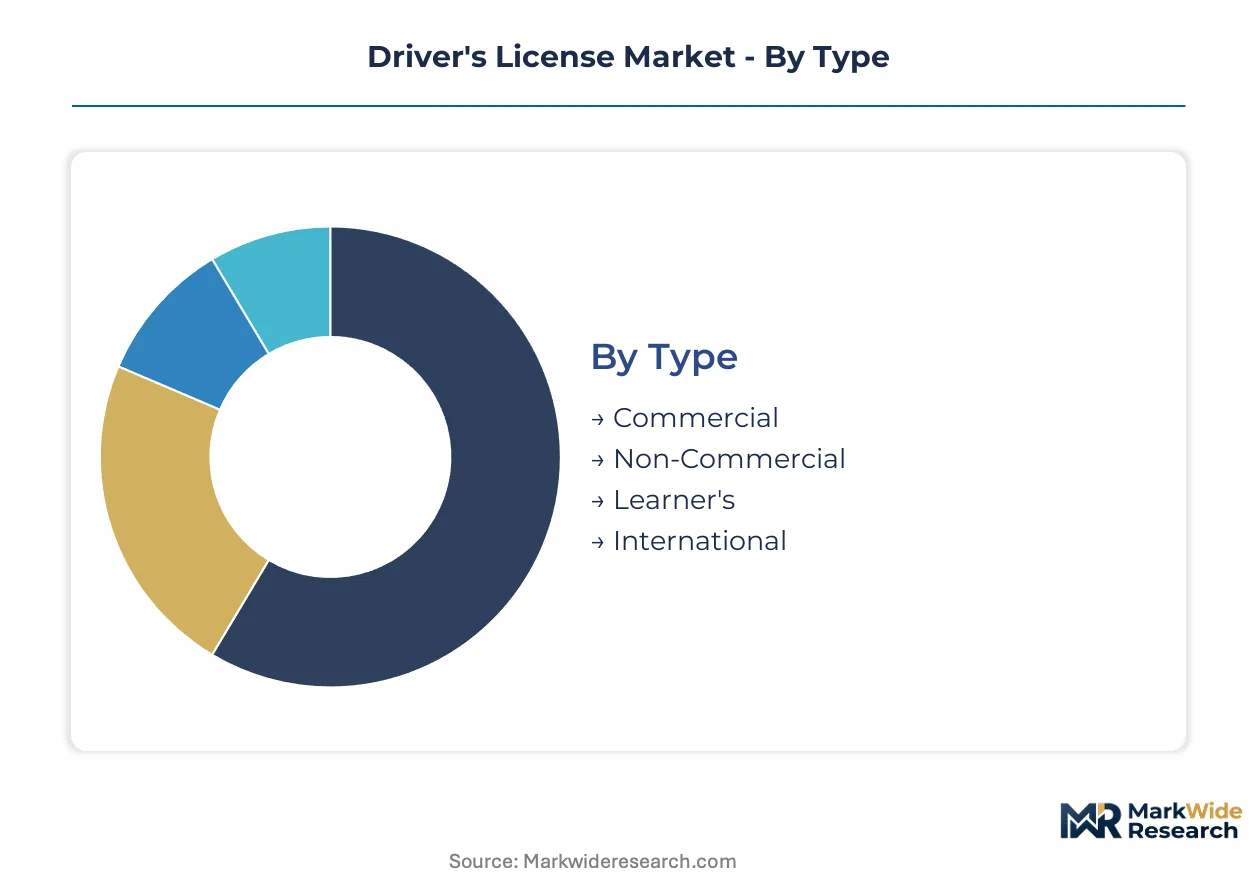
Credential segmentation in the driver's license market determines procurement priorities for state transportation agencies and shapes vendor specialization across physical card production, digital identity infrastructure, and compliance service delivery. Understanding format, authority, and renewal channel fragmentation enables targeted investment in REAL ID modernization and mobile wallet integration.
Type:
The use-case spectrum spans commercial freight operators requiring medical certification integration through casual motorists seeking standard operator authorization, with each tier imposing distinct compliance burdens and renewal frequencies on issuing authorities.
- Commercial:Federal Motor Carrier Safety Administration mandates govern medical examiner certificate tracking, drug testing administration, and safety performance history monitoring for interstate trucking operations. Fleet operators in Texas, California, and Florida concentrate procurement of bundled qualification file management services as enforcement intensifies.
- Non-Commercial:Standard passenger vehicle authorization constitutes volume majority across all state jurisdictions, with polycarbonate laser-engraved cards replacing PVC substrates to satisfy REAL ID durability standards. Urban DMV offices in New York, Illinois, and Pennsylvania process the highest renewal densities.
- Learner's:Restricted permits for novice operators require supervised driving hour logging and graduated licensing phase progression before full credential upgrade.
- International:Cross-border driving permits facilitate temporary vehicle operation for tourists and business travelers under reciprocal treaty agreements.
The dominant share belongs to Non-Commercial licenses, while Commercial licensing is closing the gap fastest through fleet consolidation of third-party administrator contracts.
Issuing Authority:
Administrative cost structures vary sharply across centralized state-level bureaucracies versus county-operated satellite offices, with automation investments diverging by fiscal capacity and population density.
- Department of Motor Vehicles:State-level centralized agencies in California, Texas, and New York manage high-volume card personalization facilities with dedicated secure production lines. These operations face compressed procurement cycles for REAL ID-compliant document authentication hardware and holographic overlay film sourcing from concentrated European and Asian suppliers.
- State Agencies:Transportation department subdivisions in Montana, Wyoming, and North Dakota operate with limited automated renewal kiosk deployment and rely more heavily on manual processing workflows.
- Local Government:County-level motor vehicle offices handle rural renewal volumes with restricted remote identity proofing capabilities.
- Federal Agencies:Military installation credentials and diplomatic operator permits follow distinct security clearance protocols separate from civilian state systems.
Department of Motor Vehicles retains dominant issuance volume, though State Agencies are expanding fastest through consolidation of fragmented county operations into unified digital platforms.
Renewal Type:
Channel migration patterns reflect generational technology adoption divides and pandemic-accelerated remote service expectations that permanently altered in-person dependency.
- Online:Web-based renewal portals with document upload and facial recognition liveness detection enable complete remote processing without physical office visits. Arizona, Colorado, and Maryland lead deployment of smartphone-integrated identity verification against centralized state databases.
- In-Person:Traditional counter service persists for first-time applicants, address changes, and complex medical certification scenarios requiring staff adjudication.
- Automated:Self-service kiosks in grocery retail and municipal buildings extend geographic access for rural populations beyond DMV branch locations.
- Mail:Paper-based renewal for elderly populations and jurisdictions with limited broadband infrastructure maintains operational redundancy.
Online renewal commands expanding share, while Automated channels are gaining traction fastest through retail partnership deployment in underserved counties.
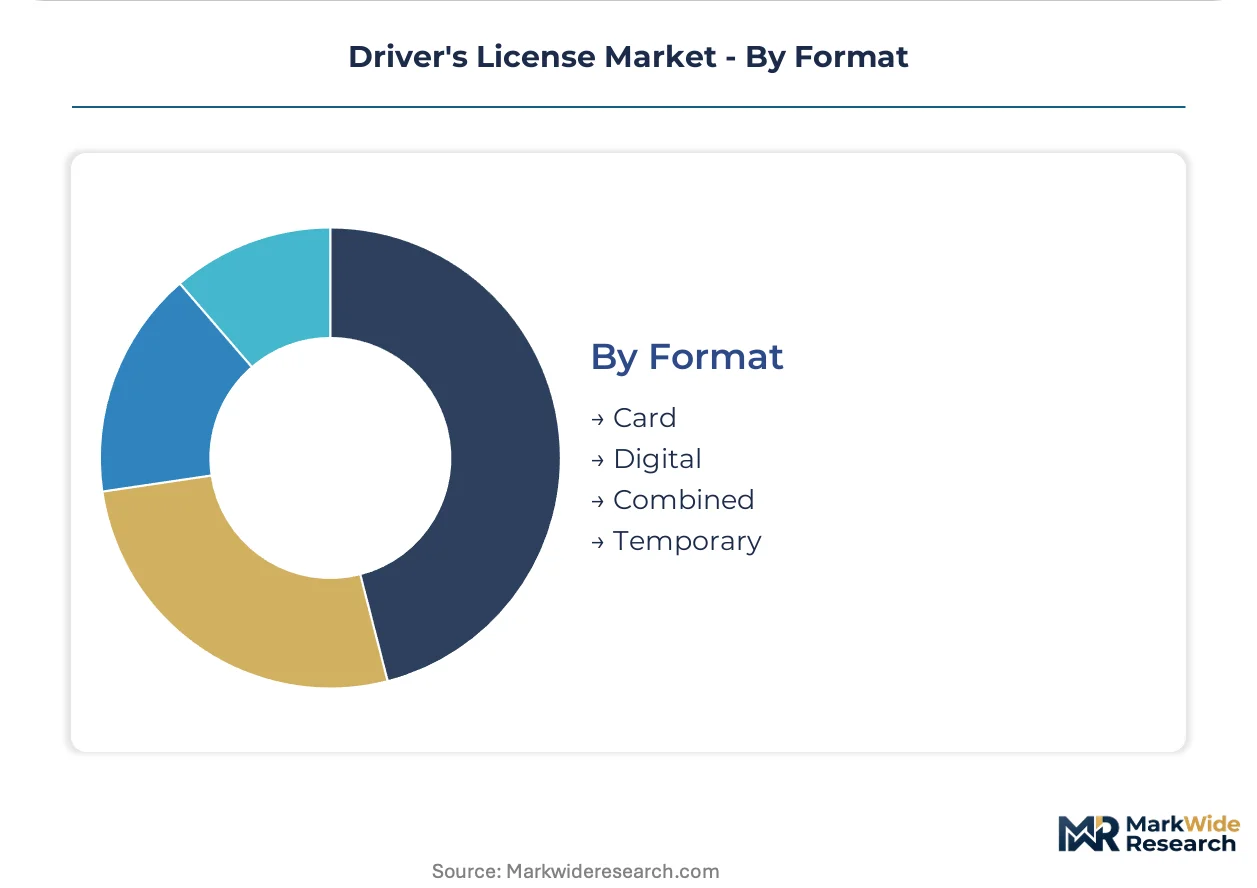
Format:
Physical-digital hybrid obligations create dual-track infrastructure demands as states maintain card production obligations while piloting smartphone credential alternatives.
- Card:Polycarbonate laser-engraved substrates with tactile surface relief and embedded RFID elements satisfy REAL ID physical presentation requirements. California, Texas, and New York completed substrate conversions rendering obsolete two decades of thermal retransfer printing equipment.
- Digital:Smartphone-based mobile driver's licenses integrate with Apple Wallet and Google Wallet for age verification and traffic stop credential presentation. Interstate interoperability gaps limit law enforcement cross-border recognition pending unified technical standard adoption.
- Combined:Parallel physical and digital credential issuance satisfies both federal compliance mandates and consumer convenience preferences.
- Temporary:Paper interim documents bridge processing gaps during card personalization or address verification delays.
Card format retains dominant issuance volume, while Digital credentials are expanding most quickly through mobile wallet integration pilots and reduced in-person renewal burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Homeland Security's REAL ID enforcement timeline has compressed state procurement cycles across multiple jurisdictions, forcing simultaneous upgrades to physical card security and digital credential infrastructure.
United States
State DMVs in California, Texas, and New York manage high-volume polycarbonate card personalization facilities with dedicated secure production lines. The REAL ID Act mandates document authentication hardware upgrades at every issuance point. Los Angeles County processes the highest renewal densities while rural Montana and Wyoming offices lag in automated kiosk deployment.
Germany
The KBA enforces stringent driver qualification standards for commercial freight operators moving through the Rhine-Ruhr logistics corridor. EU digital identity wallet interoperability standards are reshaping credential format specifications. Bavaria's motor vehicle authorities pilot smartphone-integrated identity verification against centralized federal databases.
India
The Ministry of Road Transport and Highways digitizes learner's permits and commercial licenses through the Sarathi platform. State transport departments in Maharashtra and Gujarat lead smart card substrate conversions. Bangalore's tech cluster supplies facial recognition liveness detection systems for remote renewal portals.
Japan
METI coordinates digital driver's license pilots integrating with Apple Wallet and Google Wallet for age verification scenarios. Prefectural police administer practical examination standards that determine commercial driver eligibility. Tokyo's metropolitan license center completed substrate migration to polycarbonate laser-engraved cards.
United Kingdom
The DVLA manages online renewal portals with document upload capabilities that reduce in-person dependency for standard passenger vehicle authorizations. GDPR compliance requirements shape biometric enrollment protocols for remote identity proofing. Greater Manchester's licensing offices deploy automated kiosks in municipal buildings and grocery retail locations.
Driver's License Market Competitive Landscape
Channel-controlling players compete with product-specialist players across credential production, compliance administration, and digital identity infrastructure. The vendor base clusters around three strategic archetypes: secure card manufacturers with polycarbonate laser engraving capabilities, third-party driver qualification administrators bundling medical certification and drug testing services, and software vendors supplying identity verification APIs and mobile wallet integration. Dominant competitive moves include backward integration into holographic overlay film sourcing and geographic expansion through state DMV procurement contract consolidation.
Among compliance-focused service providers, J.J. Keller & Associates and Foley Services exemplify the bundled driver qualification administration archetype, while DISA Global Solutions anchors the integrated background screening and compliance monitoring tier. These three companies sit within the commercial licensing ecosystem where fleet operators demand consolidated subscription services over fragmented point solutions.
| Leading Market Players |
|---|
| J.J. Keller & Associates |
| Foley Services |
| Texas Department of Public Safety |
| Smart Way Driving School |
| Evilsizor & Associates |
| Texas Department of Motor Vehicles |
| DISA Global Solutions |
| ProDrivers |
| Driver iQ |
| Others |
Supply & Pricing Matrix
Overcapacity in European polycarbonate substrate production is pressuring holographic overlay suppliers to absorb freight volatility while state DMVs consolidate procurement into multi-year framework agreements. This utilization squeeze compresses margins for secure card material vendors and accelerates backward integration by issuers seeking captive supply of laser-engraving equipment.
Pricing Analysis
REAL ID certification tier creates the primary spread between basic PVC replacement cards and polycarbonate laser-engraved substrates with embedded RFID. State DMVs operate on per-unit transactional pricing for physical credentials, while commercial fleet operators favor subscription-based bundled services for driver qualification administration. Price differentiation rests on substrate durability grade and holographic security feature complexity. Cost compression in standard-grade card production is intensifying because thermal retransfer printing equipment obsolescence has flooded secondary markets. Rural state agencies exhibit highest price sensitivity due to constrained modernization budgets, while California and Texas DMVs prioritize security feature density over unit cost.
Supply Chain Analysis
Polycarbonate resin feedstock concentrates in Germany, Belgium, and South Korea, with holographic overlay film production clustering in Western Europe and East Asia. Secure card manufacturing draws from specialized laser-engraving optics, tamper-evident laminates, and RFID inlay components. Single-source vulnerability in holographic master origination equipment exposes state issuers to extended lead times during REAL ID compliance surges. Distribution runs through state-procurement frameworks with designated secure production facilities rather than open-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Credential format fragmentation is splintering demand across physical card security upgrades, digital wallet infrastructure, and compliance service bundling—creating specialist niches for vendors with discrete technical capabilities rather than full-stack dominance.
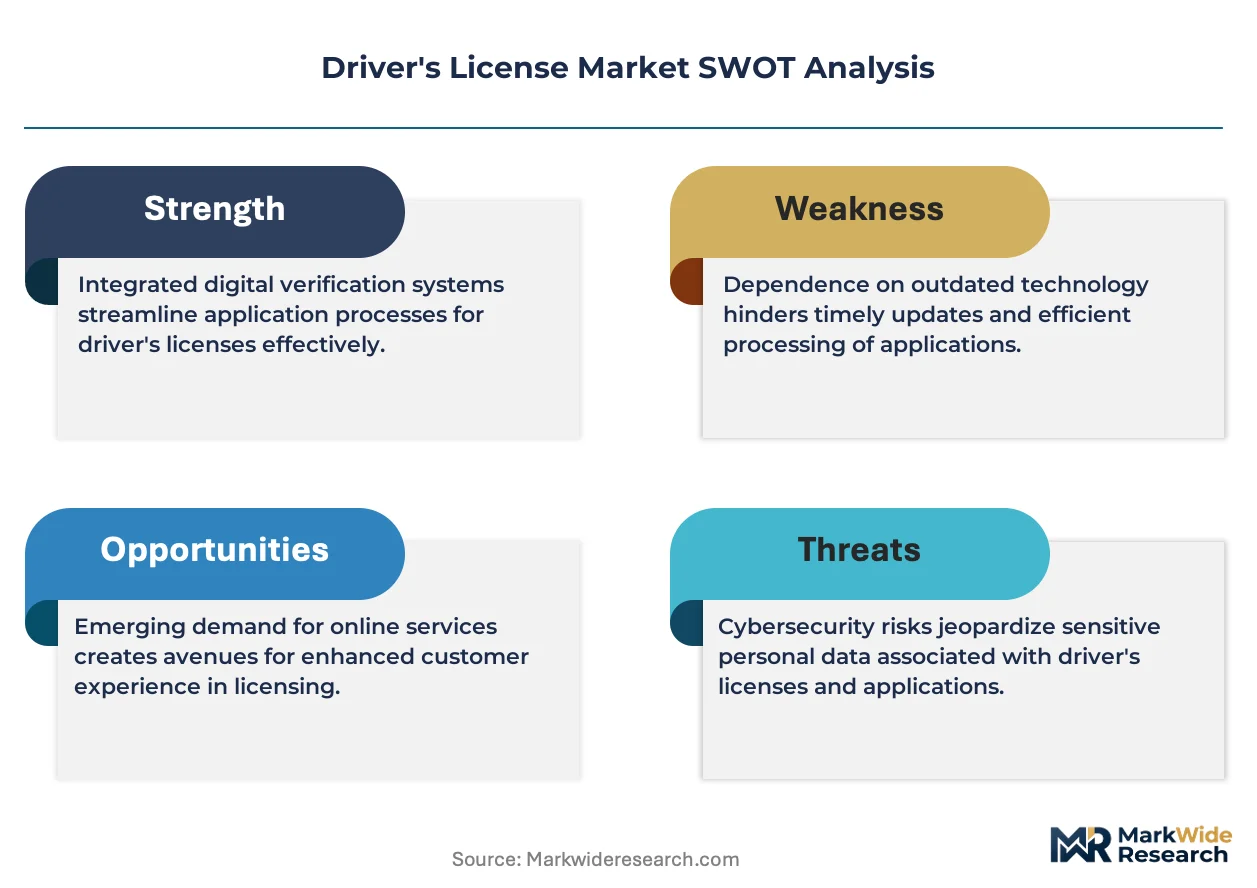
For Market Incumbents: Build switching-cost moats through embedded workflow integration in DMV legacy systems. Incumbents should deepen backward integration into polycarbonate substrate sourcing to hedge European supply concentration, while accelerating certification investment in NIST-compliant facial recognition liveness detection. The threat of mobile wallet disintermediation demands preemptive API standardization to maintain issuance system relevance. For New Entrants and Emerging Players: Pursue rural DMV digitization white space in Montana, Wyoming, and North Dakota where automated renewal kiosk penetration lags urban benchmarks. New entrants should target county-level motor vehicle offices with remote identity proofing solutions, leveraging cloud-native architectures to bypass legacy mainframe integration burdens. A channel partnership go-to-market with grocery retail kiosk networks offers fastest geographic coverage. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital credential infrastructure as smartphone-based pilots require sustained R&D before revenue conversion. Long-term viability favors acquisition targets with established state DMV procurement relationships and compliant secure production facilities. The signal to watch is federal-state coordination on mobile driver's license interoperability standards, which would trigger consolidation of fragmented point-solution vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | German and Belgian polycarbonate sourcing secures holographic overlay cost stability for state issuers. |
| Mobile Wallet API Standardization | Apple Wallet and Google Wallet integration reduces Arizona and Colorado DMV in-person renewal burdens. |
| Biometric Enrollment Platform Launch | NIST-compliant liveness detection enables remote renewal without physical office visits. |
| Commercial Fleet Subscription Consolidation | Texas and California trucking operators prefer bundled medical certification and drug testing administration. |
| Rural Kiosk Distribution Partnership | Montana and Wyoming county offices gain automated renewal access through grocery retail networks. |
Research Methodology
A standing panel of state DMV procurement directors, secure card production facility managers, commercial fleet compliance officers, and identity verification software architects provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation against Department of Homeland Security REAL ID implementation guidance, National Highway Traffic Safety Administration motor carrier safety data, state transportation agency budget disclosures, and Federal Motor Carrier Safety Administration enforcement statistics. Bottom-up credential volume modeling and top-down infrastructure spending analysis were triangulated against vendor revenue disclosures.
Scenario-bracketing framed projections across conservative, baseline, and accelerated digital adoption paths over the analysis window. Segmentation dimensions modeled include credential format, issuing authority tier, renewal channel, and commercial versus non-commercial use case. CAGRs were derived from polynomial trend fitting against historical procurement cycles and regulatory deadline impacts. Forecast inputs incorporated polycarbonate substrate pricing indices and mobile wallet pilot expansion rates.
Sensitivities concentrate around REAL ID enforcement timeline adjustments, polycarbonate supply chain disruptions, and interstate digital credential interoperability standard delays. Forecasts reflect documented assumptions regarding state budget allocations and technology adoption curves. Quarterly review of federal-state coordination announcements and secure card material spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Mobile Car Wash Service Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Car Rental Business Market
Automotive Services
Automotive Collision Repair Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Armored Transportation Services Market
Automotive Services
Americas MAP Market
Automotive Services
Europe Car Wash Market
Automotive Services
Automotive Engineering Services Market
Automotive Services
Global Street Sweeper Brushes Market