
 GCC Car Rental Market | 2026-2036
GCC Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
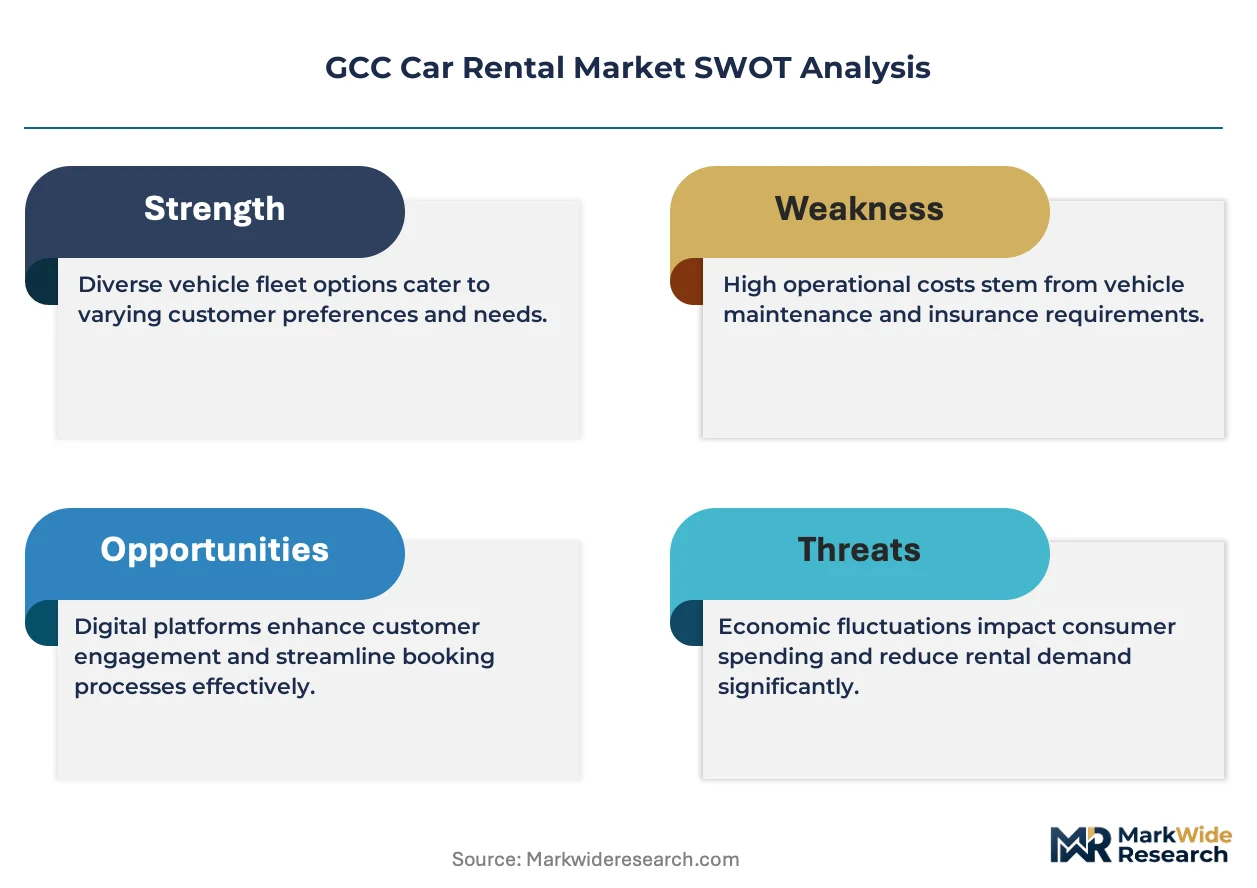
GCC Car Rental Market Analysis
Airport-based fleet deployment is tilting toward digital-first distribution as operators restructure counter presence. Sixt SE leverages its premium positioning across Abu Dhabi and Dubai terminals to sustain yield premiums. Enterprise Holdings anchors corporate account volumes through long-term leasing contracts with oil and gas firms. Ekar differentiates via its app-based hourly rental model targeting urban residents in Riyadh and Jeddah.
GCC car rental denotes the short-term commercial provision of motorized vehicles across Gulf Cooperation Council member states, typically governed by mileage limits, insurance bundles, and fuel policies structured around daily or weekly tariffs. The sector serves transit needs for business travelers, tourists, and temporary residents lacking permanent vehicle ownership in markets characterized by extreme summer temperatures that accelerate fleet depreciation cycles. Leisure-oriented short-term rentals dominate transaction volumes at airport nodes, while corporate long-term contracts capture superior margin pools through negotiated fleet maintenance inclusions. SUV and luxury vehicle categories command premium positioning in Saudi Arabia and UAE markets where consumer preference favors elevated cabin specifications for desert terrain traversal.
Saudi Arabia's Public Transport Authority and UAE's Roads and Transport Authority enforce commercial vehicle licensing standards that mandate periodic safety inspections and operator insurance minimums, elevating compliance costs for smaller fleet holders. The EU Green Deal's extraterritorial influence on Gulf sovereign wealth investment priorities is channeling capital toward electric vehicle procurement mandates in Dubai and Riyadh municipal fleets. Stakeholders must monitor how VAT harmonization discussions across Bahrain, Oman, and Kuwait reshape cross-border fleet utilization economics.
Market Dynamics
Fleet electrification mandates across Dubai, Riyadh, and Abu Dhabi are forcing operators to restructure procurement timelines and capital allocation models around battery-electric vehicle deployment.
Growth Catalysts
- SFDA commercial licensing standards:Saudi Arabia's Public Transport Authority mandates periodic safety inspections and insurance minimums that professionalize the sector and squeeze informal operators from the market.
- Desert terrain SUV preference:Consumer demand for elevated cabin specifications in Saudi Arabia and UAE markets drives premium positioning and higher per-vehicle yields for fleet holders.
- EU Green Deal capital channeling:Extraterritorial influence on Gulf sovereign wealth priorities is redirecting investment toward electric vehicle procurement mandates in municipal fleet contracts.
Market Restraints
- Extreme summer temperature depreciation:Sustained heat above 45°C accelerates tire degradation, battery performance loss, and air conditioning system failure, compressing vehicle residual values.
- Cross-border VAT harmonization friction:Divergent tax treatment across Bahrain, Oman, and Kuwait complicates fleet utilization economics for operators running multi-country vehicle pools.
- Corporate long-term contract concentration:Oil and gas firms anchor volume through negotiated maintenance inclusions, locking smaller players out of the highest-margin revenue pools.
Strategic Opportunities
- Oman leisure tourism infrastructure:Muscat International Airport expansion and resort corridor development create underpenetrated nodes for short-term rental deployment outside UAE-Saudi concentration.
- App-based hourly urban mobility:Smartphone-native distribution models targeting Riyadh and Jeddah residents for intra-city trips bypass traditional airport-centric transaction structures.
- Dubai Roads and Transport Authority EV mandates:Municipal fleet electrification targets create guaranteed offtake agreements for early-moving rental operators with charging infrastructure.
Industry Challenges
- EV technician certification gaps:High-voltage battery maintenance and diagnostics training lags behind fleet electrification timelines, constraining in-house service capacity.
- Legacy reservation system integration:Incumbent operators face friction merging real-time vehicle telemetry from connected fleets with decades-old counter-based booking architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Car Rental Market |
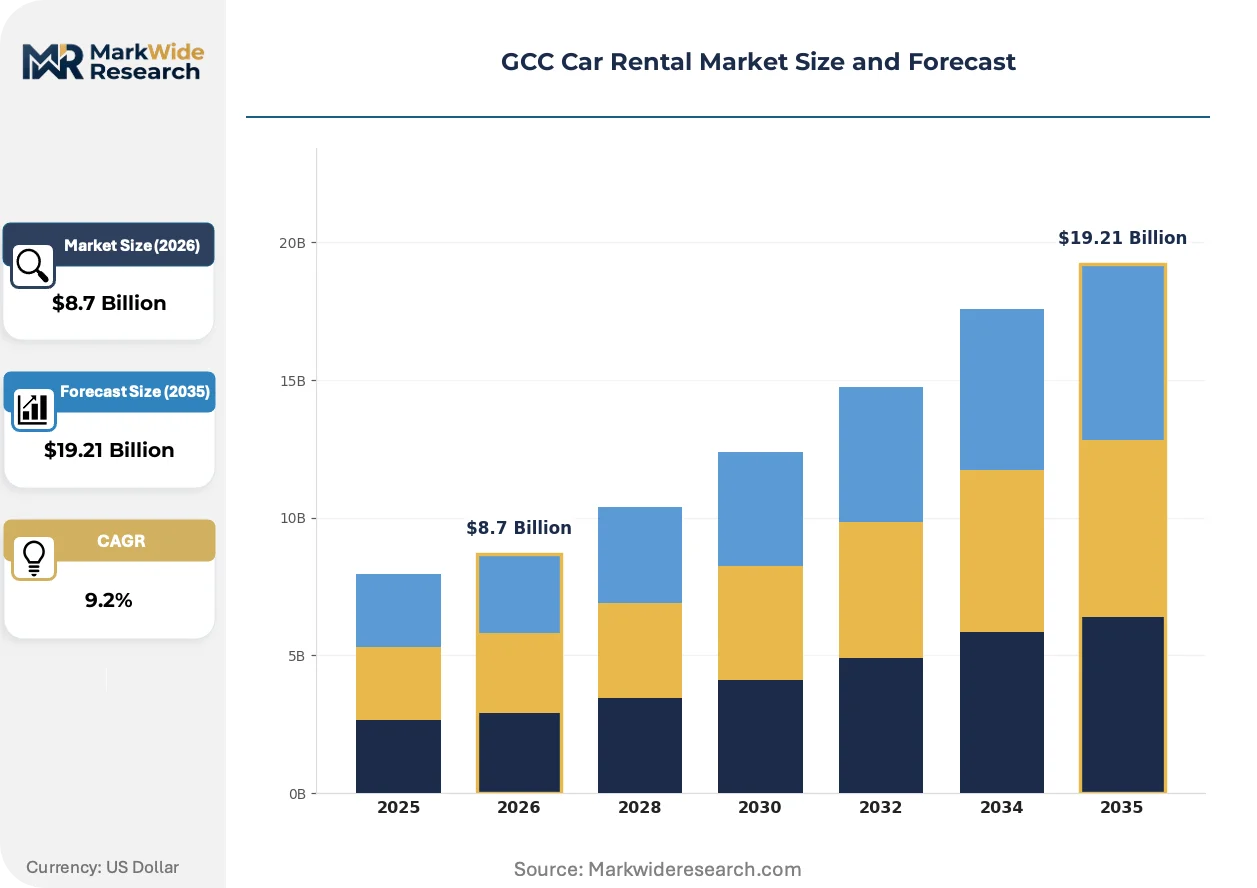
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Leisure, Business, Long-term, Short-term Vehicle Type: Sedan, SUV, Van, Luxury Customer Type: Tourists, Corporates, Residents, Government Distribution Channel: Online, Phone, Travel Agents, Kiosks |
| Companies Covered | Sixt SE, Yelo, Hertz Corporation, Fast Rent a Car, Ekar, Enterprise Holdings, Thrifty, KAYAK, Avis Budget Group, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Car Rental Market Emerging Trajectories
Digital distribution architectures are displacing physical counter presence at airport nodes, while regulatory pressure and shifting traveler expectations compress traditional rental transaction models.
Telematics-enabled fleet management platforms are digitizing vehicle utilization tracking, maintenance scheduling, and dynamic pricing for operators. Corporate travel managers in Saudi Arabia and UAE are adopting these systems fastest, demanding real-time availability visibility. The technology is digitizing how yield management decisions are executed, compressing the gap between demand spikes and price adjustments from days to hours.
The EU Green Deal's extraterritorial influence on Gulf sovereign wealth investment priorities is channeling capital toward electric vehicle procurement mandates. Dubai's Roads and Transport Authority and Riyadh municipal authorities have established EV fleet percentage targets that reshape operator procurement calendars. Short-term leisure rental segments face the steepest compliance timelines as airports prioritize visible sustainability credentials.
Hourly and subscription-based vehicle access models are fragmenting traditional daily-rate structures. Urban residents in Jeddah and Riyadh increasingly bypass airport counters for smartphone-native booking of vehicles by the hour. This behavioral shift concentrates transaction volume in dense metropolitan zones, forcing operators to redistribute fleet deployment away from terminal-based concentration.
GCC Car Rental Market Segmentation
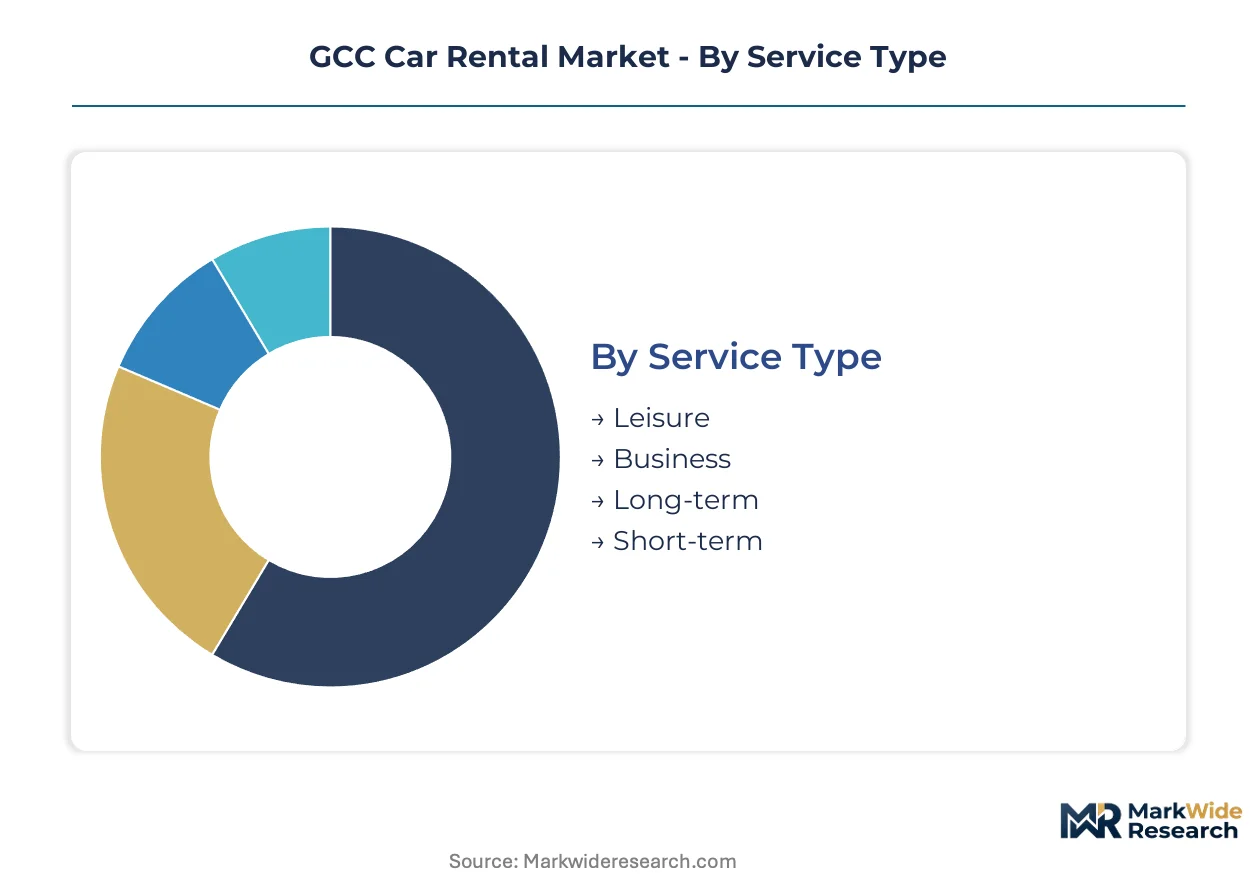
Segmentation in the GCC car rental market reveals how procurement patterns diverge across customer missions and vehicle specifications. Fleet operators configure procurement calendars and yield management systems around these divides.
Service Type:
Cost tier differentiation separates transactional daily rentals from negotiated corporate commitments with divergent margin structures.
- Leisure:Short-duration rentals for tourists and weekend travelers concentrate at Dubai International Airport and Jeddah terminals. Demand spikes during winter tourism seasons and religious pilgrimage periods compress pricing windows.
- Business:Corporate travelers require guaranteed availability and streamlined billing protocols. SFDA licensing standards professionalize this tier, squeezing informal operators from premium account pools.
- Long-term:Oil and gas firms anchor volume through maintenance-inclusive contracts capturing superior margins.
- Short-term:Hourly and daily transactions dominate transaction counts but yield lower per-rental profitability.
Leisure holds installed capacity. Business is rotating up the share rankings.
Vehicle Type:
Application-specific requirements across desert terrain and urban corridors shape fleet composition priorities.
- SUV:Elevated cabin specifications and four-wheel-drive configurations address consumer preference for desert terrain traversal in Saudi Arabia and UAE markets. Premium positioning commands higher per-vehicle yields.
- Luxury:High-specification vehicles serve executive transport and prestige tourism segments in Abu Dhabi and Dubai. EU Green Deal capital channeling is redirecting procurement toward electric variants in this tier.
- Sedan:Standard fleet workhorse for cost-conscious business travelers and residents.
- Van:Group transport and logistics applications serve family tourism and light commercial needs.
SUV holds installed capacity. Luxury is rotating up the share rankings.
Customer Type:
Volume concentration patterns distinguish transient demand from recurring revenue streams with divergent loyalty economics.
- Tourists:Seasonal inbound travelers from Europe and Asia-Pacific drive peak utilization at airport nodes. Dubai International Airport expansion concentrates this demand geographically.
- Corporates:Negotiated master service agreements with oil and gas firms lock in predictable fleet utilization across Riyadh and Dammam.
- Residents:Smartphone-native urban populations in Jeddah increasingly bypass airport counters for app-based hourly access.
- Government:Municipal fleet electrification mandates in Dubai and Riyadh create guaranteed offtake agreements for compliant operators.
Corporates holds installed capacity. Residents is rotating up the share rankings.
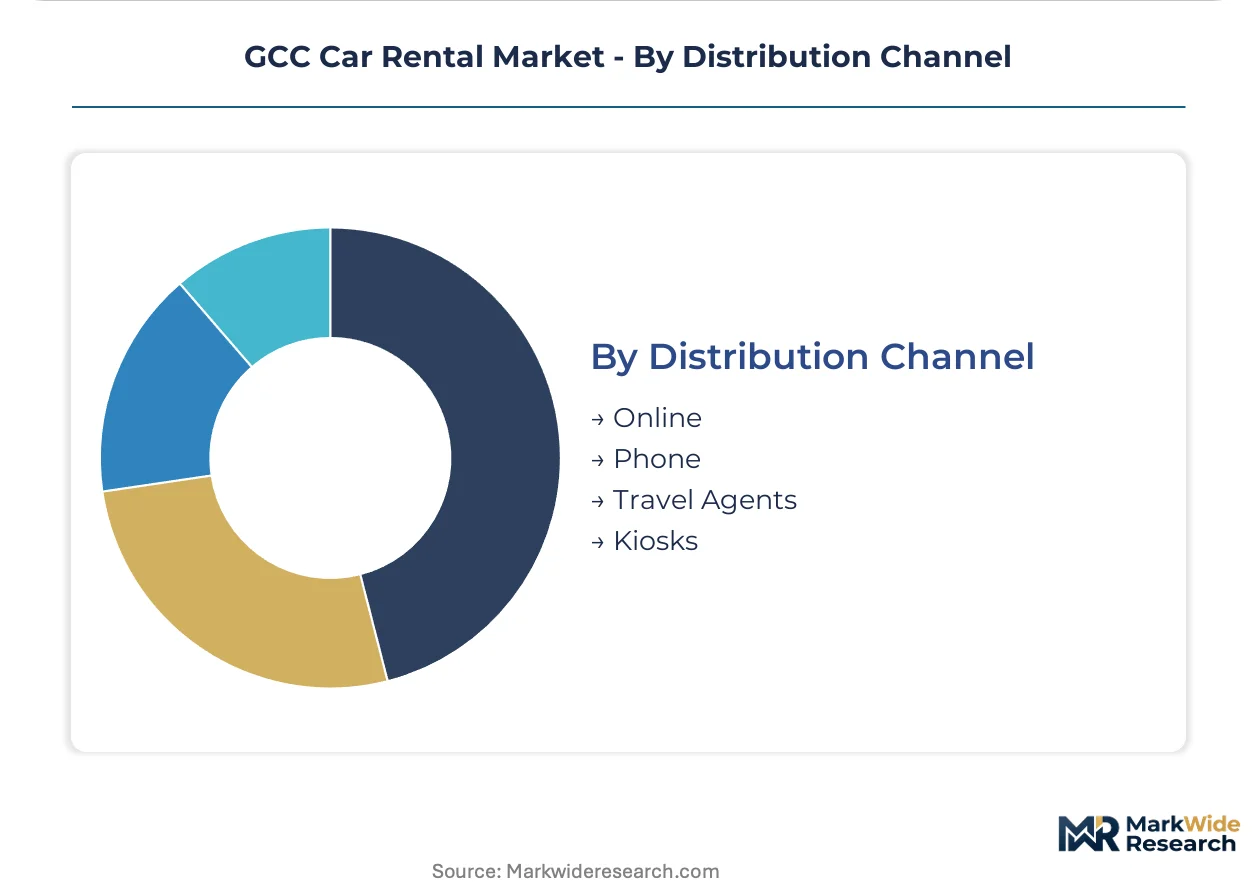
Distribution Channel:
Customer type and transaction urgency dictate channel preference with clear generational and geographic stratification.
- Online:Smartphone-native booking platforms displace physical counter presence fastest among urban residents. Ekar and similar operators leverage this channel for hourly rental models in dense metropolitan zones.
- Travel Agents:Package tourism intermediaries concentrate leisure bookings from European source markets into Dubai and Muscat corridors.
- Phone:Legacy channel persists among corporate travel managers requiring negotiated rate verification.
- Kiosks:Airport terminal presence sustains walk-up demand from unplanned arrivals.
Online holds installed capacity. Travel Agents is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UAE operators command yield premiums at Dubai International Airport while Saudi fleet holders absorb higher depreciation cycles across Riyadh's extreme summer climate. This pricing-power asymmetry reflects divergent tourism infrastructure maturity and regulatory enforcement intensity across Gulf markets.
United Arab Emirates
Dubai International Airport concentrates short-term leisure demand through expanded terminal capacity and cruise-ship connectivity. Dubai's Roads and Transport Authority mandates fleet electrification percentages that accelerate operator procurement timelines. Abu Dhabi terminal operators leverage premium positioning to sustain higher per-vehicle yields than regional peers.
Saudi Arabia
Riyadh and Jeddah urban corridors drive app-based hourly rental adoption among smartphone-native residents. Saudi Arabia's Public Transport Authority enforces commercial licensing standards that professionalize the sector and elevate compliance costs. Eastern Province oil and gas clusters anchor corporate long-term contracts with maintenance-inclusive terms.
Kuwait
Corporate account concentration in Kuwait City sustains negotiated rate structures for business travelers. Divergent VAT treatment relative to UAE and Saudi Arabia complicates cross-border fleet utilization economics. Airport terminal presence at Kuwait International Airport maintains walk-up demand from unplanned arrivals.
Oman
Muscat International Airport expansion and resort corridor development create underpenetrated nodes for short-term rental deployment. The country's national transport regulator enforces commercial vehicle safety inspections that elevate operational standards. Salalah's seasonal tourism peaks during monsoon months concentrate fleet utilization windows.
Qatar
Hamad International Airport transit passenger volumes sustain premium-tier vehicle demand for short-duration rentals. Government procurement mandates prioritize fleet electrification for municipal contracts. Doha urban development concentrates corporate account activity in the central business district.
GCC Car Rental Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base spans multinational fleet operators, app-native hourly rental platforms, and traditional counter-based agencies. Three archetypes dominate: premium-positioned terminal operators, corporate contract anchors, and smartphone-native mobility platforms. Consolidation pressure favors scale-driven procurement of electric vehicle fleets, while geographic expansion into underpenetrated Oman and Qatar markets accelerates competitive positioning.
Within the premium-tier vector, Sixt SE and Enterprise Holdings exemplify divergent strategic anchoring. Sixt SE occupies a position concentrated at Abu Dhabi and Dubai terminals where yield premiums sustain operational margins. Enterprise Holdings anchors corporate account volumes through long-term leasing structures with oil and gas sector clients. Ekar represents the app-native archetype targeting Riyadh and Jeddah urban residents with hourly access models that bypass traditional airport-centric transaction structures.
| Leading Market Players |
|---|
| Sixt SE |
| Yelo |
| Hertz Corporation |
| Fast Rent a Car |
| Ekar |
| Enterprise Holdings |
| Thrifty |
| KAYAK |
| Avis Budget Group |
| Others |
Supply Flow & Price Mechanics
Jebel Ali Port freight corridors channel vehicle import costs into fleet procurement decisions across Dubai and Abu Dhabi, concentrating pricing power with terminal-based operators who absorb logistics premiums into yield structures while squeezing peripheral competitors.
Pricing Analysis
Configured-to-order premium spreads separate standard daily-rate rentals from corporate fleet contracts with embedded maintenance and insurance bundles. Three-tier pricing structure across premium, standard, and economy levels stratifies by vehicle specification and contract duration. Pricing pressure stems from EV procurement mandates accelerating capital replacement cycles. Corporate travel managers demonstrate lowest price sensitivity due to negotiated master service agreements, while leisure tourists at Dubai International Airport exhibit highest elasticity.
Supply Chain Analysis
Supplier-financing facilities from Japanese and Korean OEMs extend payment terms for GCC fleet operators managing electrification transitions. Vehicle sourcing concentrates in Japan, South Korea, and Germany for ICE fleets, with China emerging for battery-electric procurement. Battery cell supply, semiconductor components, and tire stockpiles represent critical input dependencies. Single-source vulnerability sits with high-voltage battery suppliers as regional technician certification lags. Distribution runs through airport terminal counters, urban satellite locations, and app-native platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ride-hailing platforms and micromobility services threaten substitution for intra-urban trips, forcing rental operators to defend position through fleet differentiation and contract lock-in.
For Market Incumbents: Harden corporate account retention by embedding telematics-enabled fleet management into long-term oil and gas contracts. Deepen backward integration into charging infrastructure to capture EV mandate economics. Defend against hourly rental platforms by redistributing fleet density toward Riyadh and Jeddah urban corridors.
For New Entrants and Emerging Players: Establish a beachhead in Oman's underpenetrated leisure tourism corridor around Muscat International Airport expansion. Target Salalah's seasonal monsoon tourism peaks for differentiated short-term deployment. Leverage smartphone-native distribution to bypass legacy counter infrastructure.
For Investors and Strategic Acquirers: App-native mobility platforms with proven urban user acquisition represent the highest-conviction acquisition archetype. Long-term viability hinges on electrification compliance capability and municipal offtake relationships. Watch Dubai Roads and Transport Authority fleet percentage mandate announcements as inflection signals for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| EV Fleet Procurement Acceleration | Dubai RTA mandates create guaranteed offtake for early-compliant operators. |
| Telematics Platform Integration | Real-time utilization tracking compresses yield management decision cycles. |
| Corporate Contract Expansion | Oil and gas sector maintenance-inclusive terms lock in superior margins. |
| Urban Mobility App Development | Hourly rental models bypass airport-centric transaction concentration. |
| Oman Market Entry | Muscat International Airport expansion opens underpenetrated leisure nodes. |
Methodological Framework
Cross-validation between fleet operator procurement data and municipal regulatory filings anchors the qualitative findings in this analysis. Primary interviews with fleet procurement managers, corporate travel directors, airport concession operators, and EV infrastructure developers combine with secondary validation from Saudi Public Transport Authority licensing records, UAE Roads and Transport Authority mandate documents, customs vehicle import data, and tourism arrival statistics. Bottom-up fleet size estimates and top-down market value triangulation establish dimensional consistency.
Calibration against historical fleet deployment patterns and regulatory compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, vehicle specification tier, customer mission, and distribution channel, with EV procurement percentage tracked as a cross-cutting industry-specific dimension. CAGRs derive from fleet expansion trajectories, replacement cycle compression, and yield management digitization adoption curves. Tourism infrastructure expansion and corporate account renewal rates serve as primary forecast inputs.
Sensitivities concentrate around EV mandate acceleration, cross-border VAT harmonization outcomes, and ride-hailing substitution velocity. Forecasts reflect documented assumptions on fleet electrification timelines and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Cab Services Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Onboard Maintenance Systems Market
Automotive Services
Automotive MRO Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Electric Commercial Vehicle MRO Market
Automotive Services
Driverless Sweeper Market
Automotive Services
United States Automotive Service Market
Automotive Services
Global Cars-As-A-Service (CaaS) Market
Automotive Services
Automotive Register Market
Automotive Services
Limousine Car Hire or Rental Market