
 Automotive Repair and Service Market | 2026-2036
Automotive Repair and Service Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Repair and Service Market Analysis
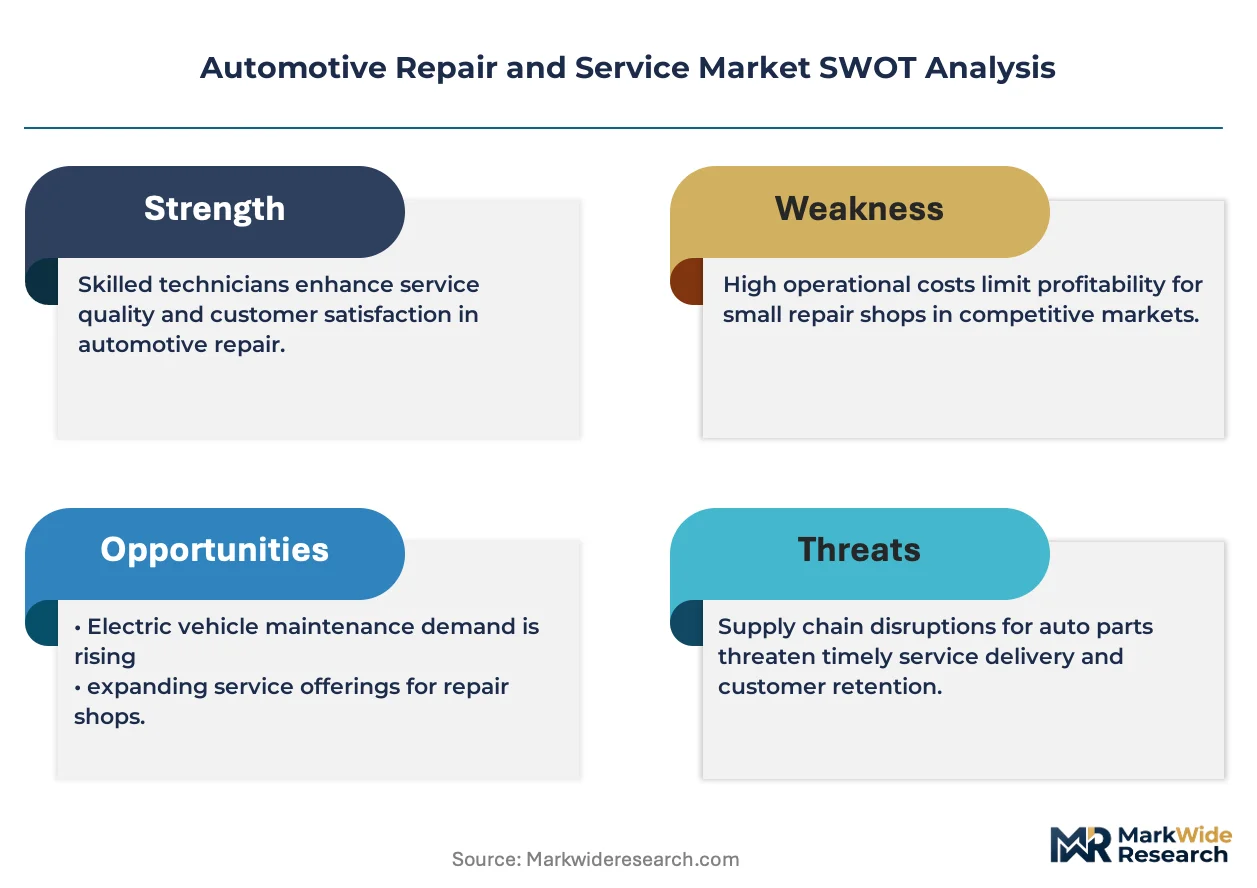
Multi-source parts procurement is restructuring how independent workshops manage inventory and margin risk. Robert Bosch GmbH leverages its captive distribution through Bosch Car Service to control technician certification and parts authenticity. Napa Autocare Center anchors its network with same-day availability commitments to fleet accounts. LKQ Corporation dominates the recycled and aftermarket collision parts channel through scale purchasing and salvage yard density.
Automotive repair and service encompasses the technical inspection, component replacement, system recalibration, and preventive maintenance of vehicles to restore or preserve operational safety and performance per manufacturer specifications. The activity requires diagnostic scan tools capable of reading manufacturer-specific fault codes, torque-calibrated fastening equipment, and emissions measurement apparatus to verify regulatory compliance. Maintenance and repair services command the largest revenue share among service types as aging vehicle populations extend useful life beyond warranty periods. Electric vehicle technology within the technology segment attracts disproportionate capital allocation as high-voltage battery systems and thermal management circuits demand specialized tooling and technician retraining. Individual owners and fleet operators split the end-user base, with fleets generating more predictable revenue through contracted preventive schedules.
The US EPA enforces emissions compliance through periodic testing mandates that create recurring demand for exhaust system diagnostics and catalytic converter replacement. California Air Resources Board regulations exceed federal stringency, forcing national service chains to maintain dual inventory and technician certification tiers. The EU F-Gas Regulation governs mobile air conditioning refrigerant handling, requiring recovery equipment investment and handler licensing across member states. Stakeholders must monitor how battery-electric vehicle adoption reshapes labor skill requirements and facility electrical infrastructure needs.
Market Dynamics
Fleet electrification timelines and high-voltage battery maintenance protocols are compressing traditional mechanical service revenue pools while forcing capital redeployment toward thermal management diagnostics and power electronics recalibration.
Growth Catalysts
- EPA tailpipe enforcement:Periodic emissions testing mandates in the United States generate recurring demand for exhaust system diagnostics and catalytic converter replacement services.
- China's eastern province clusters:Vehicle density in Jiangsu, Zhejiang, and Guangdong provinces exceeds installed service capacity, creating acute demand-supply imbalances for independent workshops.
- High-voltage battery systems:Specialized tooling requirements for electric vehicle thermal management and battery health assessment are opening premium service tiers with technician certification premiums.
Market Restraints
- Semiconductor shortage persistence:Extended lead times for engine control modules and advanced driver-assistance sensors delay repair completion and inflate parts procurement costs.
- California Air Resources Board dual-tier compliance:National service chains must maintain separate inventory and technician certification tracks, fragmenting operational scale economies.
- Qualified technician scarcity:High-voltage safety certification programs produce insufficient graduates to match electric vehicle population growth, constraining service throughput.
Strategic Opportunities
- India's aftermarket expansion:Bureau of Indian Standards quality mark adoption creates first-mover advantage for organized service networks targeting quality-conscious vehicle owners.
- Subscription-based maintenance contracts:Fleet operators in Germany and the Netherlands are consolidating vendor relationships around predictive maintenance platforms with guaranteed uptime clauses.
- Refrigerant recovery equipment:EU F-Gas Regulation handler licensing requirements position certified workshops to capture mobile air conditioning service revenue from non-compliant competitors.
Industry Challenges
- High-voltage safety certification timelines:OEM-specific battery system authorization programs extend technician qualification periods, delaying electric vehicle service capability deployment.
- Diagnostic scan tool fragmentation:Proprietary manufacturer fault code databases force multi-brand workshops into expensive subscription stacking or incomplete coverage gaps.
- Facility electrical infrastructure:Service bay upgrades for 800-volt charging and isolation equipment demand capital commitments that strain independent operator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Repair and Service Market |
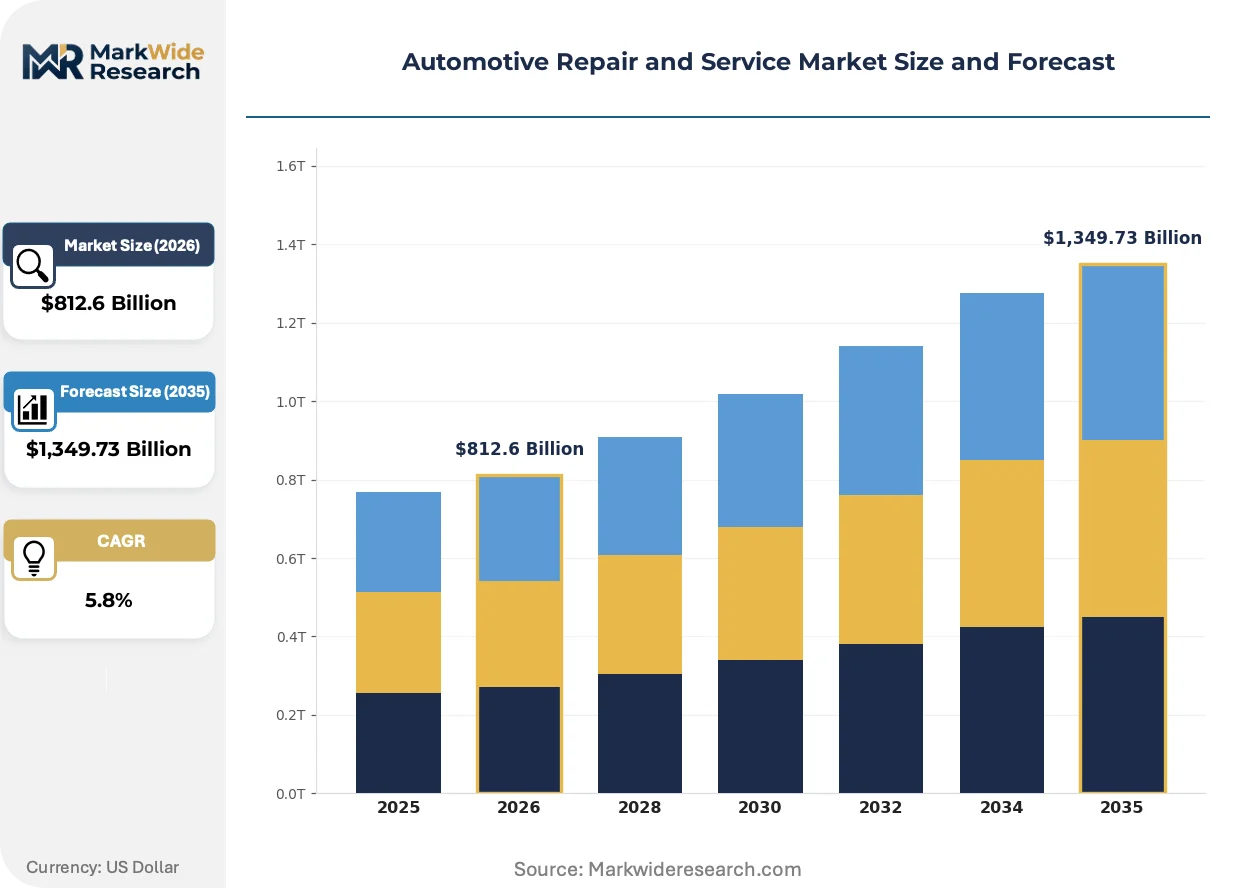
| Market Size in 2026 | $812.6 Billion |
| Market Size in 2035 | $1,349.73 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Overhaul, Diagnostics End User: Individual Owners, Fleets, Dealerships, Workshops Product Type: Parts, Tools, Equipment, Accessories Technology: Hybrid Systems, Electric Vehicles, Fuel Systems, Autonomous Tech |
| Companies Covered | LKQ Corporation, Robert Bosch GmbH (Bosch Car Service), Napa Autocare Center, Firestone Complete Auto Care, Midas, Parts Plus Car Care Center, Jiffy Lube International, Belron International Limited, Caliber Collision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Repair and Service Market Emerging Trajectories
Connected vehicle data streams and predictive algorithms are transferring diagnostic authority from physical service bays to remote monitoring platforms, compressing failure-to-repair intervals and reshaping labor deployment models.
Over-the-air software calibration is rewriting how powertrain and chassis control modules receive updates, eliminating physical service visits for parameter adjustments. Premium electric vehicle manufacturers now push firmware revisions directly to customer vehicles, reducing dealer service lane occupancy while shifting revenue toward subscription feature activation. This compression of traditional maintenance touchpoints is forcing service networks to develop companion revenue streams around hardware inspection and battery health verification.
The EU F-Gas Regulation mandates recovery equipment certification and refrigerant tracking across member states, elevating compliance costs for mobile air conditioning service providers. Workshops in France, Germany, and Italy must now maintain auditable refrigerant handling logs and invest in certified recovery machinery. Smaller independent operators face consolidation pressure as fixed compliance costs disproportionately burden low-volume service providers.
Fleet procurement departments are consolidating vendor relationships around integrated maintenance platforms that bundle preventive scheduling, parts procurement, and compliance documentation. Large logistics operators in the United States and Germany now demand API-enabled reporting that feeds directly into their enterprise resource planning systems. This integration requirement favors service networks with standardized data infrastructure over fragmented independent workshops lacking digital integration capability.
Automotive Repair and Service Market Segmentation
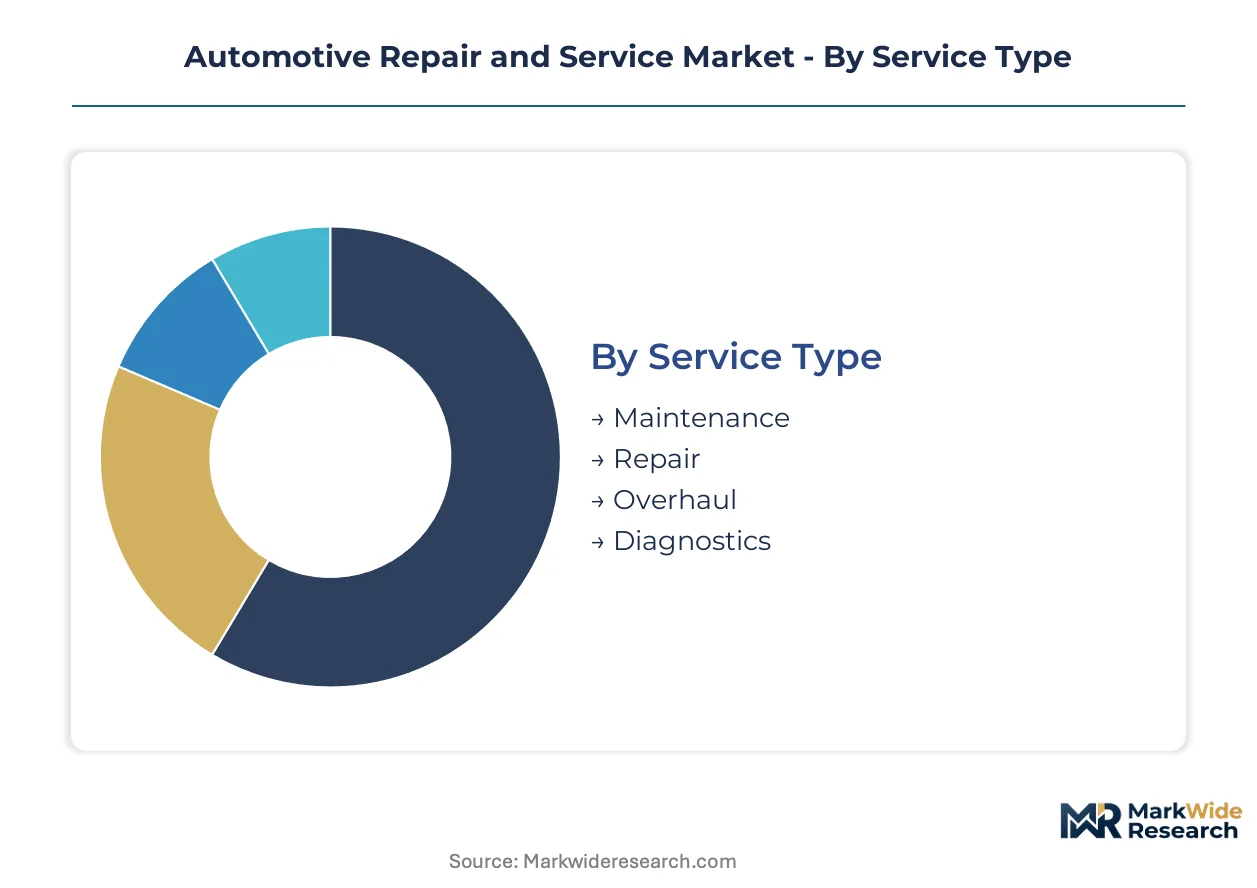
Service providers must align capability investments with distinct demand profiles across repair modalities and customer ownership structures. Fleet contracts reward predictive scheduling platforms while individual owners respond to proximity and transparency.
Service Type:
Volume concentrates in routine maintenance, yet premium margins attach to specialized diagnostics and powertrain overhaul.
- Maintenance:Scheduled fluid exchanges, filter replacements, and inspection protocols preserve manufacturer warranty compliance and residual value. Fleet operators in Germany and the Netherlands consolidate spend around predictive platforms with guaranteed uptime clauses.
- Repair:Component replacement and system restoration address wear failures and collision damage. China's eastern province clusters absorb outsized capacity as vehicle density exceeds workshop availability.
- Overhaul:Complete powertrain or chassis refurbishment extends commercial vehicle service life.
- Diagnostics:Fault code interpretation and root-cause analysis using manufacturer-specific scan tools.
Today's leader: Maintenance. Tomorrow's challenger: Diagnostics.
End User:
Customer concentration determines pricing power and contract structure, with fleet procurement departments demanding API integration and compliance documentation.
- Individual Owners:Price-sensitive demand fragmented across proximity-based workshop selection and online review platforms.
- Fleets:Commercial operators with contracted preventive schedules generate predictable revenue streams. US logistics operators require ERP-integrated reporting that favors standardized data infrastructure.
- Dealerships:OEM-authorized service lanes capture warranty work and proprietary software updates.
- Workshops:Independent operators compete on speed and parts sourcing flexibility.
Fleets command contract terms. Individual owners drive volume scale.
Product Type:
Margin structure inverts between commodity parts and specialized equipment requiring certification investment.
- Parts:Replacement components span OEM, aftermarket, and recycled channels. LKQ Corporation dominates collision parts through salvage yard density and scale purchasing.
- Tools:Torque-calibrated fastening and diagnostic equipment carry technician certification requirements.
- Equipment:Lift systems, alignment racks, and emissions testing apparatus anchor fixed facility investment.
- Accessories:Consumables and appearance products attach to service visits.
Parts generate recurring turnover. Equipment locks in facility commitment.
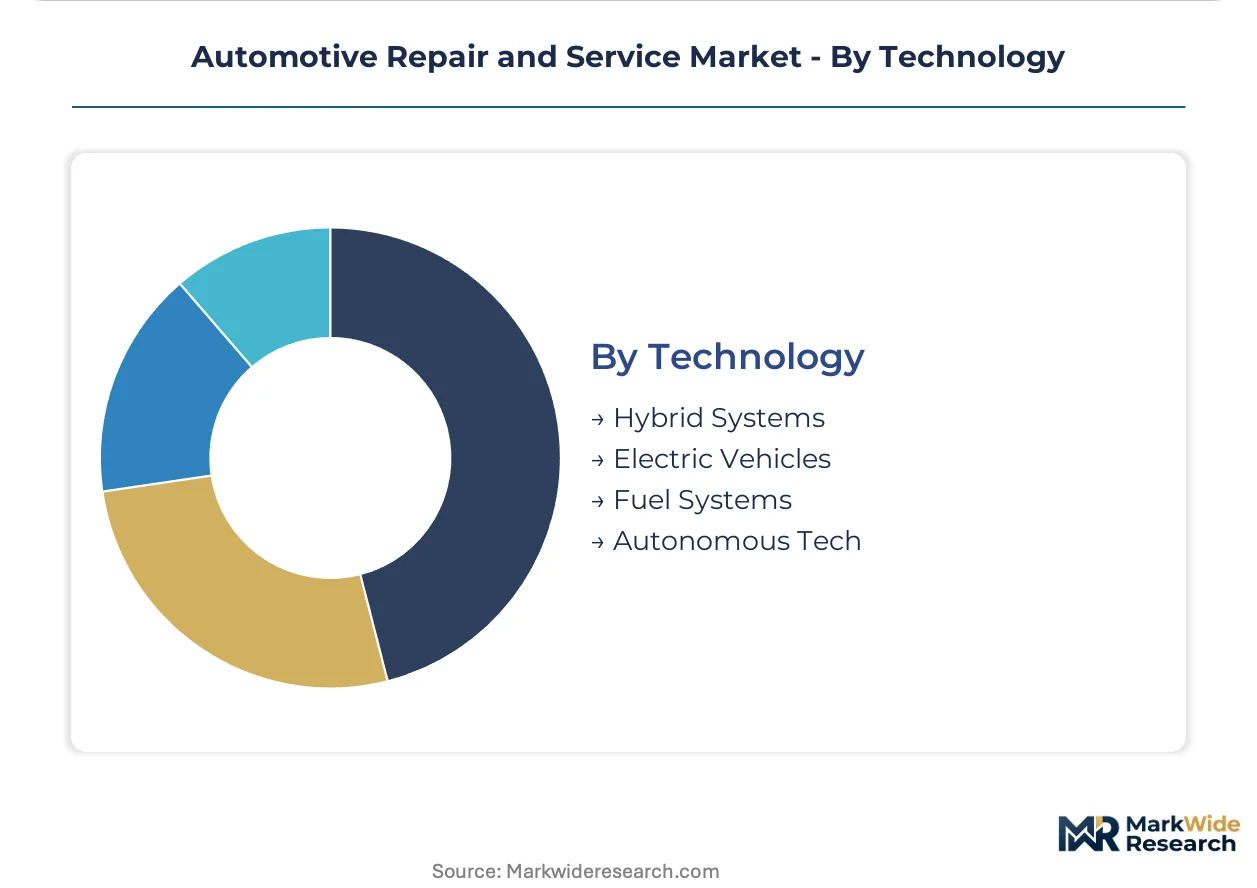
Technology:
Capital allocation shifts toward high-voltage systems as thermal management and battery health assessment open premium service tiers.
- Hybrid Systems:Dual powertrain maintenance combines internal combustion service with electric motor and battery management protocols.
- Electric Vehicles:High-voltage battery diagnostics and thermal management circuits demand specialized tooling. EU F-Gas Regulation handler licensing positions certified workshops to capture mobile air conditioning revenue from non-compliant competitors.
- Fuel Systems:EPA tailpipe enforcement generates recurring demand for exhaust diagnostics and catalytic converter replacement.
- Autonomous Tech:Sensor calibration and ADAS recalibration following collision repair.
Electric vehicles attract disproportionate investment. Fuel systems defend near-term revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu-Zhejiang-Guangdong corridor concentrates the densest vehicle populations against constrained workshop capacity, while regulatory divergence across major economies fragments compliance requirements and investment patterns.
United States
Fleet electrification timelines and commercial vehicle utilization rates compress traditional mechanical service revenue pools. EPA tailpipe enforcement generates recurring demand for exhaust diagnostics and catalytic converter replacement. Texas and California absorb outsized capacity as dual-tier compliance forces national chains to maintain separate inventory and technician certification tracks.
Germany
Logistics operators consolidate vendor relationships around predictive maintenance platforms with guaranteed uptime clauses. EU F-Gas Regulation handler licensing requirements position certified workshops to capture mobile air conditioning service revenue. Bavaria and North Rhine-Westphalia host dense fleet operator concentrations driving subscription-based contract adoption.
China
Vehicle density in eastern province clusters exceeds installed service capacity, creating acute demand-supply imbalances for independent workshops. MIIT standards and local environmental bureaus enforce emissions compliance through periodic testing mandates. Yangtze River Delta and Pearl River Delta absorb the majority of premium diagnostic equipment imports.
India
Bureau of Indian Standards quality mark adoption creates first-mover advantage for organized service networks targeting quality-conscious vehicle owners. Central Pollution Control Board mandates force earlier inspection cycles for commercial fleets. Maharashtra and Gujarat concentrate aftermarket parts distribution infrastructure serving western and northern vehicle populations.
Japan
Aging vehicle populations extend useful life beyond warranty periods, sustaining maintenance service demand. METI guidelines shape technician certification requirements for high-voltage battery systems. Kanto and Kansai regions concentrate OEM-authorized service lanes capturing proprietary software update revenue.
Automotive Repair and Service Market Vendor Landscape
Global majors compete with regional champions across parts distribution networks, technician certification ecosystems, and fleet contract structures. The market exhibits tiered concentration with integrated parts-service hybrids commanding premium positioning against fragmented independent operators. Three archetypes dominate: captive distribution networks controlling parts authenticity, scale-driven collision parts aggregators, and subscription-based fleet maintenance platforms. Consolidation pressure intensifies through multi-source parts procurement adoption and ERP integration requirements.
Within the integrated distribution tier, Robert Bosch GmbH anchors technician certification and parts authenticity control through its captive network structure. LKQ Corporation exemplifies scale-driven collision parts aggregation through salvage yard density and aftermarket channel dominance. Napa Autocare Center occupies a position among fleet-facing networks with same-day availability commitments and standardized data infrastructure. These three represent divergent strategic bets on certification control, parts sourcing scale, and fleet contract predictability.
| Leading Market Players |
|---|
| LKQ Corporation |
| Robert Bosch GmbH (Bosch Car Service) |
| Napa Autocare Center |
| Firestone Complete Auto Care |
| Midas |
| Parts Plus Car Care Center |
| Jiffy Lube International |
| Belron International Limited |
| Caliber Collision |
| Others |
Supply Flow & Price Mechanics
California Air Resources Board dual-tier compliance gates qualified supply and premium-tier pricing access, forcing national chains to maintain separate inventory and technician certification tracks that fragment operational scale economies and inflate compliance-adjusted service rates.
Pricing Analysis
Input-cost pass-through from semiconductor shortages and high-voltage battery components is reshaping margin structures across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized diagnostics from independent workshop rates and unlicensed gray-market operators. Cost compression in the standard tier is intensifying because fleet procurement departments demand API-integrated reporting and guaranteed uptime clauses. Individual owners remain most price-sensitive, while fleet operators accept premium rates for predictive maintenance platforms with compliance documentation.
Supply Chain Analysis
Warehouse-distribution layer consolidation centers on regional distribution centers in Germany, China, and the United States that feed hub-and-spoke patterns into dense vehicle population clusters. Parts procurement draws from OEM captive channels, aftermarket distributors like LKQ Corporation, and recycled salvage networks. Single-source vulnerability persists for manufacturer-specific diagnostic scan tools and high-voltage battery systems. Distribution runs through Bosch Car Service for certified components, Napa Autocare Center for fleet same-day availability, and independent jobbers for speed-critical repairs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA tailpipe enforcement and EU F-Gas Regulation handler licensing create recurring demand cycles that reward compliance infrastructure investment.
For Market Incumbents: Lock in fleet contract renewals through predictive maintenance platform integration and ERP-compatible reporting APIs before emerging battery-electric specialists capture high-voltage service volume. Deepen backward integration into thermal management diagnostics tooling to defend against parts margin erosion from multi-source procurement adoption. Prioritize technician certification pipelines for 800-volt systems to preempt qualified labor scarcity constraints. For New Entrants and Emerging Players: Fleet operators in Germany and the Netherlands present the most penetrable channel partner type for subscription-based maintenance contracts with guaranteed uptime clauses. Target India's organized service network expansion around Bureau of Indian Standards quality mark adoption as first-mover positioning. Capture mobile air conditioning service revenue through EU F-Gas Regulation handler licensing investments that disqualify non-compliant competitors. For Investors and Strategic Acquirers: Roll-up economics work for fragmented independent workshop networks because diagnostic scan tool fragmentation and facility electrical infrastructure requirements strain operator balance sheets and accelerate consolidation pressure. Focus acquisition screening on shops with existing high-voltage safety certification and thermal management capability. Monitor electric vehicle population growth rates against qualified technician graduation timelines as the inflection signal for service throughput constraints.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Investment | EPA and CARB mandates force earlier retirement cycles that demand certified battery health assessment capability. |
| Predictive Maintenance Platform Deployment | German logistics operators require API-enabled reporting feeding directly into SAP and Oracle ERP systems. |
| EU F-Gas Handler Licensing Acquisition | Certified refrigerant recovery equipment positions workshops to capture revenue from non-compliant French and Italian competitors. |
| Multi-Source Parts Procurement Integration | LKQ Corporation salvage density and Bosch captive distribution reduce inventory risk for independent operators. |
| Fleet Contract Consolidation | US logistics operators in Texas and California absorb outsized capacity through contracted preventive schedules. |
Methodological Framework
Coverage spans the United States, Germany, China, and India, with primary inputs from each regional cluster combining structured interviews with fleet procurement managers, independent workshop operators, OEM platform engineers, and aftermarket distribution heads with secondary validation. Triangulation incorporates EPA enforcement databases, EU F-Gas Regulation handler registries, vehicle production statistics, and customs records for diagnostic equipment imports. Bottom-up service volume estimates and top-down market sizing reconcile through iterative stakeholder feedback.
Rate-of-change decomposition across the analysis window segments volume and value by service type, end-user concentration, propulsion technology, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to fleet electrification timelines, technician certification graduation rates, and emissions testing mandate expansion schedules. Battery-electric vehicle population projections and high-voltage battery replacement cycle assumptions anchor the technology segment forecast.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor shortage persistence, qualified technician scarcity, and facility electrical infrastructure investment lag. Forecasts reflect documented assumptions about regulatory enforcement intensity and fleet electrification adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Garage and Service Station Service Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Europe Car Wash Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Americas MAP Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Automotive Register Market
Automotive Services
Automotive Engineering Service Providers (ESP) Market
Automotive Services
United States Automotive Service Market
Automotive Services
North America Car Wash Market
Automotive Services
Car Subscription Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Motorsports Market
Automotive Services
US Quick Lube Equipment Market