
 Limousine Car Hire or Rental Market | 2026-2036
Limousine Car Hire or Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Limousine Car Hire or Rental Market Foresight
North American fleet operators is recalibrating vehicle procurement strategies after pandemic-era fleet reductions. Sixt SE leverages its international airport counter network to sustain corporate account loyalty across major US hubs. Blacklane differentiates through all-electric premium fleets in European and North American cities. EMPIRECLS anchors its position in New York's financial district with dedicated executive transportation protocols.
Limousine car hire or rental denotes chauffeured ground transportation services utilizing luxury vehicles exceeding standard sedan dimensions, typically featuring extended wheelbases of 120 inches or more, leather interiors, and partition screens for passenger privacy. These services fulfill premium mobility requirements for corporate protocol, ceremonial occasions, and airport connectivity where scheduled reliability and service discretion supersede cost efficiency. Airport Transfer and Corporate service types command the largest revenue pools due to recurring business contracts and flight-schedule dependency, while Wedding and Event segments generate concentrated seasonal peaks with higher per-trip margins. Sedan and SUV vehicle types dominate operational fleets for their fuel efficiency and maintenance predictability, though Stretch and Party Bus configurations capture premium pricing for celebratory occasions.
The US Department of Transportation hours-of-service regulations and EPA emissions standards shape fleet composition and driver scheduling across American operators. California Air Resources Board zero-emission vehicle mandates and New York City Taxi and Limousine Commission licensing requirements create compliance thresholds that favor capitalized fleet owners over independent operators. Stakeholders must monitor electrification infrastructure readiness and driver classification litigation outcomes to determine fleet investment timing and ownership models.
Market Dynamics
Fleet electrification mandates in California and New York are forcing capital-intensive vehicle replacements across the limousine sector, compressing operator margins while reshaping procurement timelines and charging infrastructure investments.
Growth Catalysts
- Corporate Ground Transportation Budgets:Executives returning to in-person client meetings are expanding premium chauffeur service contracts, particularly for airport transfers and financial district protocols.
- California Air Resources Board Mandates:Zero-emission vehicle requirements are accelerating hybrid and electric limousine model adoption, creating compliance-driven fleet renewal cycles.
- Dubai Tourism Infrastructure:The United Arab Emirates' business event calendar and hospitality sector sustain concentrated demand for premium chauffeur services.
Market Restraints
- Vehicle Acquisition Costs:Electric and hybrid limousine platforms command premium pricing versus internal combustion equivalents, straining operator balance sheets.
- Driver Classification Litigation:Ongoing legal disputes over independent contractor versus employee status create operational uncertainty and insurance cost volatility.
- Charging Infrastructure Gaps:Inadequate fast-charging networks at airports and urban centers limit electric fleet deployment flexibility.
Strategic Opportunities
- Electrification Infrastructure Partnerships:Operators securing exclusive charging access at major airports can lock in competitive positioning for corporate accounts.
- Saudi Arabia Vision 2030:The kingdom's tourism and entertainment sector expansion creates underpenetrated demand for ceremonial and VIP ground transportation.
- Blockchain-Enabled Booking Platforms:Distributed ledger technology converging with mobile applications enables transparent, auditable corporate expense management.
Industry Challenges
- Certified Electric Vehicle Technician Shortage:Fleet maintenance operations lack personnel trained on high-voltage systems and battery management diagnostics.
- Partition Screen Retrofit Compliance:Privacy screen installations in converted electric platforms face extended homologation timelines with state transportation authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limousine Car Hire or Rental Market |
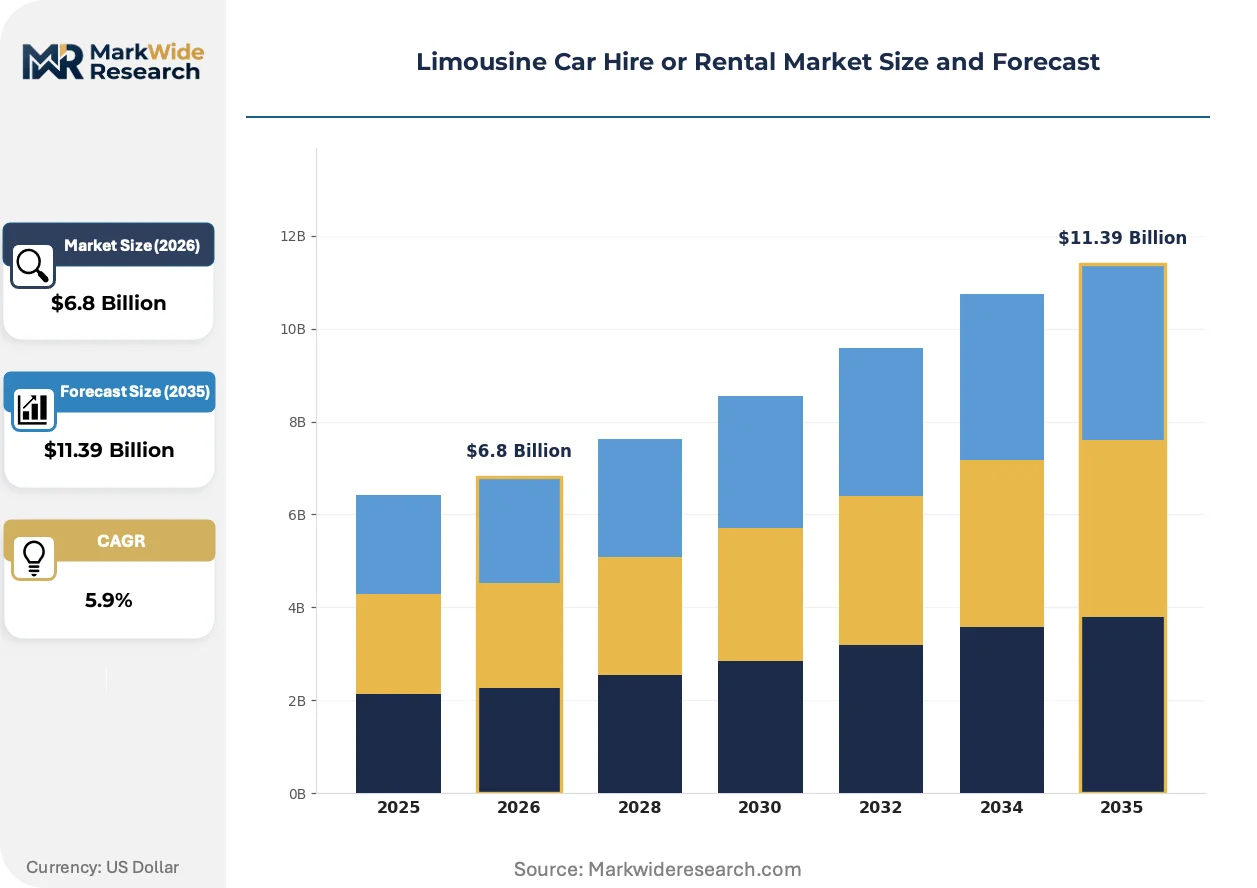
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate, Wedding, Airport Transfer, Event Vehicle Type: Sedan, Stretch, SUV, Party Bus Booking Channel: Online, Direct, Travel Agency, Third-party Apps Customer Segment: Business Travelers, Tourists, Event Planners, Locals |
| Companies Covered | Sixt SE, Blacklane, Limos.com, DiDi, Addison Lee, National Limousine Service, EMPIRECLS, Carey International, Windy City Limousine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limousine Car Hire or Rental Market Shifts & Advancements
Digital dispatch platforms and electrification technologies are converging to transform how limousine services manage fleet utilization, driver allocation, and client experience personalization.
Artificial intelligence-powered route optimization is automating real-time traffic adaptation and predictive arrival notifications. Corporate travel managers at Fortune 500 firms are adopting these platforms fastest, demanding integration with expense management systems. The technology is automating dispatch decisions previously handled by human operators, compressing fleet idle time and improving on-time performance metrics.
EPA emissions standards and hours-of-service regulations are tightening compliance burdens on multi-state operators. Fleet owners must now maintain dual certification protocols for interstate commerce and municipal livery licensing. Stretch limousine configurations face disproportionate scrutiny under revised greenhouse gas scoring methodologies.
Subscription-based mobility packages are displacing per-ride corporate accounts. Financial services and legal sector clients in Manhattan and London now prefer fixed monthly fees covering unlimited airport transfers and on-demand executive transport. This consumption-pattern shift rewards operators with density in premium commercial districts.
Limousine Car Hire or Rental Market Segmentation
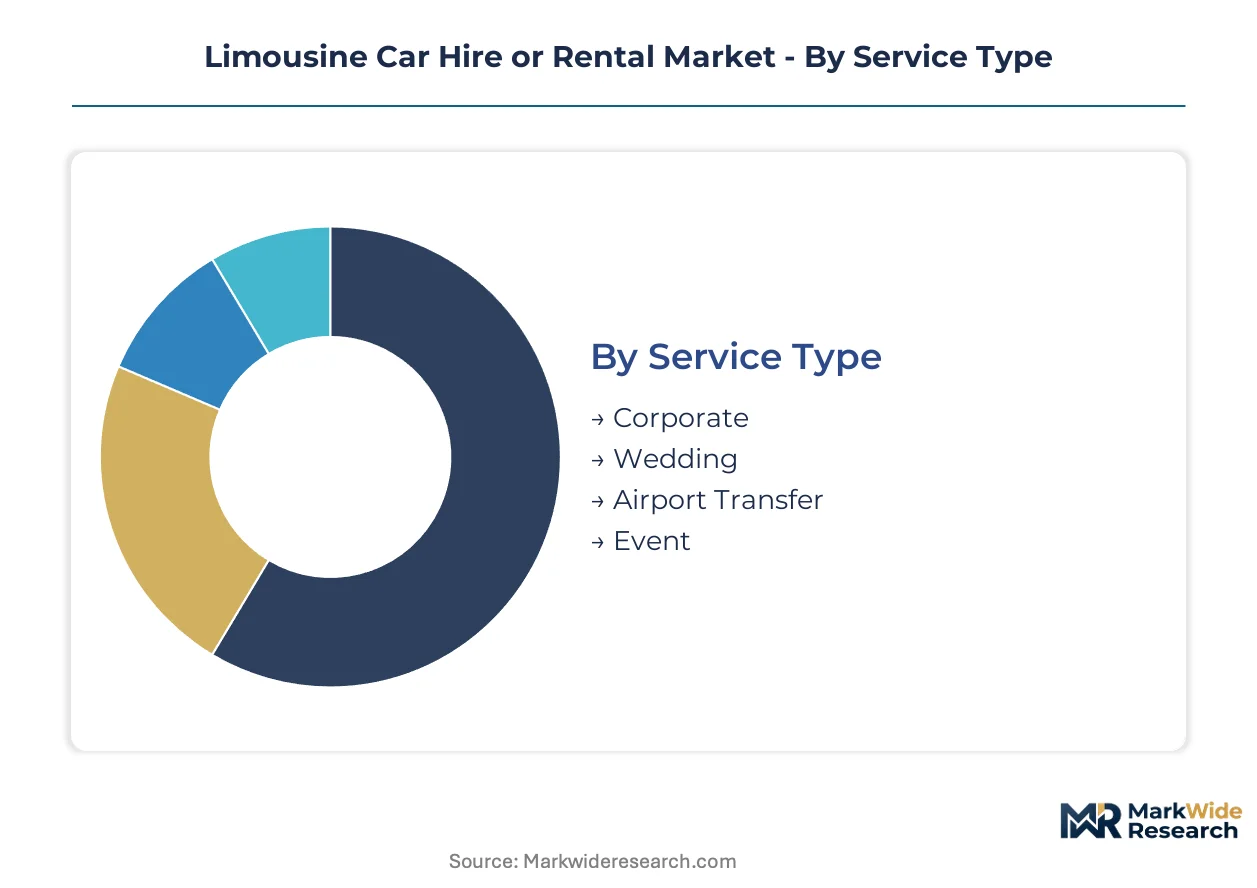
Limousine operators calibrate fleet composition and service protocols around distinct demand profiles. Segmentation reveals where capital deployment yields recurring revenue versus episodic premium pricing.
Service Type:
Upgrade cycles and replacement timelines vary sharply across service categories, with contract renewal frequencies dictating fleet planning horizons.
- Airport Transfer:Scheduled point-to-point connectivity utilizing standardized sedan and SUV configurations. Demand concentrates in Dubai and New York, where flight schedules generate predictable volume and corporate travel managers prioritize reliability over vehicle differentiation.
- Corporate:Dedicated executive transportation with protocol-specific driver training and privacy accommodations. Financial services firms in Manhattan and London sustain the largest contract pools, with subscription billing displacing per-ride invoicing.
- Wedding:Ceremonial occasions requiring stretch configurations and decorative customization. Seasonal demand peaks strain fleet utilization in spring and autumn months.
- Event:Concerts, sporting fixtures, and entertainment venue connectivity. Concentrated single-day volume demands surge capacity planning.
Volume placements concentrate in Airport Transfer; the faster expansion belongs to Corporate.
Vehicle Type:
Cost tiers separate operational workhorses from celebration-focused specialty configurations, with electrification mandates reshaping procurement economics.
- Sedan:Extended-wheelbase luxury sedans form the backbone of airport and corporate fleets. California operators face accelerated replacement timelines under CARB zero-emission mandates.
- SUV:Premium sport-utility vehicles command higher per-mile rates while offering superior luggage capacity. New York financial district accounts sustain demand for executive SUV protocols.
- Stretch:Extended limousine configurations with partition screens and entertainment systems. Wedding and event segments generate concentrated demand with steep seasonal variation.
- Party Bus:High-capacity luxury coaches for group celebrations. Margins exceed standard sedan rates but utilization rates remain volatile.
Fleet investment gravitates toward Sedan and SUV platforms; Stretch configurations capture the steepest expansion trajectory in ceremonial markets.
Booking Channel:
Customer acquisition economics diverge across channel structures, with digital platforms compressing margins while expanding reach.
- Online:Proprietary websites and mobile applications enabling direct reservation. Corporate travel managers demand API integration with expense management systems.
- Direct:Phone and walk-in bookings sustaining relationship-based accounts. High-touch service justifies premium pricing for established clientele.
- Travel Agency:Intermediary bookings from hospitality and tourism partners. Dubai's hotel concierge networks generate substantial referral volume.
- Third-party Apps:Mobility platforms aggregating multiple operators. Price transparency intensifies competition while expanding market access.
Transaction volume concentrates in Online channels; Third-party Apps are climbing the fastest among emerging segments.
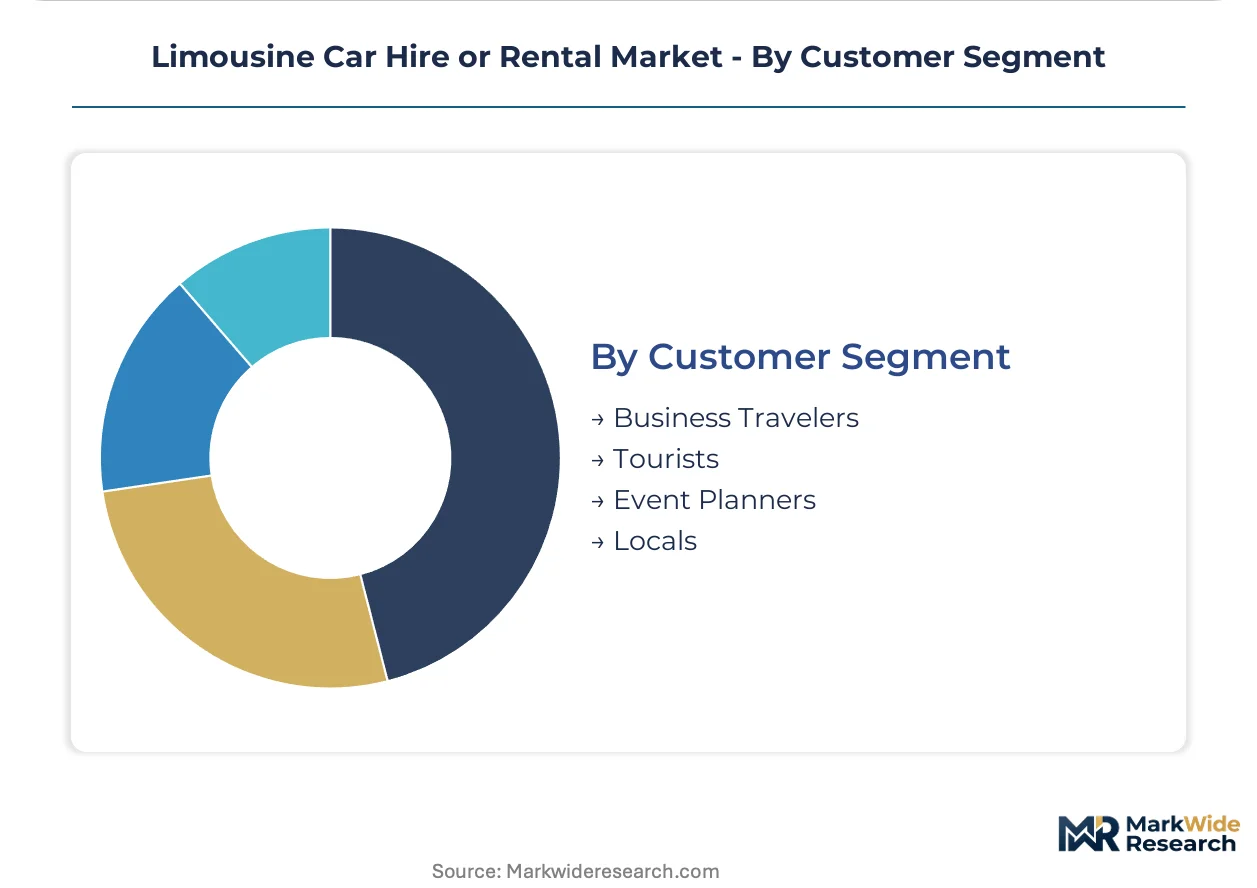
Customer Segment:
Maturity levels and margin profiles separate institutional buyers from discretionary consumers, shaping service packaging and retention strategies.
- Business Travelers:Frequent flyers requiring predictable airport connectivity and on-demand executive transport. Subscription models capture loyalty through fixed monthly fees.
- Tourists:Leisure visitors seeking premium ground transportation for sightseeing and hospitality access. Dubai's tourism infrastructure sustains concentrated demand.
- Event Planners:Professional coordinators managing transportation logistics for weddings and corporate functions. Bulk booking power demands volume discounts.
- Locals:Resident consumers utilizing limousines for special occasions and celebration transport. Price sensitivity exceeds business traveler tolerance.
Revenue concentration sits with Business Travelers; Tourists represent the segment gaining share fastest in hospitality-dependent markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining capacity along the US Gulf Coast sustains fleet fueling infrastructure for stretched vehicle configurations. Chrome plating workshops in Mexico's Bajío region supply decorative trim components for ceremonial limousine builds. Leather tanning clusters in Italy's Veneto region furnish upholstery materials for premium cabin interiors.
United States
Corporate travel budgets in Manhattan and Chicago's Loop district sustain premium chauffeur contracts for financial services executives. EPA emissions standards and DOT hours-of-service regulations compress fleet scheduling flexibility across interstate operators. Los Angeles and San Francisco operators face accelerated zero-emission vehicle procurement timelines under California Air Resources Board mandates.
United Arab Emirates
Dubai's hospitality sector and business event calendar generate concentrated demand for VIP ground transportation protocols. MOHAP commercial licensing frameworks govern operator certification and vehicle inspection standards. The Dubai International Financial Centre and Palm Jumeirah hotel corridor anchor premium service density for ceremonial and executive transport.
Germany
Luxury automotive engineering heritage in Stuttgart and Munich feeds specialized vehicle modification capabilities for extended-wheelbase platforms. KBA type-approval requirements extend homologation timelines for partition screen retrofits in converted electric chassis. Frankfurt's financial district sustains recurring corporate account contracts with subscription-based billing structures.
United Kingdom
London's Square Mile and Canary Wharf business clusters demand protocol-specific executive transportation with privacy accommodations. TfL licensing requirements and Ultra Low Emission Zone restrictions reshape fleet composition toward hybrid and electric platforms. The Heathrow and Gatwick airport corridors concentrate point-to-point transfer volume for business traveler segments.
Japan
Corporate hospitality customs in Tokyo's Marunouchi and Roppongi districts sustain premium chauffeur service demand for foreign executive visitors. METI carbon neutrality roadmaps pressure fleet operators toward electrified vehicle procurement. Osaka's Kansai International Airport connectivity and Kyoto's ceremonial tourism infrastructure generate seasonal stretch limousine utilization.
Limousine Car Hire or Rental Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrification differentiation and subscription billing models. The vendor base concentrates around capitalized fleet owners with airport counter networks and municipal licensing authority, while independent operators face margin compression from regulatory compliance costs. Three archetypes dominate: international airport-network operators, premium electric fleet specialists, and regional ceremonial service providers. Competitive dynamics center on charging infrastructure partnerships and corporate account retention through API-integrated booking platforms.
Among international network operators, Sixt SE anchors multi-hub presence across major US and European airports. Blacklane exemplifies the electrification-focused archetype with zero-emission fleet positioning in premium urban markets. EMPIRECLS occupies a position within the financial district specialist tier, serving Manhattan's corporate protocol requirements. These three represent distinct strategic vectors: geographic scale, sustainability differentiation, and vertical depth in ceremonial executive transport.
| Leading Market Players |
|---|
| Sixt SE |
| Blacklane |
| Limos.com |
| DiDi |
| Addison Lee |
| National Limousine Service |
| EMPIRECLS |
| Carey International |
| Windy City Limousine |
| Others |
Supply & Pricing Matrix
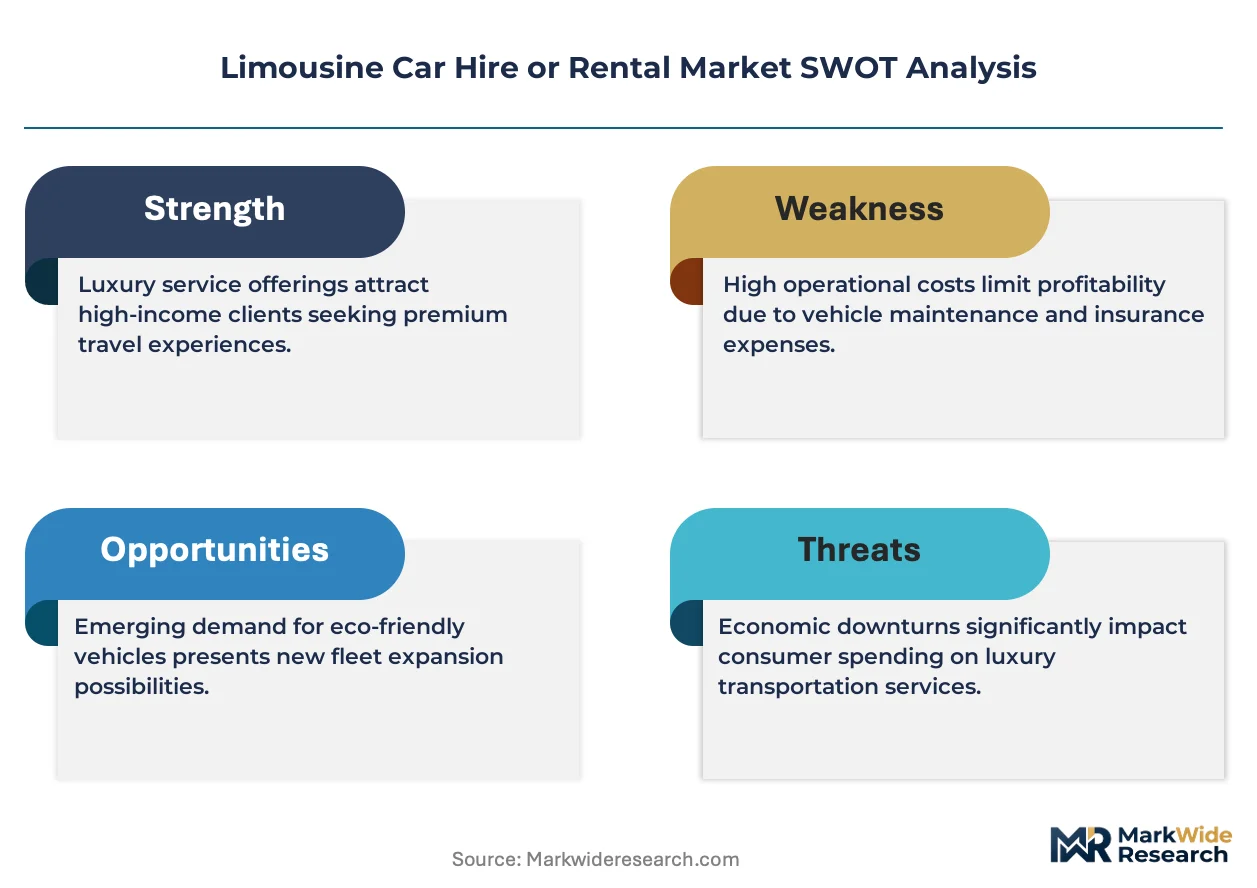
Corporate travel managers at Fortune 500 financial services firms anchor the dominant subscription billing model, consolidating purchasing power through fixed monthly fees that displace per-ride invoicing and compress operator margins.
Pricing Analysis
Service bundling separates all-inclusive corporate protocols from unbundled wedding and event packages where decorative customization and extended wait times carry surcharges. Three-tier pricing structure across premium, standard, and economy levels stratifies by vehicle configuration and driver certification tier. Pricing pressure stems from electric vehicle acquisition premiums under California Air Resources Board mandates, which strain operator balance sheets. Business travelers exhibit lowest price sensitivity due to expense account coverage, while local consumers for ceremonial occasions demonstrate highest elasticity.
Supply Chain Analysis
Freight costs for extended-wheelbase chassis modifications concentrate manufacturing dependencies across Germany, Japan, and the United States. High-voltage battery systems, partition screen assemblies, and luxury leather upholstery draw from specialized tier-one suppliers. Single-source vulnerability in certified electric vehicle technician training creates maintenance bottlenecks for electrified fleets. Distribution runs through airport counter networks and direct corporate account relationships rather than third-party aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are intensifying as CARB and New York City Taxi and Limousine Commission compliance costs force undercapitalized independent operators toward exit or acquisition.
For Market Incumbents: Extend charging infrastructure partnerships at major airports to lock in corporate account retention against emerging electric fleet specialists. Deepen backward integration into vehicle modification capabilities to control partition screen homologation timelines with state transportation authorities. For New Entrants and Emerging Players: Capture Saudi Arabia's ceremonial and VIP ground transportation demand under Vision 2030 tourism expansion before established operators establish airport counter presence. Pursue blockchain-enabled booking platforms with API integration for corporate expense management systems as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors capitalized fleet owners with municipal licensing authority and established airport counter networks. Long-term viability rests on electrification infrastructure positioning and corporate subscription account density. Monitor driver classification litigation outcomes as the critical inflection signal for operating model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Exclusive airport access locks in corporate account loyalty against competitors. |
| Electric Fleet Conversion Program | California Air Resources Board compliance secures operating license continuity. |
| Subscription Billing Platform | Fixed monthly fees capture Manhattan financial district travel manager preference. |
| Blockchain Booking Integration | Transparent expense management appeals to Fortune 500 procurement protocols. |
| Saudi Market Entry | Vision 2030 tourism expansion creates underpenetrated ceremonial demand. |
Research Methodology
Independent corroboration across fleet operator executives, corporate travel managers, municipal licensing officials, and vehicle modification specialists underwrites the qualitative findings. Primary fieldwork with airport ground transportation coordinators, charging infrastructure developers, and luxury automotive procurement leads combined with secondary validation from EPA emissions filings, DOT hours-of-service regulations, state transportation authority homologation records, and corporate travel expenditure databases. Bottom-up fleet utilization modeling and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to pandemic-era fleet reduction baselines and post-return-to-office recovery trajectories structured the forecast window. Segmentation dimensions span service type, vehicle configuration, booking channel, and customer archetype across the modeling period. CAGRs derive from contracted corporate account renewal frequencies, electrification mandate compliance timelines, and tourism infrastructure buildout schedules. Driver classification litigation outcomes and charging network deployment rates feed scenario sensitivity analysis.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery technology cost curves and municipal zero-emission enforcement intensity. Forecasts reflect assumptions about corporate travel budget persistence and regulatory compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Car Breakdown Recovery Services Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Electric Vehicle Repair Service Market
Automotive Services
Vehicle Conversion Market
Automotive Services
Australia Fire Truck Market
Automotive Services
Malaysia Car Wash Service Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Automotive Homologation Services Market
Automotive Services
Global Street Sweeper Market
Automotive Services
United States Automotive Service Market
Automotive Services
Global Car Wash Market
Automotive Services
Automotive MRO Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Driverless Sweeper Market
Automotive Services
Vehicle Subscription Market