
 Automotive Engine Encapsulation Market | 2026-2036
Automotive Engine Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Encapsulation Market Analysis
Tier-1 supplier networks is tilting toward integrated module providers capable of delivering thermal-acoustic combined systems. Autoneum Holding AG leverages its acoustic engineering heritage to dominate premium vehicle programs across European OEMs. BASF SE anchors material innovation through polyurethane foam formulations optimized for engine-bay temperatures. Continental AG competes on sensor-integrated encapsulation that feeds thermal data into vehicle energy management systems.
Automotive engine encapsulation refers to the enclosure of powertrain components with engineered materials—typically glass-mat reinforced thermoplastics, polyurethane foams, or aluminum-composite hybrids—to manage thermal flux, airborne noise, and vibrational energy within the engine compartment. The primary purpose is to shorten cold-start warm-up periods, reduce cabin noise intrusion, and protect adjacent electronics from radiant heat. Thermal shields lead product type demand due to their direct contribution to CO2 reduction via faster catalyst light-off, while composite materials represent the fastest-growing material category as OEMs seek mass reduction without sacrificing temperature resistance. Among applications, thermal management commands the deepest margin pools because it ties directly to fleet emissions compliance and powertrain efficiency benchmarking.
The EPA and NHTSA in the United States enforce Corporate Average Fuel Economy standards that effectively mandate thermal management solutions to improve cold-cycle efficiency. Europe's REACH regulation and F-Gas Directive restrict certain blowing agents and flame retardants used in encapsulation foams, forcing reformulation investments across the supply base. Stakeholders must monitor how evolving powertrain electrification strategies reshape encapsulation requirements as hybrid architectures introduce dual thermal regimes that legacy designs cannot address.
Market Dynamics
Powertrain electrification is bifurcating thermal management requirements as hybrid architectures introduce simultaneous high-temperature engine zones and low-temperature battery compartments that legacy single-regime encapsulation cannot address. This structural tension is forcing material suppliers to develop dual-zone compatible systems.
Growth Catalysts
- EPA CAFE Standards:Corporate Average Fuel Economy mandates in the United States require faster catalyst light-off, directly expanding demand for thermal shields that reduce cold-start emissions.
- Acoustic comfort premiums:Passenger vehicle OEMs in Germany are specifying encapsulated engine bays as standard equipment on mid-tier trims to differentiate cabin quietness.
- Glass-mat thermoplastic advances:Improved GMT formulations now withstand sustained 180°C under-hood temperatures, opening applications in downsized turbocharged powertrains.
Market Restraints
- Polyol feedstock volatility:Polyurethane foam production depends on propylene oxide and MDI pricing, which fluctuate with petrochemical capacity utilization in the US Gulf Coast.
- REACH compliance costs:Europe's ECHA restrictions on halogenated flame retardants force complete reformulation of established foam grades, raising R&D amortization burdens.
- Aluminum-composite substitution ceiling:Mass savings from polymer-based encapsulation plateau above 2.0-liter displacement engines where metal shields retain cost advantages.
Strategic Opportunities
- India BIS thermal standards:India's Bureau of Indian Standards is drafting mandatory under-hood temperature limits for vehicles above 1.5-liter engines, creating first-mover advantages for compliant suppliers.
- Sensor-integrated modules:Embedding thermocouples and pressure sensors within encapsulation shells enables predictive thermal management algorithms for hybrid powertrains.
- Aftermarket retrofit channels:Independent service networks in Poland and Czechia are developing acoustic upgrade kits for aging vehicle fleets, bypassing OEM captive supply arrangements.
Industry Challenges
- Multi-physics simulation talent:Coupled thermal-acoustic finite element modeling requires rare expertise combining automotive NVH and heat transfer engineering.
- Homologation timeline compression:Europe's evolving F-Gas Directive creates uncertainty in foam blowing agent approvals, delaying program sign-offs by 8-14 months.
- Legacy powertrain inventory:Suppliers must maintain parallel production lines for internal combustion encapsulation while scaling electrified-vehicle variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Encapsulation Market |
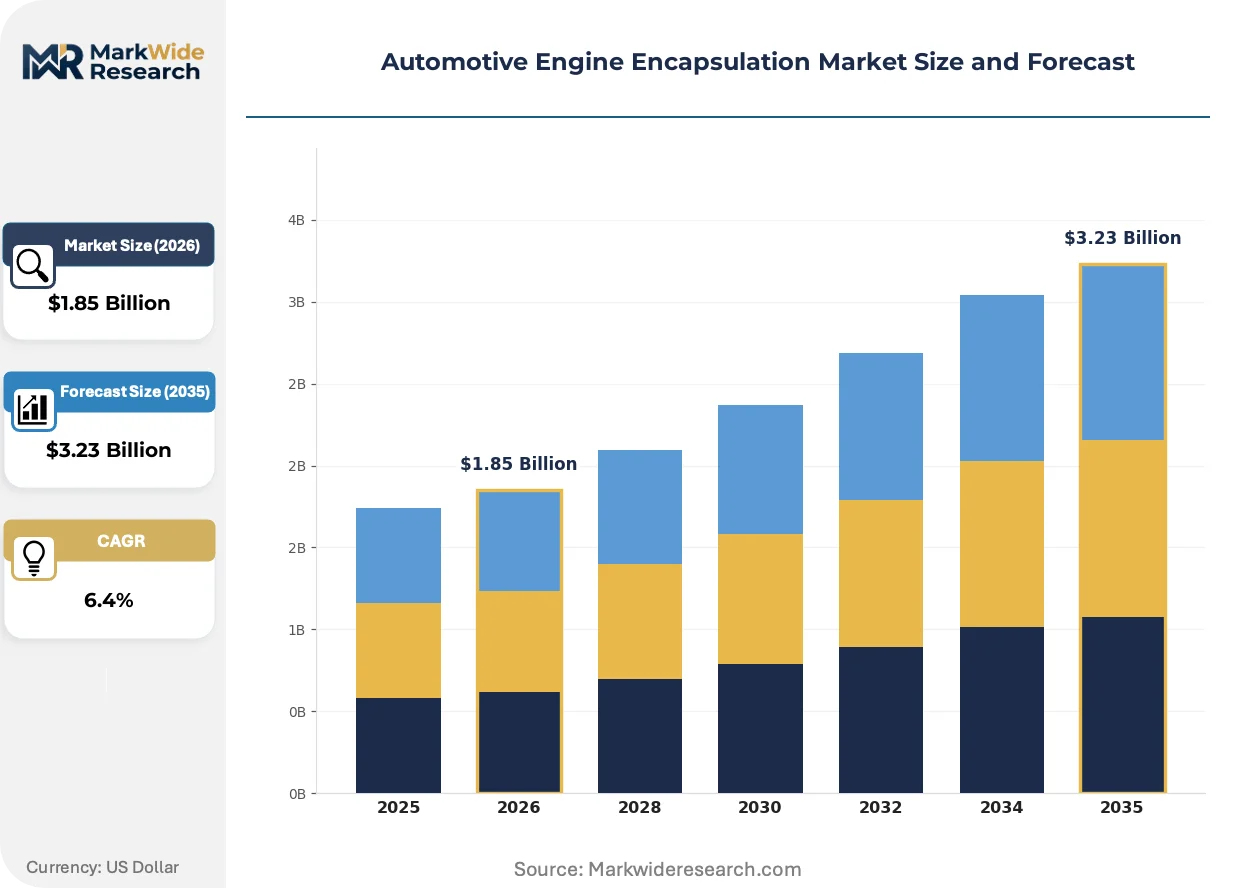
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Shields, Acoustic Covers, Oil Pans, Engine Trim Material: Plastic, Rubber, Metal, Composite Application: Noise Reduction, Thermal Management, Vibration Control, Aesthetic Enhancement End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Autoneum Holding AG, BASF SE, Continental AG, ElringKlinger AG, Roechling Group, Woco Group, Hennecke GmbH, Furukawa Electric Co., Ltd., 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Encapsulation Market Emerging Trajectories
Material science convergence with digital twin capabilities is redefining how encapsulation systems are specified, validated, and integrated into vehicle architectures. Suppliers now compete on simulation fidelity rather than sample iteration cycles.
Multi-layer composite structures are migrating from premium vehicle programs to mass-market platforms. These aluminum-polyurethane-glass mat sandwiches reduce radiated noise by 8-12 dB while cutting mass 40% versus steel shields. Volkswagen Group and Stellantis have adopted them for B-segment and C-segment engine bays. The technology is compressing traditional single-material supplier margins by favoring integrated module providers with lamination capabilities.
Europe's F-Gas Regulation is banning hydrofluorocarbon blowing agents with GWP above 150 from automotive foams by 2027. This industrial consequence forces polyurethane suppliers to validate hydrocarbon and hydrofluoroolefin alternatives without sacrificing cell structure uniformity. Thermal management applications are most affected, as dimensional stability under thermal cycling determines catalyst light-off performance.
Fleet procurement consolidation is concentrating volume with module suppliers capable of design-in at the concept phase. Tier-1 acoustic specialists now bypass traditional Tier-2 material converters, sourcing resins and fibers directly to capture margin. This pattern is most visible in Germany, where BMW and Mercedes-Benz have reduced their approved encapsulation supplier base from twelve to four since 2022.
Automotive Engine Encapsulation Market Segmentation
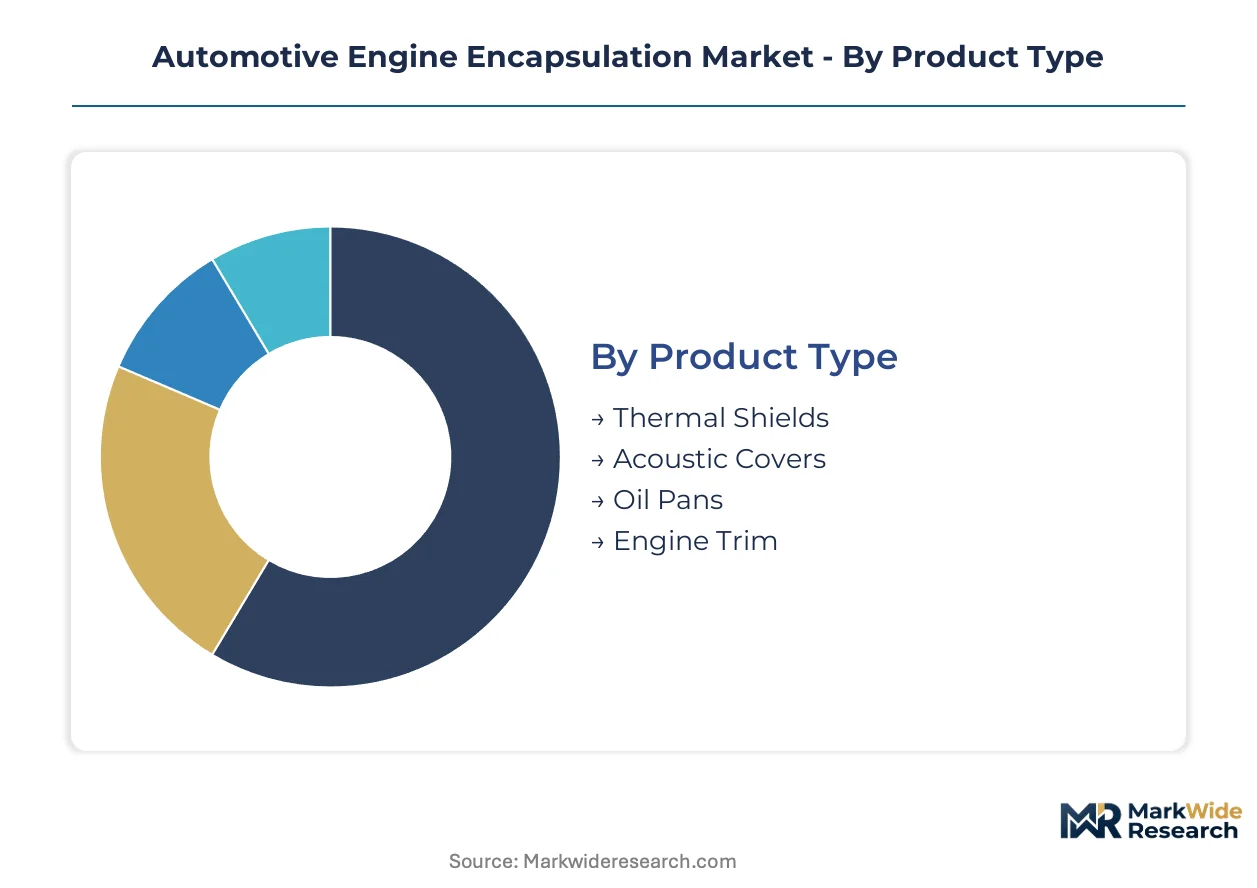
Engine encapsulation procurement cycles vary dramatically across product types, with thermal shields refreshing every 3-4 years versus acoustic covers spanning full vehicle generations. Material selection locks in at program kickoff, creating divergent supplier engagement timelines. End-user channel structure determines margin capture, with OEM direct contracts commanding premium pricing against aftermarket volume plays.
Product Type:
Thermal shields turn over fastest as emissions regulations tighten catalyst light-off requirements, while engine trim panels persist unchanged across mid-cycle facelifts.
- Thermal Shields:Aluminum-composite or steel laminates with ceramic coatings deflect radiant heat from exhaust manifolds and turbochargers. German premium OEMs specify multi-layer GMT variants for downsized turbocharged engines to meet EPA CAFE cold-start efficiency mandates.
- Acoustic Covers:Polyurethane foam or fiber-reinforced plastic shells absorb airborne powertrain noise across 500-4000 Hz frequency bands. Demand concentrates in Germany where Mercedes-Benz and BMW mandate encapsulated engine bays on mid-tier trims to differentiate cabin quietness against Japanese competitors.
- Oil Pans:Glass-mat reinforced thermoplastic or aluminum castings enclose crankcase lubricant systems while managing structural NVH. Renault and Stellantis specify composite variants for transverse front-drive architectures to reduce mass.
- Engine Trim:Decorative plastic or metal shrouds conceal ancillary components for aesthetic cohesion in open-hood displays. Porsche and Ferrari specify carbon-fiber reinforced polymer variants for engine bay visual premiumization.
Thermal shields anchor the volume base while acoustic covers gain share at the steepest rate.
Material:
Cost tier stratification separates commodity metals from engineered composites, with mid-range plastics capturing hybrid powertrain volume.
- Plastic:Polypropylene and polyamide formulations dominate mass-market thermal shields where temperature exposure stays below 150°C. Volkswagen Group specifies recycled-content grades for B-segment engine bays to meet EU Green Deal circularity targets.
- Composite:Glass-mat thermoplastic and aluminum-polyurethane sandwiches reduce mass 40% versus steel while withstanding sustained 180°C under-hood temperatures. Stellantis has adopted multi-layer composites for C-segment platforms, compressing single-material supplier margins.
- Metal:Aluminum and steel retain cost advantages above 2.0-liter displacement where polymer thermal stability plateaus. Ford and GM specify aluminum shields for full-size truck powertrains.
- Rubber:EPDM and silicone compounds seal encapsulation perimeters and isolate vibrational transmission paths. Hyundai-Kia specifies molded rubber grommets for engine cover mounting systems.
Plastic materials anchor the volume base while composites expand most quickly.
Application:
Functional priority determines specification rigor, with thermal management tied to regulatory compliance and noise reduction to brand positioning.
- Thermal Management:Encapsulation systems reduce cold-start warm-up periods and protect adjacent electronics from radiant heat flux. European OEMs prioritize this function to meet fleet CO2 emissions benchmarks under EMA frameworks.
- Noise Reduction:Acoustic barriers attenuate powertrain noise intrusion into passenger compartments. German luxury manufacturers specify this application as standard equipment to justify price premiums over volume brands.
- Vibration Control:Damped composite structures isolate structural-borne energy from engine mounts and driveline components. BMW employs this function to meet interior noise targets on electrified powertrains with irregular torque pulses.
- Aesthetic Enhancement:Surface-finished covers provide visual coherence for engine bay displays in premium vehicles. Ferrari and Lamborghini specify carbon-weave visible layers for collector-market differentiation.
Thermal management anchors the volume base while noise reduction climbs the fastest.
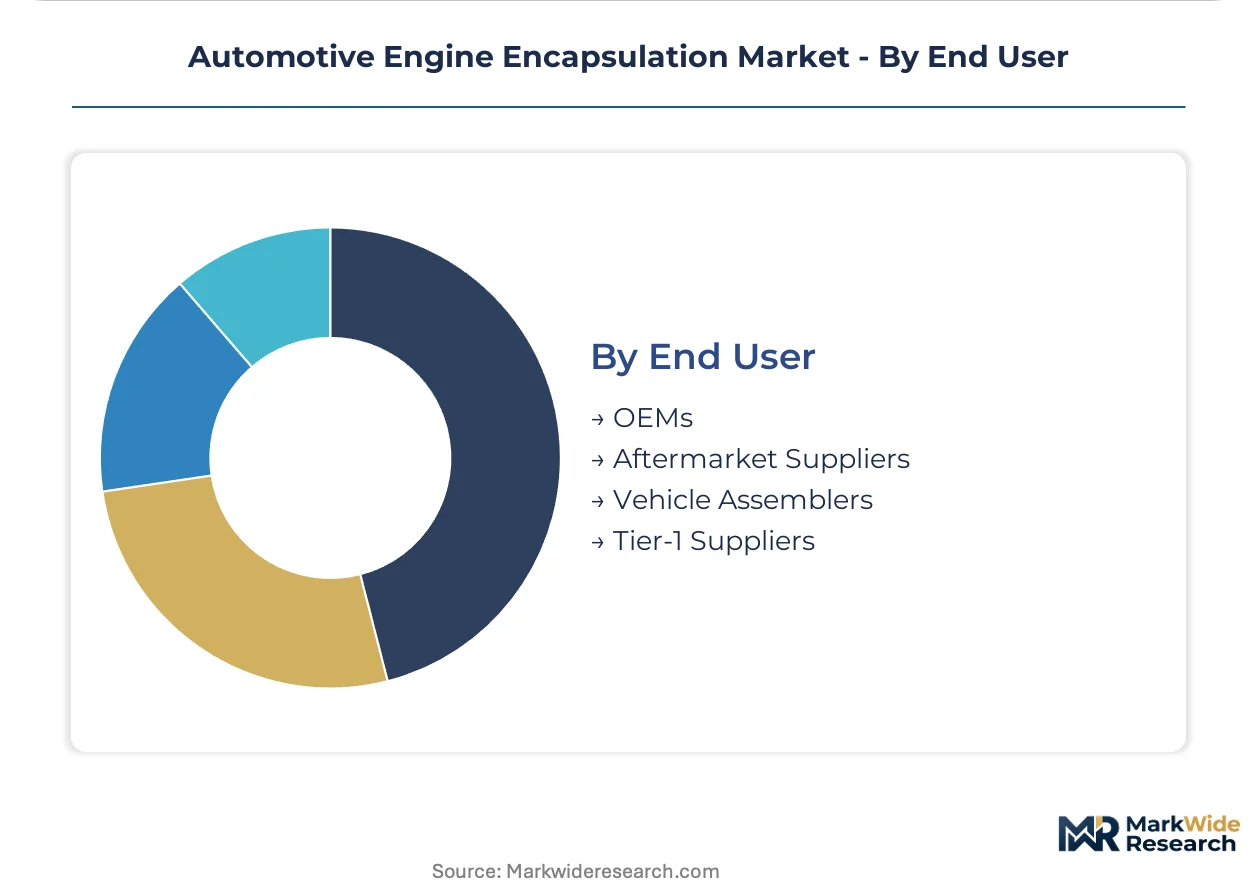
End User:
Customer type concentration shapes supplier capability requirements, with OEMs demanding design-in integration and aftermarket channels prioritizing inventory velocity.
- OEMs:Vehicle manufacturers specify encapsulation systems at concept phase, locking in suppliers for full program lifecycles. BMW and Mercedes-Benz have consolidated approved supplier bases from twelve to four since 2022.
- Tier-1 Suppliers:Integrated module providers like Autoneum and Continental combine acoustic engineering with thermal management capabilities to capture design-in contracts. These firms now source resins and fibers directly, bypassing traditional Tier-2 converters.
- Aftermarket Suppliers:Independent service networks in Poland and Czechia develop acoustic upgrade kits for aging vehicle fleets. These channels bypass OEM captive supply arrangements with lower certification barriers.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure encapsulation through OEM-directed sourcing agreements. Magna Steyr and Valmet Automotive specify systems per client brand requirements.
OEMs anchor the volume base while Tier-1 suppliers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA enforces some of the world's strictest vehicle noise and thermal regulations, anchoring European demand for advanced encapsulation systems and supplier consolidation around Stuttgart and Munich engineering clusters.
Germany
Mercedes-Benz and BMW mandate encapsulated engine bays across mid-tier trims to differentiate acoustic comfort against Japanese competitors. The F-Gas Regulation forces polyurethane suppliers to validate hydrofluoroolefin blowing agents by 2027. Stuttgart hosts Autoneum and Continental development centers where sensor-integrated thermal modules undergo validation for hybrid powertrains.
United States
Ford and GM specify aluminum thermal shields for full-size truck powertrains to meet EPA CAFE cold-start efficiency mandates. The NHTSA coordinates with EPA on fleet emissions benchmarking that indirectly requires faster catalyst light-off. Detroit's supplier corridor concentrates foam lamination capacity serving Michigan and Ohio assembly plants.
China
Domestic OEMs accelerate composite encapsulation adoption as MIIT tightens passenger vehicle fuel consumption limits under dual carbon goals. GB standards for under-hood component flammability drive material reformulation investments. Shanghai and Yangtze River Delta clusters host joint ventures between European acoustic specialists and local Tier-1 converters.
India
Maruti Suzuki and Hyundai-Kia expand encapsulated engine bay specifications as BIS drafts mandatory under-hood temperature limits for vehicles above 1.5-liter displacement. The PLI scheme for automotive components subsidizes domestic manufacturing of thermal-acoustic modules. Chennai and Pune assembly corridors attract first-mover suppliers qualifying for local content requirements.
Japan
Toyota and Honda integrate encapsulation into hybrid architectures requiring dual-zone thermal management for simultaneous high-temperature engine and low-temperature battery compartments. METI coordinates industry consortia on next-generation material standards. Nagoya's Chubu region concentrates GMT formulation expertise serving domestic and export programs.
Automotive Engine Encapsulation Market Vendor Landscape
Integrated module providers and material specialists split the market along design-in capability versus commodity supply. Supplier consolidation has reduced approved vendor bases at major OEMs from twelve to four since 2022. Two strategic archetypes dominate: acoustic engineering heritage firms with thermal management integration capabilities, and chemical conglomerates anchoring material innovation through polyurethane and composite formulations. Competitive moves center on direct resin and fiber sourcing to capture margin, and sensor integration to enable predictive thermal algorithms.
Within the integrated module tier, Autoneum Holding AG and Continental AG exemplify suppliers combining acoustic engineering with thermal management capabilities to secure design-in contracts at concept phase. BASF SE anchors the material innovation archetype through polyurethane formulation expertise. These three firms represent the consolidation trajectory as OEM procurement shifts toward single-source module responsibility.
| Leading Market Players |
|---|
| Autoneum Holding AG |
| BASF SE |
| Continental AG |
| ElringKlinger AG |
| Roechling Group |
| Woco Group |
| Hennecke GmbH |
| Furukawa Electric Co., Ltd. |
| 3M |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp petrochemical corridor's freight cost dynamics compress margins for polyurethane foam producers while amplifying price differentiation between configured-to-order thermal-acoustic modules and standard catalog shields. This logistics tension concentrates pricing power with integrated module suppliers capable of direct resin sourcing, forcing Tier-2 converters toward commodity contract structures.
Pricing Analysis
The customization-premium spread separates configured-to-order multi-layer composite systems from standard single-material shields by a factor reflecting design-in engineering hours and homologation amortization. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM direct contracts commanding substantial premiums over aftermarket channels. Cost compression in commodity foam grades is intensifying because REACH reformulation investments raise fixed cost absorption thresholds. Aftermarket distributors exhibit highest price sensitivity, while German premium OEMs prioritize thermal-acoustic performance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced GMT formulation technology limit technology transfer to certain Asian manufacturing jurisdictions, constraining supply expansion. Production concentrates in Germany, China, and the United States, with raw material flows drawing from propylene oxide crackers along the US Gulf Coast and MDI facilities in Belgium and Japan. Supply chain risk centers on single-source vulnerability for hydrofluoroolefin blowing agents as the F-Gas Regulation phases out legacy chemistries. Distribution runs through Tier-1 module suppliers delivering sequenced parts to OEM assembly plants, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive engine encapsulation is approaching a platform-economics inflection as hybrid powertrain architectures force interoperability between thermal management and battery conditioning systems. This ecosystem shift rewards suppliers capable of cross-domain module integration over single-function component providers.
For Market Incumbents: Insulate core supplier relationships by embedding design engineers within OEM platform development teams before concept freeze gates. Lock in multi-year resin supply agreements to hedge against polyol feedstock volatility threatening margin stability. Prioritize sensor-integrated module development to capture predictive thermal management data streams that emerging electronics suppliers cannot replicate.
For New Entrants and Emerging Players: Pursue acoustic upgrade kit opportunities in Poland and Czechia aftermarket channels where certification barriers remain lower than OEM captive supply. Target India's BIS thermal standard compliance window before mandatory under-hood temperature limits take effect for vehicles above 1.5-liter displacement. Establish direct relationships with domestic OEMs in China bypassing European joint venture structures.
For Investors and Strategic Acquirers: Sensor-integrated thermal module specialists with hybrid powertrain validation records represent the most defensible acquisition archetype for medium-term value capture. Long-term viability hinges on dual-zone thermal management capabilities spanning internal combustion and electrified architectures. Watch for consolidation signals when OEM approved supplier bases compress below three approved vendors per platform.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Zone Thermal Module Development | Addresses hybrid powertrain requirements that legacy single-regime encapsulation cannot satisfy for BMW and Mercedes-Benz platforms. |
| Hydrofluoroolefin Blowing Agent Validation | Ensures REACH and F-Gas Regulation compliance for European thermal shield production without cell structure degradation. |
| Direct Resin and Fiber Sourcing | Bypasses Tier-2 converters to capture margin compression from consolidated OEM procurement at Volkswagen Group and Stellantis. |
| Sensor Integration Partnership | Feeds thermal data into Continental and Autoneum vehicle energy management systems for predictive algorithms. |
| India Manufacturing Localization | Qualifies for PLI scheme subsidies while meeting BIS thermal standards for Maruti Suzuki and Hyundai-Kia supply. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier production schedules anchors the qualitative findings in observable program timelines. Primary interviews with thermal management directors, acoustic NVH engineers, procurement leads at German premium OEMs, and aftermarket distribution heads in Central Europe combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA CAFE compliance filings, and ECHA substance restriction updates. Bottom-up build from content-per-vehicle assumptions and top-down triangulation against fleet emissions benchmarks ensure methodological consistency.
Calibration against historical program adoption curves and regulatory phase-in schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material grade, application function, and OEM tier stratification. CAGRs derived from regression analysis of content-per-vehicle trends and powertrain mix shifts, with forecast inputs incorporating MIIT fuel consumption trajectory for China and EPA fleet efficiency benchmarks for the United States.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, petrochemical feedstock pricing, or electrification subsidy regimes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory phase-in timing and OEM platform consolidation patterns. Material shifts in hybrid powertrain architecture prevalence or F-Gas Regulation enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Active Seat Headrests Market