
 Global Automotive Cigarette Lighters Market | 2026-2036
Global Automotive Cigarette Lighters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Cigarette Lighters Market Intelligence
OEM procurement for in-dash power accessories is consolidating as passenger car manufacturers standardize around USB-C and wireless charging modules. BESTEK leverages its adapter specialization to sustain aftermarket channel presence across North American auto parts retailers. Shenzhen Everpower Electronics anchors volume production for budget-tier dual socket lighters serving fleet operators in emerging markets. NingBo XINHAI Electric Co., LTD differentiates through heat-resistant material certifications that compete for tier-one supplier status with European vehicle manufacturers.
Automotive cigarette lighters are standardized 12-volt DC power sockets, historically using a bimetallic strip and heating coil to generate ignition temperatures near 650 degrees Celsius, now predominantly repurposed as universal power outlets for consumer electronics and vehicle accessories. Ceramic heating elements in electronic ignition lighters dominate OEM fitment due to faster activation cycles and elimination of open-coil fire risks. USB charging ports represent the fastest-growing product category as passenger car and recreational vehicle applications displace traditional socket formats. Aftermarket retailers capture margin pools in dual socket lighters where installation complexity favors specialized automotive dealers over general electronics channels.
The US NHTSA and EPA influence automotive electrical component standards through flammability testing and material restriction protocols, while China's SAMR enforces GB certification for socket assemblies sold in domestic vehicle production. REACH compliance in Europe limits heavy metal content in lighter housings, redirecting supplier investments toward heat-resistant polymer formulations. Stakeholders must monitor regulatory divergence between emissions-focused jurisdictions and consumer-safety regimes to align product development roadmaps with divergent certification requirements.
Market Dynamics
Vehicle electrification is compressing demand for legacy 12-volt ignition sockets while simultaneously expanding power-accessory requirements across hybrid and battery-electric platforms. This structural tension is forcing component suppliers to pivot from fire-starting hardware toward multi-port charging infrastructure.
Growth Catalysts
- Two-wheeler electrification:Southeast Asian markets are generating fresh demand for weather-resistant power sockets as electric motorcycles and scooters replace internal combustion fleets across Indonesia, Vietnam, and Thailand.
- RoHS Directive:The EU's material restriction framework is accelerating supplier transitions to lead-free solder and cadmium-free contacts, creating certification premiums for compliant manufacturers.
- Ceramic heating elements:Electronic ignition systems with ceramic cores are penetrating OEM fitment due to faster heat cycles and elimination of open-coil fire hazards in passenger compartments.
Market Restraints
- Copper price volatility:Electrical contact manufacturers face margin compression from fluctuating copper and brass input costs, with limited pass-through power against consolidated automotive OEM procurement.
- USB-C substitution:Universal charging standards in consumer electronics are rendering 12-volt sockets redundant for device power, cannibalizing aftermarket replacement cycles.
- Supply concentration:Heat-resistant polymer formulations for housing materials depend on a narrow base of specialized compounders in Germany and Japan, creating single-source vulnerability.
Strategic Opportunities
- Recreational vehicle retrofit:North American RV owners are installing dual-socket charging banks to support off-grid power needs, creating a premium aftermarket channel distinct from mass-market auto retail.
- GB standards alignment:China's domestic certification requirements for socket assemblies are creating captive supply relationships for manufacturers achieving early SAMR approval.
- Fleet telematics integration:Commercial vehicle operators are demanding socket-embedded voltage monitoring for asset tracking, merging power access with IoT functionality.
Industry Challenges
- REACH compliance timelines:European chemical registration deadlines are forcing reformulation of housing polymers, with testing cycles extending 18-24 months and delaying product launches.
- Legacy vehicle integration:Aftermarket installers face wiring-harness incompatibility when retrofitting modern USB modules into pre-2010 vehicle architectures with fused 12-volt circuits.
- Cross-border certification:Divergent flammability testing protocols between NHTSA, ECE R10, and China's GB/T standards multiply validation costs for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Cigarette Lighters Market |
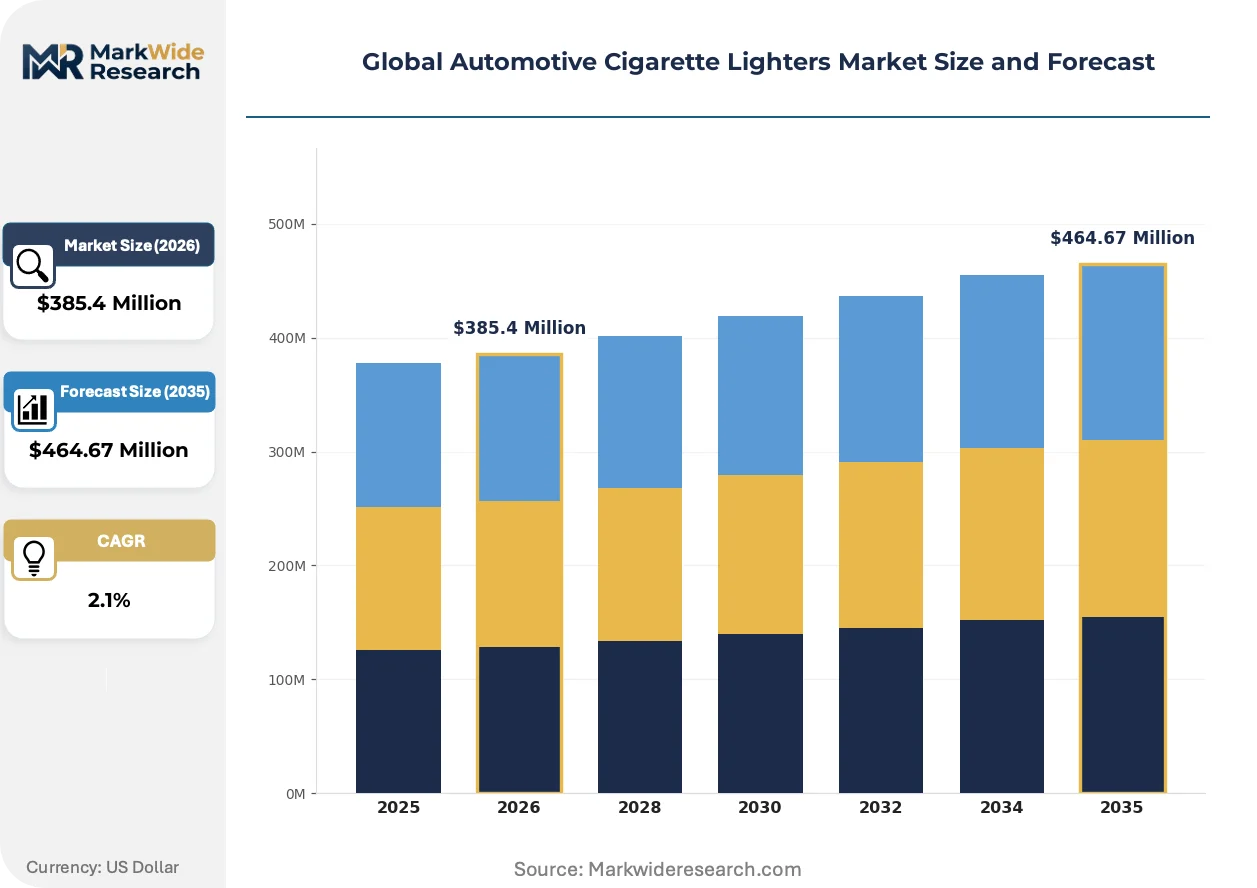
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $464.67 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Lighters, Electronic Ignition Lighters, USB Charging Ports, Dual Socket Lighters, Built-in Fuse Lighters Technology: Ceramic Heating, Piezoelectric Ignition, Inductive Charging, LED Indicators, Heat-Resistant Materials Application: Passenger Cars, Commercial Vehicles, Two Wheelers, Recreational Vehicles, Heavy Duty Trucks End User: Vehicle Manufacturers, Aftermarket Retailers, Automotive Dealers, Fleet Operators |
| Companies Covered | BESTEK, Aukey, Circle City Copperworks, Hangzhou Tonny Electric & Tools, ChargerWise, Shenzhen Everpower Electronics, Metallic Products Corporation, Omaker, NingBo XINHAI Electric Co., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Cigarette Lighters Market Strategic Shifts & Innovations
Power delivery architectures are fragmenting across three converging pathways: wireless charging surfaces, high-wattage USB-C modules, and retained 12-volt sockets for legacy accessories. Component suppliers must now engineer for protocol multiplicity rather than socket standardization.
USB-C Power Delivery modules are overtaking traditional 12-volt outlets in premium passenger vehicle segments. These 100-watt-capable ports support laptop charging and rapid smartphone replenishment. European OEMs led by German luxury manufacturers are deleting lighter sockets entirely from center consoles. The technology is overtaking residual demand for coiled heating elements in new vehicle design.
REACH Annex XVII restrictions on phthalates and heavy metals are forcing housing material substitutions across European supply chains. Compounders are accelerating heat-resistant polyamide formulations to replace legacy ABS blends. Tier-one suppliers serving Stuttgart and Munich manufacturing clusters are absorbing 15-20% raw material cost premiums to maintain CE marking compliance.
Fleet procurement departments are consolidating vendor relationships around integrated power-and-data modules. Commercial vehicle buyers in the United States are specifying socket assemblies with embedded CAN bus connectivity for telematics integration. This specification compression is squeezing standalone lighter manufacturers from approved vendor lists at major trucking and logistics operators.
Global Automotive Cigarette Lighters Market Segmentation
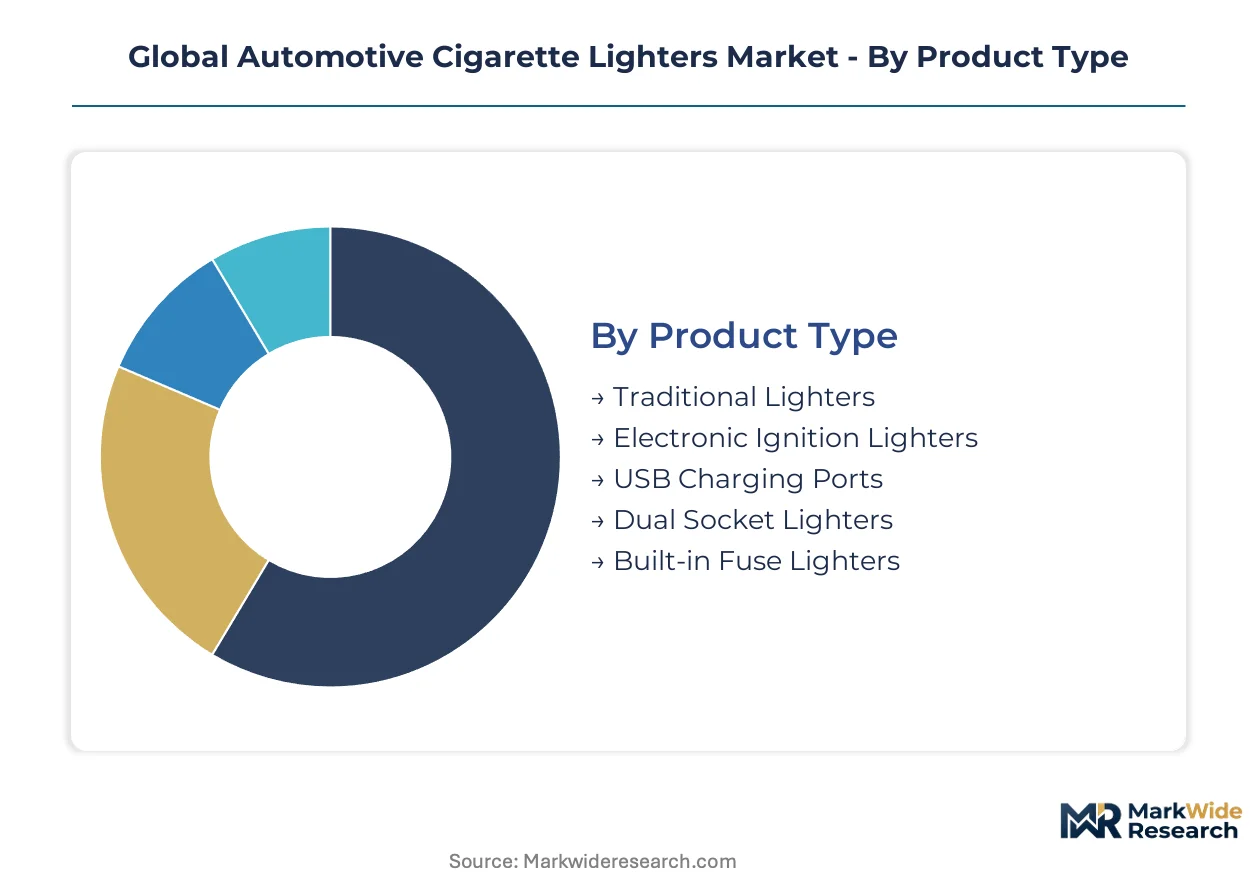
Automotive cigarette lighter segmentation reveals how power-delivery architectures fragment across legacy 12-volt sockets, electronic ignition systems, and emerging USB-C modules. Suppliers must engineer for protocol multiplicity rather than socket standardization as vehicle electrification reshapes component requirements.
Product Type:
Supply concentration for socket assemblies tilts toward manufacturers with heat-resistant polymer capabilities and multi-certification portfolios across NHTSA, ECE R10, and GB/T standards.
- USB Charging Ports:Power Delivery modules capable of 100-watt output support laptop charging and rapid smartphone replenishment. German luxury manufacturers are deleting traditional lighter sockets entirely from center consoles, concentrating procurement with tier-one electronics integrators.
- Electronic Ignition Lighters:Ceramic heating elements activate faster than bimetallic strips while eliminating open-coil fire hazards in passenger compartments. OEM fitment concentrates with suppliers holding REACH-compliant material certifications for European vehicle production.
- Traditional Lighters:Standardized 12-volt DC sockets with bimetallic strip heating coils near 650 degrees Celsius now serve primarily aftermarket replacement cycles for legacy vehicle fleets.
- Dual Socket Lighters:Installation complexity favors specialized automotive dealers over general electronics channels, capturing margin pools in recreational vehicle and commercial fleet retrofit applications.
- Built-in Fuse Lighters:Overcurrent protection integrated into housing assemblies addresses liability concerns for fleet operators managing mixed-voltage accessory loads.
Today's leader: USB Charging Ports. Tomorrow's challenger: Electronic Ignition Lighters.
Technology:
Cost tier differentiation separates premium ceramic formulations from budget-tier piezoelectric alternatives, with raw material premiums of 15-20% for REACH-compliant European supply.
- Ceramic Heating:Electronic ignition cores penetrate OEM fitment through faster heat cycles and elimination of open-coil fire risks. Demand concentrates with Stuttgart and Munich manufacturing clusters absorbing material cost premiums to maintain CE marking compliance.
- Heat-Resistant Materials:Polyamide formulations replace legacy ABS blends under REACH Annex XVII restrictions on phthalates and heavy metals. Compounders in Germany and Japan control specialized polymer supply, creating single-source vulnerability for housing manufacturers.
- Piezoelectric Ignition:Mechanical spark generation dominates budget-tier production for emerging market fleet operators where electronic component reliability remains uncertain.
- Inductive Charging:Wireless power surfaces integrate into center console designs, bypassing socket hardware entirely in premium passenger vehicle segments.
- LED Indicators:Voltage monitoring displays merge power access with IoT functionality for commercial vehicle telematics integration.
Technology leadership currently resides with Ceramic Heating. Heat-Resistant Materials are climbing the fastest as regulatory deadlines force reformulation cycles.
Application:
Volume concentration tracks two-wheeler electrification across Southeast Asian markets where weather-resistant power sockets address new power-accessory needs.
- Two Wheelers:Electric motorcycles and scooters across Indonesia, Vietnam, and Thailand generate fresh demand for weather-resistant socket assemblies. Local assemblers specify GB-compliant components for domestic production while exporting to regional markets.
- Passenger Cars:USB-C and wireless charging modules displace traditional outlets in premium segments. European OEMs led by German manufacturers are standardizing around multi-port charging infrastructure.
- Recreational Vehicles:North American owners install dual-socket charging banks for off-grid power needs, creating a premium aftermarket channel distinct from mass-market auto retail.
- Commercial Vehicles:Fleet procurement departments specify socket-embedded voltage monitoring for asset tracking, merging power access with CAN bus connectivity.
- Heavy Duty Trucks:Long-haul operators demand fused assemblies capable of sustaining continuous accessory loads across extended duty cycles.
Application dominance currently sits with Passenger Cars. Two Wheelers represent the steepest expansion trajectory as electrification accelerates across Southeast Asia.
End User:
Customer type determines margin structure, with vehicle manufacturers extracting volume discounts while fleet operators pay premiums for integrated telematics functionality.
- Vehicle Manufacturers:OEM procurement consolidates around tier-one suppliers with multi-certification portfolios. Standardization around USB-C and wireless charging modules compresses demand for legacy ignition socket hardware.
- Fleet Operators:Commercial vehicle buyers in the United States specify socket assemblies with embedded CAN bus connectivity, squeezing standalone lighter manufacturers from approved vendor lists.
- Aftermarket Retailers:Channel presence depends on adapter specialization and dual-socket portfolios as vehicle manufacturers phase out factory-installed lighters.
- Automotive Dealers:Installation complexity for modern USB modules in pre-2010 vehicle architectures favors specialized dealers over general electronics channels.
Current procurement concentration centers on Vehicle Manufacturers. Fleet Operators are gaining share fastest as telematics integration redefines power-accessory specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest production volume for automotive power accessories while Germany sets the regulatory pace for material compliance standards across European supply chains.
China
Electric two-wheeler manufacturing in Jiangsu and Zhejiang provinces generates substantial demand for weather-resistant socket assemblies. SAMR enforces GB certification requirements that create captive supply relationships for domestic component manufacturers. Shenzhen anchors volume production for budget-tier dual socket lighters serving fleet operators throughout Southeast Asian export markets.
Germany
Stuttgart and Munich manufacturing clusters absorb 15-20% raw material cost premiums to maintain REACH-compliant CE marking for polymer housings. ECHA deadlines under Annex XVII restrictions are forcing 18-24 month reformulation cycles for phthalate-free compounds. Baden-Württemberg suppliers dominate tier-one procurement relationships with luxury vehicle manufacturers deleting traditional lighter sockets entirely.
United States
Recreational vehicle owners across the Mountain West and Pacific Northwest install premium dual-socket charging banks for off-grid power needs. NHTSA flammability testing protocols diverge from ECE R10 standards, multiplying validation costs for global suppliers seeking cross-border certification. Texas-based fleet operators specify CAN bus-embedded voltage monitoring for commercial vehicle telematics integration.
Indonesia
Electric motorcycle assembly lines in Jakarta and Surabaya are generating fresh demand for GB-compliant socket components. The country's national standards body aligns domestic certification with Chinese GB frameworks to facilitate regional component trade. Local assemblers specify weather-resistant housings for tropical humidity conditions across archipelago distribution networks.
Japan
Heat-resistant polymer compounders in Osaka and Nagoya control specialized supply for housing materials, creating single-source vulnerability for downstream manufacturers. METI standards for automotive electrical components emphasize fire-safety protocols that exceed baseline international requirements. Chubu region suppliers focus on ceramic heating element formulations for premium OEM fitment in domestic vehicle production.
Global Automotive Cigarette Lighters Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Tier-one electronics integrators capture USB-C and wireless charging procurement from luxury vehicle manufacturers. Mid-scale adapter specialists sustain aftermarket channel presence through North American auto parts retail networks. Budget-tier volume producers anchor emerging market supply for fleet operators. Competitive moves concentrate on portfolio diversification toward multi-port charging infrastructure and geographic expansion into Southeast Asian two-wheeler electrification corridors.
Among China-based manufacturers, Shenzhen Everpower Electronics and NingBo XINHAI Electric Co., LTD exemplify divergent strategic positions within the supplier base. Shenzhen Everpower Electronics occupies the volume-driven tier serving budget-conscious fleet procurement across developing markets. NingBo XINHAI Electric Co., LTD sits within the certification-premium segment where heat-resistant material approvals compete for European OEM supplier status. BESTEK represents the adapter specialization archetype sustaining aftermarket relevance as factory-installed lighters phase out across passenger vehicle segments.
| Leading Market Players |
|---|
| BESTEK |
| Aukey |
| Circle City Copperworks |
| Hangzhou Tonny Electric & Tools |
| ChargerWise |
| Shenzhen Everpower Electronics |
| Metallic Products Corporation |
| Omaker |
| NingBo XINHAI Electric Co., LTD |
| Others |
Cost & Logistics Intelligence
Copper and brass futures volatility on the London Metal Exchange cascades through contact manufacturing into three distinct pricing tiers across automotive power socket procurement. Raw material premiums compound with REACH compliance costs to stratify supplier positioning between budget-tier volume producers and certification-premium specialists serving European OEMs.
Pricing Analysis
Capacity additions in China's Zhejiang and Jiangsu provinces are reshaping price floors for standard 12-volt socket assemblies. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified European suppliers absorbing 15-20% material premiums from Shenzhen-based volume producers serving Southeast Asian fleet operators. Cost compression in the economy tier intensifies because copper price pass-through remains limited against consolidated automotive OEM procurement. Fleet operators in emerging markets exhibit highest price sensitivity, while German luxury manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
Aftermarket refurbishment flows for legacy 12-volt sockets create secondary material recovery channels, particularly for brass contact assemblies and polymer housings. Manufacturing concentration centers on China, Germany, and Japan, with heat-resistant polyamide formulations drawing from specialized compounders in Osaka and Nagoya. Single-source vulnerability persists for REACH-compliant housing materials resting on a narrow German-Japanese supplier base. Distribution runs through tier-one electronics integrators for OEM fitment and specialized automotive dealers for aftermarket retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive power accessories hinges on ceramic heating element adoption and USB-C module penetration displacing legacy socket hardware. Certification premiums for REACH-compliant materials create defendable pricing power for suppliers achieving early ECHA approval.
For Market Incumbents: Deploy backward integration into heat-resistant polymer compounding to secure captive supply of REACH-certified housing materials. Consolidate procurement relationships with Southeast Asian two-wheeler assemblers before GB standards alignment creates captive supply relationships for domestic Chinese manufacturers. Channel control through specialized automotive dealers remains essential as installation complexity favors technical expertise over general electronics retail.
For New Entrants and Emerging Players: Direct-to-fleet digital platforms offer the lowest-friction route to commercial vehicle procurement departments specifying CAN bus-embedded voltage monitoring. Recreational vehicle retrofit in North American Mountain West and Pacific Northwest markets presents the most penetrable white-space, with premium dual-socket charging banks commanding margin pools distinct from mass-market auto retail. Target telematics-integrated power modules as the specific go-to-market angle for fleet operator specifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale adapter specialists sustaining aftermarket relevance through USB-C and wireless charging portfolio diversification. Long-term viability across the five-to-ten year window favors suppliers with multi-certification portfolios spanning NHTSA, ECE R10, and GB/T standards. Monitor European OEM socket deletion timelines as the critical inflection signal for legacy lighter demand compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Heating Element Scale-Up | Faster OEM fitment penetration through elimination of open-coil fire hazards in passenger compartments. |
| REACH-Compliant Material Certification | CE marking maintenance absorbs cost premiums but secures tier-one supplier status with Stuttgart and Munich clusters. |
| USB-C Power Delivery Module Launch | 100-watt output capability displaces traditional 12-volt sockets in premium passenger vehicle center consoles. |
| Southeast Asian Distribution Expansion | Weather-resistant socket demand from Indonesian and Vietnamese electric two-wheeler assemblers anchors volume growth. |
| Fleet Telematics Integration Partnership | CAN bus connectivity specifications squeeze standalone lighter manufacturers from approved vendor lists at commercial operators. |
Research Approach
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and customs trade records; and technical patent filings — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned ceramic heating element manufacturers in Japan's Chubu region, heat-resistant polymer compounders in Germany's Baden-Württemberg, and fleet procurement departments across Texas-based logistics operators.
Data-stream reconciliation applied analytical frameworks across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from modeled adoption curves for USB-C displacement of legacy sockets and ceramic element penetration rates. Forecast inputs incorporated SAMR certification timelines for Chinese domestic production and ECHA reformulation cycles for phthalate-free polymer alternatives.
The model assumes a particular technology adoption path; alternative pathways for wireless charging surface integration would alter the outlook if inductive power delivery bypasses socket hardware entirely in premium segments. Forecasts reflect assumptions around two-wheeler electrification rates and regulatory divergence between emissions-focused and consumer-safety jurisdictions. Practitioners should monitor European OEM center console redesign announcements and Chinese GB standards enforcement actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Exhaust Emission Control Device Market
Automotive Components
Global Automotive HUD Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Commutator Market
Automotive Components
India Automotive Stamping Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Chrome Accessories Market