
 Positive Displacement Motor Market | 2026-2036
Positive Displacement Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Displacement Motor Market Analysis
API Specification 7-1 is reorganizing competitive access for positive displacement motor suppliers serving oilfield directional drilling. Parker Hannifin leverages its hydraulics portfolio to anchor industrial gear motor supply for manufacturing automation. Baker Hughes competes through integrated drilling system architectures that bundle screw motors with measurement-while-drilling tools. Schlumberger dominates technology leadership in high-temperature vane motor designs rated above 200 degrees Celsius for geothermal and deep-well applications.
A positive displacement motor converts hydraulic or pneumatic fluid energy into mechanical rotary motion through a fixed volume displacement mechanism per revolution, typically operating at differential pressures between 500 and 3,000 psi with output torques proportional to pressure drop across the power section. Screw motors in the product type category lead oil and gas drilling applications due to superior torque output in slim-hole configurations, while gear motors sustain margin pools across industrial equipment installations where volumetric efficiency and cost predictability outweigh extreme-duty requirements. Piston motors occupy the highest-performance tier in aerospace and construction end-user segments where variable displacement control enables precise load matching.
The US EPA regulates hydraulic fluid discharge standards for oilfield equipment, compelling manufacturers to certify seal compatibility with biodegradable synthetic formulations. API Specification 7-1 and ISO 9001 quality frameworks govern material traceability and fatigue testing protocols that determine market access for drilling motor suppliers. OSHA mandates lockout-tagout compatibility in industrial hydraulic systems, shaping control interface designs across manufacturing and construction end-user deployments. Stakeholders must monitor how carbon intensity disclosure requirements from the EU CSRD and comparable US SEC climate rules redirect capital toward electrified actuation alternatives in European and North American industrial markets.
Market Dynamics
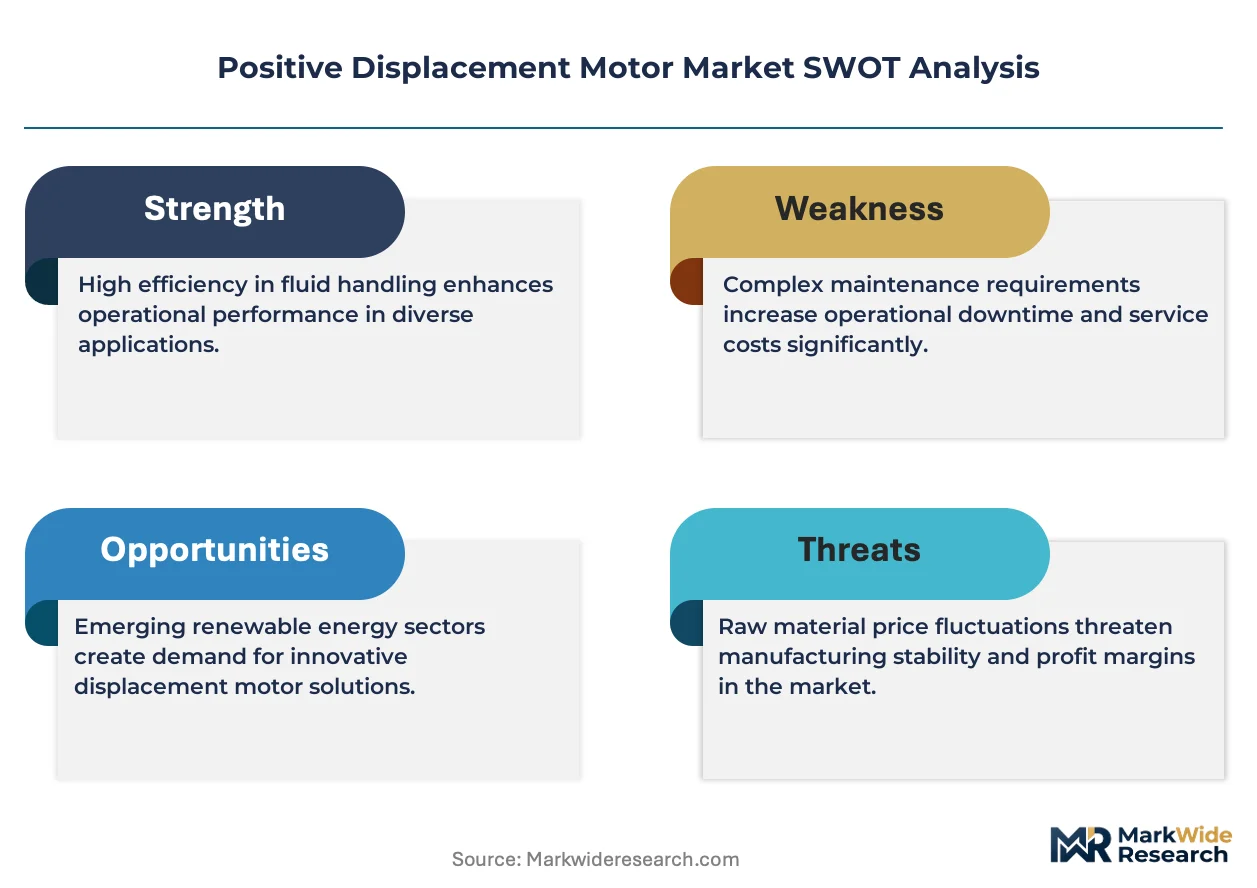
API Specification 7-1 qualification requirements are restructuring competitive access for drilling motor suppliers, forcing capital retooling toward fatigue-tested power sections and full material traceability chains that smaller fabricators cannot finance.
Growth Catalysts
- Extended-reach drilling programs:Permian Basin operators in Texas and New Mexico require higher-performance screw motor systems to access laterals beyond 15,000 feet, pulling demand for advanced elastomer stator compounds.
- OSHA lockout-tagout mandates:Industrial hydraulic systems across manufacturing and construction must integrate compatible control interfaces, expanding replacement cycles for legacy gear motor installations.
- REACH-compliant biodegradable fluids:European oilfield equipment procurement now specifies seal compatibility with synthetic ester formulations, opening specification wins for suppliers with pre-certified compound libraries.
Market Restraints
- Specialized elastomer supply concentration:High-temperature stator compounds depend on nitrile and hydrogenated nitrile feedstocks concentrated among three chemical suppliers, exposing motor fabricators to input cost volatility.
- Deep-well technical ceiling:Vane motor designs face hard temperature limits at 200 degrees Celsius, excluding suppliers from geothermal and ultra-deep drilling bids without full architecture redesign.
- Electrification substitution pressure:Variable frequency drive systems displace hydraulic power sections in manufacturing automation, compressing addressable volume for industrial gear motor categories.
Strategic Opportunities
- EU CSRD carbon disclosure rules:Capital redirection toward electrified actuation creates white space for hybrid hydraulic-electric motor architectures in European industrial markets.
- Geothermal energy expansion:Japan's METI feed-in tariff revisions for binary-cycle plants pull demand for high-temperature vane motors rated above standard oilfield specifications.
- Digital twin integration:Convergence of physics-based motor modeling with real-time downhole telemetry enables predictive maintenance contracts that unbundle hardware from service revenue.
Industry Challenges
- API 7-1 certification timeline compression:Fatigue testing protocols now require 18-month validation cycles, straining working capital for mid-tier suppliers without captive testing facilities.
- Legacy MWD integration complexity:Screw motor power sections must interface with third-party measurement-while-drilling toolchains, demanding proprietary API negotiations that delay field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Displacement Motor Market |
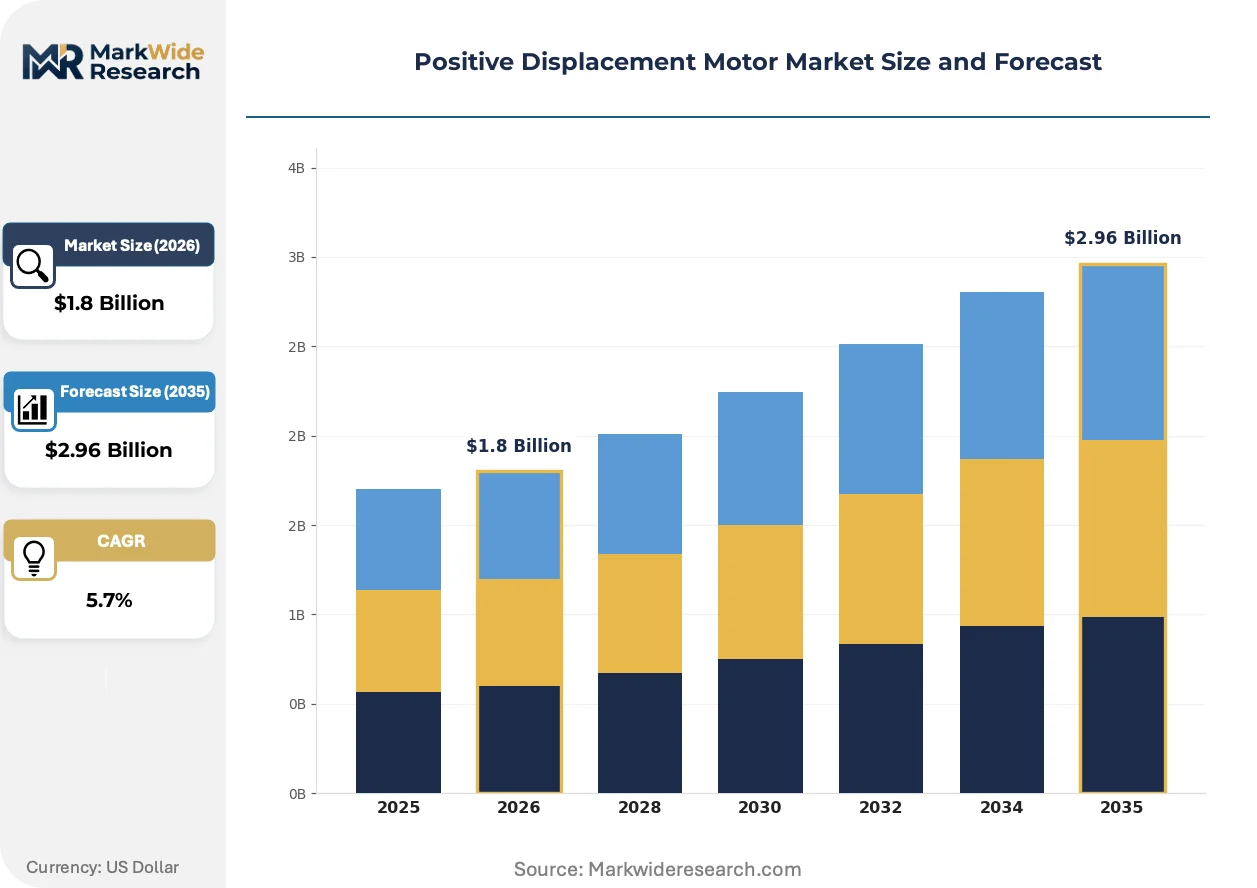
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Motors, Piston Motors, Screw Motors, Vane Motors Application: Hydraulic Systems, Industrial Equipment, Oil & Gas, Water Management End User: Manufacturing, Construction, Aerospace, Automotive Technology: Electromechanical, Pneumatic, Hydrodynamic, Thermal |
| Companies Covered | Parker Hannifin, Bosch Rexroth, Eaton Corporation, Halliburton, Schlumberger, Nabors Industries, Baker Hughes, MATRRIX Energy Technologies, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Displacement Motor Market Emerging Trajectories
Digital instrumentation and materials science are splitting the positive displacement motor market into distinct performance tiers, with specification divergence between commodity industrial supply and engineered oilfield systems accelerating vendor specialization.
Advanced elastomer compounding for stator liners is bifurcating the screw motor category. Nitrile-based formulations retain dominance in standard-temperature drilling, while hydrogenated nitrile and perfluoroelastomer compounds capture high-temperature geothermal and deep-gas applications. Permian Basin operators now specify compound grade by wellbore thermal profile, compressing margin pools for undifferentiated suppliers.
EPA hydraulic fluid discharge standards are forcing seal architecture redesign across US oilfield equipment. Biodegradable synthetic formulations degrade conventional nitrile seals within 500 operating hours, compelling fabricators to validate fluorocarbon and thermoplastic elastomer alternatives. Offshore Gulf of Mexico deployments face the tightest compliance windows, with operators now requiring pre-certified fluid-seal compatibility documentation in procurement tenders.
Buyer concentration among supermajor drilling contractors is compressing procurement cycles and unbundling aftermarket service. Integrated drilling system architects now specify motor power sections separately from measurement-while-drilling packages, reversing prior bundled sourcing patterns. This specification fragmentation is most visible in North American land drilling, where independent directional drilling companies negotiate component-level contracts to optimize fleet standardization.
Positive Displacement Motor Market Segmentation
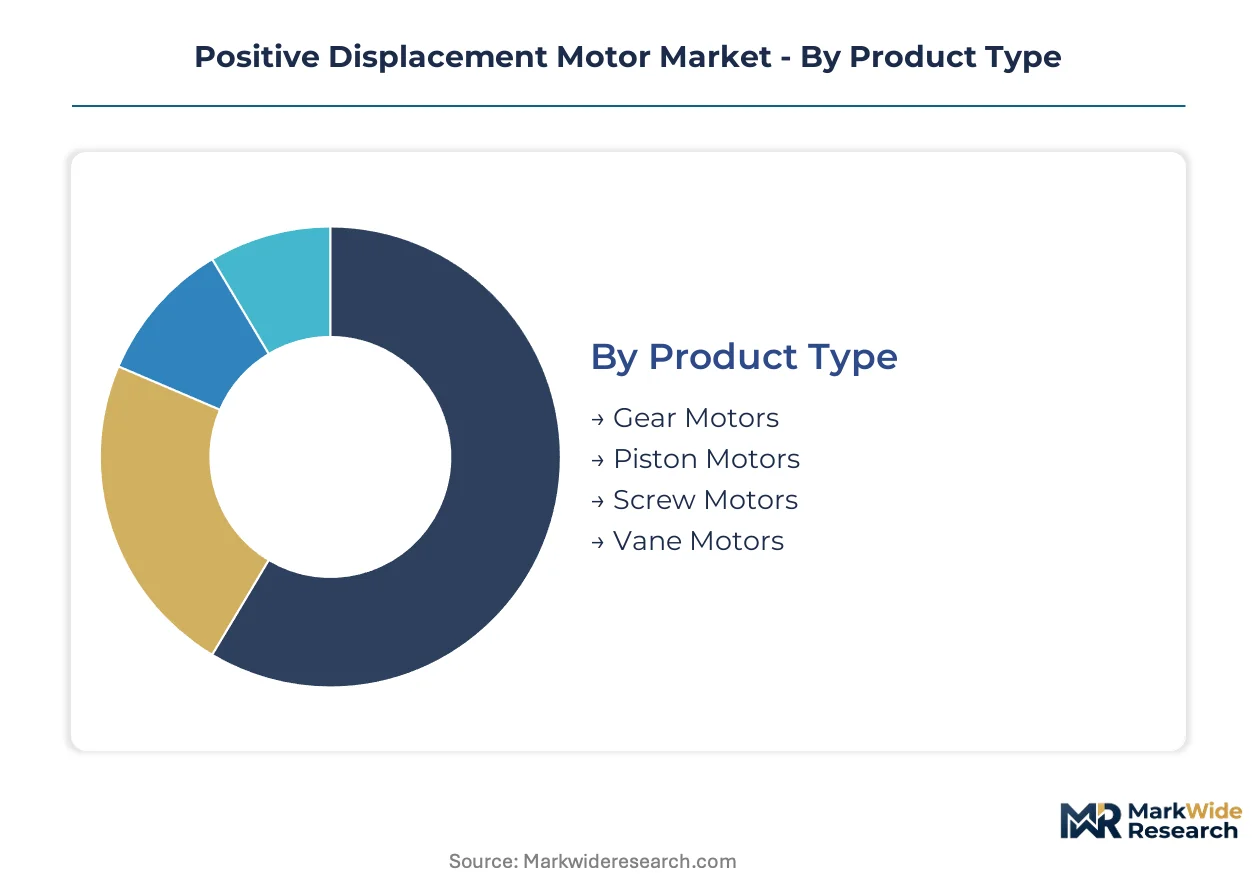
Positive displacement motor procurement splits sharply between specification-driven oilfield systems and cost-optimized industrial supply. Technology choices in each segment cascade through material selection, certification requirements, and aftermarket service architectures.
Product Type:
Screw motors capture the widest margin pools in oilfield directional drilling, while gear motors sustain volume through manufacturing automation replacement cycles.
- Screw Motors:These power sections deploy an elastomer-lined stator engaging a helical rotor to convert drilling fluid pressure into bit torque. Permian Basin operators in Texas and New Mexico specify compound grades by wellbore thermal profile, compressing margin pools for undifferentiated suppliers.
- Gear Motors:External and internal gear configurations deliver fixed displacement rotary output with volumetric efficiency above 90% in industrial hydraulic circuits. OSHA lockout-tagout mandates across US manufacturing and construction installations are expanding replacement cycles for legacy units.
- Piston Motors:Radial and axial piston architectures enable variable displacement control for precise load matching in aerospace actuation systems.
- Vane Motors:Sliding vane mechanisms operate at differential pressures up to 3,000 psi but face hard temperature ceilings at 200 degrees Celsius without full architecture redesign.
Screw motors hold installed capacity across North American land drilling. Piston motors are rotating up the share rankings in aerospace electrification transitions.
Application:
Application demand clusters around hydraulic system integration requirements, with oil and gas specifying power sections separately from measurement-while-drilling packages.
- Oil & Gas:Directional drilling programs in the Permian Basin require screw motor systems rated for extended-reach laterals beyond 15,000 feet. API Specification 7-1 fatigue testing protocols now demand 18-month validation cycles, restructuring competitive access for drilling motor suppliers.
- Industrial Equipment:Gear motor installations across manufacturing automation face displacement pressure from variable frequency drive systems. REACH-compliant biodegradable fluid specifications in European procurement now require seal compatibility with synthetic ester formulations.
- Hydraulic Systems:Mobile and stationary hydraulic power units deploy positive displacement motors for rotary actuator drive in construction and agricultural machinery.
- Water Management:Municipal and industrial water treatment facilities utilize vane motor configurations for pump drive applications where moderate torque and continuous duty cycles predominate.
Oil and gas maintains specification leadership. Industrial equipment is expanding most quickly through manufacturing reshoring initiatives.
End User:
End-user concentration among supermajor drilling contractors is compressing procurement cycles and unbundling aftermarket service from hardware supply.
- Manufacturing:Automotive production lines and metal fabrication facilities deploy gear motors for conveyor drive and press actuation. EPA hydraulic fluid discharge standards are forcing seal architecture redesign across US equipment.
- Construction:Earthmoving and material handling equipment relies on piston motor configurations for variable displacement control under shock loading conditions.
- Aerospace:Flight control surface actuation and landing gear systems specify high-performance piston motors with precise load matching capability.
- Automotive:Assembly plant automation and stamping press operations utilize compact gear motor packages for space-constrained installations.
Manufacturing retains the largest installed base. Construction is climbing the fastest through infrastructure stimulus deployment.
Technology:
Technology selection determines fluid compatibility, temperature rating, and control interface architecture across end-user deployments.
- Hydrodynamic:Fluid power conversion through positive displacement mechanisms dominates oilfield and heavy industrial applications. Biodegradable synthetic formulations degrade conventional nitrile seals within 500 operating hours, compelling fabricators to validate fluorocarbon alternatives.
- Electromechanical:Servo motor and variable frequency drive systems displace hydraulic power sections in manufacturing automation, compressing addressable volume for legacy motor categories.
- Pneumatic:Compressed air actuation serves light-duty rotary applications where oil-free operation and intrinsic safety predominate.
- Thermal:Expanding fluid or gas thermal motors occupy niche applications in remote actuation without electrical infrastructure.
Hydrodynamic technology anchors current revenue. Electromechanical alternatives are gaining share fastest through carbon disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermajor drilling contractors in the United States concentrate procurement authority for oilfield positive displacement motors, while industrial automation buyers in Germany and Japan sustain gear motor demand through manufacturing reshoring programs.
United States
Permian Basin operators in Texas and New Mexico specify screw motor compound grades by wellbore thermal profile for extended-reach laterals beyond 15,000 feet. EPA hydraulic fluid discharge standards compel seal architecture redesign for biodegradable synthetic compatibility. Houston anchors the largest concentration of directional drilling service companies procuring API Specification 7-1 certified power sections.
Germany
Automotive production lines and metal fabrication facilities deploy gear motors for conveyor drive and press actuation amid manufacturing reshoring initiatives. REACH-compliant biodegradable fluid specifications require seal compatibility with synthetic ester formulations. The Stuttgart industrial corridor concentrates precision hydraulic component fabricators serving European automation OEMs.
China
Domestic oilfield service companies expand screw motor manufacturing capacity for shale development programs in Sichuan and Xinjiang basins. GB standards and MIIT industrial equipment regulations govern material traceability for drilling motor exports. The Yangtze River Delta clusters hydraulic component suppliers targeting Southeast Asian infrastructure projects.
Japan
METI feed-in tariff revisions for binary-cycle geothermal plants pull demand for high-temperature vane motors rated above standard oilfield specifications. JIS standards certification creates specification barriers for imported power sections. The Nagoya industrial zone concentrates precision hydraulic motor fabricators serving aerospace and construction equipment OEMs.
Canada
Alberta oil sands operators require positive displacement motors rated for heavy oil viscosity and abrasive drilling conditions. Health Canada environmental regulations align with EPA fluid discharge standards for cross-border equipment procurement. Calgary hosts directional drilling contractors standardizing fleet specifications across North American land operations.
Positive Displacement Motor Market Vendor Landscape
Player mix skews toward integrated oilfield service conglomerates controlling specification authority through bundled drilling system architectures, with industrial hydraulic specialists occupying fragmented manufacturing automation tiers. Tier-one suppliers anchor premium oilfield segments through API certification and full material traceability chains, while mid-tier fabricators compete on cost in industrial replacement cycles. Dominant competitive moves include strategic partnerships with measurement-while-drilling toolchain providers and geographic expansion into Permian Basin service hubs.
Among diversified industrial hydraulics conglomerates, Parker Hannifin and Bosch Rexroth exemplify scale-driven archetypes with cross-sector gear motor portfolios spanning manufacturing automation and mobile machinery. Schlumberger and Baker Hughes occupy positions within the integrated oilfield services tier, anchoring premium screw motor supply through bundled directional drilling system architectures. Halliburton and Nabors Industries represent North American land drilling specialists with captive motor specification authority. MATRRIX Energy Technologies exemplifies the pure-play drilling motor fabricator archetype concentrated in Canadian and US shale basins.
| Leading Market Players |
|---|
| Parker Hannifin |
| Bosch Rexroth |
| Eaton Corporation |
| Halliburton |
| Schlumberger |
| Nabors Industries |
| Baker Hughes |
| MATRRIX Energy Technologies |
| Flowserve Corporation |
| Others |
Supply Flow & Price Mechanics
API Specification 7-1 fatigue-testing protocols gate both supplier qualification and price stratification simultaneously, compressing margin pools for fabricators lacking captive validation facilities while concentrating pricing power among integrated oilfield service conglomerates with full material traceability chains.
Pricing Analysis
Cost-plus contracts with nitrile and hydrogenated nitrile feedstock indexation dominate screw motor procurement for Permian Basin directional drilling programs. Three-tier pricing structure across API-certified premium, standard industrial, and economy replacement tiers reflects compound grade differentiation and thermal rating certification levels. Cost compression in economy gear motor tiers is intensifying because variable frequency drive substitution erodes addressable volume. Independent directional drilling companies exhibit highest price sensitivity, while supermajor drilling contractors prioritize performance guarantees over unit cost.
Supply Chain Analysis
United States, Germany, and Japan anchor precision power section fabrication and advanced elastomer compounding for high-temperature stator applications. Nitrile rubber feedstocks, fluorocarbon seal compounds, and specialized steel alloys for helical rotors draw from petrochemical complexes concentrated along the US Gulf Coast and Rhine-Ruhr industrial corridor. Single-source vulnerability in hydrogenated nitrile supply among three chemical suppliers exposes motor fabricators to input cost volatility. Distribution runs through OEM-direct procurement for oilfield systems and industrial distributor networks for manufacturing automation replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fatigue-testing facility scarcity and 18-month API validation timelines concentrate competitive advantage with capital-rich incumbents, creating structural barriers for mid-tier fabricators seeking specification access in premium oilfield segments.
For Market Incumbents: Compound certification moats by acquiring captive fatigue-testing facilities in Houston and Calgary service hubs, while backward integration into hydrogenated nitrile compounding insulates margin exposure to chemical supplier concentration. Electrification substitution in manufacturing automation threatens industrial gear motor volume pools. For New Entrants and Emerging Players: Lead with REACH-compliant seal architecture for European industrial procurement specifying biodegradable synthetic fluid compatibility, targeting Stuttgart and Nagoya automation OEMs with pre-certified compound libraries. Digital twin integration for predictive maintenance contracts offers unbundled service revenue without full hardware manufacturing scale. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across API 7-1 certification infrastructure, favoring acquisition of mid-tier fabricators with established material traceability systems over greenfield testing facility construction. Target pure-play drilling motor specialists with Permian Basin customer relationships and captive elastomer formulation expertise. Monitor METI geothermal feed-in tariff revisions as demand-pull signal for high-temperature vane motor capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Elastomer Compounding | Captive hydrogenated nitrile supply reduces exposure to three-supplier feedstock concentration. |
| API 7-1 Certification Facility Expansion | Houston and Calgary testing capacity shortens 18-month validation cycles for Permian Basin contracts. |
| Digital Twin Platform Development | Physics-based motor modeling enables predictive maintenance revenue unbundled from hardware sales. |
| REACH-Compliant Seal Architecture Launch | Pre-certified fluorocarbon compounds capture European procurement specifying biodegradable fluid compatibility. |
| High-Temperature Vane Motor R&D Program | METI geothermal tariff revisions pull demand for designs rated above 200 degrees Celsius. |
Methodological Framework
Desk research of API Specification 7-1 certification databases, EPA hydraulic fluid discharge enforcement records, and oilfield equipment procurement tenders preceded structured interviews with directional drilling contractors, elastomer compound suppliers, and industrial hydraulic OEM procurement teams. Secondary validation drew from SEC 10-K filings of integrated oilfield service providers, customs trade data for power section exports, and OSHA lockout-tagout compliance documentation. Bottom-up segment sizing triangulated against top-down energy sector capital expenditure projections.
Variance decomposition across product type, application, and technology dimensions structured the analytical framework over the projection horizon. Segmentation modeling captured screw motor compound grades, gear motor volumetric efficiency tiers, and piston motor variable displacement architectures. CAGRs derived from elasticity-adjusted demand curves incorporating Permian Basin lateral length trends and manufacturing automation reshoring indices. Forecast inputs included supermajor drilling contractor fleet standardization patterns and METI renewable energy subsidy revisions.
The analysis sits within stated boundaries; outcomes outside sustained Permian Basin drilling intensity or accelerated electrification substitution in European industrial markets would require recalibration. Forecasts reflect assumptions regarding API certification timeline stability and nitrile feedstock supply continuity. Recalibration cycles align with material shifts in EPA fluid discharge enforcement, EU CSRD carbon disclosure implementation, and geothermal project development permit approvals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Brush Motor Control Unit Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Electric AC Motors Market
Electric Motor
Traction Motors Market
Electric Motor
China E-Bike (Pedelec Bikes) Hub Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Trolling Motor Market