
 Gasoline Turbochargers Market | 2026-2036
Gasoline Turbochargers Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline Turbochargers Market Analysis
Electrified turbo assist is reshaping gasoline turbocharger architecture as 48-volt motor-generators integrate with compressor wheels to eliminate lag and enable torque-fill strategies. Garrett Motion Inc. leverages its electric turbo R&D pipeline to anchor technology leadership in hybrid-compatible boost systems. BorgWarner Inc. sustains manufacturing scale across multiple continents, while IHI Corporation specializes in compact turbine designs for downsized Asian powertrains.
Gasoline turbochargers are forced-induction devices that compress intake air using exhaust-driven turbine wheels typically manufactured from Inconel superalloys or cast iron, enabling smaller displacement engines to achieve power outputs comparable to larger naturally aspirated units while reducing fuel consumption and CO2 emissions. Single turbo configurations dominate volume production for mainstream passenger vehicles due to cost efficiency, while variable geometry turbos command premium positioning in performance cars where transient response precision determines drivability. Electric turbo represents the fastest-growing type category as OEMs pursue hybridization pathways that demand instantaneous boost without exhaust flow dependency.
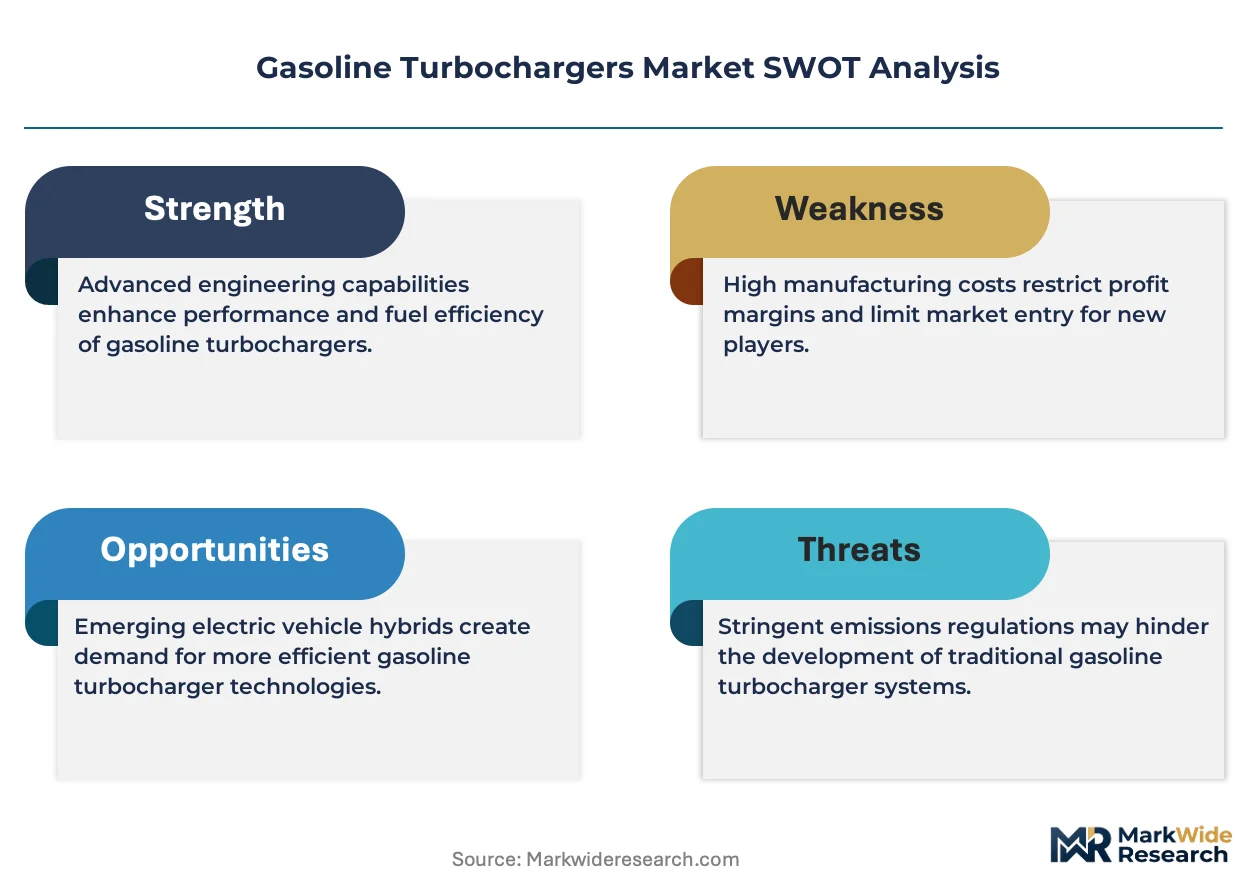
EPA tailpipe standards in the United States and Euro 7 regulations in Europe are mandating stricter NOx and particulate limits that force gasoline engine designers toward higher boost pressures and cooled exhaust gas recirculation, directly expanding turbocharger specification intensity. China's MIIT enforces corporate average fuel consumption targets that favor turbocharged downsizing across domestic brand lineups. Stakeholders must monitor how battery electric vehicle penetration rates in premium segments alter turbocharger content per vehicle and reshape supplier allocation decisions across hybrid versus pure combustion platforms.
Market Dynamics
Electrified turbo assist architectures are compressing engineering cycles across gasoline powertrain portfolios as 48-volt integration demands simultaneous mechanical and electrical optimization.
Growth Catalysts
- Euro 7 Standards:Stricter NOx and particulate mandates force gasoline engine designers toward higher boost pressures and cooled exhaust gas recirculation, directly expanding turbocharger specification intensity per vehicle.
- China MIIT Corporate Average Fuel Consumption Targets:Domestic automakers scale turbocharged downsizing across brand lineups to avoid regulatory penalties, concentrating procurement demand.
- 48-Volt Mild-Hybrid Architectures:Motor-generator integration with compressor wheels eliminates lag and enables torque-fill strategies, creating pull for electrified turbo variants.
Market Restraints
- Inconel Superalloy Input Volatility:Exhaust turbine wheels require nickel-based superalloys subject to mining supply concentration and price swings, compressing foundry margins.
- Supplier Concentration Risk:Precision casting and machining capabilities for variable geometry mechanisms cluster among specialized Tier-2 suppliers in Germany and Japan, creating single-source vulnerabilities.
- Battery Electric Vehicle Substitution:Premium segment electrification eliminates turbocharger content entirely, threatening long-term demand visibility for combustion-focused product lines.
Strategic Opportunities
- India PLI Scheme for Automotive Components:Production-linked incentives for advanced automotive systems attract turbocharger assembly investment serving domestic and export markets.
- Synthetic Fuel Compatibility:E-fuel and hydrogen-blend combustion pathways extend gasoline engine relevance, requiring turbocharger recalibration for altered flame speeds and exhaust temperatures.
- Over-the-Air Calibration:Connected vehicle architectures enable remote turbocharger map optimization, opening software-enabled recurring revenue streams.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Electrified turbo development demands engineers fluent in coupled thermal, mechanical, and electromagnetic modeling, with limited pipeline from universities.
- Homologation Timeline Compression:Euro 7 and EPA Tier 3 certification cycles for new boost systems require simultaneous emissions and durability validation, stretching engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline Turbochargers Market |
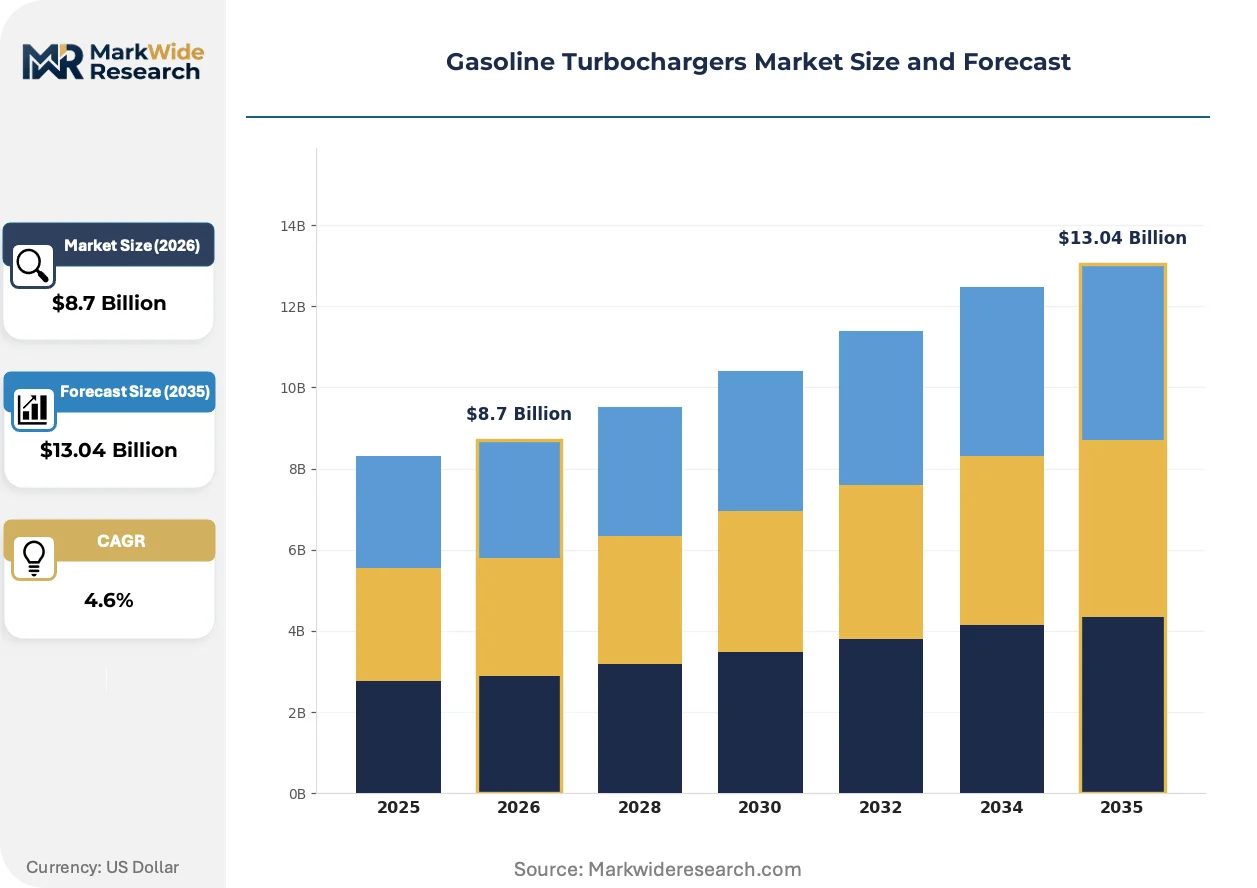
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Turbo, Twin-Turbo, Variable Geometry, Electric Turbo Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Performance Cars Material: Aluminum, Cast Iron, Stainless Steel, Composite End User: OEMs, Aftermarket Suppliers, Racing Teams, Fleet Operators |
| Companies Covered | BorgWarner Inc., Garrett Motion Inc., Mitsubishi Heavy Industries Ltd., IHI Corporation, Cummins Inc., Continental AG, Cummins Turbo Technologies, Robert Bosch GmbH, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline Turbochargers Market Emerging Trajectories
Forced-induction architectures are fragmenting across electrification pathways as 48-volt, high-voltage, and combustion-only strategies diverge tooling and R&D allocation.
Variable geometry turbocharger mechanisms are digitizing control loops through embedded position sensors and real-time blade angle adjustment algorithms. Performance vehicle OEMs adopt these systems to sharpen transient response precision where drivability determines segment positioning. The shift is digitizing the boundary between mechanical boost delivery and electronic powertrain management, collapsing the traditional separation between turbo suppliers and ECU calibration houses.
EPA tailpipe standards in the United States mandate stricter particulate limits that gasoline engine designers address through higher boost pressures and advanced thermal management. The regulatory pressure forces cooled exhaust gas recirculation integration with turbocharger housing designs, altering packaging constraints. Light-duty truck segments face the steepest compliance burden, driving specification intensity for twin-scroll and sequential turbo configurations.
Fleet procurement departments now specify turbocharger durability warranties as separate line items rather than bundled powertrain coverage, unbundling traditional supplier relationships. Tier-1 manufacturers respond with usage-based service contracts tied to telematics data streams. This restructuring is most visible in North American commercial vehicle segments where total cost of ownership calculations dominate capital allocation decisions.
Gasoline Turbochargers Market Segmentation
Gasoline turbocharger procurement patterns diverge sharply across powertrain architectures, with electrification timelines and emissions compliance trajectories reshaping specification intensity by vehicle category. Material selection and customer channel strategies further stratify competitive positioning as foundries and assemblers calibrate capacity to divergent margin and volume profiles.
Type:
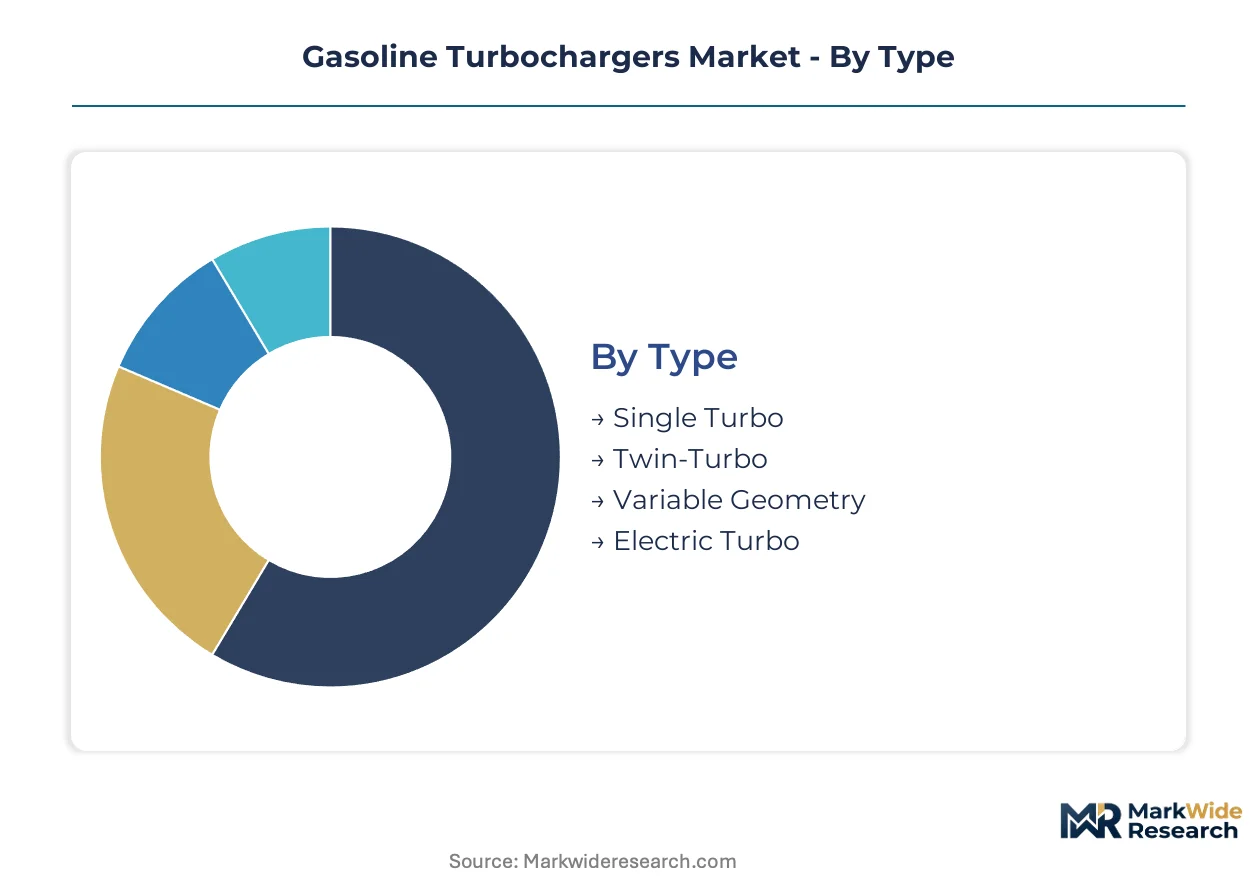
Cost tier structures the competitive landscape, with single-turbo architectures anchoring mainstream production economics while electrified variants capture premium positioning.
- Single Turbo:Compressor and turbine wheels mounted on a common shaft drive mainstream passenger vehicle applications. Procurement concentrates among Chinese domestic automakers scaling downsized three-cylinder engines for local consumption and Southeast Asian export markets, with MIIT fuel consumption targets forcing specification upgrades.
- Electric Turbo:48-volt motor-generators integrate with compressor wheels to eliminate lag and enable torque-fill strategies in mild-hybrid architectures. Demand clusters among European premium OEMs pursuing Euro 7 compliance through electrified boost systems, with fastest technology refresh cycles in the category.
- Twin-Turbo:Parallel or sequential compressor configurations serve V6 and V8 performance applications requiring staged boost delivery.
- Variable Geometry:Adjustable vane mechanisms optimize turbine flow across engine speed ranges, commanding premium positioning in performance segments.
Single Turbo commands the established base. The steepest expansion runs through Electric Turbo.
Application:
Vehicle duty cycles determine durability specifications and thermal management requirements, with light-duty and performance segments driving divergent engineering priorities.
- Passenger Vehicles:Compact and mid-size sedans and crossovers constitute the volume anchor, with turbocharged downsizing penetrating mass-market lineups. Chinese brands including BYD and Geobilize turbocharged gasoline variants for domestic market share expansion and Belt and Road export destinations, with procurement scale exceeding other categories.
- Performance Cars:Track-capable vehicles demand transient response precision where boost lag determines drivability perception. European specialist manufacturers specify twin-scroll and variable geometry systems from German and Japanese suppliers, with homologation timelines compressing development bandwidth.
- Commercial Vehicles:Light-duty trucks and vans integrate turbochargers for payload-rated torque delivery under sustained load conditions.
- Motorcycles:Supersport and touring bikes adopt compact turbochargers for power-to-weight optimization in displacement-restricted markets.
Passenger Vehicles anchor procurement volume. Performance Cars generate the highest specification intensity per unit.
Material:
Thermal and mechanical stress profiles dictate foundry process selection, with exhaust-side components requiring superalloy resilience against cost-driven aluminum alternatives.
- Cast Iron:Turbine housings in mass-market applications balance thermal mass and cost efficiency. Chinese foundry clusters in Shandong and Hebei provinces supply cast iron components for domestic OEMs and export markets, with scale economies compressing pricing.
- Aluminum:Compressor housings and intercooler end tanks reduce weight in front-wheel-drive architectures. European passenger vehicle programs specify aluminum for packaging efficiency under tight hood clearances, with recycling loops closing material cost volatility.
- Stainless Steel:High-temperature exhaust manifolds and turbine housings in performance applications resist thermal fatigue.
- Composite:Polymer-based compressor housings emerge in cost-optimized small-displacement applications.
Cast Iron retains the volume base. Aluminum gains share fastest in weight-sensitive platforms.
End User:
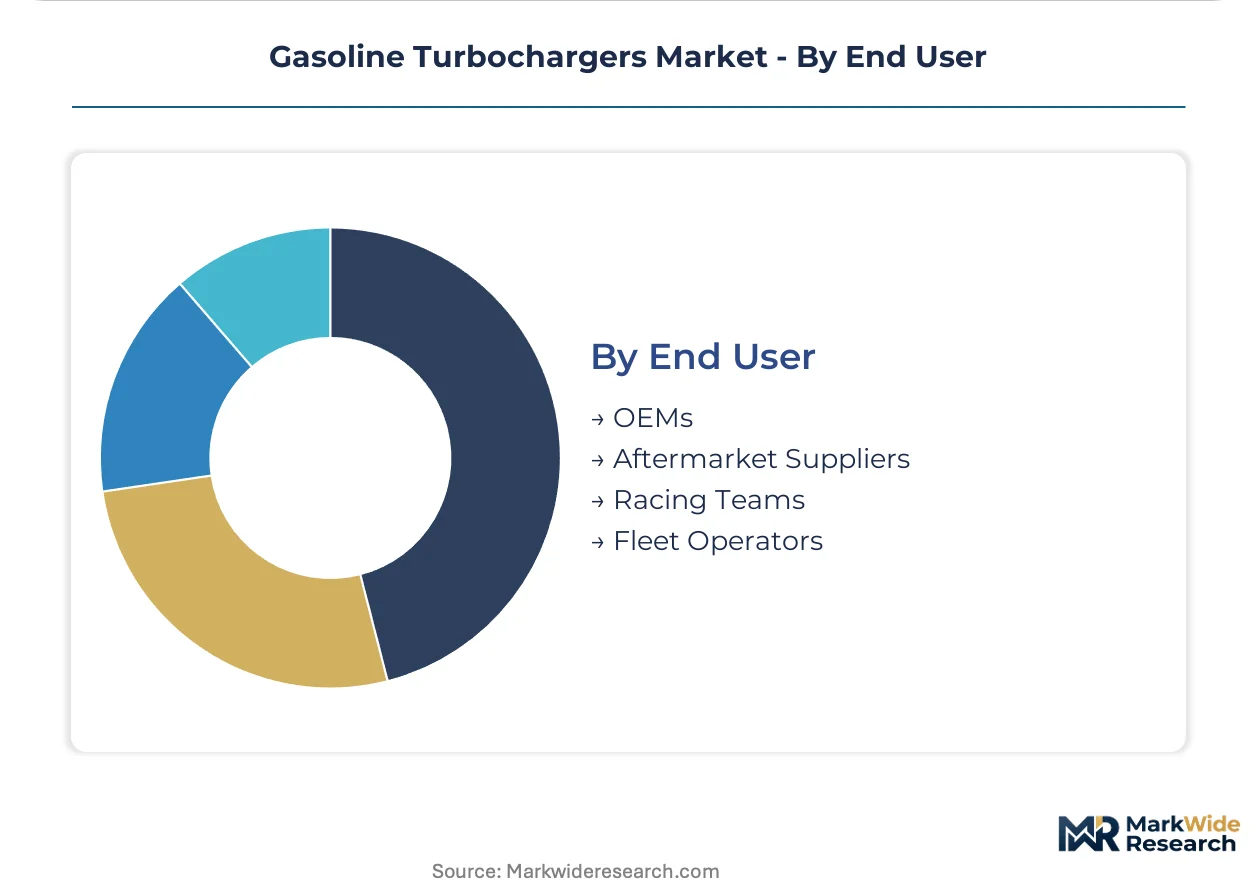
Customer type determines contract structure, warranty terms, and technical support intensity, with OEM relationships anchoring capacity planning and aftermarket channels capturing service lifecycle value.
- OEMs:Original equipment manufacturers specify turbochargers as integrated powertrain components with multi-year supply agreements. German and Japanese OEMs dominate procurement scale, with platform sharing across vehicle lines concentrating specification authority.
- Aftermarket Suppliers:Independent distributors and repair networks serve replacement demand outside warranty coverage. North American and European channels stock rotating assemblies and cartridge replacements for aging turbocharged fleets, with inventory turns determining working capital requirements.
- Racing Teams:Motorsport applications demand rapid rebuild turnaround and custom calibration support.
- Fleet Operators:Commercial vehicle and rental fleets negotiate usage-based service contracts tied to telematics data.
OEMs anchor manufacturing scale. Aftermarket Suppliers capture expanding service revenue as turbocharged vehicle populations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in gasoline turbochargers reflect divergent manufacturing footprints and regulatory stringency across major automotive production zones. Countries with concentrated OEM assembly and tightening emissions mandates drive procurement scale, while foundry economics shape component sourcing patterns.
China
Domestic automakers BYD and Geely scale turbocharged gasoline vehicle output for local consumption and Belt and Road export corridors. MIIT corporate average fuel consumption targets force specification upgrades across brand lineups. Shandong and Hebei province foundry clusters supply cast iron turbine housings with scale economies compressing regional pricing.
Germany
Premium OEM platform sharing concentrates turbocharger specification authority among powertrain engineering centers. KBA homologation timelines for Euro 7 compliance compress development bandwidth for new boost systems. Stuttgart and Munich anchor supplier R&D coordination with precision machining capabilities clustering in Baden-Württemberg.
United States
Light-duty truck segments face steep EPA Tier 3 particulate compliance burdens, driving twin-scroll and sequential turbo configurations. Ford and GM procurement departments unbundle turbocharger durability warranties from bundled powertrain coverage. Detroit-area engineering centers coordinate Tier-1 supplier integration with Mexican assembly operations.
Japan
Keiretsu supply relationships sustain captive turbocharger procurement for downsized powertrain architectures. METI carbon neutrality roadmaps accelerate 48-volt mild-hybrid turbo integration across mass-market lineups. Nagoya industrial corridor foundries specialize in compact turbine designs for Asian export markets.
India
Maruti Suzuki and Hyundai Motor India expand turbocharged petrol engine offerings to capture SUV segment share. PLI scheme production-linked incentives attract turbocharger assembly investment serving domestic and Southeast Asian export demand. Tamil Nadu and Gujarat automotive clusters concentrate stamping and machining capabilities.
Gasoline Turbochargers Market Vendor Landscape
On the supply side, the industry is consolidated around a handful of integrated Tier-1 systems suppliers with precision casting and variable geometry mechanism capabilities. Foundry economics and emissions calibration expertise create steep barriers to entry for new entrants. Two strategic archetypes dominate: full-system integrators controlling compressor-to-turbine matching and component specialists capturing niche thermal management segments. Competitive moves center on electrified turbo R&D partnerships and backward integration into superalloy casting capacity.
Within the integrated systems tier, Garrett Motion Inc. and BorgWarner Inc. occupy positions anchoring technology leadership in hybrid-compatible boost architectures. IHI Corporation exemplifies the compact turbine specialist archetype serving downsized Asian powertrain applications. Mitsubishi Heavy Industries Ltd. represents diversified industrial conglomerate participation with cross-sector thermal management capabilities. These three named entities illustrate how geographic origin and corporate structure map to divergent strategic positioning across electrification pathways.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Garrett Motion Inc. |
| Mitsubishi Heavy Industries Ltd. |
| IHI Corporation |
| Cummins Inc. |
| Continental AG |
| Cummins Turbo Technologies |
| Robert Bosch GmbH |
| Schaeffler |
| Others |
Supply Flow & Price Mechanics
German and Japanese precision-machining clusters for variable geometry mechanisms concentrate Tier-2 supplier capabilities, anchoring margin capture in specialized foundry tiers while downstream assemblers face cost compression from OEM volume procurement.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with multi-year supply agreements bundling turbocharger specifications across platform lines. Price differentiation rests on certification grade alignment with Euro 7 and EPA Tier 3 homologation tiers, plus volume scale thresholds that separate mass-market single-turbo procurement from premium electrified variants. Cost compression in cast iron turbine housings is intensifying because Chinese foundry scale economies are reshaping regional benchmarks. Fleet procurement departments exhibit highest price sensitivity, while performance vehicle OEMs prioritize transient response precision over unit cost.
Supply Chain Analysis
Shandong and Hebei province foundries alongside Baden-Württemberg machining clusters and Nagoya industrial corridor specialists hold capacity for turbine housing production and variable geometry assembly. Raw material flows draw from Inconel superalloy suppliers, aluminum smelters serving compressor housings, and precision steel feedstock for exhaust manifolds. Single-source vulnerability concentrates in nickel-based superalloy mining supply. Distribution runs through captive Tier-1 assembler networks into OEM powertrain integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery electric vehicle substitution threatens long-term demand visibility for combustion-focused product lines, forcing incumbents to defend gasoline turbocharger relevance through hybridization pathways.
For Market Incumbents: Build electrified turbo R&D moats through 48-volt motor-generator integration partnerships that anchor hybrid-compatible boost architectures. Backward integration into Inconel superalloy casting capacity secures input cost control against mining supply concentration. Prioritize over-the-air calibration capabilities to capture software-enabled recurring revenue streams as connected vehicle architectures mature.
For New Entrants and Emerging Players: India's PLI scheme production-linked incentives for automotive components represent underpenetrated assembly investment opportunities serving domestic and Southeast Asian export demand. Target Tamil Nadu and Gujarat automotive clusters where stamping and machining capabilities concentrate but turbocharger final assembly remains limited. Pursue synthetic fuel compatibility recalibration services as E-fuel and hydrogen-blend combustion pathways extend gasoline engine relevance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision casting specialists holding variable geometry mechanism capabilities in Germany and Japan. Five-to-ten year viability hinges on electrified turbo adoption rates in mild-hybrid architectures outpacing battery electric substitution in premium segments. Monitor quarterly MIIT corporate average fuel consumption compliance data from Chinese domestic automakers as inflection indicator for procurement scale direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Turbo R&D Partnership | 48-volt motor-generator integration with compressor wheels eliminates lag for hybrid architectures. |
| Backward Integration into Superalloy Casting | In-house Inconel turbine wheel production insulates margins from nickel supply volatility. |
| Over-the-Air Calibration Platform | Remote turbocharger map optimization opens recurring revenue through connected vehicle architectures. |
| PLI Scheme Assembly Investment | India's production-linked incentives attract capacity serving Southeast Asian export corridors. |
| Synthetic Fuel Compatibility Program | E-fuel and hydrogen-blend recalibration extends gasoline engine relevance for turbocharger demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed Tier-1 suppliers, and customs trade records for superalloy inputs. Interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and foundry operations managers inform demand-side validation. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporate vehicle class segmentation, propulsion architecture evolution, content per vehicle trajectories, OEM tier procurement patterns, and regional production cluster dynamics. CAGRs derive from modeled adoption curves for electrified turbo variants against battery electric substitution rates. Industry-specific inputs include MIIT corporate average fuel consumption compliance trajectories and Euro 7 homologation timeline compression effects.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic foundries or accelerated battery electric penetration in premium segments would shift outcomes. Quarterly review of MIIT compliance data, EPA certification filings, and OEM electrification roadmap disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Drive Mode-Linked Powertrain Actuator Systems Market
Powertrain
North America Torque Vectoring Market
Powertrain
Automotive Camshaft Market
Powertrain
EV Powertrain Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Automotive Conversion Kit Market
Powertrain
High-Performance IC Engine Vehicle Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Car Active Purge Pump Market
Powertrain
Global Powertrain Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Driveline Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Automotive Water Pump Market
Powertrain
Continuously Variable Transmission (CVT) Market