
 Automotive Spark Plugs and Glow Plugs Market | 2026-2036
Automotive Spark Plugs and Glow Plugs Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Spark Plugs and Glow Plugs Market Outlook
Iridium is displacing traditional nickel alloys in fine-wire center electrodes and is realigning cost structures across premium plug tiers. Robert Bosch GmbH leverages in-house precious-metal refining to sustain margin control on iridium-tipped product lines. NGK Spark Plug Co., Ltd. anchors Japanese OEM supply contracts through ceramic insulator technology leadership. DENSO Corporation competes on resistive glow plug thermal response times for direct-injection diesel platforms.
Automotive spark plugs and glow plugs are electromechanical ignition devices constructed from ceramic insulators, metal shells, and precious-metal or copper-core electrodes, engineered to initiate combustion in internal combustion engines through controlled electrical discharge or resistive heating. Spark plugs typically operate across gap distances of 0.6 to 1.3 millimeters with firing voltages between 20 and 40 kilovolts, while glow plugs achieve surface temperatures exceeding 1000°C within seconds to enable cold-start ignition in compression-ignition engines. Iridium plugs command the highest margin pool within the Product Type dimension due to extended service intervals and OEM specification density in Asian passenger car assembly. Aftermarket Providers represent the most fragmented yet volume-heavy End User channel, absorbing inventory from multiple vehicle generations and repair-shop procurement networks. Conventional technology still dominates unit shipments across the Technology spectrum, though resistive glow plug architectures are gaining specification in European light-commercial diesel applications.
EPA emission certification protocols and Euro 6d-ISC-FCM test cycles constrain glow plug energy consumption and particulate formation during cold-start phases, forcing redesigns of heating coil geometries and control module integration. Japan's METI fuel-efficiency standards and China's MIIT corporate average fuel consumption rules indirectly shape spark plug electrode durability requirements through combustion efficiency mandates. NHTSA safety recall databases and REACH substance restrictions on nickel compounds further filter material choices and supplier qualification pathways. Stakeholders must monitor evolving ICE phase-out timelines against residual fleet service-life demands to calibrate aftermarket inventory depth and precious-metal hedging positions.
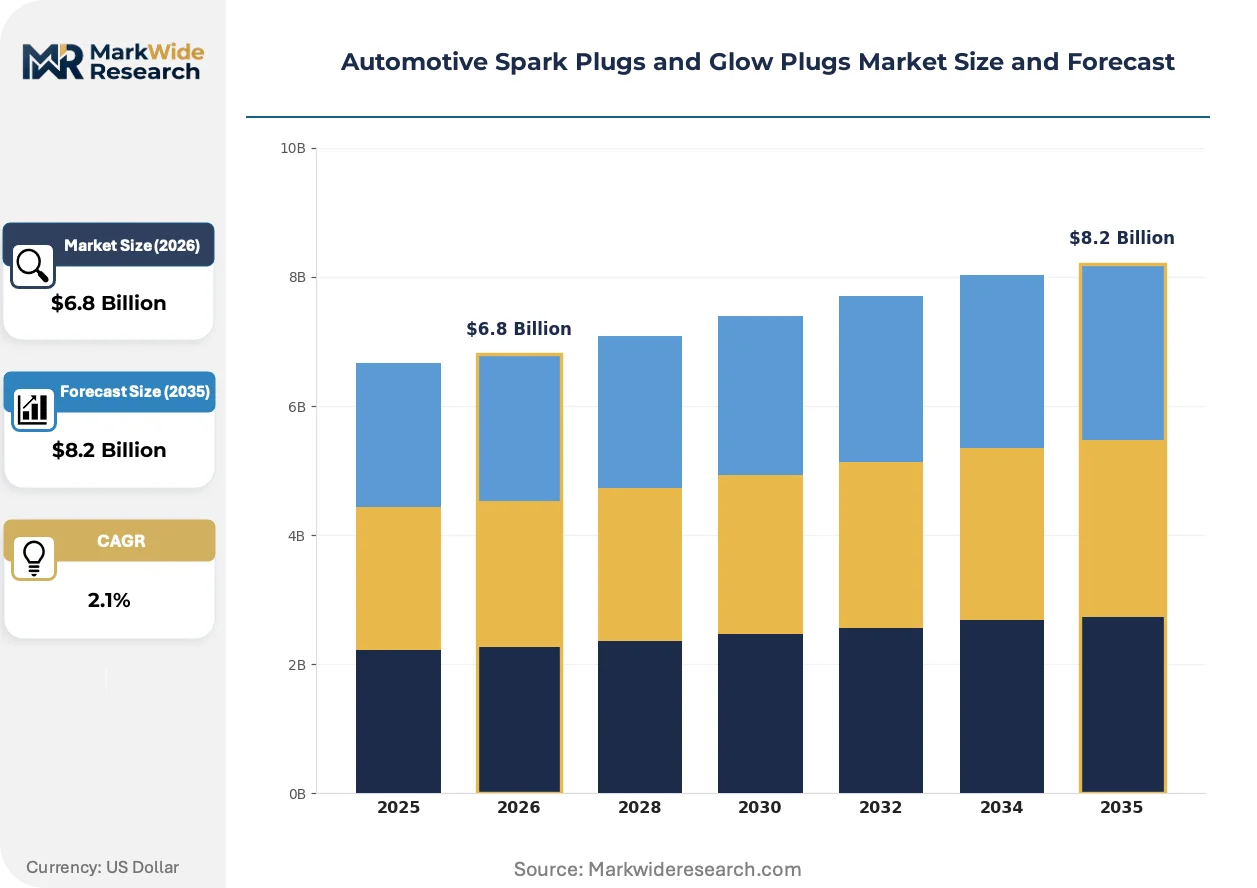
Market Dynamics
Iridium electrode technology is compressing replacement cycles while EPA Tier 4 and Euro 6 emission standards force thermal efficiency redesigns across diesel cold-start systems. Supply concentration in precious-metal refining is reshaping margin structures for premium plug tiers.
Growth Catalysts
- EPA Tier 4 Emission Protocols:Tighter ignition efficiency mandates for diesel cold-start performance are forcing OEM specification upgrades across heavy-duty commercial fleets.
- Ceramic Insulator Advances:High-alumina ceramic formulations are extending spark plug service intervals and reducing warranty claims in Asian passenger car assembly.
- Brazil:São Paulo industrial corridor demand for heavy-duty aftermarket spark plug procurement is concentrating procurement volumes in Latin America's largest automotive cluster.
Market Restraints
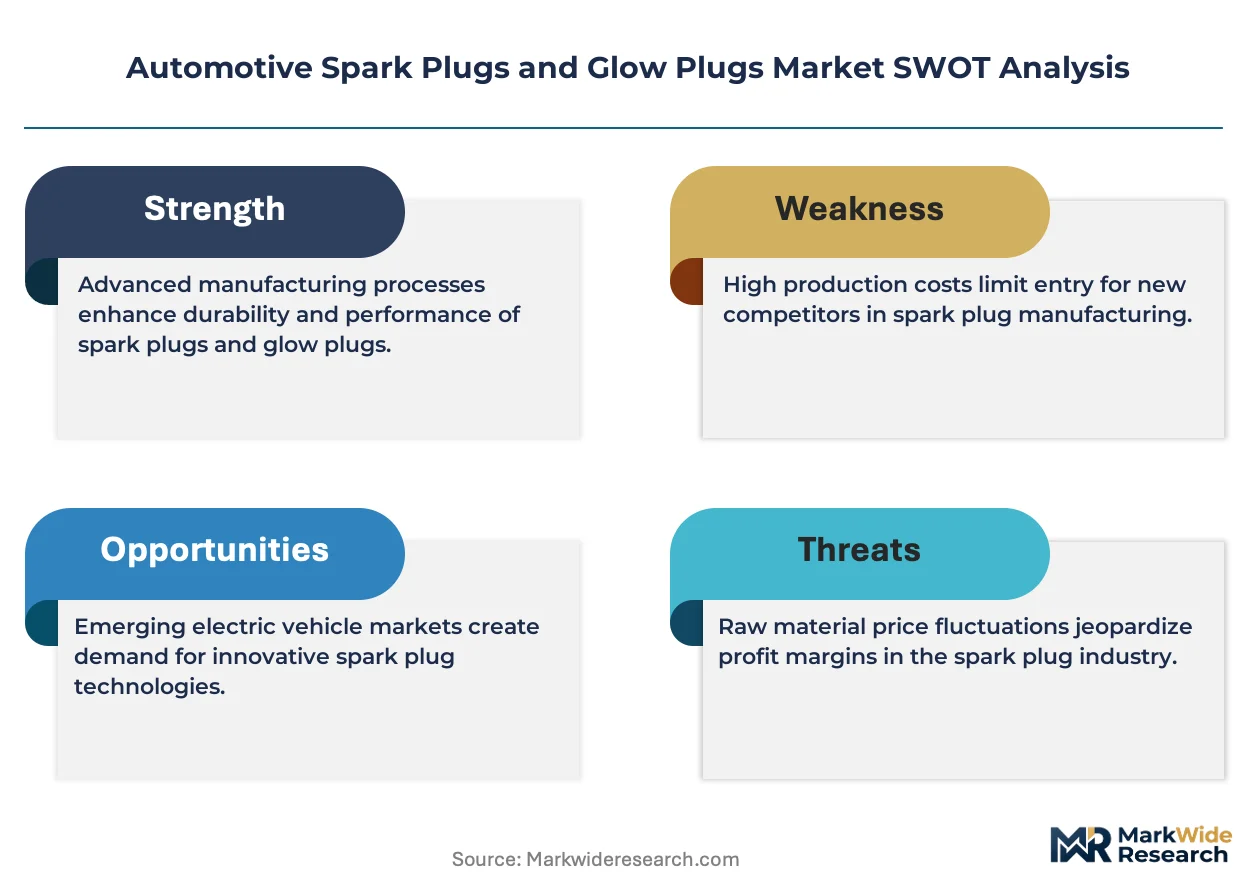
- Precious-Metal Price Volatility:Iridium and platinum spot price fluctuations compress margins on premium-tipped product lines regardless of volume scale.
- Supply Concentration Risk:In-house precious-metal refining capabilities concentrate among vertically integrated European and Japanese suppliers, limiting second-tier access.
- REACH Nickel Restrictions:ECHA substance restrictions on nickel compounds filter material choices and extend supplier qualification timelines for conventional alloy electrodes.
Strategic Opportunities
- Resistive Glow Plug Architectures:European light-commercial diesel applications are specifying faster thermal response systems for direct-injection platforms.
- Aftermarket Inventory Depth:Residual fleet service-life demands in aging vehicle parcs create white space for multi-generational plug procurement networks.
- MIIT Fuel-Efficiency Rules:China's corporate average fuel consumption standards indirectly shape electrode durability requirements through combustion efficiency mandates.
Industry Challenges
- Precious-Metal Hedging Complexity:Aftermarket inventory depth calibration requires simultaneous forecasting of iridium price movements and ICE phase-out timelines.
- Control Module Integration:Redesigned heating coil geometries for glow plug systems demand tighter software-hardware coordination with engine management units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Spark Plugs and Glow Plugs Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $8.2 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spark Plugs, Glow Plugs, Iridium Plugs, Platinum Plugs Technology: Conventional, Laser, Resistive, Capacitive End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Mechanics Installation Type: Integrated, Standalone, Modular, Custom |
| Companies Covered | DENSO Corporation, Robert Bosch GmbH, NGK Spark Plug Co., Ltd., BorgWarner Inc., Niterra Co., Ltd., Tenneco Inc., Federal-Mogul Corporation, Valeo SA, ACDelco Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Spark Plugs and Glow Plugs Market Strategic Shifts
Fine-wire center electrode materials, emission-driven thermal management requirements, and fragmented aftermarket procurement networks are simultaneously reshaping product development priorities and distribution economics.
Iridium-tipped fine-wire electrodes deliver superior spark energy concentration and erosion resistance compared to traditional nickel alloys. Japanese and Korean OEM assemblers are specifying iridium plugs as standard fitment across mid-tier passenger car platforms. This material transition is overtaking conventional copper-core designs in premium tier positioning and compressing the addressable market for standard-grade nickel products.
EPA emission certification protocols and Euro 6d-ISC-FCM test cycles now constrain glow plug energy consumption during cold-start phases. Heating coil manufacturers must demonstrate reduced particulate formation while maintaining sub-second surface temperature achievement. European light-commercial diesel OEMs are responding with integrated control module architectures that modulate resistive heating profiles in real-time.
Fleet operators in Latin America are extending replacement cycles for glow plug systems while concentrating heavy-duty spark plug procurement through authorized distributor networks. Independent repair shops face margin compression as OEM-affiliated channels capture a growing share of commercial vehicle maintenance spend. São Paulo's industrial corridor exhibits the most pronounced channel consolidation, with multi-brand service aggregators displacing traditional parts retailers.
Automotive Spark Plugs and Glow Plugs Market Segmentation
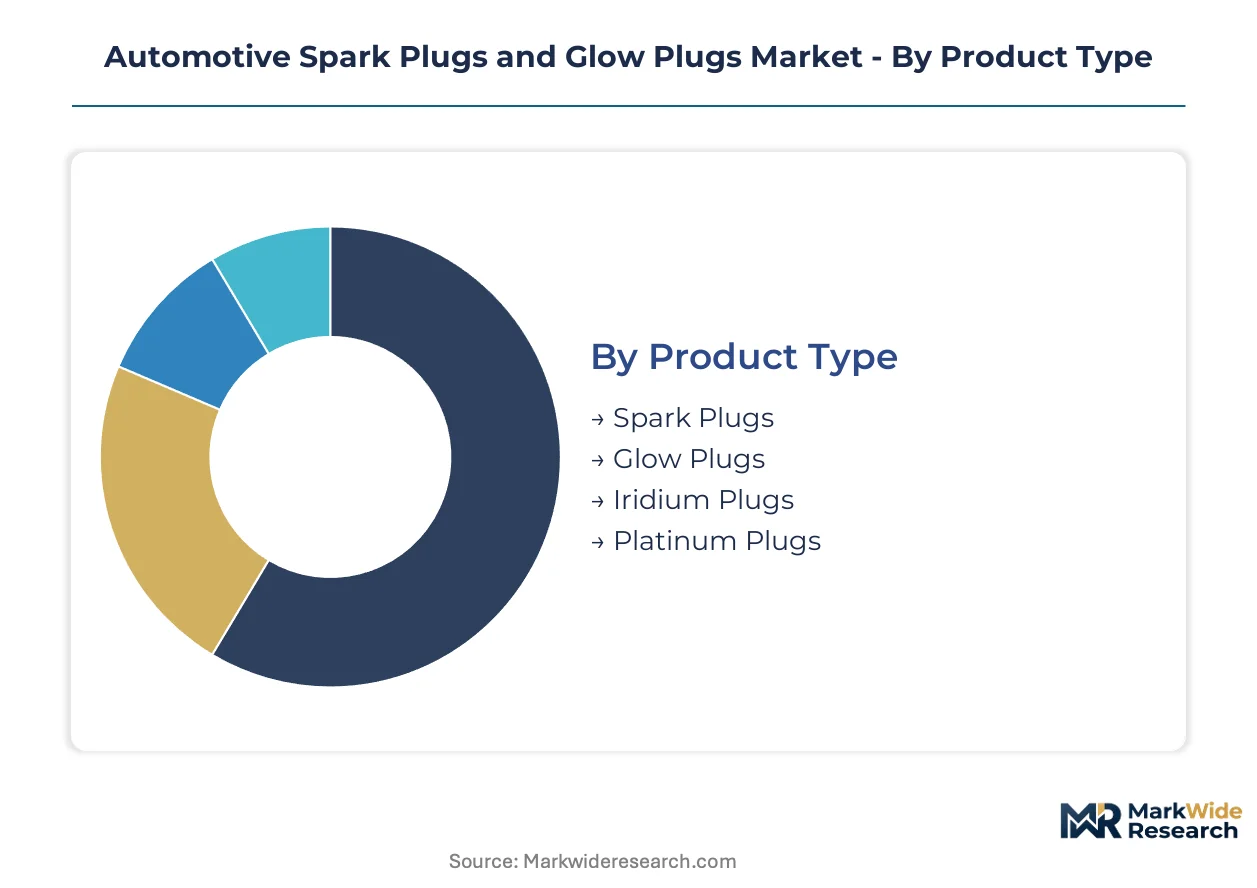
Electrode material chemistry and thermal response architectures fragment procurement specifications across passenger car, commercial vehicle, and industrial engine platforms. Each segment category carries distinct margin structures tied to precious-metal exposure, emission certification tiers, and service-interval engineering.
Product Type:
Supply concentration in iridium and platinum refining channels concentrates margin capture among vertically integrated producers with captive precious-metal sourcing.
- Spark Plugs:Ceramic insulator and metal shell assemblies with copper-core or precious-metal electrodes, firing voltages between 20 and 40 kilovolts across gap distances of 0.6 to 1.3 millimeters. Demand concentrates in Asian passenger car assembly where OEM specification density for iridium-tipped variants compresses replacement cycles and elevates aftermarket inventory carrying costs.
- Glow Plugs:Resistive heating elements achieving surface temperatures exceeding 1000°C within seconds, engineered for compression-ignition cold-start performance. European light-commercial diesel applications specify faster thermal response systems as EPA Tier 4 and Euro 6 emission protocols constrain energy consumption during cold-start phases.
- Iridium Plugs:Fine-wire center electrodes delivering superior spark energy concentration and erosion resistance, commanding premium positioning in Japanese and Korean OEM mid-tier platforms.
- Platinum Plugs:Intermediate precious-metal tier balancing service-interval extension against material cost exposure, specified in North American V6 and V8 engine architectures.
Today's leader: Spark Plugs. Tomorrow's challenger: Iridium Plugs.
Technology:
Cost tier differentiation separates legacy manufacturing from emission-certified precision engineering, with laser and resistive architectures capturing specification in premium assembly contracts.
- Conventional:Established copper-core and nickel-alloy electrode production with standardized ceramic insulator formulations. Still dominates unit shipments across price-sensitive aftermarket channels and aging fleet service networks in Latin America.
- Laser:Precision-welded fine-wire electrodes enabling tighter gap tolerances and reduced firing voltage variance. Asian OEM assemblers specify laser technology for direct-injection gasoline platforms where combustion chamber pressures demand consistent spark kernel formation.
- Resistive:Heating coil geometries with modulated thermal profiles integrated into engine management unit software. European light-commercial diesel OEMs specify resistive architectures for Euro 6d-ISC-FCM cold-start compliance.
- Capacitive:Energy storage and rapid discharge systems for specialized high-performance and racing applications with extreme ignition energy requirements.
Conventional technology holds volume dominance. Resistive systems are gaining specification fastest in certified diesel platforms.
End User:
Customer type fragmentation creates divergent procurement patterns, with OEMs demanding specification-locked supply contracts and aftermarket channels absorbing multi-generational inventory risk.
- OEMs:Original equipment manufacturers specifying electrode materials, gap geometries, and thermal response profiles through locked supply contracts. Japanese and Korean passenger car assemblers drive iridium plug specification density through mid-tier platform standard fitment.
- Aftermarket Providers:Multi-brand distributors and parts retailers carrying inventory across vehicle generations and repair-shop procurement networks. São Paulo's industrial corridor concentrates heavy-duty spark plug procurement through authorized distributor channels displacing traditional parts retailers.
- Vehicle Manufacturers:Commercial vehicle and off-highway equipment producers integrating glow plug systems into engine management architectures for EPA Tier 4 and Euro 6 compliance.
- Mechanics:Independent repair shops facing margin compression as OEM-affiliated service aggregators capture growing share of maintenance spend in Brazil and Mexico.
OEMs anchor premium-tier volume. Aftermarket Providers represent the most fragmented yet volume-heavy channel.
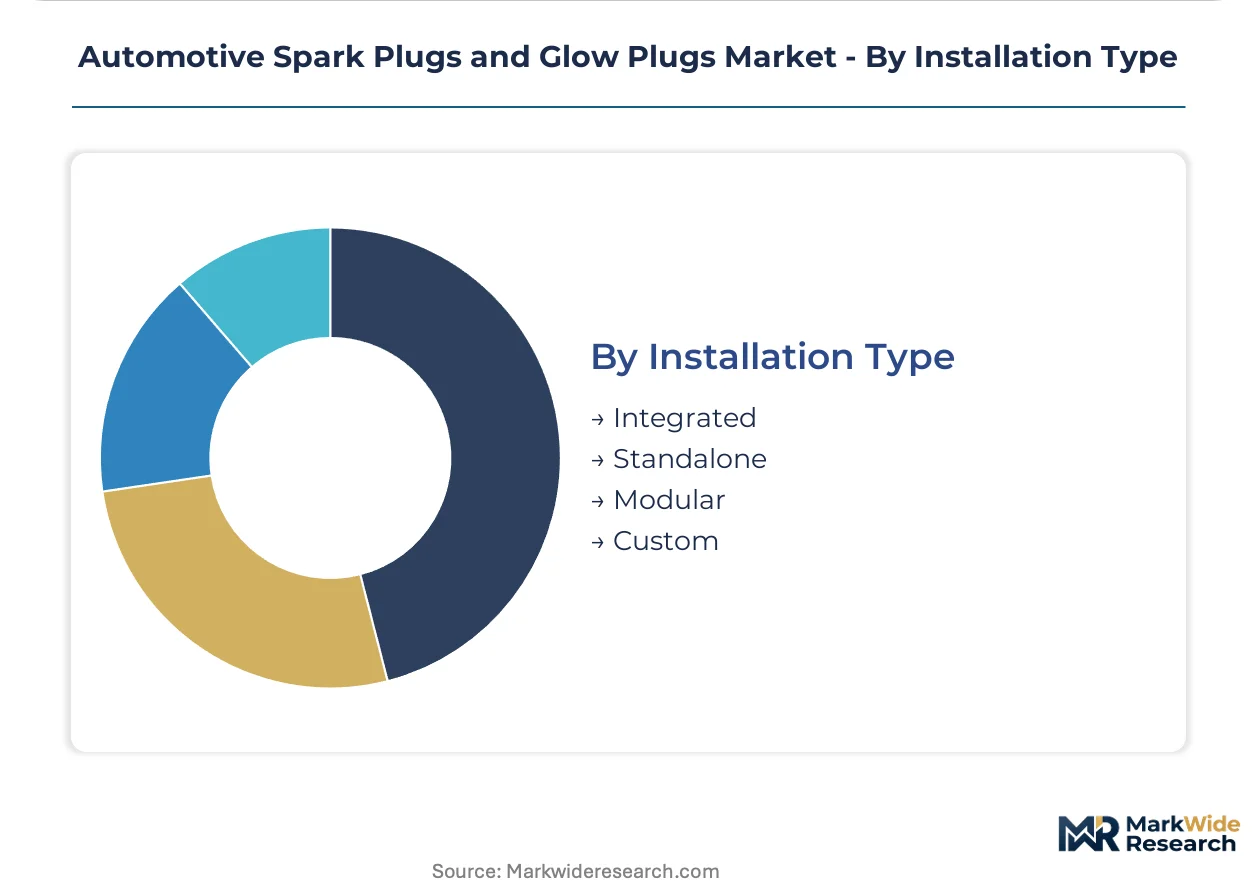
Installation Type:
Maturity gradients separate established integrated architectures from emerging modular approaches, with standalone systems retaining dominance in legacy fleet retrofit applications.
- Integrated:Spark plug and glow plug systems engineered into cylinder head and combustion chamber designs with dedicated control module coordination. Direct-injection diesel platforms specify integrated resistive glow plug architectures with real-time thermal profile modulation.
- Standalone:Conventional threaded-shell designs serviceable without engine management unit recalibration. Aging commercial fleets in Latin America extend replacement cycles through standalone glow plug procurement.
- Modular:Swappable heating coil and electrode subassemblies enabling field service without full plug replacement. Emerging specification in European heavy-duty applications where downtime minimization overrides unit cost considerations.
- Custom:Bespoke electrode geometries and thermal response profiles for racing, marine, and industrial stationary engine applications with non-standard combustion chamber architectures.
Integrated systems dominate new vehicle specification. Modular designs are expanding most quickly in service-interval-sensitive commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's industrial corridor anchors procurement concentration for heavy-duty aftermarket spark plugs, with emission protocols across multiple geographies reshaping thermal efficiency requirements for diesel cold-start systems.
United States
EPA Tier 4 protocols force ignition efficiency redesigns across heavy-duty commercial fleets operating in the Midwest manufacturing belt. NHTSA safety recall databases filter material choices for nickel-alloy electrodes. Detroit's automotive cluster concentrates OEM specification activity for iridium-tipped platforms.
Germany
Euro 6d-ISC-FCM test cycles constrain glow plug energy consumption during cold-start phases in light-commercial diesel applications. ECHA REACH restrictions on nickel compounds extend supplier qualification timelines. Stuttgart's engineering corridor drives resistive heating coil integration with engine management units.
Japan
METI fuel-efficiency standards shape electrode durability requirements through combustion efficiency mandates for passenger car assembly. Ceramic insulator technology leadership concentrates supply relationships with domestic OEMs. Nagoya's industrial zone anchors high-alumina formulation production for extended service intervals.
Brazil
ANVISA automotive component regulations align with EPA emission benchmarks for commercial vehicle fleet certification. Extended replacement cycles for glow plug systems concentrate procurement through authorized distributor networks. São Paulo's industrial corridor absorbs multi-brand service aggregator expansion displacing traditional parts retailers.
China
MIIT corporate average fuel consumption rules indirectly compress spark plug replacement cycles through durability mandates. GB standards for ignition system performance filter supplier qualification pathways. Yangtze River Delta assembly plants drive iridium plug specification density in mid-tier passenger car platforms.
Automotive Spark Plugs and Glow Plugs Market Competitive Environment
Backward integration into precious-metal refining dominates the current competitive landscape as suppliers seek margin control against spot price volatility. The vendor base stratifies across three tiers: vertically integrated Japanese and European producers with captive iridium sourcing, mid-scale regional fabricators serving aftermarket channels, and specialized heating coil engineers for diesel platforms. Strategic archetypes include precious-metal hedgers, ceramic insulator technology leaders, and resistive thermal response specialists. M&A activity and capacity expansion in high-alumina ceramic formulations represent the dominant competitive moves.
Within the vertically integrated tier, Robert Bosch GmbH and NGK Spark Plug Co., Ltd. exemplify archetypes of margin control through in-house refining and ceramic technology leadership respectively. DENSO Corporation occupies a position among resistive glow plug thermal response engineers serving direct-injection diesel specifications. These three anchors represent distinct strategic positions: German-engineered precious-metal integration, Japanese ceramic insulator dominance, and thermal management specialization for emission-certified platforms.
| Leading Market Players |
|---|
| DENSO Corporation |
| Robert Bosch GmbH |
| NGK Spark Plug Co., Ltd. |
| BorgWarner Inc. |
| Niterra Co., Ltd. |
| Tenneco Inc. |
| Federal-Mogul Corporation |
| Valeo SA |
| ACDelco Corporation |
| Others |
Value Chain & Pricing Dynamics
Premium-commodity divergence between iridium-tipped fine-wire electrodes and conventional nickel-alloy products manifests in starkly different margin structures and sourcing configurations across the automotive spark plugs and glow plugs market. Precious-metal exposure concentrates pricing power among vertically integrated Japanese and European suppliers with captive refining capabilities, while commodity-grade producers compete on ceramic insulator cost curves and freight-optimized distribution networks.
Pricing Analysis
Input-cost pass-through from iridium and platinum spot markets compresses margins on premium-tipped product lines regardless of volume scale. Three-tier pricing structure across premium, standard, and economy levels stratifies by electrode material chemistry and OEM certification grade. Pricing pressure stems from REACH nickel restrictions extending supplier qualification timelines and elevating compliance costs for conventional alloy electrodes. Fleet operators in Latin America exhibit highest price sensitivity through extended replacement cycles, while Japanese OEM assemblers absorb premium-tier pricing for iridium standard fitment.
Supply Chain Analysis
Freight cost differentials between high-alumina ceramic insulator production in Japan and metal shell fabrication in Germany shape regional sourcing strategies for global OEM supply contracts. Supply concentration rests in Japan, Germany, and China for critical inputs including high-purity alumina, precious-metal wire drawing, and resistive heating coil alloys. Single-source vulnerability concentrates in iridium refining channels controlled by vertically integrated producers. Distribution runs through authorized distributor networks in São Paulo's industrial corridor and multi-brand service aggregators displacing traditional parts retailers across Latin America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ceramic insulator technology leadership and resistive glow plug thermal response specialization as emission protocols tighten cold-start efficiency mandates. Premium-tier displacement of conventional nickel alloys creates pricing power for suppliers with backward integration into precious-metal sourcing.
For Market Incumbents: Deploy ceramic insulator capacity expansion in Nagoya's industrial zone to anchor Japanese OEM supply contracts against Korean challenger entry. Lock long-term iridium offtake agreements with South African and Russian mining consortiums to hedge spot price volatility threatening margin stability on fine-wire electrode product lines. Resistive glow plug control module integration with European engine management architectures defends specification share against BorgWarner thermal systems division. For New Entrants and Emerging Players: Laser-welded fine-wire electrode precision manufacturing offers a technology-first wedge into Asian direct-injection gasoline platform supply chains currently dominated by NGK and DENSO. Target São Paulo's aftermarket distributor consolidation wave with modular glow plug subassemblies enabling field service without full replacement. White-space penetration concentrates in European light-commercial diesel resistive architectures where Euro 6d-ISC-FCM compliance demands faster thermal response than incumbent heating coil geometries deliver. For Investors and Strategic Acquirers: Consolidation pressure builds where precious-metal refining capabilities concentrate among three Japanese and European producers controlling iridium-tipped margin pools. Acquisition target archetypes include mid-scale ceramic insulator fabricators with high-alumina formulation expertise and regional aftermarket distributors with fleet service contracts in Brazil's ANVISA-certified commercial vehicle corridors. Watch EPA Tier 5 pre-rulemaking signals as inflection indicator for accelerated glow plug thermal efficiency redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious-Metal Refining | Captive iridium sourcing locks margin control against spot volatility for premium electrode tiers. |
| High-Alumina Ceramic Capacity Expansion | Nagoya production scale-up extends service interval engineering leadership for Japanese OEM contracts. |
| Resistive Glow Plug Control Module Integration | Real-time thermal profile modulation meets Euro 6d-ISC-FCM cold-start energy consumption constraints. |
| Aftermarket Distributor Network Consolidation | São Paulo authorized channel capture displaces independent retailers in Brazil's heavy-duty fleet procurement. |
| Modular Heating Coil Subassembly Development | Field-serviceable architectures minimize downtime for European heavy-duty commercial applications. |
Study Parameters
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distributor operations heads; secondary validation through EPA emission certification databases, NHTSA recall filings, and vehicle production registries; plus customs trade data on precious-metal wire imports — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned Robert Bosch GmbH procurement strategy, NGK Spark Plug ceramic technology roadmaps, and DENSO thermal systems integration timelines. Secondary sources included METI fuel-efficiency standard filings, ECHA REACH substance restriction updates, and MIIT corporate average fuel consumption rulemakings.
Historical shipment patterns were cross-referenced against panel input from automotive component procurement directors to construct segment-level projections across the analysis window. The analytical framework modeled electrode material chemistry, thermal response architecture, end-user channel type, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from trend extrapolation of iridium plug specification density in Asian passenger car assembly and resistive glow plug adoption curves in European light-commercial diesel platforms. Industry-specific forecast inputs included EPA Tier 4 implementation timelines and ANVISA commercial vehicle fleet certification trajectories.
The model holds under stable emission protocol implementation schedules and precious-metal supply continuity; deviation in EPA pre-rulemaking acceleration or Russian iridium export restrictions would shift replacement cycle assumptions and margin pool distributions. Stakeholders should weight assumptions against their own operating context and hedge positions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market