
 Global Automotive Engine and Engine Mounts Market | 2026-2036
Global Automotive Engine and Engine Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine and Engine Mounts Market Analysis
Fleet operators and commercial vehicle buyers is rotating share toward OEMs serving electrified platforms, while individual passenger car demand softens in mature economies. Continental AG anchors its position through captive rubber compounding and vibration control R&D across German and Chinese plants. Vibracoustic competes on hydraulic mount architectures for luxury sedans, while MAHLE GmbH specializes in thermal management integration that extends engine mount functional life under turbocharged loads. Sumitomo Riko Company Limited dominates acoustic decoupling solutions for Asian OEM supply chains.
Automotive engines and engine mounts comprise powertrain assemblies that convert fuel or electrical energy into mechanical propulsion, with mounts typically fabricated from natural rubber, synthetic elastomer, or hydraulic fluid-damped assemblies engineered to isolate NVH while maintaining driveline alignment under torque loads. Engine mounts functionally secure powertrains to vehicle subframes across load cycles spanning idle vibration through peak acceleration events. Hybrid engines command expanding tooling investment as OEMs balance thermal efficiency with electrification cost targets, while turbocharged technology leads naturally aspirated configurations in new platform development. Engine mounts as a product category concentrates margin pools in hydraulic and active-controlled variants as passive rubber designs commoditize across entry vehicle segments.
EPA tailpipe standards and Euro 7 proposals from the European Commission are forcing powertrain architecture redesigns that cascade into mount stiffness specifications and material temperature ratings. China's MIIT dual carbon goals and NMPA vehicle certification protocols shape domestic OEM sourcing requirements for lightweight mount assemblies. REACH and RoHS constraints from ECHA limit certain vulcanization accelerators and heavy metal stabilizers in European-sold mount compounds. Stakeholders must monitor how regulatory phase-in calendars across Washington, Brussels, and Beijing synchronize with platform development cycles to avoid stranded tooling investments or non-compliance lockouts.
Market Dynamics
Powertrain electrification is bifurcating the engine mount supply base, as hybrid architectures demand thermal-mechanical hybrids that neither pure ICE nor pure EV suppliers can deliver alone. This structural tension concentrates margin in hydraulic and active-controlled variants while commoditizing passive rubber designs.
Growth Catalysts
- EPA Tier 3 and Euro 7 tailpipe thresholds:Fleet operators in California and Germany are accelerating hybrid procurement, forcing OEMs to redesign mount stiffness specifications for combined thermal-electric load cycles.
- Silicone-hydraulic fluid formulations:Advanced elastomer compounds now withstand turbocharger-adjacent temperatures above 150°C, extending functional life in downsized powertrains.
- China's MIIT dual carbon roadmap:Domestic passenger vehicle OEMs are sourcing lightweight aluminum-rubber hybrid mounts to meet NMPA certification mass-reduction targets.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions transmit directly to mount compound costs, compressing margins for passive rubber specialists.
- REACH Article 33 substance restrictions:ECHA limitations on zinc-based vulcanization accelerators force reformulation of European-sold mounts, extending qualification timelines.
- Solid-state battery substitution threat:Cell-to-pack architectures in premium EVs eliminate engine bays entirely, removing mount demand from nascent vehicle categories.
Strategic Opportunities
- India's PLI scheme for automotive components:BIS certification pathways now favor local mount production for Maruti Suzuki and Tata Motors export programs.
- Active electromagnetic mounts:Convergence of sensor feedback loops with hydraulic damping enables real-time NVH cancellation for luxury hybrid platforms.
- Direct OEM contracting:Tier 1 suppliers are bypassing traditional distributor networks to capture aftermarket margin in Brazil and Mexico.
Industry Challenges
- Multi-physics simulation talent scarcity:NVH engineers capable of modeling coupled thermal-mechanical-electric mount behavior command premium compensation in Stuttgart and Shanghai.
- GB standards harmonization delays:China's SAMR and MIIT are issuing conflicting test protocols for hybrid mount durability, forcing parallel validation runs.
- Legacy tool reconfiguration costs:Existing rubber injection molding assets require six-figure retrofits to process high-temperature silicone compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine and Engine Mounts Market |
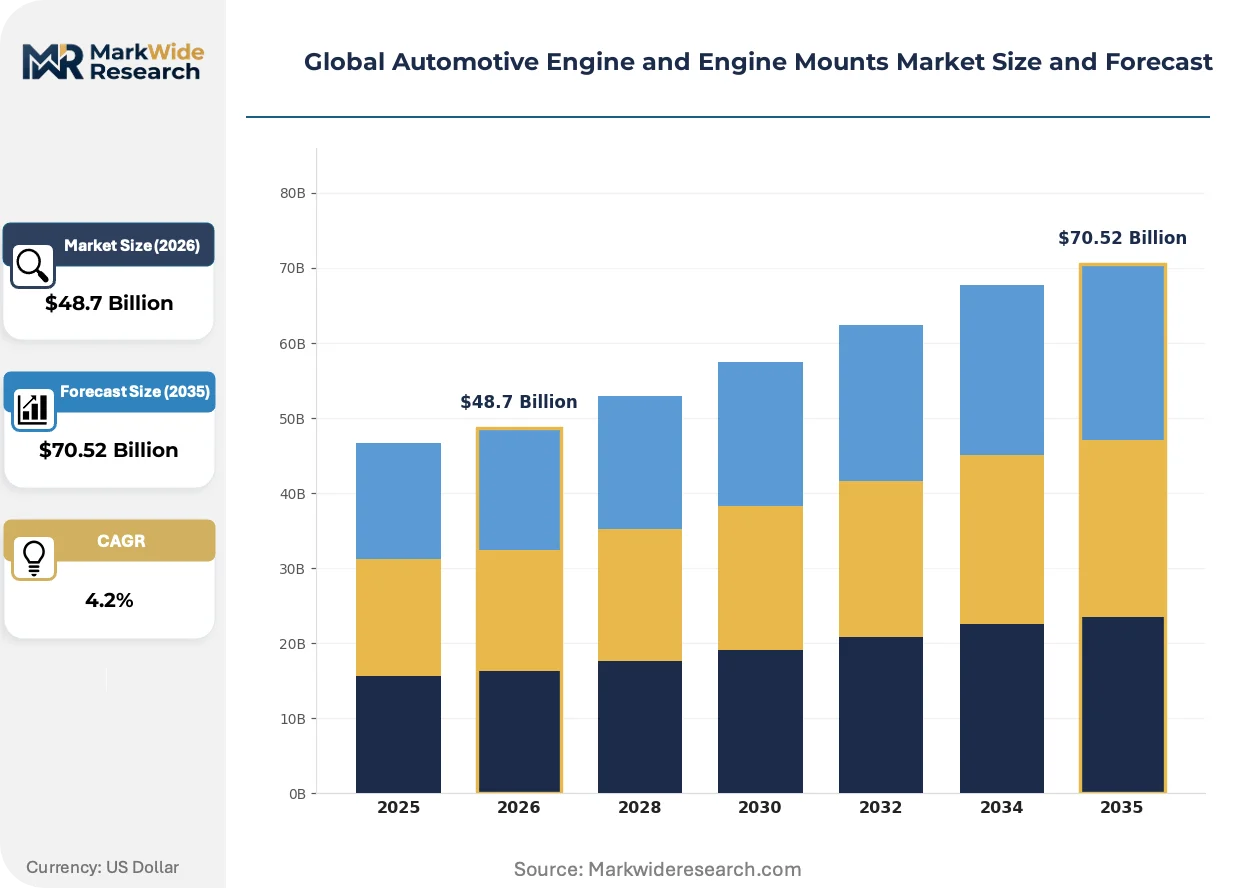
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Combustion Engines, Hybrid Engines, Electric Motors, Engine Mounts End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Automotive Manufacturers Technology: Turbocharged, Naturally Aspirated, Direct Injection, Fuel Cell Installation: Onboard Systems, Offboard Systems, Custom Installations, Retrofit Solutions |
| Companies Covered | Sumitomo Riko Company Limited, Hutchinson, Continental AG, Trelleborg AB, Vibracoustic, ZF Friedrichshafen AG, Cooper Standard, MAHLE GmbH, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine and Engine Mounts Market Emerging Trajectories
Active noise cancellation and predictive damping algorithms are migrating from luxury sedans into mass-market hybrids, compressing the technology adoption cycle from seven years to three. Mount suppliers must now deliver software-defined performance alongside mechanical hardware.
Magnetorheological fluid mounts are fragmenting the traditional hydraulic segment, as real-time viscosity modulation enables frequency-specific damping across idle, cruise, and regenerative braking modes. Korean and Japanese OEMs are qualifying these systems for mid-size crossover platforms previously served by passive designs. The technology is fragmenting supplier hierarchies, as electronics integration demands partnerships with sensor and control module vendors foreign to rubber compounders.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing European mount manufacturers to abandon legacy carbon black loadings in favor of precipitated silica and bio-based fillers. The regulation compresses compound development cycles and raises raw material costs by twelve to eighteen percent for suppliers serving German OEMs. ECHA compliance deadlines in 2027 are accelerating qualification programs, with Tier 1 suppliers front-loading R&D to secure platform approvals.
Fleet procurement departments are consolidating mount sourcing through outcome-based total cost of ownership contracts, replacing unit-price negotiations with lifetime NVH performance guarantees. Commercial vehicle lessors in the US and Germany are driving this shift, penalizing suppliers for warranty claims tied to driveline misalignment. The model concentrates volume with vertically integrated manufacturers capable of predictive maintenance data integration.
Global Automotive Engine and Engine Mounts Market Segmentation
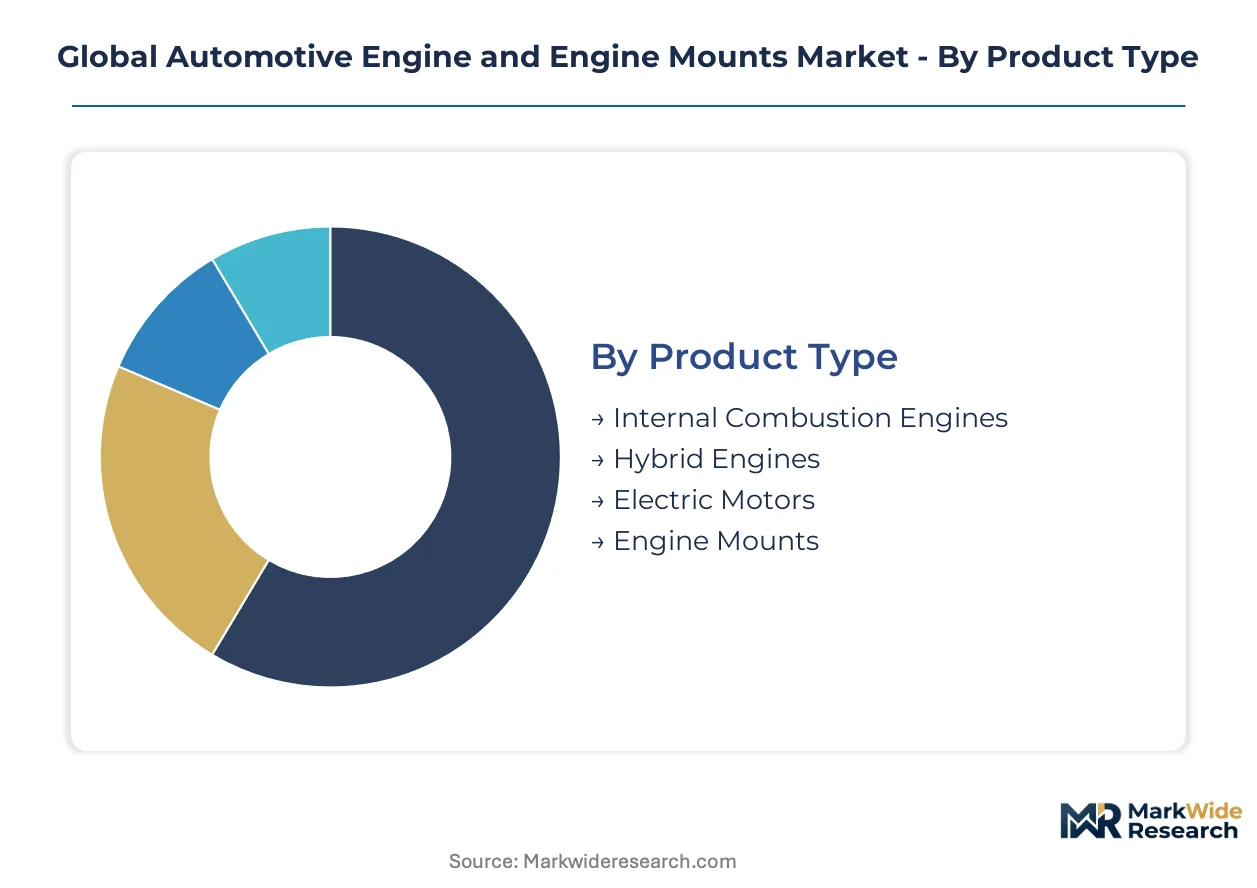
Segmentation in this market tracks how powertrain electrification splits procurement channels, with hybrid architectures forcing new distributor relationships while ICE supply chains consolidate. Understanding which configurations flow through captive OEM supply versus open aftermarket networks determines margin capture and tooling investment priorities.
Product Type:
Channel-mix patterns diverge sharply: ICE components still move through established aftermarket distributors, while hybrid and electric powertrains route almost exclusively through OEM captive channels and Tier-1 direct contracts.
- Internal Combustion Engines:Cast aluminum and iron block assemblies with multi-point or direct fuel injection systems. Demand concentrates in commercial vehicle fleets across Germany and the US as operators delay full electrification to manage capital cycles, though EPA Tier 3 compliance costs are narrowing the viable supplier base.
- Hybrid Engines:Thermal-electric powertrains combining downsized turbocharged ICE with integrated motor-generators. Procurement from China's domestic OEMs is accelerating as MIIT dual carbon targets tighten, requiring mounts that withstand thermal cycling between electric and combustion modes.
- Electric Motors:Permanent magnet synchronous and induction motor architectures eliminating traditional engine bays. Volume flows through Tesla, BYD, and Volkswagen Group direct supplier portals with minimal aftermarket presence.
- Engine Mounts:Rubber, hydraulic, and active-controlled assemblies isolating NVH across load cycles. Brazil and Mexico aftermarket distributors still dominate for passive rubber variants, while OEMs source active mounts through Continental and Vibracoustic direct contracts.
By volume, Internal Combustion Engines leads. By growth pace, Hybrid Engines is expanding most quickly.
End User:
Cost-tier stratification separates premium R&D partnerships at OEMs from price-sensitive aftermarket procurement, with Tier-1 suppliers occupying the contested middle ground.
- OEMs:Vehicle manufacturers specifying powertrain and mount performance at platform development stage. Volkswagen Group and Toyota Motor Corporation are consolidating supplier panels, reducing qualified mount vendors by forty percent over three years to cut qualification overhead.
- Aftermarket Providers:Independent distributors and service chains supplying replacement engines and mounts. Demand clusters in US rust-belt states and German Autobahn corridor where vehicle age averages exceed twelve years, though REACH compliance costs are squeezing European parts importers.
- Tier-1 Suppliers:System integrators delivering complete powertrain modules to OEM assembly plants. MAHLE and Continental are backward integrating into rubber compounding to defend margin against raw material volatility.
- Automotive Manufacturers:Captive brand networks including dealer service operations. China's NIO and XPeng are building proprietary service ecosystems that bypass traditional aftermarket channels entirely.
OEMs capture the highest absolute revenue. Aftermarket Providers are climbing the fastest as vehicle age extends across mature economies.
Technology:
Application-specific requirements split procurement: turbocharged and direct injection systems demand thermally robust mounts, while fuel cell architectures eliminate mounting points entirely.
- Turbocharged:Forced induction systems generating exhaust temperatures exceeding 900°C. Mount suppliers serving Hyundai Motor Company and Stellantis are qualifying silicone-hydraulic compounds rated above 150°C continuous operation.
- Naturally Aspirated:Conventional intake-drawn engines with lower thermal and mechanical stress. Brazil's flex-fuel market sustains volume for passive rubber mounts as cost-sensitive buyers prioritize purchase price over NVH refinement.
- Direct Injection:High-pressure fuel delivery enabling lean combustion and downsizing. Mount stiffness specifications from BMW and Mercedes-Benz Group are tightening to manage high-frequency vibration from rapid pressure cycles.
- Fuel Cell:Hydrogen-electric powertrains with radically different packaging and thermal profiles. Toyota's Mirai and Hyundai's Nexo platforms eliminate conventional engine mounts, displacing incumbent suppliers from this technology path.
Turbocharged leads by installation volume. Fuel Cell is gaining share fastest despite low absolute numbers.
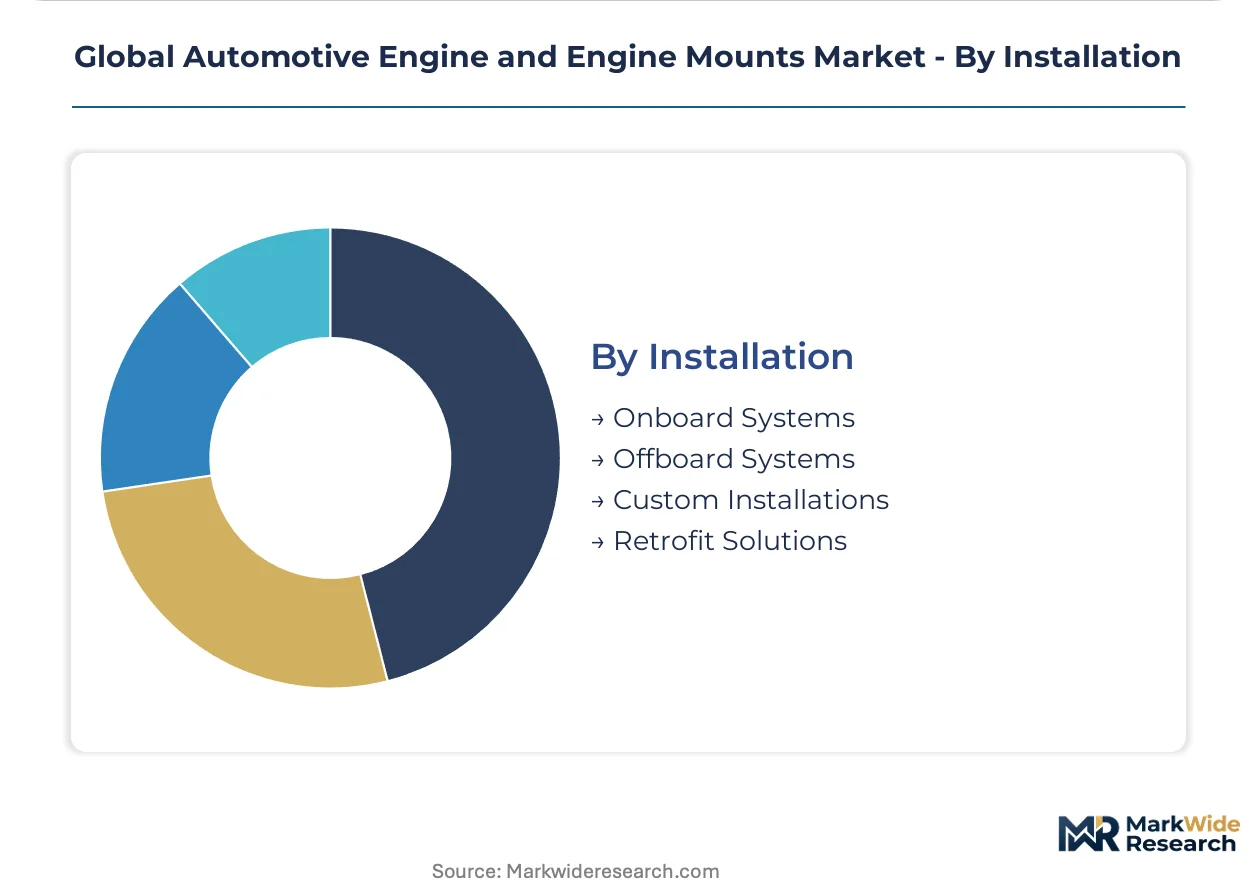
Installation:
Customer-type differentiation separates factory-integrated onboard systems from retrofit solutions targeting fleet conversion economics.
- Onboard Systems:Factory-installed powertrain and mount assemblies. OEMs in Stuttgart, Wolfsburg, and Shanghai are standardizing active electromagnetic mounts for hybrid platforms.
- Offboard Systems:Stationary charging and hydrogen refueling infrastructure with no mount content. This segment is excluded from supplier addressable market calculations.
- Custom Installations:Specialist-built performance and commercial modifications. Australia's mining vehicle converters and Germany's motorhome manufacturers sustain niche demand for heavy-duty hydraulic mounts.
- Retrofit Solutions:Aftermarket powertrain swaps and mount replacements. California's CARB compliance pathways and Germany's TÜV certification requirements are lengthening approval timelines, compressing supplier margins.
Onboard Systems dominates by unit volume. Custom Installations are expanding most quickly as commercial modifiers electrify legacy platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mount suppliers export hydraulic and active-controlled assemblies to Chinese OEMs, while Japanese compounders serve Southeast Asian assembly plants. This trade corridor concentrates high-value procurement decisions in Stuttgart, Wolfsburg, and Shanghai.
United States
Commercial fleet operators in Michigan and Ohio are delaying full electrification to manage capital replacement cycles. EPA Tier 3 compliance costs are narrowing the viable engine supplier base for heavy-duty platforms. Detroit-based OEMs are consolidating mount vendor panels to reduce qualification overhead.
Germany
Luxury automakers in Baden-Württemberg and Bavaria specify active electromagnetic mounts for hybrid architectures. REACH Article 33 restrictions on zinc-based vulcanization accelerators are forcing compound reformulation. Stuttgart suppliers are front-loading R&D to secure 2027 ECHA compliance deadlines.
China
Domestic OEMs in Shanghai and Guangdong are sourcing lightweight aluminum-rubber hybrid mounts for NMPA certification. MIIT dual carbon targets are tightening mass-reduction requirements. Yangtze River Delta fabricators are scaling silicone-hydraulic production for turbocharged domestic brands.
Japan
Acoustic decoupling demand from Toyota and Honda is concentrating procurement in Aichi and Kanagawa prefectures. METI energy efficiency standards are shaping powertrain development timelines. Nagoya-based specialists dominate Asian OEM supply chains for NVH-critical applications.
India
Maruti Suzuki and Tata Motors are expanding export programs under the PLI scheme for automotive components. BIS certification pathways now favor local mount production. Tamil Nadu and Gujarat assembly clusters are absorbing tooling investment from tier-1 compounders.
Global Automotive Engine and Engine Mounts Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and captive rubber compounding. The supplier base organizes into three tiers: global system integrators with in-house elastomer operations, regional hydraulic specialists serving luxury platforms, and commodity passive-rubber fabricators facing margin compression. Consolidation is accelerating through backward integration into compound formulation and strategic partnerships with sensor vendors for active-mount electronics.
Within the system-integrator tier, Continental AG and ZF Friedrichshafen AG represent German engineering conglomerates with captive vibration-control divisions. MAHLE GmbH exemplifies thermal-management specialists extending into mount durability under turbocharged loads. Among Asian compounders, Sumitomo Riko Company Limited anchors acoustic-decoupling supply chains for domestic OEM procurement.
| Leading Market Players |
|---|
| Sumitomo Riko Company Limited |
| Hutchinson |
| Continental AG |
| Trelleborg AB |
| Vibracoustic |
| ZF Friedrichshafen AG |
| Cooper Standard |
| MAHLE GmbH |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Silicone-hydraulic fluid substitution for conventional natural rubber compounds is redrawing procurement geography toward Yangtze River Delta chemical clusters while compressing margins for Thai rubber-dependent fabricators. This input transition simultaneously elevates active mount pricing premiums and erodes passive rubber supplier bargaining power against OEM procurement panels.
Pricing Analysis
Next-generation active electromagnetic mounts command three-to-fourfold premiums over hydraulic variants, while hydraulic assemblies maintain two-to-threefold spreads above passive rubber designs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from REACH compliance costs in European supply chains, compressing compounder margins without full pass-through to OEMs. Aftermarket distributors in Brazil and Mexico exhibit highest price sensitivity, while German luxury OEMs prioritize NVH performance guarantees over unit cost.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo is elevating inbound logistics costs for German and Japanese compounders sourcing silicone precursors from Chinese chemical producers. Manufacturing concentrates in Germany, China, and Japan, with Thailand and Indonesia supplying raw natural rubber feedstock. The chain draws from synthetic elastomer polymers, hydraulic fluids, and aluminum die-cast subframes. Single-source vulnerability runs through Yangtze River Delta silicone-hydraulic fluid production. Distribution runs through OEM captive portals for active mounts and independent aftermarket channels for passive rubber replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
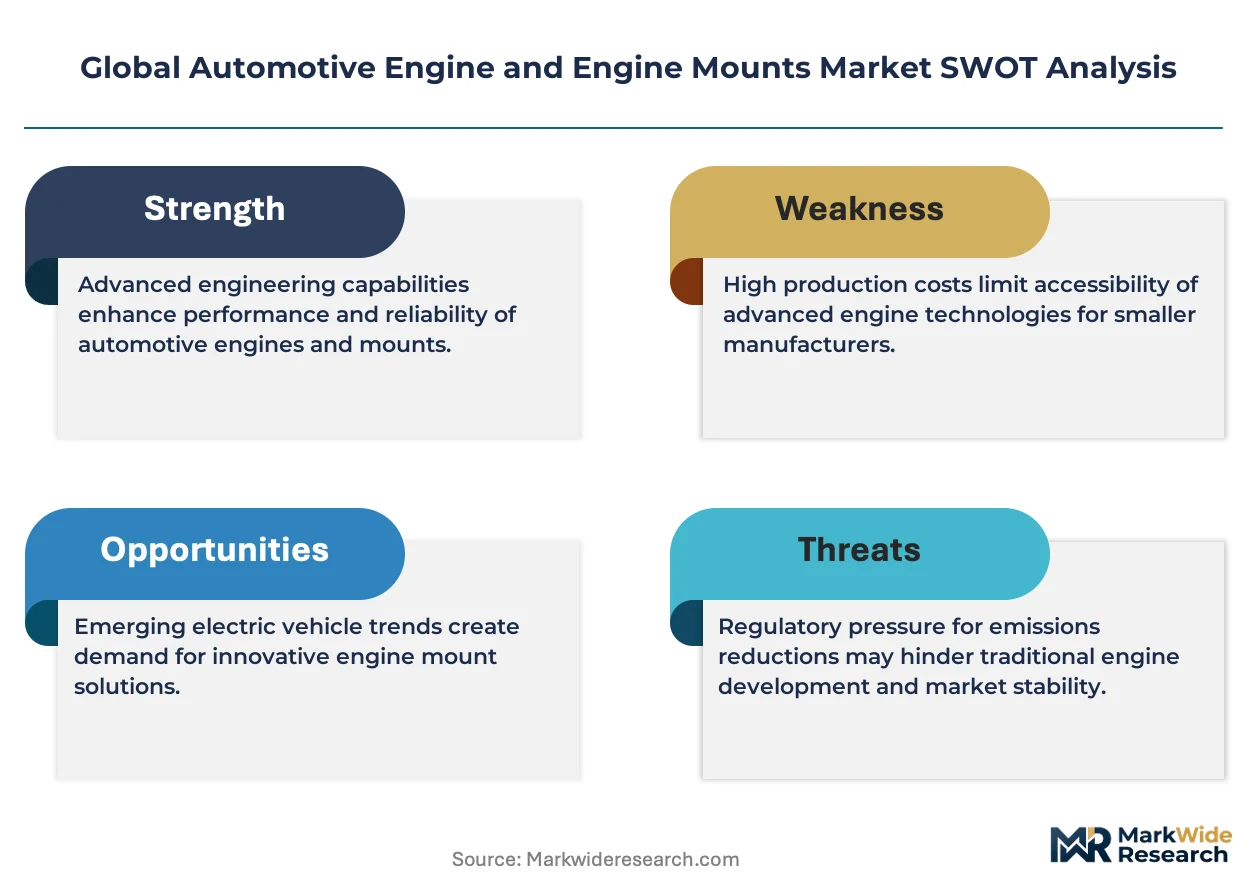
Multi-physics simulation talent scarcity is constraining supplier capacity to model coupled thermal-mechanical-electric mount behavior, creating bottlenecks for hybrid platform qualification timelines. This capability gap favors incumbents with established Stuttgart and Shanghai engineering centers over new entrants lacking NVH modeling infrastructure.
For Market Incumbents: Secure captive rubber compounding capacity to defend margin against natural rubber price volatility from Thai and Indonesian supply disruptions. Prioritize backward integration into silicone-hydraulic fluid formulation to meet Euro 7 thermal rating requirements while locking out compound-dependent competitors. Consolidate active mount electronics partnerships with sensor vendors before Korean OEMs finalize mid-size crossover platform sourcing. For New Entrants and Emerging Players: BIS certification fast-tracks under India's PLI scheme offer the most penetrable entry pathway for Maruti Suzuki and Tata Motors export programs. Target Tamil Nadu and Gujarat assembly clusters with localized passive rubber production to bypass established German-Japanese supplier hierarchies. Pursue direct OEM contracting models in Brazil and Mexico aftermarket channels to capture margin currently held by distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European hydraulic mount specialists facing REACH reformulation cost overruns and stranded tooling risks. Five-to-ten year viability hinges on successful transition to active-controlled architectures and software-defined performance capabilities. Watch for MIIT dual carbon target acceleration in China as inflection indicator for lightweight aluminum-rubber hybrid mount demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone-Hydraulic Compound Qualification | REACH 2027 compliance deadlines in Germany force accelerated ECHA-aligned reformulation programs. |
| Active Electromagnetic Mount Platform Integration | Real-time NVH cancellation capabilities secure hybrid procurement from Stuttgart luxury OEMs. |
| India PLI Localization Investment | BIS certification pathways in Tamil Nadu capture Maruti Suzuki and Tata Motors export volume. |
| Predictive Maintenance Data Partnerships | Lifetime performance guarantees align with US and German fleet lessor outcome-based contracting. |
| Magnetorheological Fluid Electronics Convergence | Sensor feedback integration fragments traditional hydraulic supplier hierarchies in Korean crossover platforms. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations converged on the working assumptions underlying volume and value estimates. Primary fieldwork across Stuttgart, Wolfsburg, Shanghai, and Nagoya was cross-referenced with vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and MIIT certification records. Bottom-up build from component-level bill-of-materials analysis was reconciled against top-down OEM powertrain sourcing disclosures to establish triangulated baseline figures.
Segmentation dimensions modeled span propulsion architecture, mount technology tier, vehicle class, OEM tier positioning, and regional production cluster. CAGRs were derived from regression against historical platform launch cadences and regulatory phase-in calendars across the analysis window. Forecast inputs incorporated EPA Tier 3 and Euro 7 compliance cost trajectories, MIIT dual carbon mass-reduction targets, and silicone-hydraulic compound adoption curves from turbocharged powertrain penetration.
Decision-makers should treat outputs as directional under base assumptions of synchronized regulatory phase-in calendars and stable natural rubber supply from Southeast Asia; material deviation would warrant model refresh. Specific risks include REACH Annex XVII restriction acceleration, solid-state battery platform cancellations eliminating engine bays entirely, and conflicting GB standards from SAMR and MIIT extending hybrid mount qualification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission Fluid Market
Powertrain
North America Precision Gearbox Market
Powertrain
Transmission Repair Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
North America Torque Vectoring Market
Powertrain
EV Powertrain Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Automotive Retrofit Electric Vehicle Powertrain Market
Powertrain
Iridium Spark Plug Market
Powertrain
Automotive Engine Market
Powertrain
Engine Rocker Arm Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Drive Shaft Market
Powertrain
Global Automotive Engine Belt and Hose Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Automotive Engine Cylinder Block Market