
 Global Automotive Engine Cover Market | 2026-2036
Global Automotive Engine Cover Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Engine Cover Market Intelligence
IATF 16949 certification for automotive quality management systems is bifurcating the supplier landscape for engine covers. This standard separates large, globally certified suppliers from smaller, regional players. Magna International leverages its scale in polymer processing and molding to serve global OEM platforms. Faurecia competes on integrated acoustic and thermal management solutions embedded within its cover designs, while MAHLE specializes in engine components, offering a systems-based approach.
An automotive engine cover is a molded component designed to fit over the top of an internal combustion engine or electric motor components. Often manufactured from materials like polypropylene or glass-fiber reinforced polymers, these covers are engineered for specific thermal resistance and Noise, Vibration, and Harshness (NVH) damping properties. Composite covers represent the fastest-growing product type, driven by vehicle lightweighting initiatives. The passenger vehicles application dominates volume, with OEM manufacturers constituting the primary procurement channel for new vehicle production lines.
Regulatory frameworks directly influence material selection and design. In the United States, EPA fuel economy mandates push for lighter composite materials, while the EU Green Deal encourages the use of recyclable polymers. Chinese GB standards also set stringent requirements for material safety and performance. Suppliers must now decide how to adapt their product portfolios and material science expertise for the distinct requirements of battery electric vehicle platforms.
Market Dynamics
The automotive engine cover market is defined by a fundamental design bifurcation. Material science and engineering are being pulled in two directions by the simultaneous demands of lightweighting internal combustion engines and developing entirely new components for electric vehicle thermal management systems.
Growth Catalysts
- Vehicle Lightweighting Initiatives:Mandates such as the EPA's fuel economy standards in the United States compel automakers to adopt lighter components, driving the substitution of metal with advanced glass-fiber reinforced polymer covers on passenger vehicles.
- OEM Manufacturing Concentration:The expansive automotive OEM sector in China creates concentrated, high-volume demand, rewarding suppliers who establish local production and supply chain capabilities compliant with GB standards for materials.
- Advanced Material Adoption:The development of new composite formulations with superior thermal resistance and NVH damping properties enables suppliers to offer higher-performance products, expanding applications in premium and performance vehicle segments.
Market Restraints
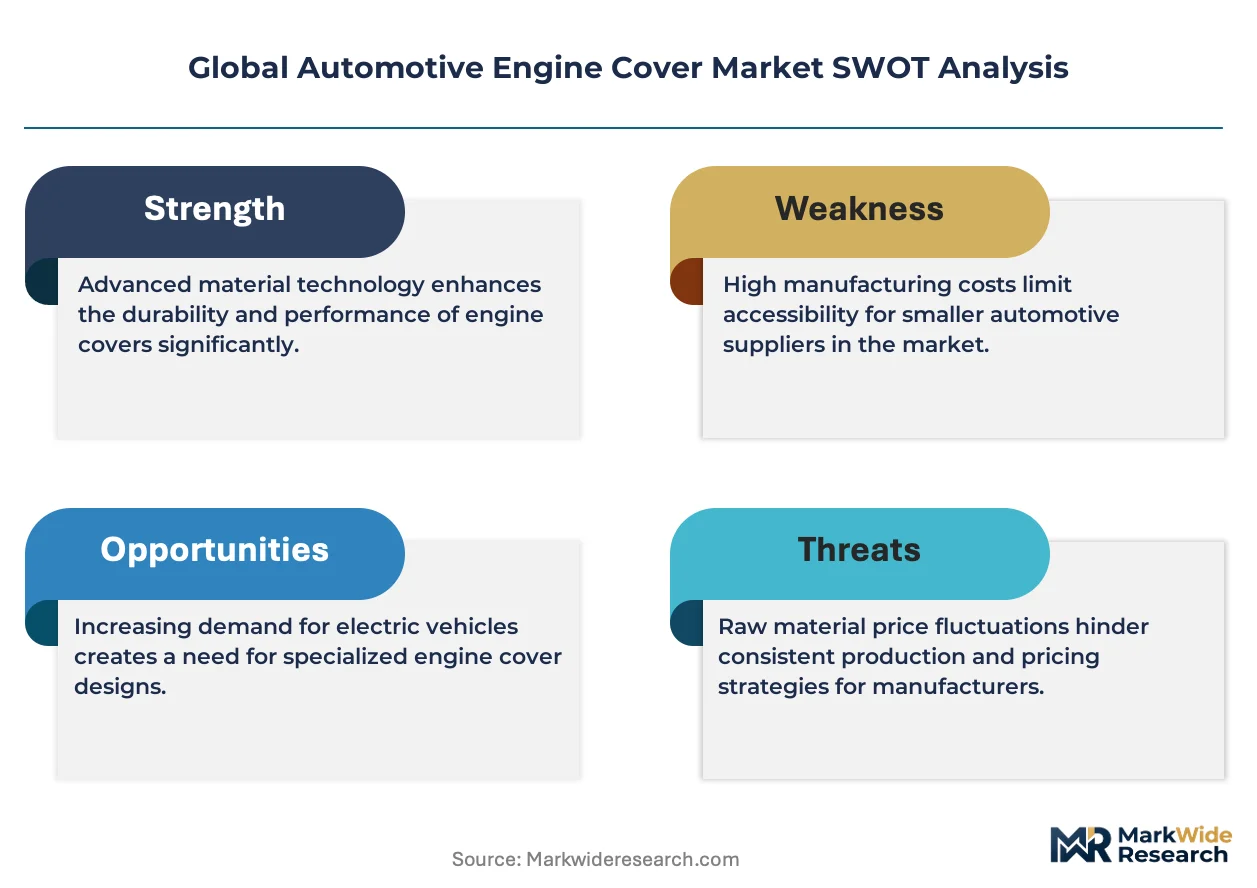
- Input Cost Volatility:Supplier margins are exposed to price fluctuations in key raw materials, particularly for polypropylene resins and glass fibers, which are tied to global petrochemical and energy markets.
- Electric Vehicle Substitution:The transition to battery electric vehicles (BEVs) eliminates the traditional engine cover, presenting a direct substitution threat as demand shifts toward integrated battery pack enclosures and thermal system components.
- Technical Performance Trade-offs:Engineering composite covers involves a difficult balance between weight, stiffness, acoustic damping, and thermal stability, with material limitations sometimes hindering performance in extreme temperature environments.
Strategic Opportunities
- EV-Specific Components:There is a significant opportunity to design and manufacture covers and enclosures for BEV components like inverters, onboard chargers, and battery packs, which require unique thermal, structural, and EMI shielding properties.
- Sustainable Materials Integration:European Union Green Deal incentives create an opening for suppliers to commercialize engine covers made from recycled polymers or bio-based composites, appealing to OEMs focused on circular economy goals.
- Expansion in Emerging Auto Hubs:Supplying the growing automotive production ecosystems in countries like India and Mexico offers a path to growth as local manufacturers upgrade vehicle platforms and adopt more sophisticated components.
Industry Challenges
- Stringent Certification Hurdles:Achieving and maintaining the mandatory IATF 16949 quality certification for new materials or manufacturing facilities is a time-consuming and resource-intensive process that can delay market entry.
- Capital Investment for Automation:The production of complex, molded composite covers requires significant upfront capital expenditure in specialized presses, tooling, and robotic handling systems to achieve OEM quality and volume targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Engine Cover Market |
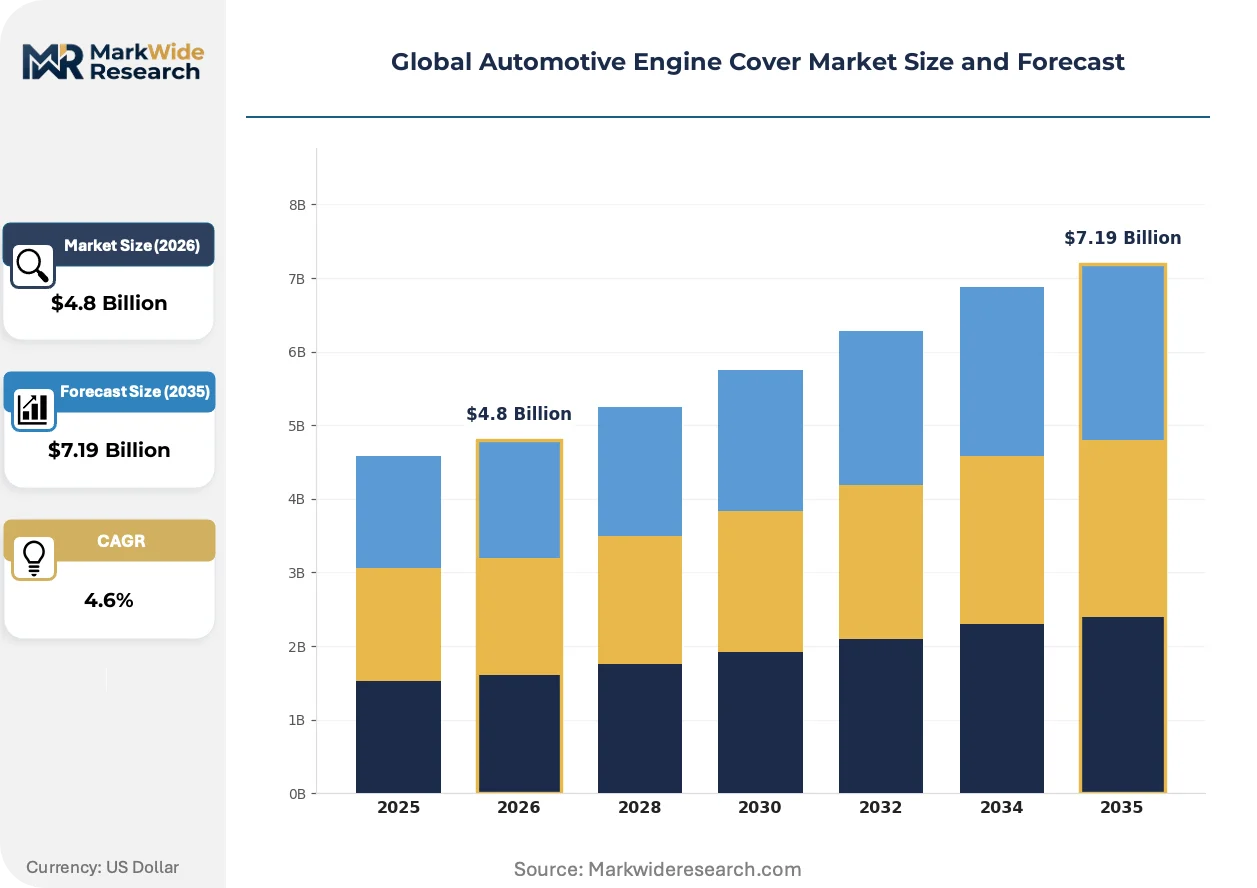
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Covers, Steel Covers, Composite Covers, Plastic Covers, Carbon Fiber Covers Material: Polypropylene, Thermoplastic Elastomer, Polycarbonate, Glass-Fiber Reinforced Polymer, Nylon Application: Passenger Vehicles, Commercial Fleet, Off-Highway Vehicles, Specialty Vehicles, Agricultural Machinery End User: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Providers, Vehicle Assemblers |
| Companies Covered | Magna International, Faurecia, Samvardhana Motherson, Denso, MAHLE, Röchling Automotive, Plastic Omnium, Montaplast, Toyoda Gosei Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Engine Cover Market Strategic Shifts & Innovations
Adaptation is the central theme defining product development. Suppliers are evolving their material science and engineering focus to serve two divergent powertrain architectures: increasingly efficient internal combustion engines and the distinct thermal and acoustic needs of electric vehicle platforms.
Embedded sensor technology is a key area of product evolution. These systems integrate monitoring capabilities for temperature and vibration directly into the cover's structure. Premium vehicle manufacturers are adopting this technology to gain more precise engine operating data, and the cover itself is miniaturizing the need for separate sensor brackets and wiring.
Regulatory frameworks like the EU Green Deal are accelerating the push for material circularity. This policy is forcing a design shift toward mono-material polypropylene covers that are more easily recycled at a vehicle's end of life. The composite materials segment is most affected, now facing pressure to demonstrate viable recycling pathways for its products.
A notable behavioral shift is occurring in how automakers source these components. OEMs are increasingly seeking integrated engine bay modules rather than procuring individual parts. This trend disrupts traditional Tier-2 component specialists, favoring larger Tier-1 suppliers who can deliver a complete acoustic and thermal management solution, a pattern highly visible among German automakers.
Global Automotive Engine Cover Market Segmentation

Segmentation within the global automotive engine cover market reveals the nuanced shifts in material science, application demands, and procurement strategies. This granular view highlights how lightweighting mandates and the electric vehicle transition are fundamentally reshaping product development and supplier engagement across the industry.
Product Type:
The product type segmentation highlights the ongoing material substitution pressures as traditional metal covers face displacement by advanced polymer solutions.
- Composite Covers:These covers integrate multiple materials, often thermoset or thermoplastic matrices reinforced with fibers, to achieve high strength-to-weight ratios. Demand concentrates in passenger vehicles, driven by stringent EPA fuel economy mandates in the United States and EU Green Deal lightweighting objectives.
- Plastic Covers:Typically molded from polypropylene or other engineering plastics, these covers offer a balance of cost, weight reduction, and basic Noise, Vibration, and Harshness (NVH) damping. High-volume procurement occurs within the Chinese automotive OEM sector for mainstream passenger vehicle platforms, prioritizing cost-efficiency.
- Aluminum Covers:These covers offer superior thermal management and structural rigidity, primarily serving high-performance or heavy-duty engine applications.
- Steel Covers:Steel covers provide robust protection and cost-effectiveness for entry-level or legacy internal combustion engine designs.
- Carbon Fiber Covers:Offering ultimate lightweighting and aesthetic appeal, carbon fiber covers are exclusive to premium and performance vehicle segments.
Plastic Covers anchor the volume base while Composite Covers gain share at the steepest rate.
Material:
Material segmentation reflects the diverse cost and performance tiers available to automotive manufacturers, balancing thermal and acoustic requirements.
- Glass-Fiber Reinforced Polymer:These advanced composites combine polymer matrices with glass fibers, offering enhanced stiffness, impact resistance, and thermal stability for engine bay applications. Adoption is accelerating in premium passenger vehicle platforms across Europe and North America, supporting vehicle lightweighting initiatives.
- Polypropylene:A versatile thermoplastic polymer, polypropylene offers excellent moldability, chemical resistance, and a favorable cost profile for mass-produced engine covers. High-volume use is concentrated in mainstream passenger vehicles, particularly in Asia, due to its balance of performance and manufacturing economy.
- Thermoplastic Elastomer:These materials provide flexibility and NVH damping properties, often used for seals or integrated acoustic components within covers.
- Polycarbonate:Polycarbonate offers high impact strength and temperature resistance, suitable for applications requiring enhanced durability.
- Nylon:Nylon, or polyamide, provides good mechanical strength and thermal performance, utilized in more demanding under-hood environments.
Polypropylene supply remains highly concentrated among major petrochemical producers, influencing global pricing and availability for engine cover manufacturers.
Application:
The application segments illustrate distinct volume profiles and performance requirements across various vehicle types.
- Passenger Vehicles:Engine covers for passenger vehicles prioritize lightweighting, NVH reduction, and aesthetic integration, often utilizing advanced composites and plastics. This application segment accounts for the largest volume globally, with significant procurement from OEM manufacturers in China, Europe, and North America.
- Commercial Fleet:Covers for commercial fleet vehicles emphasize durability, thermal resistance for heavy-duty cycles, and ease of maintenance, often employing robust plastics or aluminum. Procurement is driven by truck and bus manufacturers seeking long-life components for demanding operational environments.
- Off-Highway Vehicles:These applications require extreme durability and resistance to harsh environmental conditions, often employing heavy-duty plastic or metal covers.
- Specialty Vehicles:Engine covers for specialty vehicles demand customized designs to meet unique performance, protection, or aesthetic criteria.
- Agricultural Machinery:Covers in agricultural machinery prioritize robust protection against dust, debris, and vibration in challenging field conditions.
Passenger Vehicles represent a mature application segment, while Off-Highway Vehicles continue to evolve with specific material and design needs.
End User:
End user segmentation delineates the primary procurement channels and customer relationships defining the automotive engine cover market.
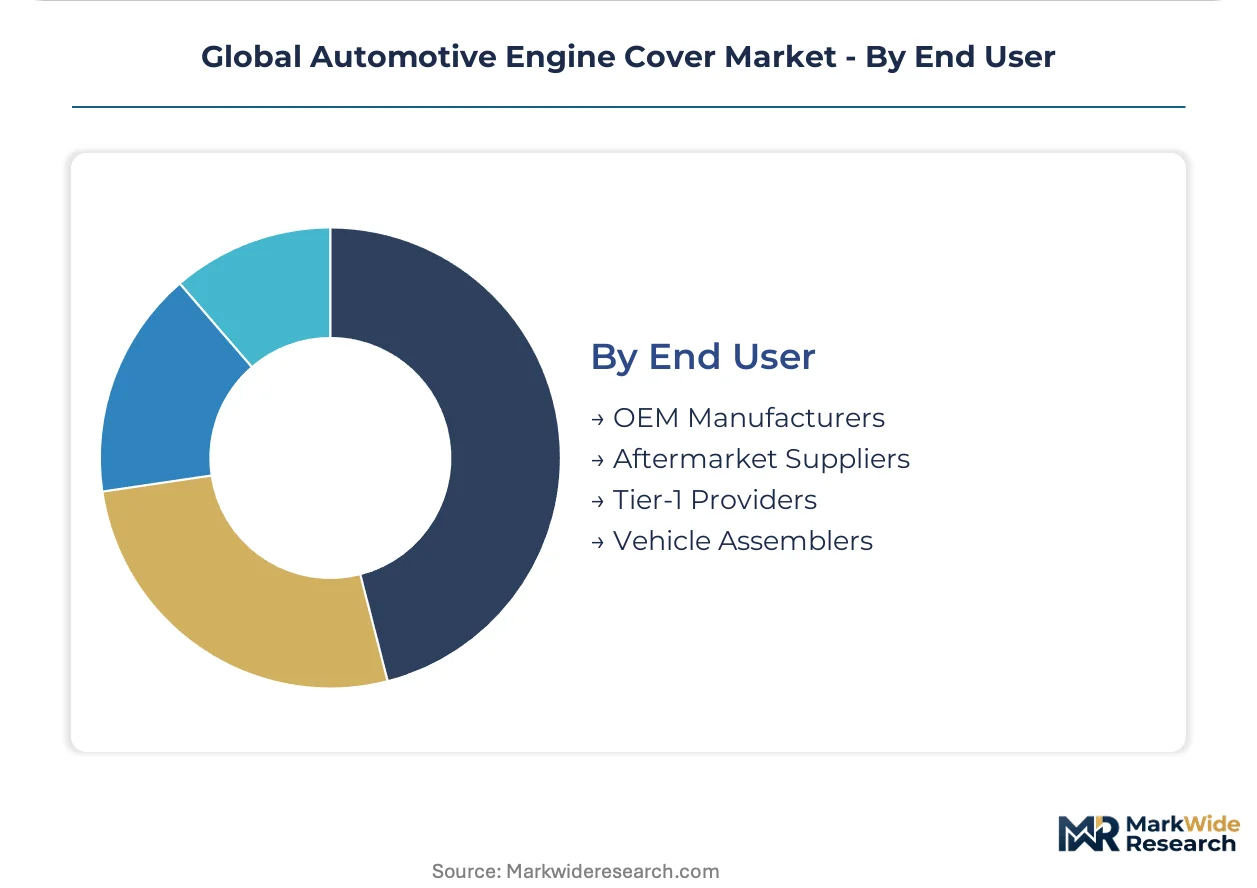
- OEM Manufacturers:Original Equipment Manufacturers procure engine covers directly for new vehicle production lines, dictating precise design, material, and quality specifications. This segment represents the largest and most influential customer base, particularly within the concentrated automotive manufacturing hubs of China and Germany.
- Tier-1 Providers:Tier-1 suppliers integrate engine covers into larger sub-assemblies or modules, offering OEMs comprehensive thermal and acoustic management solutions. This channel is growing as automakers increasingly seek integrated engine bay modules, favoring large suppliers like Magna International and Faurecia.
- Aftermarket Suppliers:Aftermarket channels provide replacement engine covers for vehicle repair and maintenance, focusing on compatibility and cost-effectiveness.
- Vehicle Assemblers:Vehicle assemblers procure engine covers as part of their final assembly process, often through direct relationships or via Tier-1 suppliers.
OEM Manufacturers drive competitive dynamics through stringent certification requirements, while Tier-1 Providers increasingly shape product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal incentives drive demand for recyclable polymers and lightweighting across the global automotive industry. These policies influence material selection for engine covers, particularly in key manufacturing regions. Automakers respond by seeking advanced composite solutions to meet environmental targets.
China
The expansive automotive OEM sector in China creates concentrated, high-volume demand for engine covers. Chinese GB standards set stringent requirements for material safety and performance within this market. Automotive production hubs in the Yangtze River Delta integrate local suppliers to meet these specific demands.
United States
Vehicle lightweighting initiatives in the United States compel automakers to adopt lighter components for engine covers. EPA fuel economy standards directly push for the substitution of metal with advanced composite materials. Michigan's automotive corridor sees OEMs and Tier-1 suppliers collaborating on advanced polymer cover development.
Germany
German premium vehicle manufacturers demand integrated acoustic and thermal management solutions within their engine covers. The EU Green Deal encourages the use of recyclable polymers, influencing material choices for component suppliers. Major automakers and Tier-1 suppliers in Bavaria and Baden-Württemberg drive innovation in engine bay modules.
India
India's growing automotive production ecosystem creates demand as local manufacturers upgrade vehicle platforms. Government initiatives encourage domestic component sourcing and local manufacturing capabilities. Automotive manufacturing hubs like Chennai and Pune see increased demand for cost-effective plastic and composite covers.
Global Automotive Engine Cover Market Key Industry Players
Player mix skews toward large, globally certified Tier-1 suppliers capable of delivering integrated solutions. The market structure is tiered, separating these major players from smaller, regional component specialists who focus on niche applications. Strategic archetypes include global system integrators, specialized material processors, and localized volume manufacturers. Competitive moves involve portfolio diversification into EV components and geographic expansion into emerging automotive hubs.
Within the integrated solutions tier, Magna International represents a polymer processing and molding powerhouse, leveraging its scale to serve global OEM platforms with diverse engine cover solutions. Faurecia exemplifies a competitor focused on embedded acoustic and thermal management solutions, integrating these advanced features directly into its cover designs for enhanced vehicle performance. MAHLE, a German-based entity, occupies a position as a systems-based supplier, specializing in broader engine components and offering a comprehensive approach to under-hood thermal management.
| Leading Market Players |
|---|
| Magna International |
| Faurecia |
| Samvardhana Motherson |
| Denso |
| MAHLE |
| Röchling Automotive |
| Plastic Omnium |
| Montaplast |
| Toyoda Gosei Co. Ltd |
| Others |
Cost & Logistics Intelligence
Large-scale polymer processing capacity drives supply concentration, establishing significant price floors for high-volume engine cover manufacturing. This scale advantage shapes both supplier market power and the competitive pricing environment for OEM procurement.
Pricing Analysis
IATF 16949 certification creates the primary spread in pricing, separating globally approved suppliers from regional players. Transactional pricing dominates the market, with differentiation driven by material quality, customization level, and geographic delivery costs. Pricing pressure stems from input cost volatility for polypropylene resins and glass fibers, alongside OEM cost-cutting initiatives. Chinese automotive OEMs for mainstream passenger vehicles exhibit the highest price sensitivity, while premium European manufacturers prioritize advanced features over cost.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized tooling and advanced materials, influence regional supply chain configurations. Geographic supply concentrates in China, Germany, and the United States, reflecting major automotive production hubs. The market relies heavily on polypropylene resins and glass fibers as key raw materials. Commodity price volatility for petrochemicals represents a significant structural supply chain risk. Distribution runs through direct channels to OEM manufacturers and indirectly via Tier-1 providers integrating engine covers into larger modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Expertise in composite material science for thermal management systems represents a significant capability scarcity in the evolving automotive engine cover market. This gap creates strategic opportunities for focused investment.
For Market Incumbents:
Secure long-term contracts with major OEMs for next-generation EV thermal management components, mitigating the substitution threat from traditional engine covers. Invest heavily in advanced material R&D for bio-based composites and mono-material recyclable polymers to meet EU Green Deal mandates. Expand global manufacturing footprints in emerging automotive hubs, leveraging IATF 16949 certification to capture new demand. Prioritize capital investment in automation for complex molded composite covers to maintain cost efficiency and quality standards.
For New Entrants and Emerging Players:
A fast-track to IATF 16949 certification offers a direct route into established OEM supply chains. Target white space in EV-specific component enclosures, focusing on inverter or onboard charger covers that require unique EMI shielding properties. Penetrate growing automotive production ecosystems in India and Mexico by offering cost-effective plastic and composite solutions tailored to local GB standards. A go-to-market angle focused on sustainable, easily recyclable materials can appeal to OEMs pursuing circular economy goals.
For Investors and Strategic Acquirers:
Recurring-revenue conversion is highest among Tier-1 suppliers offering integrated thermal and acoustic management solutions to global OEM platforms. The market's long-term viability depends on successful product portfolio adaptation to battery electric vehicle components. Target specialized material science firms or Tier-1 suppliers with proven expertise in advanced composites for acquisition. The signal to watch is OEM long-term contracts for BEV thermal management solutions, indicating sustained demand for specialized components.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into EV Components | Magna International expands its offerings to include battery pack enclosures, addressing the EV transition. |
| Geographic Expansion into Emerging Auto Hubs | Faurecia establishes production facilities in India, capitalizing on local OEM demand. |
| Advanced Composite Material R&D | MAHLE invests in next-generation glass-fiber reinforced polymers for enhanced NVH damping. |
| IATF 16949 Certification Attainment | Smaller regional players pursue certification, enabling access to global OEM supply chains. |
| Sustainable Polymer Commercialization | Röchling Automotive develops recyclable polypropylene covers, aligning with EU Green Deal mandates. |
Research Approach
Operator-level perspectives from OEM platform engineers, Tier-1 procurement leads, material science R&D directors, and automotive supply chain managers anchored the qualitative base. This primary research was triangulated with extensive secondary validation from vehicle production databases, automotive OEM annual reports, material science journals, and regulatory body publications like EPA and EU Green Deal documents. A rigorous bottom-up and top-down approach ensured comprehensive market sizing and validation.
Sensitivity analysis framed the analytical framework across the analysis window, modeling various scenarios for market evolution. Segmentation dimensions like product type (composite, plastic), material (GFRP, polypropylene), application (passenger, commercial), end-user (OEM, Tier-1), and regional production cluster were meticulously modeled. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected market shifts, integrating key industry-specific forecast inputs such as vehicle lightweighting mandates and BEV production forecasts.
Underlying assumptions cover regulatory stability and material cost trends, with deviation risk concentrated in rapid shifts in BEV adoption rates and unforeseen disruptions in petrochemical supply. Forecasts reflect these assumptions, providing a robust, data-driven outlook. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Fuel Injection Systems Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Clutch Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Power Steering Filter Market
Powertrain
Diesel Engine Management System Market
Powertrain
Reciprocating Engine Market
Powertrain
Automotive Clutch Rotor Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Automotive Camshaft Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Yaw Damper Market