
 Automotive Seat Frame Market | 2026-2036
Automotive Seat Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Frame Market Analysis
Aftermarket refurbishment programs for seat frame subassemblies are reshaping margin distribution across the value chain. Adient leverages its global manufacturing footprint to capture platform-standardization contracts from multinational OEMs. Toyota Boshoku anchors its position through captive supply relationships within the Toyota Group's vehicle programs. Lear Corporation competes on R&D intensity, particularly in magnesium-intensive frame architectures for luxury seating.
An automotive seat frame constitutes the load-bearing skeletal structure of a vehicle seat, typically fabricated from stamped high-strength steel or extruded aluminum alloy tubing with wall thicknesses between 1.2 mm and 2.5 mm, engineered to withstand crash loads specified in occupant-safety protocols while providing mounting interfaces for cushion, recliner, and track mechanisms. Steel material dominates current production volumes due to established stamping infrastructure and cost structures, though aluminum and composite alternatives are gaining share in electric vehicle programs where mass reduction directly extends driving range. Adjustable frame designs command premium positioning as OEMs consolidate seat variants across platform architectures, while fixed frames retain volume leadership in entry-segment vehicles where cost minimization overrides feature complexity.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standard 207 in the United States, mandating seat retention strength that directly governs frame gauge and joint-design requirements for vehicles sold in that market. China's Ministry of Industry and Information Technology administers GB standards for automotive seating that influence domestic frame specifications and create compliance barriers for non-certified suppliers. Japan's Ministry of Economy, Trade and Industry coordinates JIS standards that shape export-oriented frame designs from Japanese seating suppliers. Stakeholders must monitor divergence between regional crash-safety test protocols and carbon-accounting rules to anticipate where frame material specifications will tighten next.
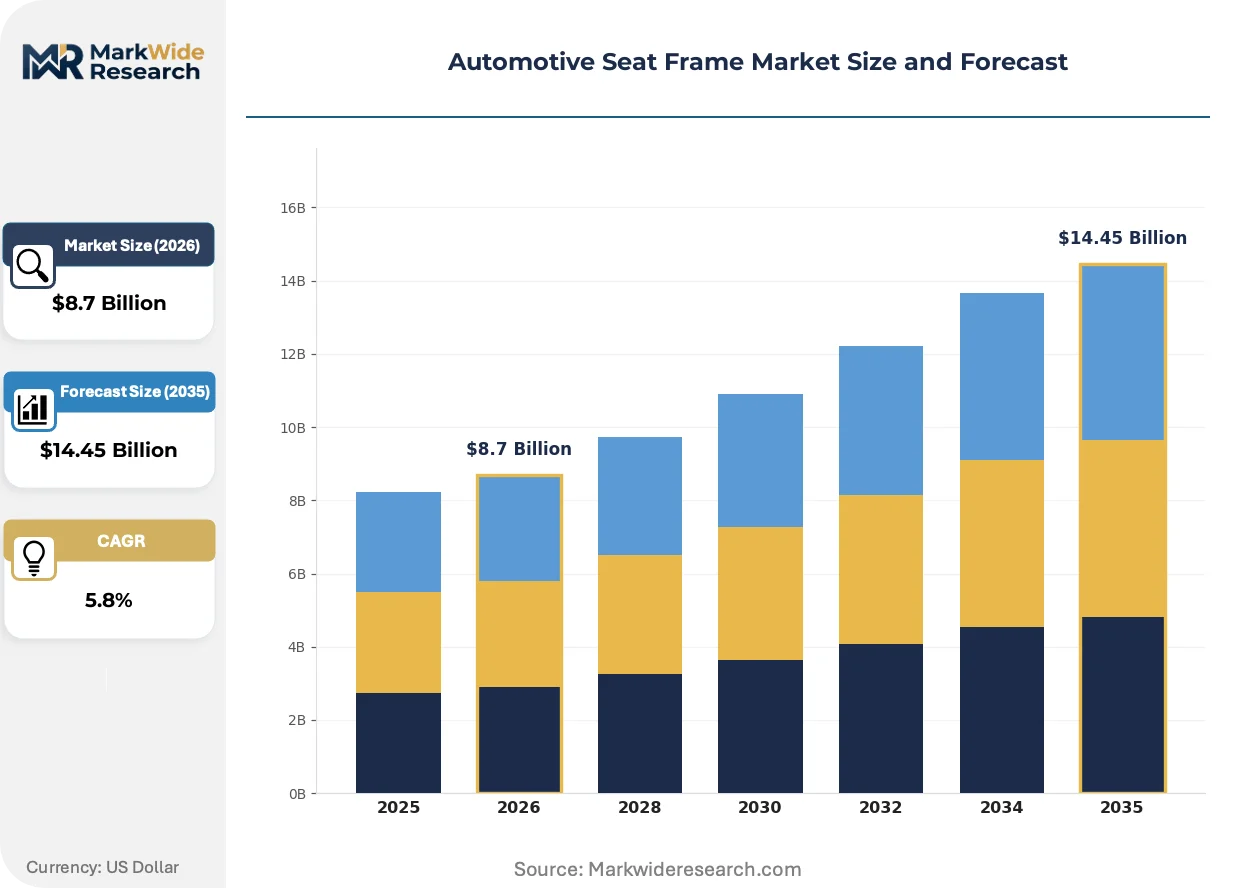
Market Dynamics
Platform consolidation across multinational OEMs is compressing seat frame variant counts while simultaneously demanding higher crash-performance ratings, forcing suppliers to amortize development costs across larger production runs.
Growth Catalysts
- EU Green Deal:Material emissions caps for stamped metal components are accelerating aluminum adoption in European electric vehicle programs, creating specification pull for lighter frame architectures.
- Adjustable frame designs:OEM platform consolidation strategies are expanding premium positioning for modular seat skeletons that reduce variant complexity across multiple vehicle lines.
- China's dual carbon goals:Domestic MIIT enforcement of carbon-accounting rules for automotive components is tightening compliance requirements and favoring certified suppliers with verified low-carbon steel sourcing.
Market Restraints
- High-strength steel price volatility:Input cost swings for automotive-grade stamped sheet metal compress margins for frame manufacturers locked into annual pricing contracts with seating Tier 1s.
- Japan keiretsu concentration:Toyota Boshoku's captive supply relationships within the Toyota Group create structural barriers for independent frame suppliers seeking access to Japanese OEM volume.
- Magnesium corrosion limitations:Salt-spray durability constraints restrict magnesium-intensive frame architectures to dry-climate luxury applications, capping addressable market expansion.
Strategic Opportunities
- Aftermarket refurbishment:Seat frame subassembly remanufacturing programs for commercial vehicle fleets are opening margin capture outside OEM captive supply chains.
- GB standard alignment:China's MIIT certification requirements for domestic seating create compliance barriers that certified foreign suppliers can leverage for premium positioning in local electric vehicle programs.
- Topology optimization software:Convergence of generative design tools with additive manufacturing prototyping is compressing frame development cycles for low-volume specialty vehicle applications.
Industry Challenges
- Crash-safety certification timelines:Divergence between NHTSA FMVSS 207, EU UNECE regulations, and China's GB standards forces suppliers to maintain parallel testing protocols, extending program validation cycles.
- Weld-quality automation:High-strength steel gauge reductions for mass reduction require robotic laser welding investments that mid-cap frame stampers struggle to finance.
- Legacy track mechanism interfaces:Seat frame mounting point standardization lags behind platform consolidation, forcing custom bracket engineering for each OEM seat program.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Frame Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Frame, Reclining Frame, Folding Frame, Adjustable Frame Material: Steel, Aluminum, Composite, Plastic End User: OEMs, Aftermarket Providers, Dealers, Manufacturers Feature: Lightweight Design, Enhanced Comfort, Modular Structure, Safety Compliance |
| Companies Covered | Adient, Lear Corporation, Faurecia, Toyota Boshoku Corporation, Magna International, Brose, Johnson Controls, TS Tech, Hyundai Dymos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Frame Market Emerging Trajectories
Digital thread integration across design-to-manufacturing workflows is compressing seat frame development cycles while enabling real-time performance simulation against evolving crash-safety protocols.
Generative design software is digitizing frame topology optimization, allowing engineers to algorithmically distribute material only where load-path analysis demands. Luxury seating suppliers are adopting these tools fastest, using topology-optimized stampings to meet aggressive mass targets without sacrificing FMVSS 207 retention strength. The technology is digitizing traditional iterative prototyping, collapsing months of physical testing into simulation loops that validate joint designs before tool steel is cut.
REACH substance restrictions on hexavalent chromium plating are forcing conversion to trivalent alternatives or zinc-nickel coatings for seat frame corrosion protection. European seating suppliers face the tightest compliance deadlines, with surface treatment lines requiring capital retrofit by 2026. German OEM supply chains are responding fastest, qualifying alternative coatings through accelerated corrosion testing protocols that maintain warranty coverage.
Fleet operators are unbundling seat refurbishment from complete vehicle lifecycle contracts, creating direct procurement relationships with frame subassembly specialists. This disintermediation is most visible in North American commercial vehicle markets, where leasing companies now specify remanufactured frame cores with refreshed track mechanisms. The shift compresses supplier margins on new-frame sales while opening aftermarket service revenue streams previously captured by seating integrators.
Automotive Seat Frame Market Segmentation
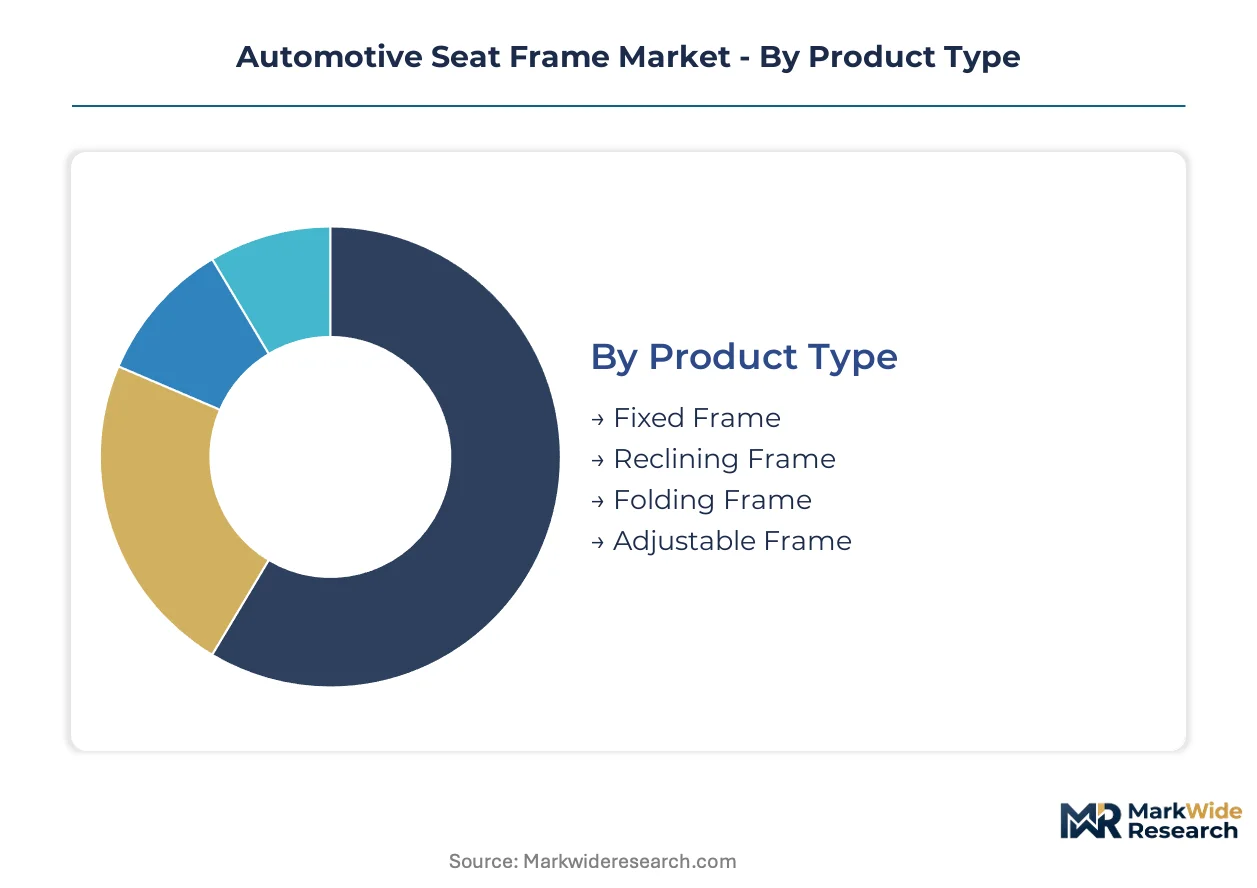
Seat frame procurement cycles vary dramatically across product architectures and material specifications. OEM platform consolidation is compressing variant counts in high-volume segments while opening premium niches for specialized configurations.
Product Type:
Fixed frames turn over on 5-7 year vehicle platform cycles, while adjustable architectures refresh every 2-3 years as seating feature sets expand.
- Fixed Frame:Stamped high-strength steel skeletons with welded joint construction dominate entry-segment and fleet vehicle specifications. Demand concentrates in China's domestic OEM supply chain where MIIT cost-pressure compliance favors minimal-complexity designs.
- Reclining Frame:Hinged backrest mechanisms with integrated recliner hardware enable occupant posture adjustment across multiple detent positions. German premium OEM programs in Baden-Württemberg and Bavaria specify these architectures for mid-luxury sedans where seat customization commands pricing premiums.
- Folding Frame:Collapsible seat structures with quick-release latch mechanisms support cargo flexibility in compact MPVs and commercial vans.
- Adjustable Frame:Multi-axis positioning systems integrating track, height, and tilt actuators serve flagship vehicle lines. Japan's keiretsu seating networks capture the bulk of specification development for these complex assemblies.
Fixed frames dominate installed base. Adjustable frames are where expansion concentrates.
Material:
Raw material selection stratifies sharply by cost tier and regulatory exposure, with carbon-accounting rules now penetrating sourcing decisions.
- Steel:Automotive-grade high-strength low-alloy stampings with tensile strengths exceeding 500 MPa anchor volume production. China's dual carbon enforcement through MIIT is tightening low-carbon steel verification requirements for domestic OEM supply chains.
- Aluminum:Extruded 6061-T6 tubing and cast nodes reduce mass 40-50% versus steel equivalents. EU Green Deal material emissions caps are accelerating specification pull from Stuttgart, Wolfsburg, and Munich-based electric vehicle programs.
- Composite:Glass-fiber reinforced polyamide structures serve ultra-lightweight niche applications.
- Plastic:Injection-molded structural polymers with metal inserts occupy cost-minimized segments in emerging market vehicle lines.
Steel retains volume leadership. Aluminum is climbing the fastest on regulatory-driven specification shifts.
End User:
Customer type determines contract structure, with captive supply relationships exhibiting fundamentally different margin profiles than arm's-length procurement.
- OEMs:Direct platform-standardization contracts with multinational vehicle manufacturers specify frame architectures across multiple nameplates. Germany's premium OEM supply chain and Japan's keiretsu networks represent the most concentrated demand pools.
- Aftermarket Providers:Independent remanufacturing specialists serving commercial fleet refurbishment programs. North American leasing companies now unbundle seat lifecycle contracts, creating direct procurement channels previously intermediated by seating integrators.
- Dealers:Authorized service networks handling warranty replacement and collision repair volume.
- Manufacturers:Tier 1 seating suppliers producing captive frame subassemblies for in-house final assembly.
OEMs dominate installed base. Aftermarket providers are gaining share fastest as fleet operators unbundle refurbishment contracts.
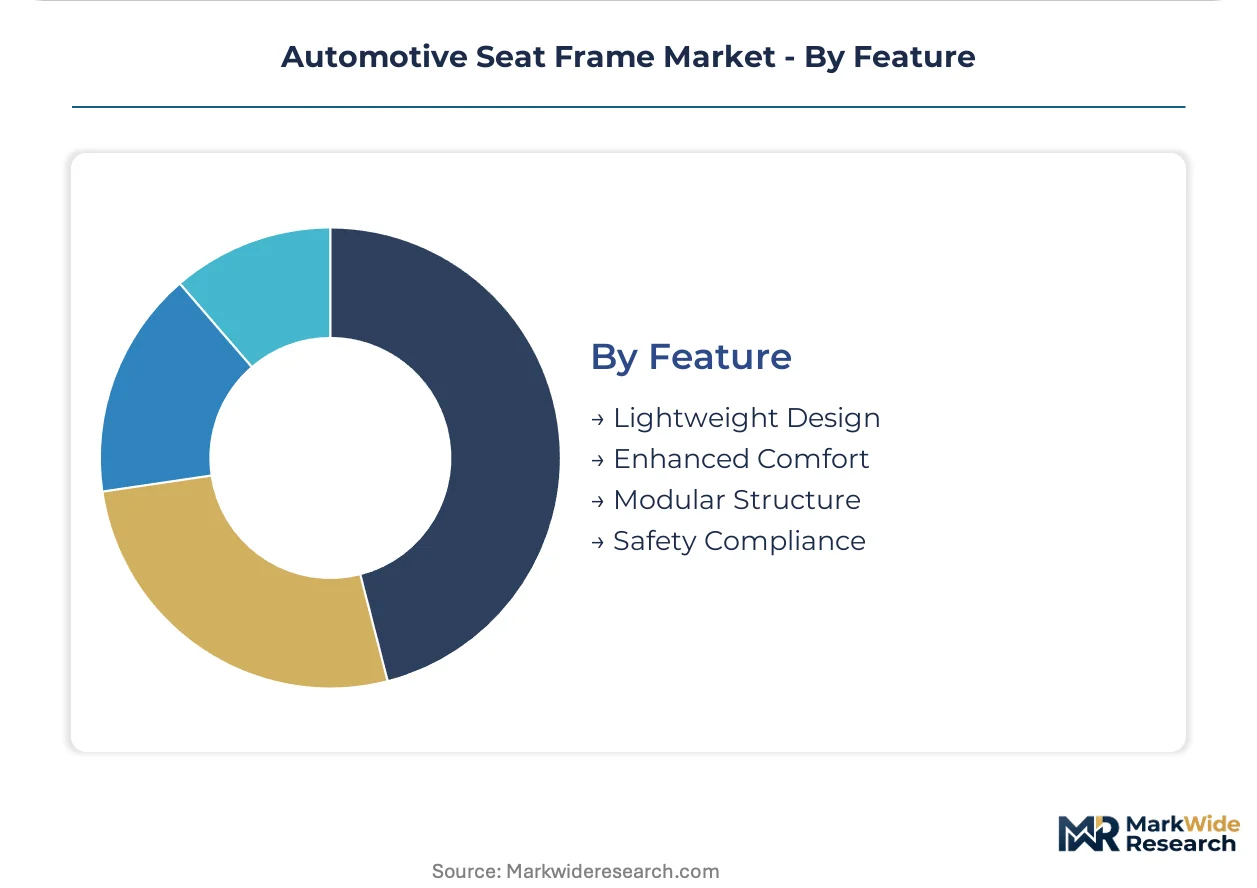
Feature:
Feature prioritization correlates with vehicle segment positioning, with safety compliance now a baseline rather than differentiator.
- Lightweight Design:Topology-optimized stampings and hollow-section extrusions target electric vehicle range extension. Germany's KBA type-approval processes for modified crash structures are tightening validation requirements for mass-reduced architectures.
- Enhanced Comfort:Vibration-damping frame isolators and ergonomic contour mounting interfaces serve long-haul commercial applications. Japanese OEM specifications for highway coach seating incorporate these features as standard.
- Modular Structure:Common frame cores with variant-specific bracket kits reduce tooling investment across platform derivatives.
- Safety Compliance:FMVSS 207-certified retention strength and UNECE R14 anchor point specifications form mandatory baseline requirements.
Safety compliance dominates installed base as a universal requirement. Lightweight design is where specification investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major automotive manufacturing bases. German premium OEMs prioritize lightweight aluminum architectures for electric vehicle range extension. Chinese domestic brands favor stamped steel fixed frames under MIIT cost compliance pressure. Japanese keiretsu networks concentrate specification development for complex adjustable assemblies.
Germany
Baden-Württemberg and Bavaria anchor European demand for aluminum-intensive frame architectures. The EU Green Deal's material emissions caps for stamped metal components accelerate specification pull from Stuttgart and Munich-based electric vehicle programs. Wolfsburg-area OEM supply chains consolidate platform-standardization contracts across multiple nameplates.
China
Domestic OEMs in the Yangtze River Delta and Pearl River Delta drive volume demand for cost-minimized steel fixed frames. MIIT enforcement of dual carbon goals tightens low-carbon steel verification requirements for component suppliers. Beijing-based regulators shape GB standards that influence frame specifications for export-oriented production.
Japan
Toyota Boshoku's captive supply relationships within the Toyota Group concentrate adjustable frame development in Aichi Prefecture. METI-coordinated JIS standards shape export-oriented designs from Nagoya-area seating networks. Keiretsu procurement patterns create structural barriers for independent suppliers seeking access to domestic OEM volume.
United States
NHTSA FMVSS 207 retention strength requirements govern frame gauge specifications for vehicles sold in this market. Michigan and Ohio-based OEM supply chains source high-strength steel stampings from regional Tier 1 seating integrators. North American commercial fleet operators unbundle seat refurbishment contracts, creating direct procurement channels for frame subassembly specialists.
South Korea
Hyundai Motor Group and Kia specification development concentrates in Seoul Capital Area and Busan-Ulsan manufacturing corridors. Domestic seating suppliers capture platform-standardization contracts for both steel and aluminum architectures. Government-backed electric vehicle transition programs accelerate lightweight material adoption in domestic production.
Automotive Seat Frame Market Vendor Landscape
Capability concentration sits with keiretsu-affiliated specialists; scale advantage sits with multinational seating integrators. The market structures around three tiers: global Tier 1s with captive frame production, independent metal stampers serving arm's-length procurement, and regional specialists embedded in OEM supply chains. Dominant competitive moves include backward integration into stamping operations and geographic expansion through platform-standardization contracts.
Within the multinational integrator tier, Adient and Lear Corporation exemplify scale-driven positioning across multiple OEM programs. Toyota Boshoku occupies a keiretsu-anchored position within Japanese supply networks. Brose represents European-based specialization in mechatronic seat systems. These archetypes capture divergent margin structures: arm's-length contract manufacturers face annual pricing pressure, while captive suppliers defend position through program exclusivity.
| Leading Market Players |
|---|
| Adient |
| Lear Corporation |
| Faurecia |
| Toyota Boshoku Corporation |
| Magna International |
| Brose |
| Johnson Controls |
| TS Tech |
| Hyundai Dymos |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta stamping capacity expansion feeds directly into pricing leverage for high-volume steel frame contracts. Chinese MIIT cost-compliance pressure on domestic OEMs compresses margins for fixed-frame suppliers locked into annual pricing agreements with Tier 1 seating integrators.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational OEMs and Tier 1 seating suppliers, with spot purchasing limited to aftermarket refurbishment volume. Price differentiation stems from certification grade under FMVSS 207 and UNECE R14 standards versus uncertified aftermarket alternatives, alongside volume scale across platform-standardization agreements. Cost compression in entry-segment steel fixed frames is intensifying because Chinese domestic brands prioritize MIIT compliance over feature complexity. Fleet operators exhibit highest price sensitivity due to unbundled lifecycle contracts, while German premium OEMs accept premium positioning for aluminum-intensive architectures.
Supply Chain Analysis
Extended payment terms from multinational OEMs strain working capital for mid-cap frame stampers serving arm's-length procurement channels. Raw material sourcing draws from high-strength low-alloy steel mills in China, aluminum extruders in Germany, and magnesium alloy suppliers in Japan. Single-source vulnerability concentrates in robotic laser welding equipment for high-strength steel gauge reduction, with European and Japanese machine tool builders dominating installed base. Distribution runs through captive Tier 1 seating assembly plants for OEM volume, with independent stampers accessing aftermarket refurbishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation across multinational OEMs fragments specification authority, creating niche opportunities for specialists in adjustable frame architectures and low-carbon material verification.
For Market Incumbents: Entrench position through backward integration into high-strength steel stamping operations in cost-competitive manufacturing clusters, while accelerating certification investment for EU Green Deal material emissions compliance. Threat from aluminum-intensive frame architectures displacing steel in European electric vehicle programs demands captive R&D capacity in topology-optimized extrusion design. Priority lever centers on platform-standardization contract capture across multiple OEM nameplates to amortize development costs. For New Entrants and Emerging Players: Southeast Asian electric vehicle manufacturing corridors present underpenetration for aluminum frame subassembly supply, with local content requirements creating procurement preference for regional suppliers. Most penetrable segment sits in commercial fleet refurbishment programs where North American leasing companies unbundle seat lifecycle contracts from vehicle procurement. Go-to-market angle targets direct relationships with fleet operators, bypassing incumbent Tier 1 seating integrators. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because keiretsu-anchored supply relationships in Japan and platform-standardization concentration in Germany create durable moats for scale operators. Acquisition target archetype includes mid-cap stampers with FMVSS 207 certification and unutilized capacity in Yangtze River Delta or Detroit-area manufacturing corridors. Signal to watch involves MIIT enforcement intensity for dual carbon steel verification, which would accelerate certified supplier preference in Chinese domestic supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Adient leverages global footprint to consolidate frame variants across multiple OEM nameplates. |
| Backward Integration | Lear Corporation captures margin through in-house magnesium alloy casting for luxury seating architectures. |
| GB Standard Alignment | Certified foreign suppliers leverage MIIT compliance barriers for premium positioning in Chinese electric vehicle programs. |
| Aftermarket Refurbishment | North American fleet operators unbundle seat lifecycle contracts, creating direct procurement channels for subassembly specialists. |
| Topology Optimization Software | Generative design tools compress development cycles for low-volume specialty vehicle frame applications. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement patterns anchors the qualitative findings in this analysis. Primary interviews with seating program directors, automotive stamping operations managers, aftermarket fleet procurement officers, and MIIT certification specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records. Bottom-up triangulation across material consumption estimates and top-down reconciliation against OEM platform production schedules ensures dimensional consistency.
Calibration against historical platform cycle timing and material substitution elasticities shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include frame architecture type, material specification grade, end-user procurement channel, and regional regulatory cluster. CAGRs derive from compound growth pathing across discrete vehicle production forecasts and content-per-vehicle assumptions for electric vehicle versus internal combustion architectures. Industry-specific inputs incorporate EU Green Deal material emissions trajectory and MIIT dual carbon enforcement intensity.
Practitioners should monitor divergence between NHTSA, UNECE, and GB crash-safety test protocols for early signals of specification fragmentation that would reshape compliance investment requirements. Forecasts reflect assumptions regarding platform consolidation velocity, aluminum price stability, and keiretsu supply relationship durability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Catalyst Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automobile Accessories Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Bulgaria Commercial Vehicles Lubricants Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Australia Automotive Pneumatic Actuators Market