
 Automotive Active Seat Headrests Market | 2026-2036
Automotive Active Seat Headrests Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Seat Headrests Market Intelligence
A long-standing reliance on aftermarket providers for basic headrest upgrades is unwinding as OEMs directly integrate active systems into new vehicle platforms. Lear Corporation leverages its deep relationships with global automakers to embed these safety features early in the design phase. Magna International Inc. competes through its broad portfolio of seating and interior systems, offering integrated solutions. Grammer AG specializes in commercial vehicle applications, a segment with distinct durability requirements.
An automotive active seat headrest is a vehicle safety device designed to automatically move forward and upward during a rear-end collision. Its primary purpose is to reduce the distance between the occupant's head and the headrest, minimizing the potential for whiplash injuries. Electronic systems, which use sensors and pyrotechnic or spring-loaded actuators, are displacing older mechanical designs. Within technology, electromechanical solutions dominate new passenger car applications due to their reliability and fast response times.
Safety mandates from bodies like the National Highway Traffic Safety Administration (NHTSA) in the United States and testing protocols from Euro NCAP directly influence design specifications. These regulations require proven effectiveness in mitigating whiplash, pushing automakers to adopt more advanced headrest technologies. The key decision for suppliers involves balancing the cost of sophisticated electronic systems against the performance requirements of evolving crash test standards.
Market Dynamics
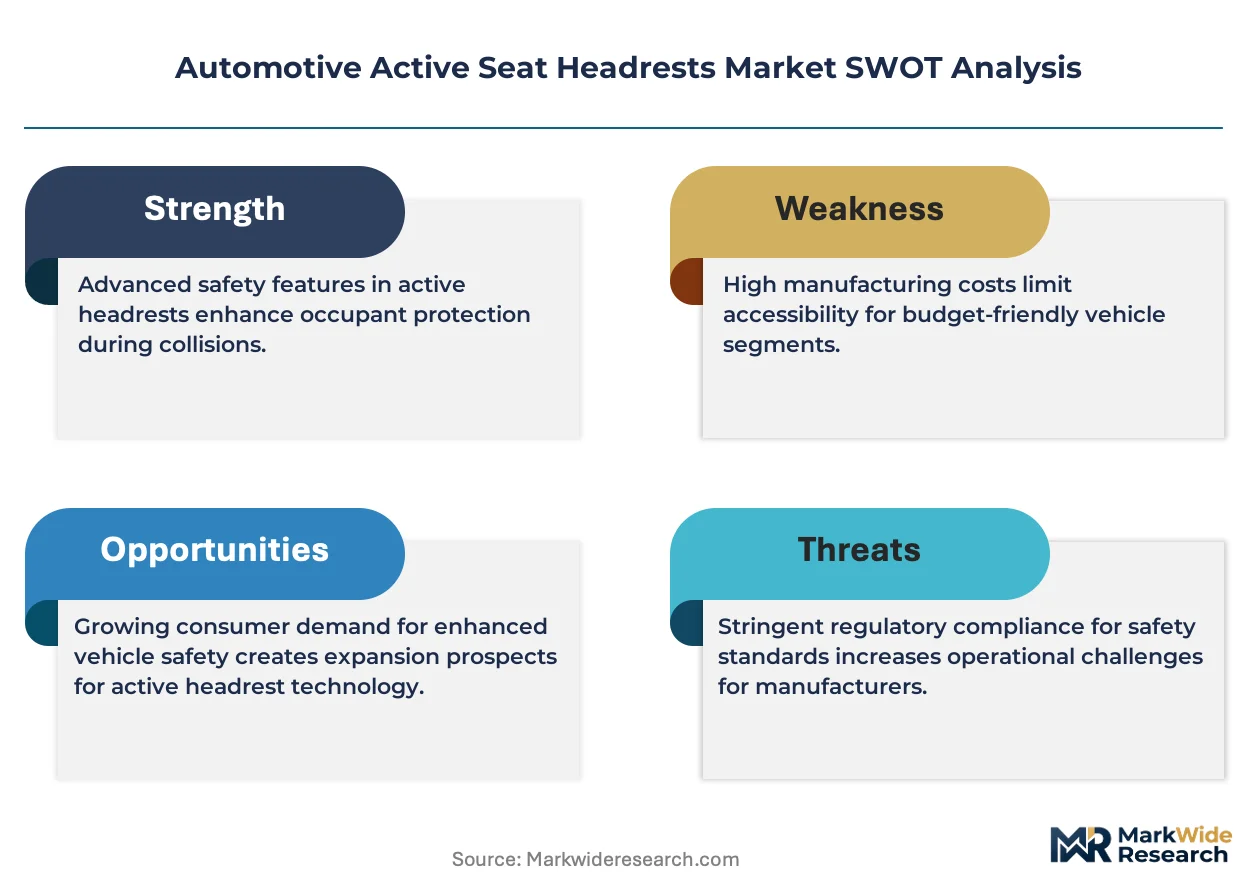
The market's central dynamic is the regulatory-driven shift from passive to active safety systems. Mandates and stringent testing protocols from bodies like Euro NCAP and the NHTSA are forcing OEMs to integrate advanced headrests to achieve top safety ratings, particularly in high-volume luxury segments.
Growth Catalysts
- Stringent Safety Protocols:Testing regimes, including Euro NCAP's whiplash assessment, directly incentivize the adoption of headrests that demonstrate measurable reductions in neck injury criteria, especially within the premium passenger vehicle segment.
- ADAS Integration:The convergence of active headrests with broader Advanced Driver-Assistance Systems (ADAS) creates a more responsive safety network, using forward-looking sensor data to pre-arm safety features before an impact.
- Demand Concentration in Automotive Hubs:Production centers in Germany and Japan show high adoption rates, as local automakers compete on safety technology for both domestic and export markets, influenced by rigorous local testing standards like those from the KBA.
Market Restraints
- High System Cost:The significant cost differential between sophisticated electromechanical active systems and basic passive headrests limits their adoption in economy and mid-range vehicle models where price sensitivity is high.
- Component Supply Bottlenecks:A reliance on a limited number of specialized semiconductor and sensor suppliers for critical components like accelerometers and microcontrollers creates supply chain vulnerability and pricing pressure for headrest manufacturers.
- Technical Complexity and Reliability:The integration of pyrotechnic or electromechanical actuators introduces greater complexity in design and testing, with potential failure points and calibration challenges not present in simpler mechanical systems.
Strategic Opportunities
- Commercial Vehicle Penetration:Expanding active headrest technology into light and heavy commercial vehicles presents a significant growth avenue, addressing unique durability and occupant safety requirements in a largely underserved segment.
- In-Cabin Monitoring Synergy:Integrating active headrests with emerging driver and occupant monitoring systems allows for dynamic adjustment based on occupant posture and size, optimizing headrest position for maximum effectiveness in a collision.
- Expansion into Emerging Auto Markets:As safety standards rise in markets like India and Brazil, introducing cost-optimized active headrest variants offers a pathway to capture new volume and establish an early market presence.
Industry Challenges
- Software and Electrical Integration:Ensuring seamless compatibility of active headrest control modules with diverse and often proprietary vehicle electrical architectures and software platforms from multiple OEMs is a major engineering hurdle.
- Multi-Jurisdictional Certification:Suppliers face long and costly certification processes to comply with varying safety standards and validation requirements across different regulatory domains, such as the NHTSA in the US and national authorities in Europe.
- OEM Cost-Down Pressure:Automotive OEMs exert continuous pressure on suppliers to reduce the per-unit cost of active systems, forcing manufacturers to innovate on materials and production processes to protect margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Seat Headrests Market |
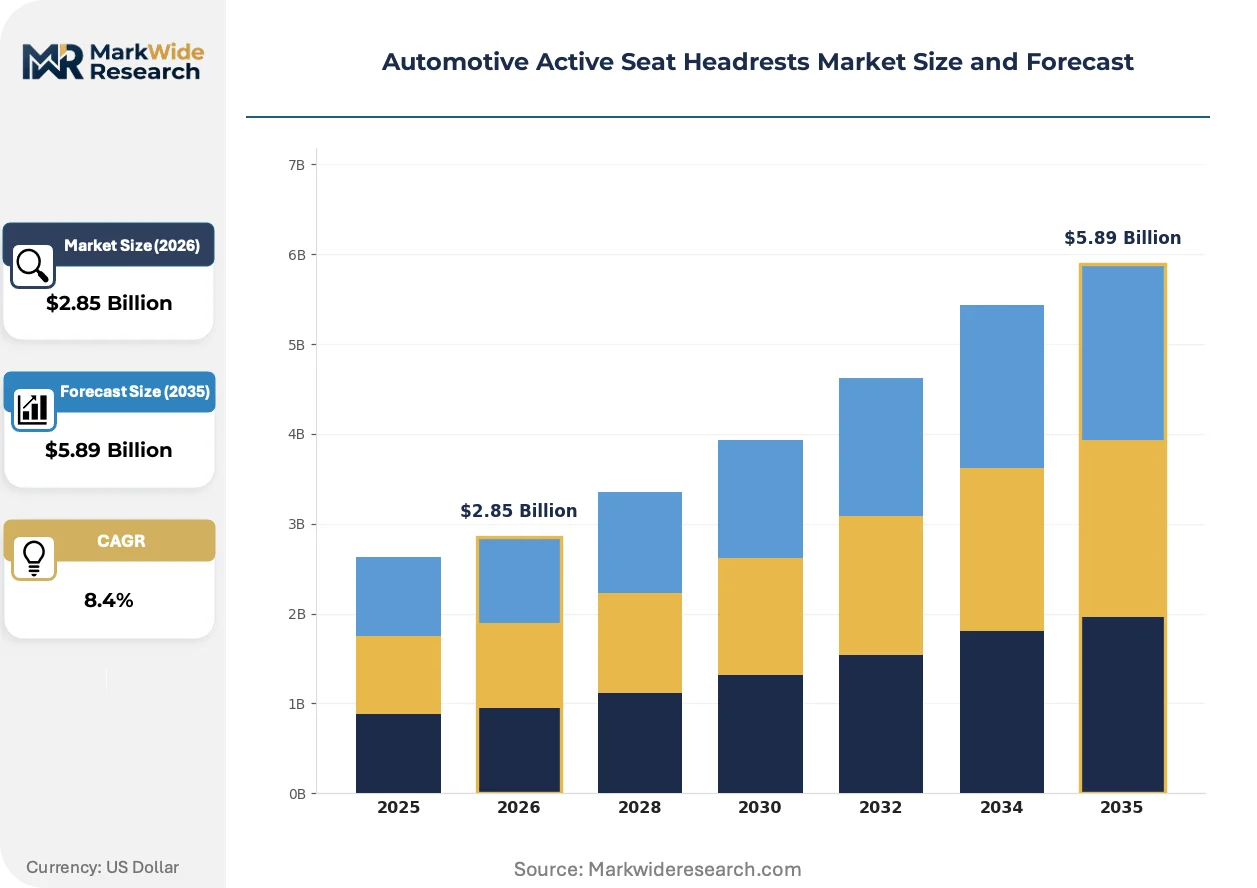
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Energy-Absorbing, Mechanical, Electronic, Airbag-Integrated Technology: Hydraulic, Electromechanical, Pneumatic, Magnetic Application: Passenger Cars, Commercial Vehicles, Off-Road Vehicles, Specialty Vehicles End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Toyota Boshoku Corporation, Yanfeng Automotive Interior Systems Co. Ltd, Grammer AG, JR Manufacturing Inc, Magna International Inc, Lear Corporation, TS Tech Co. Ltd, Shanghai Daimay Automotive Interior Co. Ltd, Adient Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Seat Headrests Market Strategic Shifts & Innovations
The evolution of the active seat headrest is defined by its transformation into an intelligent, data-driven node within the vehicle's overall safety ecosystem. This shift prioritizes preemptive action and system integration over purely reactive mechanical responses, fundamentally altering design and technology choices.
Electromechanical actuators, which utilize small, precise electric motors and gearsets to position the headrest, are a key product evolution. Luxury and premium passenger car segments are adopting these systems for their testability and reset capabilities following deployment. This reliability and reusability is supplanting older, single-use pyrotechnic and less precise mechanical systems in new vehicle designs.
Regulatory frameworks are a primary catalyst for innovation, particularly Euro NCAP's rear impact testing protocols. These standards directly reward technologies that can prove a significant reduction in the forces that cause whiplash injuries. As a result, European automakers are increasingly specifying advanced active headrests as standard equipment on new platforms to secure coveted five-star safety ratings.
A notable behavioral shift is the unbundling of advanced safety features from exclusive top-tier trim packages. Automakers are now offering active safety systems, including active headrests, as standalone options or in dedicated safety packages on mid-range models. This trend is most prominent in the competitive North American market, where consumers increasingly prioritize and shop for specific safety technologies.
Automotive Active Seat Headrests Market Segmentation
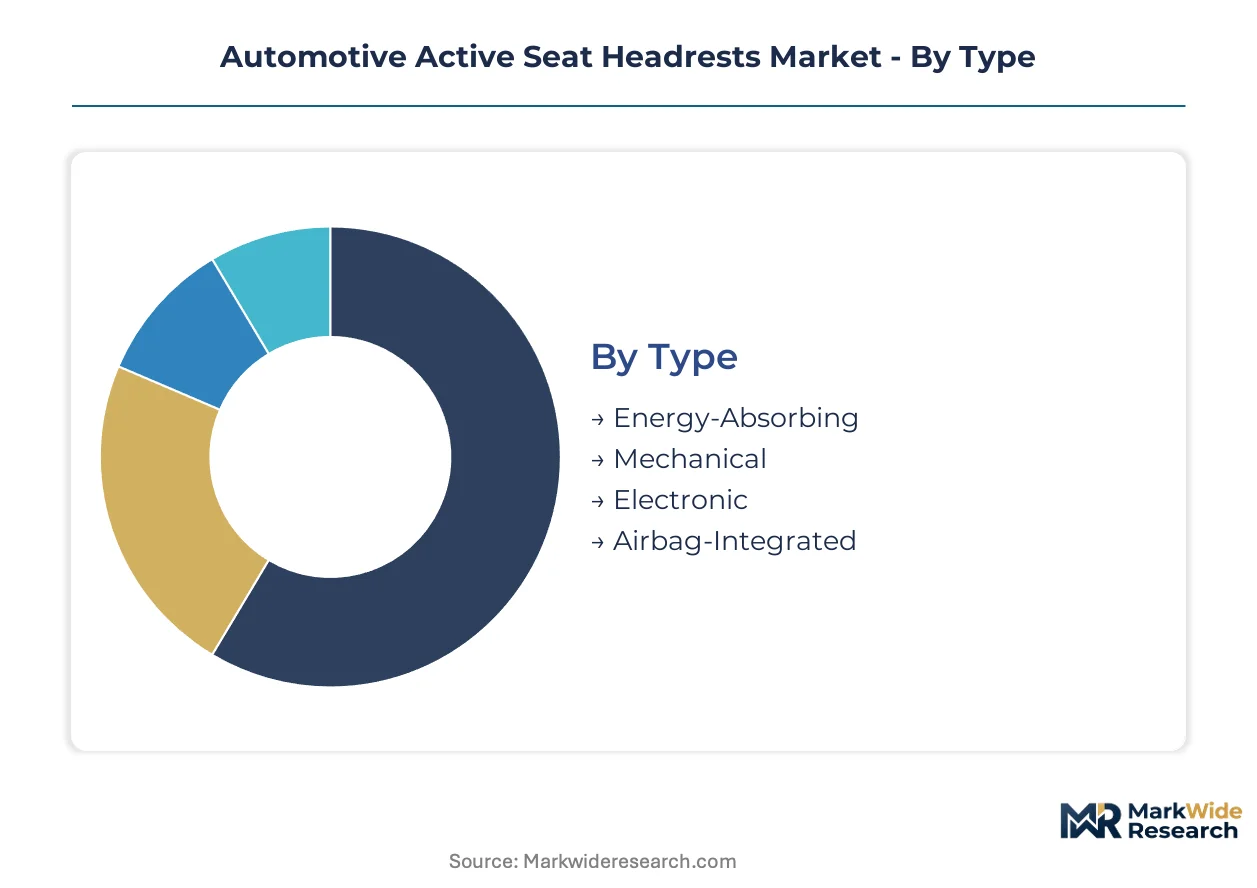
The Automotive Active Seat Headrests market segmentation provides a granular view of product types, underlying technologies, diverse applications, and key end-user groups. This detailed breakdown helps identify specific demand drivers and distinct competitive dynamics across the industry. Regulatory mandates and technological advancements influence adoption patterns within each segment.
Type:
The market's "Type" segmentation highlights how different headrest designs are channeled through various vehicle platforms and sales models, influencing their availability to end consumers.
- Energy-Absorbing:These headrests are engineered with internal structures or materials designed to deform upon impact, dissipating crash energy to reduce whiplash severity. Demand is strong in European luxury sedans, driven by Euro NCAP's stringent whiplash assessment protocols.
- Electronic:Electronic active headrests use sensors and actuators to automatically position the headrest during a rear-end collision, optimizing occupant protection. Their adoption is concentrating in premium passenger cars in Germany, spurred by OEM focus on advanced safety features.
- Mechanical:Mechanical headrests rely on kinetic energy from the occupant's body during a rear-end impact to deploy forward, offering a cost-effective safety solution.
- Airbag-Integrated:These systems combine an active headrest with a small airbag, deploying simultaneously to further cushion the occupant's head and neck.
Electronic systems dominate the installed base in new vehicle platforms. Airbag-integrated solutions are where expansion concentrates for enhanced protection.
Technology:
The "Technology" segment reflects the varying cost tiers and performance capabilities integrated into active headrest systems, impacting their suitability for different vehicle classes.
- Electromechanical:These systems employ electric motors and gearsets for precise, reversible headrest positioning, offering high reliability and advanced diagnostic capabilities. New passenger car applications in Japan increasingly favor electromechanical solutions due to their fast response times and reusability.
- Hydraulic:Hydraulic active headrests use fluid pressure to move the headrest, providing smooth and controlled deployment, often found in specialized high-performance vehicle applications. Their integration into commercial vehicles is gaining traction as safety requirements stiffen.
- Pneumatic:Pneumatic systems utilize compressed air to actuate headrest movement, offering a lightweight and compact design for certain vehicle models.
- Magnetic:Magnetic active headrests leverage electromagnetic forces for rapid deployment, though their complexity can limit broader application outside niche segments.
Performance differentiation drives adoption in this segment, with electromechanical solutions leading in advanced applications and pneumatic systems offering a cost-effective alternative.
Application:
The "Application" segment reveals how active headrest designs are tailored to meet the specific operational requirements and occupant protection needs of different vehicle types.
- Passenger Cars:This segment includes sedans, SUVs, and hatchbacks, where active headrests are increasingly standard, particularly in luxury and mid-range models. Demand is concentrated in the United States, influenced by consumer preference for comprehensive safety packages.
- Commercial Vehicles:This category covers light and heavy trucks, buses, and vans, requiring robust and durable active headrests to withstand varied operating conditions. Growth in this segment is a strategic opportunity, especially in Europe, driven by evolving fleet safety regulations.
- Off-Road Vehicles:Active headrests for off-road vehicles must endure extreme vibrations and impacts, focusing on occupant retention and injury mitigation in rugged environments.
- Specialty Vehicles:This segment includes emergency vehicles, armored cars, and custom builds, where headrests are often customized for specific protection or ergonomic needs.
The diverse operational environments of these applications necessitate tailored headrest designs, with passenger cars demanding high-volume solutions and commercial vehicles requiring robust, durable systems.
End User:
The "End User" segmentation illustrates distinct procurement models and integration strategies for active headrest systems across the automotive value chain, impacting market access and sales channels.
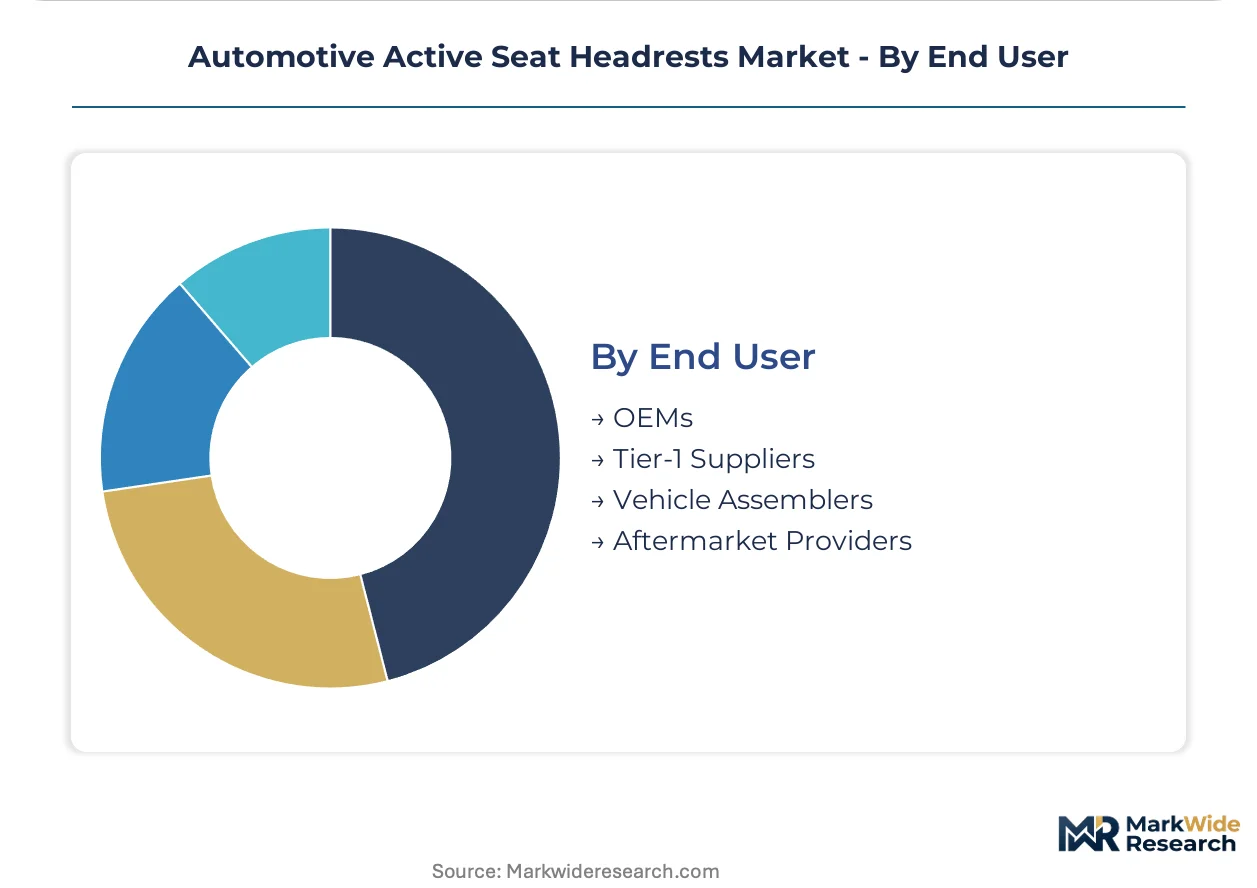
- OEMs:Original Equipment Manufacturers integrate active headrests directly into vehicle platforms during the initial design and manufacturing phases, often working closely with Tier-1 suppliers. German automakers are increasingly specifying these systems as standard equipment to achieve top safety ratings.
- Aftermarket Providers:These entities supply active headrest solutions for installation in vehicles after their initial sale, catering to consumers seeking upgrades or replacements. The US aftermarket for safety enhancements provides a steady demand for these components.
- Tier-1 Suppliers:Tier-1 suppliers design, develop, and manufacture complete active headrest systems for OEMs, acting as critical intermediaries in the supply chain.
- Vehicle Assemblers:Vehicle assemblers integrate pre-manufactured active headrest units into the final vehicle structure, focusing on efficient installation and quality control.
Procurement models vary significantly across these end users, with OEMs driving early design integration and aftermarket providers focusing on retrofit solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive components from Germany often flow into global assembly lines, highlighting the interconnectedness of the industry. The market for active seat headrests demonstrates diverse regional adoption patterns shaped by local regulations and consumer preferences. Demand concentration in key automotive production hubs influences technological advancements and market growth.
Germany
Luxury passenger car manufacturers in Germany drive significant demand for advanced active headrests. Euro NCAP's stringent whiplash assessment protocols directly incentivize the adoption of these safety systems. The KBA (Kraftfahrt-Bundesamt) mandates rigorous testing for vehicle safety components. Stuttgart's automotive industry cluster actively integrates sophisticated active headrest technologies into new vehicle designs.
Japan
New passenger car applications in Japan increasingly favor electromechanical solutions for active headrests. These systems offer fast response times and enhanced reusability, meeting consumer expectations for advanced safety. Japanese Industrial Standards (JIS) influence the design and performance requirements for automotive safety features. Nagoya's prominent automotive manufacturing belt sees high adoption of integrated active safety components.
United States
Consumer preference for comprehensive safety packages concentrates demand for active headrests in the United States. Automakers offer these features as standalone options or within dedicated safety bundles. The National Highway Traffic Safety Administration (NHTSA) issues safety mandates that push for continuous improvement in whiplash protection. Detroit's traditional automotive hub remains a focal point for integrating and testing advanced occupant safety systems.
China
China's rapidly expanding automotive market and rising safety standards contribute to the growing adoption of active seat headrests. Local manufacturers are increasingly incorporating advanced safety features to meet consumer expectations. Chinese GB standards for automotive safety components influence product specifications and market entry. Shanghai's automotive manufacturing base is a significant center for the production and integration of these systems.
India
Safety standards are rising in India, creating a pathway for cost-optimized active headrest variants. This market presents a strategic opportunity for manufacturers to establish an early presence. The Bureau of Indian Standards (BIS) develops vehicle safety norms that encourage the use of advanced occupant protection. Chennai's automotive industry cluster is exploring greater integration of active safety technologies in new vehicle platforms.
Automotive Active Seat Headrests Market Key Industry Players
Player mix skews toward established Tier-1 suppliers and vertically integrated automotive interior specialists. The market structure exhibits a tiered approach, with a few large players dominating the premium segment and numerous smaller entities serving niche or aftermarket needs. Strategic partnerships with OEMs and continuous portfolio diversification represent dominant competitive moves.
Within the established Tier-1 supplier segment, Lear Corporation leverages its deep relationships with global automakers to embed safety features early in the design phase. Magna International Inc. competes through its broad portfolio of seating and interior systems, offering integrated solutions to a wide customer base. Grammer AG occupies a specialized position, focusing on commercial vehicle applications where durability and specific occupant safety requirements are paramount.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Yanfeng Automotive Interior Systems Co. Ltd |
| Grammer AG |
| JR Manufacturing Inc |
| Magna International Inc |
| Lear Corporation |
| TS Tech Co. Ltd |
| Shanghai Daimay Automotive Interior Co. Ltd |
| Adient Plc |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for critical semiconductor components directly influences the pricing power of active headrest manufacturers, reflecting global supply chain vulnerabilities. This dynamic pushes OEMs to secure long-term contracts, stabilizing component costs.
Pricing Analysis
The technology-generation pricing gap shows sophisticated electromechanical systems commanding a premium over older mechanical designs. Per-unit transactional pricing dominates the market, reflecting direct component sales to OEMs. Price differentiation stems from certification level, particularly for Euro NCAP compliance, and the volume scale of OEM orders. Pricing pressure stems from continuous OEM cost-down mandates, especially in mid-range vehicle segments. Economy vehicle models remain highly price-sensitive, while luxury passenger cars show lower sensitivity to advanced safety feature costs.
Supply Chain Analysis
Port congestion in key Asian manufacturing hubs creates inbound logistics challenges for active headrest components. Geographic supply concentration centers on Germany, Japan, and China for complex electromechanical assemblies. Raw material dependencies include specialized accelerometers, microcontrollers, and high-strength plastics. Single-source vulnerability for advanced sensors represents a structural risk. Distribution runs through a direct-to-OEM model, with Tier-1 suppliers delivering integrated systems to vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption, driven by stringent regulatory mandates and the integration of ADAS technologies. The shift from passive to active safety systems is fundamentally reshaping vehicle design.
For Market Incumbents:Consolidate market share by deepening relationships with global automakers, embedding active headrest features early in the design phase. Invest in R&D for next-generation electromechanical systems to counter emerging threats from new sensor technologies. Expand capacity in key automotive production hubs like Germany to maintain localized supply. Pursue strategic partnerships with semiconductor suppliers to mitigate component supply bottlenecks.
For New Entrants and Emerging Players:A service-layer gap exists in providing cost-optimized active headrest variants for emerging markets like India and Brazil. Target the commercial vehicle segment, which remains underserved by advanced safety features, as a white-space opportunity. Focus on modular, easily integrable solutions for smaller OEMs. A go-to-market angle involves demonstrating clear ROI through enhanced fleet safety and reduced insurance premiums.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified automotive interior specialists seeking to streamline their portfolios. The long-term viability of this market is strong, driven by persistent regulatory pressure for occupant safety. Seek out specialized Tier-1 suppliers with proprietary electromechanical actuator technology. A signal to watch is the increasing standardization of active headrests across mid-range vehicle platforms, indicating broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical R&D Investment | Advances precise headrest positioning and reusability for luxury vehicle platforms. |
| Commercial Vehicle Market Entry | Addresses unique durability requirements in a largely untapped segment in Europe. |
| Strategic Semiconductor Sourcing | Mitigates supply chain risks for critical electronic components from Asian suppliers. |
| OEM Design Phase Integration | Ensures early adoption of active safety features into new vehicle platforms. |
| Cost-Optimized Variant Development | Unlocks new volume opportunities in price-sensitive emerging automotive markets. |
Research Approach
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, and automotive safety regulators converged on the working assumptions for this analysis. This involved combining primary interviews with extensive secondary validation. Key secondary sources included Euro NCAP crash test reports, NHTSA safety mandates, and national automotive production data from Germany and Japan. Bottom-up and top-down triangulation ensured data consistency.
The segmentation dimensions modeled include product type, underlying technology, diverse applications, and key end-user groups, along with regional regulatory clusters. The analytical framework projects market growth across the analysis window by correlating historical adoption rates with evolving safety standards. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth drivers. Industry-specific forecast inputs include vehicle production forecasts and regulatory compliance timelines.
Underlying assumptions cover current regulatory trajectories and technological development, with deviation risk concentrated in unforeseen macroeconomic shifts or rapid material science breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Emblem Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Pedals Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Spark Plug Market
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Brackets Market