
 China Automotive Composites Market | 2026-2036
China Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Composites Market Outlook
China's dual carbon goals are recalibrating the cost-of-entry calculus for automotive composites manufacturers, forcing carbon-intensive suppliers to retool or exit. Toray Industries leverages its PAN-based carbon fiber precursor technology to sustain premium positioning in structural applications. HENGRUI CORPORATION anchors domestic supply security through backward integration into raw fiber production. Kingfa Sci & Tech competes on thermoplastic compound scale, serving cost-sensitive interior programs for local OEMs.
Automotive composites encompass fiber-reinforced polymer matrices—typically carbon, glass, or aramid fibers embedded in epoxy, polypropylene, or polyamide resins—engineered to achieve strength-to-weight ratios exceeding steel at 60-70% lower mass. These materials primarily enable vehicle lightweighting to extend electric range and reduce fuel consumption. Thermoplastic composites lead volume adoption due to recyclability and cycle time advantages in injection molding, while thermosetting composites dominate structural parts where elevated temperature performance commands margin premiums. Reinforced glass fiber compounds occupy the high-volume interior and exterior panel segments, whereas nanocomposite formulations remain confined to specialized electrical component shielding applications.
MIIT enforces GB standards for passenger vehicle corporate average fuel consumption that directly mandate lightweight material penetration rates. SAMR oversees quality certification protocols that shape product liability exposure for Tier-1 suppliers selecting composite grades. The country's national environmental regulator implements dual carbon compliance timelines that compress decision windows for resin system transitions. Stakeholders must monitor regulatory threshold adjustments for recycled content mandates and polymer carbon footprint disclosure requirements that will determine qualification status in domestic OEM procurement frameworks.
Market Dynamics
Electric vehicle battery enclosure specifications are rewriting material qualification protocols across China's automotive supply base, compressing development cycles from 36 months to 18 months for composite structural components.
Growth Catalysts
- MIIT Corporate Average Fuel Consumption mandates:GB standards enforce escalating lightweight material penetration thresholds that OEMs must meet through composite-intensive platform redesigns.
- Shanghai-Ningbo manufacturing corridor concentration:The Yangtze River Delta cluster aggregates 60% of domestic composite Tier-1 capacity, slashing logistics costs for just-in-sequence battery tray delivery.
- Thermoplastic recycling infrastructure maturation:Pyrolysis and solvolysis lines at Kingfa and Hengli enable closed-loop polypropylene recovery, satisfying emerging dual carbon audit requirements.
Market Restraints
- Acrylonitrile price volatility:PAN precursor costs swing 15-25% quarterly, eroding margin stability for carbon fiber laminates in premium EV programs.
- Import dependency for aerospace-grade epoxy systems:70% of high-Tg resin supply concentrates in Japanese and German chemical conglomerates, exposing structural component makers to forex and tariff risk.
- Thermoset cure cycle inflexibility:45-minute autoclave processing limits throughput versus steel stamping, constraining adoption in high-volume A-segment vehicles.
Strategic Opportunities
- Western China EV battery hub expansion:Chengdu-Chongqing corridor OEMs lack qualified local composite suppliers, creating first-mover advantage for qualified entrants with MEE environmental clearance.
- SAMR recycled content mandates:Pending disclosure rules for polymer carbon footprint will disqualify virgin-only suppliers, advantaging compounders with certified post-industrial feedstock streams.
- Multi-material joining technology convergence:Laser-assisted tape placement hybridized with in-situ polymerization enables steel-composite hybrid battery enclosures, opening structural applications previously closed to monolithic designs.
Industry Challenges
- Autoclave operator skill scarcity:Cure cycle optimization requires 5,000+ hour apprenticeship pipelines that vocational programs have failed to scale.
- SAMR GB/T certification timelines:New composite grades face 14-18 month homologation queues, misaligning with 24-month vehicle platform development windows.
- Legacy ERP integration friction:Composite batch traceability systems clash with OEM SAP environments, forcing redundant quality documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Composites Market |
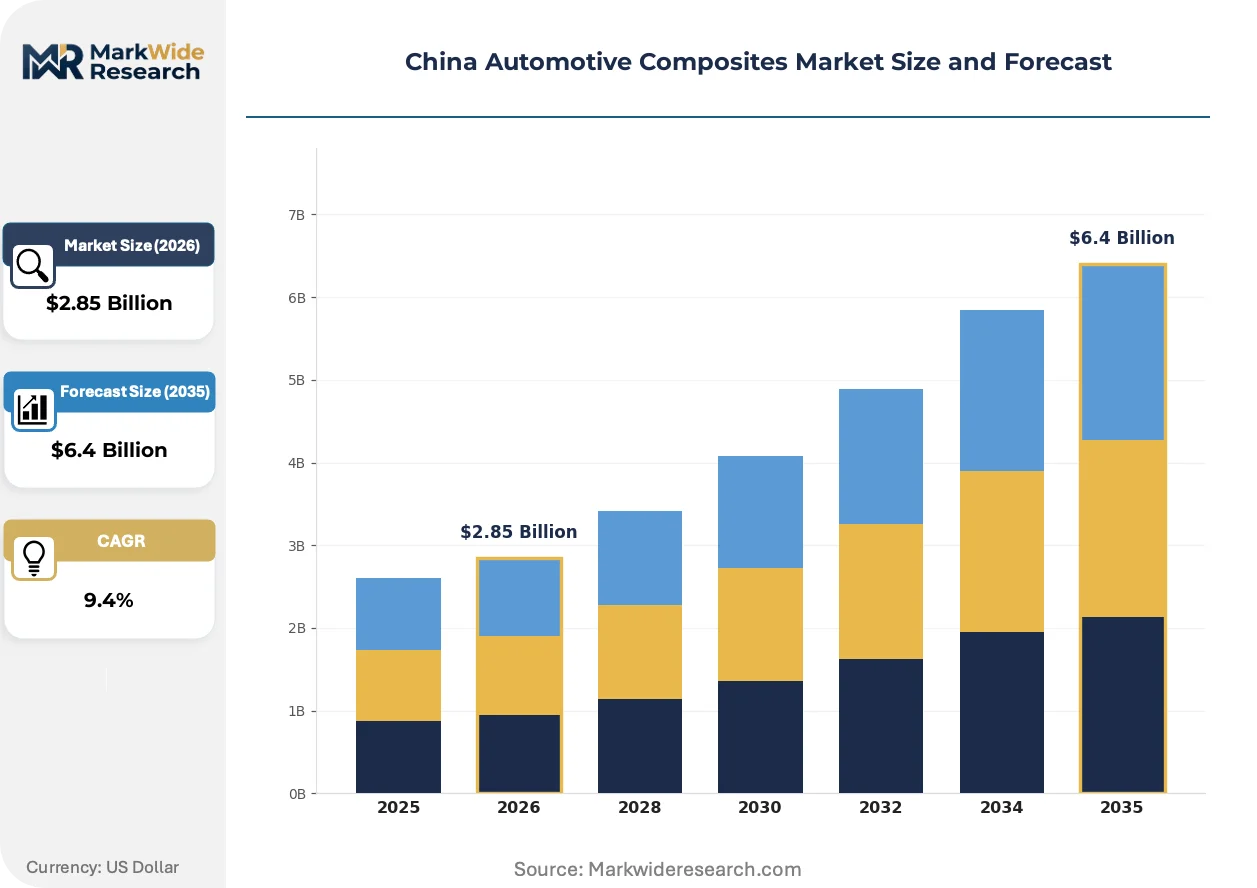
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.4 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Composites, Thermosetting Composites, Reinforced Composites, Nanocomposites Application: Interior Components, Exterior Body Panels, Structural Parts, Electrical Components End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Compression Molding, Vacuum Infusion, Filament Winding |
| Companies Covered | Toray Industries, Inc., Teijin Limited, Mitsubishi Chemical Corporation, SGL Carbon SE, Hexcel Corporation, BASF SE, HENGRUI CORPORATION (HRC), Kingfa Sci & Tech, Jiuding New Material Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Composites Market Strategic Shifts
Automotive composite manufacturing is bifurcating into two velocity tiers: thermoplastic injection molding for interior scale and thermoset autoclave processing for structural performance premiums.
Continuous fiber-reinforced thermoplastic (CFRTP) tape technology is consolidating position in battery enclosure manufacturing. BYD and NIO have qualified unidirectional polyamide tapes for lower pack structures, displacing aluminum extrusions at 40% mass reduction. The technology is consolidating supplier power among compounders with in-house prepreg lines, compressing toll-converter margins to single digits.
MIIT's 2024 draft GB standard for vehicle lifecycle carbon accounting imposes upstream resin disclosure obligations on Tier-1 suppliers. Compounders must now document Scope 3 emissions from acrylonitrile production through finished component delivery. Battery enclosure programs face the steepest compliance burden, as epoxy and polyamide systems carry 3-5x the cradle-to-gate carbon intensity of steel equivalents.
Geographic procurement concentration around Shanghai is fragmenting as CATL and BYD expand cell production to Sichuan and Shaanxi. Interior panel suppliers in Jiangsu face freight cost penalties exceeding 8% for western delivery routes. Qualified compounders are establishing satellite compounding operations in Chengdu suburbs to defend position against local entrants with MEE environmental permits.
China Automotive Composites Market Segmentation
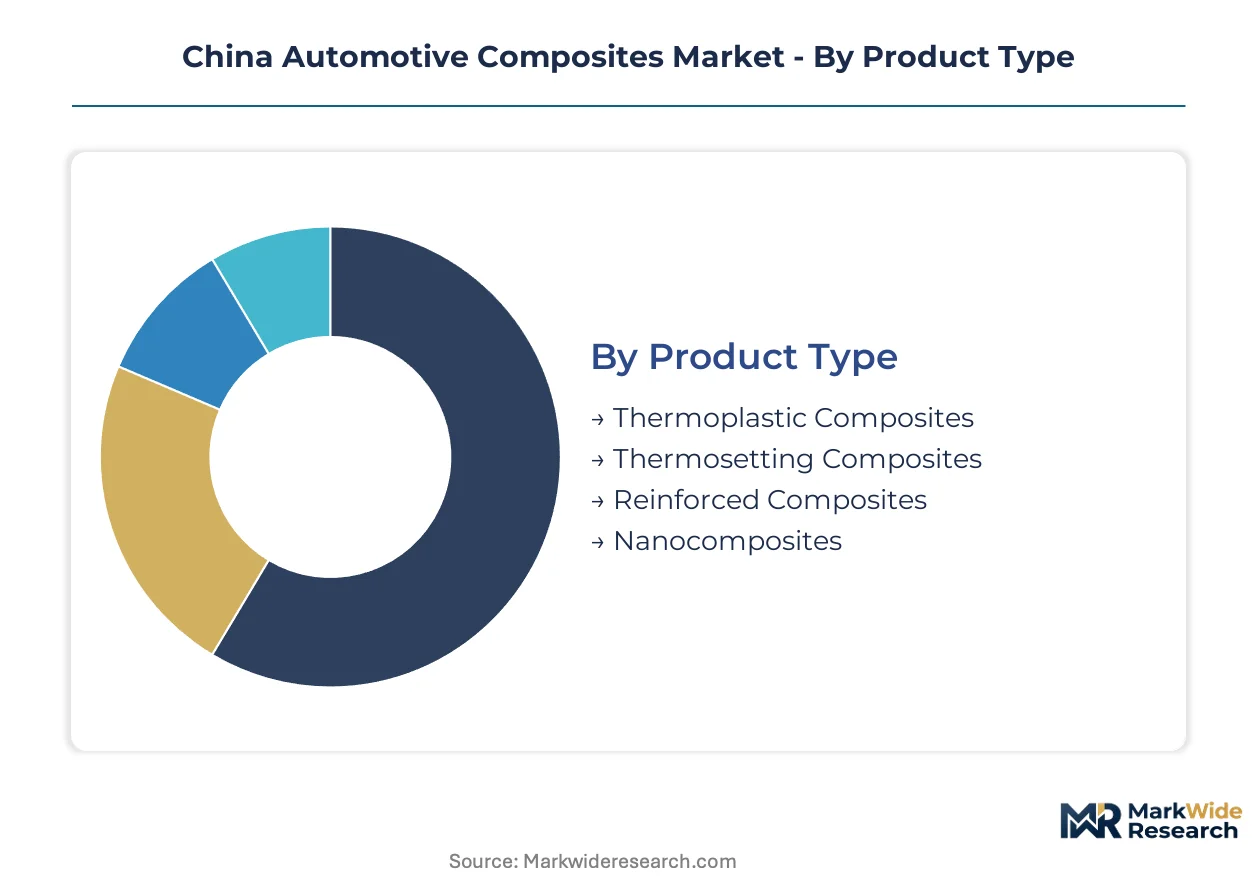
Composite material selection in China's automotive sector follows divergent logic across cost tiers and performance requirements. Segmentation reveals where thermoplastic scale economies dominate versus where thermoset premiums command margin capture.
Product Type:
Thermoplastic composites anchor high-volume production through injection molding recyclability, while thermosetting variants capture structural premiums in battery enclosures.
- Thermoplastic Composites:Polypropylene and polyamide matrices reinforced with chopped glass fiber enable sub-60-second cycle times in interior panel production. Yangtze River Delta OEMs specify these compounds for door modules and instrument carriers where MIIT recyclability audits apply.
- Thermosetting Composites:Epoxy and vinyl ester systems cured via autoclave or resin transfer molding deliver elevated temperature resistance for battery enclosure structural members. BYD and NIO qualification protocols favor carbon fiber laminates in lower pack structures despite 45-minute processing cycles.
- Reinforced Composites:Continuous glass fiber rovings in sheet molding compound formulations serve exterior body panels where Class A surface finish requirements intersect with 30% mass reduction targets.
- Nanocomposites:Clay and carbon nanotube dispersions in polymer matrices provide electromagnetic shielding for high-voltage electrical housings in premium EV architectures.
Mature deployment sits with thermoplastic compounds in interior applications. Newer deployment is concentrated in thermosetting structural components for battery integration.
Application:
Application segmentation tracks the migration of composites from cosmetic substitution to load-bearing primary structures.
- Interior Components:Door panels, seat structures, and cargo systems utilize short-fiber thermoplastic compounds for NVH dampening and 40% mass reduction versus steel substrates. Kingfa Sci & Tech compounds dominate this specification band.
- Exterior Body Panels:Fenders, hoods, and liftgates in sheet molding compound construction face surface quality constraints that limit adoption to low-volume premium platforms.
- Structural Parts:Battery enclosures, crash structures, and suspension links represent the steepest expansion trajectory as continuous fiber thermoplastic tapes displace aluminum extrusions at equivalent stiffness.
- Electrical Components:Connector housings and inverter enclosures leverage flame-retardant thermoplastic formulations meeting GB/T electrical safety standards.
Procurement volume clusters in interior specifications. Margin capture concentrates in structural battery applications.
End User:
End user segmentation reflects tiered technical capability and qualification authority across China's automotive supply chain.
- OEMs:BYD, NIO, and Geely maintain direct composite specification authority for battery enclosure platforms, bypassing traditional Tier-1 intermediaries in strategic lightweighting programs.
- Tier-1 Suppliers:Huayu Automotive Systems and Yanfeng Automotive Interiors compound and mold interior components under OEM brand requirements, absorbing SAMR certification liability.
- Aftermarket Providers:Cosmetic carbon fiber accessories for vehicle personalization operate outside MIIT homologation frameworks with limited volume scale.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-qualified composite modules from designated Tier-1 supply bases.
Specification control sits with OEMs in structural programs. Execution responsibility concentrates in Tier-1 suppliers for interior volume.
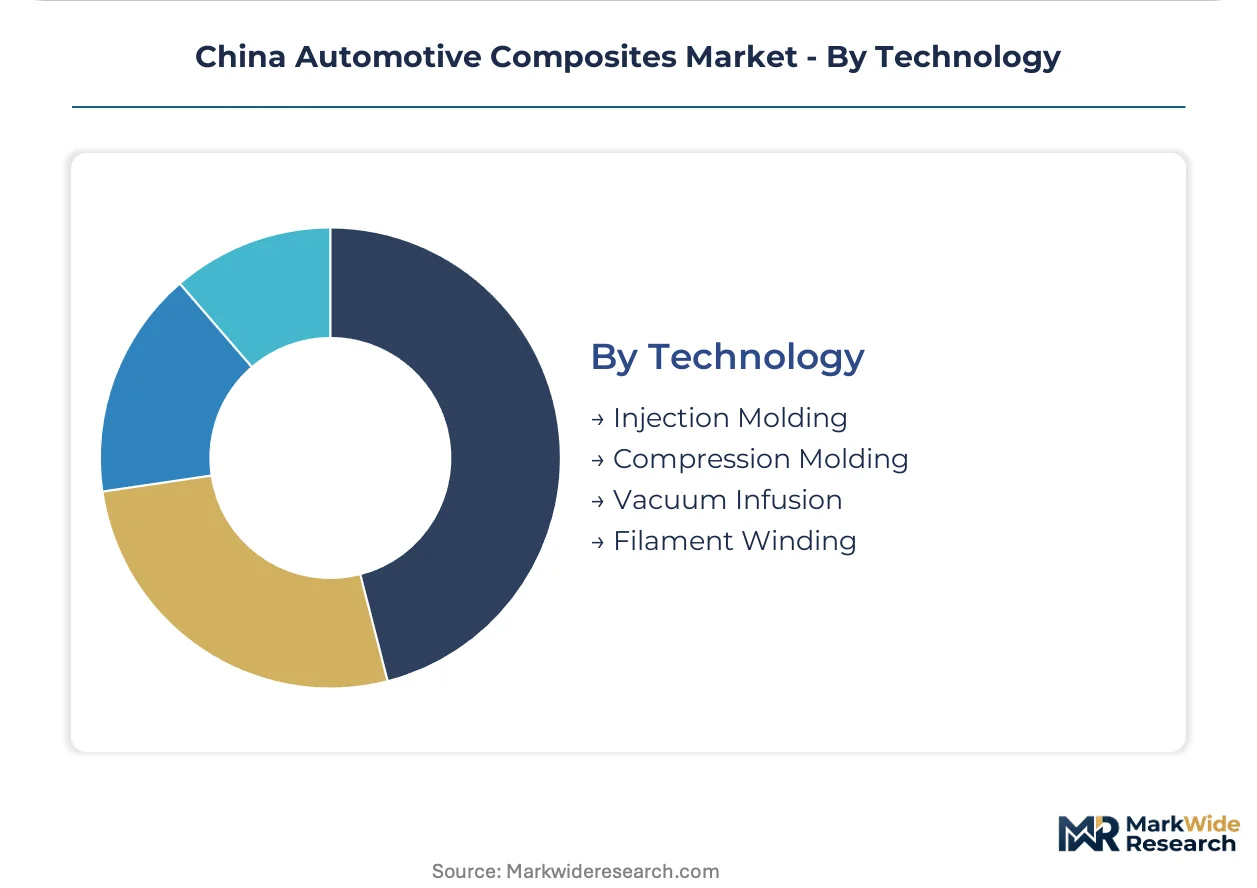
Technology:
Process technology selection determines throughput economics and geometric complexity limits.
- Injection Molding:High-pressure impregnation of short-fiber compounds achieves 90-second cycle times for interior brackets and housings, dominating Jiangsu manufacturing clusters.
- Compression Molding:Sheet molding compound and bulk molding compound processes serve exterior panels where fiber length preservation conflicts with flow requirements.
- Vacuum Infusion:Dry fiber preform impregnation under vacuum pressure enables large-format battery enclosure production with reduced void content versus resin transfer molding.
- Filament Winding:Automated fiber placement around mandrels produces pressure vessels and drive shafts with optimized fiber orientation for torsional loading.
Production maturity sits with injection molding. Capability expansion is concentrated in vacuum infusion for battery scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta Special Economic Zones concentrate 60% of China's automotive composite capacity, with tax incentives for advanced material R&D accelerating supplier clustering around Shanghai's battery manufacturing corridor.
Yangtze River Delta
BYD and NIO battery enclosure programs drive thermoset composite demand across Jiangsu and Zhejiang provinces. MIIT corporate average fuel consumption mandates enforce lightweight material quotas that OEMs meet through regional supplier partnerships. Shanghai's Pudong district hosts Toray Industries' carbon fiber precursor facility, serving structural component fabricators within 150-kilometer just-in-sequence radius.
Pearl River Delta
Guangdong province OEMs source interior thermoplastic compounds for electric vehicle platforms targeting Southeast Asian export markets. SAMR quality certification protocols require Tier-1 suppliers to maintain dual carbon audit documentation for polymer feedstock. Shenzhen's manufacturing corridor aggregates Kingfa Sci & Tech compounding operations, supplying flame-retardant formulations to BYD's local assembly plants.
Sichuan-Chongqing Corridor
CATL's western China cell expansion creates qualified supplier shortages for battery enclosure composite programs. MEE environmental clearance requirements filter new entrants seeking to serve Chengdu-based OEMs. Chongqing's Liangjiang New Area hosts emerging thermoplastic tape placement facilities, positioning for NIO and Xpeng western logistics hub requirements.
Beijing-Tianjin-Hebei
State-owned OEM lightweighting mandates prioritize domestic composite sourcing for official vehicle fleets. GB standards for recycled content disclosure shape procurement criteria for Tier-1 suppliers in the capital region. Tianjin's Binhai New Area concentrates epoxy resin import terminals, exposing structural component makers to yen-denominated feedstock volatility.
Shandong Peninsula
Industrial vehicle manufacturers in Qingdao specify glass fiber reinforced composites for commercial truck cabins. Provincial dual carbon implementation timelines compress decision windows for resin system transitions. Weihai's marine composite heritage translates into emerging automotive filament winding capability for hydrogen storage vessel integration.
China Automotive Composites Market Competitive Environment
Japanese and German producers anchor the premium carbon fiber tier; Chinese domestic specialists hold volume thermoplastic positions through backward integration into raw fiber production. Market structure bifurcates between consolidated global chemical conglomerates controlling high-Tg epoxy supply and fragmented local compounders competing on polypropylene cycle time economics. Three archetypes dominate: PAN precursor technology licensors, in-house prepreg line operators, and toll-converting molders serving cost-sensitive interior programs. Capacity expansion and strategic raw material partnerships constitute the dominant competitive moves across both tiers.
Within the domestic specialist tier, HENGRUI CORPORATION exemplifies backward-integrated supply security through captive carbon fiber production, while Kingfa Sci & Tech anchors thermoplastic compound scale for high-volume interior specifications. Toray Industries occupies a position representing premium PAN-based precursor technology sustained through structural application qualification protocols. These three entities collectively illustrate the geographic and technological segmentation defining competitive positioning in China's automotive composite supply base.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| SGL Carbon SE |
| Hexcel Corporation |
| BASF SE |
| HENGRUI CORPORATION (HRC) |
| Kingfa Sci & Tech |
| Jiuding New Material Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Acrylonitrile feedstock volatility cascades through PAN precursor pricing tiers, compressing margins for carbon fiber laminates serving premium EV battery enclosures while polypropylene compounders in the Yangtze River Delta exploit scale economies to defend position in cost-sensitive interior specifications.
Pricing Analysis
Short lead-time premiums command margin capture in thermoset structural components, where 45-minute autoclave cycles and SAMR GB/T certification queues create supply rigidity. Contract-based long-term offtake dominates carbon fiber laminates, with price differentiation hinging on MIIT compliance grade and volume scale. Cost compression in thermoplastic compounds intensifies because Kingfa and Hengli pyrolysis lines enable closed-loop recovery. Local OEMs exhibit highest price sensitivity in interior panel procurement, while NIO and BYD absorb premiums for qualified battery enclosure materials.
Supply Chain Analysis
MIIT domestic-content mandates for corporate average fuel consumption compliance reshape sourcing toward HENGRUI CORPORATION and Kingfa Sci & Tech captive fiber production. Raw material dependencies draw from Japanese and German high-Tg epoxy systems, Chinese PAN precursor facilities, and Korean acrylonitrile supply. Single-source vulnerability concentrates in aerospace-grade resin imports. Distribution runs through just-in-sequence Tier-1 hubs clustered within 150 kilometers of Shanghai-Ningbo battery manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's automotive composites sector sits in a technology-transition phase where continuous fiber-reinforced thermoplastic tapes displace aluminum extrusions in battery enclosures, compressing development cycles and rewiring supplier qualification protocols.
For Market Incumbents: Extend backward integration into raw fiber production to offset acrylonitrile price volatility eroding carbon fiber laminate margins. Establish satellite compounding operations in Chengdu suburbs before CATL and BYD western logistics hubs mature, defending position against local entrants with MEE environmental clearance.
For New Entrants and Emerging Players: Capture the Sichuan-Chongqing corridor battery enclosure specification gap where qualified composite suppliers remain scarce. Target western China OEM procurement frameworks lacking local thermoplastic tape placement capability, entering through MEE environmental permit acquisition and NIO supplier qualification partnerships.
For Investors and Strategic Acquirers: SAMR's pending recycled content disclosure rules are the leading indicator that certified post-industrial feedstock streams will determine Tier-1 qualification status. Over the projection horizon, compounders with closed-loop polypropylene recovery infrastructure represent priority acquisition targets. Watch MIIT GB standard threshold adjustments for recycled content mandates as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor Production | Captive acrylonitrile processing insulates HENGRUI CORPORATION from quarterly feedstock volatility swings. |
| Western China Satellite Compounding Expansion | Chengdu operations defend Jiangsu-based suppliers against freight cost penalties exceeding 8% for Sichuan delivery. |
| Closed-Loop Thermoplastic Recycling Infrastructure | Pyrolysis and solvolysis lines at Kingfa satisfy emerging dual carbon audit requirements for OEM procurement. |
| Multi-Material Joining Technology Investment | Laser-assisted tape placement enables steel-composite hybrid battery enclosures previously closed to monolithic designs. |
| SAMR GB/T Certification Pre-Positioning | Early homologation queue placement aligns composite grade approval with compressed 18-month EV platform development windows. |
Study Parameters
Independent corroboration across MIIT regulatory filings, SAMR quality certification databases, and Yangtze River Delta customs records underwrites the qualitative findings in this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, composite plant managers, and MEE environmental compliance officers combined with secondary validation from vehicle production databases, IHS Markit registration data, and SEC 10-K disclosures from multinational chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Comparable-period anchoring to historical MIIT corporate average fuel consumption mandate implementation phases structured the forecast framework. Segmentation dimensions modeled include product type, application, end user, and technology process across vehicle class, propulsion architecture, and regional production cluster. CAGRs derive from elasticity-adjusted penetration curves for composite-intensive platform redesigns, incorporating battery energy density improvement trajectories and dual carbon compliance timeline compressions as industry-specific forecast inputs.
The model holds under stable MIIT regulatory enforcement and acrylonitrile supply continuity; deviation in SAMR certification timeline acceleration or epoxy resin import restriction escalation would shift supplier qualification dynamics and regional capacity expansion priorities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Europe Automotive AHSS Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Gear Oil Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Automotive Bushing Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Global Automotive Composite Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Germany Automotive Carbon Fiber Composites Market