
 Global Automotive Bumpers Market | 2026-2036
Global Automotive Bumpers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Bumpers Market Analysis
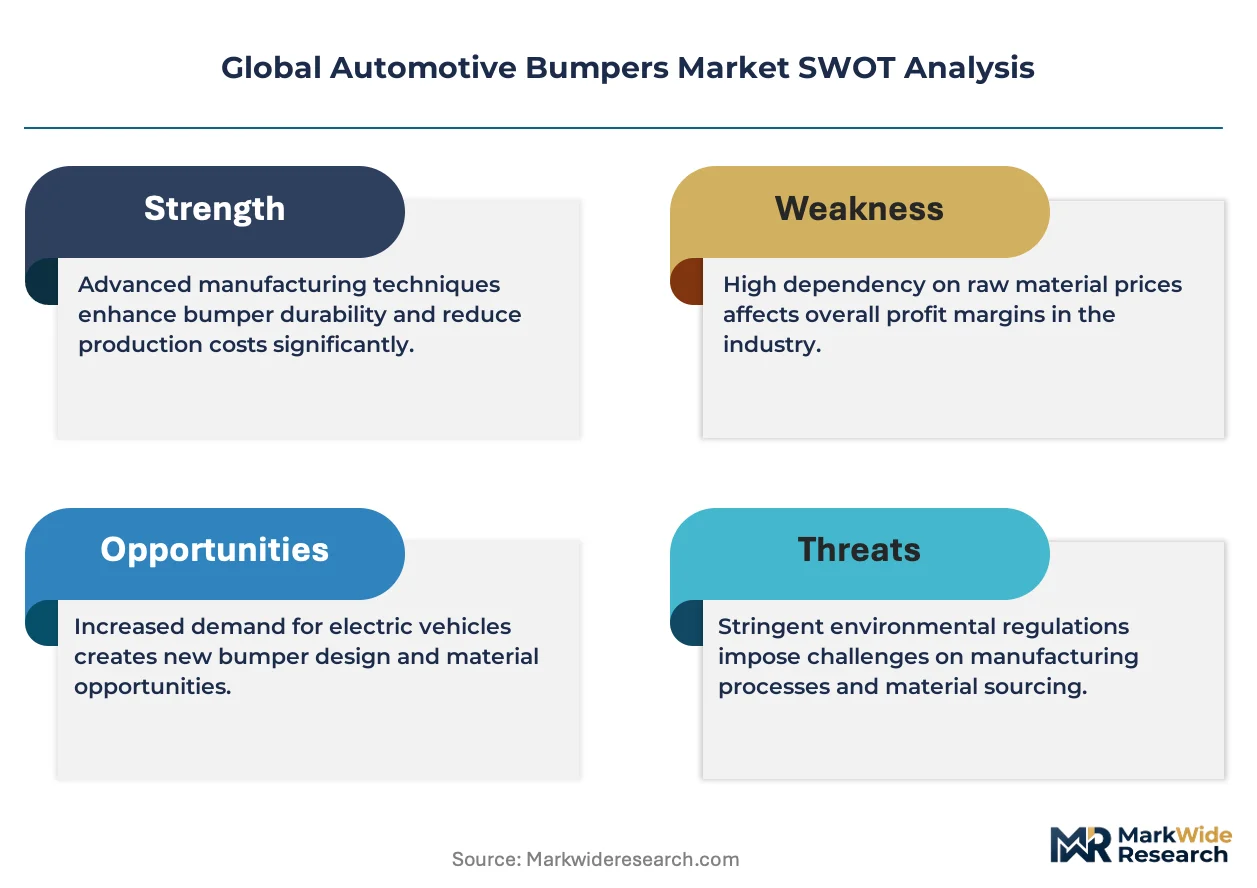
Europe's REACH chemical restrictions is rebalancing material cost structures across the supplier base, forcing compounders to certify alternatives to legacy additives. Plastic Omnium leverages its European molding footprint to sustain premium positioning in modular bumper systems. Faurecia anchors its competitive stance through vertical control over recycled polymer feedstocks. Tong Yang Group competes aggressively on injection-molding scale across Asian OEM contracts.
Automotive bumpers are energy-absorbing structural assemblies typically molded from polypropylene blends or stamped aluminum, designed to manage low-speed collision forces while integrating sensors, lighting, and aerodynamic surfaces. Front bumpers and rear bumpers remain the volume core, though modular bumpers command disproportionate margin pools by enabling OEMs to swap fascias and sensor carriers across trim levels without retooling main beams. Plastic dominates material throughput due to weight advantages, yet aluminum sustains share in premium SUVs and trucks where stiffness-to-mass ratios justify unit cost premiums.
The EPA in the United States enforces fleet fuel-economy standards that directly penalize bumper mass, while China's MIIT mandates dual carbon goals that restrict energy-intensive steel stamping. Japan's METI drives harmonization through JIS crash-test protocols that shape exportable product architectures. Stakeholders must monitor how pending revisions to pedestrian-impact regulations across these jurisdictions will alter crush-zone geometries and sensor-integration depths.
Market Dynamics
OEM platform consolidation toward modular electric vehicle architectures is compressing bumper development cycles while forcing suppliers to validate sensor-integrated assemblies under harmonized crash protocols across multiple jurisdictions.
Growth Catalysts
- MIIT dual carbon mandates:China's energy-intensity restrictions on steel stamping redirect investment toward recyclable thermoplastic molding capacity.
- Sensor integration density:LiDAR and radar module mounting requirements in front bumper beams expand addressable content per vehicle.
- Pedestrian safety directives:Europe's active hood and energy-absorbing fascia regulations mandate crush-zone redesigns that favor advanced polymer compounds.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer prices tied to naphtha cracking margins expose compounders to petrochemical cycle swings.
- Tooling concentration in East Asia:Large injection mold fabrication capacity clusters in China and South Korea create single-source risks for Western OEMs.
- REACH additive substitution:Legacy flame retardants and UV stabilizers face ECHA authorization sunsets, forcing reformulation costs without immediate performance parity.
Strategic Opportunities
- Closed-loop recycling infrastructure:EU Green Deal funding streams for automotive plastic recovery create first-mover advantages in post-industrial regrind certification.
- Modular bumper-to-fascia unbundling:Separate procurement of structural beams and aesthetic skins enables tier-2 suppliers to bypass integrated system incumbents.
- Software-defined vehicle alignment:Over-the-air calibration of integrated parking sensors positions bumper suppliers for recurring service revenue attachment.
Industry Challenges
- Multi-physics simulation talent scarcity:Combined crash, thermal, and electromagnetic modeling for sensor-embedded bumpers outpaces available CAE specialist supply.
- Homologation timeline compression:Simultaneous validation against NHTSA, ECE R42, and JIS pedestrian protocols strains testing facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Bumpers Market |
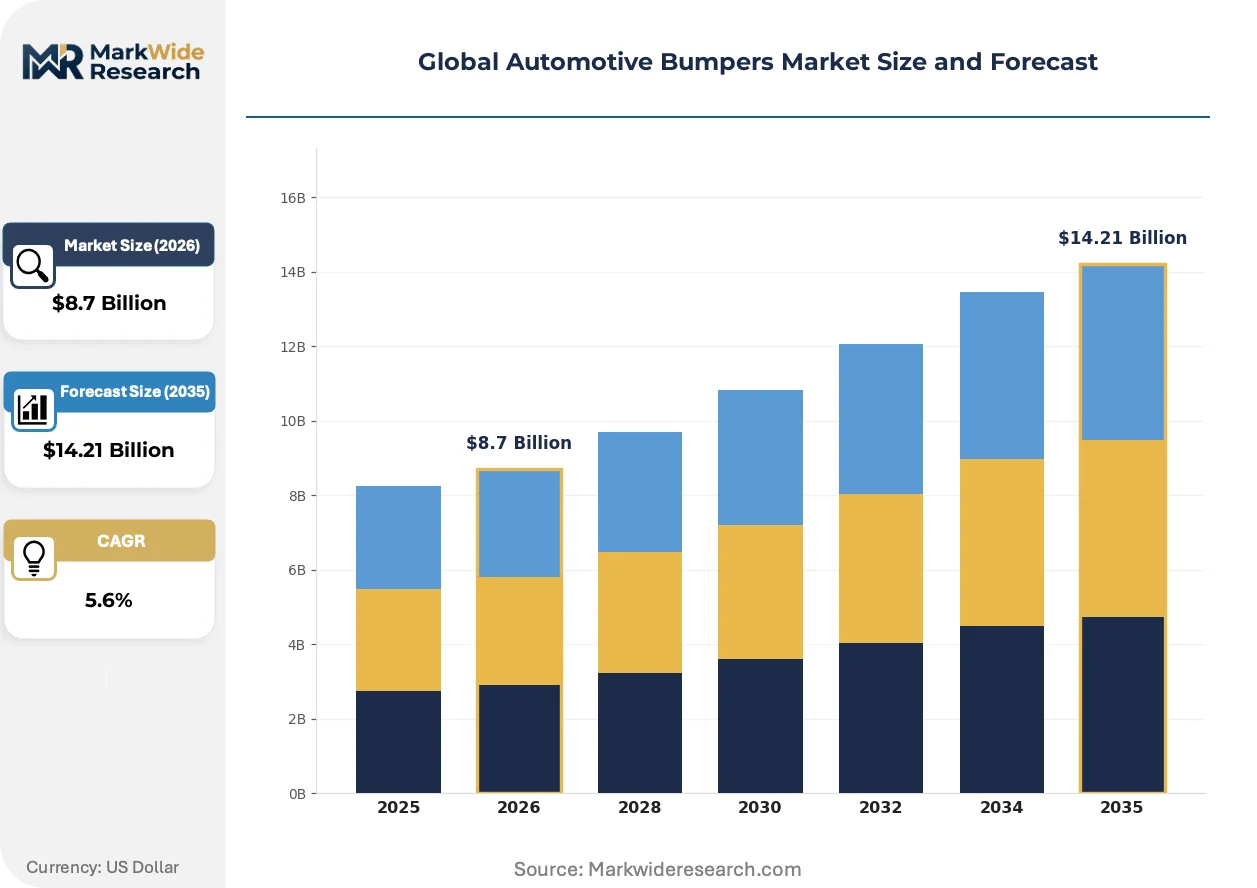
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Bumpers, Rear Bumpers, Modular Bumpers, Decorative Bumpers Material: Plastic, Aluminum, Steel, Composite Vehicle Type: SUVs, Sedans, Trucks, Hatchbacks Manufacturing Process: Injection Molding, Blow Molding, Extrusion, 3D Printing |
| Companies Covered | Toyoda Gosei, Faurecia, Plastic Omnium, Forvia SE, Flex-N-Gate Corporation, Hyundai Mobis, Tong Yang Group, SMP Deutschland GmbH, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Bumpers Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are converging to reshape how bumper systems absorb energy, integrate electronics, and satisfy end-of-life obligations across vehicle platforms.
Long-fiber thermoplastic (LFT) composites are displacing short-fiber polypropylene in main beam applications due to superior stiffness-to-impact resistance ratios. European premium OEMs specify LFT for modular carrier platforms that must accommodate varying sensor payloads across trim levels. This material transition is decentralizing molding capacity toward regional compounders capable of direct fiber impregnation, reducing reliance on centralized resin supply chains.
REACH chemical restrictions are accelerating substitution of halogenated flame retardants with phosphorus-nitrogen intumescent systems in bumper substrates. ECHA substance evaluation deadlines force compounders to recertify formulations ahead of 2027 sunset clauses. Asian export-oriented suppliers face disproportionate compliance burdens as European OEMs demand full material disclosure cascading to tier-3 feedstock sources.
Fleet procurement managers now specify outcome-based performance contracts for bumper systems, tying supplier payments to field warranty rates and sensor calibration accuracy rather than unit piece prices. This model compresses incumbent margins while rewarding predictive quality analytics capabilities. North American electric vehicle startups deploy this mechanism most aggressively to offset limited supplier track records.
Global Automotive Bumpers Market Segmentation
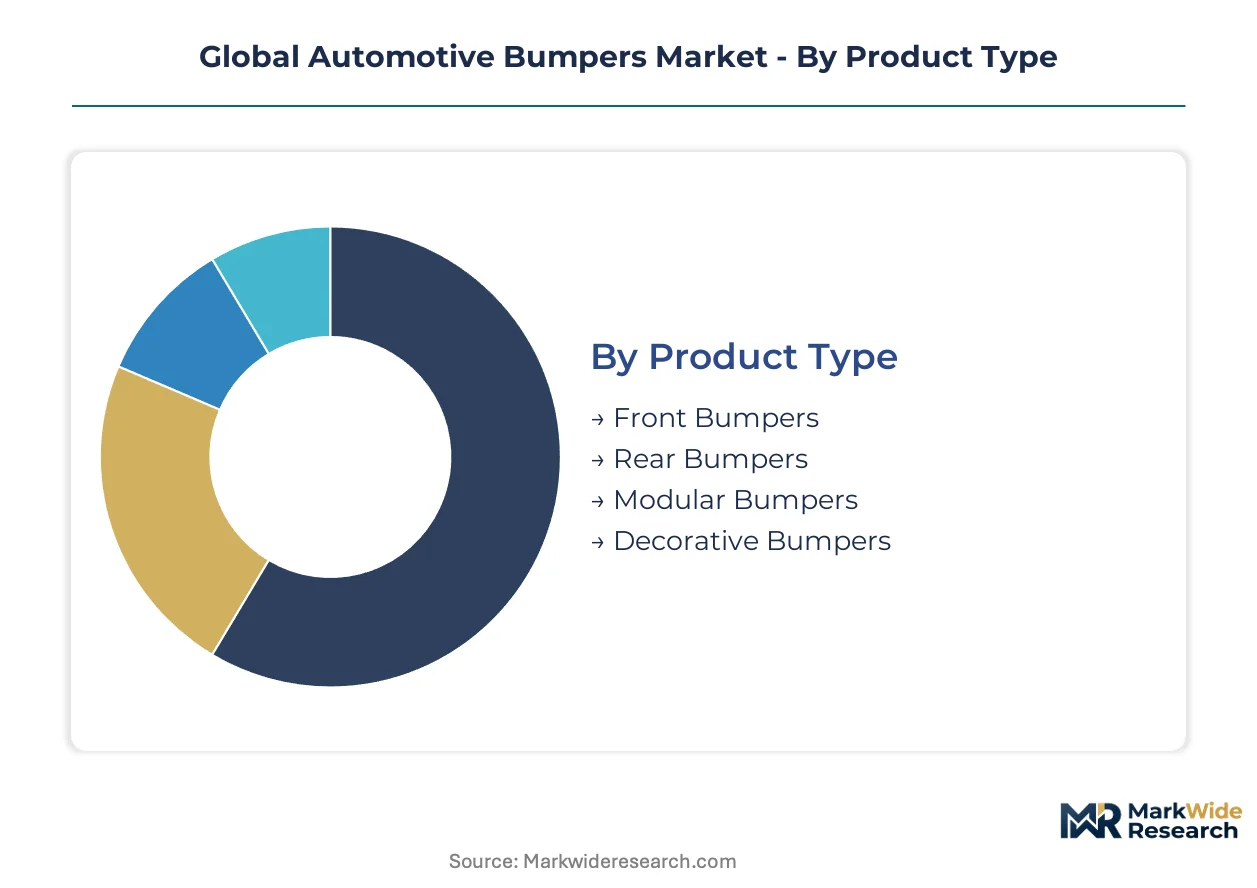
Automotive bumper segmentation reveals how capital deployment, regulatory compliance, and platform consolidation reshape supplier economics across distinct technical specifications. Understanding these divides exposes where tooling investments concentrate and where material substitution disrupts incumbent positioning.
Product Type:
Capital intensity varies sharply across bumper architectures, with sensor-integrated platforms demanding multimillion-dollar mold investments and validation cycles that modular designs amortize across multiple vehicle programs.
- Front Bumpers:Structural assemblies integrating crush cans, energy absorbers, and mounting brackets for advanced driver-assistance sensors. OEM procurement in Germany and the United States concentrates here due to pedestrian-impact regulations that mandate active hood actuation systems and deformable fascias, compressing development timelines.
- Modular Bumpers:Separable beam-and-skin architectures enabling trim-level variation without retooling. Chinese electric vehicle platforms deploy these most aggressively to accelerate mid-cycle refreshes while containing validation costs across export markets.
- Rear Bumpers:Lower sensor density reduces complexity, though parking-assist integration is climbing. Japanese OEM specifications dominate harmonized export designs.
- Decorative Bumpers:Non-structural fascia elements for aesthetic differentiation. Aftermarket channels in Brazil and India absorb significant volume.
Front bumpers absorb the bulk of installed capacity; modular bumpers are expanding most quickly.
Material:
Feedstock security and recycling infrastructure determine regional competitiveness, with compounders in jurisdictions lacking chemical recycling capacity facing compliance penalties under extended producer responsibility frameworks.
- Plastic:Polypropylene blends dominate through weight advantages and design flexibility. Long-fiber thermoplastic variants specified by European premium OEMs for modular carrier platforms require direct fiber impregnation capabilities that decentralize molding toward regional compounders.
- Aluminum:Stamped or cast alloys sustaining share in premium SUVs and heavy trucks where stiffness-to-mass ratios justify unit cost premiums. MIIT dual carbon mandates in China redirect some capacity toward recyclable thermoplastic alternatives.
- Steel:Legacy stamping for commercial vehicle applications facing energy-intensity restrictions. South Korean production clusters retain cost advantages through integrated mill supply.
- Composite:Carbon fiber or natural fiber reinforcements for low-volume performance vehicles. Italian and British specialist suppliers anchor this niche.
Plastic commands the deepest installed base; aluminum is gaining share fastest in electrified premium platforms.
Vehicle Type:
Platform scale economics favor high-volume segments where bumper-to-vehicle attachment standardization spreads mold costs across millions of units annually.
- SUVs:Higher ground clearance requirements and towing hardware integration expand bumper envelope dimensions. North American and Chinese OEMs drive specification diversity across compact, mid-size, and full-size architectures.
- Sedans:Aerodynamic optimization priorities compress bumper depth while expanding sensor integration density. European fleet CO2 regulations accelerate active grille shutter adoption within bumper assemblies.
- Trucks:Steel retention highest here due to payload and durability requirements. EPA fuel-economy penalties on bumper mass create tension with crash performance needs.
- Hatchbacks:Shorter rear overhangs and cost-sensitive positioning favor simplified injection-molded designs. Indian and Southeast Asian production volumes concentrate in this segment.
SUVs carry the heaviest tooling allocation; sedans are climbing fastest on electrification-driven platform consolidation.
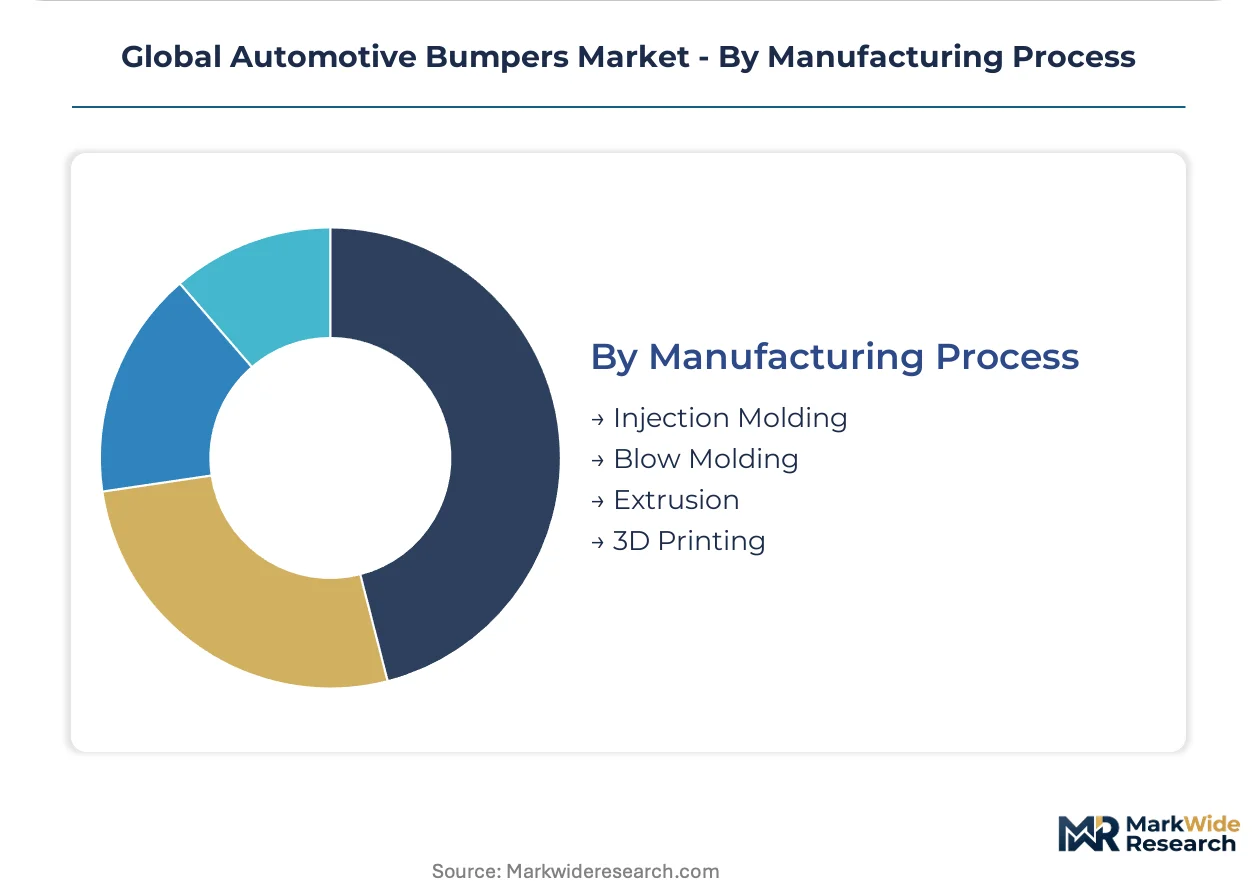
Manufacturing Process:
Process selection locks in cycle times, surface finish capabilities, and design freedom trade-offs that persist across entire vehicle program lifecycles.
- Injection Molding:Dominant for thermoplastic bumper beams and fascias, enabling complex geometries and integrated mounting features. Tong Yang Group and Plastic Omnium compete on scale across Asian and European OEM contracts respectively.
- Blow Molding:Hollow energy absorbers and ducts where weight reduction outweighs dimensional precision requirements. Limited to specific crush-can applications.
- Extrusion:Continuous profiles for bumper reinforcement bars and trim strips. Aluminum extrusion competes with roll-formed steel in select truck applications.
- 3D Printing:Prototyping and low-volume tooling inserts, with production applications emerging for aftermarket replacement components and motorsport customization.
Injection molding holds the deepest capital commitment; 3D printing is advancing fastest on digital inventory and mass-customization pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate bumper molding capacity for export-oriented electric vehicle platforms. MIIT dual carbon mandates redirect investment from steel stamping toward recyclable thermoplastic infrastructure. Regional governments in Jiangsu and Zhejiang provinces deploy tax incentives for compounders certifying REACH-compliant additive packages.
China
MIIT energy-intensity restrictions on steel production redirect capital toward thermoplastic molding lines serving domestic EV platforms. Provincial governments in Jiangsu and Anhui offer consumption tax rebates for facilities achieving post-industrial plastic recovery rates above 85%. Ningbo and Taizhou industrial clusters host the densest concentration of long-fiber thermoplastic compounders supplying modular bumper platforms.
Germany
KBA pedestrian-safety homologation requirements compress development timelines for active hood actuation systems integrated into front bumper assemblies. ECHA authorization sunsets for legacy flame retardants force compounders in North Rhine-Westphalia to recertify formulations by 2027. Stuttgart and Munich metropolitan areas concentrate R&D facilities for sensor-embedded modular carrier platforms.
United States
NHTSA fleet fuel-economy standards penalize bumper mass, accelerating aluminum-to-plastic substitution in light-truck platforms. EPA enforcement of crash-test harmonization pressures suppliers to validate assemblies against multiple jurisdictional protocols simultaneously. Detroit-Warren-Dearborn and Nashville-Davidson-Murfreesboro-Franklin metropolitan statistical areas anchor injection-molding capacity for domestic OEM electrification programs.
Japan
METI harmonization through JIS crash-test protocols shapes exportable bumper architectures for Southeast Asian markets. Keidanren industry group coordination accelerates standardization of sensor-mounting interfaces across keiretsu supplier networks. Aichi Prefecture and Kanagawa Prefecture maintain concentration in steel-aluminum hybrid stamping for commercial vehicle applications.
South Korea
Ministry of Trade, Industry and Energy carbon-neutral manufacturing mandates redirect Hyundai-Kia supplier networks toward closed-loop thermoplastic recovery. GB standards alignment requirements for Chinese export markets compound homologation burdens for compounders in Gyeonggi-do. Busan-Ulsan industrial corridor hosts specialized mold fabrication capacity serving both domestic OEMs and tier-1 system integrators.
Global Automotive Bumpers Market Vendor Landscape
European producers anchor the integrated-system tier; Asian specialists hold scale advantages in injection-molding capacity. The vendor structure fragments across three strategic layers: global tier-1 system integrators with full-modular capabilities, regional compounders serving single-OEM platforms, and specialized mold-fabrication shops. Dominant competitive moves include backward integration into recycled polymer feedstocks and geographic expansion through joint ventures with Chinese EV startups.
Within the European integrated-system tier, Plastic Omnium and Faurecia exemplify archetypes of regulatory-compliant modular platform suppliers. Tong Yang Group occupies a position among Asian-scale compounders competing on injection-molding throughput across multi-OEM contracts. These three entities represent distinct strategic postures: European regulatory anticipation, feedstock vertical control, and manufacturing scale deployment.
| Leading Market Players |
|---|
| Toyoda Gosei |
| Faurecia |
| Plastic Omnium |
| Forvia SE |
| Flex-N-Gate Corporation |
| Hyundai Mobis |
| Tong Yang Group |
| SMP Deutschland GmbH |
| Magna International |
| Others |
Supply Flow & Price Mechanics
OEM consolidation toward modular electric vehicle platforms is compressing development timelines and forcing suppliers to absorb upfront tooling costs, which in turn squeezes margins on standard-grade bumper assemblies while inflating premiums for rapid-turnaround sensor-integrated systems.
Pricing Analysis
Lead-time compression commands substantial premiums in the current procurement environment, with European OEMs paying 15-25% markups for crash-test-validated modular platforms delivered under compressed homologation schedules. Three-tier pricing structure across premium sensor-integrated, standard modular, and economy stamped-steel tiers reflects certification burden and volume scale. Price differentiation hinges on REACH-compliant additive packages and JIS/ECE dual-protocol validation status. Cost compression in standard-grade polypropylene beams is intensifying because Chinese compounders are flooding Asian EV supply chains with spot-market resin. Fleet procurement managers at North American electric vehicle startups exhibit the highest price sensitivity, while German premium OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Ningbo, Stuttgart, and Detroit-Warren-Dearborn anchor hub-and-spoke fulfillment patterns that position finished bumper modules within 48-hour delivery windows of final assembly plants. Geographic supply concentration centers on China, Germany, and the United States, with mold fabrication capacity clustering in Busan-Ulsan and Taizhou. Raw material dependencies draw from Saudi propylene feedstocks, German long-fiber thermoplastic compounds, and Japanese steel-aluminum hybrid substrates. Single-source vulnerability pervades large injection mold fabrication, where Chinese and South Korean toolmakers control 70% of global capacity for complex sensor-integrated carrier platforms. Distribution runs through tier-1 system integrators operating captive logistics networks to OEM assembly sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive bumper market is traversing a material-transition phase as long-fiber thermoplastic composites displace short-fiber polypropylene in structural beam applications, rendering legacy compounding assets stranded without fiber-impregnation retrofit.
For Market Incumbents: Cement market position by securing backward integration into post-industrial polypropylene regrind streams ahead of EU Green Deal funding exhaustion, and by acquiring specialized CAE talent pools capable of combined crash-electromagnetic-thermal modeling for sensor-embedded platforms. Threat substitution from aluminum stamping in premium SUVs demands preemptive capacity rationalization in steel-intensive commercial vehicle segments. For New Entrants and Emerging Players: REACH authorization sunsets for halogenated flame retardants in Europe open a window for phosphorus-nitrogen intumescent compounders to capture reformulation contracts from incumbent suppliers facing ECHA recertification deadlines. White-space targets include modular bumper-to-fascia unbundling procurement at Chinese EV startups and aftermarket decorative fascia channels in Brazil and India. Go-to-market execution should anchor on rapid additive-package certification and regional compounding joint ventures. For Investors and Strategic Acquirers: The window for entry favors mid-cap compounders with captive fiber-impregnation capabilities and established OEM platform engineering relationships. Long-term viability rests on positioning for closed-loop recycling infrastructure economics as extended producer responsibility frameworks mature across European and Chinese jurisdictions. Acquisition target archetype: regional compounders with REACH-certified formulation libraries and underutilized molding capacity in Yangtze River Delta special economic zones. Monitor MIIT enforcement intensity on steel stamping energy quotas as the inflection signal for thermoplastic substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Recycling Infrastructure | EU Green Deal funding streams reward first-movers in post-industrial regrind certification. |
| Long-Fiber Thermoplastic Capacity Expansion | Direct fiber impregnation capabilities decentralize molding toward regional compounders. |
| Sensor Integration Platform Standardization | Harmonized LiDAR mounting interfaces reduce validation costs across multi-OEM contracts. |
| REACH-Compliant Additive Recertification | ECHA authorization deadlines force compounders to secure phosphorus-nitrogen formulations. |
| Joint Venture with Chinese EV Startups | Provincial tax incentives in Jiangsu and Zhejiang accelerate modular bumper deployment. |
Methodological Framework
Trade databases, OEM production forecasts, and regulatory filing repositories formed the secondary backbone, supplemented by primary interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and compounder technical directors. Bottom-up and top-down triangulation validated volume estimates against IHS Markit vehicle registration data and customs records for polypropylene resin and aluminum sheet imports.
Bottom-up modeling anchored on platform-level content-per-vehicle assumptions across vehicle class, propulsion architecture, and regional production cluster dimensions, while top-down reconciliation checked aggregate market value against disclosed tier-1 supplier revenue allocations. CAGRs were derived from regression analysis of historical OEM procurement patterns and forward platform electrification schedules. Industry-specific forecast inputs included MIIT dual carbon mandate enforcement trajectories and ECHA substance evaluation timelines.
The model assumes a particular technology adoption path; alternative pathways for aluminum-to-plastic substitution in light-truck platforms would alter the outlook if EPA fuel-economy penalties intensify or propylene monomer volatility disrupts compounder margins. Forecasts reflect documented assumptions around pedestrian-safety regulation harmonization and sensor integration density curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Automotive Chromium Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
China Automotive Actuators Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Automotive Bearing Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Global Automotive Sun Visor Market
Automotive Components
Automotive Engine Encapsulation Market