
 Asia Pacific Automotive Engine Market | 2026-2036
Asia Pacific Automotive Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Engine Market Outlook
Aluminum is decoupling traditional cast-iron block economics across the Asia Pacific Automotive Engine landscape, trimming weight and thermal management costs for mass-market programs. Toyota Industries Corporation leverages its captive foundry network to sustain cost advantages on high-volume four-cylinder architectures. Hyundai Motor Group anchors its competitiveness through in-house continuous variable valve timing systems that reduce parasitic losses. Mahindra & Mahindra Limited dominates the commercial vehicle diesel segment in India with indigenized CRDi platforms.
An automotive engine converts chemical energy from fuel into mechanical work through controlled combustion within cylinders, with bore diameters, stroke lengths, and compression ratios calibrated to specific duty cycles and emission targets. The assembly serves as the primary propulsion system for road vehicles, translating thermal efficiency into drivetrain torque. Gasoline engines retain the largest installed base across passenger vehicle applications, though hybrid engines are capturing the fastest growth as OEMs bridge toward electrification without abandoning combustion supply chains. Direct injection technology commands premium positioning within the technology stack, while diesel engines face structural compression in compact car segments due to urban air quality mandates.
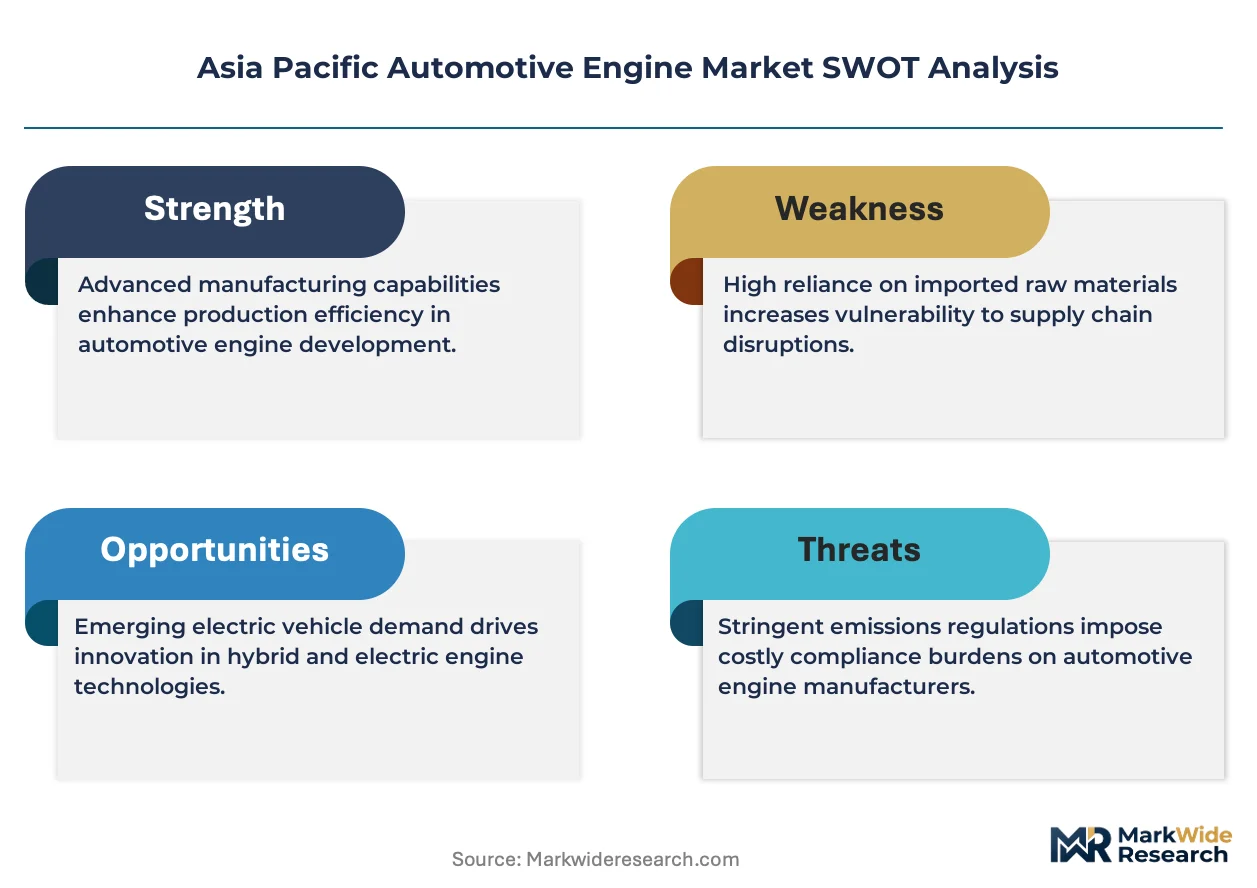
China's MEE enforces escalating fuel economy thresholds that force engine downsizing and turbocharger penetration. India's BIS and the country's automotive research agencies are tightening particulate matter limits for commercial vehicle powertrains, reshaping supplier qualification requirements. Japan's METI coordinates domestic OEM alignment on hydrogen-compatible internal combustion development. Stakeholders must weigh the durability of combustion R&D investment against the accelerating capital reallocation toward full-electric platforms in key ASEAN manufacturing clusters.
Market Dynamics
Engine downsizing and forced induction architectures are compressing displacement volumes across Asia Pacific passenger vehicle programs as China's MEE fuel economy thresholds and India's BIS emission mandates harden compliance requirements.
Growth Catalysts
- Commercial vehicle fleet expansion:Logistics network densification across Southeast Asia is pulling procurement of medium-duty diesel powertrains for last-mile freight operations.
- Dual carbon goals:China's national carbon neutrality targets are accelerating hybrid engine development timelines and captive production of electrified combustion systems.
- CRDi platform localization:Indigenous common-rail direct injection manufacturing in India is reducing import dependency for commercial vehicle powertrains.
Market Restraints
- Aluminum ingot cost volatility:Foundry-grade aluminum price swings are squeezing margin structures for lightweight block production programs.
- Urban air quality mandates:Diesel particulate limits in Indian megacities are compressing addressable market for compact car oil-burners.
- Full-electric substitution:Battery-electric platform capital reallocation in ASEAN manufacturing clusters is diverting combustion R&D budgets.
Strategic Opportunities
- Hydrogen-compatible combustion:Japan's METI coordination on hydrogen ICE development opens white space for dual-fuel architecture suppliers.
- Continuous variable valve timing convergence:Integration of electromechanical cam phasing with turbocharger control systems enables efficiency gains in mass-market segments.
- Indonesian commercial vehicle demand:Archipelago logistics infrastructure buildout is creating unmet need for durable medium-duty powertrains.
Industry Challenges
- Combustion-electric integration complexity:Hybrid powertrain calibration demands cross-functional expertise spanning thermal management and battery control systems that remains scarce in regional engineering pools.
- Emissions certification timelines:India's BIS particulate matter testing protocols are extending type-approval cycles and compressing model-year launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Engine Market |
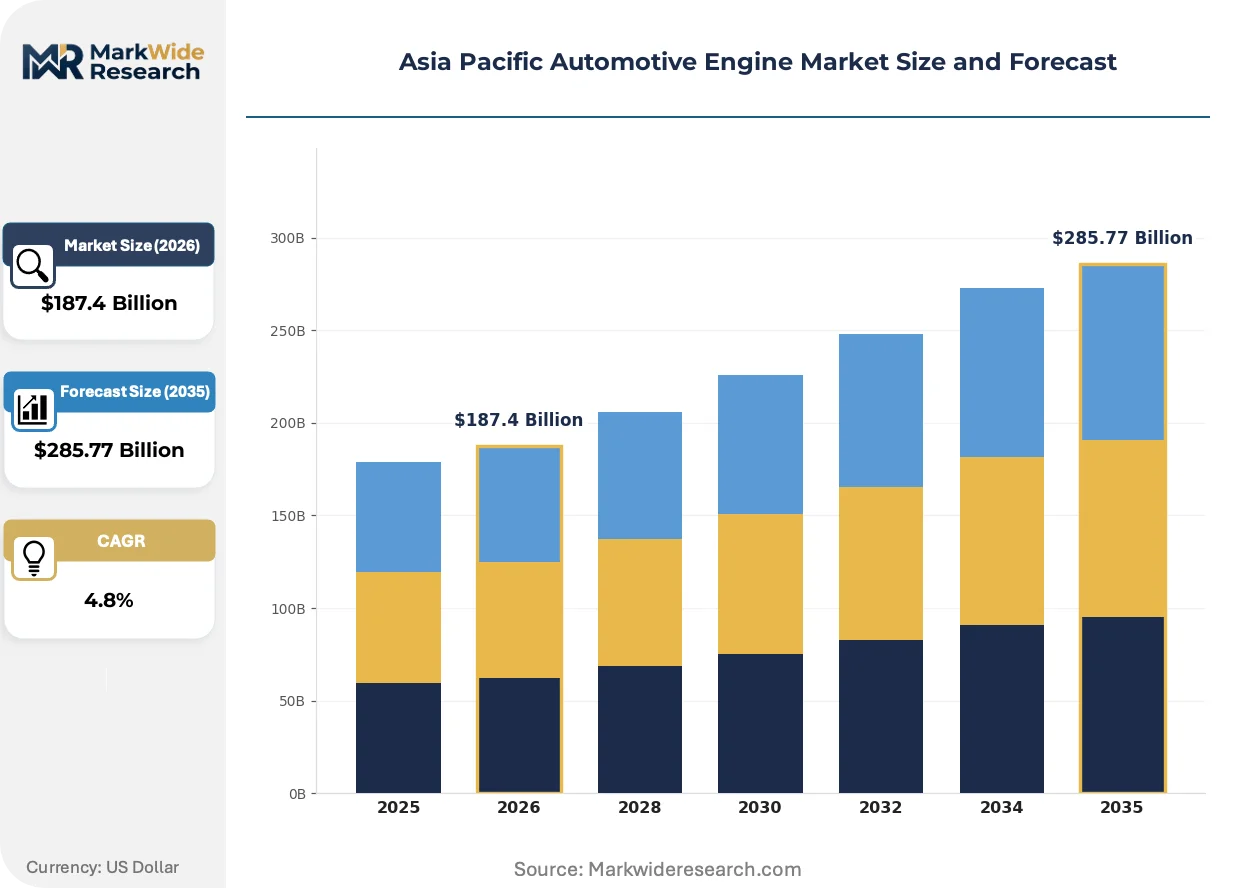
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Hybrid Engines, Electric Motors End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Light Truck Manufacturers Technology: Turbocompressor, Direct Injection, Variable Valve Timing, EFI Vehicle Type: Compact Cars, SUVs, Sedans, Pickup Trucks |
| Companies Covered | Honda Motor Company Limited, Maruti Suzuki Limited, Toyota Industries Corporation, AVL, Mahindra & Mahindra Limited, Hyundai Motor Group, Tata Motors Limited, Isuzu Motors Limited, Nissan Motor Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Engine Market Strategic Shifts
Thermal efficiency optimization and electrified auxiliary systems are redefining powertrain architecture trade-offs across Asia Pacific manufacturing footprints.
Variable compression ratio technology is electrifying conventional spark-ignition economics by enabling knock-limited optimization across load ranges. Japanese OEM captive suppliers are deploying production-scale electromechanical piston stroke control for high-volume four-cylinder programs. This architecture is electrifying the cost-performance boundary between naturally aspirated and forced induction configurations.
China's MEE enforcement of corporate average fuel consumption ceilings is mandating widespread turbocharger penetration and cylinder deactivation activation. The regulation is compressing development timelines for dedicated hybrid engines with Atkinson-cycle optimization. Passenger vehicle programs targeting domestic Chinese sales are responding with accelerated in-house turbocharger foundry investments.
Fleet operators across India and Southeast Asia are consolidating powertrain procurement through direct OEM relationships, bypassing traditional dealer network intermediaries. Large logistics conglomerates are negotiating captive service contracts with fixed per-kilometer maintenance pricing. This concentration is most visible in Indian e-commerce fulfillment networks where standardized diesel powertrain specifications dominate tender requirements.
Asia Pacific Automotive Engine Market Segmentation
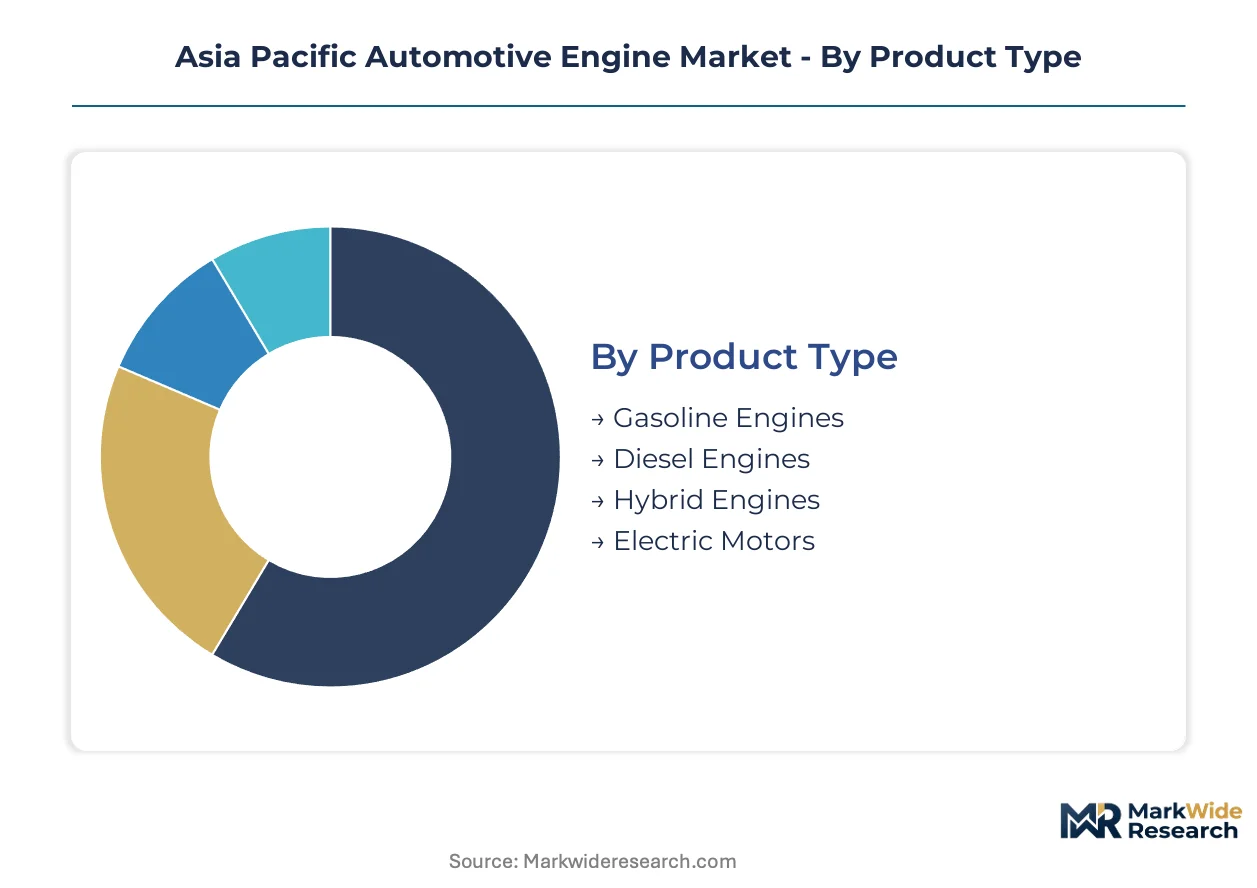
Engine architecture choices in Asia Pacific reflect divergent capital deployment strategies across OEM portfolios. Product type selection determines foundry investment scale, while technology tier locks in supplier qualification timelines.
Product Type:
Gasoline and diesel platforms demand the heaviest upfront foundry and machining capital, while hybrid architectures require cross-functional integration with electrified systems.
- Gasoline Engines:Spark-ignition architectures with aluminum block construction dominate mass-market passenger vehicle programs. India's Maruti Suzuki and China's Geely anchor high-volume four-cylinder production for domestic consumption.
- Diesel Engines:Compression-ignition powertrains with common-rail direct injection deliver torque density for commercial freight applications. Fleet procurement across Indonesia and Vietnam concentrates demand for medium-duty CRDi platforms.
- Hybrid Engines:Atkinson-cycle combustion integrated with electric motor assist.
- Electric Motors:Permanent magnet synchronous architectures displacing combustion in premium Chinese EV programs.
Most installed capacity flows through Gasoline Engines. Expansion is steepest in Hybrid Engines.
End User:
Customer concentration shapes pricing power and service contract structures across the value chain.
- Passenger Vehicles:Individual ownership models with replacement cycles tied to emission regulation phase-ins. China's MEE fuel economy thresholds accelerate downsizing and turbocharger penetration in this segment.
- Commercial Vehicles:Fleet-operated powertrains with standardized maintenance protocols and per-kilometer service pricing. E-commerce logistics networks across India negotiate direct OEM procurement bypassing dealer intermediaries.
- Motorcycles:Single-cylinder and parallel-twin architectures for two-wheeler mobility.
- Light Truck Manufacturers:Medium-duty chassis cab producers serving last-mile delivery consolidation.
Passenger Vehicles absorb the majority of unit volume. Commercial Vehicles command the highest per-unit engineering investment.
Technology:
Patent density and supplier exclusivity agreements create tiered access to performance tiers.
- Turbocompressor:Forced induction systems enabling downsized displacement without torque sacrifice. China's MEE corporate average fuel consumption mandates accelerate turbocharger foundry investments by domestic OEMs.
- Direct Injection:High-pressure fuel delivery into combustion chambers for precise charge control. Hyundai Motor Group's in-house GDI platforms anchor competitiveness in Korean and ASEAN export markets.
- Variable Valve Timing:Electromechanical cam phasing optimizing valve events across load ranges.
- EFI:Port fuel injection architectures retaining cost advantage in price-sensitive segments.
Direct Injection captures the dominant share of new program launches. Variable Valve Timing is climbing the fastest as electromechanical systems replace hydraulic actuation.
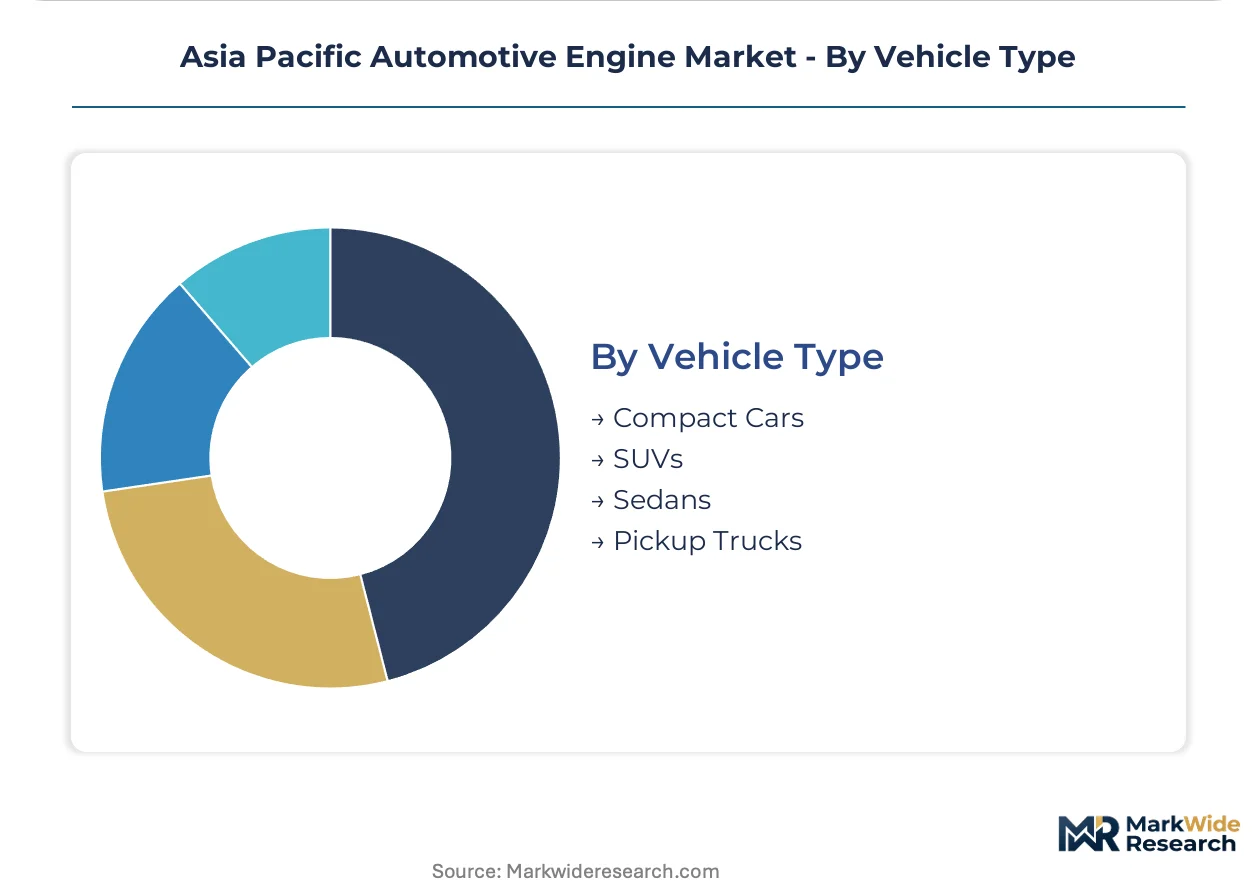
Vehicle Type:
Platform scale economies and body style popularity determine engine specification standardization.
- Compact Cars:Sub-four-meter passenger vehicles with three-cylinder and small four-cylinder powertrains. India's tax structure favoring this length class concentrates small-displacement engine demand.
- SUVs:Higher ride height architectures requiring torque-rich powertrains for all-terrain capability. Chinese domestic brands deploy turbocharged gasoline engines across this fastest-expanding body style.
- Sedans:Three-box passenger vehicles with longitudinal and transverse engine layouts.
- Pickup Trucks:Ladder-frame utility vehicles with diesel dominance in Thai and Australian markets.
SUVs now absorb the largest share of engine program development hours. Compact Cars retain the highest unit volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta anchors the densest concentration of automotive engine manufacturing capacity across the Asia Pacific, with foundry investments clustering around Shanghai and Jiangsu province as domestic OEMs scale turbocharger production.
China
Corporate average fuel consumption enforcement by MEE accelerates downsized gasoline engine programs. The dual carbon goals compress development timelines for dedicated hybrid architectures. Yangtze River Delta foundries in Shanghai and Wuxi expand captive turbocharger casting capacity to serve Geely and BYD powertrain divisions.
India
Commercial vehicle fleet procurement for e-commerce logistics concentrates demand for medium-duty diesel powertrains. BIS particulate matter testing protocols extend type-approval cycles for new engine launches. Tamil Nadu's Sriperumbudur belt hosts Maruti Suzuki and Hyundai Motor Group engine plants serving domestic compact car demand.
Japan
Hybrid engine development for export markets sustains investment in Atkinson-cycle optimization. METI coordination on hydrogen-compatible internal combustion creates white space for dual-fuel R&D. Aichi prefecture's Nagoya-Toyota corridor retains captive foundry networks for high-volume four-cylinder production.
Thailand
Pickup truck manufacturing for ASEAN and Australian export markets stabilizes demand for ladder-frame diesel architectures. Board of Investment incentives attract powertrain component suppliers to Eastern Economic Corridor zones. Rayong province hosts Isuzu and Mitsubishi Fuso engine assembly serving regional commercial vehicle programs.
Indonesia
Archipelago logistics infrastructure buildout generates unmet need for durable medium-duty powertrains. Ministry of Industry localization requirements pressure foreign OEMs to establish engine machining operations. Karawang Industrial Estate outside Jakarta concentrates Toyota and Daihatsu engine production for domestic vehicle assembly.
Asia Pacific Automotive Engine Market Competitive Environment
Global majors compete with regional champions across technology tiers and supply chain depth. The vendor base stratifies between captive OEM powertrain divisions, independent engine builders, and tier-one component specialists. Three archetypes dominate: integrated automotive groups with captive foundry networks, commercial vehicle specialists with indigenized diesel platforms, and technology licensors supplying combustion calibration expertise. Competitive moves concentrate on hybrid powertrain integration partnerships and in-house turbocharger foundry investments.
Among Japan-based integrated manufacturers, Toyota Industries Corporation and Honda Motor Company Limited occupy positions defined by captive supply chain control and high-volume production scale. Hyundai Motor Group represents the Korea-centric archetype with in-house continuous variable valve timing development. India's Maruti Suzuki Limited anchors the regional champion category through localization depth and mass-market program dominance.
| Leading Market Players |
|---|
| Honda Motor Company Limited |
| Maruti Suzuki Limited |
| Toyota Industries Corporation |
| AVL |
| Mahindra & Mahindra Limited |
| Hyundai Motor Group |
| Tata Motors Limited |
| Isuzu Motors Limited |
| Nissan Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers across China and Thailand anchor foundry capacity expansion, translating captive aluminum supply into disciplined pricing for turbocharger castings while insulating domestic OEMs from spot-market volatility.
Pricing Analysis
Input-cost pass-through from foundry-grade aluminum ingots governs lightweight block economics, with China's MEE fuel economy mandates forcing rapid turbocharger adoption that absorbs premium pricing for forced-induction architectures. Price differentiation rests on thermal management grade and BIS certification tier for Indian commercial vehicle exports. Pricing pressure stems from battery-electric capital reallocation compressing combustion R&D recovery timelines. Fleet procurement offices exhibit highest price sensitivity; captive OEM powertrain divisions show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Japanese and Korean OEMs mandate qualified secondary suppliers for continuous variable valve timing systems, fragmenting electromechanical cam phasing procurement across domestic and ASEAN machining houses. Geographic concentration centers on China, India, and Thailand for aluminum block foundries and CRDi injector manufacturing. Raw material dependencies span foundry-grade aluminum, high-pressure steel tubing, and rare-earth magnet feedstock for hybrid motor integration. Tariff exposure on precision-machined components from ASEAN trade corridors constitutes the dominant structural risk. Distribution runs through direct OEM procurement contracts with fleet operators, bypassing traditional dealer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific Automotive Engine Market functions as a stable compounder, with logistics network densification across Southeast Asia generating durable replacement demand for medium-duty diesel powertrains.
For Market Incumbents: Cement hybrid powertrain integration partnerships before full-electric substitution accelerates in ASEAN manufacturing clusters. Deepen captive foundry control over turbocharger casting capacity to defend margin structures against aluminum cost volatility. Prioritize BIS certification pre-qualification to compress type-approval cycles for Indian commercial vehicle launches. For New Entrants and Emerging Players: Fleet procurement offices represent the most penetrable channel partner type for bypassing entrenched dealer networks in Indonesian archipelago logistics. Target medium-duty diesel powertrain white space in Eastern Economic Corridor zones where Board of Investment incentives reduce capital barriers. Pursue direct service contracting with per-kilometer maintenance pricing to match incumbent fleet retention models. For Investors and Strategic Acquirers: Valuations sit cheapest among independent engine builders lacking hybrid-electric integration capabilities, where stranded combustion asset risk is already priced in. Frame long-term viability around hydrogen-compatible internal combustion development timelines coordinated by Japan's METI. Monitor MEE enforcement intensity as the critical inflection signal for Chinese downsizing program sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Integration Partnership | Enables OEMs to bridge electrification timelines while retaining combustion supply chain leverage. |
| In-House Turbocharger Foundry Investment | Secures captive casting capacity for MEE-mandated downsized engine programs across Chinese OEMs. |
| CRDi Platform Localization | Reduces import dependency for Indian commercial vehicle fleets under BIS particulate mandates. |
| Hydrogen-Compatible Combustion R&D | Opens dual-fuel architecture white space through METI-coordinated Japanese OEM alignment. |
| Direct Fleet Procurement Contracting | Bypasses dealer intermediaries in Southeast Asian e-commerce logistics network densification. |
Study Parameters
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and commercial fleet operations managers grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs and trade flow records, and regulatory filings with China's MEE and India's BIS. Bottom-up segment sizing and top-down macroeconomic cross-checks produced convergent estimates.
Output trajectories across the projection horizon reflect modeled interactions between vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs emerged from iterative reconciliation of historical penetration patterns with regulatory enforcement schedules. Forecast inputs incorporated MEE corporate average fuel consumption trajectory assumptions and BIS particulate testing protocol evolution.
Revisions become necessary when MEE enforcement intensity shifts, aluminum ingot volatility exceeds historical bands, or ASEAN battery-electric capital reallocation accelerates beyond modeled substitution curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Gear Oil Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Automotive Chain Tensioners Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Global Automotive Dyno Market
Powertrain
Car Drive System Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
North America Precision Gearbox Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Clutch Hub Puller Market
Powertrain
France Automotive Engine Oils Market