
 Automotive Fuel Tank Covers Market | 2026-2036
Automotive Fuel Tank Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Tank Covers Market Analytics
Crash-grade impact resistance is collapsing the gap between commodity and premium fuel tank cover tiers. Magna International leverages integrated fuel system engineering to sustain OEM relationships across North American passenger car programs. Plastic Omnium anchors European supply through composite material leadership in lightweight tank enclosures. TI Fluid Systems competes on thermal management integration, extending its position into hybrid vehicle thermal-fluid architectures.
Automotive fuel tank covers are protective enclosures, typically manufactured from injection-molded polypropylene, stamped steel, or aluminum sheet, designed to shield fuel filler necks and tank caps from debris, moisture, and impact damage while maintaining evaporative emissions compliance. Their primary purpose is to preserve fuel system integrity and meet regulatory permeation limits across internal combustion and hybrid electric vehicle platforms. Plastic cap covers lead volume due to cost scalability, yet composite materials represent the fastest-expanding segment as OEMs pursue mass reduction targets. Steel fuel fillers retain dominance in heavy-duty truck applications where puncture resistance governs specification, while aluminum overflow vents capture margin pools in premium SUV and van segments.
EPA tailpipe and evaporative emissions standards, NHTSA Federal Motor Vehicle Safety Standards, and EU REACH chemical compliance frameworks collectively dictate material selection, permeation thresholds, and fastening system durability requirements for fuel tank cover suppliers. The EU F-Gas Regulation and CE marking obligations further constrain polymer formulations and adhesive chemistries used in European-market components. Stakeholders must monitor regulatory divergence between California Air Resources Board zero-emission vehicle mandates and Euro 7 proposal timelines to align R&D portfolios with diverging compliance pathways.
Market Dynamics
Crash-grade impact resistance specifications are collapsing the historical tier separation between commodity and premium fuel tank cover categories, forcing suppliers to recalibrate material portfolios and certification investments simultaneously.
Growth Catalysts
- EPA evaporative emissions standards:Tightening permeation thresholds under EPA Tier 3 regulations are compelling OEMs to upgrade sealing systems across light-duty vehicle platforms.
- Commercial truck fleet procurement:Fleet operators in the United States are expanding orders for corrosion-resistant tank cover systems to extend asset life cycles in severe-service applications.
- Composite material adoption:Mass reduction targets for hybrid electric platforms are accelerating substitution from stamped steel toward glass-fiber reinforced polymer formulations.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost fluctuations tied to propylene supply constraints are compressing margins for injection-molded cover producers.
- Steel supply concentration:Heavy-duty truck-grade steel filler production concentrates among a limited supplier base in the Midwestern United States, creating procurement bottlenecks.
- REACH chemical compliance:EU restrictions on specific polymer additives are forcing reformulation cycles that extend development timelines by 12-18 months.
Strategic Opportunities
- India commercial vehicle localization:PLI scheme incentives for component manufacturing are attracting tank cover suppliers to establish captive production for domestic OEM programs.
- Thermal-fluid architecture convergence:Integration of fuel tank covers with battery thermal management systems creates cross-platform engineering contracts for hybrid vehicle builders.
- California ZEV mandate alignment:CARB zero-emission vehicle requirements are generating specification work for covers compatible with hydrogen storage and range-extender fuel systems.
Industry Challenges
- Multi-material welding certification:Bonding dissimilar substrates for composite-steel hybrid covers requires new technician training and equipment capital deployment.
- Legacy platform integration:Retrofitting advanced sealing systems into existing vehicle architectures demands custom tooling that fragments production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Tank Covers Market |
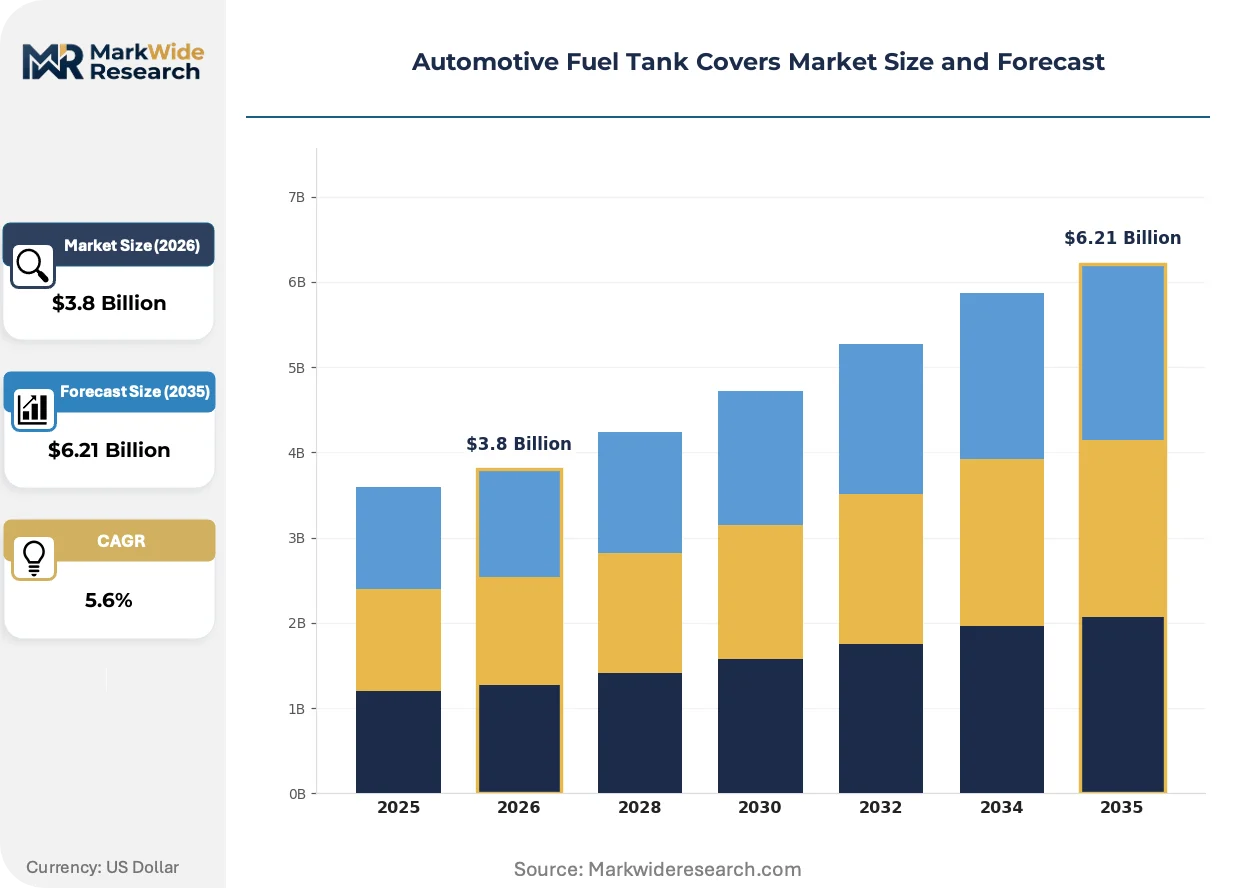
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cap Covers, Locking Mechanisms, Fuel Fillers, Overflow Vents Material: Plastic, Steel, Aluminum, Composite Installation Type: OEM, Aftermarket, Integrated, Retrofit Vehicle Type: Passenger Cars, Trucks, SUVs, Vans |
| Companies Covered | Belmor Inc., Peterbilt Motors Company, A & F Bug Screens, DEI Powersports, Freightliner, Kenworth, Magna International, Plastic Omnium, TI Fluid Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Tank Covers Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine performance benchmarks, with supplier R&D portfolios pivoting toward multi-functional enclosure systems.
Glass-fiber reinforced polypropylene compounds are bifurcating the traditional steel-plastic material hierarchy in fuel tank cover applications. European OEMs have adopted these composites for C-segment passenger cars at scale, while North American manufacturers phase them in across crossover SUV platforms. The technology is bifurcating procurement specifications into crash-graded premium tiers and standard commodity tiers that previously shared material platforms.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are constraining adhesive chemistries and polymer processing aids used in European-market fuel system components. Industrial consequence includes accelerated qualification of water-based adhesive alternatives and bio-based polymer modifiers. German and French OEM supply chains are most affected, with tier-one suppliers restructuring formulation labs to meet 2025 compliance deadlines.
Fleet procurement departments are consolidating vendor relationships and demanding consolidated fuel system module supply rather than discrete component sourcing. Direct OEM-tier supplier contracts are displacing traditional aftermarket distribution for commercial truck covers in the United States. This concentration is most visible in long-haul trucking segments where total cost of ownership calculations dominate specification authority.
Automotive Fuel Tank Covers Market Segmentation
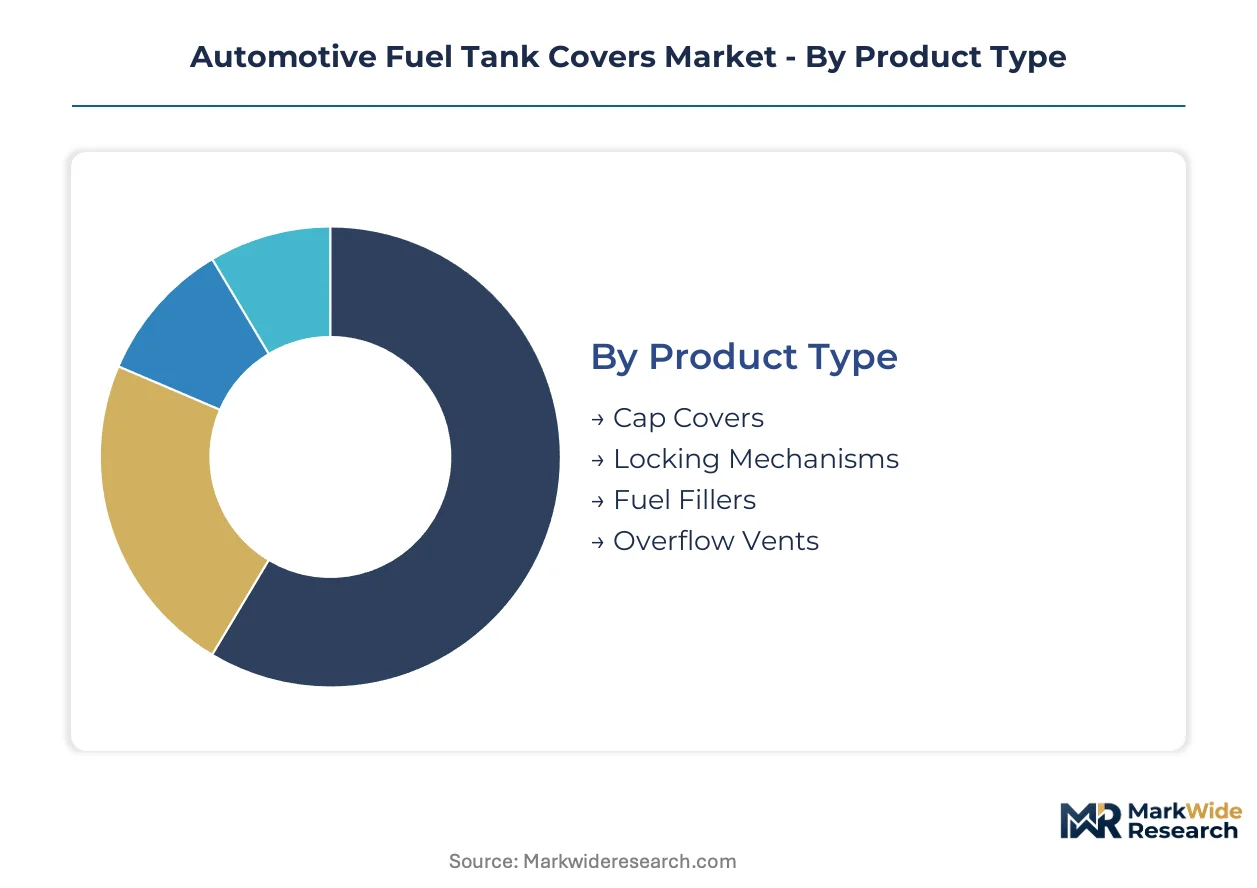
Material substitution pressures and regulatory tiering are fragmenting procurement specifications across fuel tank cover categories. OEMs now segment supplier portfolios by emissions compliance grade rather than legacy commodity classifications.
Product Type:
Cap covers face the strongest substitution threat from integrated fuel system modules that combine multiple functions into single assemblies.
- Cap Covers:Injection-molded polypropylene enclosures shield filler necks from debris and moisture ingress. Demand concentrates in United States passenger car programs where EPA Tier 3 permeation thresholds drive sealing system upgrades.
- Locking Mechanisms:Tamper-resistant latching systems prevent fuel theft and vapor escape. European OEMs specify these for fleet vehicles in Germany and France under EU F-Gas Regulation compliance frameworks.
- Fuel Fillers:Stamped steel or aluminum neck assemblies connect tanks to external fueling points.
- Overflow Vents:Pressure-relief channels prevent tank rupture during thermal expansion events.
Cap covers retain volume leadership; locking mechanisms hold the steepest expansion curve as fleet procurement consolidates toward security-integrated systems.
Material:
Cost tier stratification separates premium crash-graded formulations from commodity-grade alternatives.
- Plastic:Polypropylene compounds dominate light-duty applications through injection molding scalability. United States OEMs favor these for high-volume crossover SUVs where cost-per-unit governs sourcing decisions.
- Steel:Heavy-duty stamped fillers withstand puncture impacts in severe-service trucking. Midwestern United States steel suppliers concentrate production for commercial fleet operators extending asset life cycles.
- Aluminum:Sheet-formed vents reduce mass in premium SUV and van segments.
- Composite:Glass-fiber reinforced polymers bifurcate specifications into crash-graded premium tiers.
Plastic retains volume leadership; composite holds the steepest expansion curve as hybrid platforms accelerate mass reduction targets.
Installation Type:
Customer type segmentation reveals diverging procurement authority between captive OEM supply and independent aftermarket channels.
- OEM:Direct vehicle manufacturer contracts specify covers during platform development. United States commercial truck builders integrate these into chassis assembly lines under NHTSA Federal Motor Vehicle Safety Standards.
- Aftermarket:Replacement part distribution serves collision repair and fleet maintenance networks. United States long-haul trucking segments increasingly bypass this channel through consolidated vendor relationships.
- Integrated:Fuel system module suppliers bundle covers with pumps and sensors.
- Retrofit:Custom tooling adapts advanced sealing systems to legacy vehicle architectures.
OEM retains volume leadership; integrated holds the steepest expansion curve as module consolidation displaces discrete component sourcing.
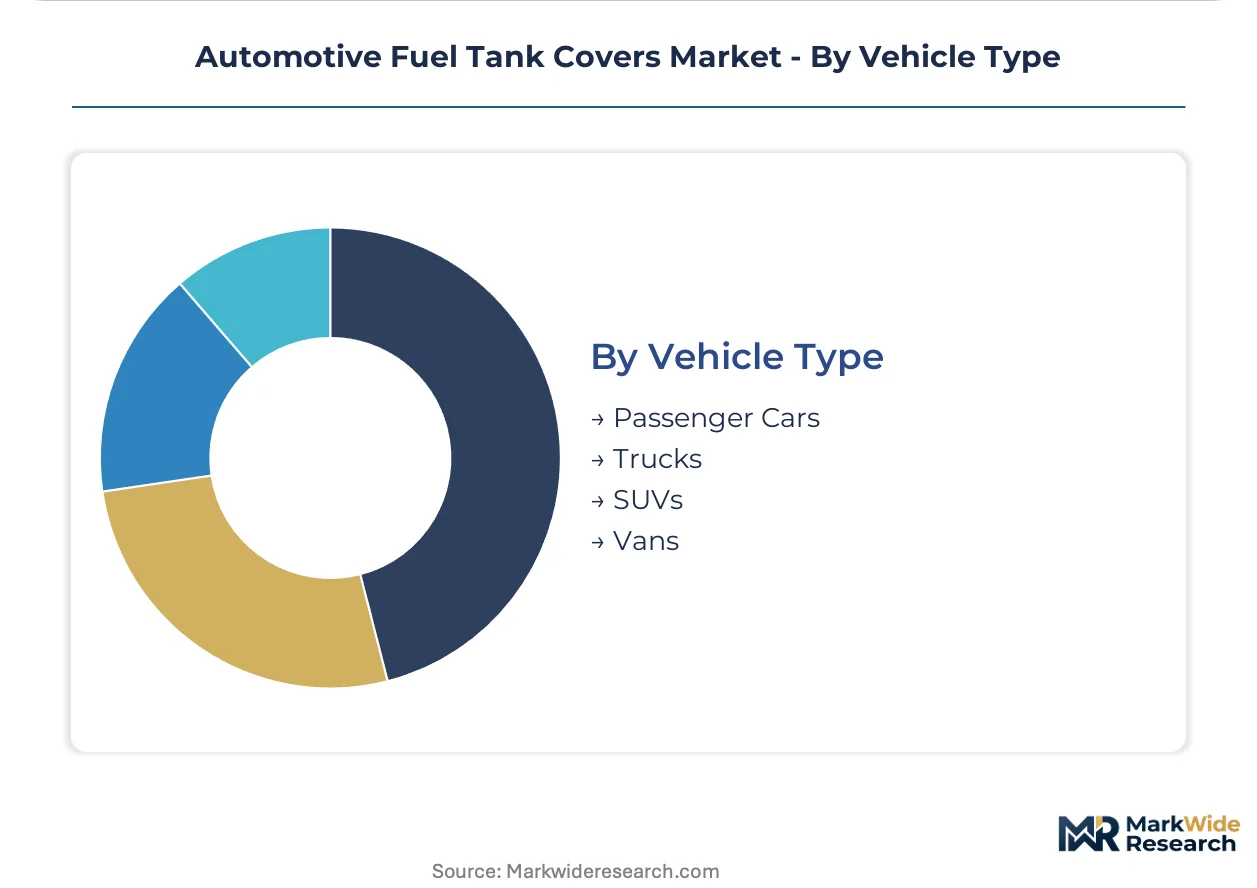
Vehicle Type:
Application-based segmentation tracks diverging material specifications across weight classes and duty cycles.
- Passenger Cars:Lightweight plastic and composite covers prioritize evaporative emissions compliance. European C-segment platforms in Germany and France adopt glass-fiber reinforced formulations at scale.
- Trucks:Corrosion-resistant steel systems dominate severe-service applications. United States fleet operators specify these for extended asset life cycles in long-haul and vocational segments.
- SUVs:Premium segments specify aluminum overflow vents for mass reduction.
- Vans:Commercial delivery platforms balance durability with payload optimization.
Passenger cars retain volume leadership; trucks hold the steepest expansion curve as fleet procurement accelerates corrosion-resistant system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern United States steel suppliers concentrate heavy-duty filler production for commercial fleets, while German and Chinese OEMs localize composite supply chains for hybrid platform compatibility. Demand clusters in three regulatory jurisdictions with diverging emissions timelines.
United States
Commercial truck fleet operators in Michigan, Ohio, and Indiana specify corrosion-resistant steel systems to extend asset life cycles in severe-service applications. EPA Tier 3 evaporative emissions standards and NHTSA Federal Motor Vehicle Safety Standards govern material selection and permeation thresholds. Detroit-Warren-Dearborn automotive cluster anchors OEM supply relationships for integrated fuel system modules.
Germany
Glass-fiber reinforced polypropylene compounds penetrate C-segment passenger cars at scale as OEMs pursue mass reduction targets. EU F-Gas Regulation and REACH chemical compliance frameworks constrain adhesive chemistries and polymer processing aids. Stuttgart and Munich engineering centers restructure formulation labs to meet 2025 compliance deadlines for bio-based polymer modifiers.
China
Domestic OEMs localize supply chains for electric-hybrid platform compatibility, accelerating composite material substitution from stamped steel. MIIT fuel economy standards and GB emissions regulations tighten fitment specifications for new energy vehicles. Yangtze River Delta manufacturing bases scale injection-molded polypropylene production for high-volume crossover SUV programs.
India
PLI scheme incentives for component manufacturing attract tank cover suppliers to establish captive production for domestic commercial vehicle programs. BIS automotive standards and DGFT localization mandates pressure import substitution in fuel system components. Maharashtra and Gujarat industrial corridors host emerging tier-one supplier facilities serving Tata Motors and Mahindra & Mahindra chassis assembly lines.
Japan
METI carbon neutrality roadmaps drive hybrid thermal-fluid architecture convergence, creating cross-platform engineering opportunities. JIS standards and PMDA chemical safety frameworks regulate polymer formulations in automotive applications. Kanto and Kansai manufacturing belts concentrate precision stamping operations for premium SUV aluminum overflow vent segments.
Automotive Fuel Tank Covers Market Competitive Landscape
Concentration sits with diversified automotive suppliers holding integrated fuel system engineering capabilities. Tier-one fabricators with captive polymer compounding operations command premium positioning in composite formulations, while metal-forming specialists retain heavy-duty truck segments through puncture-resistant steel specifications. Two strategic archetypes dominate: integrated system engineers leveraging thermal-fluid architecture contracts, and material science leaders commanding glass-fiber reinforced polymer supply. Competitive moves center on backward integration into resin compounding and geographic expansion through PLI-scheme manufacturing footprints in India.
Among North American diversified suppliers, Magna International anchors integrated fuel system engineering relationships across passenger car programs. Plastic Omnium occupies a position exemplifying European composite material leadership in lightweight tank enclosures. TI Fluid Systems represents thermal-fluid architecture convergence, extending positioning into hybrid vehicle battery thermal management integration. These three entities collectively illustrate the competitive tension between commodity-scale injection molding and premium crash-graded composite certification tiers.
| Leading Market Players |
|---|
| Belmor Inc. |
| Peterbilt Motors Company |
| A & F Bug Screens |
| DEI Powersports |
| Freightliner |
| Kenworth |
| Magna International |
| Plastic Omnium |
| TI Fluid Systems |
| Others |
Value Network & Pricing Analysis
EPA Tier 3 evaporative emissions certification gates both supplier qualification and price differentiation simultaneously, forcing OEMs to segment procurement by compliance grade rather than legacy material tiers. Crash-grade impact resistance specifications collapse historical commodity-premium separations, concentrating pricing power with resin compounders holding captive formulation capabilities.
Pricing Analysis
EPA Tier 3 regulations dictate the pricing tier structure across fuel tank cover procurement, separating crash-graded composite formulations from standard polypropylene injection molding. Price differentiation rests on certification investment scale and thermal management integration depth. Cost compression in commodity-grade plastic tiers is intensifying because propylene feedstock volatility fragments margin structures. Fleet procurement departments demonstrate lowest price sensitivity, prioritizing total cost of ownership calculations over per-unit costs in severe-service trucking segments.
Supply Chain Analysis
Inventory buffers for glass-fiber reinforced compounds stretch 8-12 weeks longer than commodity polypropylene due to specialized compounding batch requirements. Geographic supply concentration centers on Germany, China, and the United States, with Midwestern steel suppliers anchoring heavy-duty filler production for commercial fleets. Raw material dependencies draw from propylene monomer, glass fiber roving, and automotive-grade steel sheet. Single-source vulnerability concentrates in steel filler stamping operations serving long-haul truck builders. Distribution runs through captive OEM supply contracts that displace aftermarket channels in fleet procurement consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
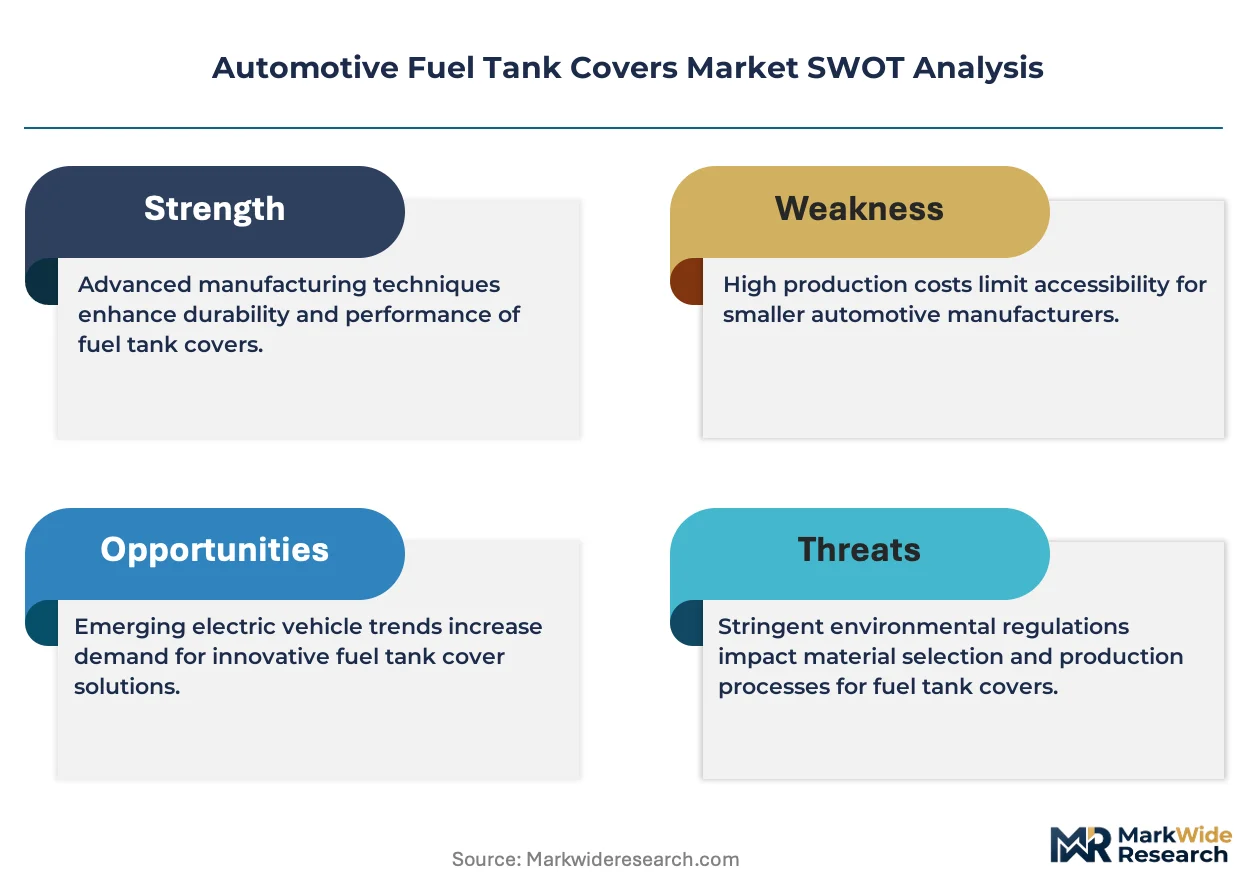
This market operates as a defensive-moat structure where regulatory certification entrenchment creates switching costs that lock OEMs into validated supplier relationships across platform lifecycles.
For Market Incumbents: Shield margin structures by deepening backward integration into resin compounding operations, particularly for glass-fiber reinforced formulations where formulation IP concentrates pricing power. Accelerate certification investments for hydrogen storage compatibility ahead of California ZEV mandate alignment. Threat substitution from integrated fuel system module suppliers demands channel control through thermal-fluid architecture contracts that bundle covers with battery management components. For New Entrants and Emerging Players: CARB fast-track certification for range-extender fuel system compatibility opens white-space entry into California-compliant hydrogen storage cover segments. Target India's PLI scheme manufacturing corridors where domestic OEM localization creates penetrable supply gaps for commercial vehicle programs. Pursue go-to-market positioning through thermal management integration partnerships rather than discrete component bidding. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive suppliers holding composite formulation labs but lacking thermal-fluid architecture capabilities. Long-term viability hinges on cross-platform engineering contracts spanning internal combustion and hybrid electric vehicle production. Acquisition targets center on mid-cap resin compounders with captive glass-fiber processing and EPA certification portfolios. Signal to monitor: fleet procurement consolidation velocity in United States long-haul trucking segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive formulation control locks OEM relationships through EPA Tier 3 certification exclusivity. |
| Thermal-Fluid Architecture Convergence | Battery thermal management integration extends positioning into hybrid platform engineering contracts. |
| India PLI Manufacturing Footprint | Domestic production localization captures Tata Motors and Mahindra commercial vehicle program sourcing. |
| California ZEV Certification Investment | Hydrogen storage compatibility opens specification work under CARB zero-emission vehicle mandates. |
| Fleet Procurement Channel Consolidation | Direct OEM-tier contracts displace aftermarket distribution in United States long-haul trucking segments. |
Research Methodology
Desk research of vehicle production databases, EPA certification filings, and customs trade records preceded structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and resin compounding technical directors. Primary fieldwork combined telephone interviews and facility observations across Midwestern United States steel stamping operations and German composite formulation labs. Secondary validation drew from IHS Markit registration data, NHTSA safety standard documentation, and SEC automotive supplier filings. Bottom-up volume modeling triangulated against top-down OEM production allocation analysis.
Variance decomposition across material substitution rates, regulatory compliance timelines, and fleet procurement cycle timing shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from unit volume trajectory analysis against average selling price evolution by certification tier. Industry-specific forecast inputs incorporated EPA Tier 3 permeation threshold implementation schedules and MIIT fuel economy standard phase-in curves.
Underlying assumptions cover stable propylene feedstock availability and REACH compliance deadline adherence, with deviation risk concentrated in EU F-Gas Regulation reformulation timeline extensions and steel tariff policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Rear-View Mirror Market