
 Turkey Automotive Plastic Compounding Market | 2026-2036
Turkey Automotive Plastic Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Automotive Plastic Compounding Market Intelligence
Multi-source procurement among Tier-1 suppliers is consolidating as Turkish automakers seek supply security for engineered polymers. Elastron TPE leverages its thermoplastic elastomer expertise to serve interior component specialists. Petkim Petrokimya Holding A.Ş. anchors domestic polypropylene supply through its Aliaga petrochemical complex. EPSAN competes with reinforced nylon compounds for under-the-hood functional parts.
Automotive plastic compounding involves melt-blending base resins with additives, fillers, and reinforcements to achieve specified mechanical, thermal, and aesthetic properties for vehicle applications. Typical specifications include melt flow indices of 5–50 g/10 min and heat deflection temperatures exceeding 120°C for engine-bay grades. Polypropylene dominates volume demand across interior and exterior component applications, while polycarbonate compounds command premium positioning in headlamp housings and glazing applications. Injection molding technology leads processing method selection, though extrusion gains share in bumper fascia and sealing profiles.
Turkish Standards Institution automotive material certifications and EU REACH compliance requirements shape import substitution strategies for domestic compounders. BIS-equivalent testing protocols for flammability and VOC emissions influence formulation decisions. Stakeholders must monitor EV platform material specifications as Turkish vehicle assemblers expand electrified model lines.
Market Dynamics
Turkish OEMs are consolidating engineered polymer procurement around domestic compounders as BIS-equivalent Turkish Standards Institution certification requirements tighten material traceability for electric vehicle platforms. This supplier rationalization is compressing qualification timelines while elevating technical performance thresholds across Istanbul and Bursa industrial corridors.
Growth Catalysts
- EU Green Deal alignment:Turkish vehicle exporters must meet REACH and RoHS compliance for EU market access, driving reformulation of flame-retardant compounds toward halogen-free alternatives.
- EV platform lightweighting:Battery enclosure manufacturers specify glass-reinforced polypropylene compounds to offset powertrain mass, expanding heat-deflection temperature requirements above 140°C.
- Aliaga petrochemical complex expansion:Domestic propylene supply integration reduces import dependency for base resin feedstocks serving Bursa automotive clusters.
Market Restraints
- Crude oil derivative volatility:Polypropylene and polycarbonate pricing tracks naphtha and benzene feedstock swings, compressing compounder margins during petrochemical upcycles.
- Engineered resin import concentration:Specialty nylon and PBT grades remain captive to German and Belgian suppliers, exposing Tier-1 molders to euro-denominated cost pass-throughs.
- VOC emission test protocols:Turkish Standards Institution cabin air quality specifications exceed legacy SAE methods, requiring additive package redesigns that extend development cycles.
Strategic Opportunities
- Recycled content mandates:EU End-of-Life Vehicles Directive pressure on Turkish exporters creates demand for post-industrial polypropylene recompounders with certified traceability systems.
- Interior surface haptics:Soft-touch thermoplastic elastomer specifications for instrument panels and door trims open formulation partnerships between compounders and injection molders.
- Adana-Mersin corridor development:Emerging automotive supplier parks in Mediterranean Turkey offer greenfield compounding capacity closer to Levant export markets.
Industry Challenges
- Colorimetric matching expertise:Exterior body-color compounds require spectrophotometric formulation capabilities that outpace current technical training pipelines in Anatolian production facilities.
- Multi-standard certification overlap:Simultaneous Turkish Standards Institution, OEM-specific, and EU type-approval testing creates redundant validation costs for compound product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Automotive Plastic Compounding Market |
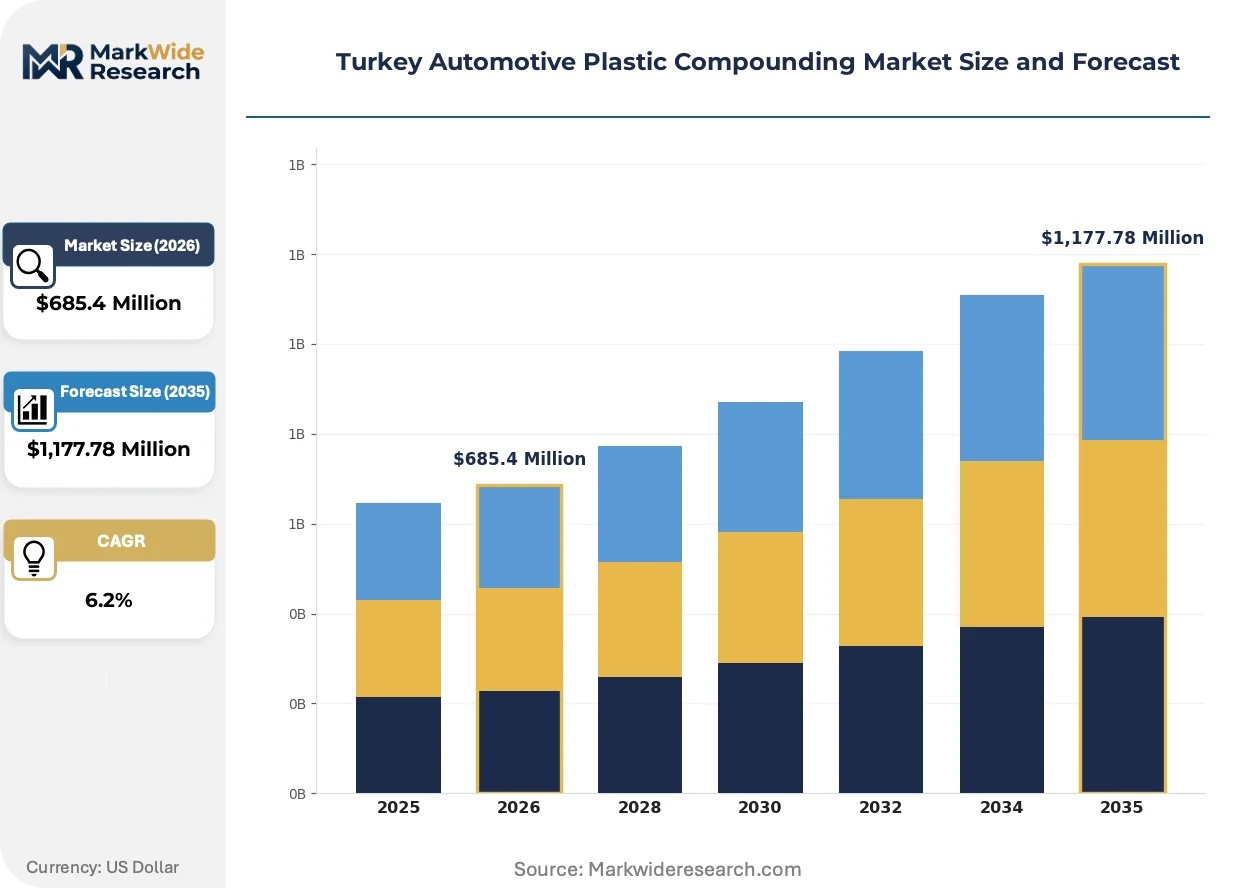
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Acrylonitrile Butadiene Styrene, Polycarbonate Application: Interior Components, Exterior Components, Functional Parts, Engine Components End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming |
| Companies Covered | Elastron TPE, EPSAN, Petkim Petrokimya Holding A.Ş., ALBIS Distribution GmbH und Co. KG, MASKOM Plastik San. ve Tic. Ltd. Şti., Alfa Polimer İnovasyon Plastik A.Ş., Pimar-Plastics Limited, Tosaf, Tisan Mühendislik Plastikleri San. Tic. Ltd. Şti., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Automotive Plastic Compounding Market Strategic Shifts & Innovations
Long-fiber thermoplastic injection molding is compressing metal-to-plastic conversion timelines in Turkish structural component supply chains. Material-process integration is reshaping how compounders collaborate with tier suppliers on part-performance guarantees.
Hybrid long-glass polypropylene compounds are unifying structural and aesthetic functions in single-material solutions for battery trays and underbody shields. Turkish EV startups specify these grades to eliminate secondary painting operations. The technology is unifying design-for-manufacturing workflows between compounders and OEM engineering teams.
REACH SVHC candidate list expansion is forcing reformulation of plasticizers and flame retardants in interior compounds. Turkish compounders face inventory obsolescence risk as substance restrictions accelerate. Headlamp polycarbonate grades containing legacy brominated retardants face the most immediate substitution pressure.
Consolidated supplier agreements are replacing spot purchasing for engineered polymers among Istanbul-based Tier-1 seating and dashboard manufacturers. Multi-year volume commitments with technical collaboration clauses displace transactional procurement. This pattern is most visible in relationships between domestic compounders and Renault and Fiat-Tofaş supply chain managers.
Turkey Automotive Plastic Compounding Market Segmentation
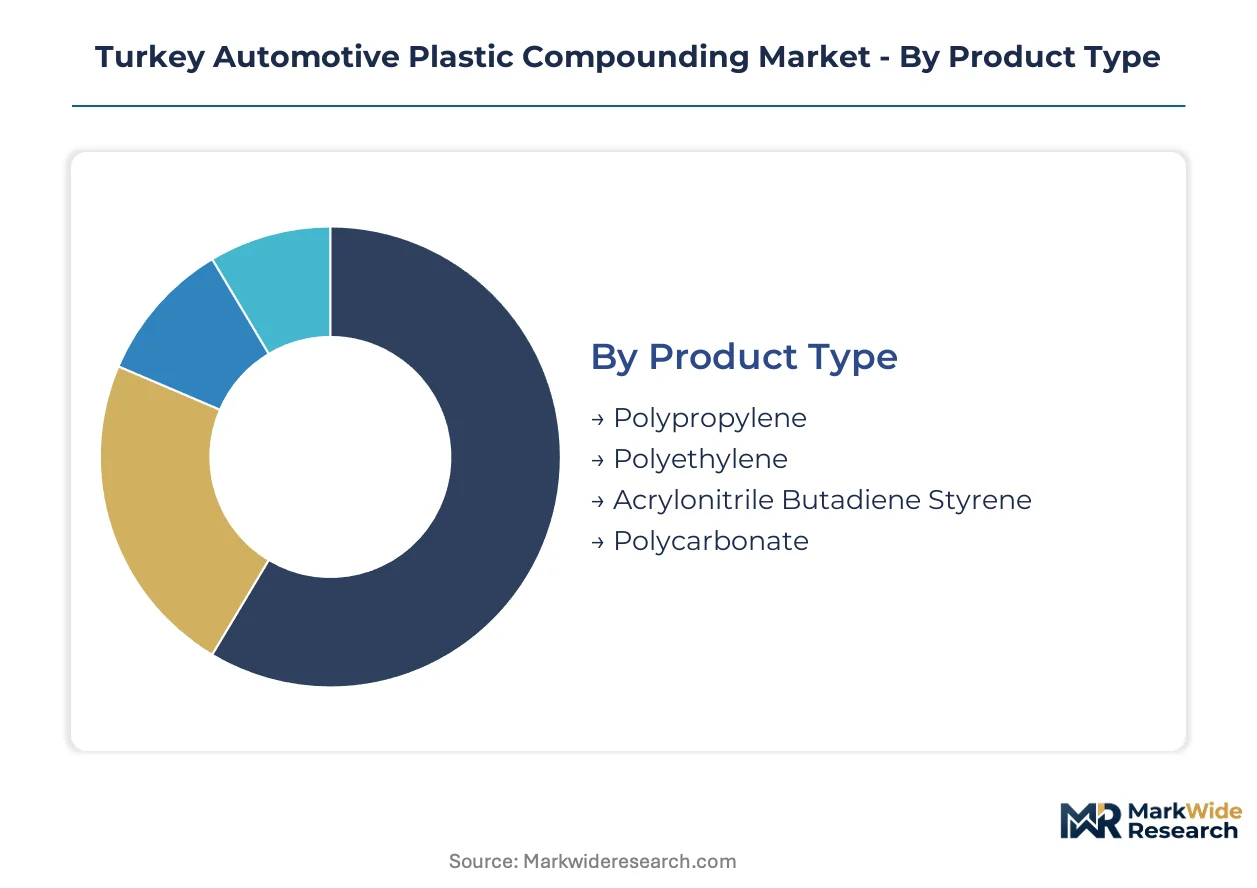
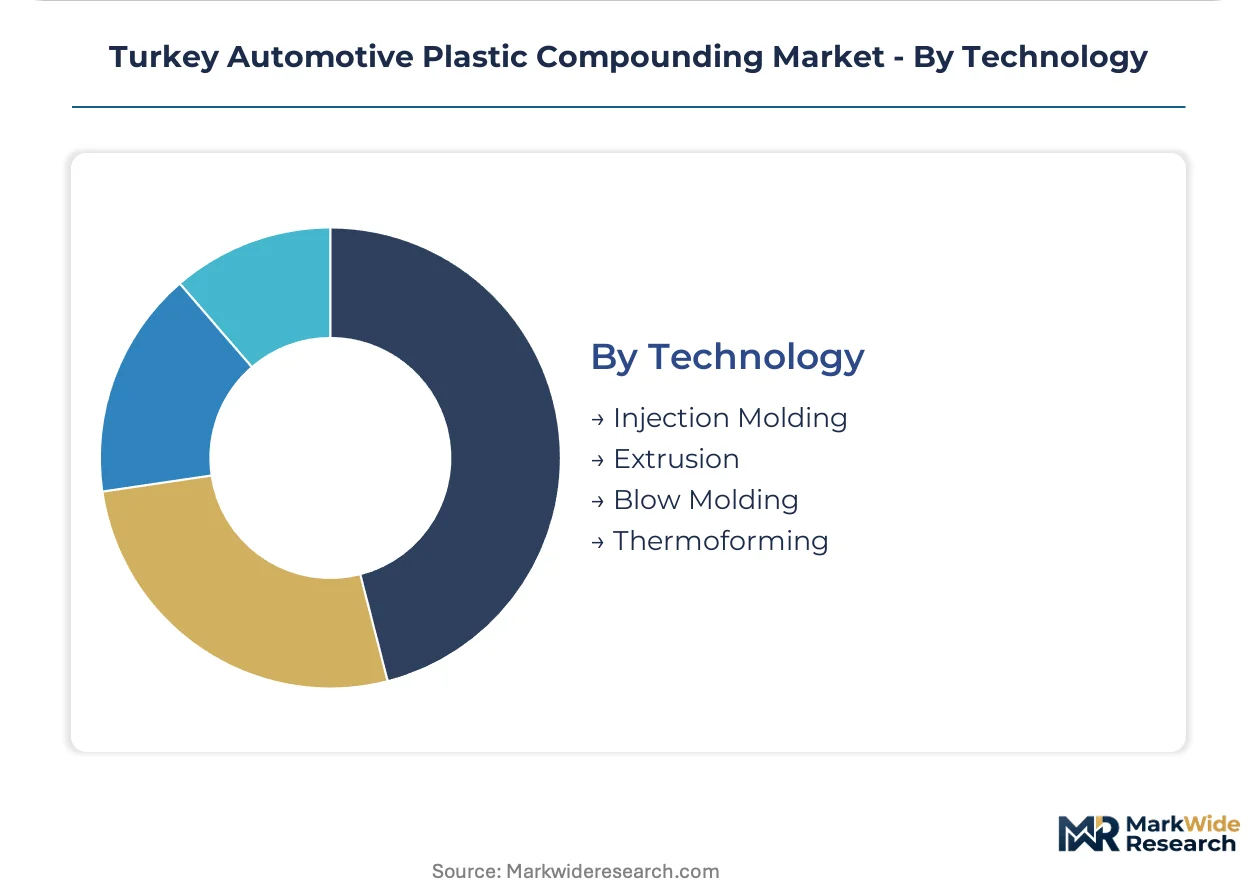
Turkish automotive plastic compounding segments reflect distinct technical specifications, processing requirements, and supply chain relationships. Material selection and conversion technology choices directly influence qualification timelines with Istanbul and Bursa vehicle assemblers.
Product Type:
Material specifications for Turkish EV platforms prioritize heat resistance and lightweighting performance across compounded resin families.
- Polypropylene:Glass-reinforced and mineral-filled grades achieve heat deflection temperatures above 140°C for battery enclosures. Demand concentrates in Bursa automotive clusters serving Renault and Fiat-Tofaş assembly lines, driven by Aliaga petrochemical complex feedstock integration.
- Polycarbonate:High-clarity compounds with halogen-free flame retardants meet headlamp housing specifications. Turkish OEMs specify these grades for glazing applications where optical properties and impact resistance converge, though REACH SVHC list expansion forces reformulation cycles.
- Polyethylene:Rotational molding and blow molding grades serve fuel tank and fluid reservoir applications with chemical resistance requirements.
- Acrylonitrile Butadiene Styrene:ABS compounds deliver surface aesthetics for interior trim with colorimetric matching capabilities.
Mature deployment sits with polypropylene across established vehicle platforms. Newer deployment is concentrated in polycarbonate compounds for electrified model lines.
Application:
Functional requirements and regulatory exposure vary sharply between passenger-facing and under-the-hood component categories.
- Interior Components:Dashboard assemblies, door panels, and seating substrates demand low-VOC emission profiles exceeding Turkish Standards Institution cabin air quality protocols. Istanbul-based Tier-1 suppliers consolidate procurement around compounders with spectrophotometric formulation capabilities for body-color matching.
- Functional Parts:Structural brackets, cooling module tanks, and HVAC housings unify mechanical load-bearing with chemical resistance. These specifications are climbing fastest among Turkish EV startups seeking metal-to-plastic conversion in battery tray assemblies.
- Exterior Components:Bumper fascias and body panels require weathering resistance and paint adhesion properties for integrated styling.
- Engine Components:Under-the-hood applications specify thermal stability above 150°C sustained operating temperatures.
Procurement consolidation is most advanced in interior components. Functional parts exhibit the steepest expansion trajectory as electrification redefines thermal management requirements.
End User:
Customer type determines volume scale, technical collaboration intensity, and inventory responsibility allocation.
- OEMs:Direct material specifications from Turkish vehicle assemblers increasingly mandate Turkish Standards Institution certification and REACH compliance documentation. These relationships feature multi-year volume commitments with embedded technical collaboration clauses.
- Tier-1 Suppliers:Seating, dashboard, and lighting system manufacturers in Istanbul industrial corridors consolidate engineered polymer procurement around domestic compounders.
- Vehicle Assemblers:Contract manufacturing operations prioritize supply security and qualification speed over formulation customization.
- Aftermarket Providers:Collision repair and replacement part distributors focus on color-matched compounds with compressed lead times.
Long-term agreements dominate OEM procurement. Aftermarket channels show the most price sensitivity and spot purchasing behavior.
Technology:
Processing method selection shapes compound formulation parameters including melt flow index, filler orientation, and surface finish requirements.
- Injection Molding:Dominates interior and exterior component production with cycle time efficiency and dimensional precision. Long-fiber thermoplastic grades for structural applications require specialized screw designs and process window optimization.
- Extrusion:Gains share in bumper fascia, sealing profiles, and sheet applications where continuous production economics outperform discrete molding.
- Blow Molding:Serves fluid containment applications including fuel tanks and washer reservoirs with blow ratio and wall thickness control.
- Thermoforming:Processes extruded sheet into large-format interior panels and exterior cladding with lower tooling investment than injection alternatives.
Equipment utilization is highest for injection molding across Bursa supplier parks. Extrusion capacity is expanding fastest to serve sealing and glazing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Aliaga petrochemical complex anchors Turkey's automotive plastic compounding supply base. Domestic propylene feedstock integration reduces import exposure for Bursa and Istanbul compounders. Industrial corridor concentration shapes regional competitive dynamics across Marmara and Mediterranean zones.
Marmara Region
Glass-reinforced polypropylene demand for battery enclosures concentrates in Bursa automotive clusters. Turkish Standards Institution certification requirements tighten material traceability for Renault and Fiat-Tofaş supply chains. Istanbul industrial corridors host Tier-1 seating and dashboard manufacturers consolidating procurement around domestic compounders.
Aegean Region
Izmir-based suppliers serve fluid reservoir and rotational molding applications with polyethylene compounds. REACH compliance documentation requirements from EU export markets drive reformulation investments. Aliaga petrochemical complex feedstock integration benefits compounders serving western Anatolian automotive supplier parks.
Mediterranean Region
Adana-Mersin corridor development attracts greenfield compounding capacity targeting Levant export markets. Halogen-free flame retardant specifications for interior components accelerate technical qualification timelines. Emerging automotive supplier parks offer proximity advantages for Middle Eastern vehicle assembler contracts.
Central Anatolia Region
Ankara-based research institutions collaborate with compounders on heat-deflection temperature improvements for EV thermal management. Konya automotive component manufacturers source mineral-filled polypropylene for interior substrates. Regional vocational training programs address spectrophotometric formulation capability gaps.
Turkey Automotive Plastic Compounding Market Key Industry Players
Capacity expansion dominates the current landscape as domestic compounders respond to EV platform procurement consolidation. The market structure features integrated petrochemical producers alongside independent specialty compounders serving niche specification tiers. Three strategic archetypes anchor competitive positioning: captive resin producers with backward feedstock control, independent engineering polymer specialists, and distribution-technical service hybrids. Geographic expansion into Mediterranean supplier corridors and portfolio diversification toward recycled-content grades represent the dominant competitive moves.
Among domestic resin-integrated producers, Petkim Petrokimya Holding A.Ş. anchors supply security through Aliaga complex feedstock capture. Independent engineering polymer specialists exemplified by EPSAN occupy positions in reinforced nylon compounds for under-the-hood functional applications. Thermoplastic elastomer expertise concentrates with Elastron TPE, representing the soft-touch formulation archetype for interior haptics specifications.
| Leading Market Players |
|---|
| Elastron TPE |
| EPSAN |
| Petkim Petrokimya Holding A.Ş. |
| ALBIS Distribution GmbH und Co. KG |
| MASKOM Plastik San. ve Tic. Ltd. Şti. |
| Alfa Polimer İnovasyon Plastik A.Ş. |
| Pimar-Plastics Limited |
| Tosaf |
| Tisan Mühendislik Plastikleri San. Tic. Ltd. Şti. |
| Others |
Cost & Logistics Intelligence
Spectrophotometric formulation specialists concentrated in Bursa and Istanbul command wage premiums that compress pricing spreads between premium body-color compounds and standard interior grades. Labor-cost differentials between these industrial corridors and emerging Adana-Mersin facilities create arbitrage opportunities for volume buyers seeking REACH-compliant material at lower landed cost.
Pricing Analysis
Technical service bundling separates premium compounders from transactional suppliers, with Turkish Standards Institution certification support and colorimetric matching included in long-term agreements but unbundled in spot transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with OEM direct contracts showing lowest price sensitivity and aftermarket channels absorbing maximum margin compression. Cost compression in economy-tier polypropylene is intensifying because Aliaga complex feedstock integration has not fully propagated to specialty nylon grades. Tier-1 seating manufacturers exhibit least price sensitivity due to consolidated procurement mandates, while independent molders in Central Anatolia remain most exposed to euro-denominated engineered resin volatility.
Supply Chain Analysis
Specialty nylon and PBT feedstock rests on German and Belgian petrochemical producers, exposing Turkish compounders to currency fluctuation and logistics disruption. Base polypropylene draws from domestic Aliaga complex integration, while polycarbonate and ABS resins source from South Korean and Chinese suppliers. Single-source vulnerability concentrates in halogen-free flame retardant additives, where REACH SVHC list expansion accelerates inventory obsolescence cycles. Distribution runs through Istanbul-based technical distributors serving Bursa automotive clusters, with direct mill relationships gaining share among large-volume OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkish automotive plastic compounding represents a consolidation play as REACH SVHC compliance costs and Turkish Standards Institution certification requirements force sub-scale compounders toward exit. Technical qualification timelines and capital intensity for spectrophotometric capabilities favor integrated players with captive feedstock positions.
For Market Incumbents: Anchor backward integration into Aliaga propylene supply to defend margin position against imported base resin volatility. Expand long-fiber thermoplastic compounding capacity in Bursa corridors to capture EV platform lightweighting specifications from Renault and Fiat-Tofaş engineering teams. Prioritize REACH compliance documentation systems as a barrier against emerging Mediterranean corridor competitors. For New Entrants and Emerging Players: Capture white-space in post-industrial polypropylene recompounding with certified traceability systems serving EU End-of-Life Vehicles Directive pressure on Turkish exporters. Target Adana-Mersin corridor greenfield positions with halogen-free flame retardant formulations for Levant market vehicle assemblers. Pursue formulation partnerships with injection molders seeking soft-touch TPE specifications for interior haptics differentiation. For Investors and Strategic Acquirers: Re-rating potential sits with independent engineering polymer specialists given EV platform procurement consolidation and multi-year volume commitment trends. Long-term viability favors compounders with demonstrated Turkish Standards Institution certification capabilities and backward integration into domestic propylene supply. Watch battery enclosure glass-reinforced polypropylene qualification timelines as inflection indicator for structural market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Aliaga Complex Feedstock Integration | Captive propylene supply reduces euro-denominated import exposure for Bursa compounders serving Renault assembly. |
| Long-Fiber Thermoplastic Capacity Addition | Structural battery tray specifications from Turkish EV startups demand heat-deflection temperatures above 140°C. |
| REACH SVHC Compliance Reformulation | Headlamp polycarbonate grades face immediate substitution pressure from brominated retardant restrictions. |
| Post-Industrial Recompounding Certification | EU End-of-Life Vehicles Directive creates demand for traceable recycled content in export-bound compounds. |
| Spectrophotometric Formulation Partnership | Istanbul Tier-1 suppliers consolidate procurement around compounders with body-color matching capabilities. |
Research Approach
Independent corroboration across Turkish Standards Institution certification databases, Aliaga petrochemical complex production disclosures, and EU REACH registration files underwrites the qualitative findings. Primary interviews with Tier-1 supplier procurement managers, OEM platform engineers, and compounder technical directors combined with secondary validation from customs trade data, SEC filings of multinational resin suppliers, and vehicle production databases. Bottom-up volume estimates triangulated against top-down resin consumption models across the analysis window.
Comparable-period anchoring to historical automotive production cycles and polymer consumption patterns shaped the projection horizon calibration. Segmentation dimensions modeled include resin family, vehicle application category, propulsion architecture, and regional production cluster. CAGRs derived from regression analysis of feedstock cost pass-through elasticities and OEM platform material specification trends, with EV content-per-vehicle assumptions and Turkish export market exposure as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal regulatory acceleration and crude derivative volatility. Forecasts reflect documented assumptions around Aliaga complex capacity expansion timing and REACH SVHC list revision frequency. A small set of triggers—battery enclosure material specification shifts, Turkish lira volatility against euro-denominated engineered resin contracts, and Mediterranean corridor infrastructure completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Brackets Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Air Intake Manifold Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive V-Belts Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Global Automotive Water Separation Systems Market