
 Africa and Middle East Automotive Pneumatic Actuators Market | 2026-2036
Africa and Middle East Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Automotive Pneumatic Actuators Market Outlook
Aluminum is decoupling from traditional cast-iron housings in pneumatic actuator construction, cutting unit weight and improving thermal response in underhood installations. Continental AG leverages its regional tire and brake electronics footprint to bundle actuator sales with chassis control systems across North African assembly plants. Bosch Rexroth AG anchors its position through localized valve-manifold production that shortens lead times for Saudi commercial vehicle builders. SMC Corporation competes on standardized cylinder bore ranges that simplify maintenance protocols for fleet operators in South Africa.
Automotive pneumatic actuators convert compressed air into linear or rotary mechanical motion, typically operating at pressures between 0.4 and 1.0 MPa to actuate brakes, clutch mechanisms, and suspension leveling systems in commercial and passenger vehicles. Double acting actuators dominate volume demand because their bidirectional force output suits heavy-truck brake caliper retraction and automated manual transmission clutch engagement. OEMs capture the largest value share as vehicle manufacturers in Morocco and Egypt integrate pneumatic modules directly into platform designs during assembly. The aftermarket provider channel is expanding fastest as aging commercial fleets in Nigeria and Kenya extend service intervals through component replacement rather than full-system overhaul.
Saudi Arabia's SASO mandates crashworthiness and environmental durability testing for pneumatic safety components, while South Africa's NRCS enforces SABS automotive standards that govern actuator cycle-life certification. The UAE's MOIAT conformity assessment requirements for industrial equipment imports create a gatekeeping function that favors suppliers with pre-certified test documentation. Stakeholders must monitor how Egypt's GOEIC import inspection protocols and evolving local-content rules reshape sourcing economics for actuator assemblies destined for North African vehicle plants.
Market Dynamics
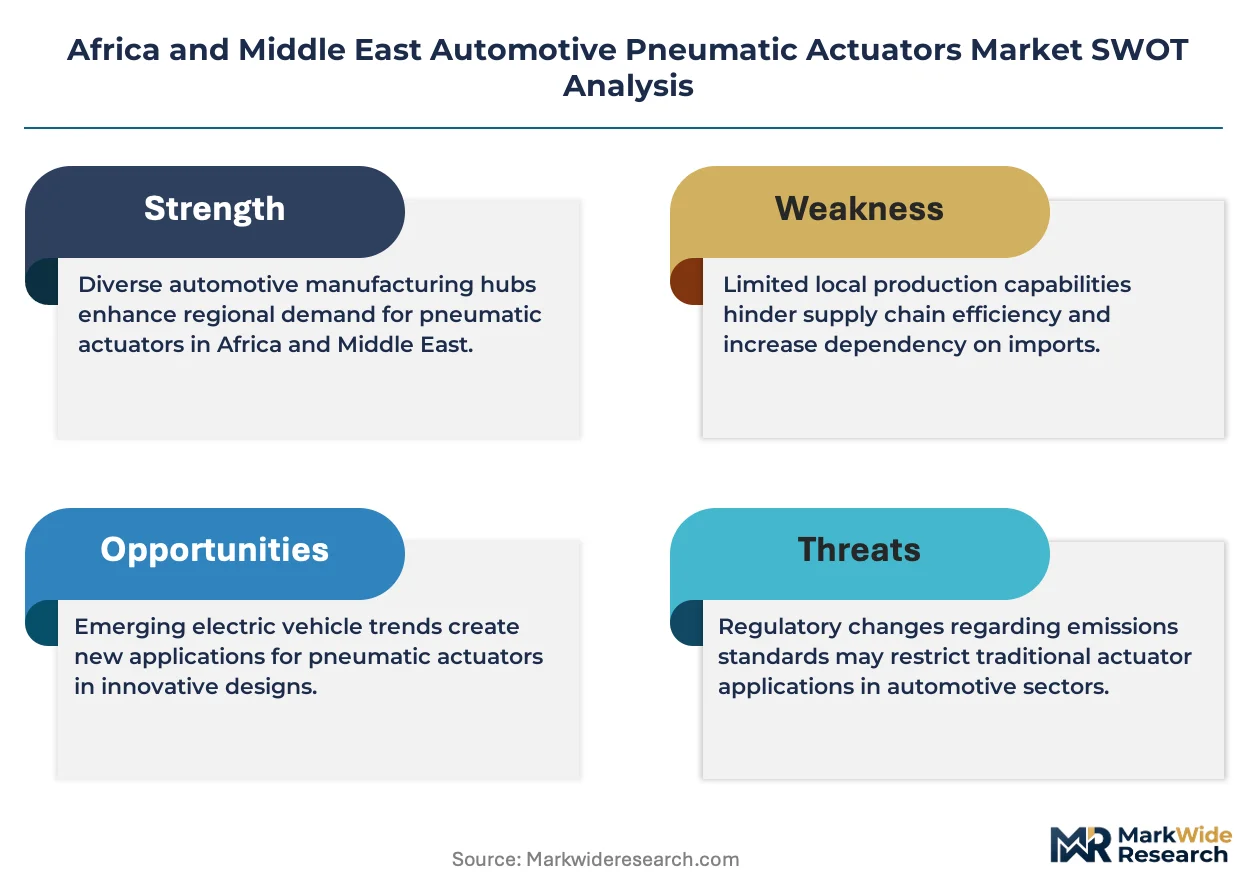
Aluminum housing adoption is compressing unit weights and accelerating thermal cycling performance for underhood pneumatic modules across Gulf commercial vehicle production.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's tightening crashworthiness mandates for pneumatic safety components are forcing fleet-wide actuator upgrades in heavy-duty braking systems.
- Aluminum Die-Casting:Regional foundries in the UAE are scaling high-pressure die-cast aluminum actuator housings that cut thermal mass and improve response times.
- Dubai-Jebel Ali Corridor:Assembly plant concentration in this manufacturing cluster is generating localized demand pull for integrated pneumatic chassis modules.
Market Restraints
- Silicone Sealant Cost Volatility:Fluctuating petrochemical feedstock prices for high-temperature diaphragm materials are squeezing margin structures on replacement actuator kits.
- Single-Source Valve Manifolds:Concentrated supply of precision-machined manifold blocks from German and Japanese tier-2 suppliers creates vulnerability for North African vehicle builders.
- Compressed Air Infrastructure Gaps:Inconsistent shop air pressure standards across Nigerian and Kenyan maintenance facilities limit reliable actuator performance in aftermarket service.
Strategic Opportunities
- Egyptian Local-Content Rules:GOEIC import inspection protocols favor actuator assemblies with rising Egyptian-manufactured content share, incentivizing joint ventures near Suez Canal industrial zones.
- Electro-Pneumatic Hybrid Actuation:Convergence of traditional pneumatic force generation with electronic position sensing is opening precision control applications in automated manual transmissions.
- Direct Fleet Procurement Platforms:Digital B2B marketplaces are disintermediating traditional parts distributors for South African mining and logistics fleet operators.
Industry Challenges
- Pneumatic Technician Shortage:Compressed air system diagnostics and seal refurbishment skills are scarce across North African independent repair networks.
- SABS Cycle-Life Certification Timelines:South Africa's NRCS testing protocols for actuator durability validation extend product qualification cycles by eight to fourteen months.
- Legacy Brake System Integration:Retrofitting modern double-acting actuators into older single-circuit air brake architectures requires custom adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Automotive Pneumatic Actuators Market |
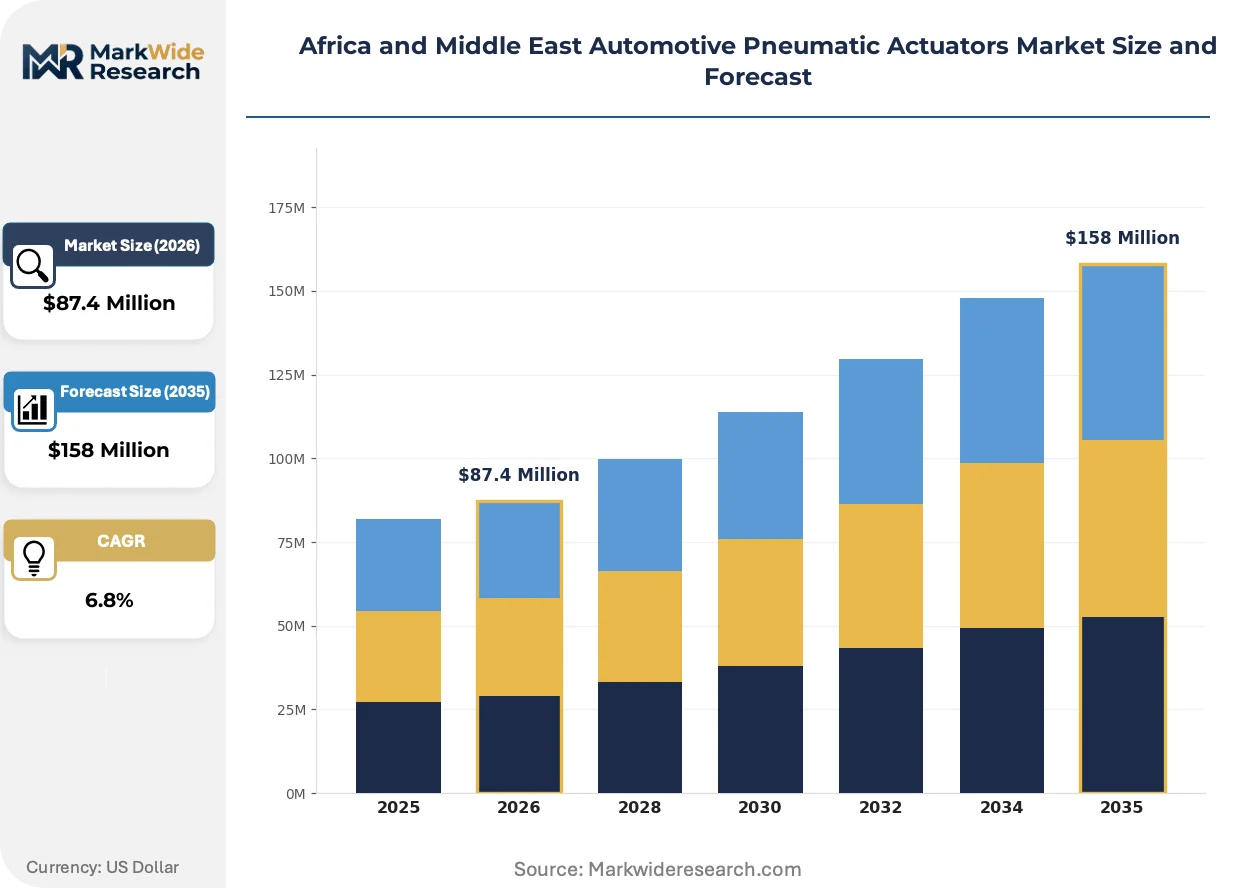
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Acting, Single Acting, Rotary, Vacuum End User: OEMs, Aftermarket Providers, Dealerships, Tier-1 Suppliers Operation Mechanism: Direct, Indirect, Proportional, Automated Installation Type: Fixed, Portable, Integrated, Modular |
| Companies Covered | Emerson Electric Co, Continental AG, Bosch Rexroth AG, SMC Corporation, Denso Corporation, Nidec Corporation, ZF Friedrichshafen AG, Robert Bosch GmbH, Hydrofit Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Automotive Pneumatic Actuators Market Strategic Shifts
Material substitution and regulatory digitization are rewriting actuator specification sheets across regional vehicle platforms. Procurement patterns are fragmenting as fleet operators gain direct supplier access.
Aluminum alloy housings with integrated cooling fins are overtaking traditional cast-iron shells in high-cycling brake actuator applications. Saudi commercial vehicle assemblers are specifying these units for desert thermal conditions. The shift is compressing supplier qualification timelines as foundries prove die-cast repeatability.
SASO's electronic conformity tracking system now mandates digital test documentation uploads for pneumatic safety components entering Saudi Arabia. Industrial consequence includes pre-certification cost burdens for smaller tier-2 suppliers. North African export-oriented plants are responding by consolidating testing under regional third-party laboratories.
Fleet maintenance managers are unbundling actuator replacement from full brake system overhauls, purchasing individual cylinders and seal kits through direct channels. Traditional parts distributors in Kenya and Nigeria are losing volume to manufacturer-direct e-procurement portals. This pattern is most visible in long-haul trucking segments where downtime costs dominate supplier selection.
Africa and Middle East Automotive Pneumatic Actuators Market Segmentation
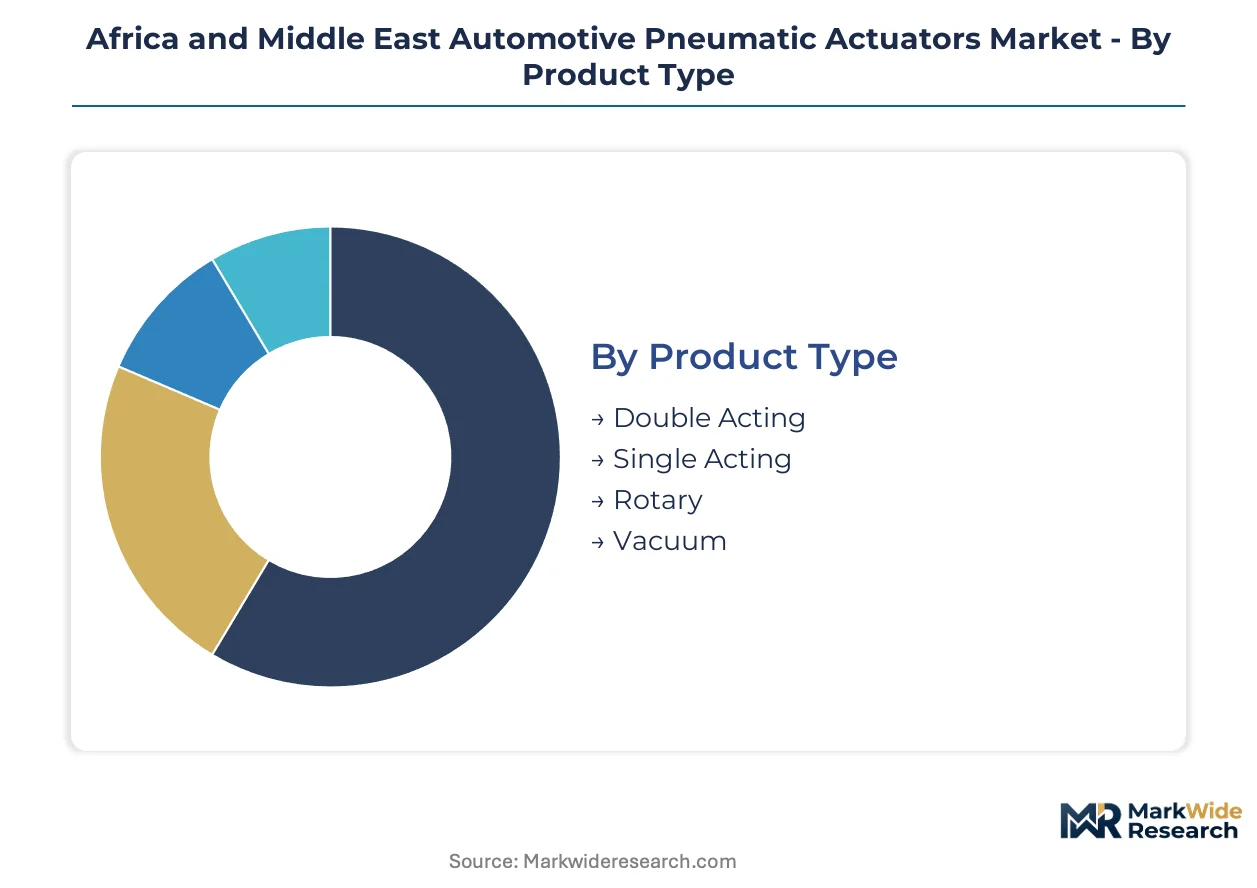
Actuator specification in the Africa and Middle East market fragments across four structural dimensions. Each dimension carries distinct capital requirements, margin profiles, and regulatory exposure that shape supplier positioning across Saudi, UAE, Egyptian, and South African demand centers.
Product Type:
Capital intensity peaks with rotary and proportional-control variants requiring precision-machined gear trains and position-feedback electronics. Die-cast aluminum housing investments dominate double-acting cylinder production at regional foundries.
- Double Acting:Bidirectional force output suits heavy-truck brake caliper retraction and automated manual transmission clutch engagement. Fleet operators across the Gulf Cooperation Council specify these units for desert thermal cycling durability under SASO crashworthiness mandates.
- Single Acting:Spring-return mechanisms reduce component count and maintenance complexity in light-commercial parking brake applications. Nigerian and Kenyan aftermarket channels favor these units for retrofitting legacy single-circuit air brake architectures where shop air pressure consistency remains problematic.
- Rotary:Rack-and-pinion or vane configurations convert linear pneumatic pressure into angular motion for throttle and HVAC damper control. Lower volume demand concentrates in premium passenger vehicle assembly near Casablanca and Tunis.
- Vacuum:Engine manifold pressure differential drives brake booster diaphragms in light-duty applications. Egyptian GOEIC import protocols subject these assemblies to rising local-content scrutiny.
Double Acting absorbs the bulk of installed capacity; Vacuum is expanding most quickly as Egyptian vehicle plants source brake boosters with rising domestic value-add.
End User:
Customer-type segmentation reveals divergent procurement rhythms and technical specification authority. OEM integration decisions lock in platform designs years ahead of production, while aftermarket channels respond to fleet aging patterns and regulatory enforcement waves.
- OEMs:Vehicle manufacturers in Morocco and Egypt integrate pneumatic modules directly into platform designs during assembly. SASO pre-certification requirements and SABS cycle-life testing extend qualification timelines, favoring suppliers with established regional test documentation.
- Aftermarket Providers:Component replacement demand from aging commercial fleets in Nigeria and Kenya is climbing the fastest as operators unbundle actuator service from full-system overhaul. Digital B2B procurement platforms are disintermediating traditional parts distributors.
- Dealerships:Authorized service networks handle warranty-period actuator replacement under manufacturer service contracts. Volume concentrates in South African mining and logistics fleet maintenance.
- Tier-1 Suppliers:Chassis system integrators in the Dubai-Jebel Ali corridor bundle pneumatic actuators with brake electronics and suspension modules for regional vehicle assembly.
OEMs dominate current value capture; Aftermarket Providers show the steepest expansion trajectory as fleet replacement cycles compress across Sub-Saharan Africa.
Operation Mechanism:
Control sophistication determines electronics content and software validation burden. Direct-acting mechanisms minimize subsystem integration cost; automated variants require sensor fusion and control algorithm development.
- Direct:Pneumatic pressure applies force without intermediate mechanical advantage stages. Saudi heavy-duty brake actuators deploy this architecture for reliability under high-cycle desert operation.
- Indirect:Leverage mechanisms amplify force output for clutch engagement in mid-duty commercial vehicles. South African assembly plants source these units from localized valve-manifold producers.
- Proportional:Pressure-modulating valves enable variable force output for precision suspension leveling. Electro-pneumatic hybrid architectures are gaining share fastest in automated manual transmission applications.
- Automated:Closed-loop position control with electronic feedback enables autonomous chassis functions. UAE MOIAT conformity assessment creates pre-certification barriers for non-regional suppliers.
Direct mechanisms retain the largest installed base; Proportional control is climbing the fastest as transmission electrification demands precision actuation.
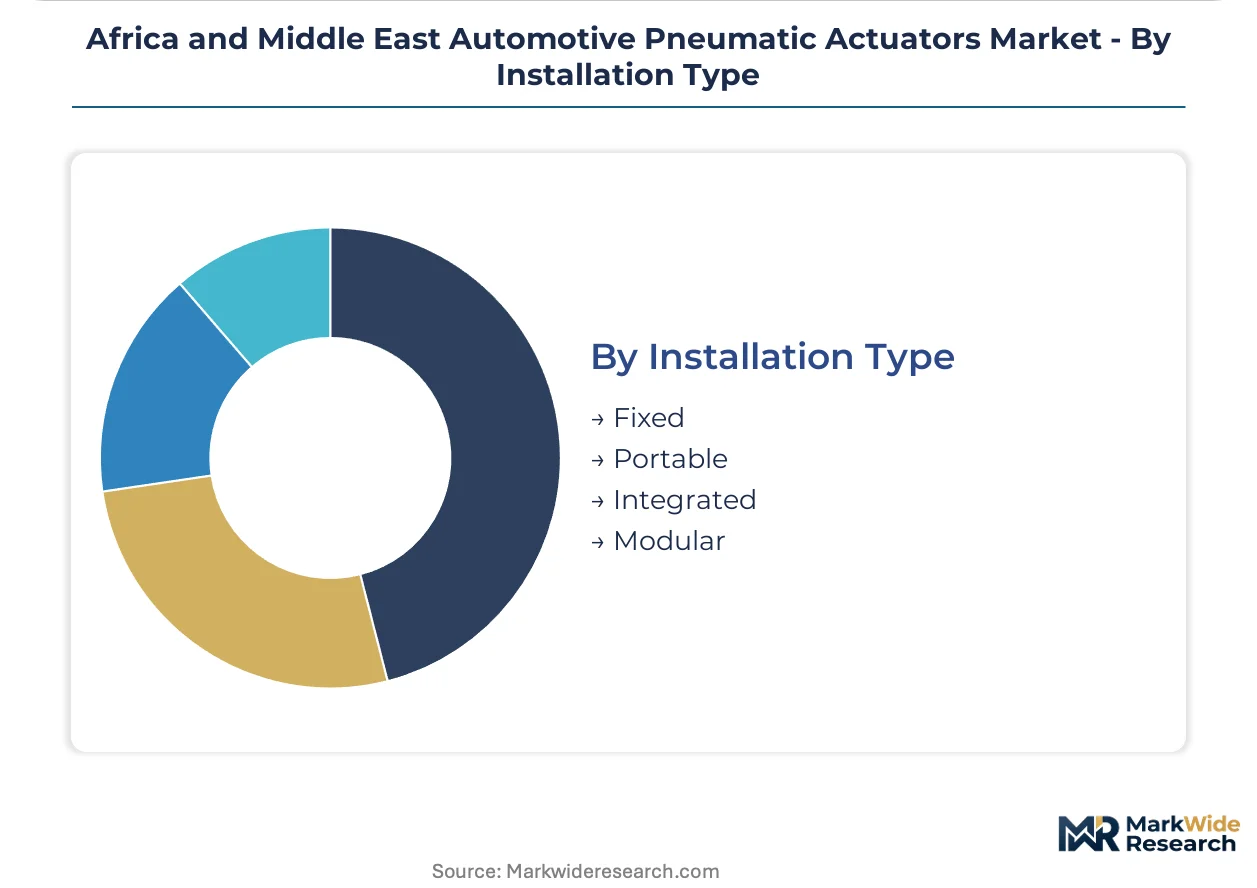
Installation Type:
Mounting configuration shapes thermal management, service accessibility, and platform design flexibility. Fixed installations dominate high-vibration underhood environments; modular approaches enable field reconfiguration.
- Fixed:Permanent bracket mounting secures actuators in brake and clutch applications where vibration resistance is critical. Cast-iron housing variants still predominate in this category despite aluminum substitution trends.
- Portable:Quick-disconnect fittings enable temporary actuator deployment in maintenance and diagnostic applications. Limited automotive adoption concentrates in service equipment rather than vehicle-integrated systems.
- Integrated:Actuator functions embedded within larger chassis modules reduce plumbing complexity. Dubai-Jebel Ali assembly plants specify integrated pneumatic-electronic units for regional light-commercial production.
- Modular:Standardized interface dimensions enable cylinder and valve interchange without system redesign. Fleet operators in South Africa favor this architecture for simplified spare parts logistics across mixed-vintage truck populations.
Fixed installations command the majority of current deployment; Modular configurations are gaining share fastest as fleet standardization priorities reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle fleet operators across the Gulf Cooperation Council are driving concentrated demand for heavy-duty braking and suspension actuators. Assembly plant clustering in strategic manufacturing corridors is reshaping supplier logistics and localization incentives.
Saudi Arabia
SASO technical regulations for automotive safety components are tightening compliance requirements for pneumatic systems. Fleet-wide actuator upgrades in heavy-duty braking systems are accelerating as crashworthiness mandates take effect. Riyadh-based commercial vehicle assemblers are qualifying new aluminum-housing suppliers for desert thermal cycling applications.
United Arab Emirates
High-pressure die-cast aluminum actuator housings from regional foundries are cutting thermal mass and improving response times. MOIAT conformity assessment requirements for industrial equipment imports favor suppliers with pre-certified test documentation. The Dubai-Jebel Ali manufacturing corridor is generating localized demand pull for integrated pneumatic chassis modules.
Egypt
GOEIC import inspection protocols and evolving local-content rules are reshaping sourcing economics for actuator assemblies. Rising Egyptian-manufactured content share is incentivizing joint ventures near Suez Canal industrial zones. Vehicle plants in the Greater Cairo region are consolidating pneumatic module testing under regional third-party laboratories.
South Africa
NRCS enforcement of SABS automotive standards governs actuator cycle-life certification for regional supply. Extended product qualification cycles of eight to fourteen months are favoring established suppliers with existing test documentation. Mining and logistics fleet operators are migrating toward manufacturer-direct e-procurement portals for replacement components.
Nigeria
Aging commercial fleets are extending service intervals through component replacement rather than full-system overhaul. Inconsistent shop air pressure standards across maintenance facilities limit reliable actuator performance in aftermarket service. Lagos-based long-haul trucking operators are unbundling actuator replacement from full brake system overhauls through digital procurement channels.
Africa and Middle East Automotive Pneumatic Actuators Market Competitive Environment
Strategic partnerships dominate the current landscape as suppliers position for regulatory pre-certification and localized production. The vendor base clusters around three tiers: diversified industrial conglomerates with chassis system integration capabilities, specialized pneumatic component manufacturers with standardized product ranges, and regional fabricators serving aftermarket replacement demand. Two strategic archetypes are consolidating share: integrated brake-and-chassis module suppliers leveraging OEM relationships, and maintenance-focused specialists capturing fleet replacement cycles. Geographic expansion into Egyptian industrial zones and portfolio diversification toward electro-pneumatic hybrid architectures represent the dominant competitive vectors.
Within the diversified industrial tier, Continental AG and Bosch Rexroth AG exemplify scale-driven positioning anchored by regional manufacturing footprints. SMC Corporation occupies a distinct position among standardized cylinder specialists competing on maintenance protocol simplicity for fleet operators. Denso Corporation and ZF Friedrichshafen AG sit within the chassis integration archetype, representing the convergence of pneumatic actuation with electronic control systems. These five entities collectively span the value chain from precision-machined valve manifolds to fully integrated pneumatic-electronic modules, with each anchoring a distinct competitive position without overlapping strategic territory.
| Leading Market Players |
|---|
| Emerson Electric Co |
| Continental AG |
| Bosch Rexroth AG |
| SMC Corporation |
| Denso Corporation |
| Nidec Corporation |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Hydrofit Group |
| Others |
Value Chain & Pricing Dynamics
Captive die-cast aluminum production at UAE foundries anchors both supply security and pricing leverage for pneumatic actuator assemblers serving Gulf commercial vehicle builders. This backward integration into high-pressure housing manufacturing compresses thermal mass advantages into cost structures while insulating margin positions from petrochemical feedstock volatility in silicone sealant markets.
Pricing Analysis
Volume concentration in double-acting brake actuators compresses margins at the commodity end, while precision proportional-control variants retain pricing power through embedded electronics content. Three-tier pricing structure across premium, standard, and economy levels separates SASO-certified aluminum housings from cast-iron legacy units and unbranded aftermarket kits. Pricing pressure stems from silicone diaphragm material cost volatility squeezing replacement kit profitability. Fleet operators in Nigeria and Kenya exhibit highest price sensitivity, whereas Saudi OEMs prioritize thermal cycling certification over unit cost.
Supply Chain Analysis
Egyptian GOEIC local-content mandates are forcing actuator assemblers to requalify valve-manifold suppliers with rising Egyptian-manufactured content share. Precision-machined manifold blocks draw from German and Japanese tier-2 sources, while aluminum die-casting feeds from UAE and Egyptian foundries. Single-source vulnerability concentrates in high-tolerance valve machining capacity. Distribution runs through Dubai-Jebel Ali logistics hubs for regional OEM supply, with direct digital procurement disintermediating traditional parts distributors in South African aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-pneumatic hybrid architectures are displacing pure pneumatic control in automated manual transmission applications, compressing the window for legacy actuator technology investment across the Africa and Middle East vehicle production base.
For Market Incumbents: Cement SASO pre-certification advantages by consolidating testing documentation under regional third-party laboratories before Egyptian GOEIC rules tighten further. Deepen backward integration into aluminum die-casting capacity near Suez Canal industrial zones to defend margin positions against silicone sealant cost volatility. Prioritize valve-manifold localization to mitigate single-source supply vulnerability from German and Japanese tier-2 suppliers. For New Entrants and Emerging Players: Launch via direct digital procurement platforms targeting South African mining and logistics fleet operators unbundling actuator replacement from full brake system overhauls. The most penetrable white-space sits in modular standardized cylinder ranges for mixed-vintage truck populations where maintenance protocol simplicity commands premium positioning. Pursue electro-pneumatic hybrid development partnerships with Dubai-Jebel Ali chassis integrators seeking precision transmission actuation capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified industrial conglomerates seeking chassis system integration capabilities. Long-term viability hinges on electro-pneumatic hybrid technology transition completion rather than pure pneumatic legacy positioning. The signal to watch is SASO digital conformity tracking system adoption velocity as smaller tier-2 suppliers face pre-certification cost burdens that consolidate vendor share toward documented regional players.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Die-Casting Localization | UAE and Egyptian foundry investments cut thermal mass and improve desert cycling performance for SASO compliance. |
| Electro-Pneumatic Hybrid Development | Convergence of pneumatic force with electronic sensing opens automated manual transmission precision control applications. |
| Direct Fleet Procurement Platforms | Digital B2B marketplaces disintermediate traditional distributors for South African mining and logistics operators. |
| Regional Third-Party Testing Consolidation | North African export plants centralize SASO and SABS certification under localized laboratories to compress qualification timelines. |
| Valve-Manifold Supply Diversification | Joint ventures near Suez Canal zones reduce single-source dependency on German and Japanese precision machining capacity. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance directors combined with SASO technical documentation, Egyptian GOEIC import protocols, SABS automotive standards, and vehicle production databases. Bottom-up actuator shipment estimates triangulated against top-down commercial vehicle production forecasts across the analysis window.
Data-stream reconciliation aligned production volume estimates with regulatory certification timelines and raw material trade flows. Segmentation modeling spanned product type, end user category, operation mechanism sophistication, and installation configuration across regional production clusters. CAGRs derived from regression analysis of historical shipment patterns and projected fleet replacement cycles. Industry-specific forecast inputs included SASO crashworthiness mandate enforcement schedules and Egyptian local-content rule phase-in trajectories.
The model assumes a particular technology adoption path; alternative pathways for electro-pneumatic hybrid architectures would alter the outlook if transmission electrification accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and fleet operator procurement behavior shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Commutator Market
Automotive Components
Polyamide in E-Mobility Market
Automotive Components
Europe Automotive Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
North America Automotive Glass Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Automotive Catalyst Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Bushing Market
Automotive Components
Automotive Key Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Japan Automotive Actuators Market