
 China Automotive Electric Power Steering (EPS) Market | 2026-2036
China Automotive Electric Power Steering (EPS) Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive Electric Power Steering (EPS) Market Insights
Passenger vehicle electrification is expanding faster than commercial fleet retrofit cycles, tilting procurement volumes toward integrated smart-steering platforms. JTEKT Corporation leverages its column-assist heritage to anchor supply relationships with legacy joint-venture brands. Nexteer Automotive competes through brushless motor specialization calibrated for Chinese OEM torque specifications. Robert Bosch GmbH sustains R&D intensity in sensor fusion architectures that merge lane-keeping data with steering rack feedback.
Automotive Electric Power Steering replaces hydraulic pumps with electric motors mounted on the steering column, rack, or pinion, delivering torque assistance through brushless DC drives with response latencies under 50 milliseconds. The technology eliminates engine-belt parasitic losses while enabling variable assist curves tuned by vehicle speed and driver preference. Rack-assist configurations now lead unit shipments among passenger applications where packaging space permits direct gear engagement. Column-assist systems retain dominance in compact vehicle segments where cost thresholds constrain design complexity. Smart steering with integrated ECUs and CAN-bus connectivity represents the fastest-growing technology tier as automakers bundle ADAS preconditioning into steering hardware.
MIIT enforces GB standards governing steering system failure modes and electromagnetic compatibility, while SAMR oversees market-access conformity assessment for replacement parts. These frameworks elevate compliance costs for aftermarket providers but reinforce quality differentiation among certified OEM suppliers. Stakeholders must monitor how NEV platform consolidation and steer-by-wire regulatory readiness reshape supplier qualification timelines.
Market Dynamics
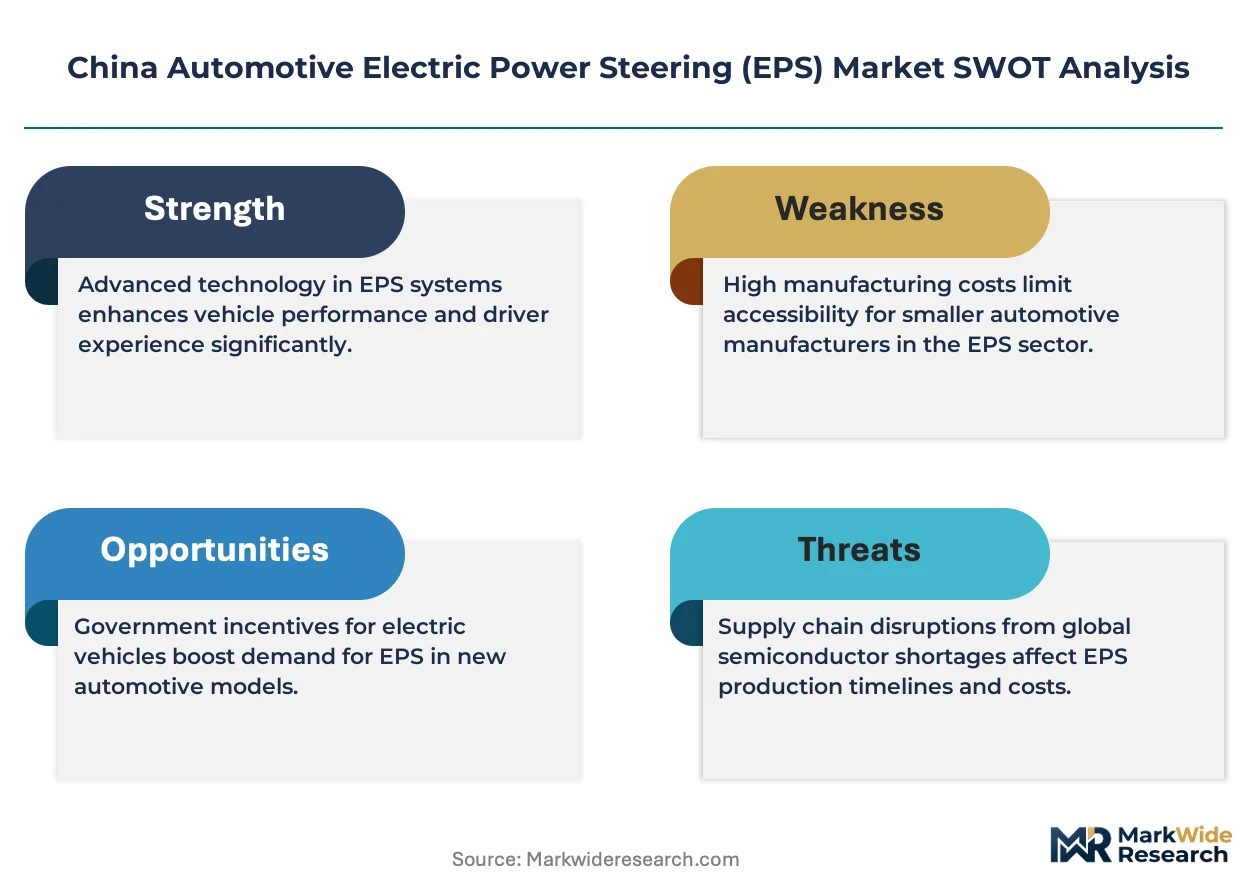
NEV platform consolidation is compressing supplier qualification timelines while MIIT tightens electromagnetic compatibility certification for steering subsystems.
Growth Catalysts
- MIIT fuel-consumption mandates:Stringent corporate average fuel economy targets force ICE vehicle electrification of auxiliary systems. OEMs substitute hydraulic steering with EPS to recover parasitic loss reductions.
- GB standards for steering safety:Mandatory failure-mode testing and electromagnetic compatibility protocols elevate entry barriers for uncertified aftermarket suppliers. Tier-1 incumbents capture expanded replacement-part volumes.
- Yangtze River Delta cluster concentration:Shanghai-Jiangsu-Zhejiang manufacturing density reduces logistics costs for rack-assist EPS assembly. Proximity to NEV final assembly plants accelerates just-in-sequence delivery cycles.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium-iron-boron permanent magnets constitute critical brushless motor inputs. Price swings in dysprosium and terbium feedthrough squeeze motor supplier margins.
- Steer-by-wire regulatory unreadiness:GB standards have not finalized fail-operational requirements for fully electronic steering without mechanical backup. Product roadmaps stall at pre-production validation stages.
- Joint-venture supply lock-in:Legacy Sino-foreign automotive partnerships maintain multi-year EPS sourcing contracts with incumbent Japanese and German tier-1s. Domestic challengers face contract renewal friction.
Strategic Opportunities
- Software-defined steering calibration:Over-the-air torque curve updates enable subscription-based performance tiering. NEV OEMs monetize driver personalization without hardware swaps.
- ADAS preconditioning integration:Lane-keeping assist and automated parking demand predictive steering rack priming. EPS ECUs with sensor fusion architectures command premium positioning.
- Aftermarket smart-retrofit kits:Aging compact vehicle parc creates demand for column-assist EPS upgrades. Certified conversion workshops in tier-2 cities capture service revenue pools.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification for steering systems demands specialized hardware-software integration expertise. Domestic universities produce insufficient qualified graduates.
- Legacy hydraulic service infrastructure:Independent repair shops retain fluid-based steering maintenance capabilities. EPS diagnostic equipment retrofit requires capital outlays that fragment aftermarket service quality.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive Electric Power Steering (EPS) Market |
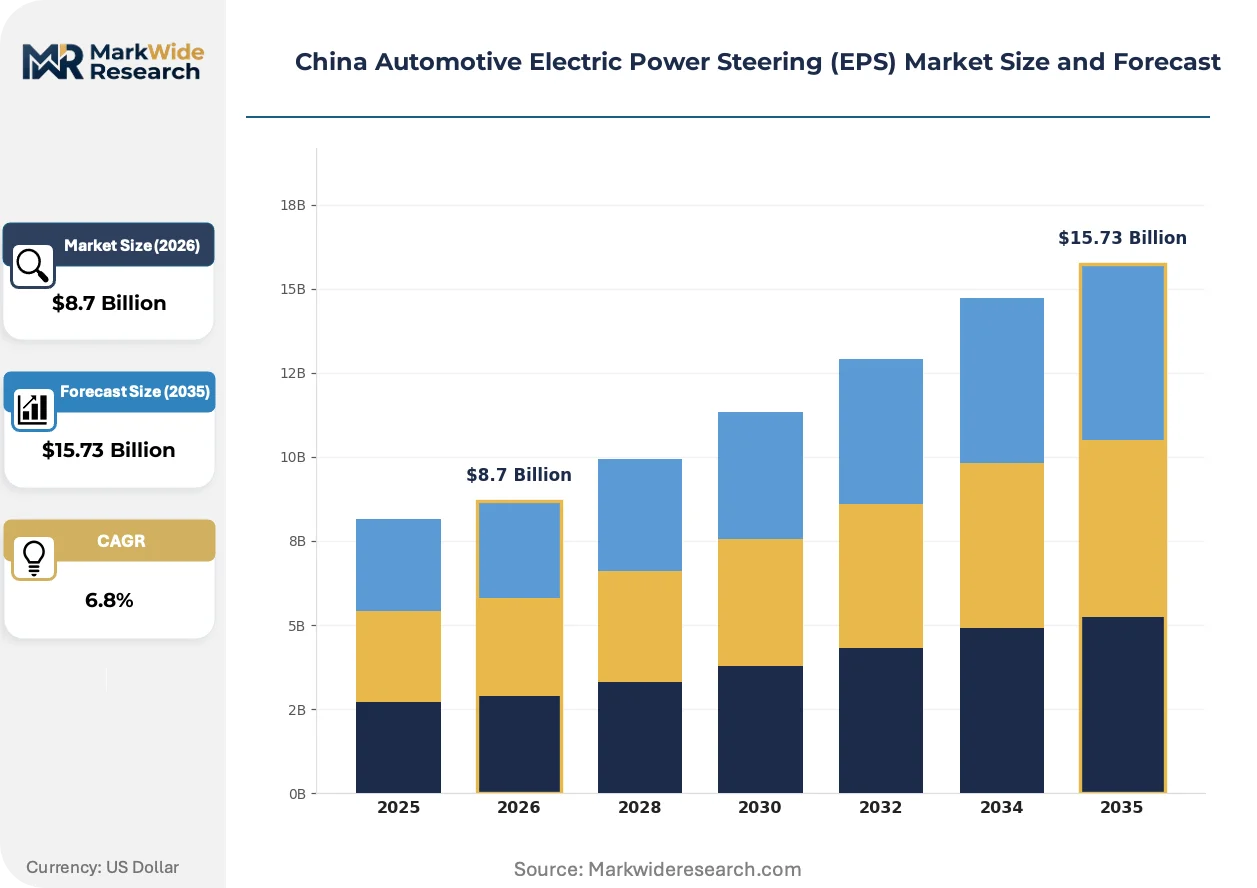
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Electro-Hydraulic, Full Electric End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Brushless Motor, DC Motor, Integrated Systems, Smart Steering Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Sports Cars |
| Companies Covered | JTEKT Corporation, Nexteer Automotive, Robert Bosch GmbH, ZF Friedrichshafen AG, Denso Corporation, NSK Ltd., China Automotive Systems, Hyundai Mobis, Hitachi Astemo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive Electric Power Steering (EPS) Market Trends and Innovations
Sensor fusion architectures are merging lane-keeping data with steering rack feedback, compressing the boundary between chassis control and autonomous driving compute layers.
Brushless DC motor drives with integrated torque angle sensors are automating real-time assist curve adjustment based on vehicle speed and road surface estimation. Domestic NEV OEMs adopt these systems at scale for mid-size sedan platforms. The technology is automating the displacement of fixed-ratio hydraulic boost curves with continuously variable electric assistance profiles.
MIIT enforcement of updated GB standards for electromagnetic compatibility and steering system failure modes is elevating product certification costs. SAMR conformity assessment timelines for replacement parts have extended by four to six months for uncertified suppliers. Aftermarket providers in Guangdong and Shandong provinces are consolidating testing capabilities to share compliance infrastructure.
Fleet procurement of rack-assist EPS for electric light commercial vehicles is compressing traditional three-year model cycles into eighteen-month platform refreshes. Tier-1 suppliers face tooling amortization pressure as OEMs demand annual torque specification updates. This pattern concentrates most intensely in Zhejiang province where NEV van and truck assembly capacity is scaling fastest.
China Automotive Electric Power Steering (EPS) Market Segmentation
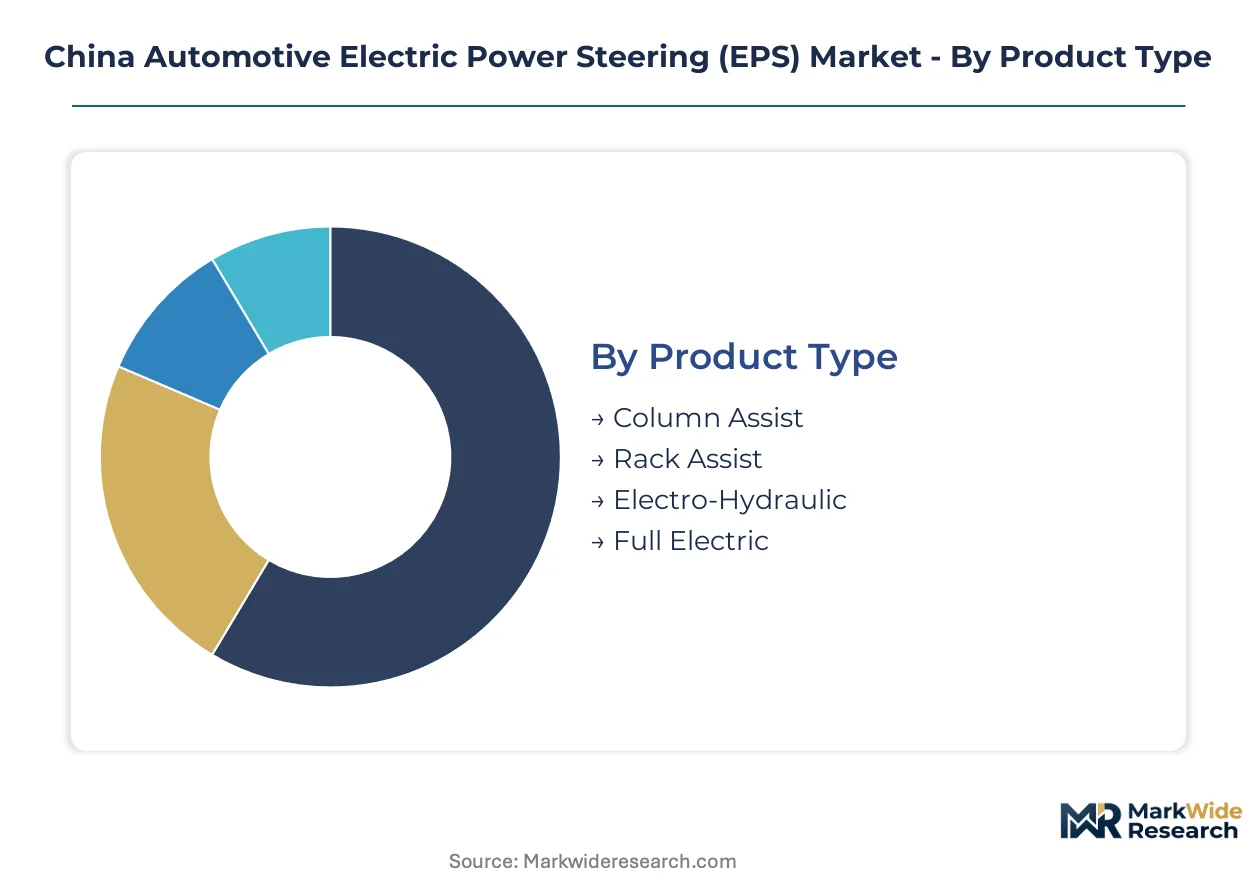
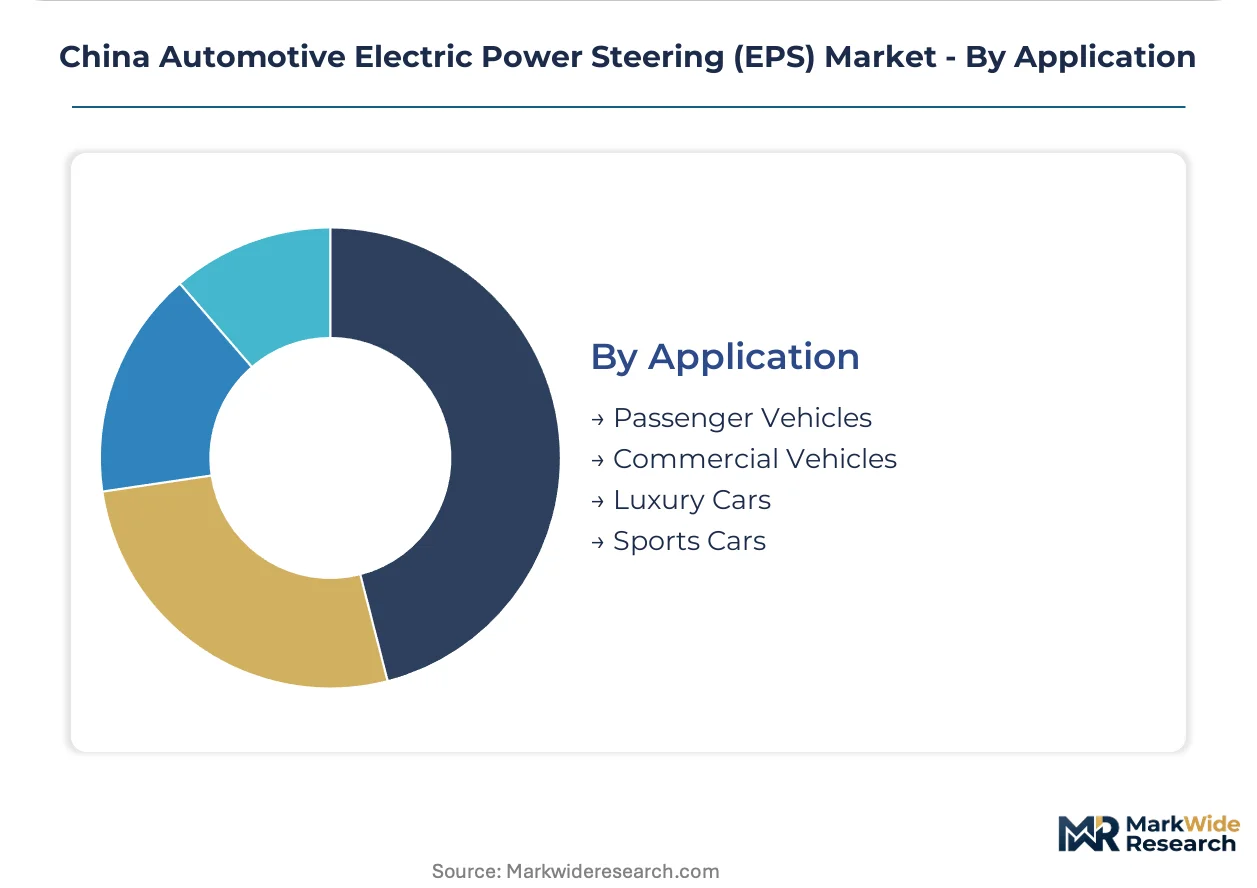
Segmentation in the China Automotive EPS market reveals how procurement patterns split between mass-market standardization and premium customization tiers. Product architecture, motor technology, and vehicle application each create distinct margin profiles that reshape supplier qualification requirements.
Product Type:
The customization-vs-standardization spectrum spans from compact vehicle cost optimization to full electric architectures with steer-by-wire readiness.
- Column Assist:Electric motors mount directly to the steering column, reducing packaging complexity for compact vehicle platforms. Demand concentrates among domestic OEMs in tier-2 and tier-3 cities where cost thresholds dominate procurement decisions, constrained by torque limitations that exclude heavy vehicle applications.
- Rack Assist:Motors integrate with the steering rack gear, delivering higher torque output for mid-size sedans and SUVs. Procurement from NEV OEMs in the Yangtze River Delta cluster accelerates as platform consolidation favors direct rack engagement for automated parking preconditioning.
- Electro-Hydraulic:Hybrid architecture retains hydraulic boost with electric pump substitution for commercial vehicle retrofits.
- Full Electric:Steer-by-wire capable designs await GB standards finalization for fail-operational certification.
Leading the category by volume: Rack Assist. Growing fastest: Full Electric.
End User:
Cost tier separation distinguishes volume-driven OEM contracts from margin-rich aftermarket conversion opportunities.
- OEMs:Sino-foreign joint ventures and domestic NEV manufacturers procure through multi-year supply agreements with tier-1 incumbents. MIIT fuel-consumption mandates force ICE platform electrification, expanding EPS specification into entry vehicle segments previously served by hydraulic systems.
- Aftermarket Providers:Certified conversion workshops in Guangdong and Shandong provinces retrofit aging compact vehicle parc with column-assist upgrades. SAMR conformity assessment timelines extend replacement-part market access for uncertified suppliers, consolidating revenue among tested incumbents.
- Vehicle Assemblers:Contract manufacturers for NEV startups source rack-assist units through just-in-sequence delivery from Yangtze River Delta suppliers.
- Fleet Operators:Electric light commercial vehicle procurement compresses traditional model cycles into accelerated refresh timelines.
Highest contract value: OEMs. Fastest margin expansion: Aftermarket Providers.
Technology:
Application maturity separates proven motor architectures from emerging integrated compute platforms.
- Brushless Motor:Permanent magnet synchronous designs with neodymium-iron-boron rotors deliver response latencies under 50 milliseconds. Domestic NEV OEMs in Zhejiang province specify these units for mid-size sedan platforms, though dysprosium and terbium price volatility squeezes supplier margins.
- Smart Steering:Integrated ECUs with CAN-bus connectivity and sensor fusion architectures merge lane-keeping data with rack feedback. ADAS preconditioning demand from premium NEV brands commands premium positioning as automakers bundle autonomous compute layers into steering hardware.
- DC Motor:Brushed designs retain limited share in cost-constrained compact vehicle applications.
- Integrated Systems:Motor-controller-sensor combinations reduce assembly complexity for tier-1 suppliers.
Widest deployment: Brushless Motor. Steepest technology climb: Smart Steering.
Application:
Customer type fragmentation splits between mass-market volume and performance-tier differentiation.
- Passenger Vehicles:Mid-size sedans and compact crossovers absorb the majority of rack-assist and column-assist shipments. Domestic NEV output scaling in Jiangsu and Shanghai accelerates platform-specific torque calibration requirements.
- Commercial Vehicles:Electric van and truck assembly in Zhejiang province drives fleet procurement of heavy-duty rack-assist units with annual specification updates.
- Luxury Cars:Premium brands specify smart steering with over-the-air torque curve personalization.
- Sports Cars:Low-volume performance applications demand variable ratio rack designs with track-mode calibration.
Dominant volume share: Passenger Vehicles. Quickest procurement acceleration: Commercial Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate EPS procurement through Shanghai-Jiangsu-Zhejiang manufacturing corridors. MIIT dual carbon mandates accelerate NEV platform consolidation across these coastal clusters.
Shanghai-Jiangsu Corridor
NEV sedan output scaling drives rack-assist EPS procurement from domestic OEMs. MIIT fuel-consumption mandates force ICE auxiliary system electrification. Suzhou and Wuxi assembly plants compress supplier qualification timelines through just-in-sequence delivery contracts.
Zhejiang Province
Electric light commercial vehicle fleet procurement accelerates platform refresh cycles. SAMR conformity assessments extend replacement-part market access timelines. Ningbo and Hangzhou manufacturing hubs concentrate heavy-duty rack-assist assembly for van and truck applications.
Beijing-Tianjin-Hebei
Premium NEV brands specify smart steering with ADAS preconditioning integration. GB standards for electromagnetic compatibility elevate certification costs. Beijing R&D centers anchor sensor fusion architecture development for autonomous steering compute layers.
Guangdong Province
Aftermarket conversion workshops retrofit aging compact vehicle parc with column-assist upgrades. SAMR testing timelines consolidate revenue among certified incumbents. Shenzhen and Guangzhou service networks share compliance infrastructure to offset extended conformity assessments.
Sichuan-Chongqing
Western China NEV assembly capacity expansion attracts tier-1 supplier branch plants. MIIT steering safety standards tighten product certification for entry vehicle segments. Chengdu logistics hubs reduce inland distribution costs for column-assist systems targeting cost-optimized platforms.
China Automotive Electric Power Steering (EPS) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. Tier-1 incumbents anchor supply relationships through multi-year joint-venture contracts while domestic challengers face renewal friction. Two archetypes dominate: legacy Sino-foreign partnership suppliers with column-assist heritage, and brushless motor specialists calibrating for Chinese OEM torque specifications. Competitive moves concentrate on M&A for testing capabilities and capacity expansion in Yangtze River Delta corridors.
Among Japanese and German tier-1s, JTEKT Corporation and Robert Bosch GmbH occupy positions within legacy partnership supply tiers, while Nexteer Automotive exemplifies the motor specialization archetype targeting domestic NEV procurement. These three represent contrasting strategic postures: heritage-based relationship anchoring versus technical specification calibration for platform-consolidation timelines.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Denso Corporation |
| NSK Ltd. |
| China Automotive Systems |
| Hyundai Mobis |
| Hitachi Astemo |
| Others |
Pricing and Supply Chain Analysis
NEV OEM procurement concentration in the Yangtze River Delta enforces contract-based long-term offtake pricing with annual torque specification renegotiation clauses. MIIT certification timelines and rare-earth magnet cost pass-through mechanisms tether unit economics to supplier qualification status.
Pricing Analysis
Short lead-time premiums attach to just-in-sequence rack-assist contracts for Zhejiang electric van platforms, while spot inventory of column-assist units trades at discounted rates. Pricing stratifies across smart steering with ADAS preconditioning, certified brushless motor systems, and economy DC motor configurations. Cost compression in entry vehicle segments intensifies as domestic OEMs consolidate platform sourcing. Fleet operators exhibit highest price sensitivity, whereas premium NEV brands absorb premium positioning for sensor fusion architectures.
Supply Chain Analysis
Regional distribution centers in Suzhou and Ningbo anchor hub-and-spoke patterns feeding Shanghai-Jiangsu-Zhejiang assembly corridors. Brushless motor production draws from neodymium-iron-boron magnet supplies concentrated in China, with additional winding equipment sourced from Japan and Germany. Single-source vulnerability in dysprosium and terbium feedstock exposes margin stability to mineral price volatility. Distribution runs through tier-1 supplier direct OEM contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineer scarcity props pricing for ASIL-D certified suppliers, constraining capacity expansion timelines across the Yangtze River Delta cluster.
For Market Incumbents: Cement multi-year joint-venture contract renewals before NEV platform consolidation accelerates supplier switching. Invest in captive magnet sourcing partnerships to offset rare-earth price volatility threatening margin stability. Deepen backward integration into torque sensor calibration capabilities to defend against domestic brushless motor specialists. For New Entrants and Emerging Players: Certified aftermarket conversion workshops in Guangdong tier-2 cities present the most penetrable entry vector. Target column-assist retrofit demand from aging compact vehicle parc with SAMR pre-certified kit offerings. Lead with software-defined torque curve personalization as the go-to-market differentiator against legacy hydraulic service infrastructure. For Investors and Strategic Acquirers: The window for entry favors testing capability consolidators with MIIT electromagnetic compatibility infrastructure. Five-to-ten year viability hinges on steer-by-wire regulatory readiness positioning. Monitor GB standards finalization for fail-operational certification as the inflection signal for full electric architecture deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | NEV OEMs compress supplier qualification timelines through unified rack-assist specifications across sedan and SUV architectures. |
| Software-Defined Vehicle Investment | Over-the-air torque calibration enables subscription revenue streams from driver personalization tiers. |
| Geographic Manufacturing Footprint | Yangtze River Delta concentration reduces logistics costs for just-in-sequence delivery to Zhejiang van assembly plants. |
| Battery Supply Agreement | Electric light commercial fleet procurement ties EPS specification updates to eighteen-month platform refresh cycles. |
| Charging Infrastructure Partnership | Smart steering ADAS preconditioning integration aligns with autonomous parking compute layer development in Beijing R&D centers. |
Research Methodology
Multi-period observation of MIIT certification timeline extensions, SAMR conformity assessment backlogs, and NEV platform consolidation patterns anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket conversion workshop operators, and functional safety certification specialists. Secondary validation drew from MIIT fuel-consumption mandate disclosures, GB standards publication records, vehicle production databases, and customs trade data for rare-earth magnet imports. Bottom-up unit shipment estimates triangulated against top-down OEM procurement contract values.
Input-output matrices mapped brushless motor cost structures, torque specification calibration complexity, and regional logistics premiums across vehicle class, propulsion architecture, and OEM tier segmentation dimensions. CAGRs were derived from production capacity buildout schedules and platform lifecycle assumptions throughout the forecast period. Industry-specific forecast inputs incorporated NEV output scaling trajectories and steer-by-wire regulatory readiness milestones.
Revisions become necessary when MIIT accelerates electromagnetic compatibility certification timelines, rare-earth export restrictions materialize, or GB standards finalization delays steer-by-wire deployment. Forecasts reflect documented assumptions regarding supplier qualification friction and joint-venture contract renewal patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market