
 Automotive Engine Management Sensors Market | 2026-2036
Automotive Engine Management Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Engine Management Sensors Market Analysis
The capital-intensity divergence between MEMS-capable fabs and legacy analog producers is rotating competitive advantage toward semiconductor-integrated suppliers. Robert Bosch GmbH leverages captive wafer capacity to sustain margin control across oxygen sensor lines. Continental AG anchors European OEM relationships through embedded software-defined sensing architectures. DENSO Corporation competes on thermal management integration, extending its dominance in engine temperature sensors for hybrid powertrains.
Automotive engine management sensors are electromechanical transducers that monitor combustion parameters including air-fuel ratio, cylinder temperature, and knock events with response thresholds below 50 milliseconds; their primary purpose is to enable real-time ECU calibration for emissions compliance and fuel efficiency optimization. MEMS technology is displacing analog architectures in mass airflow applications where miniaturization and multi-axis measurement reduce wiring harness complexity. Oxygen sensors retain the largest installed base but face margin compression as piezoelectric knock sensors capture premium positioning in direct-injection gasoline engines. Digital sensor platforms are creating new revenue pools by embedding diagnostic protocols that reduce warranty exposure for OEMs.
EPA Tier 3 standards and Euro 7 proposals are mandating sub-percentage-point air-fuel measurement accuracy, forcing NHTSA-aligned suppliers to recalibrate production lines for tighter tolerance bands. REACH substance restrictions and RoHS compliance are eliminating certain lead-based solder formulations in sensor housings, redirecting procurement toward certified Asian and European component sources. Stakeholders must monitor how ISO 26262 functional safety grades reshape qualification timelines for next-generation combustion feedback systems.
Market Dynamics
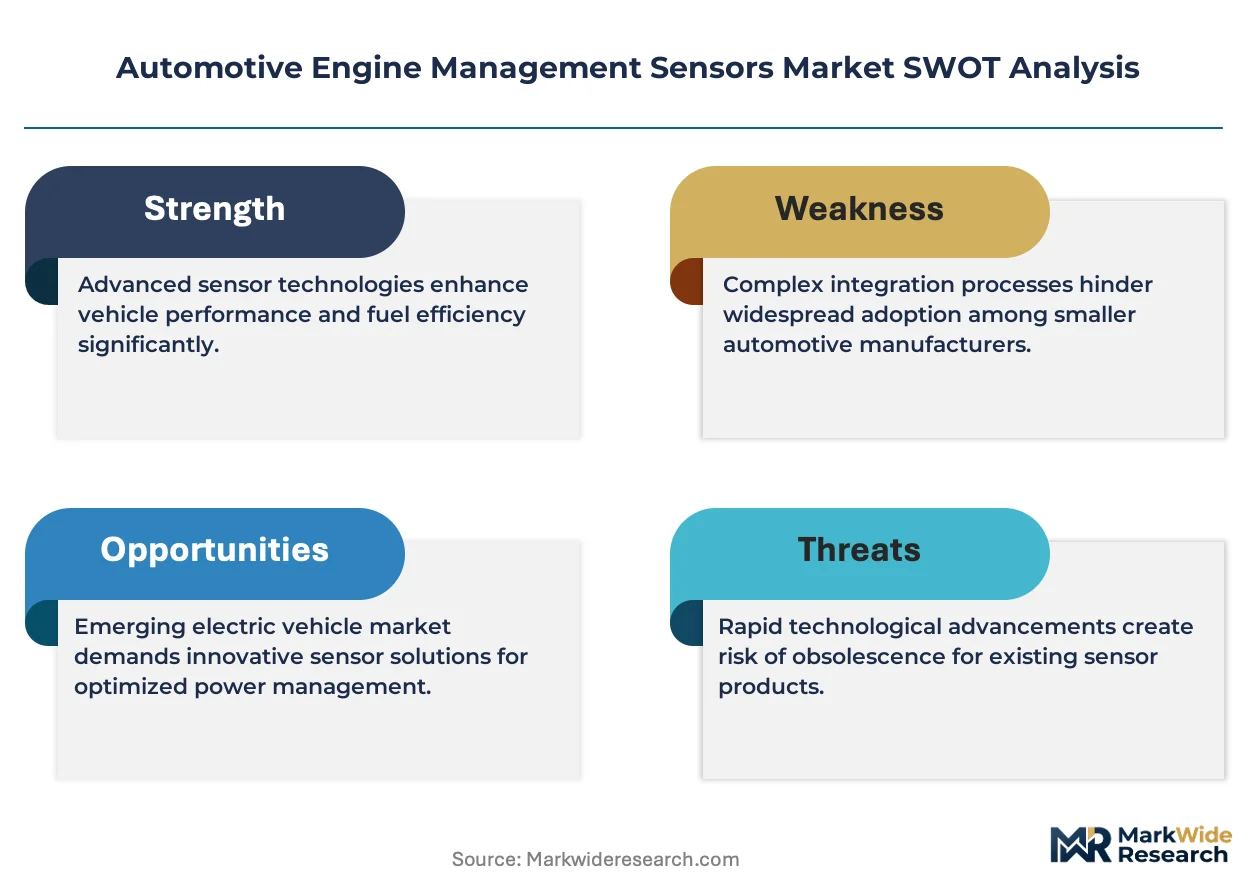
Powertrain electrification is bifurcating sensor demand between legacy combustion feedback systems and hybrid-optimized thermal management architectures, forcing suppliers to dual-track R&D investments while maintaining margin discipline on oxygen sensor lines facing volume erosion.
Growth Catalysts
- Euro 7 emission standards:Sub-percentage-point air-fuel ratio mandates are compelling OEMs to upgrade sensor accuracy specifications across gasoline direct-injection platforms.
- Hybrid powertrain proliferation:Thermal cycling demands in PHEV architectures are expanding the addressable market for multi-point temperature sensing arrays.
- Piezoelectric knock detection:High-pressure combustion chambers in downsized turbocharged engines require faster-response detonation monitoring than legacy accelerometer designs permit.
Market Restraints
- Palladium price volatility:Oxygen sensor electrodes depend on platinum-group metal coatings, exposing producers to commodity swings that compress gross margins unpredictably.
- MEMS fab concentration:Wafer capacity for microelectromechanical airflow sensors concentrates in Taiwan and South Korea, creating single-source vulnerability for European Tier-1 suppliers.
- Lead-free solder restrictions:REACH and RoHS compliance eliminates traditional housing alloys, forcing qualification of alternative metallurgies with unproven field reliability.
Strategic Opportunities
- India automotive production:Domestic OEM capacity expansion under PLI scheme incentives creates greenfield demand for localized sensor assembly operations.
- Software-defined sensing:Embedded diagnostic protocols in digital sensor platforms enable recurring revenue streams through over-the-air calibration updates.
- Carbon border adjustments:EU CBAM implementation favors suppliers with verified low-carbon supply chains, rewarding early movers in renewable-energy-powered manufacturing.
Industry Challenges
- ISO 26262 ASIL-D qualification:Functional safety certification for combustion-critical feedback loops extends development timelines by 18-24 months and requires specialized verification engineering talent.
- Legacy ECU integration:Digital sensor outputs must interface with analog-dominant engine control units through costly signal conditioning hardware, complicating platform migration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Engine Management Sensors Market |
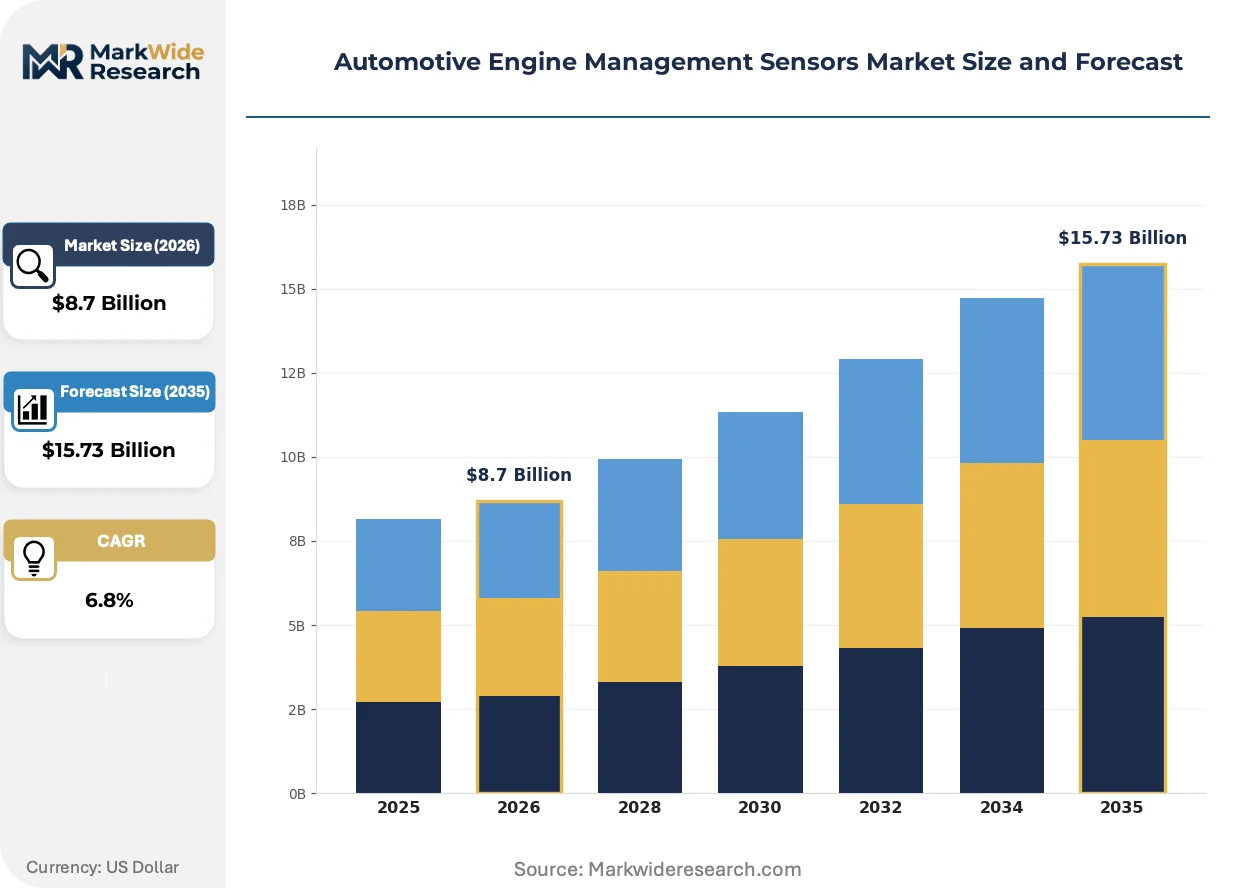
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Sensors, Mass Airflow Sensors, Engine Temperature Sensors, Knock Sensors Technology: Digital Sensors, Analog Sensors, MEMS Sensors, Piezoelectric Sensors End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, BorgWarner Inc., Hella KGaA Hueck & Co., Sensata Technologies, Infineon Technologies AG, NGK Spark Plugs, Hitachi Automotive Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Engine Management Sensors Market Emerging Trajectories
Sensor architectures are converging around semiconductor-integrated designs that embed processing intelligence at the measurement point, reducing wiring harness complexity while enabling predictive maintenance capabilities that reshape aftermarket economics.
Wideband oxygen sensing technology is fragmenting the installed base of narrowband lambda probes by delivering continuous air-fuel ratio measurement rather than binary rich-lean switching. OEMs in Germany and Japan are adopting these sensors for gasoline particulate filter regeneration strategies. The shift is fragmenting supplier hierarchies as semiconductor-capable manufacturers capture specification-setting authority previously held by ceramic specialists.
EPA Tier 3 and NHTSA-aligned state implementation plans are mandating onboard diagnostic verification of emission control system performance across the full vehicle lifetime. Suppliers must engineer sensors with drift compensation algorithms and redundant measurement paths. The compliance burden falls heaviest on mass-market passenger car programs where per-unit cost targets conflict with precision requirements.
Fleet operators and leasing companies are consolidating procurement authority for powertrain sensors through long-term service agreements that bundle hardware, installation, and predictive replacement scheduling. Direct OEM purchasing of individual sensor units is giving way to subsystem-level contracts managed by powertrain integrators. The restructuring is most visible in North American commercial vehicle segments where total cost of ownership modeling dominates sourcing decisions.
Automotive Engine Management Sensors Market Segmentation

Engine management sensor procurement splits across four dimensions that determine pricing power and qualification timelines. Product type and technology choices dictate semiconductor integration depth, while end-user and application segments govern volume scale and aftermarket attach rates.
Product Type:
Margin pools concentrate in sensors requiring platinum-group metal electrodes or piezoelectric ceramics, where material science expertise creates supply scarcity.
- Oxygen Sensors:Lambda probes with zirconia or titania electrolyte cores dominate installed base volume. Euro 7 and EPA Tier 3 mandates for sub-percentage-point air-fuel accuracy are forcing upgrades from narrowband to wideband architectures in Germany, Japan, and the United States.
- Knock Sensors:Piezoelectric resonant discs detect cylinder pressure oscillations above 6 kHz in downsized turbocharged gasoline engines. Demand is climbing fastest in high-compression direct-injection platforms where detonation margins have tightened.
- Mass Airflow Sensors:Hot-wire and hot-film thermal anemometry designs measure intake air mass with ±2% precision for ECU fuel mapping.
- Engine Temperature Sensors:NTC thermistor and RTD probe configurations monitor coolant and oil thermal states across hybrid thermal cycling profiles.
The dominant share belongs to oxygen sensors, while knock sensors are closing the gap fastest.
Technology:
Architecture choices determine wiring harness complexity and diagnostic capability depth, with semiconductor-integrated designs capturing specification authority from legacy analog suppliers.
- MEMS Sensors:Microelectromechanical systems enable multi-axis airflow measurement in packages under 5mm thickness. Taiwan and South Korea wafer fabs supply Tier-1 integrators serving OEMs in Germany and Japan.
- Digital Sensors:Embedded microcontrollers execute drift compensation algorithms and OBD-II diagnostic protocols at the measurement node. REACH and RoHS compliance requirements are accelerating displacement of analog outputs in new vehicle platforms.
- Piezoelectric Sensors:Ceramic transducer elements convert mechanical vibration to electrical signals without external power.
- Analog Sensors:Voltage-output designs persist in legacy ECU architectures requiring signal conditioning hardware for digital conversion.
MEMS architectures command the highest unit economics, with digital platforms expanding most quickly through software-defined sensing roadmaps.
End User:
Procurement authority is consolidating toward subsystem integrators who bundle hardware, calibration, and predictive maintenance services.
- Tier-1 Suppliers:Continental AG, Robert Bosch GmbH, and DENSO Corporation manage powertrain subsystem contracts that specify sensor performance envelopes. These firms qualify multi-source supply chains to mitigate palladium price volatility and single-source MEMS fab exposure.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and Ford Motor Company retain direct specification authority for combustion-critical feedback loops requiring ISO 26262 ASIL-D certification.
- Aftermarket Providers:Independent distributors service replacement demand through service bay networks and e-commerce channels.
- Vehicle Assemblers:Contract manufacturers in India under PLI scheme incentives are localizing sensor assembly for domestic OEM capacity expansion.
Tier-1 suppliers control the largest volume channel, though OEM direct procurement is gaining share fastest in functional safety-critical applications.
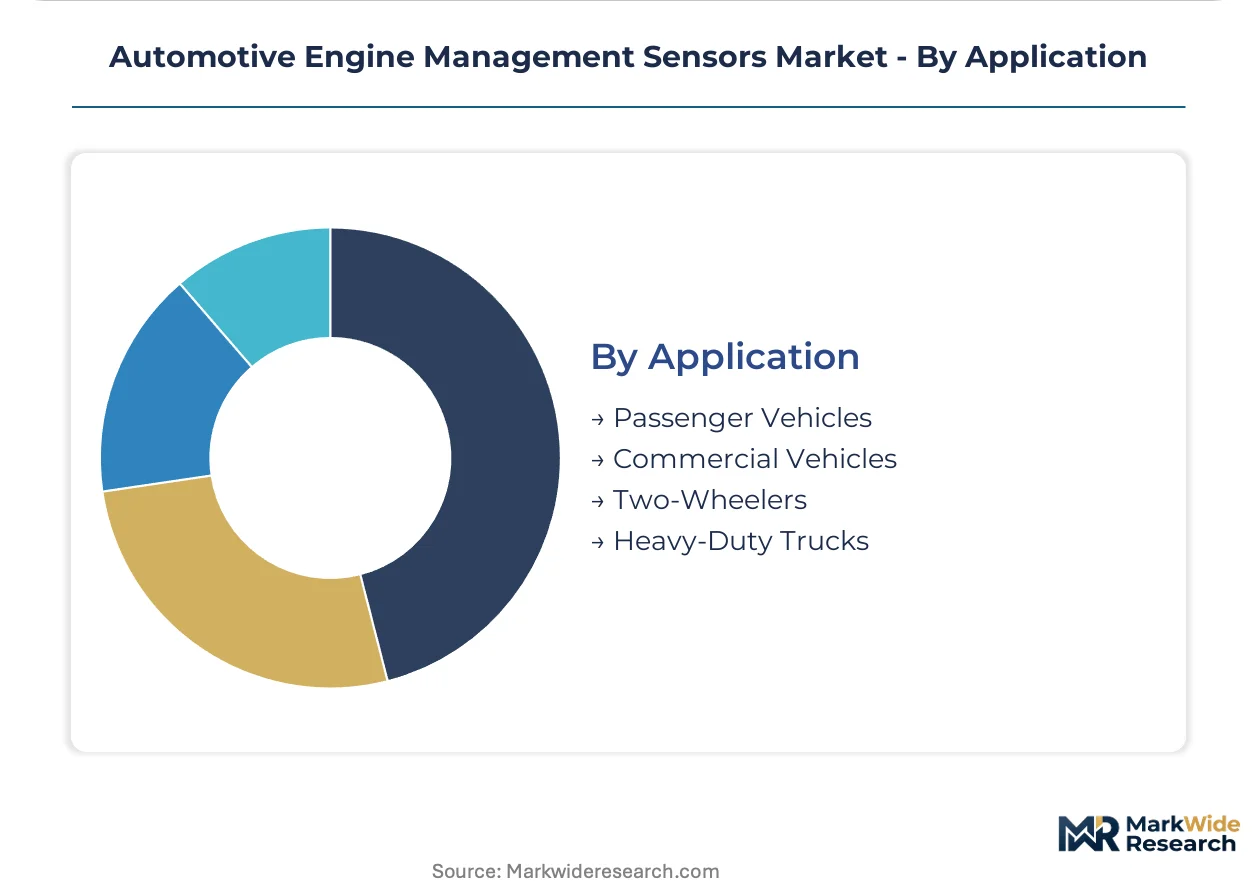
Application:
Vehicle class determines thermal cycling severity, emissions compliance tier, and sensor count per powertrain.
- Passenger Vehicles:Gasoline direct-injection and diesel platforms carry 8-12 engine management sensors for air-fuel ratio, temperature, and knock monitoring. EPA Tier 3 and Euro 7 implementation is forcing sensor accuracy upgrades across compact and mid-size segments in the United States and Germany.
- Heavy-Duty Trucks:Commercial diesel engines require extended-lifetime oxygen sensors with platinum-group metal electrodes rated for 800,000+ kilometer durability. Fleet operators in North America are consolidating procurement through total cost of ownership agreements.
- Commercial Vehicles:Light trucks and vans operate on simplified sensor arrays with narrower operating temperature ranges.
- Two-Wheelers:Single-cylinder engines use basic narrowband lambda and temperature probes with reduced precision requirements.
Passenger vehicles retain the dominant application share, while heavy-duty trucks are climbing fastest through fleet consolidation and predictive maintenance bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor consumption patterns diverge sharply across major automotive manufacturing bases. German OEMs prioritize wideband oxygen architectures for Euro 7 pre-compliance, while Japanese producers emphasize thermal cycling durability for hybrid powertrains. United States demand concentrates on heavy-duty fleet applications with extended service intervals.
United States
Heavy-duty truck fleet operators drive sensor procurement through total cost of ownership agreements bundling hardware and predictive maintenance. EPA Tier 3 implementation mandates onboard diagnostic verification across full vehicle lifecycles. Detroit and Indiana manufacturing corridors host Tier-1 supplier assembly operations serving domestic OEM powertrain programs.
Germany
Gasoline direct-injection platforms in premium passenger vehicles require sub-percentage-point air-fuel accuracy specifications. KBA enforcement of Euro 7 pre-standards accelerates wideband lambda probe adoption ahead of formal implementation. Stuttgart and Munich precision engineering clusters concentrate semiconductor-integrated sensor design capabilities.
Japan
Hybrid powertrain proliferation expands demand for multi-point temperature sensing arrays managing thermal cycling stress. METI carbon neutrality roadmaps push sensor suppliers toward renewable-energy-powered manufacturing certifications. Nagoya and Toyota City automotive production belts anchor DENSO Corporation and affiliated supplier networks.
China
Domestic OEM capacity expansion under dual carbon goals creates demand for localized sensor assembly reducing import dependency. MIIT new energy vehicle mandates accelerate hybrid platform sensor counts beyond conventional combustion architectures. Yangtze River Delta manufacturing zones concentrate MEMS wafer fabrication serving regional Tier-1 integrators.
India
Domestic automotive production scaling under PLI scheme incentives generates greenfield demand for engine management sensor localization. BIS emission compliance timelines for Bharat Stage VI stage II implementation mirror Euro 7 accuracy requirements. Tamil Nadu and Gujarat automotive corridors attract sensor assembly investments from multinational Tier-1 suppliers.
Automotive Engine Management Sensors Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive semiconductor fabrication and platinum-group metal supply relationships determining pricing power. The market structure rewards backward integration into wafer capacity and ceramic substrate production. Three archetypes dominate: diversified automotive electronics conglomerates with full powertrain subsystem capabilities; MEMS-focused semiconductor suppliers leveraging foundry partnerships; and ceramic specialists defending oxygen sensor positions through material science expertise. Competitive dynamics center on M&A activity consolidating Tier-2 sensor specialists and strategic partnerships securing palladium supply commitments against commodity volatility.
Within the integrated conglomerate tier, Robert Bosch GmbH and Continental AG exemplify players combining captive manufacturing depth with OEM specification authority. DENSO Corporation occupies a distinct position emphasizing thermal management integration for hybrid architectures. BorgWarner Inc. and Hella KGaA Hueck & Co. represent specialists transitioning toward software-defined sensing platforms through embedded diagnostic capabilities. Sensata Technologies and Infineon Technologies AG anchor the semiconductor-centric vector, leveraging MEMS fabrication relationships for mass airflow sensor supply.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| BorgWarner Inc. |
| Hella KGaA Hueck & Co. |
| Sensata Technologies |
| Infineon Technologies AG |
| NGK Spark Plugs |
| Hitachi Automotive Systems |
| Others |
Supply Flow & Price Mechanics
Wafer-scale economies in Taiwan and South Korea MEMS fabrication anchor both supply concentration and price floors across mass airflow sensor tiers, compressing margin headroom for European Tier-1 integrators lacking captive foundry relationships. This scale asymmetry forces procurement officers to accept longer lead times or premium pricing for semiconductor-integrated designs, while legacy analog suppliers defend oxygen sensor positions through platinum-group metal supply relationships.
Pricing Analysis
After-sales service bundling and predictive replacement contracts drive lifetime value capture in heavy-duty truck segments, where fleet operators prioritize total cost of ownership over per-unit sensor cost. Three-tier pricing structure across premium wideband oxygen architectures, standard narrowband lambda probes, and economy-grade temperature sensors reflects ISO 26262 certification grade and volume scale differentiation. Cost compression in economy-tier narrowband sensors is intensifying because Chinese domestic OEMs are localizing assembly under PLI-equivalent incentives. Tier-1 suppliers exhibit lowest price sensitivity due to subsystem-level contract structures, while independent aftermarket distributors face acute margin pressure from e-commerce price transparency.
Supply Chain Analysis
Taiwan Strait transit vulnerability concentrates single-source risk for MEMS wafer supply serving German and Japanese OEM programs. Production gravity centers on Taiwan, South Korea, and Germany, with raw material dependencies spanning palladium electrodes for oxygen sensors, piezoelectric ceramics for knock detection, and silicon wafers for thermal anemometry. Commodity price volatility in platinum-group metals exposes margin unpredictability across ceramic sensor specialists. Distribution runs through Tier-1 powertrain integrators who bundle hardware, calibration software, and predictive maintenance services for OEM direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments sensor demand between legacy combustion feedback and hybrid-optimized thermal architectures, creating niche opportunities for specialists who can bridge both technology trajectories without duplicating full-platform R&D investment.
For Market Incumbents: Consolidate through targeted acquisition of MEMS-capable Tier-2 specialists to secure wafer capacity against Taiwan fab concentration risk. Deepen backward integration into platinum-group metal supply relationships to hedge palladium price volatility. Prioritize ISO 26262 ASIL-D certification investment for combustion-critical feedback loops to defend specification authority against semiconductor entrants.
For New Entrants and Emerging Players: ISO 26262 functional safety fast-track programs offer qualification acceleration for software-defined sensing platforms with embedded diagnostic protocols. White-space targets concentrate in Indian domestic OEM supply under PLI scheme localization mandates, and in aftermarket predictive maintenance bundling for North American heavy-duty fleets. Go-to-market execution should anchor on subsystem integration partnerships with powertrain specialists lacking semiconductor design capabilities.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor suppliers with embedded software platforms enabling over-the-air calibration updates and long-term service agreements. Long-term viability across the five-to-ten year window favors targets with verified low-carbon manufacturing certifications positioning for EU carbon border adjustment implementation. Acquisition priority targets ceramic sensor specialists with material science IP and stranded MEMS design houses seeking foundry partnerships. The signal to watch is wideband oxygen sensor specification share in German premium passenger vehicle programs.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fab Capacity Expansion | Taiwan and South Korea wafer additions reduce single-source vulnerability for European Tier-1 integrators. |
| Software-Defined Sensing Platform | Embedded diagnostic protocols enable recurring revenue through over-the-air calibration updates for OEMs. |
| Platinum-Group Metal Supply Agreement | Long-term palladium commitments hedge commodity volatility compressing oxygen sensor margins. |
| ISO 26262 ASIL-D Certification Investment | Functional safety qualification extends development timelines but secures specification authority in combustion-critical loops. |
| India Manufacturing Localization | PLI scheme incentives attract sensor assembly investments serving domestic OEM capacity expansion. |
Methodological Framework
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution managers, and MEMS foundry operations executives provided ongoing calibration against secondary validation from vehicle production databases, IHS Markit registration data, EPA emission compliance filings, and customs trade records. Primary fieldwork combined structured interviews with semiconductor fabrication specialists and ceramic sensor material scientists. Bottom-up sensor unit demand modeling triangulated against top-down powertrain production forecasts across passenger vehicle, heavy-duty truck, and hybrid platform segments.
Consistency checks validated volume and value outputs against external benchmarks including regional automotive production data and Tier-1 supplier revenue disclosures. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derived from unit shipment trajectories and average selling price evolution, with industry-specific inputs including Euro 7 implementation timelines, EPA Tier-3 state adoption patterns, and hybrid powertrain penetration curves.
Underlying assumptions cover emission standard enforcement schedules, palladium price stability, and MEMS wafer capacity expansion, with deviation risk concentrated in regulatory delay, commodity spike, or geopolitical disruption to Taiwan supply corridors. Practitioners should keep alternative scenarios live as Euro 7 pre-standards enforcement and carbon border adjustment mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Wireline Trucks Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Europe Automotive Pressure Sensor Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Europe Automotive Display Market