
 Automotive Electronic Manufacturing Services Market | 2026-2036
Automotive Electronic Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electronic Manufacturing Services Market Analytics
Mexico is tilting toward automotive EMS investment as OEMs nearshore electronics assembly to serve North American EV programs. Foxconn leverages its vertical manufacturing scale to capture power module and inverter assembly contracts from major automakers. Jabil Inc. anchors its competitive position through advanced PCB and sensor packaging capabilities tailored to ADAS architectures.
Automotive Electronic Manufacturing Services encompass the outsourced design, assembly, testing, and lifecycle management of electronic components and subsystems for vehicles, typically operating under IPC-A-610 Class 3 standards for high-reliability solder joints and conformal coating integrity. These services enable OEMs and Tier-1 suppliers to access specialized surface-mount technology lines, functional test fixtures, and regulatory compliance expertise without capital-intensive fab ownership. ECU assembly dominates current revenue contribution due to the proliferation of domain controllers for powertrain and chassis management, while PCB Assemblies represents the fastest-growing product category as layer counts and HDI densities escalate with zonal E/E architectures. Embedded Systems technology leads contract value owing to firmware integration complexity, whereas IoT Solutions is expanding fastest through connected vehicle telematics and over-the-air update infrastructure.
NHTSA, EPA, and ISO 26262 collectively shape automotive EMS demand by mandating functional safety validation, emissions-related electronics traceability, and failure-mode coverage across supply tiers. The EU AI Act and UNECE WP.29 cybersecurity regulations are extending compliance burdens to contract manufacturers performing software integration and V2X module assembly. Stakeholders must monitor how functional safety certification requirements propagate downstream from OEMs to EMS providers as vehicle architectures consolidate compute into fewer, more powerful domain controllers.
Market Dynamics
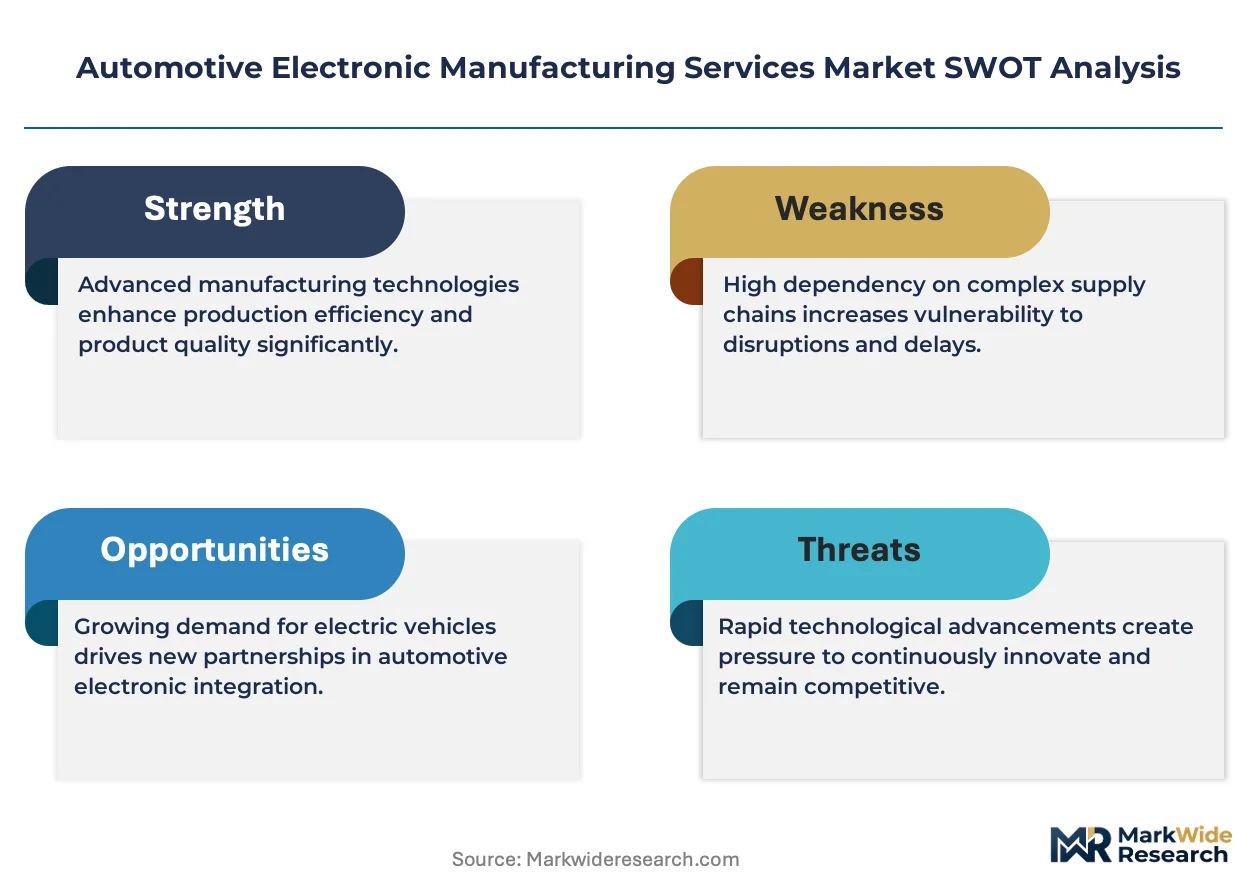
Powertrain electrification is compressing development cycles and forcing Tier-1 suppliers to outsource ECU assembly, PCB fabrication, and sensor packaging to specialized contract manufacturers rather than maintaining captive production.
Growth Catalysts
- NHTSA Safety Mandates:Advanced driver-assistance systems now require redundant sensor architectures and validated PCB assemblies, expanding contract manufacturing scope for domain controllers and radar modules.
- EV Powertrain Electrification:Battery management systems and inverter electronics demand high-reliability surface-mount capacity that OEMs lack in-house, accelerating outsourcing to EMS providers with IPC-A-610 Class 3 certification.
- China Production Concentration:Dedicated automotive EMS campuses in Shenzhen and Zhengzhou offer integrated PCB-to-box-build capabilities, attracting Western automaker programs seeking cost-competitive volume manufacturing.
Market Restraints
- Semiconductor Input Volatility:Automotive-grade MCU and power discrete shortages create allocation risk for EMS providers dependent on constrained foundry output from Taiwan and South Korea.
- ISO 26262 Certification Burden:Functional safety validation for ASIL-D rated assemblies extends qualification timelines and requires specialized auditor accreditation, raising barriers to contract entry.
- Substrate Material Concentration:High-Tg laminates and low-loss dielectrics for high-density interconnect PCBs source predominantly from Japanese and Taiwanese suppliers, creating geographic supply vulnerability.
Strategic Opportunities
- Mexico Nearshoring:OEMs are relocating electronics assembly to Baja California and Chihuahua to satisfy USMCA content rules and reduce logistics exposure for North American EV programs.
- EU AI Act Compliance Services:Contract manufacturers performing software integration for autonomous driving modules can capture value-added validation work as machine-learning component traceability mandates expand.
- Zonal E/E Architecture Convergence:Integration of power distribution, body control, and telematics into consolidated domain controllers creates demand for system-level assembly and firmware integration services.
Industry Challenges
- Embedded Firmware Talent Scarcity:Automotive EMS providers face acute shortages of engineers qualified in AUTOSAR stack configuration and functional safety software validation.
- Test Fixture Capital Intensity:Boundary-scan and in-circuit test equipment for multi-layer HDI PCBs requires seven-figure capital commitments with rapid obsolescence cycles as node densities escalate.
- Legacy Vehicle Platform Integration:Hybrid production lines must simultaneously support 12V architectures and 800V high-voltage assemblies, complicating process control and operator training protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electronic Manufacturing Services Market |
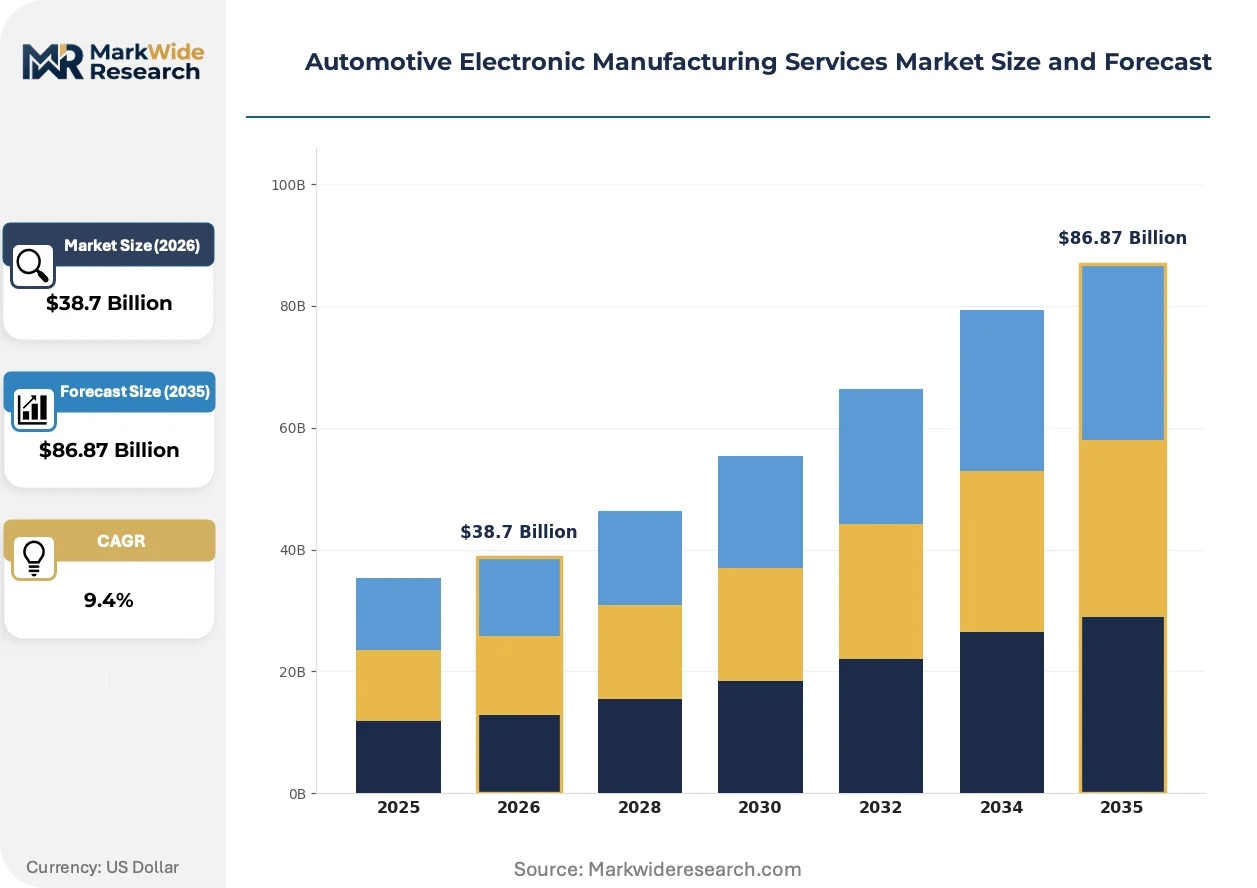
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ECUs, Sensors, Wiring Harnesses, PCB Assemblies Technology: Embedded Systems, Control Systems, IoT Solutions, Robotics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Service Type: Design Services, Prototyping, Testing Services, Repair Services |
| Companies Covered | Foxconn, Jabil Inc., Flex Ltd, Sanmina Corporation, BYD Electronics, Pegatron Corporation, Zollner Elektronik AG, Venture Corporation Limited, Celestica Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electronic Manufacturing Services Market Evolving Landscape
Automotive electronics manufacturing is converging around three vectors: process technology hybridization, regulatory compliance automation, and procurement model restructuring toward system-level accountability.
Chiplet-based packaging is hybridizing traditional PCB assembly with advanced substrate interposers, enabling power module and inverter manufacturers to integrate silicon carbide dies with control electronics in thermally optimized footprints. Tier-1 powertrain suppliers are adopting these heterogeneous integration techniques to reduce parasitic inductance and improve switching efficiency. This convergence is compressing the boundary between semiconductor packaging and EMS box-build services, forcing contract manufacturers to acquire flip-chip and wire-bond capabilities.
UNECE WP.29 cybersecurity regulations and the EU AI Act are mandating software bill-of-materials documentation and vulnerability management across automotive supply tiers. EMS providers performing V2X module assembly and over-the-air update infrastructure must now implement structured cybersecurity management systems audited against ISO/SAE 21434. European contract manufacturers are responding by building dedicated secure software integration cells with air-gapped development environments and hardware security module provisioning.
Automakers are consolidating vendor bases and awarding multi-year system integration contracts that bundle PCB fabrication, functional test, firmware loading, and logistics sequencing under single-source accountability. This procurement compression displaces component-level spot purchasing and favors EMS providers with vertical test capability and regional fulfillment networks. The shift is most visible in Germany and the United States, where OEMs are reducing qualified supplier lists for domain controller programs from dozens to fewer than five integrated partners.
Automotive Electronic Manufacturing Services Market Segmentation

Automotive EMS segmentation reveals how contract manufacturers allocate capital across divergent cycle times. Powertrain electrification and zonal E/E architectures are compressing development timelines for some segments while extending validation periods for safety-critical assemblies.
Product Type:
Cycle times vary dramatically across product categories, with power electronics assemblies turning over fastest while safety-validated sensor modules face extended qualification periods.
- ECUs:Domain controllers integrate powertrain, chassis, and body management functions into consolidated compute units. OEMs in Germany and the United States are outsourcing ECU box-build to specialized EMS providers with ISO 26262 ASIL-D certification capability as vehicle architectures consolidate.
- PCB Assemblies:High-density interconnect boards with 12+ layers and buried vias support zonal E/E architectures. Demand concentrates in China, where Shenzhen-based campuses offer integrated PCB fabrication-to-assembly services for Western automaker programs.
- Sensors:Radar, LiDAR, and camera module assemblies require hermetic sealing and thermal management for underhood placement.
- Wiring Harnesses:High-voltage cable assemblies for 800V architectures demand specialized crimping and insulation testing protocols.
ECUs dominate installed base. PCB Assemblies is where expansion concentrates.
Technology:
Cost tiers separate mature embedded platforms from emerging connectivity stacks requiring cybersecurity certification.
- Embedded Systems:AUTOSAR-compliant firmware integration for real-time control applications commands premium contract values. Tier-1 suppliers in Japan and Germany rely on EMS partners for stack configuration and functional safety validation as compute demands escalate.
- IoT Solutions:Connected vehicle telematics modules and over-the-air update infrastructure are climbing the fastest. European contract manufacturers are building secure integration cells to satisfy UNECE WP.29 cybersecurity mandates for V2X assemblies.
- Control Systems:Closed-loop motor control and battery management firmware require deterministic timing validation.
- Robotics:Automated assembly line integration and collaborative robot programming for EMS facilities themselves.
Embedded Systems anchors current revenue contribution. IoT Solutions is expanding most quickly through connected vehicle mandates.
End User:
Customer type determines contract structure, with OEMs demanding system-level accountability and Tier-1 suppliers seeking component flexibility.
- Tier-1 Suppliers:Bosch, Continental, and Denso are accelerating outsourcing of power module and inverter assembly to capture EMS scale without captive fab investment. These contracts emphasize IPC-A-610 Class 3 reliability and rapid volume ramp capability.
- OEMs:Direct OEM relationships concentrate on domain controller programs where automakers seek single-source accountability for PCB fabrication, functional test, and logistics sequencing.
- Vehicle Assemblers:Contract manufacturers performing final vehicle integration in Mexico and Eastern Europe.
- Aftermarket Providers:Replacement ECU and sensor refurbishment services with shorter validation cycles.
Tier-1 Suppliers dominate transaction volume. OEMs are where contract value is concentrating through system-level awards.
Service Type:
Margin profiles diverge sharply between capital-intensive testing infrastructure and labor-weighted repair operations.
- Testing Services:Boundary-scan, in-circuit, and functional validation for multi-layer HDI PCBs requires seven-figure capital commitments with rapid obsolescence cycles. EMS providers in South Korea and Taiwan are investing in automated optical inspection lines to capture this high-barrier work.
- Design Services:DfM and DfT optimization for automotive thermal and vibration environments commands engineering premiums. North American contract manufacturers leverage these capabilities to anchor multi-year platform relationships.
- Prototyping:Quick-turn NPI for powertrain electrification programs with compressed development cycles.
- Repair Services:Warranty return processing and remanufacturing for legacy vehicle electronics.
Testing Services dominates capital deployment. Design Services is where margin expansion concentrates.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturing capacity clusters where automotive electronics demand intersects with established electronics manufacturing infrastructure. China hosts the densest concentration of dedicated automotive EMS campuses, while Mexico and Eastern Europe attract nearshoring investments for regional market access.
China
BYD Electronics and Foxconn have expanded dedicated automotive EMS campuses in Shenzhen and Zhengzhou to serve Western automaker programs. MIIT regulations on new energy vehicle component localization push foreign OEMs toward domestic contract manufacturing partners. The Pearl River Delta offers integrated PCB fabrication-to-assembly services with rapid volume scaling capability.
United States
NHTSA safety mandates and EPA emissions rules tighten PCB assembly and sensor validation requirements for domestic production. Jabil Inc. anchors advanced PCB and sensor packaging capabilities in Florida and Michigan tailored to ADAS architectures. The Southeast region attracts power module assembly investments to support Detroit Three EV programs.
Germany
OEMs consolidate vendor bases for domain controller programs, reducing qualified supplier lists from dozens to fewer than five integrated partners. The EU AI Act and UNECE WP.29 cybersecurity regulations extend compliance burdens to contract manufacturers performing software integration. Bavaria hosts specialized secure software integration cells with air-gapped development environments.
Mexico
OEMs nearshore electronics assembly to Baja California and Chihuahua to satisfy USMCA content rules and reduce logistics exposure for North American EV programs. Foxconn leverages vertical manufacturing scale to capture power module and inverter assembly contracts from major automakers. The northern border states offer tariff-advantaged export positioning to US assembly plants.
Japan
Tier-1 suppliers including Denso accelerate outsourcing of power module assembly to capture EMS scale without captive fab investment. METI guidelines on automotive semiconductor supply chain resilience encourage diversified contract manufacturing relationships. The Chubu region around Nagoya maintains concentrated demand from Toyota and Honda electrification programs.
Automotive Electronic Manufacturing Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base organizes around three tiers: diversified global electronics manufacturers with automotive certifications, regional specialists focused on PCB-to-box-build integration, and captive operations of Tier-1 suppliers seeking external capacity during demand spikes. Consolidation pressures intensify as OEMs award multi-year system integration contracts bundling fabrication, test, and logistics under single-source accountability. Geographic expansion and strategic partnerships dominate competitive moves as players seek regional fulfillment networks.
Among Asia-Pacific-based diversified manufacturers, Foxconn and BYD Electronics exemplify scale-driven platform integrators with dedicated automotive campus investments. Jabil Inc. represents North American specialists leveraging advanced packaging capabilities to anchor multi-year OEM relationships. These three occupy positions across the system-level accountability spectrum that automakers increasingly demand for domain controller programs.
| Leading Market Players |
|---|
| Foxconn |
| Jabil Inc. |
| Flex Ltd |
| Sanmina Corporation |
| BYD Electronics |
| Pegatron Corporation |
| Zollner Elektronik AG |
| Venture Corporation Limited |
| Celestica Inc. |
| Others |
Value Network & Pricing Analysis
The Shenzhen-Long Beach maritime corridor anchors cost dynamics across the Automotive Electronic Manufacturing Services value chain, where freight rate volatility feeds directly into contract pricing differentials between China-based volume producers and Mexico-nearshored alternatives. Tier-1 suppliers sourcing high-reliability PCB assemblies face a pricing landscape where logistics concentration amplifies procurement power for integrated campus operators while squeezing margins for fragmented component specialists.
Pricing Analysis
IPC-A-610 Class 3 certification dictates the pricing tier structure across automotive EMS contracts, separating ASIL-D validated assemblies commanding engineering premiums from standard Class 2 production. Pricing stratifies across premium, standard, and economy tiers based on functional safety grade and volume commitment scale, with long-term offtake agreements dominating OEM procurement. Cost compression in standard-tier PCB assembly is intensifying because Chinese campus operators are absorbing test fixture capital intensity through shared infrastructure pools. Tier-1 suppliers exhibit highest price sensitivity due to captive fab alternative evaluation, while OEMs direct-sourcing domain controllers prioritize single-source accountability over unit cost minimization.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for automotive EMS providers serving North American EV programs. High-Tg laminates and low-loss dielectrics for HDI PCBs draw from Japanese and Taiwanese substrate specialists, while automotive-grade MCUs and silicon carbide power discretes source predominantly from Taiwan and South Korea. Single-source vulnerability concentrates in advanced substrate interposers for chiplet-based packaging, where heterogeneous integration requirements outstrip qualified supplier expansion. Distribution runs through integrated campus-to-OEM direct fulfillment models, displacing traditional distributor intermediation for high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive EMS market fragmentation creates entry niches as zonal E/E architecture convergence splinters legacy component categories into system-level integration opportunities. Domain controller consolidation and cybersecurity compliance burdens favor specialized players over generalist assemblers.
For Market Incumbents: Entrench platform relationships through captive ISO 26262 auditor accreditation and ASIL-D validation infrastructure investments that emerging competitors cannot replicate within compressed OEM qualification windows. Prioritize backward integration into high-density interconnect PCB fabrication to capture margin compression points currently held by substrate specialists. Defend against Foxconn and BYD Electronics scale advantages by anchoring regional fulfillment networks in Mexico and Eastern Europe with USMCA-advantaged export positioning.
For New Entrants and Emerging Players: Pursue EU AI Act compliance service white space in secure software integration cells, where UNECE WP.29 cybersecurity mandates create validated supplier scarcity for V2X module assembly. Target aftermarket ECU refurbishment and warranty return processing segments with shorter validation cycles and lower certification barriers than OEM-direct programs. Establish go-to-market positioning through Tier-1 supplier subcontractor relationships rather than direct OEM pursuit, leveraging incumbent qualification pathways.
For Investors and Strategic Acquirers: Regional specialists with IPC-A-610 Class 3 certification and established OEM relationships represent the most defensible acquisition profile as procurement consolidation reduces qualified supplier lists. Long-term viability hinges on embedded firmware talent depth and functional safety software validation capabilities that automate compliance cost structures. Watch for inflection signals in OEM domain controller program award announcements, where multi-year system integration contract bundling indicates procurement compression acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Software Integration Cell Buildout | Captures EU AI Act and UNECE WP.29 compliance value as cybersecurity mandates propagate downstream. |
| Mexico Campus Expansion | Satisfies USMCA content rules and reduces logistics exposure for Detroit Three EV programs. |
| Flip-Chip and Wire-Bond Capability Acquisition | Enables chiplet-based packaging for silicon carbide power module heterogeneous integration. |
| ISO 26262 ASIL-D Auditor Accreditation | Creates qualification barrier against uncertified competitors pursuing safety-critical domain controller assembly. |
| Automated Optical Inspection Line Investment | Captures high-barrier testing services margin as multi-layer HDI PCB node densities escalate. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, EMS facility operations managers, and automotive semiconductor distribution specialists; and secondary validation against SEC 10-K filings, vehicle production databases, IHS Markit registration data, and customs trade records. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from EMS provider revenue disclosures and automotive electronics content-per-vehicle benchmarks.
Forecast inputs span product type segmentation across ECU, PCB assembly, sensor, and wiring harness categories; technology tiers separating embedded systems from IoT solutions; and end-user distinctions between Tier-1 supplier outsourcing and OEM direct procurement. Vehicle class, propulsion architecture, and regional production cluster dimensions anchor the analytical framework across the projection horizon. CAGRs derive from regression analysis of historical outsourcing penetration rates correlated with powertrain electrification program announcements and safety mandate implementation timelines.
Sensitivities concentrate around semiconductor input allocation disruptions, functional safety certification timeline extensions, and nearshoring investment pace acceleration. Forecasts reflect documented assumptions regarding EV adoption trajectories and regulatory compliance burden propagation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Russia Automotive Eps Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Automotive E-Axle Market