
 Automotive Power Steering Pump Market | 2026-2036
Automotive Power Steering Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Steering Pump Market Analytics
China is reconfiguring regional supply patterns through expanded electric steering component capacity. Robert Bosch GmbH leverages its integrated motor-pump manufacturing footprint to serve European and Asian OEM programs. ZF Friedrichshafen AG anchors its competitive stance through R&D intensity in brushless DC steering architectures. JTEKT Corporation specializes in compact hydraulic units for legacy commercial vehicle platforms where conversion timelines lag.
An automotive power steering pump converts rotational engine energy into pressurized hydraulic fluid or electrical assistance to reduce steering effort, with modern electric variants employing brushless DC motors rated between 250–800 watts depending on vehicle class. Its primary industrial purpose is enabling precise vehicle directional control while minimizing driver fatigue across passenger cars, light trucks, and commercial vehicles. Hydraulic product type retains residual share in heavy-duty segments where load-bearing capacity demands persist, though electric systems capture margin pools through higher unit values and software integration. Brushless DC technology leads installation growth as OEMs prioritize energy recuperation and on-demand torque modulation.
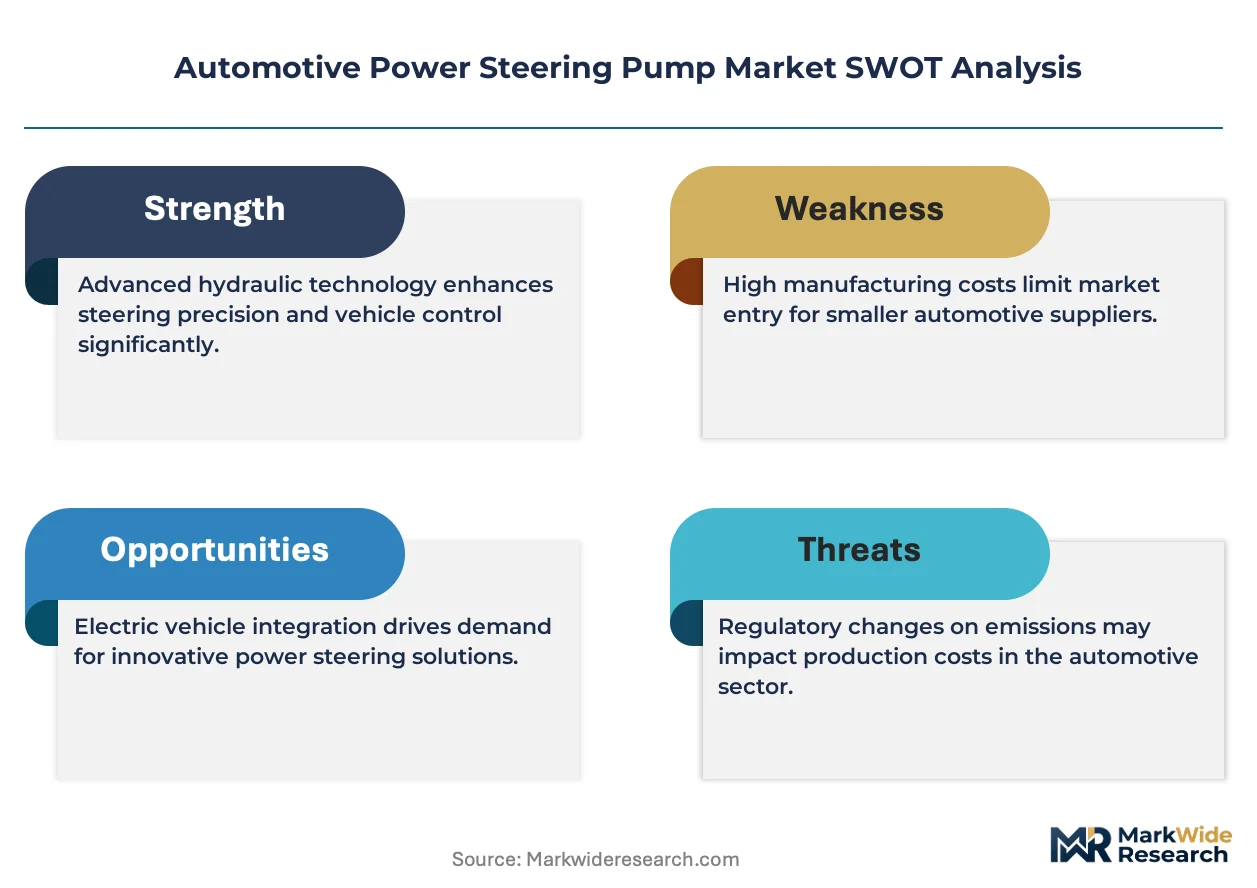
NHTSA safety standards govern steering system failure-mode requirements in the United States, while EPA fuel-economy regulations penalize parasitic hydraulic losses that electric pumps eliminate. ECE R79 in Europe mandates steering performance validation across speed ranges, reinforcing product certification barriers for non-compliant suppliers. Stakeholders must monitor how NEV platform proliferation in China and India reshapes procurement specifications before committing capacity allocation across hydraulic and electric production lines.
Market Dynamics
EPA fuel-economy standards and EU CO2 fleet mandates are forcing hydraulic-to-electric conversion programs across OEM supply chains, compressing legacy pump procurement timelines while amplifying brushless DC motor demand.
Growth Catalysts
- EPA Fuel-Economy Penalties:Parasitic hydraulic losses trigger compliance costs that electric pumps eliminate, accelerating electrification roadmaps for passenger vehicle platforms.
- NEV Procurement Volumes:China's new energy vehicle targets amplify steering system electrification requirements through domestic OEM production scale.
- Brushless DC Architecture:On-demand torque modulation and energy recuperation capabilities align with fleet efficiency mandates while reducing component count.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings concentrate supply risk in Chinese processing facilities, squeezing electric pump cost structures.
- Heavy-Duty Hydraulic Lock-In:Load-bearing capacity requirements in commercial trucking segments preserve hydraulic share where electric torque density remains insufficient.
- ECE R79 Certification Barriers:Steering performance validation across speed ranges creates product approval friction for non-European suppliers entering EU markets.
Strategic Opportunities
- India NEV Platform Proliferation:Subsidy schemes and domestic manufacturing incentives reshape procurement specifications before capacity allocation finalizes.
- Software-Defined Steering:Integration of torque modulation algorithms with ADAS architectures creates recurring revenue streams beyond hardware sales.
- Commercial Vehicle Electrification Lag:Extended conversion timelines in legacy trucking fleets allow hybrid hydraulic-electric transitional product development.
Industry Challenges
- Brushless DC Motor Control Expertise:Shortage of embedded firmware engineers with automotive safety-critical experience delays electric pump program launches.
- Dual Production Line Capex:Simultaneous hydraulic and electric capacity expansion strains balance sheets during technology transition windows.
- ISO 26262 Functional Safety Timeline:ASIL-D certification requirements for steering systems extend validation cycles and compress margin recovery periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Steering Pump Market |
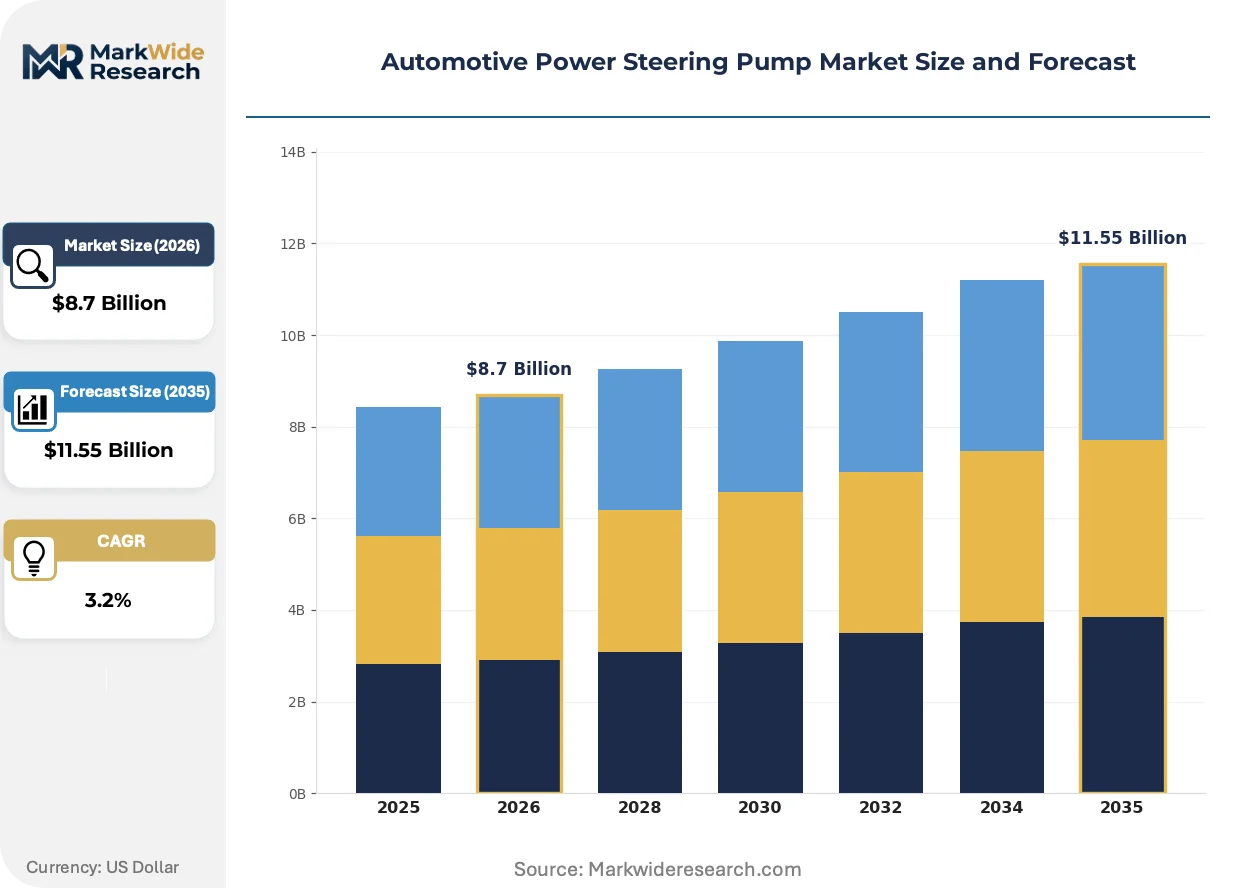
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Electric, Electro-Hydraulic, Variable Assist End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Service Centers Technology: Brushless DC, AC Synchronous, Power-On-Demand, Conventional Installation: Rack and Pinion, Recirculating Ball, Integral, Remote |
| Companies Covered | Robert Bosch GmbH, ZF Friedrichshafen AG, JTEKT Corporation, Nexteer Automotive, Denso Corporation, Mando Corporation, Hitachi Astemo, Showa Corporation, TRW Automotive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Steering Pump Market Evolving Landscape
Steering system architecture is digitizing through embedded motor control, regulatory pressure is compressing hydraulic residual share, and procurement patterns are consolidating around integrated Tier 1 supply relationships.
Integrated motor-pump units with embedded torque sensors and CAN bus communication are digitizing steering feedback loops for real-time vehicle dynamics adjustment. Passenger car OEMs in Germany and Japan are adopting these architectures at program refresh cycles rather than platform redesigns. The technology is digitizing traditional hydraulic valve bodies into software-modulated current loops, collapsing mechanical component counts while expanding margin capture through firmware licensing.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are eliminating hydraulic fluid formulations with high global warming potential from new vehicle certifications. This industrial consequence accelerates electric pump adoption in European passenger vehicle segments previously tolerant of hydraulic efficiency penalties. Light commercial van manufacturers in Spain and Poland are responding fastest, driven by fleet operator pressure for Scope 3 emissions reporting compliance.
Consolidated Tier 1 supply relationships are displacing fragmented multi-source procurement as OEMs seek single-responsibility steering system integration. Direct purchasing from integrated motor-pump specialists is replacing traditional hydraulic component distributor networks in passenger vehicle channels. This concentration is most visible in China's Yangtze River Delta manufacturing cluster, where NEV platform producers bundle steering electrification with battery thermal management contracts.
Automotive Power Steering Pump Market Segmentation
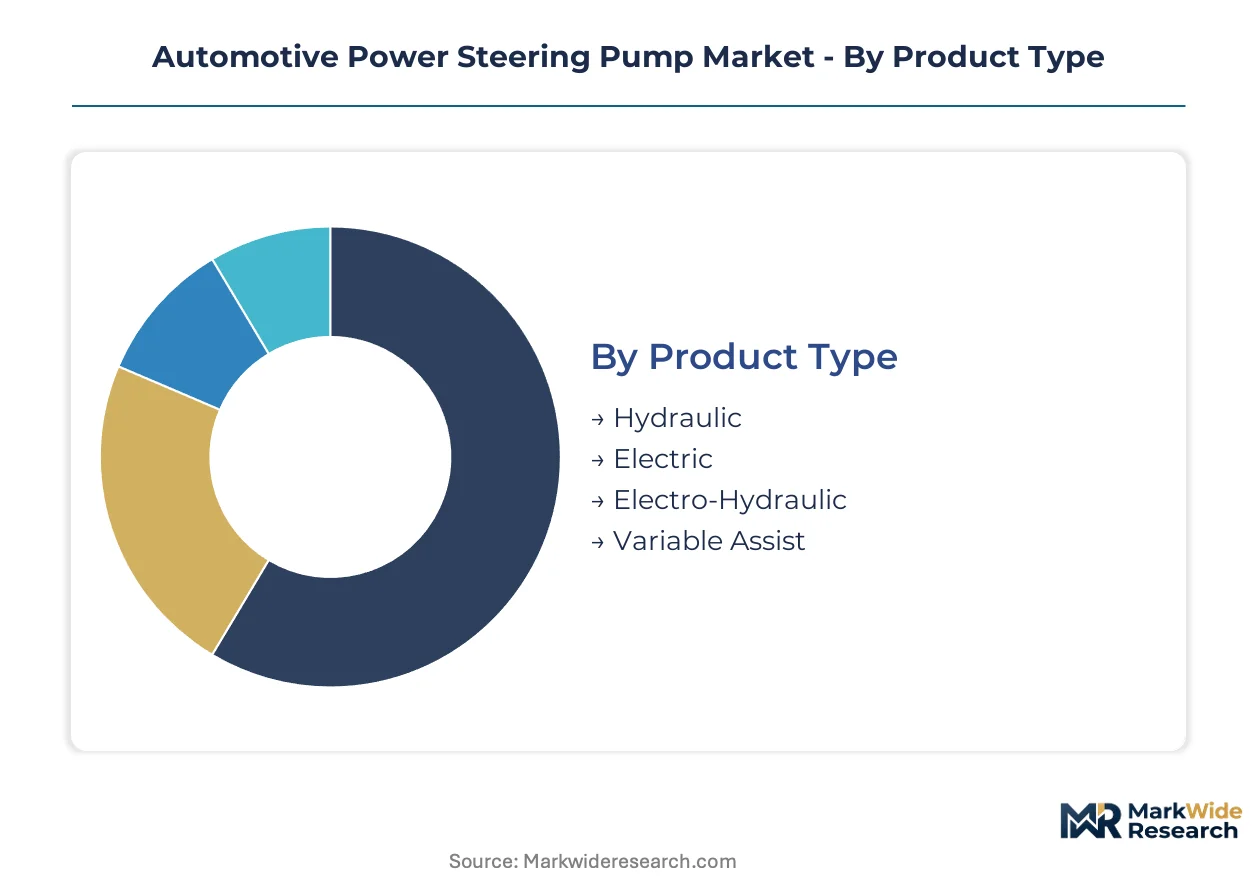
Segmentation in the automotive power steering pump market exposes divergent technology adoption curves across vehicle classes and regulatory environments. Distinct procurement patterns separate passenger vehicle electrification from commercial hydraulic retention, while installation architectures determine supplier integration depth with OEM chassis programs.
Product Type:
Cost tier differentiation separates legacy hydraulic systems from premium electric architectures, with mid-range electro-hydraulic variants bridging technology transition gaps.
- Electric:Brushless DC motor-driven units rated 250–800 watts eliminate parasitic engine load through on-demand torque delivery. Demand concentrates in German and Japanese passenger vehicle OEMs facing EU CO2 fleet mandates and EPA fuel-economy penalties, with procurement volumes amplifying through China's NEV platform proliferation.
- Hydraulic:Engine-driven vane or gear pumps generate continuous hydraulic pressure through belt-pulley mechanical coupling. Commercial trucking fleets in North America and heavy-duty segments across India preserve installed share where load-bearing capacity requirements exceed current electric torque density limits.
- Electro-Hydraulic:Hybrid architectures retain hydraulic actuation while replacing continuous engine drive with electric motor-on-demand. Transit bus manufacturers in Spain and Poland favor this transitional configuration for fleet electrification roadmaps.
- Variable Assist:Speed-sensitive hydraulic flow modulation reduces pump output at highway speeds through electronic solenoid control. Light truck platforms in legacy OEM programs employ this cost-optimized efficiency bridge.
Electric holds installed capacity in passenger vehicle greenfield platforms. Electro-Hydraulic is rotating up the share rankings in commercial vehicle transition segments.
End User:
Customer type determines contract structure, with direct OEM supply relationships displacing fragmented aftermarket channels as electrification concentrates procurement authority.
- OEMs:Original equipment manufacturers specify integrated motor-pump units with embedded CAN bus communication and torque sensor feedback. Volkswagen Group, Toyota, and BYD bundle steering electrification with thermal management contracts in Yangtze River Delta manufacturing clusters.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities procure steering systems through Tier 1 consolidated supply relationships. SAIC-GM and FAW-Volkswagen operations in China source through Robert Bosch GmbH integrated manufacturing footprints.
- Aftermarket Providers:Independent distributors serve legacy hydraulic replacement demand in aging vehicle parcs across Eastern European and Southeast Asian markets.
- Service Centers:Dealer networks and independent repair facilities handle warranty electric pump replacements and hydraulic system refurbishment.
OEMs hold installed capacity in electric platform procurement. Vehicle Assemblers is rotating up the share rankings as NEV joint ventures expand production scale.
Technology:
Maturity gradients separate established brushless DC architectures from emerging power-on-demand intelligence, with AC synchronous variants serving specific thermal and efficiency envelopes.
- Brushless DC:Permanent magnet synchronous motors with Hall-effect position sensing enable precise torque modulation and energy recuperation. ZF Friedrichshafen AG anchors competitive positioning through R&D intensity in this architecture for European and Asian OEM programs.
- Power-On-Demand:Intelligent current-loop control adjusts motor output based on real-time steering angle, vehicle speed, and lateral acceleration inputs. ADAS integration requirements in premium German platforms drive firmware licensing revenue beyond hardware margins.
- AC Synchronous:Induction motor alternatives reduce rare earth magnet dependency amid neodymium price volatility concentrated in Chinese processing facilities.
- Conventional:Brushed DC and hydraulic valve-body technologies retain residual share in cost-sensitive economy vehicle segments and legacy commercial platforms.
Brushless DC holds installed capacity across passenger vehicle electrification. Power-On-Demand is rotating up the share rankings through software-defined steering integration.
Installation:
Application architecture determines mechanical packaging constraints, with rack and pinion dominance in passenger vehicles contrasting recirculating ball retention in heavy-duty frames.
- Rack and Pinion:Linear steering gear integrated directly with the front axle crossmember provides precise feedback and compact packaging. Compact and mid-size passenger cars across China, Germany, and Japan standardize this configuration with electric power assist modules.
- Recirculating Ball:Worm gear and ball nut mechanism multiplies steering torque for heavy load-bearing requirements. Full-size pickup trucks in North America and commercial vehicle chassis in India preserve this architecture with hydraulic or electro-hydraulic assist.
- Integral:Steering gear and power assist cylinder combined in single housing unit. Classic rear-wheel-drive platforms and specialty vehicle manufacturers employ this consolidated packaging.
- Remote:Power assist unit mounted separately from steering gear via hydraulic lines or electrical harnesses. Aftermarket conversion kits and certain commercial vehicle configurations utilize this flexible mounting approach.
Rack and Pinion holds installed capacity in passenger vehicle platforms. Recirculating Ball is rotating up the share rankings in commercial vehicle electrification lag segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for electric steering components clusters in China, Germany, Japan, and the United States, with each geography responding to distinct regulatory pressures and OEM procurement timelines. NEV platform proliferation and emissions mandates are redrawing supplier footprints across these production centers.
China
Domestic vehicle production scale and NEV procurement targets are amplifying demand for steering system electrification in the Yangtze River Delta cluster. MIIT dual carbon goals and GB standards for new energy vehicles mandate efficiency improvements that hydraulic pumps cannot deliver. BYD and SAIC-GM operations in Shanghai and Jiangsu province are bundling steering electrification with battery thermal management contracts.
Germany
Volkswagen Group and premium OEM programs are driving brushless DC motor adoption to meet EU CO2 fleet mandates and avoid penalty payments. ECE R79 steering performance validation requirements create certification barriers that favor established Tier 1 suppliers with EU testing infrastructure. Manufacturing concentrates in Baden-Württemberg and Lower Saxony, where ZF Friedrichshafen AG anchors R&D intensity in integrated motor-pump architectures.
United States
EPA fuel-economy penalties on parasitic hydraulic losses are compressing conversion timelines for passenger vehicle platforms. NHTSA safety standards govern steering system failure-mode requirements, reinforcing supplier qualification barriers. Production activity centers on Michigan and Ohio, where Detroit Three OEMs are refreshing programs with electric power assist modules rather than waiting for full platform redesigns.
Japan
Toyota and Honda electrification roadmaps are standardizing brushless DC steering across compact and mid-size vehicle lines. METI efficiency regulations and JIS standards support technology transition while preserving quality certification rigor. Manufacturing concentrates in Aichi and Shizuoka prefectures, where JTEKT Corporation and Denso Corporation maintain integrated production footprints for domestic and export supply.
India
Subsidy schemes and PLI scheme incentives for domestic manufacturing are reshaping procurement specifications before capacity allocation finalizes. Heavy-duty commercial vehicle segments preserve hydraulic share where load-bearing requirements exceed current electric torque density. Manufacturing activity clusters in Maharashtra and Tamil Nadu, where joint-venture assemblers source through consolidated Tier 1 relationships.
Automotive Power Steering Pump Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in motor and pump sub-assembly supply. The supplier base exhibits tiered consolidation, with integrated motor-pump manufacturers capturing direct OEM relationships while hydraulic component distributors lose share in passenger vehicle channels. Three archetypes dominate: German-Japanese conglomerates with full-system integration capability, Korean-Taiwanese specialists in brushless DC motor control, and legacy hydraulic fabricators serving commercial vehicle transition timelines. Competitive moves center on firmware licensing for torque modulation algorithms and capacity allocation across dual hydraulic-electric production lines.
Within the integrated-system tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the German conglomerate archetype with manufacturing footprints spanning European and Asian OEM programs. JTEKT Corporation occupies a position representing Japanese specialists with heritage in compact hydraulic units and evolving electric architectures. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across the electrification transition.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| JTEKT Corporation |
| Nexteer Automotive |
| Denso Corporation |
| Mando Corporation |
| Hitachi Astemo |
| Showa Corporation |
| TRW Automotive |
| Others |
Value Network & Pricing Analysis
Rare earth magnet processing concentration in Chinese facilities captures margin pools downstream in electric power steering pump manufacturing, where neodymium and dysprosium cost volatility feeds directly into Tier 1 supplier pricing power. OEM procurement consolidation around integrated motor-pump units has shifted value capture toward firmware-embedded architectures and away from commodity hydraulic components.
Pricing Analysis
EU CO2 fleet mandates and EPA fuel-economy penalties dictate the pricing tier structure across electric, electro-hydraulic, and hydraulic pump categories. Three-tier pricing structure across premium brushless DC systems, standard electro-hydraulic transitional units, and economy-grade hydraulic legacy products separates OEMs by compliance urgency and platform electrification timeline. Cost compression in hydraulic tiers is intensifying because electric alternatives eliminate parasitic losses that trigger regulatory penalties. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity, while premium passenger vehicle OEMs prioritize software integration over unit cost.
Supply Chain Analysis
Tariff exposure between China and major automotive manufacturing regions dominates supply chain risk assessment for rare earth magnet-dependent electric pump production. Manufacturing concentrates in China, Germany, and Japan, with component sourcing drawing from Malaysian semiconductor packaging facilities and Taiwanese motor control IC foundries. Neodymium magnet supply, copper winding materials, and Hall-effect position sensors constitute critical input dependencies. Single-source vulnerability in Chinese rare earth processing facilities threatens cost stability. Distribution runs through consolidated Tier 1 direct supply relationships rather than fragmented aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around OEM platform integrators capable of bundling steering electrification with thermal management and battery system contracts, compressing supplier margins and favoring full-system specialists over component vendors.
For Market Incumbents: Build firmware licensing moats around torque modulation algorithms integrated with ADAS architectures. Secure ASIL-D certification ahead of competitor timelines to lock in Volkswagen Group and Toyota platform programs. Acquire brushless DC motor control engineering talent from Korean-Taiwanese specialist firms to offset embedded firmware engineer shortages. Deepen backward integration into rare earth magnet supply through offtake agreements with Chinese processing facilities to hedge neodymium price volatility. For New Entrants and Emerging Players: Mid-market commercial vehicle electrification lag in India and Southeast Asia represents the most penetrable entry point for hybrid electro-hydraulic transitional products. Transit bus fleet operators in Spain and Poland seeking F-Gas Regulation compliance offer immediate procurement windows before full electric conversion. Target aftermarket hydraulic refurbishment channels in Eastern European aging vehicle parcs where OEM direct relationships remain unconsolidated. Pursue joint development contracts with emerging NEV platform producers in India's Maharashtra and Tamil Nadu manufacturing clusters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive component platforms holding hydraulic legacy revenue but lacking electric architecture transition capital. Five-to-ten-year viability hinges on dual-production-line capex deployment timing and firmware differentiation rather than manufacturing scale alone. Target acquisition archetype: mid-cap electro-hydraulic specialists with established commercial vehicle relationships and unexploited brushless DC R&D pipelines. Monitor India PLI scheme incentive disbursement velocity as inflection indicator for NEV procurement specification finalization.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Motor Control Firmware Development | Torque modulation algorithms licensed to German and Japanese OEMs generate recurring revenue beyond hardware margins. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processing facilities hedge neodymium price volatility for electric pump cost structures. |
| ASIL-D Functional Safety Certification | ISO 26262 compliance accelerates qualification for Volkswagen Group and Toyota steering system programs. |
| India Manufacturing Footprint Expansion | PLI scheme incentives and NEV platform proliferation in Maharashtra clusters capture emerging procurement volumes. |
| ADAS Integration Partnership | Software-defined steering architectures bundled with autonomous vehicle platforms deepen OEM relationship stickiness. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering teams, Tier 1 supplier procurement directors, aftermarket distribution channel managers, and commercial vehicle fleet operators. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings of listed automotive suppliers, and customs trade records for rare earth magnet flows. Bottom-up segment sizing triangulated against top-down market envelope estimates from regulatory compliance modeling.
Historical volume and value outputs were calibrated against actual OEM program launches and platform refresh cycles across the projection horizon. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster regulatory stringency. CAGRs were derived from technology adoption curve fitting against EPA and EU mandate compliance deadlines, with electric pump penetration rates cross-referenced to NEV production forecasts.
Stress conditions across rare earth magnet price volatility, commercial vehicle electrification timeline delays, and ASIL-D certification bottleneck severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory penalty enforcement consistency and OEM platform electrification commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Power Steering Cooler Market
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Engines Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Europe Electro Hydraulic Power Steering Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Diesel Engine Market
Powertrain
Automotive Coil Spring Market
Powertrain
Turbocharger Market
Powertrain
Transmission Fluids Market
Powertrain
Global Automotive Fuel Delivery and Injection Systems Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Power Liftgate for Automotive Market