
 Automotive Pressure Sensors Market | 2026-2036
Automotive Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Pressure Sensors Market Analysis
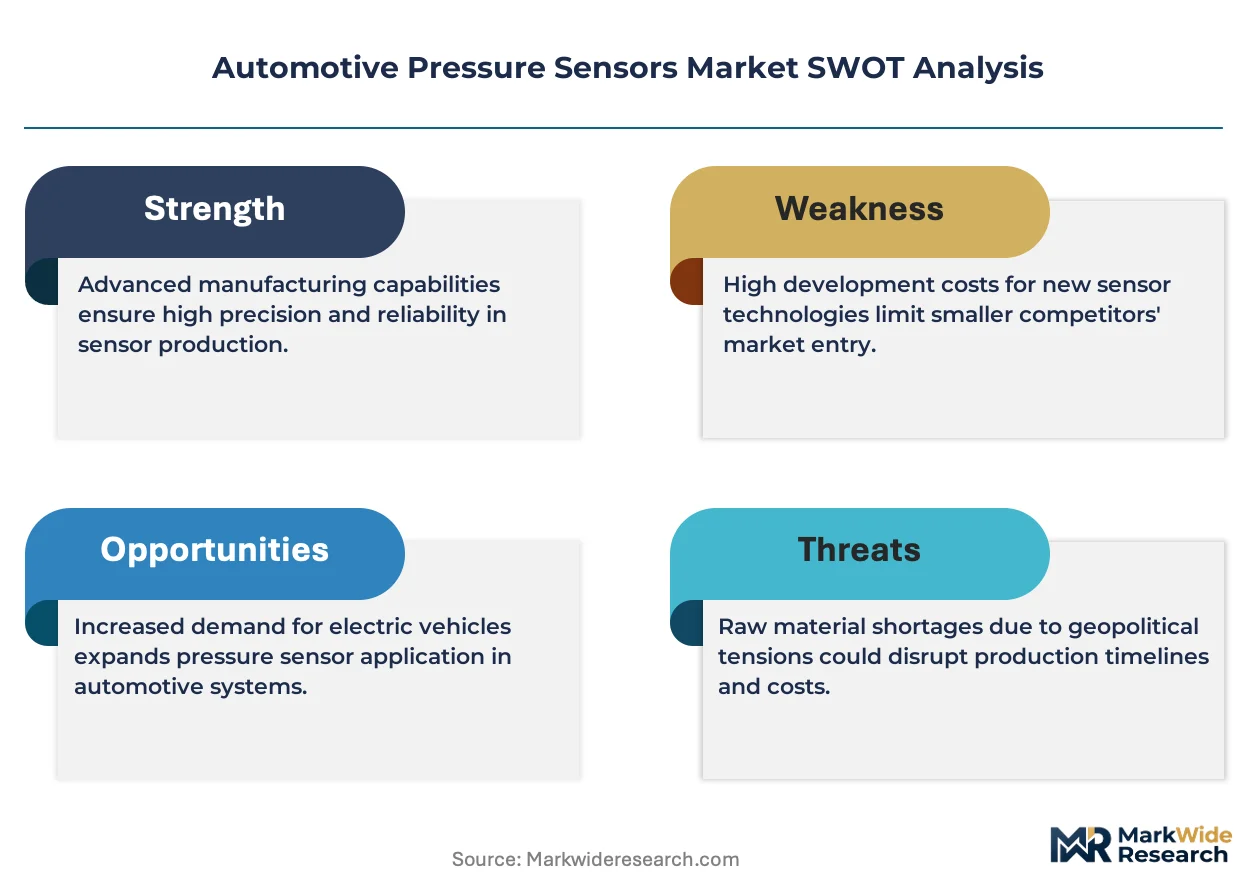
Asset-light manufacturing partnerships and sensor-as-a-service leasing models is reconfiguring competitive entry barriers for mid-tier suppliers. Sensata Technologies leverages its captive MEMS fabrication capacity to sustain margin control across tire and brake pressure categories. Robert Bosch GmbH anchors European OEM supply through integrated calibration networks. Infineon Technologies AG differentiates via silicon-carbide compatible sensing architectures for high-voltage electric vehicle platforms.
Automotive pressure sensors are transducer devices that convert fluid or gas pressure into electrical signals, typically operating across ranges from 0.5 bar to 700 bar with accuracy tolerances of ±0.25% full scale, and serve primarily to enable real-time powertrain optimization, occupant safety systems, and emissions compliance monitoring. Tire pressure sensors dominate unit volume due to mandatory direct TPMS fitment in major automotive markets, while brake pressure sensors command premium pricing through integration with electronic stability control and autonomous emergency braking systems. Digital sensors are displacing analog architectures fastest in electric vehicle applications where controller-area-network communication reduces wiring complexity.
The EPA tailpipe standards and NHTSA Federal Motor Vehicle Safety Standards govern sensor accuracy and durability requirements in the United States, while EU Green Deal emissions targets and CE marking obligations shape European product certification pathways. China's MIIT new-energy vehicle mandates and GB standards for battery system safety are creating divergent technical specifications that fragment sensor design homogeneity. Stakeholders must monitor regulatory divergence between major automotive markets to determine whether regional sensor variants or unified global platforms offer superior capital efficiency.
Market Dynamics
Electrification roadmaps across major automotive manufacturing clusters are forcing sensor architecture redesigns, as high-voltage battery thermal management and electric powertrain monitoring displace legacy internal-combustion measurement points with precision digital sensing requirements.
Growth Catalysts
- EU Green Deal emissions mandates:Fleet-average CO2 reduction targets require real-time powertrain optimization, multiplying sensor density per vehicle across German and French OEM supply chains.
- Silicon-carbide compatible architectures:High-voltage electric vehicle platforms demand sensing elements rated for 800V+ operation, opening specification windows for advanced piezoelectric and MEMS designs.
- TPMS regulatory harmonization:Direct tire pressure monitoring mandates from NHTSA in the United States and corresponding GB standards in China sustain baseline unit volume across passenger and commercial vehicle segments.
Market Restraints
- MEMS fabrication concentration:Captive cleanroom capacity resides with a limited supplier base in Germany, Japan, and the United States, constraining mid-tier access to cost-competitive sensing elements.
- Raw material volatility:Palladium and platinum group metal pricing fluctuations impact piezoelectric ceramic electrode costs, compressing margin stability for brake and exhaust pressure sensor categories.
- Regulatory fragmentation:Divergent GB standards for battery system safety in China versus EPA tailpipe accuracy requirements in the United States force redundant design validation cycles.
Strategic Opportunities
- India automotive electrification:PLI scheme incentives for domestic electric vehicle manufacturing create first-mover positioning for localized pressure sensor assembly and calibration infrastructure.
- Sensor-as-a-service leasing:Fleet operators in Germany and the United States are piloting subscription-based tire and brake monitoring, shifting revenue from unit sales to recurring data services.
- ADAS sensor fusion convergence:Integration of pressure data with lidar and radar inputs for autonomous emergency braking creates specification pull from Tier-1 integrators seeking consolidated sensing modules.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for ASIL-D rated brake pressure sensors extends development timelines by 18-24 months.
- Legacy vehicle integration:Analog-to-digital protocol translation for controller-area-network retrofit in existing fleets demands backward-compatible form factors that constrain miniaturization roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Pressure Sensors Market |
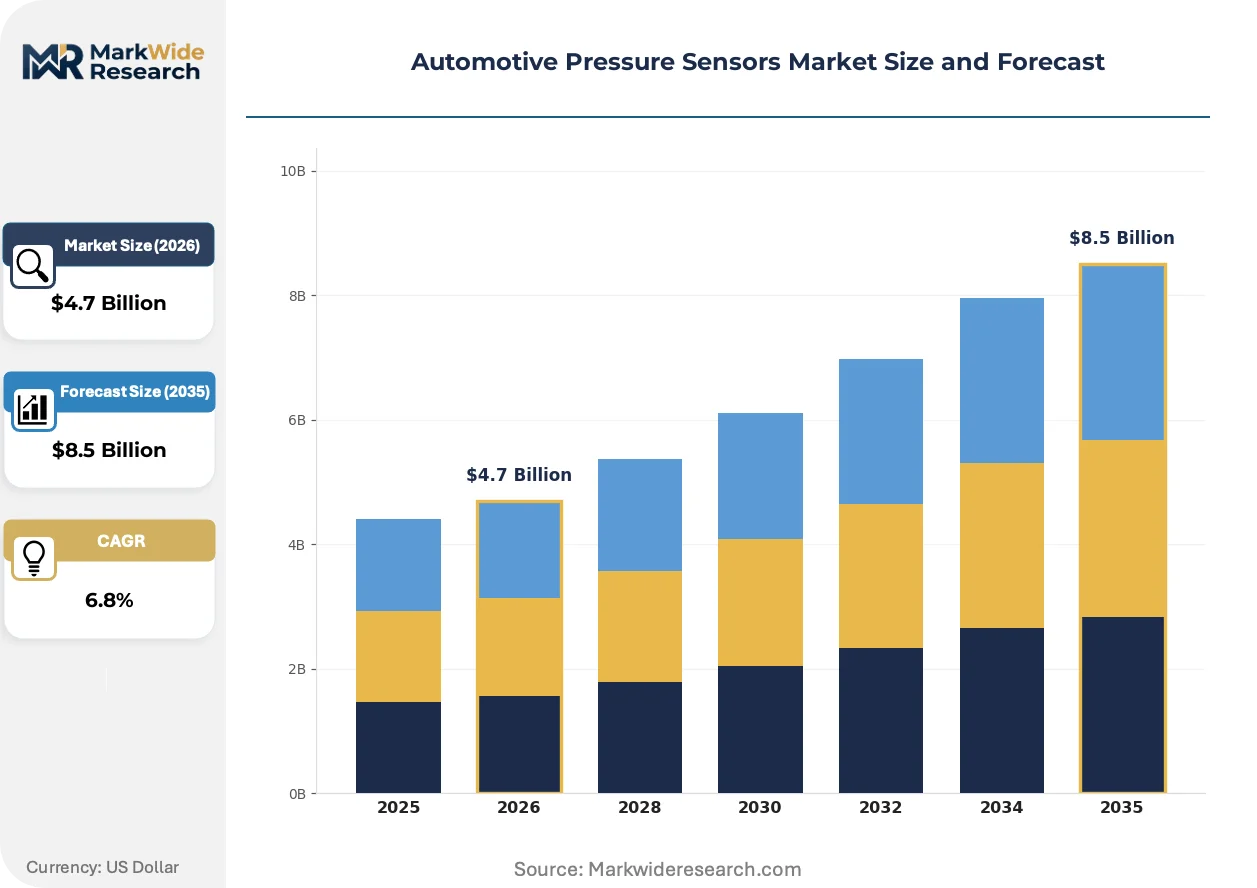
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
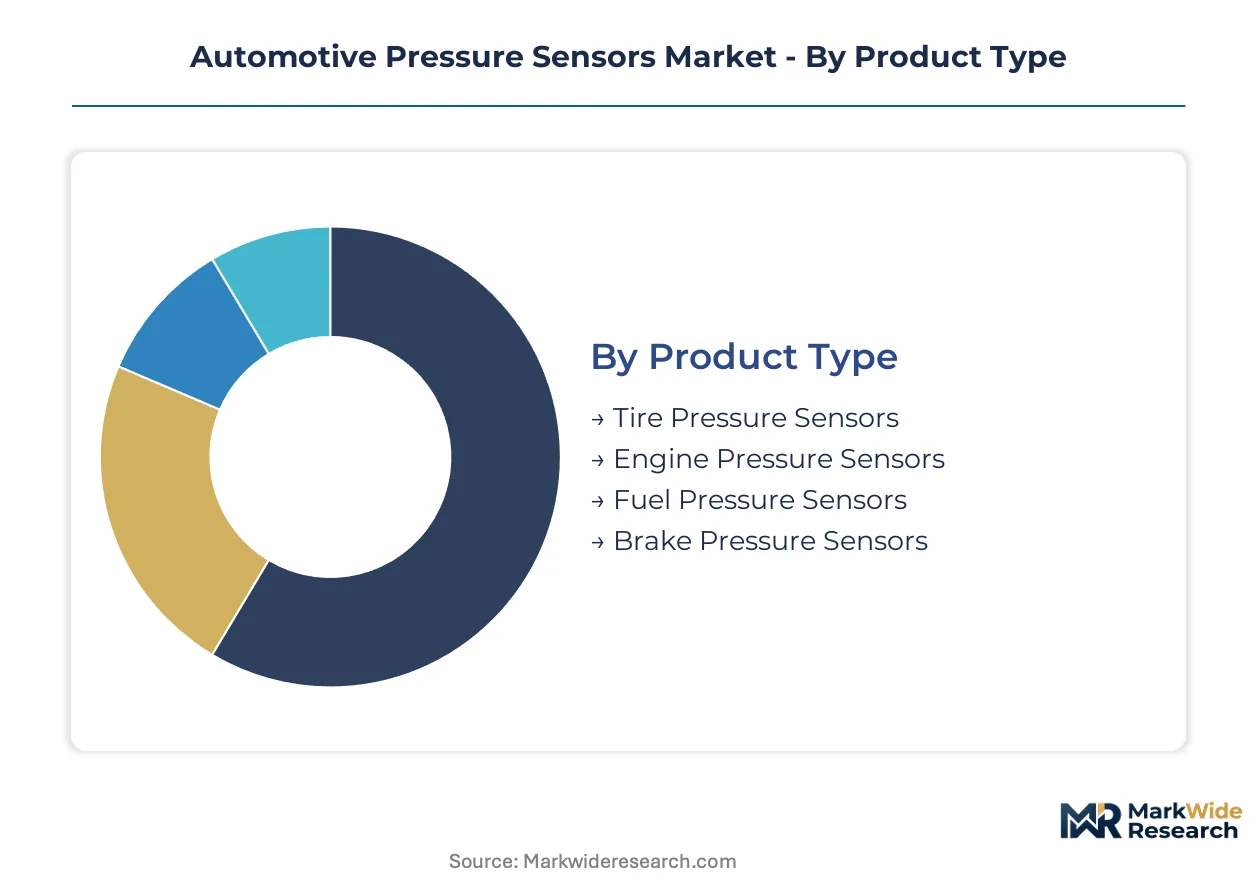
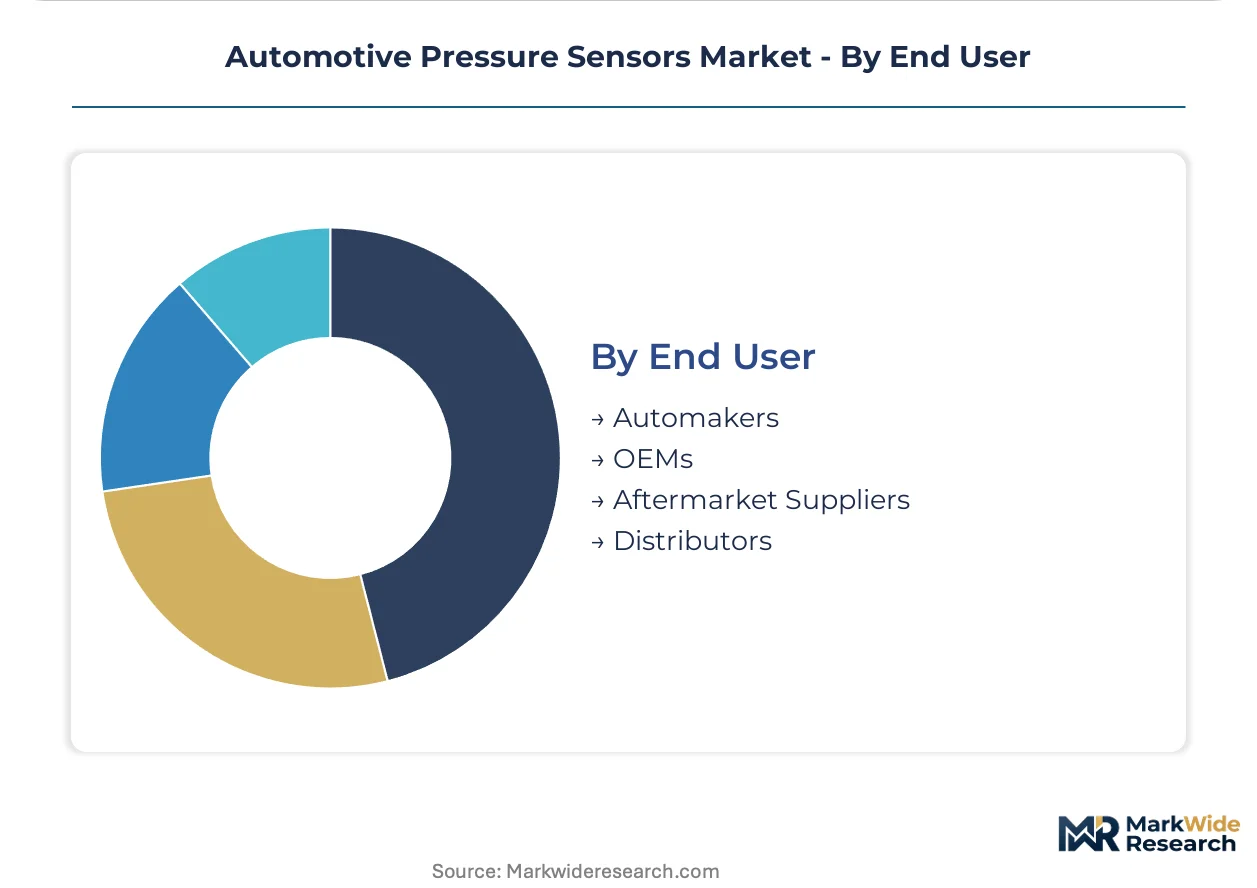
| Segmentation | Product Type: Tire Pressure Sensors, Engine Pressure Sensors, Fuel Pressure Sensors, Brake Pressure Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Piezoelectric Sensors Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Electric Vehicles End User: Automakers, OEMs, Aftermarket Suppliers, Distributors |
| Companies Covered | Sensata Technologies, Infineon Technologies AG, Robert Bosch GmbH, Honeywell International Inc., STMicroelectronics, DENSO Corporation, TE Connectivity, NXP Semiconductors, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Pressure Sensors Market Emerging Trajectories
Digital sensing architectures and wireless telemetry protocols are compressing wiring harness complexity while enabling edge-computing diagnostics, fundamentally altering how pressure data flows through vehicle networks.
MEMS-based capacitive pressure sensing is migrating from analog voltage-output designs toward digital I2C and SPI interfaces with onboard temperature compensation. Electric vehicle manufacturers in Germany and China are specifying these digital variants for battery thermal management modules. This migration from analog architectures eliminates signal-conditioning electronics, reducing bill-of-materials cost and electromagnetic interference susceptibility.
EPA tailpipe standards and NHTSA Federal Motor Vehicle Safety Standards are tightening accuracy tolerances for exhaust and brake pressure monitoring, mandating ±0.25% full-scale precision across temperature extremes. Sensor suppliers must recalibrate production test protocols and expand environmental chamber capacity. Heavy-duty commercial vehicle segments in the United States face the most immediate compliance deadlines, accelerating procurement of validated sensor platforms.
Fleet maintenance departments are unbundling sensor replacement from dealer service networks, sourcing direct-fit aftermarket units through e-commerce channels and mobile diagnostic providers. Independent repair shops in the United States and Germany now account for a growing share of TPMS and brake pressure sensor volume. This channel shift pressures OEM-captive pricing structures while rewarding suppliers with aftermarket brand recognition and cross-reference database completeness.
Automotive Pressure Sensors Market Segmentation
Automotive pressure sensor procurement patterns diverge sharply across vehicle architectures and supply chain tiers. Understanding these fault lines reveals where specification power concentrates and which technology transitions command capital allocation priority.
Product Type:
Mature regulatory mandates anchor volume in established categories, while emerging electrification requirements reshape specification trajectories for powertrain-adjacent variants.
- Tire Pressure Sensors:MEMS-based capacitive transducers operating at 433 MHz or 315 MHz transmit real-time inflation data to vehicle control modules. NHTSA direct TPMS mandates and corresponding GB standards in China sustain unit volume across German and Japanese OEM supply chains, though module pricing faces persistent compression from aftermarket competitors.
- Brake Pressure Sensors:Piezoelectric and strain-gauge architectures rated for 200+ bar hydraulic pressure enable electronic stability control and autonomous emergency braking. These command premium positioning through ASIL-D functional safety requirements and integration with ADAS sensor fusion arrays in Detroit and Stuttgart manufacturing clusters.
- Engine Pressure Sensors:Manifold absolute pressure variants with ceramic diaphragm technology support internal combustion powertrain optimization.
- Fuel Pressure Sensors:Stainless steel isolated designs withstand corrosive biofuel blends and high-pressure direct injection rail environments.
Tire pressure sensors handle the majority of throughput; brake pressure sensors are expanding most quickly on share as ADAS penetration deepens.
Technology:
Cost tier stratification separates legacy analog architectures from digital and wireless variants commanding design wins in electrified platforms.
- Digital Sensors:I2C and SPI interface variants with onboard temperature compensation eliminate external signal conditioning. German and Chinese electric vehicle manufacturers specify these for battery thermal management modules, where controller-area-network integration reduces wiring complexity and electromagnetic interference susceptibility.
- Piezoelectric Sensors:Ceramic crystal elements generate charge signals proportional to dynamic pressure, excelling in high-frequency measurement contexts. These dominate brake and exhaust applications where 800V+ electric vehicle platforms demand silicon-carbide compatible sensing architectures.
- Analog Sensors:Voltage-output designs with external amplification persist in cost-sensitive commercial vehicle segments.
- Wireless Sensors:Battery-less passive RFID and energy-harvesting architectures enable retrofit TPMS and fleet monitoring without harness modifications.
Digital variants command the steepest expansion trajectory; analog sensors retain residual volume in heavy-duty retrofit channels.
Application:
Volume concentration in passenger segments contrasts with margin opportunity in electric vehicle platforms requiring redesigned thermal and powertrain monitoring architectures.
- Electric Vehicles:High-voltage battery pack thermal management and electric motor coolant loop monitoring demand precision digital sensors rated for 800V+ isolation. MIIT new-energy vehicle mandates in China and EPA tailpipe standards in the United States create divergent specification pathways that fragment design homogeneity.
- Passenger Vehicles:Direct TPMS fitment, brake pressure monitoring for ESC, and turbocharger boost control sustain baseline demand across German, Japanese, and United States manufacturing clusters.
- Commercial Vehicles:Heavy-duty exhaust aftertreatment and air brake systems drive durability-focused procurement with extended calibration intervals.
- Two-Wheelers:Simplified TPMS and fuel injection pressure variants address cost-constrained emerging market requirements.
Passenger vehicles handle the majority of throughput; electric vehicle applications are gaining share fastest as electrification roadmaps accelerate.
End User:
Supply concentration with Tier-1 integrators and OEMs shapes pricing power, while aftermarket channel expansion redirects replacement volume toward independent distributors.
- Automakers:Captive specification authority at Volkswagen, Toyota, and General Motors determines platform-level sensor architecture choices. These entities mandate calibration network compatibility and multi-year supply agreements that lock in Tier-1 sensor suppliers.
- Aftermarket Suppliers:E-commerce channels and mobile diagnostic providers in the United States and Germany now capture growing TPMS and brake pressure sensor volume as fleet maintenance departments bypass dealer service networks.
- OEMs:Tier-1 integrators consolidate sensing modules across multiple measurement points to reduce harness complexity.
- Distributors:Regional warehousing and cross-reference database completeness determine aftermarket capture rates.
Automakers control the majority of specification authority; aftermarket suppliers are climbing the fastest on volume share as fleet channel shifts mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA direct TPMS mandates and EPA tailpipe standards in the United States anchor baseline demand, while MIIT new-energy vehicle mandates in China and EU Green Deal emissions targets in Germany reshape specification trajectories across manufacturing clusters.
United States
Detroit manufacturing clusters drive procurement for brake pressure sensors integrated with ADAS platforms. NHTSA Federal Motor Vehicle Safety Standards mandate direct TPMS fitment across passenger and commercial segments. Heavy-duty vehicle producers in Michigan and Ohio face immediate compliance deadlines for exhaust aftertreatment sensors.
Germany
Stuttgart and Munich automotive clusters specify silicon-carbide compatible sensing architectures for 800V+ electric vehicle platforms. EU Green Deal fleet-average CO2 targets multiply sensor density per vehicle across Volkswagen and BMW supply chains. Bosch anchors European OEM supply through integrated calibration networks in Baden-Württemberg.
China
Shanghai and Shenzhen manufacturing bases scale procurement for battery thermal management sensors under MIIT new-energy vehicle mandates. GB standards for battery system safety create divergent technical specifications from Western markets. BYD and CATL supply chains in Guangdong and Jiangsu provinces drive digital sensor adoption.
Japan
Toyota City and Nagoya clusters sustain demand for precision manifold absolute pressure sensors in hybrid powertrain optimization. METI carbon neutrality roadmaps accelerate electrification sensor redesigns. Denso and Aisin supply networks in Aichi Prefecture concentrate MEMS fabrication capacity.
India
Tamil Nadu and Maharashtra automotive corridors attract PLI scheme incentives for domestic electric vehicle manufacturing. BIS certification requirements and state-level EV policies create first-mover positioning for localized sensor assembly. Chennai and Pune clusters host emerging calibration infrastructure for Tier-1 suppliers.
Automotive Pressure Sensors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where captive MEMS fabrication capacity separates margin-sustainable suppliers from price-pressured assemblers. The vendor base stratifies into three archetypes: integrated semiconductor fabricators with captive cleanroom capacity, Tier-1 automotive suppliers with OEM-locked specification authority, and regional component specialists serving aftermarket channels. Dominant competitive moves include backward integration into MEMS wafer production and strategic partnerships for 800V-compatible sensing architectures.
Within the integrated fabrication tier, Sensata Technologies and Infineon Technologies AG occupy positions defined by captive manufacturing depth, while Robert Bosch GmbH anchors European supply relationships through calibration network control. These three exemplify how geographic clustering—Massachusetts-based, Neubiberg-based, and Stuttgart-based respectively—correlates with regulatory proximity and OEM specification influence.
| Leading Market Players |
|---|
| Sensata Technologies |
| Infineon Technologies AG |
| Robert Bosch GmbH |
| Honeywell International Inc. |
| STMicroelectronics |
| DENSO Corporation |
| TE Connectivity |
| NXP Semiconductors |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Stuttgart's MEMS fabrication clusters in Baden-Württemberg concentrate captive cleanroom capacity for piezoelectric ceramic processing, translating upstream scarcity into premium pricing power for brake pressure sensors rated at ASIL-D functional safety levels. This geographic concentration of wafer-level production creates asymmetric leverage where Tier-1 suppliers with in-house fabrication command margin sustainability while mid-tier assemblers face persistent cost compression from palladium electrode volatility.
Pricing Analysis
Certification level creates the primary spread across the Automotive Pressure Sensors Market, with ISO 26262 ASIL-D rated brake pressure sensors commanding substantial premiums over standard TPMS variants. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety grade, volume commitment scale, and backward integration depth. Cost compression in aftermarket tire pressure sensors is intensifying because e-commerce channel expansion enables fleet operators to bypass dealer service networks. Heavy-duty commercial vehicle segments exhibit highest price sensitivity due to extended replacement cycles, while electric vehicle platform engineering teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced lithography equipment and silicon-carbide substrate technology limit MEMS fabrication capacity expansion outside established hubs in Germany, Japan, and the United States. Raw material dependencies center on palladium and platinum group metals for piezoelectric electrodes, high-purity silicon wafers for capacitive sensing elements, and ceramic substrates for high-temperature exhaust applications. Single-source vulnerability concentrates in 200mm MEMS wafer supply from Aichi Prefecture fabrication facilities. Distribution runs through Tier-1 integrator consolidation points in Detroit, Stuttgart, and Shanghai before final vehicle assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Pressure Sensors Market represents a high-growth disruption driven by 800V+ electric vehicle platform proliferation and divergent battery safety mandates across major manufacturing clusters. This technological inflection compresses legacy analog sensor margins while opening specification windows for silicon-carbide compatible architectures.
For Market Incumbents: Build calibration network moats by expanding environmental chamber capacity for EPA tailpipe accuracy validation and NHTSA Federal Motor Vehicle Safety Standards compliance. Deepen backward integration into MEMS wafer production to offset palladium electrode cost volatility threatening brake pressure sensor margins. Lock multi-year supply agreements with Volkswagen and Toyota platform engineering teams before MIIT new-energy vehicle mandates fragment design homogeneity further. For New Entrants and Emerging Players: Pursue sensor-as-a-service leasing pilots with German and United States fleet operators seeking subscription-based tire and brake monitoring solutions. Target India's Tamil Nadu and Maharashtra automotive corridors where PLI scheme incentives for domestic electric vehicle manufacturing create first-mover positioning for localized assembly infrastructure. Enter through aftermarket e-commerce channels with direct-fit TPMS units featuring cross-reference database completeness against dealer service networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive MEMS fabrication specialists with 800V-compatible sensing architecture roadmaps and established OEM calibration relationships. Long-term viability hinges on exposure to electric vehicle battery thermal management specifications rather than legacy internal combustion powertrain optimization. Monitor GB standards divergence from EPA requirements as the critical signal for whether regional sensor variants or unified global platforms deliver superior capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Compatible Architecture Development | Enables 800V+ electric vehicle platform specification wins against legacy MEMS designs. |
| Calibration Network Expansion | Secures ASIL-D functional safety validation capacity for Detroit and Stuttgart OEM supply chains. |
| Sensor-as-a-Service Platform Launch | Converts unit sales to recurring revenue with German fleet operator subscription pilots. |
| India Manufacturing Footprint Establishment | Captures PLI scheme incentives for Tamil Nadu electric vehicle sensor assembly localization. |
| Aftermarket Channel Direct Integration | Bypasses dealer service networks through e-commerce TPMS cross-reference database dominance. |
Methodological Framework
Operator-level perspectives from Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership service operations anchored the qualitative base for this study. Primary field engagement combined with secondary validation against EPA tailpipe filings, NHTSA Federal Motor Vehicle Safety Standards documentation, MIIT new-energy vehicle mandate releases, and vehicle production databases from IHS Markit. Bottom-up sensor unit economics triangulated against top-down automotive production forecasts across the analysis window.
Scenario-bracketing around electrification penetration rates and regulatory divergence timelines shaped the analytical framework. Segmentation dimensions modeled include vehicle propulsion architecture, functional safety certification tier, content per vehicle by system type, and regional production cluster regulatory pathway. CAGRs derived from installed base growth, replacement cycle compression, and specification upgrade trajectories. Forecast inputs incorporated silicon-carbide adoption curves in high-voltage platforms and TPMS regulatory harmonization progress.
Sensitivities concentrate around MIIT mandate acceleration, EPA tailpipe standard tightening schedules, and palladium price volatility impacts on piezoelectric ceramic electrode costs. Forecasts reflect documented assumptions regarding electric vehicle platform rollout timing and aftermarket channel shift velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Chassis Electronics Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Mexico Automotive EPS Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
TPMS Battery Market