
 New Energy Automotive Antenna Module Market | 2026-2036
New Energy Automotive Antenna Module Market Size, Share, and Industry Trends Forecast 2026-2036
New Energy Automotive Antenna Module Market Insights
REACH compliance is consolidating the cost-of-entry calculus for antenna module suppliers serving European OEM programs. Continental AG leverages its in-house filter and substrate capabilities to sustain margin control across 5G-ready product lines. Amphenol Corporation anchors North American supply relationships through high-volume connector-to-antenna integration. Denso Corporation dominates Japanese OEM channels with thermal-stabilized module designs.
New energy automotive antenna modules are radio-frequency subsystems that integrate radiating elements, low-noise amplifiers, and signal-conditioning circuits within sealed housings rated for automotive temperature ranges. These modules enable real-time vehicle-to-everything communication, over-the-air software updates, and precision navigation for electric and hybrid powertrains. Active antenna configurations capture the fastest expansion as OEMs specify embedded amplifiers to offset signal attenuation from composite body panels. Plastic housing materials lead volume shipments due to weight-reduction protocols, though composite substrates are gaining share in premium electric vehicle architectures where multi-band isolation requirements tighten.
EMA's extended producer responsibility frameworks and the EU AI Act's connectivity safety provisions are reshaping module validation protocols for European-bound vehicles. China's MIIT enforces GB-standard electromagnetic compatibility testing that gates market access for imported antenna assemblies. OEMs and tier-1 suppliers must monitor divergence between regional certification regimes when architecting single-platform global modules.
Market Dynamics
V2X communication mandates are compressing antenna module redesign cycles as electric vehicle OEMs consolidate embedded connectivity architectures across platform generations.
Growth Catalysts
- MIIT Certification Acceleration:China's GB-standard electromagnetic compatibility testing gates market access, forcing tier-1 suppliers to pre-validate modules for dual domestic-export compatibility. This compresses development timelines and raises entry barriers for non-compliant assemblies.
- 5G-Ready Vehicle Architectures:Multi-band antenna integration is converging with composite body panel adoption, creating demand for active amplification circuits that offset signal attenuation from non-conductive vehicle structures.
- Thermal Management Specifications:Electric powertrain heat profiles are driving OEM specifications for stabilized module designs capable of sustained operation across expanded automotive temperature ranges.
Market Restraints
- Substrate Cost Volatility:Ceramic and high-frequency laminate input costs fluctuate with semiconductor foundry capacity allocation, squeezing margin control for mid-volume module suppliers.
- Production Corridor Concentration:Tier-1 manufacturing gravity centers on Germany, Japan, and South Korea, creating geographic vulnerability to regional logistics disruptions or trade policy shifts.
- REACH Compliance Burden:ECHA substance restrictions on housing materials and flame retardants are extending qualification timelines for European-bound product lines.
Strategic Opportunities
- India PLI Scheme Alignment:Component-level production incentives for automotive electronics create localized assembly opportunities for suppliers establishing captive operations serving domestic electric vehicle programs.
- Over-the-Air Update Infrastructure:Software-defined vehicle architectures are expanding antenna count per vehicle, with separate modules dedicated to telematics, navigation, and cybersecurity certificate management.
- EU AI Act Connectivity Provisions:Safety-critical communication validation requirements are creating premium certification tiers that command price differentiation against non-compliant alternatives.
Industry Challenges
- RF Engineering Talent Scarcity:Millimeter-wave antenna design expertise concentrates within aerospace and telecom sectors, forcing automotive suppliers to compete for specialized simulation and testing capabilities.
- Multi-Regulatory Certification Parallelism:Divergent electromagnetic compatibility protocols between MIIT, FCC, and EU frameworks require redundant testing matrices that extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Energy Automotive Antenna Module Market |
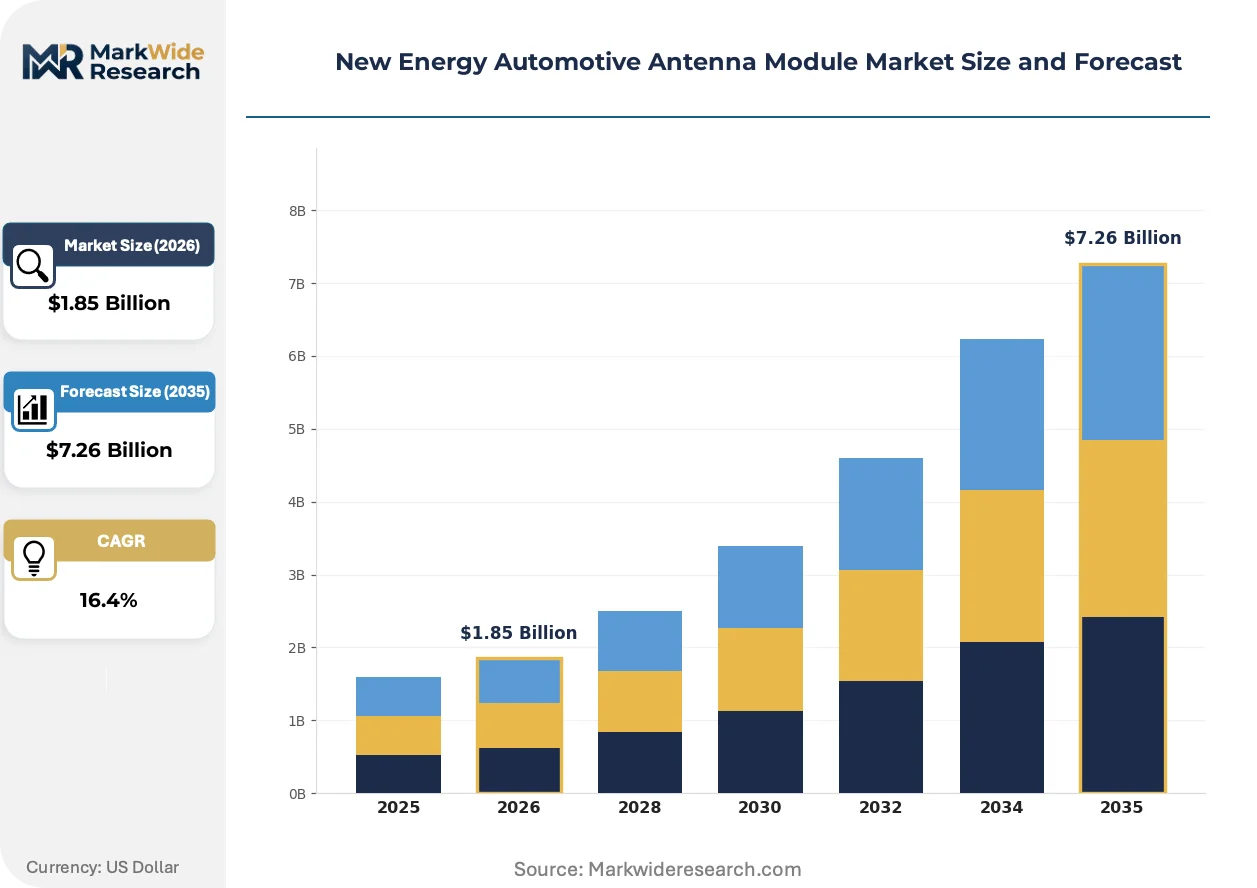
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Antennas, Active Antennas, Integrated Antennas, Beamforming Antennas Material: Plastic, Metal, Composite, Silicon Technology: 5G, LTE, Wi-Fi, Bluetooth End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Continental AG, Amphenol Corporation, Denso Corporation, TE Connectivity, Harman International, Harada Industry, Ficosa, Robert Bosch, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Energy Automotive Antenna Module Market Trends and Innovations
Antenna module architectures are pivoting from passive distributed elements toward integrated active subsystems as vehicle connectivity requirements multiply across safety, infotainment, and powertrain domains.
Active antenna configurations are converging with embedded low-noise amplifier circuits to compensate for signal degradation through carbon-fiber-reinforced body panels. Premium electric vehicle platforms specify these modules for simultaneous 5G, GNSS, and V2X reception without external amplification hardware. The structural consequence is compressing the addressable market for purely passive antenna designs to entry-segment applications.
REACH substance restrictions are reshaping housing material selection across European supply chains. ECHA candidate list updates on phthalates and halogenated flame retardants are forcing module suppliers to requalify plastic compounds and sealing gaskets. Suppliers serving German OEM programs are accelerating bio-based polymer validation to preempt downstream compliance risks.
Buyer concentration among integrated electric vehicle platforms is consolidating procurement authority at the tier-1 level. Tier-2 antenna specialists must now certify through Continental AG, Denso Corporation, or Amphenol Corporation integration programs rather than direct OEM qualification. This channel compression is most visible in South Korea and Japan, where Hyundai-Kia and Toyota procurement systems have eliminated direct component sourcing for connectivity subsystems.
New Energy Automotive Antenna Module Market Segmentation
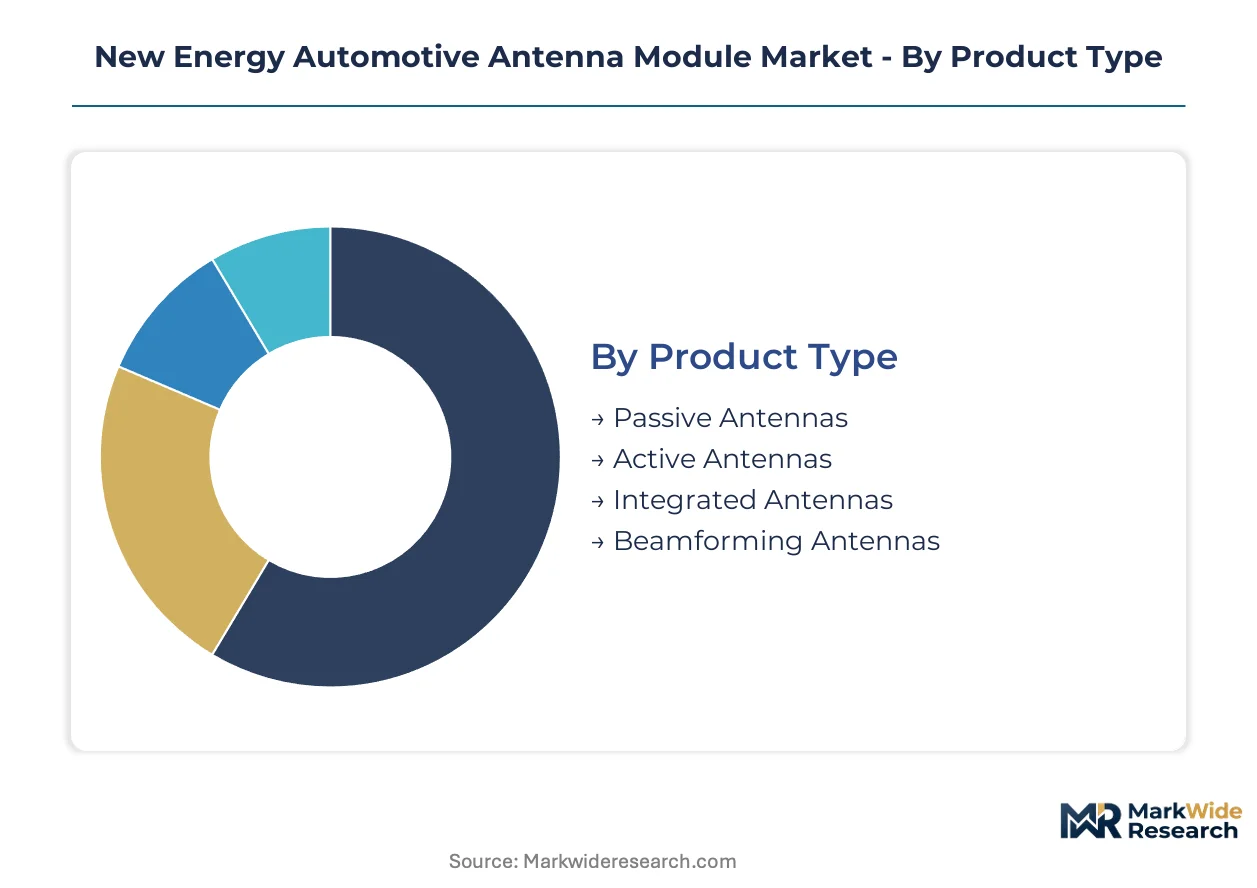
New energy automotive antenna module architectures diverge sharply across product generations, with each segment category reflecting distinct upgrade cycles driven by V2X mandate timelines and composite body panel adoption. Procurement patterns concentrate where platform redesigns intersect with regional certification deadlines.
Product Type:
Module replacement cycles compress as OEMs consolidate multi-band connectivity into single-assembly designs, forcing tier-1 suppliers to pre-validate active configurations for dual-platform compatibility.
- Passive Antennas:Distributed radiating elements without embedded amplification circuits serve entry-segment electric vehicles where cost minimization outweighs signal performance requirements. Demand concentrates in India's domestic electric vehicle programs where PLI scheme localization favors simplified module architectures.
- Active Antennas:Embedded low-noise amplifiers compensate for signal attenuation through carbon-fiber-reinforced body panels, with Continental AG and Denso Corporation dominating procurement channels for premium electric vehicle platforms. Germany's KBA type-approval requirements for V2X safety systems are accelerating OEM specification of these modules across mid-range and luxury segments.
- Integrated Antennas:Multi-band subsystems combining 5G, GNSS, and V2X reception within sealed housings reduce vehicle assembly complexity for software-defined architectures.
- Beamforming Antennas:Phased-array configurations with dynamic signal steering capabilities address millimeter-wave 5G deployment in South Korean and Japanese urban corridors.
Passive antennas sit at the top of the volume ranking, with active antennas climbing the fastest.
Material:
Substrate selection tracks directly with thermal management specifications and electromagnetic compatibility testing requirements across MIIT, FCC, and EU regulatory frameworks.
- Plastic:Injection-molded housings dominate volume shipments due to weight-reduction protocols, though ECHA REACH substance restrictions on phthalates and halogenated flame retardants are forcing requalification cycles for European-bound product lines.
- Metal:Aluminum and zinc-alloy enclosures provide electromagnetic shielding for high-frequency applications, with Japanese OEMs specifying these materials for thermal-stabilized module designs in hybrid powertrain architectures where heat profiles exceed plastic operational limits.
- Composite:Carbon-fiber-reinforced substrates balance structural rigidity with dielectric properties for multi-band isolation in premium electric vehicle platforms.
- Silicon:Semiconductor-integrated antenna-on-chip configurations are emerging for cybersecurity certificate management modules in over-the-air update architectures.
Plastic leads absolute shipment volumes, with composites gaining share fastest in premium segments.
Technology:
Connectivity protocol adoption follows regional spectrum allocation decisions and automotive safety regulation sequencing.
- 5G:New Radio (NR) sub-6 GHz and millimeter-wave configurations enable vehicle-to-everything communication with sub-10 millisecond latency, with China's MIIT spectrum assignments for connected-vehicle services driving module redesign cycles for domestic and export-bound assemblies.
- LTE:Category M1 and NB-IoT protocols sustain telematics and basic over-the-air update functionality in cost-optimized electric vehicle platforms where 5G hardware costs exceed connectivity value capture.
- Wi-Fi:802.11p and 802.11bd standards support dedicated short-range communications for V2X safety messaging in European ETSI deployment corridors.
- Bluetooth:Low-energy configurations handle smartphone keyless entry and cabin device pairing, with minimal antenna complexity requirements.
LTE maintains installed base dominance, with 5G modules expanding most quickly as OEMs consolidate platform architectures.
End User:
Channel structure concentrates procurement authority at integrated tier-1 suppliers, compressing direct OEM access for component specialists.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and BYD Company Limited retain direct antenna module sourcing only for flagship electric vehicle platforms with proprietary connectivity architectures, with most volume production delegated to tier-1 integration programs.
- Tier-1 Suppliers:Continental AG, Denso Corporation, and Amphenol Corporation control qualification pathways for connectivity subsystems, with Hyundai-Kia and Toyota procurement systems eliminating direct component sourcing in South Korea and Japan.
- Aftermarket Providers:Replacement module demand concentrates in collision repair and connectivity upgrade segments where vehicle owners retrofit V2X-capable antennas to pre-mandate electric vehicle fleets.
- Vehicle Assemblers:Contract manufacturers serving emerging electric vehicle brands source pre-certified modules through tier-1 distributor channels rather than direct supplier relationships.
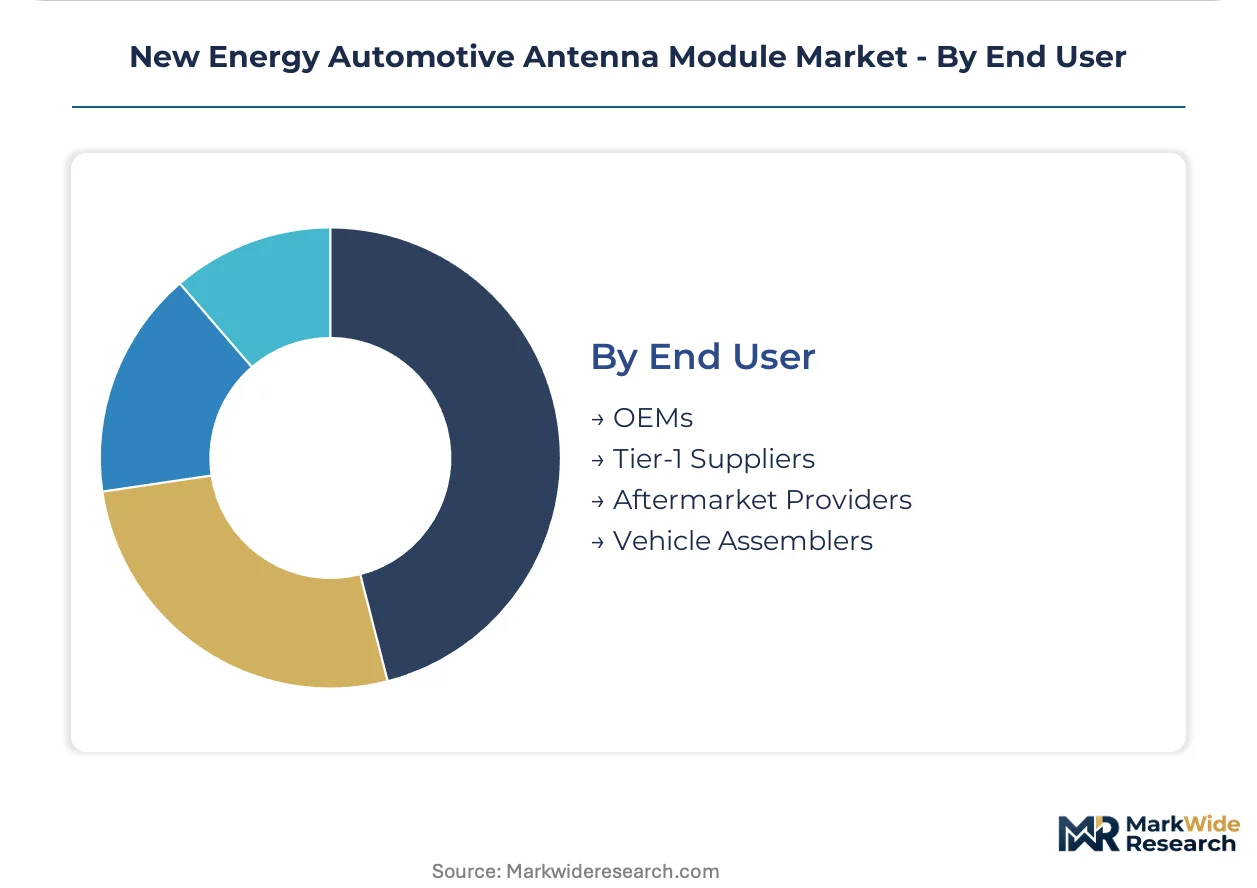
Tier-1 suppliers capture the dominant procurement share, with aftermarket providers expanding fastest as V2X retrofit demand builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent clusters in Germany, Japan, and South Korea anchor antenna module design capabilities, while China's MIIT certification regime and India's PLI scheme reshape manufacturing geography.
China
Domestic electric vehicle OEMs scale embedded antenna orders as MIIT enforces GB-standard electromagnetic compatibility testing for connected-vehicle components. The certification gates market access for imported assemblies, compressing development timelines for dual domestic-export compatibility. Module redesign cycles concentrate in the Yangtze River Delta where tier-1 suppliers anchor production corridors serving BYD and emerging EV brands.
Germany
Continental AG and Valeo SA procurement systems dominate European OEM channels, with REACH compliance consolidating cost-of-entry calculus for housing materials and flame retardants. The KBA type-approval requirements for V2X safety systems accelerate specification of active antenna modules across Volkswagen Group platforms. Bavaria and Baden-Württemberg host thermal-stabilized design centers where ECHA substance restrictions force bio-based polymer validation.
Japan
Denso Corporation controls qualification pathways for Toyota and Hyundai-Kia connectivity subsystems, eliminating direct component sourcing for tier-2 specialists. METI safety provisions and JIS standards govern multi-band isolation specifications for composite body panel integration. Kansai and Chubu industrial corridors concentrate thermal-stabilized module production for hybrid powertrain architectures.
South Korea
Hyundai-Kia procurement compression forces tier-2 antenna specialists to certify through Denso or Amphenol integration programs rather than direct OEM relationships. The country's spectrum allocation for millimeter-wave 5G deployment drives beamforming antenna specifications in urban corridors. Seoul Capital Area and Busan-Ulsan production clusters serve domestic EV programs and export-bound assemblies.
India
Component-level PLI scheme incentives for automotive electronics create localized assembly opportunities for suppliers establishing captive operations. BIS electromagnetic compatibility protocols diverge from MIIT and FCC frameworks, requiring redundant testing matrices. Maharashtra and Gujarat industrial zones concentrate passive antenna production for cost-optimized domestic EV platforms where simplified module architectures dominate procurement.
New Energy Automotive Antenna Module Market Competitive Landscape
The competitive structure tilts toward integrated tier-1 suppliers with captive RF engineering capabilities. Three archetypes dominate: diversified automotive electronics conglomerates with in-house substrate and filter production, specialized connectivity component manufacturers with high-volume connector integration expertise, and diversified industrial technology groups with cross-sector antenna design heritage. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with M&A activity targeting millimeter-wave simulation capabilities.
Within the diversified automotive electronics tier, Continental AG exemplifies the integrated conglomerate archetype through its captive filter and substrate capabilities. Denso Corporation anchors the Japanese OEM channel position with thermal-stabilized module designs. Amphenol Corporation occupies the North American connectivity integration position through high-volume connector-to-antenna programs. These three entities collectively represent the tier-1 gateway function compressing direct OEM access for component specialists.
| Leading Market Players |
|---|
| Continental AG |
| Amphenol Corporation |
| Denso Corporation |
| TE Connectivity |
| Harman International |
| Harada Industry |
| Ficosa |
| Robert Bosch |
| Valeo SA |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of ceramic substrates and RF filters by Continental AG and Denso Corporation anchors both supply security and pricing power for tier-1 antenna module suppliers serving European and Japanese OEM programs. This backward integration insulates margin control from semiconductor foundry capacity volatility while compressing procurement pathways for tier-2 component specialists.
Pricing Analysis
Antenna module pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Active configurations with embedded low-noise amplifiers command premium positioning due to KBA type-approval requirements for V2X safety systems in Germany. Cost compression in passive antenna tiers is intensifying because India's PLI scheme localization favors simplified module architectures for domestic EV programs. Entry-segment electric vehicle OEMs exhibit highest price sensitivity, while premium EV platforms prioritize thermal-stabilized designs over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and South Korea operate hub-and-spoke patterns that feed tier-1 integration plants. Manufacturing gravity draws from ceramic substrate foundries in Japan, high-frequency laminate producers in South Korea, and injection-molding compounds in Germany. Single-source vulnerability concentrates in millimeter-wave simulation software and specialized RF engineering talent pools. Distribution runs through tier-1 supplier qualification programs that eliminate direct OEM component sourcing in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in India's PLI scheme corridor, where component-level production incentives offset REACH compliance costs burdening European-bound supply chains.
For Market Incumbents: Deepen captive filter production to defend margin position against substrate cost volatility squeezing mid-volume competitors. Accelerate bio-based polymer validation for ECHA substance restrictions before downstream qualification deadlines. Secure tier-2 specialist partnerships to preempt RF engineering talent scarcity from aerospace and telecom sectors. For New Entrants and Emerging Players: Enter via India's domestic EV programs where PLI incentives and BIS electromagnetic compatibility protocols create localized assembly white space. Target passive antenna architectures for cost-optimized platforms where tier-1 procurement compression has eliminated direct OEM access. Pursue aftermarket V2X retrofit channels as mandate deadlines generate collision repair demand. For Investors and Strategic Acquirers: Roll-up economics work for specialized RF simulation boutiques because millimeter-wave design expertise concentrates outside automotive and acquisition multiples reflect cross-sector scarcity. Five-to-ten year viability hinges on software-defined vehicle architectures expanding antenna count per vehicle. Monitor MIIT certification acceleration as inflection signal for module redesign cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates multi-band connectivity into single-assembly designs for Volkswagen Group architectures. |
| Battery Supply Agreement | Secures thermal-stabilized module specifications aligned with electric powertrain heat profiles. |
| Software-Defined Vehicle Investment | Expands antenna count per vehicle for telematics, navigation, and cybersecurity certificate management. |
| Geographic Manufacturing Footprint | Captures India's PLI scheme incentives while positioning for BIS electromagnetic compatibility testing. |
| Charging Infrastructure Partnership | Enables V2X communication integration with grid-interactive electric vehicle programs. |
Research Methodology
Direct dialogue with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and RF engineering directors grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, MIIT GB-standard filings, and ECHA REACH substance restriction updates. Bottom-up module shipment estimates and top-down OEM platform content assumptions were triangulated to anchor volume figures.
Segment-level outputs across the projection horizon reflect product type, material substrate, connectivity technology, and end-user channel dimensions. CAGRs were derived from platform redesign cycle timing intersecting with regional certification deadlines. Forecast inputs incorporated composite body panel adoption curves and V2X mandate sequencing across KBA, MIIT, and FCC jurisdictions.
The model holds under stable regulatory divergence between electromagnetic compatibility frameworks; deviation in trade policy or semiconductor foundry capacity allocation would shift supply chain cost structures. Forecasts reflect documented assumptions about tier-1 procurement compression and talent scarcity persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
North America Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market