
 UK Automotive Eps Market | 2026-2036
UK Automotive Eps Market Size, Share, and Industry Trends Forecast 2026-2036
UK Automotive Eps Market Analytics
Market Context
A widening capital-intensity divergence between integrated system suppliers and component specialists is unwinding competitive stability across the UK supply base. JTEKT Corporation leverages its steering-system heritage to anchor high-volume contracts with domestic OEMs. ZF Friedrichshafen AG sustains R&D intensity across mechatronic integration, while Robert Bosch GmbH dominates aftermarket channel control through its service network density. Nexteer Automotive specializes in advanced torque-sensing architectures that differentiate its portfolio.
Technical Definition and Structural Segments
Automotive EPS refers to expanded polystyrene foam engineered with precise density grades between 15-30 kg/m³, manufactured through steam-expansion of polystyrene beads followed by mold-fusion to create lightweight, impact-absorbing structures for vehicle applications. Its primary commercial purpose centers on reducing curb weight while maintaining crash-energy management in bumpers, door cores, and seat components. Standard EPS occupies the mature volume tier with thin margins, whereas High-Performance EPS captures expanding demand from electric vehicle platforms requiring enhanced thermal insulation in battery enclosures. Customized EPS commands premium positioning where OEMs specify multi-density laminations for structural components.
Regulatory Frame and Outlook
The UK's Department for Transport and the Environment Agency enforce end-of-life vehicle directives that mandate recoverable material thresholds, while BSI standards govern flammability and VOC emissions in cabin applications. These frameworks compel suppliers to reformulate base resins and validate closed-loop recycling pathways. Stakeholders must monitor post-Brexit regulatory divergence from EU REACH protocols and assess whether domestic recyclability targets will outpace continental benchmarks.
Market Dynamics
The UK's automotive EPS sector faces structural pressure from the Department for Transport's escalating material recyclability mandates, which force suppliers to reformulate resins and validate closed-loop pathways while maintaining crash-performance specifications for electric vehicle platforms.
Growth Catalysts
- West Midlands cluster concentration:England's Birmingham-Coventry corridor hosts dense OEM-final assembly proximity, compressing logistics costs and enabling just-in-time EPS component delivery to vehicle manufacturers.
- ELV directive compliance:The Environment Agency's end-of-life vehicle recoverable material thresholds compel suppliers to invest in chemical recycling infrastructure, creating first-mover advantages for compliant foam producers.
- Battery enclosure thermal insulation:High-Performance EPS grades with enhanced R-values are capturing specification wins from lithium-ion pack engineers seeking lightweight fire-barrier solutions.
Market Restraints
- Styrene monomer volatility:Feedstock price swings from European petrochemical suppliers compress margin predictability for UK molders lacking long-term offtake contracts.
- Single-region supply risk:Steam-expansion bead production concentrates in continental EU facilities, exposing UK converters to cross-border tariff friction and transport bottlenecks.
- Polypropylene substitution:Expanded polypropylene foam from German and Italian compounders is displacing standard EPS in bumper core applications where multi-impact durability matters.
Strategic Opportunities
- Northern England manufacturing revival:Sunderland and Liverpool automotive plants offer underutilized capacity corridors for EPS converters seeking proximity to Nissan and Jaguar Land Rover assembly.
- Chemical recycling partnerships:Pyrolysis-based polystyrene recovery creates circular material streams that satisfy BSI VOC emissions standards while differentiating supplier offerings.
- Multi-density lamination contracts:OEM specifications for structural seat components combining 15 kg/m³ and 30 kg/m³ grades open premium positioning for customized EPS specialists.
Industry Challenges
- Material scientist recruitment:Formulation chemists with dual expertise in fire-retardant additives and closed-loop recycling pathways command scarcity premiums that inflate R&D overhead.
- BSI certification timelines:Flammability testing protocols for cabin-grade EPS extend validation cycles by 8-14 months, delaying contract awards and freezing working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Automotive Eps Market |
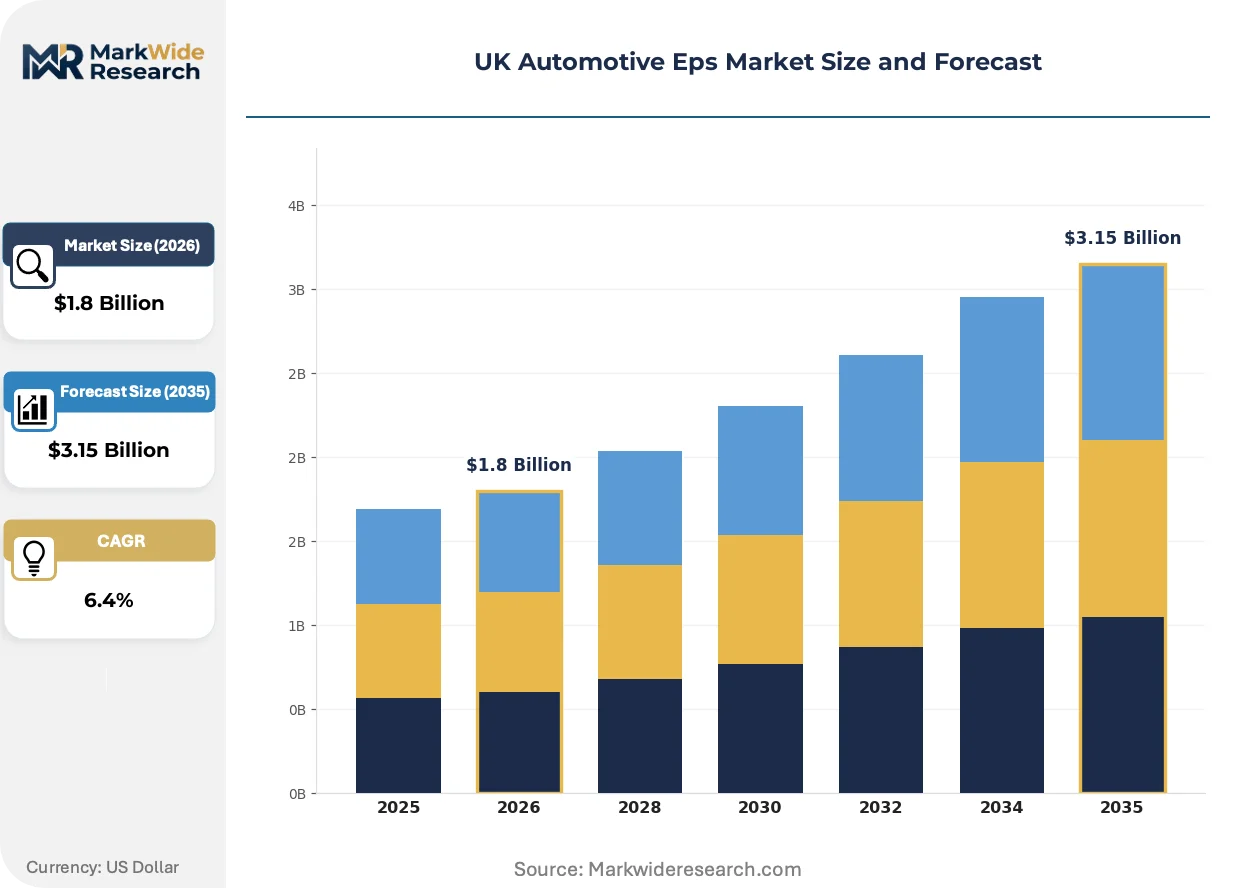
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard EPS, High-Performance EPS, Biodegradable EPS, Customized EPS End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Application: Interior Components, Exterior Parts, Structural Components, Insulation Applications Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | JTEKT Corporation, ZF Friedrichshafen AG, Nexteer Automotive, Robert Bosch GmbH, Hyundai Mobis, NSK Ltd., Mitsubishi Electric Corporation, GKN Automotive, Mando Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Automotive Eps Market Evolving Landscape
Active reformulation of base resins and mold-fusion processes is reshaping competitive positioning among UK suppliers, with thermal performance and recyclability credentials now outweighing unit cost in OEM specification decisions.
High-Performance EPS with graphite-infused bead structures is displacing conventional foam in battery pack thermal management systems. Jaguar Land Rover and Nissan's Sunderland operations have accelerated specification of these grades for electric platform launches. The shift is compressing demand for standard-density EPS in underhood applications while opening premium contract structures for qualified suppliers.
The Department for Transport's post-Brexit divergence from EU REACH protocols is creating regulatory friction for importers. UK-specific substance restriction schedules now require separate compliance documentation from continental suppliers. Domestic molders with validated UKCA marking pathways are capturing specification share from EU competitors facing dual-certification burdens.
Fleet procurement managers at commercial vehicle operators are unbundling after-sales service contracts from component supply agreements. Direct sourcing of EPS replacement cores through authorized distributor networks is replacing bundled OEM service packages. This pattern concentrates in England's light commercial vehicle segment where operators prioritize parts availability over manufacturer-captive service networks.
UK Automotive Eps Market Segmentation
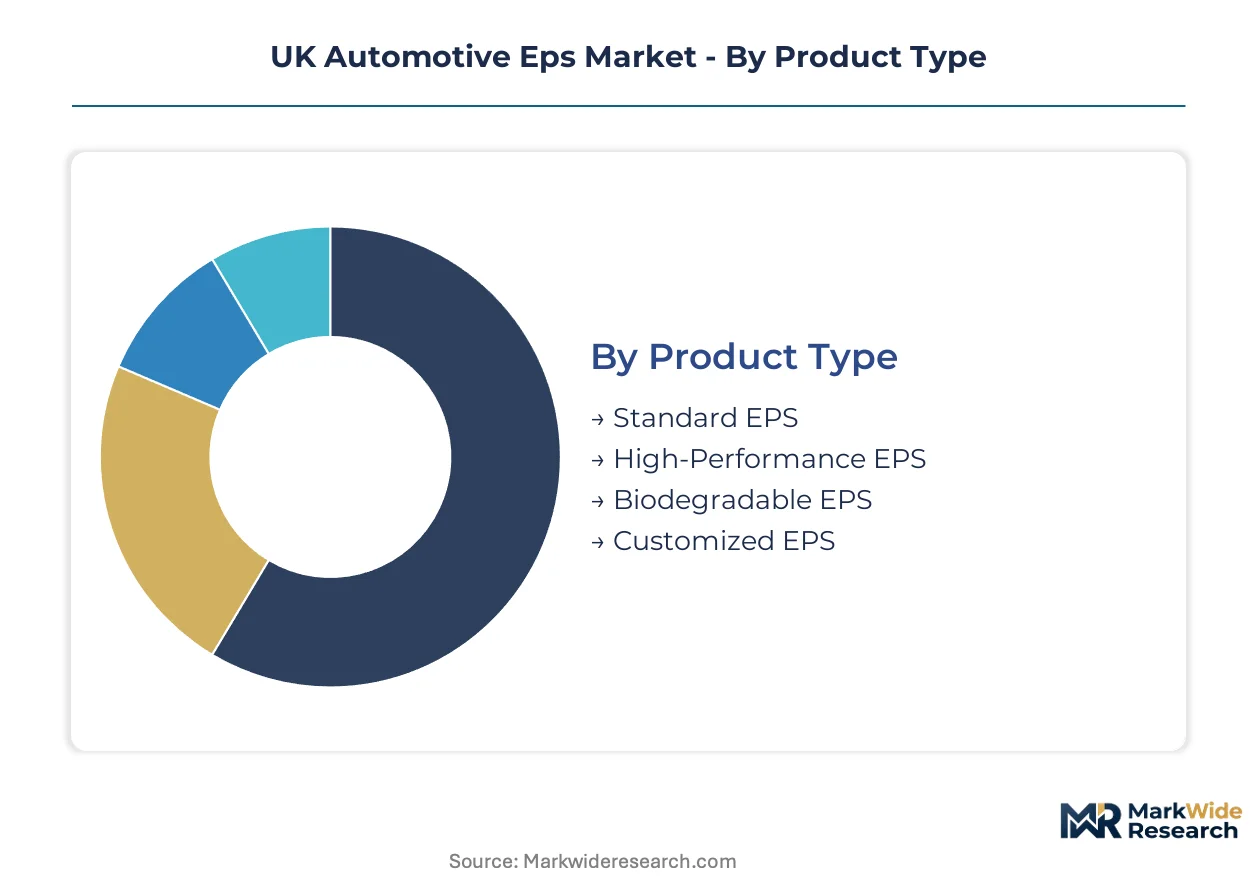
Segmentation in the UK automotive EPS market reveals how regulatory pressure and electrification are fragmenting demand across material grades and manufacturing technologies. Each dimension exposes distinct margin structures and competitive entry points for suppliers navigating the Department for Transport's tightening recyclability mandates.
Product Type:
Department for Transport end-of-life vehicle directives create divergent compliance burdens across density grades, forcing suppliers to validate closed-loop recovery pathways for each formulation tier.
- Standard EPS:Conventional bead-expanded foam at 15-20 kg/m³ density serves bumper cores and door panels where cost minimization dominates procurement. Demand concentrates with legacy internal combustion vehicle programs across England's West Midlands cluster, though margin compression from polypropylene substitution is accelerating volume decline.
- High-Performance EPS:Graphite-infused bead structures deliver enhanced thermal resistance for battery enclosure fire barriers. Jaguar Land Rover and Nissan Sunderland operations specify these grades for electric platform thermal management, capturing premium positioning as OEMs prioritize pack safety over unit cost.
- Biodegradable EPS:Starch-blended resins address BSI compostability standards for demonstration fleets and municipal procurement vehicles with mandated circularity targets.
- Customized EPS:Multi-density laminations combine 15 kg/m³ and 30 kg/m³ grades for structural seat components requiring tailored energy absorption profiles.
Established volume favors Standard EPS; emerging adoption favors High-Performance EPS.
End User:
Procurement authority is fragmenting as fleet operators unbundle service contracts from component supply, reshaping channel economics across the value chain.
- OEMs:Vehicle manufacturers specify material grades during platform development and lock in multi-year supply agreements through integrated system suppliers.
- Aftermarket Providers:Independent distributors capture replacement core demand from light commercial vehicle operators prioritizing parts availability over captive service networks.
- Dealerships:Authorized service centers source EPS components through OEM-mandated channels, maintaining brand-compliant repair standards.
- Vehicle Assemblers:Contract manufacturers at Sunderland and Liverpool plants procure EPS directly for just-in-time interior panel installation.
Direct procurement is climbing the fastest among Vehicle Assemblers; channel intermediation retains strength with Dealerships.
Application:
Crash-performance specifications and thermal management requirements are redistributing material volumes across vehicle zones as electrification reshapes engineering priorities.
- Interior Components:Dashboard substrates, pillar trims, and headliner cores employ low-density EPS for acoustic dampening and occupant protection.
- Exterior Parts:Bumper energy absorbers and fender liners require multi-impact recovery properties where expanded polypropylene is displacing conventional EPS.
- Structural Components:Seat frames and load-floor reinforcements utilize high-compression grades with 25-30 kg/m³ density for crash-load distribution.
- Insulation Applications:Battery pack thermal barriers and HVAC ducting specify fire-retardant formulations meeting BSI flammability protocols.
Structural load-bearing demand favors Structural Components; thermal management expansion favors Insulation Applications.
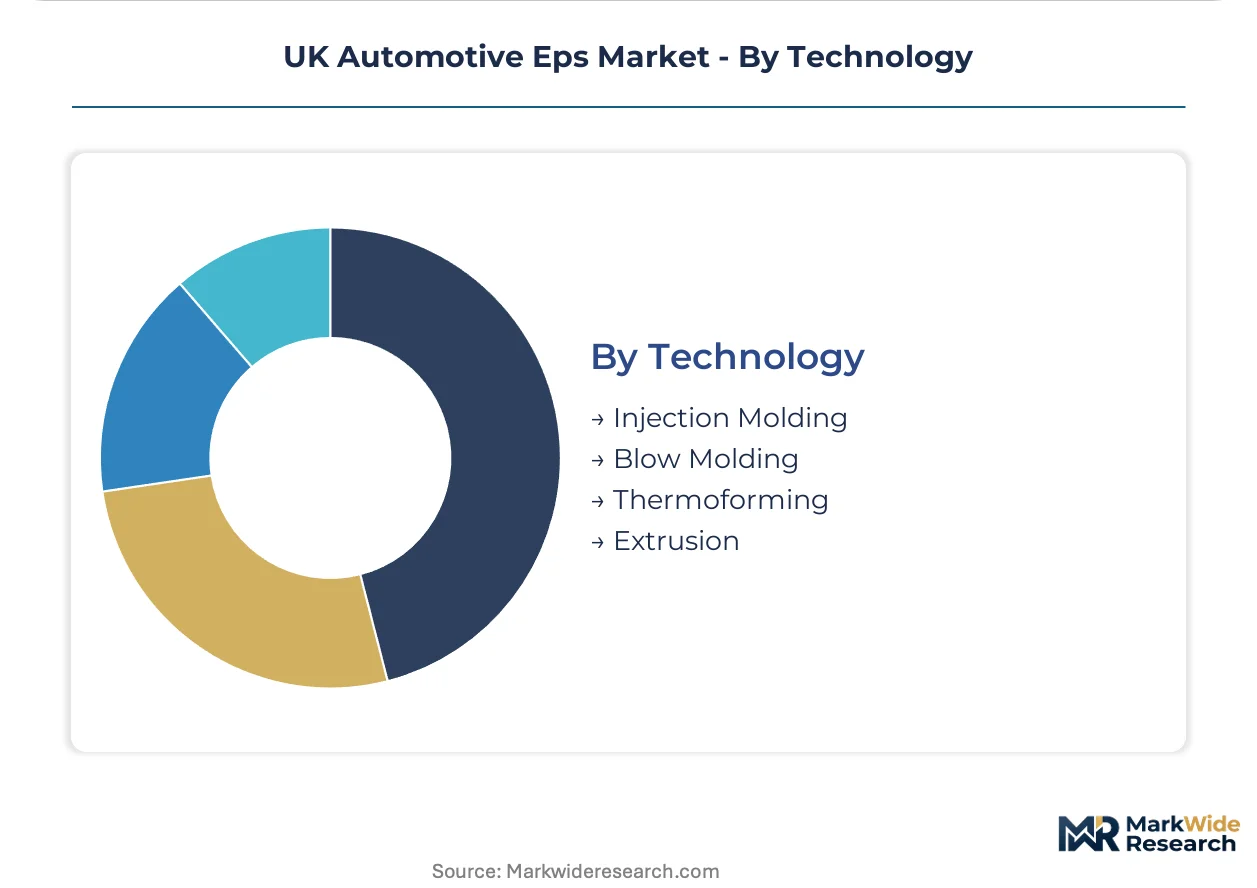
Technology:
Process selection determines bead fusion quality, cycle economics, and the feasibility of multi-density component manufacturing for complex geometries.
- Injection Molding:Steam-chest fusion of pre-expanded beads enables complex shapes with uniform density distribution for structural seat components.
- Blow Molding:Hollow-profile extrusion serves HVAC ducting and conduit applications where internal pressurization creates seamless geometries.
- Thermoforming:Sheet-based vacuum forming produces large-format interior panels with surface skins for dashboard and door trim applications.
- Extrusion:Continuous profile output generates bumper core sections and insulation boards with consistent cross-sectional density.
Geometric complexity favors Injection Molding; scale efficiency favors Extrusion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK's automotive EPS trade balance tilts toward import dependency for steam-expansion bead feedstock, with domestic molders sourcing raw material from continental EU facilities and converting it within England's manufacturing corridors.
West Midlands
Birmingham and Coventry anchor the densest OEM-final assembly proximity in the UK, compressing logistics costs for just-in-time EPS component delivery. The Department for Transport's material recyclability mandates compel local suppliers to validate closed-loop recovery pathways. JLR's Castle Bromwich and Solihull plants drive specification of high-performance thermal insulation grades for electric platform launches.
North East England
Sunderland hosts Nissan's EV36Zero gigafactory and vehicle assembly operations, generating concentrated demand for battery enclosure fire-barrier EPS. The Environment Agency's end-of-life vehicle recoverable material thresholds push regional molders toward chemical recycling infrastructure investment. The Nissan supplier park creates captive demand corridors for qualified foam producers.
North West England
Liverpool and Greater Manchester automotive plants offer underutilized capacity corridors for EPS converters seeking proximity to Jaguar Land Rover and emerging EV assembly. BSI flammability testing protocols for cabin-grade applications extend validation cycles, delaying contract awards for regional entrants. The Merseyside logistics hub enables cross-border distribution to Irish markets.
East Midlands
Derbyshire and Leicestershire host tier-two component suppliers feeding West Midlands OEMs, with EPS molders specializing in standard-density bumper cores and door panels. The region's polymer processing heritage supports reformulation capabilities for Department for Transport-mandated recyclable resin systems. Toyota's Burnaston assembly plant maintains steady demand for interior acoustic dampening components.
South East England
London orbital logistics corridors and Thames Valley distribution centers channel aftermarket EPS replacement cores to light commercial vehicle operators unbundling service contracts. Post-Brexit UKCA marking requirements create regulatory friction for continental suppliers, advantaging domestic molders with validated compliance pathways. Heathrow-adjacent air freight enables rapid prototype delivery for OEM development programs.
UK Automotive Eps Market Competitive Landscape
Concentration sits with integrated system suppliers leveraging steering-system heritage and mechatronic integration capabilities to anchor high-volume OEM contracts. The UK supply base exhibits tiered structure with volume-tier molders competing on logistics proximity and premium-tier specialists capturing thermal management specification wins. Three archetypes dominate: integrated automotive suppliers with multi-component portfolios, dedicated EPS converters with formulation expertise, and aftermarket channel operators controlling service network density. Competitive moves center on chemical recycling partnerships for circular material streams and multi-density lamination capabilities for structural seat components.
Among Japanese-heritage integrated suppliers, JTEKT Corporation and NSK Ltd. occupy positions anchored in steering-system supply relationships with domestic OEMs. ZF Friedrichshafen AG, a German GmbH-structured automotive supplier, exemplifies the mechatronic integration archetype sustaining R&D intensity across vehicle control systems. These three represent distinct strategic postures within a supply base where heritage relationships and validated UKCA marking pathways determine specification access.
| Leading Market Players |
|---|
| JTEKT Corporation |
| ZF Friedrichshafen AG |
| Nexteer Automotive |
| Robert Bosch GmbH |
| Hyundai Mobis |
| NSK Ltd. |
| Mitsubishi Electric Corporation |
| GKN Automotive |
| Mando Corporation |
| Others |
Value Network & Pricing Analysis
Sixty-day inventory cycles for steam-expansion bead feedstock concentrate working capital exposure among UK molders, amplifying pricing power for continental suppliers while compressing margin buffers for domestic converters facing Department for Transport recyclability mandates.
Pricing Analysis
The customization-premium spread between multi-density laminations and standard-density bumper cores spans roughly three-to-one, with Jaguar Land Rover and Nissan Sunderland procurement teams paying configured-to-order premiums for battery enclosure thermal barriers. Contract-based long-term offtake agreements dominate OEM relationships, while spot purchasing prevails in aftermarket channels where independent distributors compete on parts availability. Price differentiation rests on BSI flammability certification tier and graphite-infusion grade, with uncertified molders facing accelerating price erosion from polypropylene substitution in exterior applications. Light commercial vehicle fleet operators exhibit highest price sensitivity, prioritizing replacement core availability over material specification compliance.
Supply Chain Analysis
Belgium and the Netherlands anchor European steam-expansion bead production, with UK molders drawing from these continental facilities to convert raw material into finished automotive components. The supply chain rests on styrene monomer feedstock from German and Dutch petrochemical complexes, specialized mold-fusion equipment from Italian and German machinery builders, and fire-retardant additive packages sourced through Swiss and German chemical distributors. Single-region supply risk concentrates in cross-Channel logistics chokepoints, where post-Brexit customs friction extends lead-time variability. Distribution runs through tier-one system suppliers for OEM channels and authorized distributor networks for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK automotive EPS market tracks a cyclical recovery anchored to electric vehicle platform launches, with Jaguar Land Rover and Nissan Sunderland production ramps driving specification volume for thermal management grades.
For Market Incumbents: Shield specification share by securing UKCA marking pathways before EU competitors complete dual-certification compliance, and deepen backward integration into chemical recycling infrastructure to satisfy Environment Agency recoverable material thresholds. Expanded polypropylene substitution in bumper cores threatens standard-density volume, making fire-retardant formulation expertise the critical defensive lever. For New Entrants and Emerging Players: Aftermarket service unbundling among light commercial vehicle operators creates white-space opportunity for direct distributor relationships bypassing OEM-captive networks. Northern England manufacturing corridors around Liverpool offer underutilized capacity proximity to Jaguar Land Rover assembly with lower competitive density than the West Midlands cluster. A go-to-market angle emphasizing rapid BSI flammability validation turnaround addresses the eight-to-fourteen-month certification bottlenecks freezing incumbent working capital. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded automotive EPS divisions lacking electric vehicle platform exposure. Long-term viability favors specialists with validated thermal management grades and closed-loop recycling partnerships over commodity bumper core producers. The signal to watch is Department for Transport regulatory divergence accelerating beyond EU REACH protocols, which would revalue domestic UKCA-compliant capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-based polystyrene recovery satisfies Environment Agency recoverable material mandates while differentiating supplier offerings. |
| Multi-Density Lamination Capability | Combining 15 kg/m³ and 30 kg/m³ grades captures premium positioning for structural seat component contracts. |
| UKCA Marking Pathway Investment | Validated compliance documentation advantages domestic molders over EU competitors facing dual-certification burdens. |
| Northern England Manufacturing Footprint | Sunderland and Liverpool proximity to Nissan and Jaguar Land Rover assembly compresses logistics costs for just-in-time delivery. |
| Graphite-Infused Grade Development | Enhanced thermal resistance specifications capture battery enclosure demand from lithium-ion pack engineers. |
Research Methodology
Desk research of vehicle production databases, customs and trade flow records, and BSI standards documentation preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, EPS converter plant managers, and aftermarket distributor operations heads. Primary fieldwork combined telephone and video interviews with secondary validation against regulatory filings from the Department for Transport and Environment Agency. Bottom-up volume modeling from individual facility capacities and top-down demand triangulation from vehicle production forecasts were cross-referenced for consistency.
Variance decomposition across density grade, vehicle propulsion architecture, and regional manufacturing cluster dimensions shaped the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by content-per-vehicle assumptions for thermal management versus acoustic dampening applications. Forecast inputs incorporated electric vehicle platform launch schedules, ELV directive compliance timelines, and styrene monomer price elasticity assumptions.
Forecasts assume regulatory continuity in UK end-of-life vehicle directives and BSI flammability protocols; material policy shifts would require re-modeling. Forecasts reflect assumptions regarding electric vehicle adoption curves, chemical recycling technology maturation, and post-Brexit trade friction persistence. Recalibration cycles align with material shifts in Department for Transport regulatory announcements and major OEM platform launch decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive E/ E Architecture Market
Automotive Electrical & Electronics
Automotive Battery Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive Rotor Position Sensor for E-Axle Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
South Africa Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electric Motor Horn Market
Automotive Electrical & Electronics
X-By-Wire Systems Market