
 Automotive Rotor Position Sensor for E-Axle Market | 2026-2036
Automotive Rotor Position Sensor for E-Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rotor Position Sensor for E-Axle Market Insights
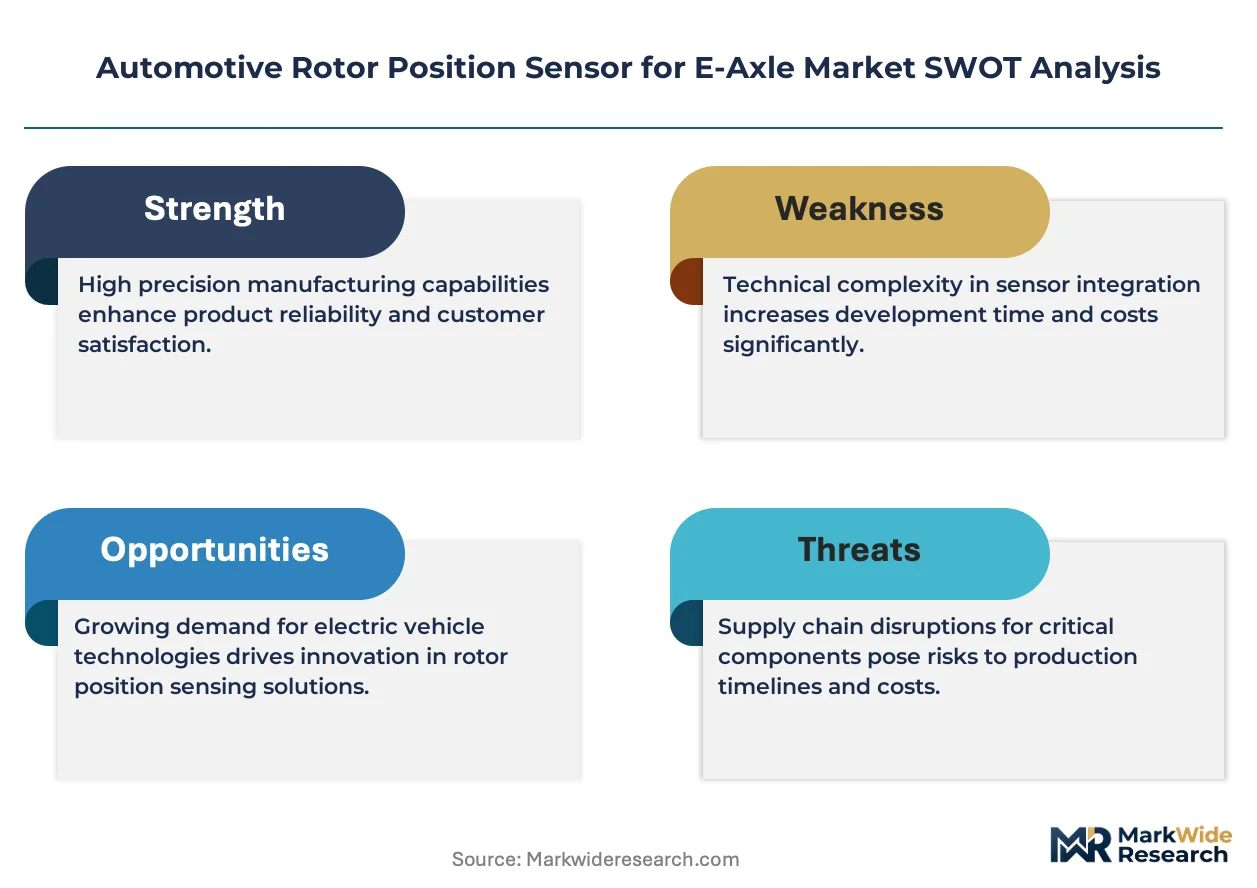
A widening capability gap between integrated semiconductor-sensor houses and discrete component vendors is reorganizing competitive dynamics in automotive rotor position sensing. Robert Bosch leverages in-house wafer fabrication and magnetic sensing IP to control premium e-axle programs at European OEMs. Infineon Technologies anchors its position through silicon-based Hall-effect die production scaled to automotive AEC-Q100 qualification. Melexis specializes in programmable magnetic sensors with on-chip temperature compensation, differentiating its offering for high-temperature motor environments.
An automotive rotor position sensor for e-axle is a magnetic or inductive sensing element that detects angular rotor position in permanent magnet synchronous motors operating at rotational speeds exceeding 15,000 RPM, converting mechanical orientation into electrical signals for field-oriented motor control algorithms. Its primary purpose is enabling precise torque vectoring and regenerative braking coordination in integrated e-axle drive units. Hall Effect sensor types dominate current volume production due to cost maturity and magnetic field robustness, though Magnetoresistive variants are capturing design wins where sub-degree angular accuracy is required for autonomous vehicle traction control. Digital Output technology configurations command margin premiums over legacy Analog Output architectures by eliminating external signal conditioning and reducing EMC susceptibility in dense e-axle enclosures.
NHTSA motor vehicle safety standards and EPA zero-emission vehicle mandates in the United States are tightening accuracy and reliability requirements for electrified powertrain feedback systems, directly shaping sensor qualification protocols and OEM sourcing criteria. The EU Green Deal's CO2 fleet targets, enforced through EMA-aligned automotive emissions frameworks, are accelerating European OEM migration from resolver-based to solid-state magnetic position sensing in next-generation e-axles. Stakeholders must monitor how ISO 26262 functional safety等级 upgrades from ASIL-B to ASIL-D reshape semiconductor architecture choices and vendor qualification timelines.
Market Dynamics
Permanent magnet synchronous motor architectures are forcing a sensor technology transition from resolver-based to solid-state magnetic solutions, compressing qualification timelines and rewiring vendor-OEM relationships across European e-axle programs.
Growth Catalysts
- EU Green Deal fleet mandates:CO2 reduction targets enforced through EMA-aligned frameworks are compelling European OEMs to redesign e-axle systems with higher-precision rotor feedback.
- Field-oriented control algorithm maturation:Advanced motor control software in passenger electric vehicles now demands sub-degree angular accuracy that only solid-state magnetic sensors deliver.
- Germany's manufacturing corridor:Stuttgart and Munich production clusters are concentrating procurement decisions for precision e-axle components among a tight supplier base.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet motors transmit directly to sensor procurement budgets.
- Wafer fabrication concentration:Automotive-qualified Hall-effect die production clusters in specific European and Asian foundry regions create single-source vulnerability.
- Resolver legacy lock-in:Existing e-axle platforms with resolver-based position sensing require full motor controller redesigns to accommodate solid-state alternatives.
Strategic Opportunities
- ASIL-D functional safety tier:ISO 26262 certification upgrades from ASIL-B to ASIL-D open premium pricing tiers for vendors with redundant sensing architectures.
- Magnetoresistive-inductive convergence:Hybrid sensor technologies combining magnetoresistive angular accuracy with inductive noise immunity target autonomous vehicle traction control applications.
- Digital output channel expansion:Elimination of external signal conditioning through native digital interfaces creates aftermarket retrofit potential for legacy analog e-axle systems.
Industry Challenges
- Magnetic sensing IC design talent scarcity:Specialized expertise in temperature-compensated Hall-effect and magnetoresistive architectures concentrates among a limited pool of semiconductor houses.
- AEC-Q100 qualification timeline compression:Automotive reliability testing protocols for high-temperature motor environments extend development cycles beyond typical OEM platform deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rotor Position Sensor for E-Axle Market |
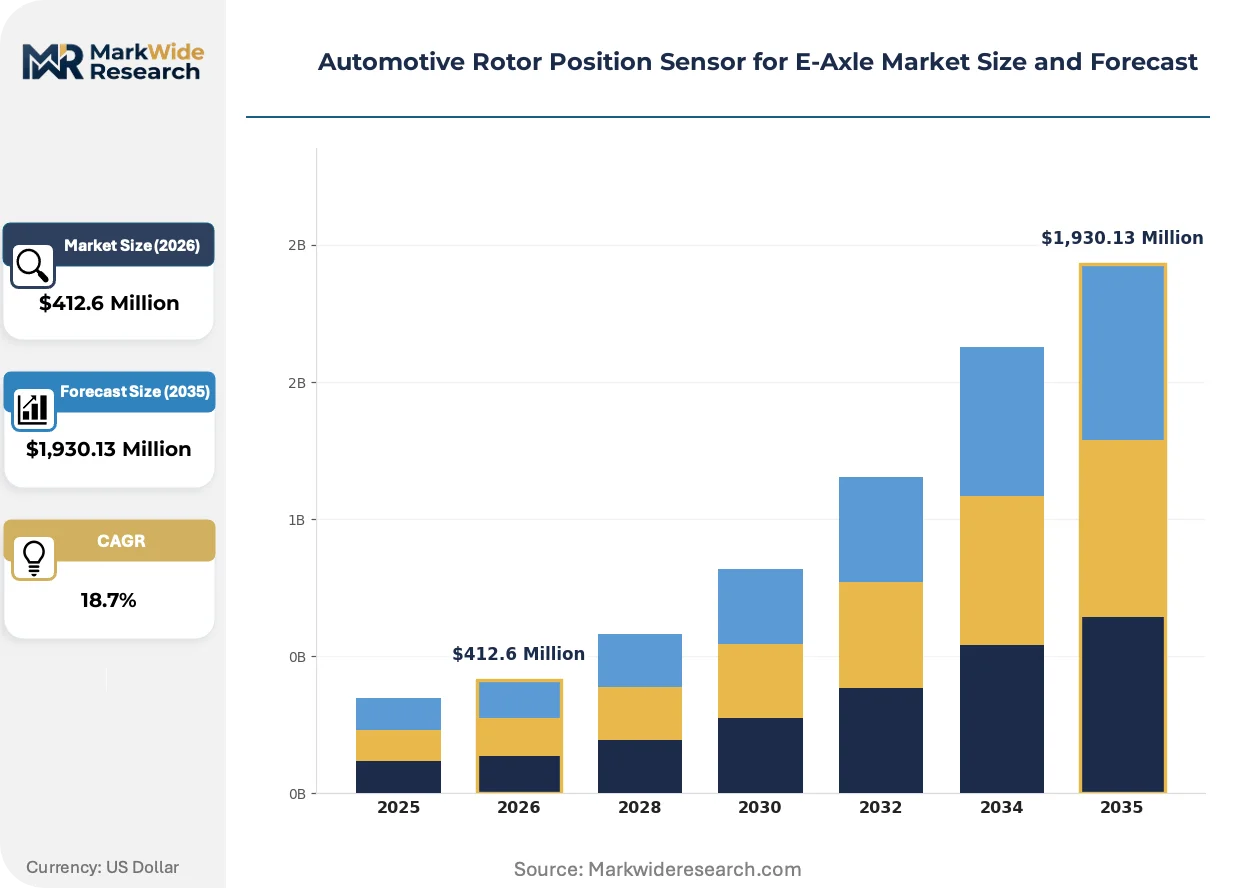
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Hall Effect, Magnetoresistive, Inductive, Capacitive Technology: Analog Output, Digital Output, Pulse Width Modulation, Frequency Output Application: Electric Vehicles, Hybrid Vehicles, Autonomous Vehicles, Commercial Vehicles End User Industry: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Robert Bosch, Continental, ZF Friedrichshafen, Denso, Valeo, Infineon Technologies, NXP Semiconductors, Melexis, Piher Sensing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rotor Position Sensor for E-Axle Market Trends and Innovations
Sensor packaging architectures and signal processing topologies are converging around integration density and electromagnetic compatibility requirements specific to dense e-axle enclosures. Three developments are restructuring technical roadmaps.
Magnetoresistive sensor elements with on-chip temperature compensation are miniaturizing into single-package solutions that eliminate external magnetic concentrators. Tier-1 suppliers in Germany are adopting these for next-generation 800V e-axle platforms. The technology is miniaturizing magnetic sensing subsystems from multi-component assemblies to die-level integration, compressing bill-of-materials complexity and footprint.
NHTSA motor vehicle safety standards are tightening accuracy requirements for electrified powertrain feedback systems in the United States. The EPA zero-emission vehicle mandate is accelerating OEM migration to solid-state sensing architectures that demonstrate higher reliability under thermal cycling. Premium passenger electric vehicle segments are responding with dedicated sourcing teams for ASIL-D qualified components.
Buyer concentration among German OEMs is consolidating procurement decisions into centralized e-axle platform teams. Long-term supply agreements with semiconductor-sensor houses are displacing spot-market component purchasing for magnetic position sensing. This pattern is most visible in Stuttgart and Munich manufacturing corridors where integrated drive unit production has concentrated.
Automotive Rotor Position Sensor for E-Axle Market Segmentation
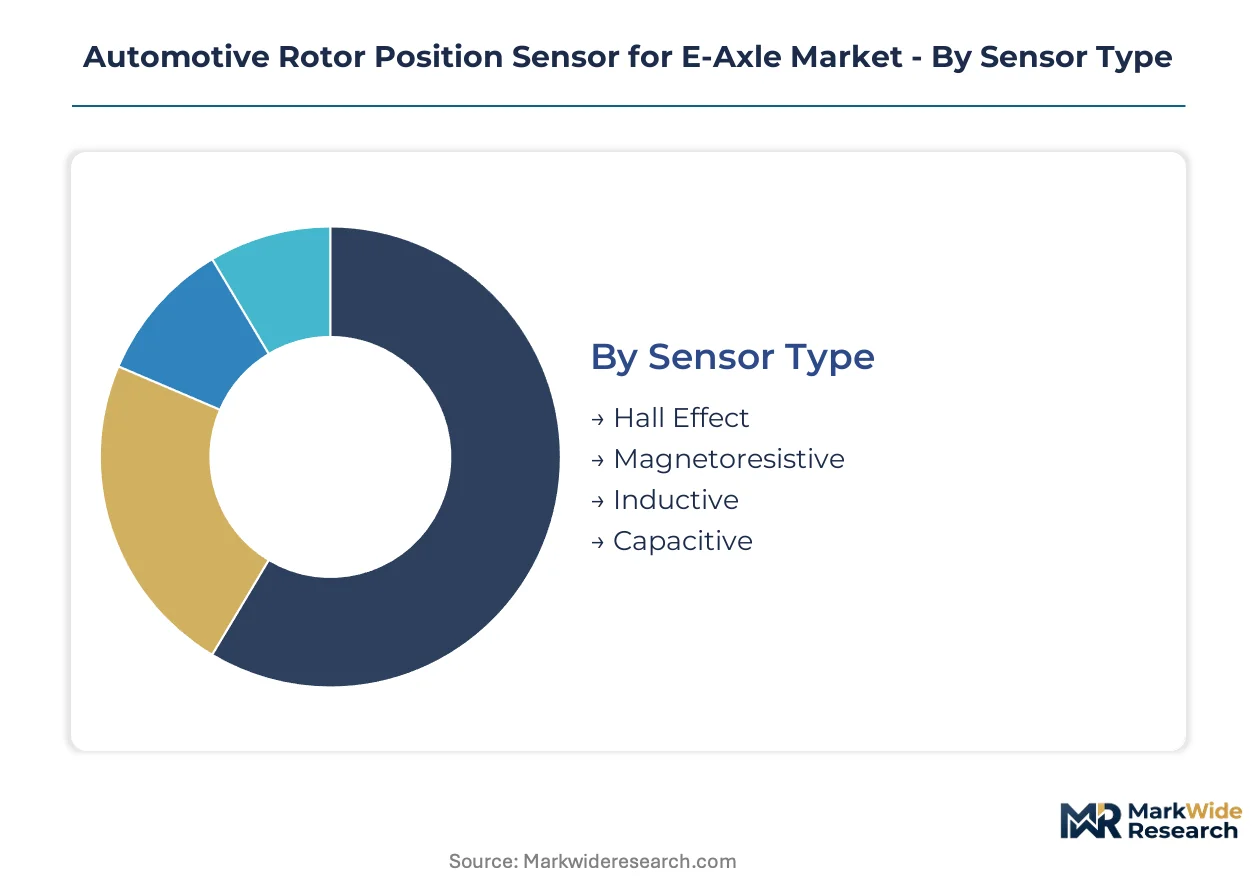
Rotor position sensor procurement splits across incompatible technical architectures and safety-critical qualification tiers. Purchasing decisions in e-axle programs diverge sharply based on motor control precision requirements and thermal operating envelopes.
Sensor Type:
Hall Effect variants face intensifying substitution pressure from magnetoresistive alternatives in premium traction motor applications where sub-degree accuracy commands sourcing priority.
- Hall Effect:Silicon-based magnetic sensing elements leverage mature wafer fabrication economics for cost-sensitive e-axle volumes. Procurement concentrates among German OEM platform teams in Stuttgart manufacturing corridors where AEC-Q100 qualification timelines align with 800V motor program deadlines.
- Magnetoresistive:Thin-film magnetic field sensors deliver angular resolution below 0.5 degrees for autonomous vehicle traction control. Demand clusters in Munich-area e-axle development centers where field-oriented control algorithms require redundant position feedback for ASIL-D certification.
- Inductive:Eddy-current sensing architectures operate without rare-earth magnetic concentrators in high-temperature motor environments.
- Capacitive:Electrostatic position detection targets specialized low-speed auxiliary motor applications with minimal magnetic interference susceptibility.
Hall Effect anchors the volume base while magnetoresistive gains share at the steepest rate.
Technology:
Output signal architectures stratify procurement budgets through interface complexity and electromagnetic immunity specifications.
- Analog Output:Continuous voltage signal conditioning demands external filtering components in dense e-axle enclosures. Cost-sensitive hybrid vehicle programs in European manufacturing clusters retain this legacy architecture for resolver-to-solid-state retrofits.
- Digital Output:Native SPI or SENT protocol transmission eliminates external ADC conversion and reduces EMC susceptibility. Premium electric vehicle platforms specify this configuration for integrated drive units where space constraints prohibit discrete signal conditioning.
- Pulse Width Modulation:Duty-cycle encoded position data serves motor control systems with legacy controller hardware.
- Frequency Output:Oscillator-based signal generation targets isolated safety-critical channels requiring galvanic separation from high-voltage motor bus.
Analog Output retains the largest installed base while Digital Output climbs the fastest among new e-axle platform awards.
Application:
Vehicle electrification intensity determines sensor accuracy tiers and functional safety qualification requirements.
- Electric Vehicles:Battery-electric powertrains with 15,000+ RPM permanent magnet synchronous motors demand solid-state position sensing for regenerative braking coordination. Procurement concentrates in German OEM integrated drive unit programs subject to EU Green Deal fleet emission mandates.
- Hybrid Vehicles:Dual-powertrain architectures combine internal combustion and electric traction with less stringent rotor feedback precision.
- Autonomous Vehicles:Redundant position sensing for fail-operational traction control requires ASIL-D qualified components with diagnostic coverage exceeding 99 percent.
- Commercial Vehicles:Heavy-duty e-axle applications prioritize magnetic robustness over angular resolution for high-torque low-speed operation.
Electric Vehicles anchor current procurement volumes while Autonomous Vehicles expand most quickly on safety-critical specification upgrades.
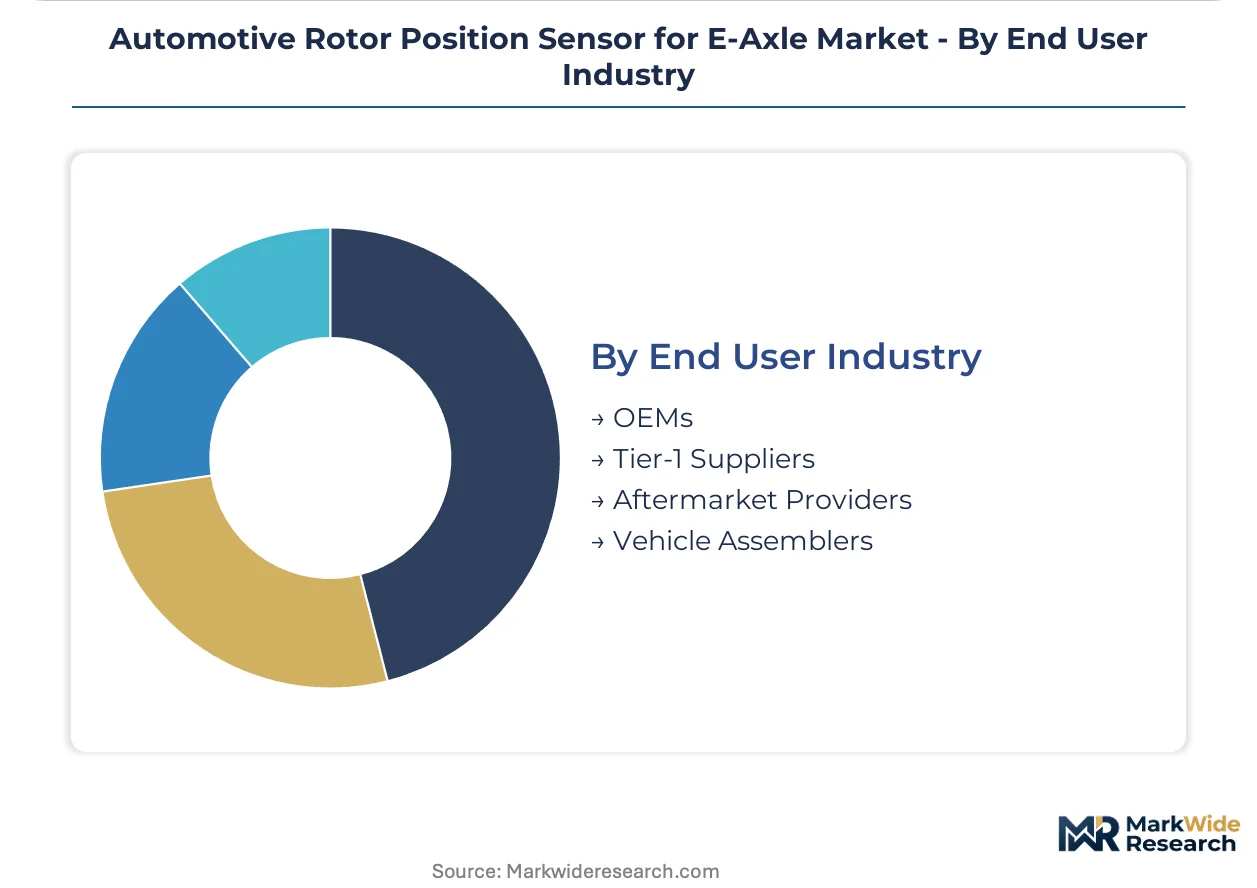
End User Industry:
Supply chain position determines technical specification authority and long-term agreement structures.
- OEMs:Vehicle manufacturers with captive e-axle design teams specify rotor position sensors directly for proprietary motor control algorithms. BMW and Volkswagen Group platforms in Germany centralize these sourcing decisions within powertrain electrification divisions.
- Tier-1 Suppliers:Integrated drive unit specialists procure sensors as sub-assemblies for motor controller integration.
- Aftermarket Providers:Service channel distributors target legacy hybrid vehicle resolver replacements with solid-state retrofit kits.
- Vehicle Assemblers:Contract manufacturers without powertrain design authority implement sensor specifications dictated by platform owners.
OEMs control premium platform specification while Tier-1 Suppliers capture volume through integrated e-axle module sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German procurement corridors while cost-sensitive volume manufacturing gravitates toward Asian supply bases. This asymmetry fragments margin capture across the value chain. Regulatory divergence between EU Green Deal mandates and EPA zero-emission vehicle timelines widens specification gaps between regional sensor markets.
Germany
Stuttgart and Munich manufacturing clusters anchor European e-axle production with integrated drive unit assembly lines demanding ASIL-D qualified position sensing. KBA enforces type approval standards that accelerate migration from resolver-based to solid-state magnetic architectures. Bavarian OEM platform teams centralize procurement decisions for 800V motor programs.
United States
Detroit-area electrification engineering centers specify rotor position sensors for permanent magnet synchronous motor control in next-generation truck platforms. NHTSA motor vehicle safety standards tighten accuracy requirements for regenerative braking coordination systems. Michigan-based Tier-1 suppliers consolidate sensor sourcing through long-term semiconductor house agreements.
China
Domestic EV platform proliferation drives procurement of cost-optimized Hall-effect sensors for high-volume permanent magnet motor production. MIIT dual carbon goals accelerate local content requirements for electrified powertrain feedback components. Yangtze River Delta manufacturing corridors concentrate magnetic sensing IC packaging and motor controller integration.
Japan
Premium hybrid vehicle programs retain resolver-based position sensing for legacy motor controller compatibility. METI industrial policy supports domestic semiconductor-sensor house capacity for automotive AEC-Q100 qualification. Nagoya-area automotive electronics clusters specialize in temperature-compensated magnetic sensing architectures.
South Korea
Battery-electric vehicle exports to EU markets require ISO 26262 functional safety certification upgrades for rotor feedback systems. Seoul Capital Area R&D centers develop magnetoresistive sensor elements for autonomous vehicle traction control applications. Busan-Ulsan manufacturing bases integrate position sensing into domestic e-axle module production.
Automotive Rotor Position Sensor for E-Axle Market Competitive Landscape
Concentration sits with integrated semiconductor-sensor houses controlling premium e-axle platform awards. Discrete component vendors compete for cost-sensitive hybrid vehicle retrofits and aftermarket replacement volumes. Two strategic archetypes dominate: captive wafer fabrication operations with magnetic sensing IP, and fabless design houses specializing in programmable temperature compensation. Competitive moves center on AEC-Q100 qualification timeline acceleration and ASIL-D certification portfolio expansion.
Within the integrated fabrication tier, Robert Bosch and Infineon Technologies exemplify the captive supply model for automotive magnetic sensing. Melexis occupies a position among programmable sensor specialists addressing high-temperature motor environment requirements. These three anchors represent divergent approaches to functional safety certification and OEM platform integration timelines.
| Leading Market Players |
|---|
| Robert Bosch |
| Continental |
| ZF Friedrichshafen |
| Denso |
| Valeo |
| Infineon Technologies |
| NXP Semiconductors |
| Melexis |
| Piher Sensing Systems |
| Others |
Pricing and Supply Chain Analysis
ISO 26262 functional safety certification tiers simultaneously gate supplier qualification and stratify price premiums across e-axle rotor position sensor procurement. ASIL-D validation requirements compress the qualified vendor pool while commanding configured-to-order pricing multiples over standard ASIL-B components.
Pricing Analysis
Configured-to-order pricing for ASIL-D qualified sensors with redundant architectures commands substantial premiums over standard ASIL-B catalog offerings. Price differentiation rests on certification grade and volume scale, with OEM direct-sourcing contracts achieving cost compression through multi-year offtake commitments while spot-market purchasers absorb volatility. Pricing pressure stems from rare-earth magnet cost volatility transmitting through permanent magnet motor procurement budgets. Aftermarket retrofit providers exhibit highest price sensitivity; autonomous vehicle platform teams show lowest sensitivity due to safety-critical specification rigidity.
Supply Chain Analysis
Strategic stockpiling of automotive-qualified Hall-effect die concentrates among German and South Korean Tier-1 suppliers buffering against foundry allocation constraints. Wafer fabrication draws from Taiwan, Germany, and South Korea; magnetic sensing IC packaging clusters in Malaysia and China. Neodymium and dysprosium rare-earth dependencies tether the chain to Chinese and Australian extraction. Single-source vulnerability concentrates in AEC-Q100 qualified foundry capacity. Distribution runs through integrated drive unit assemblers directly to OEM platform teams, bypassing traditional component distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the capital expenditure cycle of European OEM electrification programs, with procurement intensity tied to EU Green Deal fleet mandate compliance deadlines.
For Market Incumbents: Shield premium platform positions through captive wafer fabrication capacity expansion in Germany and accelerated ASIL-D certification portfolio breadth. Magnetoresistive technology substitution threatens Hall-effect volume dominance; backward integration into magnetic sensing IP and temperature-compensated die design secures margin protection against fabless competitors. For New Entrants and Emerging Players: Differentiate on inductive sensing architectures for high-temperature motor environments where rare-earth magnet elimination resonates with cost-volatile procurement teams. Commercial vehicle e-axle applications present the most penetrable white space, with lower angular resolution requirements and minimal incumbent lock-in. Target aftermarket retrofit channels with digital output retrofit kits for legacy hybrid resolver replacements. For Investors and Strategic Acquirers: EU Green Deal enforcement timeline reshapes the acquisition landscape toward semiconductor-sensor houses with demonstrated AEC-Q100 qualification velocity. Long-term viability favors integrated fabrication operations with magnetic sensing IP depth over fabless design houses exposed to foundry allocation risk. Watch MIIT dual carbon goal implementation in China as the signal indicating acceleration or deceleration of local content substitution threatening Western supplier export positions.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Acceleration | Opens premium pricing tiers for redundant sensing architectures at BMW and Volkswagen Group platforms. |
| Backward Integration into Wafer Fabrication | Captures margin erosion protection against foundry concentration in Taiwan and South Korea. |
| Magnetoresistive-Inductive Hybrid Development | Targets autonomous vehicle traction control specifications requiring sub-degree angular accuracy. |
| Digital Output Channel Expansion | Eliminates external signal conditioning and reduces EMC susceptibility in dense 800V e-axle enclosures. |
| Long-term Supply Agreement Structuring | Displaces spot-market purchasing as German OEMs consolidate procurement into centralized platform teams. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and semiconductor house product managers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from KBA type approval filings, EPA zero-emission vehicle mandate documentation, vehicle production databases, and IHS Markit registration data. Bottom-up sensor unit demand modeling triangulated against top-down e-axle production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including sensor type, output technology, vehicle electrification architecture, functional safety tier, and regional production cluster. CAGRs derived from fitted growth curves incorporating EU Green Deal fleet mandate compliance trajectories and permanent magnet synchronous motor penetration rates. Forecast inputs included OEM platform electrification timelines and rare-earth magnet price indices.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement continuity or rare-earth supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding AEC-Q100 qualification timeline compression and ASIL-D certification upgrade adoption curves. Revision becomes warranted when MIIT dual carbon goal implementation intensity or NHTSA motor vehicle safety standard amendments cross threshold levels altering OEM sourcing criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Engine Management Sensors Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
New Energy Automotive Antenna Module Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market