
 Global Automotive Charge Air Cooler Market | 2026-2036
Global Automotive Charge Air Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Charge Air Cooler Market Intelligence
Customer concentration among major automotive OEMs is shifting procurement power towards suppliers with global scale and integrated thermal management expertise. This dynamic benefits large, technologically advanced firms. MAHLE GmbH leverages its deep portfolio in engine components to offer comprehensive solutions. Meanwhile, BorgWarner Inc. specializes in advanced turbocharging and cooling technologies, solidifying its role in high-performance vehicle applications.
An automotive charge air cooler, or intercooler, is a heat exchanger used to cool compressed air from a turbocharger or supercharger before it enters the engine. These devices, often using aluminum plate fin technology, increase air density to improve combustion efficiency and power output. While air-to-air coolers dominate the passenger vehicles application due to cost, air-to-liquid coolers are gaining share. This growth is driven by packaging constraints and higher thermal efficiency requirements in commercial vehicles.
Global emissions standards are the primary regulatory force shaping the market. Mandates such as the EU's Euro 7 and regulations from the US Environmental Protection Agency (EPA) compel automakers to adopt more efficient engine cooling technologies to meet stricter pollutant targets. This regulatory pressure directly links cooler performance to compliance. Future investment decisions for suppliers will hinge on accurately forecasting the adoption rate of liquid-cooled systems versus traditional air-cooled designs.
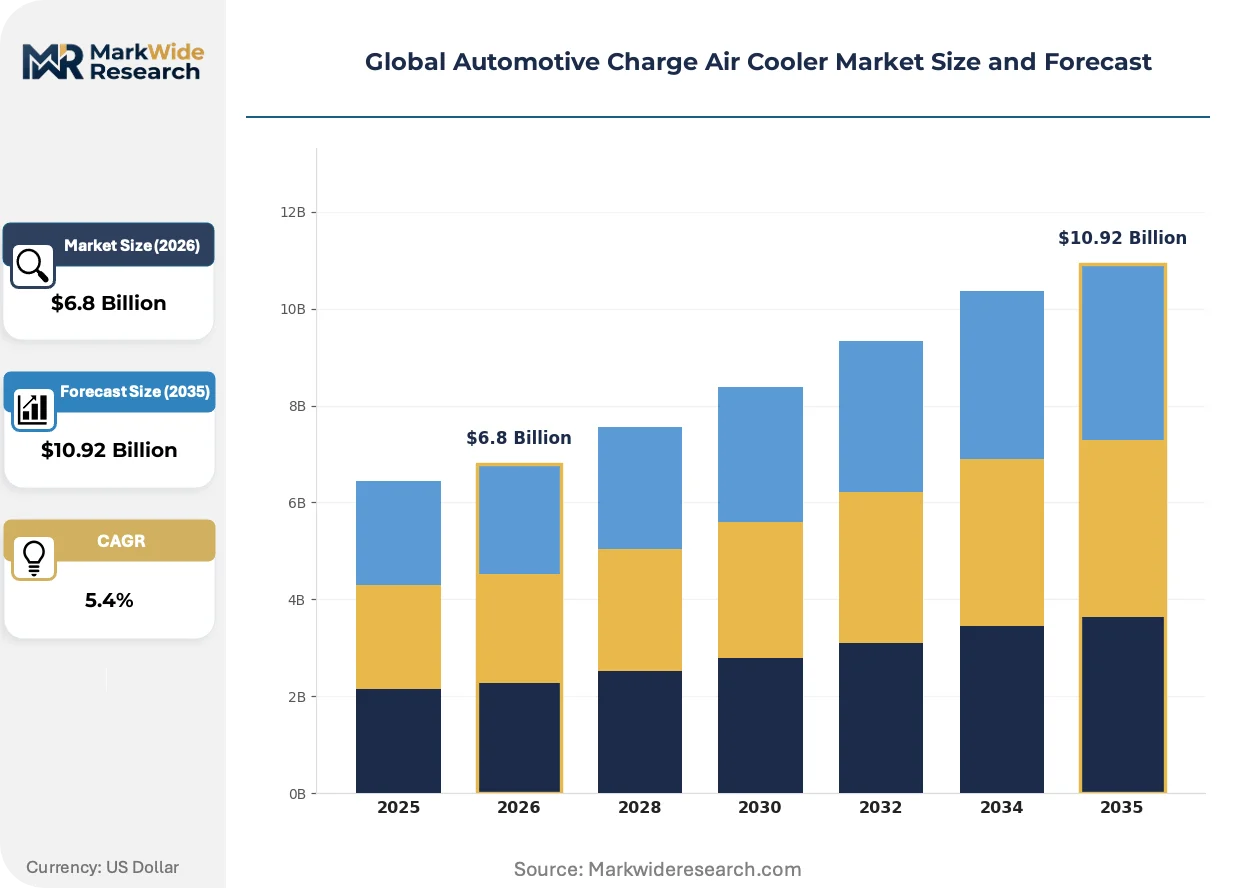
Market Dynamics
The imperative to meet stringent global emissions standards while satisfying consumer demand for higher engine power is the central force governing the automotive charge air cooler market. This dynamic creates a technical pull for more efficient cooling technologies, directly influencing design choices between air-to-air and air-to-liquid systems.
Growth Catalysts
- Stringent Emissions Regulations:Mandates such as the EU's Euro 7 standards require significant reductions in NOx and particulate matter, compelling automakers to adopt more effective charge air cooling to optimize combustion and minimize harmful byproducts.
- Engine Downsizing Trend:The widespread adoption of smaller, turbocharged engines in passenger vehicles to improve fuel economy necessitates charge air coolers to restore the air density needed for performance, creating baseline demand.
- Commercial Vehicle Demand:Expansion in logistics and freight, particularly in China's manufacturing regions, drives demand for high-performance coolers in heavy-duty trucks to enhance fuel efficiency and engine longevity under heavy loads.
Market Restraints
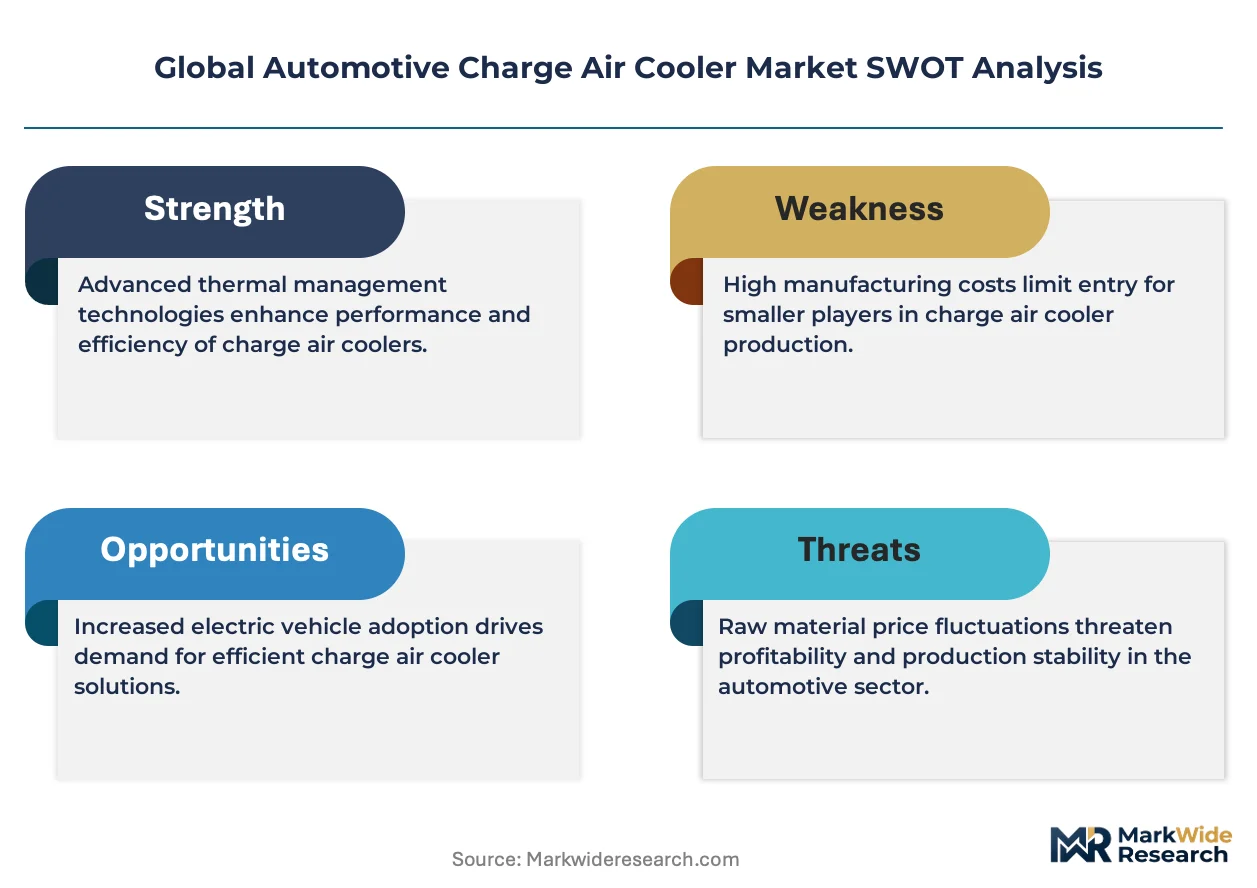
- Input Material Price Volatility:The market's heavy reliance on aluminum makes it vulnerable to fluctuations in global commodity prices, which can compress supplier margins and create pricing instability for finished cooler units.
- Packaging and Space Constraints:In modern vehicles, especially compact passenger cars and hybrids, the crowded engine bay presents a significant physical barrier to installing larger, more effective air-to-air coolers, limiting design options.
- Threat of Electrification:The long-term transition to battery electric vehicles (BEVs) represents an existential threat, as BEVs do not use internal combustion engines and therefore have no requirement for charge air coolers.
Strategic Opportunities
- Aftermarket Performance Segment:A significant opportunity exists in the performance aftermarket, where enthusiasts and tuners seek higher-capacity charge air coolers to support engine modifications for increased horsepower and torque.
- Thermal System Integration:Developing integrated thermal management modules that combine the charge air cooler with other heat exchangers, such as the radiator and battery cooler in hybrid vehicles, offers a path to higher value.
- Fleet Modernization in Developing Economies:New emissions norms in markets like India and Brazil are forcing commercial fleet operators to upgrade older vehicles, creating new demand for modern, efficient charge air cooler systems.
Industry Challenges
- High Capital Expenditure:The shift towards more complex brazed aluminum plate-and-fin or liquid-cooled designs requires substantial upfront investment in specialized manufacturing equipment, tooling, and validation testing.
- System Integration Complexity:Integrating advanced liquid-cooled charge air coolers with a vehicle's existing electronic control unit (ECU) and low-temperature coolant circuits presents a significant engineering challenge for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Charge Air Cooler Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-to-Air Cooler, Air-to-Liquid Cooler, Water-to-Air Cooler, Liquid-to-Liquid Cooler Technology: Aluminum Plate Fin, Tube Fin, Brazed Heat Exchanger, Cast Aluminum Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers |
| Companies Covered | Dana Incorporated, Modine Manufacturing Company, Valeo SA, T.RAD Co. Ltd., MAHLE GmbH, Denso Corporation, BorgWarner Inc., Hanon Systems, Garrett Motion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Charge Air Cooler Market Strategic Shifts & Innovations
Component design is evolving from standalone parts to integrated systems. This shift prioritizes thermal efficiency and compact packaging, forcing suppliers to develop deeper expertise in fluid dynamics and heat exchange management to remain competitive with vehicle original equipment manufacturers.
Liquid-cooled charge air coolers (LCCACs) use a separate coolant circuit to reduce intake air temperature. High-performance passenger cars and heavy-duty commercial vehicles are adopting this technology for its superior thermal efficiency and packaging flexibility. This technology is integrating the engine cooling circuit with the intake air cooling loop, enabling more compact and responsive thermal management systems.
Mandates from the US Environmental Protection Agency (EPA) for heavy-duty engines are a primary regulatory driver. These standards place strict limits on nitrogen oxide (NOx) emissions, which are directly influenced by the efficiency of the charge air cooling system. The North American commercial truck segment is most affected, pushing manufacturers to invest in advanced coolers to ensure compliance.
Automotive OEMs are altering their sourcing strategies for thermal components. There is a clear trend away from purchasing individual coolers toward procuring complete, pre-validated thermal management modules from a single-source supplier. This change disrupts the traditional component-level supply chain and is most prominent in Europe, where vehicle platforms are increasingly standardized.
Global Automotive Charge Air Cooler Market Segmentation
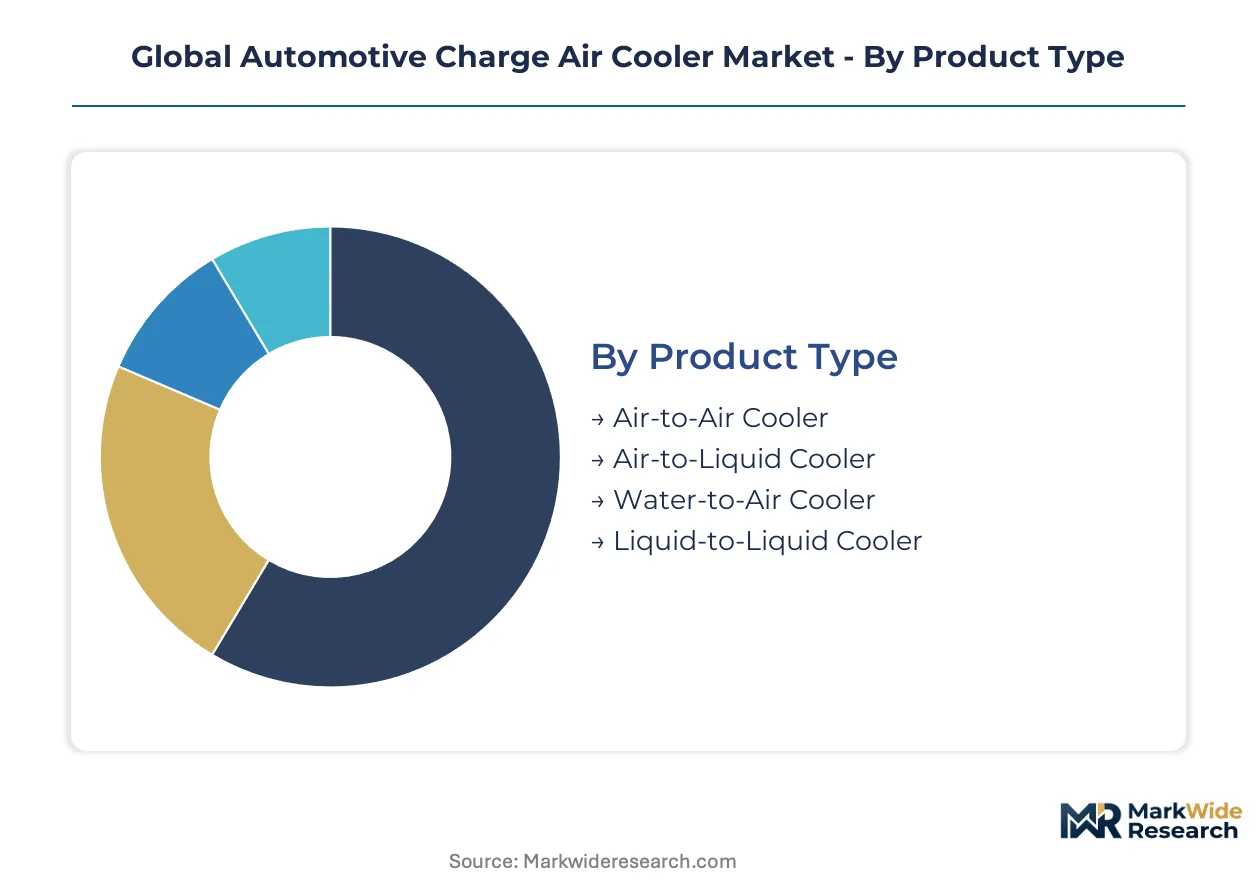
The automotive charge air cooler market exhibits diverse segmentation, reflecting varying technical requirements, application demands, and end-user procurement models. Understanding these distinct segments is essential for suppliers to tailor product development and market strategies effectively within this evolving industry landscape.
Product Type:
The customization-vs-standardization spectrum significantly influences charge air cooler product types, balancing bespoke thermal solutions with mass-produced components for broad vehicle platforms.
- Air-to-Air Cooler:This heat exchanger uses ambient air to cool compressed intake air, offering a cost-effective and robust solution primarily for passenger vehicles and some commercial applications. Its widespread use stems from simpler design and lower system complexity.
- Air-to-Liquid Cooler:This system employs a separate liquid coolant circuit to cool the intake air, providing superior thermal efficiency and packaging flexibility, especially critical in high-performance engines and commercial vehicles with constrained engine bays.
- Water-to-Air Cooler:This configuration typically refers to a specific type of air-to-liquid cooler where water is the primary coolant in the secondary circuit, common in certain heavy-duty and industrial engine setups.
- Liquid-to-Liquid Cooler:These units exchange heat between two liquid circuits, often used for highly integrated thermal management systems where precise temperature control of multiple fluids is necessary.
Leading the category by volume: Air-to-Air Cooler. Growing fastest: Air-to-Liquid Cooler.
Technology:
Performance demands and material science advancements drive the evolution of charge air cooler technologies, impacting efficiency and durability across diverse applications.
- Aluminum Plate Fin:This widely adopted technology utilizes stacked aluminum plates and fins to create a lightweight and efficient heat exchange core, favored for its balance of performance and manufacturing cost. It is a staple in high-volume passenger vehicle production.
- Brazed Heat Exchanger:These units are constructed by brazing multiple components together, forming a robust and highly efficient structure capable of withstanding high pressures and temperatures, often found in advanced commercial vehicle engines.
- Tube Fin:This design employs tubes passing through a series of fins, providing a simpler and often more cost-effective solution, particularly suitable for less demanding applications or specific packaging requirements.
- Cast Aluminum:Charge air coolers made from cast aluminum offer high strength and design flexibility, allowing for complex internal geometries that can optimize airflow and heat transfer in specialized engine architectures.
Aluminum Plate Fin technology maintains significant market presence. Brazed Heat Exchanger designs are gaining traction for high-performance requirements.
Application:
Customer type and operational environment define the specific requirements for charge air cooler applications, from light-duty passenger vehicles to heavy-duty industrial machinery.
- Passenger Vehicles:This segment includes cars, SUVs, and light trucks, where charge air coolers support engine downsizing trends and fuel efficiency goals, balancing performance with compact design. Demand is influenced by global emissions standards like Euro 7.
- Commercial Vehicles:Covering heavy-duty trucks, buses, and vans, this application demands robust and highly efficient coolers to enhance fuel economy and engine longevity under sustained heavy loads, particularly in logistics and freight sectors.
- Construction Equipment:Charge air coolers in construction machinery operate in harsh environments, requiring durable designs that can maintain engine performance and reduce emissions in demanding off-highway applications.
- Agricultural Machinery:This segment utilizes charge air coolers to optimize engine efficiency and power output for tractors, harvesters, and other farm equipment, addressing fuel consumption and emissions targets for agricultural operations.
Passenger Vehicles command the largest share. Commercial Vehicles exhibit substantial expansion.
End User:
Supply concentration patterns dictate how charge air coolers reach their final integration point, influencing procurement strategies and partnership structures across the automotive value chain.
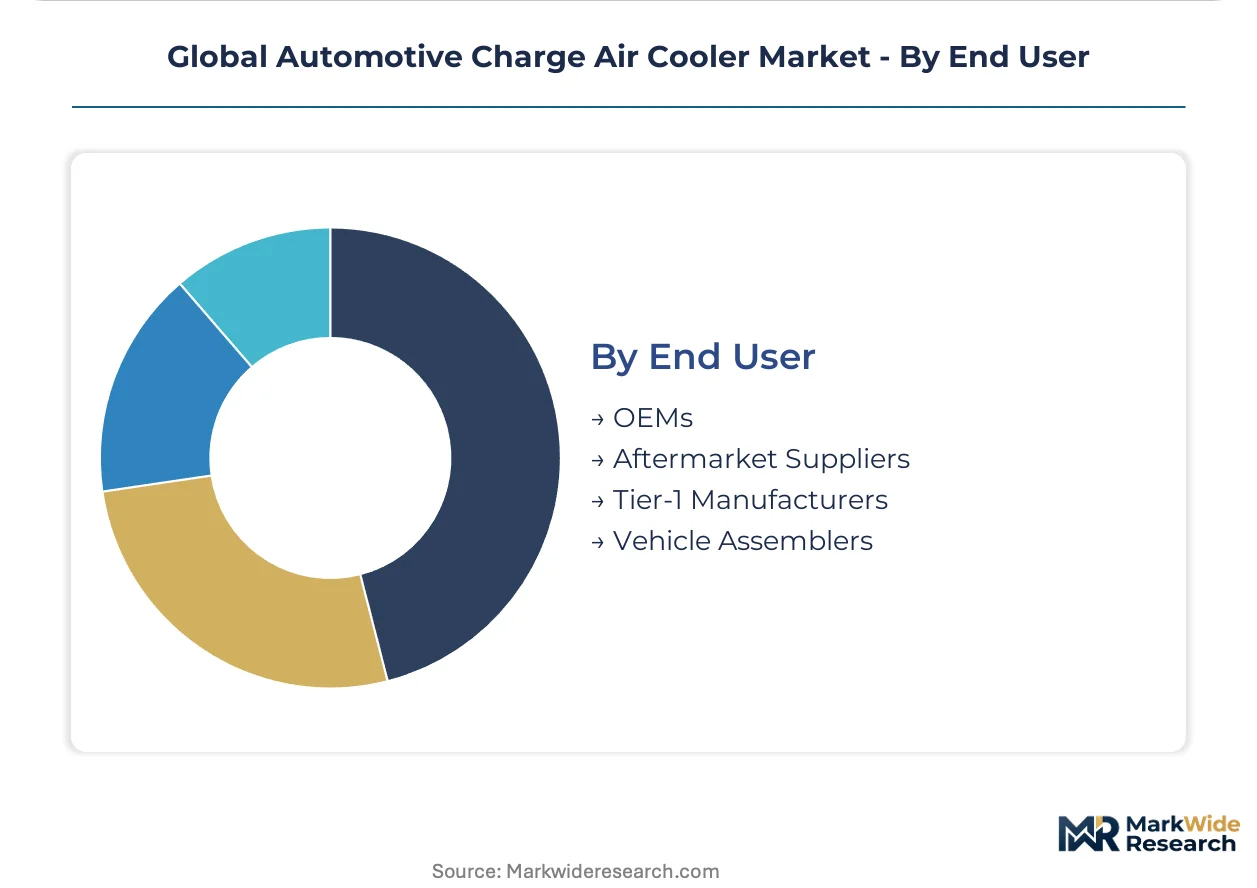
- OEMs:Original Equipment Manufacturers procure charge air coolers directly from suppliers for integration into new vehicle production lines, requiring high-volume manufacturing capabilities and adherence to stringent specifications. These relationships involve extensive validation and testing.
- Tier-1 Manufacturers:These suppliers provide complete sub-systems or modules to OEMs, often integrating charge air coolers as part of a broader thermal management or engine component assembly. They require advanced engineering and integration expertise.
- Aftermarket Suppliers:This segment addresses the demand for replacement parts and performance upgrades for existing vehicles. Aftermarket suppliers offer a range of coolers, from OE-equivalent replacements to enhanced performance units for enthusiasts.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, receiving components and sub-assemblies from various suppliers, including charge air coolers, to complete the manufacturing process.
OEMs represent the primary procurement channel. Aftermarket Suppliers address replacement and performance upgrade needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Customer concentration among major automotive OEMs drives significant demand across key global regions, influencing where charge air cooler manufacturing and innovation are most active. China's automotive production hubs, in particular, represent a focal point for both supply and demand. This geographical dynamic shapes investment decisions for suppliers worldwide.
China
Commercial vehicle expansion and logistics growth in China create substantial demand for high-performance charge air coolers. The country's dual carbon goals and GB standards push for more efficient engine technologies. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta lead automotive component production and adoption.
United States
The United States market sees demand from stringent EPA regulations for heavy-duty engines and ongoing engine downsizing trends in passenger vehicles. These mandates compel automakers to integrate advanced cooling systems. Major automotive manufacturing states like Michigan and Ohio are central to the development and adoption of these technologies.
Germany
Germany's automotive sector focuses on meeting the EU's Euro 7 emissions standards, driving demand for advanced charge air cooling in high-performance passenger vehicles. The nation's strong engineering base supports the development of sophisticated thermal management solutions. Automotive clusters in Bavaria and Baden-Württemberg remain key innovation centers.
India
New emissions norms in India are forcing commercial fleet operators to upgrade older vehicles, creating fresh demand for modern, efficient charge air cooler systems. The country's PLI scheme encourages local manufacturing of automotive components. Major automotive production hubs such as Chennai and Pune are expanding their capabilities to meet this demand.
Global Automotive Charge Air Cooler Market Key Industry Players
Asian producers anchor one tier, emphasizing scale and cost-effectiveness for high-volume segments, while European and North American specialists hold positions in advanced thermal management solutions. The market exhibits a tiered structure, with global integrated system providers and specialized component manufacturers. Strategic archetypes include large-scale OEM suppliers, technology-focused innovators, and niche aftermarket providers. Companies often pursue strategic partnerships for system integration and portfolio diversification to enhance their market reach.
Within the global integrated thermal management tier, MAHLE GmbH and BorgWarner Inc. exemplify firms offering comprehensive solutions across engine components and advanced cooling technologies. These companies leverage their deep engineering expertise to meet stringent performance and emissions requirements. Valeo SA, another significant player, occupies a position as a broad thermal systems supplier, providing a wide array of automotive components to OEMs globally.
| Leading Market Players |
|---|
| Dana Incorporated |
| Modine Manufacturing Company |
| Valeo SA |
| T.RAD Co. Ltd. |
| MAHLE GmbH |
| Denso Corporation |
| BorgWarner Inc. |
| Hanon Systems |
| Garrett Motion Inc. |
| Others |
Cost & Logistics Intelligence
The performance gap between standard air-to-air coolers and advanced liquid-cooled systems creates a distinct pricing bifurcation, influencing procurement strategies and supply chain specialization across the automotive market.
Pricing Analysis
The volume-driven passenger vehicle segment operates with tight margins, contrasting with higher profitability in specialized commercial vehicle and performance applications. Pricing for charge air coolers is predominantly contract-based long-term offtake for Original Equipment Manufacturers, shifting to transactional models in the aftermarket. Price differentiation stems from customization levels for integrated thermal modules, performance efficiency, and manufacturing complexity like brazed heat exchanger designs. Pricing softness in the air-to-air segment stems from high volume and commoditization. Passenger vehicle OEMs are highly price-sensitive for standard components; commercial vehicle OEMs are less sensitive for high-performance, integrated solutions.
Supply Chain Analysis
Reverse logistics for automotive charge air coolers primarily involves end-of-life recycling and occasional remanufacturing for the aftermarket, rather than widespread refurbishment. Geographic supply concentration for charge air coolers centers on manufacturing hubs in China, Germany, and Japan. The industry draws heavily from raw materials such as aluminum and specialized brazing materials. Commodity price volatility, particularly for aluminum, remains a structural supply chain risk. Distribution runs through direct channels to OEMs and Tier-1 suppliers, with aftermarket sales facilitated by a network of distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive charge air cooler market presents a clear consolidation play, driven by the existential threat of electrification which forces weaker, less diversified players out of the market.
For Market Incumbents:Acquire specialized thermal management software expertise to enhance system integration capabilities for hybrid and electric vehicle platforms. Invest significantly in advanced liquid-cooled system manufacturing capacity, particularly in regions with stringent emissions regulations like the United States and Europe. This defensive move mitigates the long-term threat of electrification by repositioning for future thermal demands. Focus R&D on integrated thermal modules that combine multiple cooling functions, providing a comprehensive solution to OEMs.
For New Entrants and Emerging Players:Begin with targeting the performance aftermarket segment, where enthusiasts seek higher-capacity charge air coolers for engine modifications. This niche offers higher margins and lower entry barriers compared to OEM supply. Focus on developing application-specific designs that offer superior thermal efficiency and packaging flexibility. A go-to-market angle should emphasize proven performance gains and ease of installation for specific vehicle models, building brand reputation within this enthusiast community.
For Investors and Strategic Acquirers:Re-rating potential sits with integrated thermal management specialists given the accelerating shift towards advanced liquid-cooled systems and electrification. Long-term viability, over a 5-10 year horizon, favors companies with deep expertise in complex thermal management modules. Target acquisition candidates should be firms with strong intellectual property in liquid-cooled designs or advanced materials for heat exchange. The signal to watch is the increasing proportion of OEM procurement shifting towards complete thermal management systems rather than individual components.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Liquid-Cooled Manufacturing | Secures future market share as air-to-liquid systems gain traction in high-performance and commercial vehicles. |
| Develop Integrated Thermal Modules | Addresses OEM demand for compact, efficient, and pre-validated thermal solutions, enhancing value proposition. |
| Expand Aftermarket Performance Offerings | Captures a high-margin segment driven by consumer demand for engine upgrades and customization. |
| Secure Long-Term Aluminum Supply | Mitigates commodity price volatility, ensuring stable production costs and competitive pricing. |
| Form Strategic OEM Partnerships | Ensures early involvement in new vehicle platform development, aligning products with future market needs. |
Research Approach
Multi-period observation of emissions standard evolution and vehicle production statistics anchored the trend analysis, supplemented by interviews with OEM procurement managers, Tier-1 engineering leads, aftermarket distributors, and commercial fleet operators. This approach integrated primary insights with secondary validation from sources including EPA regulations, Euro standards, vehicle production databases, and commodity market reports. Bottom-up and top-down triangulation ensured comprehensive market understanding.
An input-output matrix framework was utilized to project market dynamics across the analysis window, integrating segmented data for product type, technology, application, and end-user. The framework also incorporated regional regulatory compliance as a key dimension. Compound annual growth rates were derived from historical data, projected market shifts, and specific industry inputs such as engine downsizing rates and electrification adoption curves.
Underlying measurement precision varies by segment; passenger vehicle and commercial vehicle applications carry tighter precision than construction equipment. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Practitioners should monitor shifts in global emissions mandates and raw material supply stability for early signals of market trajectory changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
GCC Automotive Lead-Acid Battery Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Middle East and Africa Automotive DC-DC Converters Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Jump Starter Market