

Bicycle Electronic Drivetrain Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Electronic Drivetrain Market Insights
Subscription-based firmware leasing and asset-light component financing is tilting competitive dynamics toward firms with recurring revenue infrastructure. SRAM leverages direct-to-consumer channel control to bypass traditional bike shop networks. Shimano anchors its position through backward integration into precision forging and motor winding operations. Bosch sustains R&D intensity across both drive systems and battery management architectures.
Bicycle electronic drivetrains integrate servo-actuated derailleurs, wireless shifters, and lithium-polymer power modules to automate gear selection with millisecond response times and sub-millimeter alignment accuracy. The primary commercial purpose is eliminating mechanical cable friction and manual adjustment burden across high-cycle-count riding applications. Derailleurs and control units capture the dominant margin pools due to firmware complexity and sensor density requirements. Wireless connectivity and Bluetooth integration segments are expanding fastest as frame builders eliminate internal cable routing complexity. Hydraulic actuation remains mature in downhill and enduro mountain biking where force requirements exceed electric servo limits.
FCC equipment authorization governs wireless transmission protocols for US-market systems, while EU CE marking and RoHS substance restrictions shape material selection and electromagnetic compatibility testing for European distribution. The EU AI Act and GDPR frameworks increasingly influence connected drivetrain data collection policies as manufacturers deploy ride-analytics and over-the-air update capabilities. Stakeholders must monitor how firmware interoperability standards evolve across proprietary wireless protocols versus open-architecture alternatives.
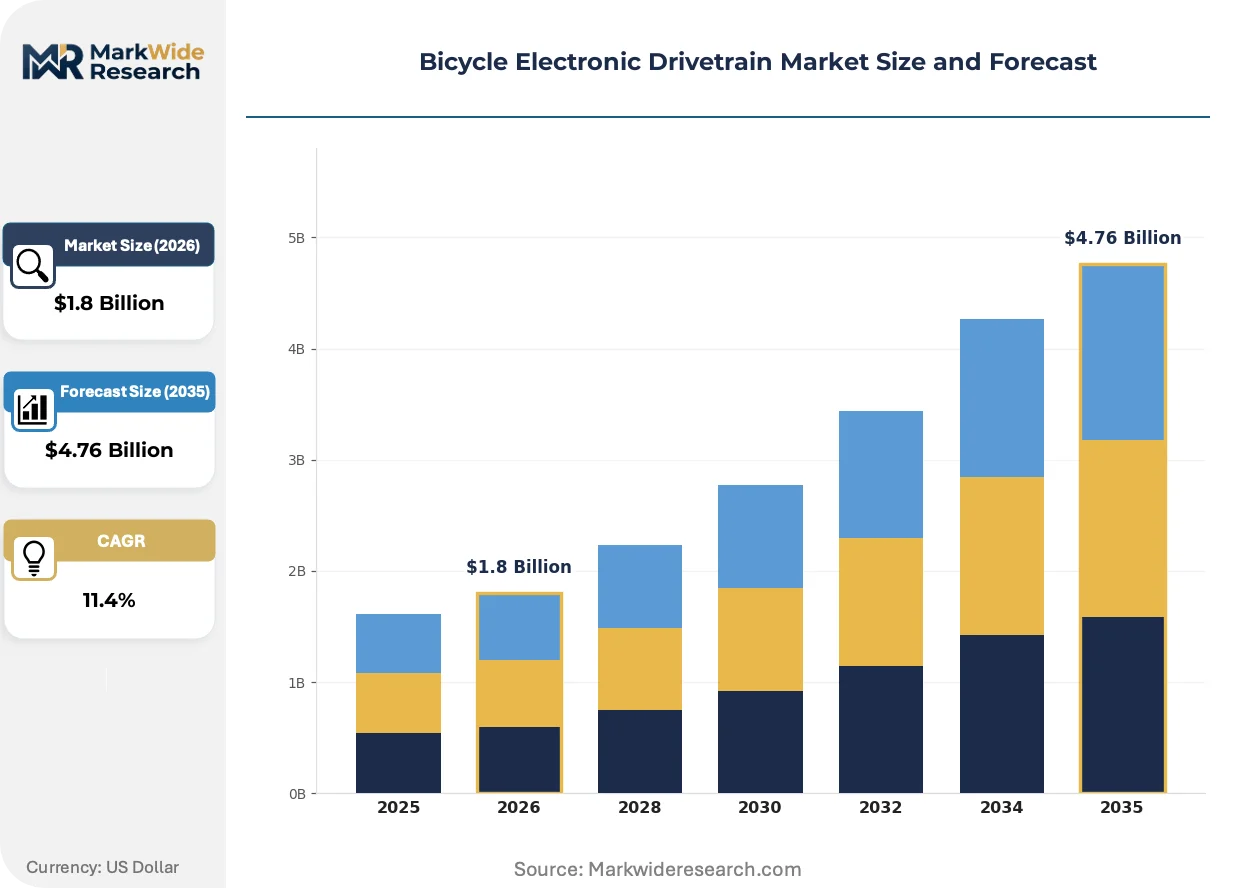
Market Dynamics
Wireless protocol standardization is fragmenting supplier ecosystems as proprietary stacks from drivetrain incumbents collide with open-architecture alternatives pushed by frame builders seeking interoperability.
Growth Catalysts
- EU Green Deal infrastructure mandates:Member states must expand cycling lane networks and active mobility corridors, accelerating fleet electrification requirements for municipal bike-share operators and delivery logistics providers.
- Lithium-polymer energy density improvements:Cell chemistry advances extend derailleur actuator endurance between charges, reducing range anxiety for ultra-endurance racing and bikepacking applications.
- Germany's supplier clustering:Precision forging and motor winding capabilities concentrate in Baden-Württemberg and Bavaria, shortening development cycles for domestic OEMs and export-oriented frame builders.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings from Chinese export quotas compress servo motor margins and complicate long-term supplier contracting.
- FCC equipment authorization timelines:Wireless transmission protocol testing for US market entry adds 4-6 month certification delays that disadvantage smaller drivetrain entrants against established authorization holders.
- Hydraulic actuation substitution in gravity disciplines:Downhill and enduro mountain biking retains cable-actuated systems where force requirements exceed electric servo torque limits, capping addressable market share in these segments.
Strategic Opportunities
- India's PLI scheme for advanced automotive components:Component suppliers can access production-linked incentives by establishing servo motor and sensor assembly operations for export to European and North American bike manufacturers.
- Over-the-air firmware monetization:Subscription tiers for shift-optimization algorithms and predictive maintenance analytics create recurring revenue streams beyond hardware sales.
- Bluetooth LE Audio convergence with cycling computers:Drivetrain control units integrating with head-unit ecosystems reduce handlebar clutter and consolidate vendor relationships for performance-oriented consumers.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time control algorithm development and RF protocol engineering expertise concentrates in automotive and aerospace sectors, forcing drivetrain firms to compete for specialized labor.
- CE marking electromagnetic compatibility testing:RoHS substance restrictions and EMC validation for European distribution require dedicated compliance teams and extended product validation cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Electronic Drivetrain Market Trends and Innovations
Digital twin simulation and predictive maintenance architectures are compressing product development timelines while reshaping how manufacturers validate firmware reliability across variable terrain conditions.
Edge computing integration in rear derailleur housings is virtualizing the traditional split between mechanical hardware and control intelligence. Servo controllers now process terrain gradient and cadence data locally rather than routing through handlebar-mounted head units. Professional cycling teams and gran fondo organizers are adopting these systems for real-time gear optimization during multi-day events. This architecture is virtualizing supplier boundaries as frame builders specify integrated smart-hanger designs that embed sensors directly into dropout interfaces.
The EU AI Act's risk classification framework is tightening algorithmic transparency requirements for connected drivetrains that process biometric and geolocation data. Manufacturers deploying ride-analytics and automated shift recommendation engines must document training data provenance and decision logic for notified body review. High-end road and gravel bike segments face the steepest compliance burden as these categories collect the most granular rider performance metrics.
Bike shop service departments are unbundling from traditional distribution networks as direct-to-consumer brands build proprietary diagnostic and remote-tuning capabilities. Riders now expect over-the-air firmware updates and video-guided calibration rather than in-person mechanical adjustment. This pattern is most pronounced in Germany and the Netherlands where dense urban cycling populations support centralized technical support centers serving multiple metropolitan markets.
Bicycle Electronic Drivetrain Market Segmentation
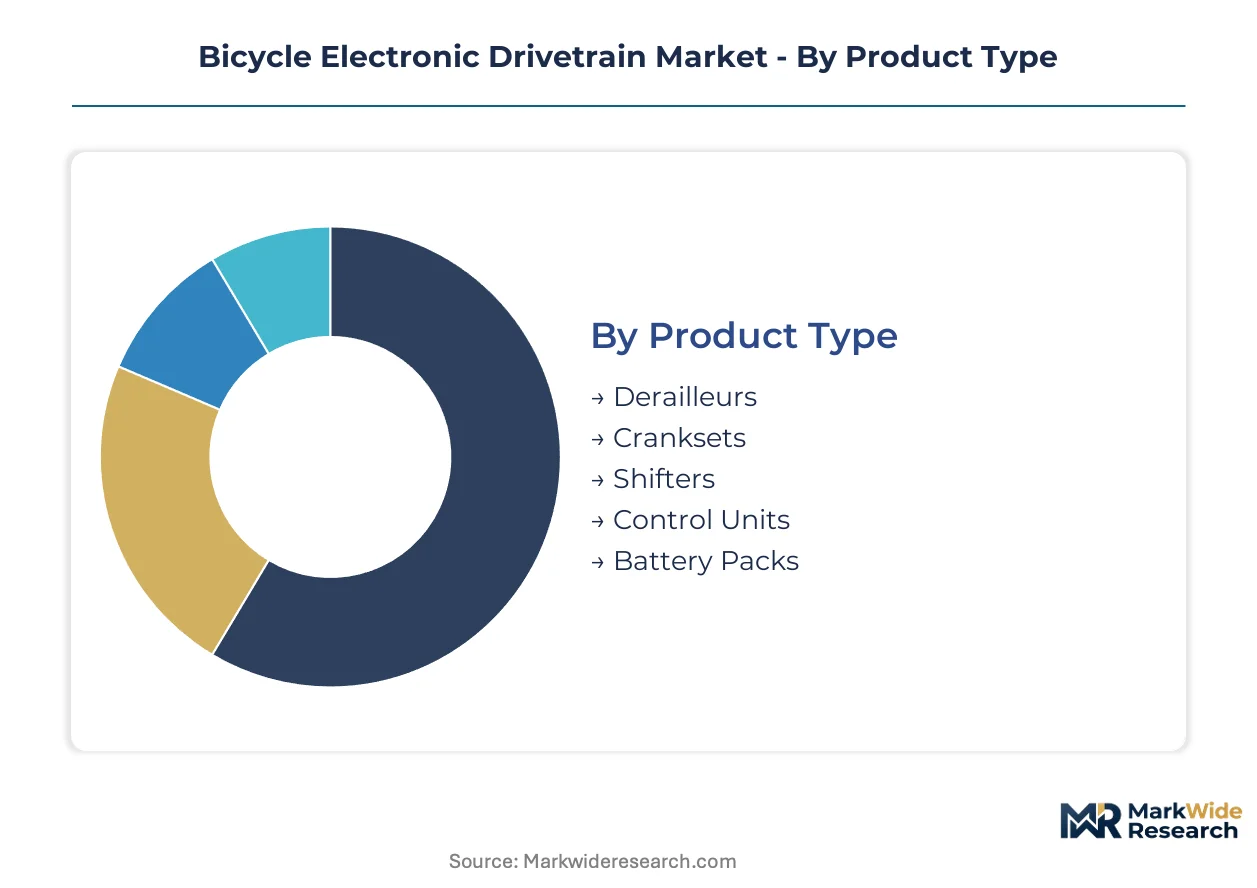
Electronic drivetrain segmentation reveals how component specialization, transmission protocols, and rider intensity tiers create distinct margin architectures. Manufacturers configure R&D allocation and firmware roadmaps around these boundaries.
Product Type:
Cost tier stratification separates precision-forged mechanical components from firmware-intensive control systems, with margin pools concentrating at opposite ends of the value chain.
- Derailleurs:Servo-actuated rear mechanisms integrate brushless motors, planetary gearboxes, and Hall-effect position sensors within weather-sealed housings. Professional cycling teams in Germany and Belgium specify these for cobblestone classics where millisecond shift response prevents chain drops. Rare earth magnet supply constraints from Chinese export quotas compress motor margins.
- Control Units:Handlebar-mounted processors execute real-time terrain algorithms and manage wireless protocol handshakes with derailleur servos. High-end road and gravel bike builders in the Netherlands integrate these with head-unit ecosystems to reduce cockpit clutter. Firmware complexity creates recurring revenue potential through subscription-tier shift optimization.
- Cranksets:Hollow-forged aluminum or carbon fiber arms with integrated power meter spiders and chainring mounting interfaces.
- Shifters:Wireless transmitters or hydraulic master cylinders converting rider input into electronic or mechanical actuation signals.
- Battery Packs:Lithium-polymer cells with battery management systems providing 60-100 hour endurance ratings between charges.
Derailleurs hold installed capacity. Control units are rotating up the share rankings.
Technology:
Application context determines protocol selection, with force requirements and frame integration complexity driving trade-offs between wireless convenience and hydraulic power transmission.
- Wireless Connectivity:Proprietary RF protocols eliminate internal cable routing and enable frame builders to simplify manufacturing workflows. EU CE marking electromagnetic compatibility testing adds validation cycles for European market entry. FCC equipment authorization timelines in the US extend certification windows.
- Hydraulic Actuation:Mineral oil or DOT fluid systems transmit rider input through sealed lines to servo-assisted derailleurs. Downhill and enduro mountain biking in the French Alps and Italian Dolomites retains these where impact forces exceed electric servo torque limits. Gravity discipline substitution caps addressable share.
- Mechanical-Linkage:Traditional cable-actuated systems with electronic trim assistance for hybrid transition architectures.
- Bluetooth Integration:Standardized protocols enabling third-party device pairing and over-the-air firmware distribution.
- CAN Bus:Automotive-derived controller area network protocols for e-bike drive system integration with motor and battery management.
Wireless connectivity is climbing the fastest. Hydraulic actuation maintains defensive positions in gravity segments.
Application:
Rider intensity and event duration shape durability requirements, with competitive racing segments demanding redundant systems and recreational categories prioritizing ease of maintenance.
- Mountain Biking:Cross-country, trail, and gravity disciplines expose drivetrains to mud contamination, chain slap, and impact loading. German frame builders in Baden-Württemberg specify sealed servo housings and reinforced hanger interfaces. Wireless protocol standardization fragmentation complicates interoperability across proprietary ecosystems.
- Road Racing:Peloton dynamics and sprint finishes require sub-200-millisecond shift execution under 1000-watt power outputs. Professional teams competing in Belgium's spring classics and Italy's grand tours drive specification for integrated power meter and shift-logic combinations. EU AI Act algorithmic transparency requirements tighten for connected ride-analytics.
- Touring:Multi-day self-supported riding prioritizes battery endurance and field-serviceable components over weight minimization.
- Commuting:Urban stop-start riding patterns favor automatic shift modes and low-maintenance sealed systems.
- Triathlon:Aerodynamic integration and single-chainring simplicity dominate time-trial and Ironman-distance specifications.
Road racing holds installed capacity. Mountain biking is rotating up the share rankings.
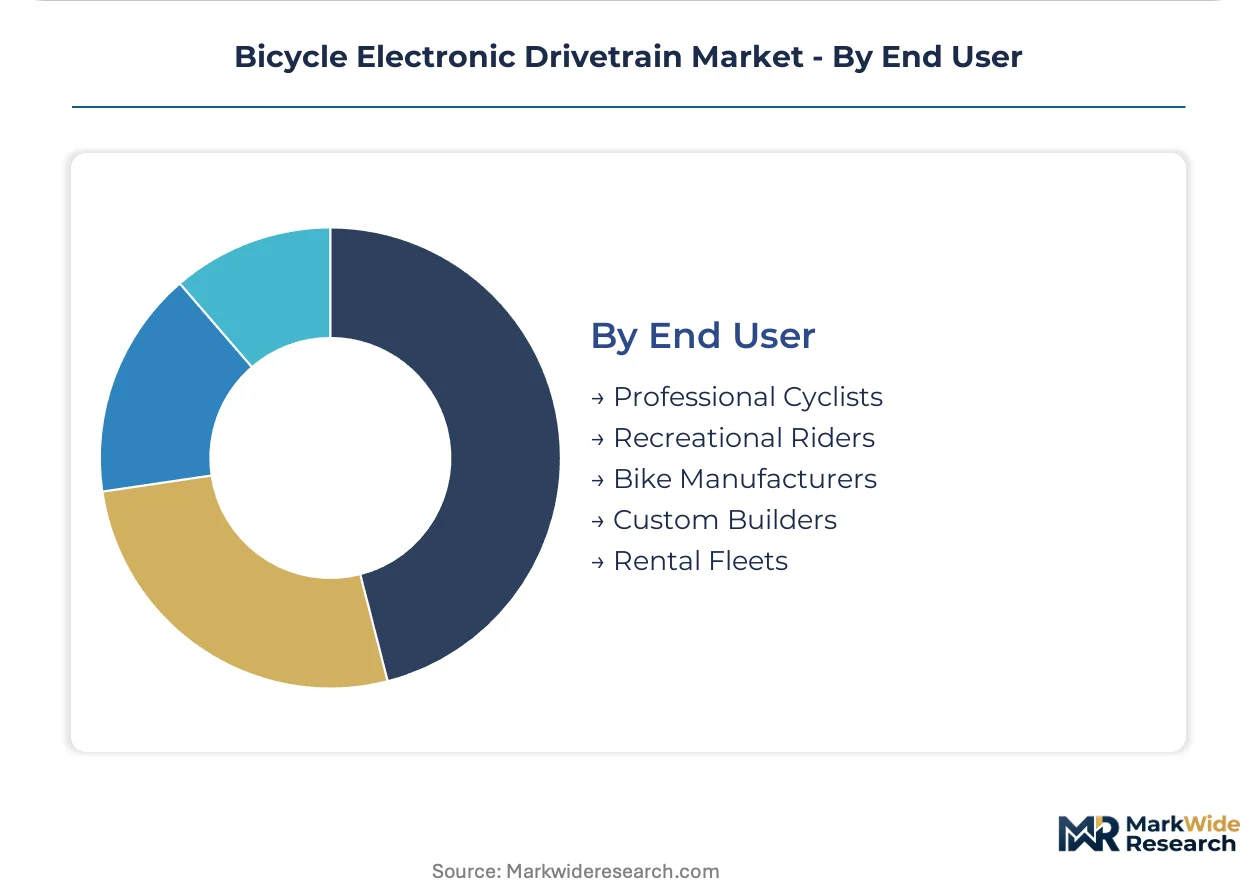
End User:
Customer type determines procurement channel structure, with direct-to-consumer brands bypassing traditional bike shop networks for recreational segments while professional teams maintain technical partnership relationships.
- Professional Cyclists:UCI-registered teams and continental squads receive pre-release firmware and dedicated engineering support. SRAM leverages direct channel control to supply WorldTour outfits with custom shift mapping. Embedded systems firmware talent scarcity forces competition with automotive and aerospace sectors.
- Bike Manufacturers:OEM frame builders specify integrated dropout sensors and smart-hanger designs that embed control intelligence directly into frame interfaces. Bosch and Shimano maintain deep supplier relationships with domestic German e-bike producers. Backward integration into precision forging shortens development cycles.
- Recreational Riders:Gran fondo participants and club cyclists purchasing through retail or direct channels.
- Custom Builders:Small-batch frame constructors specifying open-architecture wireless protocols for interoperability.
- Rental Fleets:Municipal bike-share operators and commercial tourism providers prioritizing durability and remote diagnostics.
Bike manufacturers hold installed capacity. Professional cyclists are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal infrastructure mandates are accelerating procurement cycles for electronic drivetrain systems across member states, while India's PLI scheme for advanced automotive components attracts servo motor assembly investment targeting export markets.
Germany
Baden-Württemberg and Bavaria host precision forging and motor winding clusters that shorten development cycles for domestic e-bike OEMs. The EU Green Deal cycling corridor investments push municipal procurement of fleet-grade electronic shifting systems. Bosch and Shimano maintain captive supplier relationships with frame builders in Stuttgart and Munich metropolitan zones.
United States
FCC equipment authorization timelines extend certification windows for wireless transmission protocols, favoring established authorization holders. Professional cycling teams in Colorado and California drive specification for integrated power meter combinations. The IRA clean vehicle tax credit structures indirectly support active mobility infrastructure spending in progressive municipalities.
India
The PLI scheme for advanced automotive components subsidizes servo motor and sensor assembly operations for export to European and North American bike manufacturers. Domestic frame builders in Pune and Chennai trial open-architecture wireless protocols for cost-sensitive export models. BIS certification requirements for electronic components add validation layers for subcontinent-sourced subassemblies.
Netherlands
Dense urban cycling populations in Amsterdam and Rotterdam support centralized technical support centers serving multiple metropolitan markets. EU GDPR frameworks constrain connected drivetrain data collection policies for ride-analytics deployments. Frame builders in Eindhoven specify integrated dropout sensors that embed control intelligence directly into carbon fiber layups.
Belgium
Professional teams competing in Flanders spring classics drive specification for sub-200-millisecond shift execution under sustained power outputs. CE marking electromagnetic compatibility testing requirements shape firmware validation cycles for European distribution. Precision component suppliers in Flemish manufacturing corridors export servo-actuated mechanisms to German and Italian frame builders.
Bicycle Electronic Drivetrain Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: precision-forged mechanical specialists with captive motor winding capabilities, firmware-intensive control system developers monetizing recurring revenue streams, and integrated drive system architects spanning battery management and actuator design. Dominant competitive moves include backward integration into rare earth magnet supply chains and direct-to-consumer channel construction bypassing traditional bike shop networks.
Among the precision-forged mechanical tier, Shimano and Campagnolo exemplify heritage component houses that anchor market positioning through in-house production of alloy forgings and planetary gearboxes. SRAM occupies a distinct vector as a direct-to-consumer channel architect, while Bosch represents the integrated drive system archetype spanning motor control and energy management architectures. These three anchors collectively illustrate how competitive positioning fragments across mechanical mastery, channel control, and system integration capabilities.
| Leading Market Players |
|---|
| Shimano |
| SRAM |
| Campagnolo |
| Bosch |
| Bafang |
| Fazua |
| Giant Manufacturing |
| MAGURA |
| TranzX |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet cost volatility from Chinese export quotas compresses servo motor margins and determines both three-tier pricing spreads across premium, standard, and entry-level drivetrain tiers and the geographic clustering of backward-integrated suppliers in Germany and Japan.
Pricing Analysis
Certification level creates the primary spread between CE-marked European-market systems and FCC-authorized US-market variants, with electromagnetic compatibility testing costs embedded in landed pricing. Subscription-based firmware tiers for shift-optimization algorithms now capture recurring revenue alongside hardware transactions. Pricing pressure stems from lithium-polymer cell cost compression as Korean and Chinese battery suppliers expand capacity. Recreational riders through direct-to-consumer channels exhibit highest price sensitivity, while professional cycling teams prioritize shift-response specifications over unit cost.
Supply Chain Analysis
Neodymium and dysprosium feedstock draws from Chinese mining and separation facilities, with secondary refining capabilities in Japan and the United States. Precision-forged aluminum crank arms and planetary gearboxes source from Baden-Württemberg machining clusters and Taiwanese forging houses. Hall-effect sensors and brushless motor windings hinge on semiconductor fabrication concentrated in South Korea and Taiwan. Single-source vulnerability in rare earth magnet supply creates margin volatility for servo motor producers. Distribution runs through OEM frame builder specifications in Germany and the Netherlands, with aftermarket service increasingly centralized in technical support hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle electronic drivetrain market sits at a wireless-protocol disruption inflection where EU Green Deal infrastructure mandates accelerate fleet procurement cycles beyond historical replacement rates.
For Market Incumbents: Build firmware interoperability moats through proprietary wireless protocol ecosystems that lock frame builders into integrated dropout sensor specifications. Deepen backward integration into precision forging and motor winding operations in Baden-Württemberg to compress development cycles for domestic OEMs. Channel control through direct-to-consumer diagnostic platforms defends against bike shop network disintermediation. Invest in CE marking and FCC authorization infrastructure to extend certification timelines that disadvantage smaller entrants. For New Entrants and Emerging Players: Build out open-architecture wireless protocol stacks targeting custom frame builders in India and Southeast Asia seeking interoperability outside proprietary ecosystems. India's PLI scheme for advanced automotive components offers subsidized servo motor assembly capacity for export to European and North American manufacturers. Municipal bike-share operators in EU member states present the most penetrable segment, with fleet-grade durability requirements and centralized procurement channels. Pursue over-the-air firmware monetization through subscription-tier predictive maintenance analytics rather than competing on hardware margins. For Investors and Strategic Acquirers: The market sits at an early-mass-adoption phase that favors integrated drive system architects with captive battery management and actuator design capabilities. Long-term viability across the projection horizon rests on firms combining precision mechanical production with recurring revenue infrastructure for connected ride-analytics. Acquisition targets should demonstrate firmware talent density in real-time control algorithms and RF protocol engineering. Watch for EU AI Act enforcement patterns around algorithmic transparency requirements as the inflection indicator for compliance-cost winners versus losers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Mitigates Chinese export quota exposure for servo motor margins. |
| Direct-to-Consumer Diagnostic Platform Launch | Bypasses traditional bike shop networks for firmware update distribution. |
| Open-Architecture Wireless Protocol Development | Captures custom frame builder demand outside proprietary ecosystems. |
| Subscription-Based Firmware Monetization | Creates recurring revenue streams beyond hardware transaction cycles. |
| PLI Scheme Manufacturing Footprint in India | Accesses subsidized servo motor assembly for export markets. |
Research Methodology
A spread of perspectives from drivetrain engineering directors, frame builder procurement leads, professional team technical liaisons, and bike shop service managers converged on the working assumptions. Primary interviews combined with secondary validation from FCC equipment authorization databases, EU CE marking registries, customs trade data for rare earth magnet flows, and SEC filings from listed component suppliers. Bottom-up unit shipment estimates triangulated against top-down OEM production forecasts.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by derailleur, control unit, and battery pack categories; technology segmentation across wireless, hydraulic, and mechanical architectures; and application segmentation by mountain biking, road racing, and commuting intensity tiers. CAGRs derived from regression analysis of historical procurement cycles against EU Green Deal infrastructure spending trajectories. Forecast inputs included lithium-polymer energy density improvement curves and embedded systems firmware talent availability indices.
Stress conditions across rare earth export quota severity, FCC certification timeline extensions, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about wireless protocol standardization velocity and municipal fleet electrification commitment durability. Cross-checking against IEA active mobility infrastructure spending benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.