
 Jump Starter Market | 2026-2036
Jump Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Jump Starter Market Outlook
Lithium-ion battery chemistry replacing lead-acid architectures is reshaping how jump starters are engineered, packaged, and distributed. NOCO Company leverages vertical integration in battery management systems to sustain premium positioning across North American retail channels. Shenzhen CARKU Technology anchors high-volume production of compact lithium units for Asian and European private-label brands. Stanley Black & Decker competes through brand strength and channel control in mass-market hardware retail.
A jump starter is a portable power device delivering high-current bursts to crank internal combustion engines with depleted batteries, typically rated between 400 and 3,000 peak amperes depending on vehicle class. Its primary commercial purpose is eliminating dependency on second-vehicle jump assistance or tow services in automotive service, fleet maintenance, and consumer roadside emergencies. Lithium-ion jump starters now lead unit growth due to weight reduction and USB charging integration, while lead-acid units retain margin pools in heavy-duty commercial applications requiring sustained cranking cycles. Smart jumper technology with reverse-polarity protection and voltage sensing commands pricing premiums in the automotive service provider channel.
The US NHTSA and DOT shape product safety mandates for highway emergency equipment, while the EU REACH regulation and F-Gas Directive constrain battery material sourcing and refrigerant-based accessory designs for European market entry. China's SAMR enforces GB standards for lithium battery transport and retail certification, directly affecting Shenzhen and Xiamen manufacturers' export documentation burdens. Stakeholders must monitor how evolving battery chemistry regulations and charger standard harmonization reshape component sourcing and regional market access requirements.
Market Dynamics
Lithium-ion battery chemistry is displacing lead-acid architectures across portable jump starter designs, compressing unit weights by 60-70% while integrating USB power delivery for consumer electronics. This chemistry shift concentrates manufacturing capability in Chinese industrial clusters and reshapes certification requirements for air transport and retail distribution.
Growth Catalysts
- Diesel Cold-Start Reliability Mandates:Fleet operators in commercial logistics face tightening uptime guarantees that make roadside battery failure economically punitive. Lithium-ion jump starters with 2,000+ peak amperes satisfy heavy-duty cranking requirements without second-vehicle dependency.
- EU F-Gas Directive Constraints:Refrigerant-based accessory designs for integrated air compressor jump starters face phase-down schedules. Manufacturers pivoting to compressor-free or alternative refrigerant architectures gain accelerated market access across Germany, France, and Benelux.
- Shenzhen-Dongguan Manufacturing Density:Component sourcing for battery management systems, USB-C power delivery controllers, and lithium pouch cells concentrates within 50 kilometers. This geographic clustering reduces procurement lead times and enables rapid private-label turnaround for European and North American brands.
Market Restraints
- Lithium Carbonate Price Volatility:Cathode material input costs swing with electric vehicle battery demand cycles. Jump starter manufacturers lack long-term offtake agreements that automotive OEMs negotiate, exposing margin compression during supply tightness.
- GB Standard Certification Burden:China's SAMR enforces lithium battery transport documentation and retail certification that adds 6-8 weeks to export timelines. Shenzhen and Xiamen manufacturers face documentation friction when routing through Shanghai or Ningbo ports.
- Lead-Acid Residual Demand in Commercial Fleets:Sustained cranking cycles for diesel fleet maintenance favor lead-acid units with higher thermal mass. Lithium-ion alternatives face replacement cost resistance in price-sensitive municipal and construction fleet procurement.
Strategic Opportunities
- India Automotive Service Channel:Organized roadside assistance networks under Orix Auto Infrastructure and Mahindra First Choice Wheels remain underpenetrated by branded lithium jump starter suppliers. Local assembly partnerships with BIS-certified battery packers circumvent import duty structures.
- Vehicle-to-Load (V2L) Convergence:Bidirectional power electronics from electric vehicle charging infrastructure migrate into premium jump starter designs. Integration of 110V/220V AC inverters targets camping and emergency preparedness segments beyond traditional automotive use.
- US IRA Domestic Content Incentives:Battery assembly tax credits for North American-produced cells create margin expansion for manufacturers establishing US-based pack assembly. Final assembly in Mexico or US border states satisfies origin requirements while preserving component sourcing flexibility.
Industry Challenges
- Battery Management System Firmware Talent Scarcity:Lithium-ion safety architectures require embedded systems engineers with IEC 62619 and UN 38.3 testing experience. Shenzhen employers compete with electric vehicle and energy storage sectors for this specialized labor pool.
- Multi-Certification Parallel Tracking:Simultaneous UL 2743 (US), CE (EU), and PSE (Japan) approvals demand distinct testing protocols and documentation sets. Smaller manufacturers face resource strain maintaining concurrent certification validity across 18-24 month renewal cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jump Starter Market |
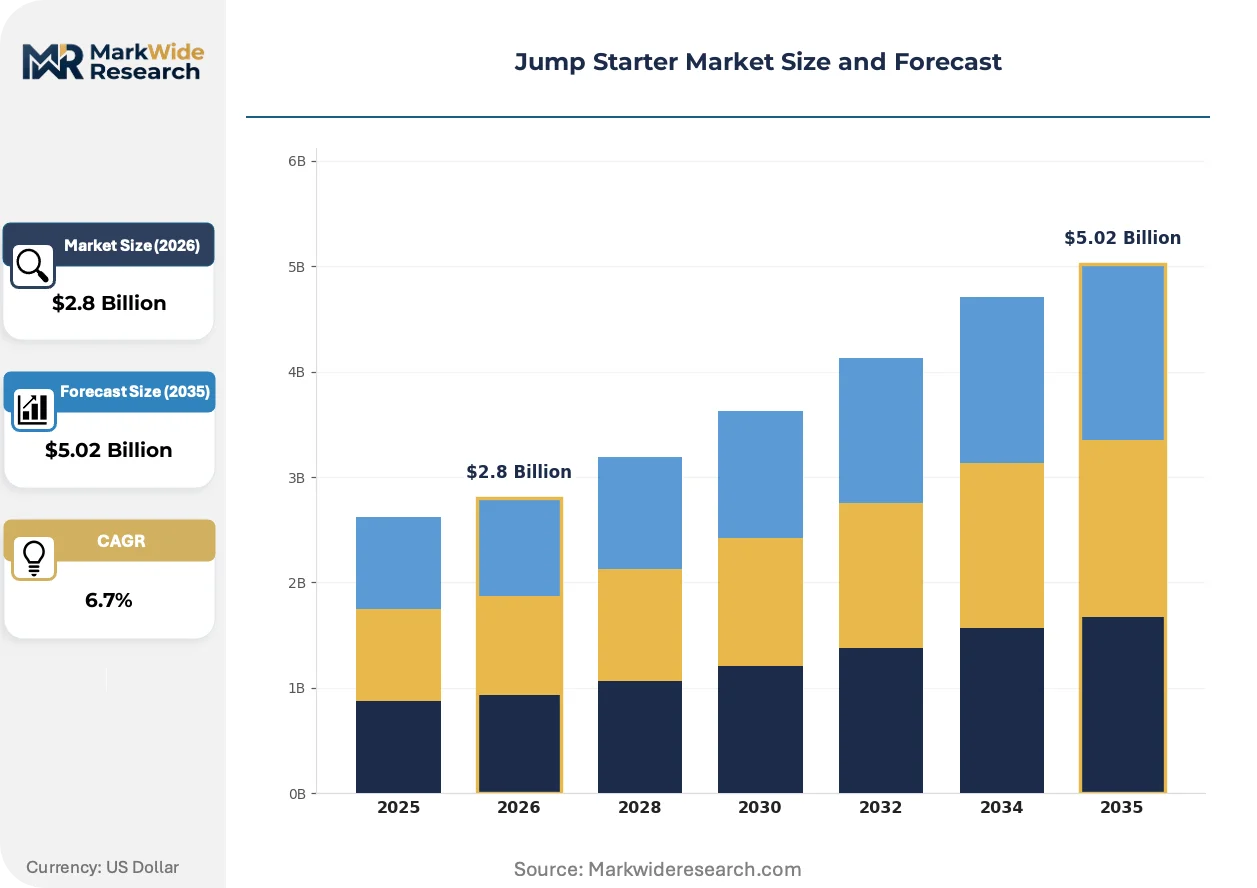
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
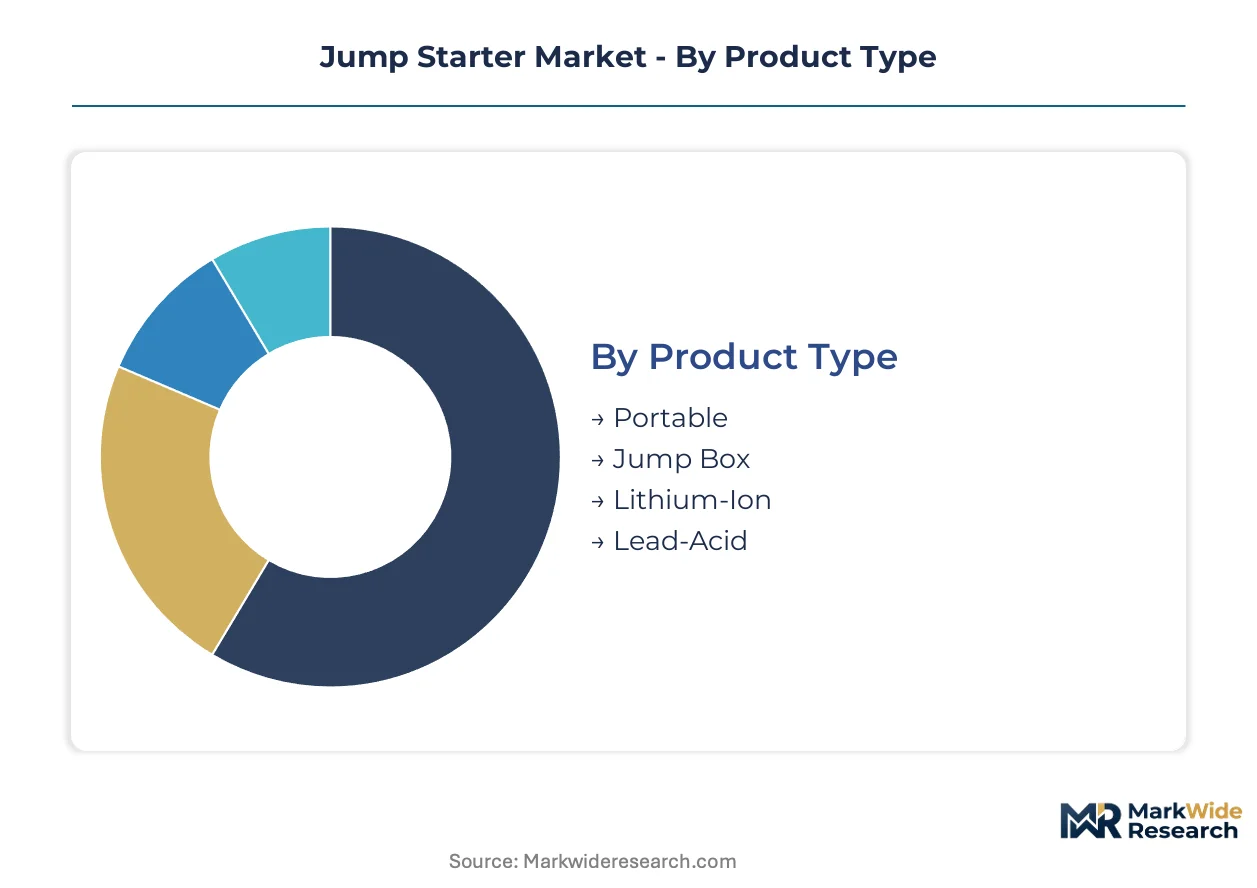
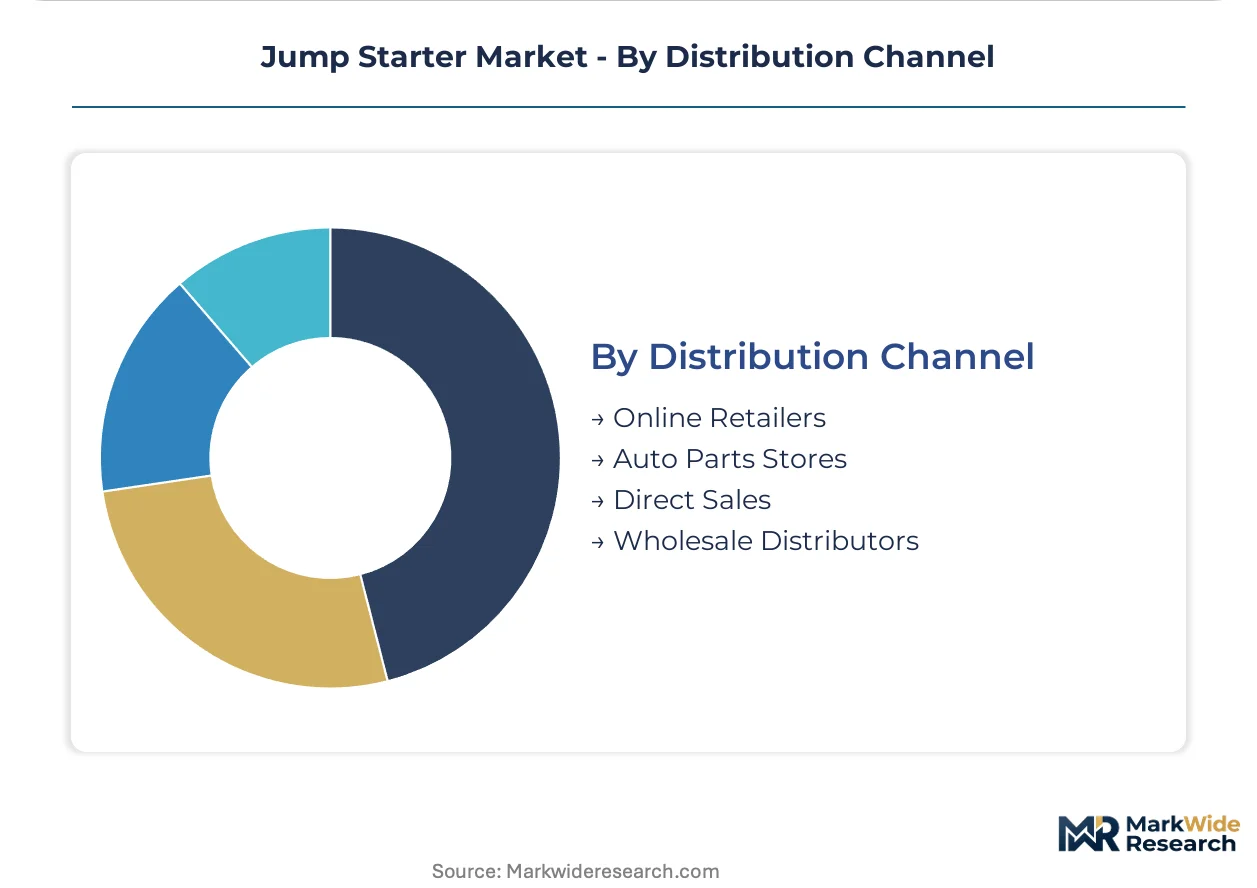
| Segmentation | Product Type: Portable, Jump Box, Lithium-Ion, Lead-Acid Technology: Smart Jumpers, Traditional Jumpers, Solar-Powered, USB Charger End User: Consumer, Automotive Service Providers, Fleet Managers, OEMs Distribution Channel: Online Retailers, Auto Parts Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | NOCO Company, Schumacher Electric Corporation, Clore Automotive, Stanley Black & Decker, Shenzhen CARKU Technology Co., Ltd, Antigravity Batteries LLC, Xiamen GOOLOO Technology Co., Ltd., Shenzhen DBPower Technology Co., Ltd., CTEK Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jump Starter Market Strategic Shifts
Smart jumper technology with integrated voltage sensing and reverse-polarity protection is redefining product differentiation in automotive service channels. Three convergent developments are compressing traditional hardware margins while opening premium pricing tiers.
Battery management system firmware is digitizing safety monitoring functions previously handled by discrete analog circuitry. Automotive service providers in Germany and the US adopt units with Bluetooth diagnostic logging that records cranking voltage curves for warranty documentation. This capability is digitizing how fleet maintenance departments justify equipment refresh cycles and negotiate service level agreements with roadside assistance contractors.
REACH regulation substance restrictions and the EU Battery Passport framework are forcing material provenance documentation for cobalt, nickel, and lithium content. European distributors now require supply chain attestation for conflict minerals and carbon intensity metrics before listing private-label products. German KBA type approval processes for highway emergency equipment are extending to encompass end-of-life recycling responsibility allocation between manufacturers and importers.
Fleet procurement departments are consolidating vendor relationships and demanding multi-year total cost of ownership guarantees rather than unit purchase pricing. This behavior shift compresses distributor margins in North American commercial vehicle channels while favoring manufacturers with captive battery cell supply and extended warranty underwriting capabilities. The transformation is most visible in US Class 8 trucking fleet maintenance contracts, where uptime penalties now exceed equipment capital costs by factors of ten.
Jump Starter Market Segmentation
Jump starter procurement patterns diverge sharply across vehicle classes, power requirements, and operational intensity. Fleet operators prioritize sustained cranking cycles and warranty-backed uptime guarantees, while consumer segments favor portability and multi-function USB integration.
Product Type:
Use-case spectrum spans roadside emergency assistance to scheduled fleet maintenance, with chemistry and form factor determining deployment context.
- Portable:Compact lithium-polymer units under 2 kilograms dominate consumer roadside kits and ride-share driver equipment. Demand concentrates in North American big-box retail and Chinese e-commerce platforms where USB-C power delivery integration commands modest premiums.
- Jump Box:Wheeled lead-acid configurations with 3,000+ peak amperes serve municipal fleets and construction equipment yards. US Class 8 trucking maintenance contracts favor these units for sustained diesel cranking cycles where thermal mass prevents overheating.
- Lithium-Ion:Energy density advantages enable glove-box stowage and air-travel compliance under UN 38.3 protocols. Shenzhen manufacturers anchor production capacity for European private-label brands seeking REACH-attested supply chains.
- Lead-Acid:Lower unit costs and repairability sustain residual demand in price-sensitive emerging markets and heavy-duty commercial applications requiring field-serviceable cell replacement.
Established volume favors Lead-Acid; emerging adoption favors Lithium-Ion.
Technology:
Margin structure correlates with firmware complexity and safety certification tier.
- Smart Jumpers:Integrated voltage sensing and reverse-polarity protection eliminate spark hazards during clamp connection. German KBA type approval and US UL 2743 certification create pricing separation from unprotected alternatives.
- Traditional Jumpers:Passive copper cable designs with clamp-based polarity indicators retain cost-sensitive fleet procurement share. Indian automotive service channels and Latin American independent repair shops represent concentrated demand pockets.
- Solar-Powered:Photovoltaic panel integration targets off-grid emergency preparedness and remote mining operations. Australian mining camps and South African agricultural cooperatives drive niche procurement for grid-independent battery maintenance.
- USB Charger:Bidirectional power electronics enable consumer electronics charging from vehicle battery reserves. Japanese PSE certification requirements for power delivery controllers constrain supplier qualification timelines.
Premium positioning clusters with Smart Jumpers; volume scale concentrates with Traditional Jumpers.
End User:
Procurement authority and total cost accountability reshape vendor selection criteria across buyer categories.
- Consumer:Individual vehicle owners purchasing through retail channels or roadside assistance program memberships. Amazon and Walmart dominate North American transaction volume with private-label and branded lithium units.
- Automotive Service Providers:Independent repair shops and dealership service departments requiring warranty documentation and diagnostic logging. Bluetooth-enabled cranking voltage recording supports customer dispute resolution and insurance claims.
- Fleet Managers:Commercial logistics operators with uptime penalty clauses exceeding equipment capital costs by order of magnitude. Multi-year total cost of ownership guarantees replace unit pricing in vendor negotiations.
- OEMs:Vehicle manufacturers bundling jump starters with new vehicle sales or roadside assistance program enrollment. Telematics integration opportunities drive specification requirements for voltage monitoring and predictive battery failure alerting.
Contract value scales with Fleet Managers; transaction frequency peaks with Consumer.
Distribution Channel:
Channel control determines margin capture and brand positioning autonomy.
- Online Retailers:Amazon, Alibaba, and specialty automotive e-commerce platforms aggregate consumer search traffic and review-driven purchase decisions. Shenzhen manufacturers direct-list to bypass distributor markups.
- Auto Parts Stores:O'Reilly, AutoZone, and NAPA maintain counter staff recommendation influence for emergency replacement purchases. Inventory turns favor compact lithium units with minimal shelf footprint.
- Direct Sales:Manufacturer-owned channels serving fleet procurement departments with customized warranty terms and volume pricing. NOCO and CARKU operate direct sales teams for North American and European fleet accounts.
- Wholesale Distributors:Regional automotive supply houses stocking private-label inventory for independent repair shop procurement. Documentation burdens for lithium battery transport certification constrain cross-border distribution efficiency.
Margin retention favors Direct Sales; market access breadth concentrates with Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan manufacturers export lithium-ion jump starters to Germany, the United States, and Japan, with certification documentation determining market access velocity across destination regimes.
United States
Class 8 trucking fleets and municipal procurement departments drive demand for wheeled lead-acid jump boxes with sustained cranking capacity. The NHTSA enforces battery safety protocols for highway emergency equipment under DOT oversight. Manufacturing concentrates in Mexico border states and US Southeast assembly plants serving retail channels.
Germany
Automotive service providers and fleet maintenance contractors prioritize smart jumper technology with diagnostic logging capabilities. The KBA extends type approval processes to encompass end-of-life recycling responsibility under REACH substance restrictions. Industrial distribution clusters around Stuttgart and Munich anchor premium-tier equipment sourcing.
China
Shenzhen and Dongguan manufacturing clusters supply global private-label demand for compact lithium-polymer units. SAMR enforces GB standards for lithium battery transport documentation and retail certification. Xiamen exporters face documentation friction when routing through Shanghai or Ningbo ports.
India
Roadside assistance networks under Orix Auto Infrastructure and Mahindra First Choice Wheels present procurement expansion targets. BIS certification requirements constrain direct import pathways for unbranded equipment. Local assembly partnerships with battery packers in Maharashtra and Gujarat circumvent duty structures.
Japan
Consumer electronics integration and bidirectional power delivery specifications shape product requirements. METI oversees PSE certification for power delivery controllers in USB-equipped units. Industrial buyers in the Kanto and Kansai regions demand compact form factors for passenger vehicle roadside kits.
Jump Starter Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The structure concentrates around brand-holding retail distributors and high-volume contract manufacturers serving private-label demand. Three archetypes dominate: vertically integrated battery management system developers, Shenzhen-based production specialists, and diversified tool conglomerates with hardware retail channel control. Competitive moves center on geographic certification expansion and captive supply chain development for lithium cell procurement.
Among US-based specialists, NOCO Company and Antigravity Batteries LLC occupy positions emphasizing firmware-driven safety architectures and premium-tier positioning. Shenzhen CARKU Technology Co., Ltd anchors the high-volume production archetype for Asian and European private-label supply. These three exemplify how geographic origin and organizational structure map to divergent competitive vectors across certification-intensive destination markets.
| Leading Market Players |
|---|
| NOCO Company |
| Schumacher Electric Corporation |
| Clore Automotive |
| Stanley Black & Decker |
| Shenzhen CARKU Technology Co., Ltd |
| Antigravity Batteries LLC |
| Xiamen GOOLOO Technology Co., Ltd. |
| Shenzhen DBPower Technology Co., Ltd. |
| CTEK Sweden AB |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate price volatility serves as the dominant risk vector determining both pricing tier spreads and supply chain shape across the jump starter market. Swings in cathode material input costs compress margins for manufacturers lacking long-term offtake agreements while forcing tiered pricing stratification between premium firmware-integrated units and commodity lithium alternatives.
Pricing Analysis
The technology-generation pricing gap separates legacy lead-acid wheeled units, current-generation lithium-polymer compact designs, and emerging vehicle-to-load integrated architectures. Three-tier pricing structure across premium smart-jumper, standard lithium, and economy lead-acid levels reflects certification grade differentiation and USB power delivery integration. Cost compression in standard lithium tiers is intensifying because electric vehicle battery demand cycles divert cell supply. Fleet procurement departments exhibit lowest price sensitivity due to uptime penalty clauses, while emerging market municipal buyers retain highest sensitivity.
Supply Chain Analysis
Upstream feedstock for lithium pouch cells draws from Chinese cathode material refiners, Australian spodumene concentrate exporters, and Chilean carbonate processors. Battery management system controllers source from Taiwanese semiconductor foundries and South Korean power electronics specialists. Single-source vulnerability concentrates in Shenzhen-Dongguan manufacturing clusters where component sourcing within 50-kilometer radius enables rapid turnaround. Distribution runs through direct sales teams for fleet accounts, online retailers for consumer segments, and wholesale distributors for independent repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across the jump starter market as fleet procurement consolidation creates vendor relationship gaps that specialized players can exploit. The divergence between heavy-duty commercial uptime requirements and consumer portability demands generates distinct competitive arenas with limited overlap.
For Market Incumbents: Insulate margin position through captive supply arrangements for lithium cells and backward integration into battery management system firmware development. NOCO Company's vertical control over safety architectures demonstrates how certification investment creates pricing separation from unprotected alternatives. Shenzhen manufacturers must defend against emerging Indian assembly partnerships by accelerating GB standard documentation efficiency.
For New Entrants and Emerging Players: India's organized roadside assistance networks present the most penetrable geographic underpenetration for branded lithium jump starter suppliers. Local assembly partnerships with BIS-certified battery packers in Maharashtra and Gujarat circumvent import duty structures while satisfying fleet procurement localization preferences. Target automotive service providers with Bluetooth diagnostic logging as the entry wedge against established unbranded competitors.
For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors manufacturers with captive cell supply and extended warranty underwriting capabilities. Acquisition targets should demonstrate firmware talent depth with IEC 62619 and UN 38.3 testing experience. Monitor lithium carbonate contract pricing as the inflection signal for margin compression severity across the standard tier.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Certification Investment | Shenzhen manufacturers reduce export documentation friction through SAMR-aligned testing protocols. |
| Vehicle-to-Load Product Development | Bidirectional power electronics from EV infrastructure migrate into camping and emergency preparedness segments. |
| India Local Assembly Partnership | BIS-certified battery packers in Maharashtra circumvent import duties for Orix Auto Infrastructure supply. |
| Fleet Direct Sales Team Expansion | NOCO and CARKU capture multi-year total cost of ownership contracts from Class 8 trucking operators. |
| REACH-Attested Supply Chain Documentation | European distributors require material provenance attestation before listing private-label lithium products. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, automotive service provider procurement managers, Shenzhen manufacturing executives, and lithium cell sourcing specialists. Secondary validation incorporated UN 38.3 transport documentation databases, SAMR GB standard certification registries, NHTSA highway equipment safety filings, and EU REACH substance restriction updates. Bottom-up segment sizing triangulated against top-down market value estimates across chemistry, technology, and end-user dimensions.
Calibration against historical lithium-ion adoption curves in adjacent portable power categories anchored growth rate assumptions across the projection horizon. Segmentation modeling spanned battery chemistry, product form factor, smart versus traditional jumper technology, and fleet versus consumer procurement authority. CAGRs derived from unit shipment trajectories weighted by average selling price evolution through the chemistry transition. Forecast inputs incorporated diesel cold-start reliability mandate adoption timelines and EU F-Gas Directive phase-down schedules for compressor-integrated designs.
Practitioners should monitor lithium carbonate spot pricing and GB standard documentation processing times for early signals of margin compression or export timeline extension. Cross-checking against IEA critical minerals supply benchmarks and SAMR certification processing statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Pressure Sensors Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market