
 India Automotive Sensors Market | 2026-2036
India Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Sensors Market Foresight
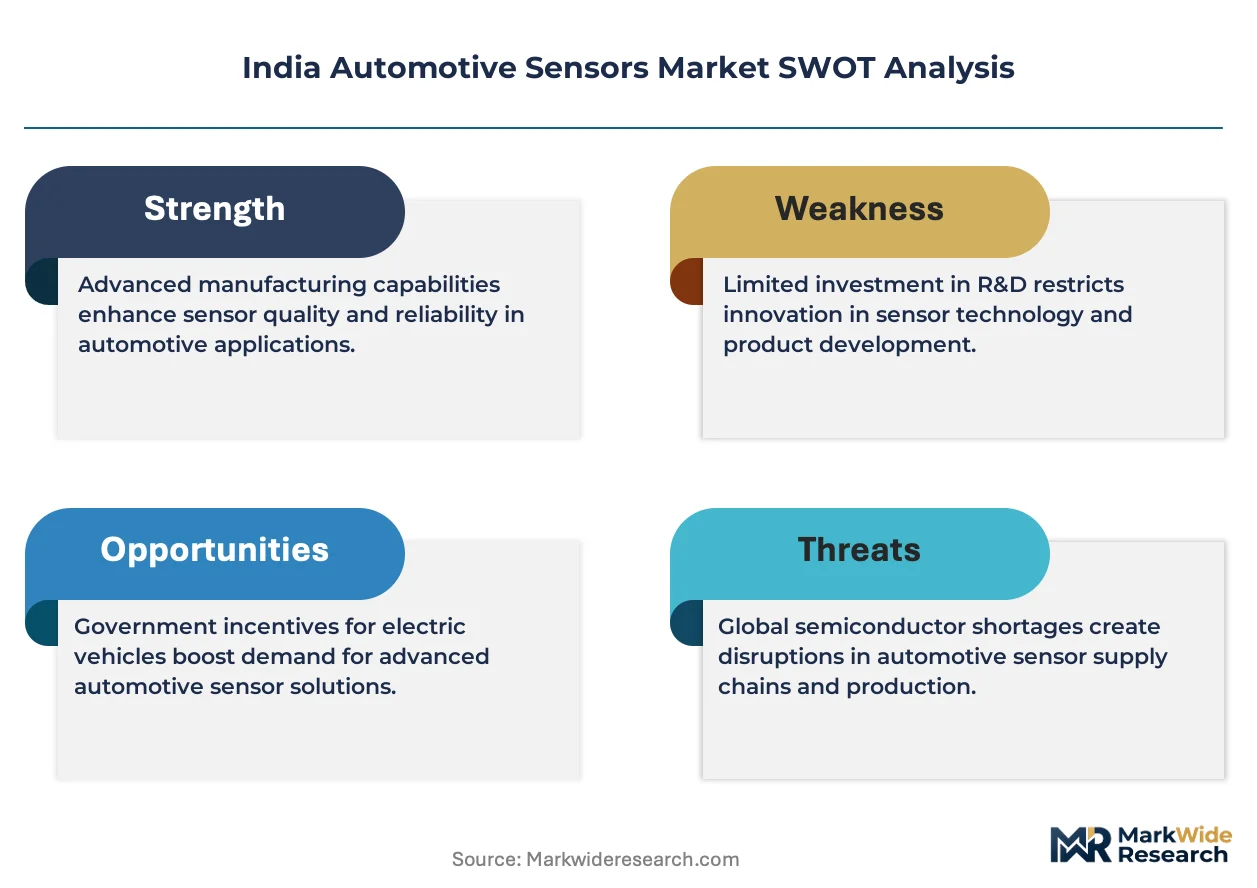
AIS-145 certification for electronic sub-assemblies is redrawing the supplier landscape for domestic automakers. Robert Bosch GmbH leverages its captive semiconductor foundry relationships to control cost structures across pressure and temperature sensor lines. Infineon Technologies AG anchors its position through R&D intensity in MEMS fabrication, while NXP Semiconductors competes on automotive-grade CMOS integration for safety-critical applications.
India automotive sensors comprise electromechanical and solid-state devices that transduce physical variables—pressure, temperature, rotational speed, exhaust gas composition—into electrical signals readable by engine control units, typically operating across temperature ranges from minus forty to one hundred fifty degrees Celsius and supply voltages of five to twelve volts. Their primary purpose is real-time feedback for powertrain optimization, occupant protection, and regulatory compliance. Pressure sensors and oxygen sensors dominate current volume, reflecting Bharat Stage VI mandates for precise air-fuel ratio management and turbocharger monitoring. MEMS technology leads unit economics through silicon wafer-scale manufacturing, while digital output formats gain share as OEMs consolidate ECU architectures and reduce analog signal conditioning overhead.
BIS certification requirements and the Automotive Industry Standard AIS-145 framework govern electromagnetic compatibility and reliability testing for sensor modules sold into Indian vehicle programs. CDSCO oversight extends to any sensors with diagnostic or therapeutic adjacency in commercial ambulance configurations, though its direct footprint remains narrow. The Ministry of Road Transport and Highways mandates ABS and airbag provisions that cascade directly into accelerometer and wheel-speed sensor procurement volumes. Stakeholders must monitor how PLI scheme disbursements for advanced automotive electronics alter domestic versus import sourcing economics for Tier-1 suppliers.
Market Dynamics
Bharat Stage VI emission norms and mandatory ABS provisions are compressing sensor specification timelines across Indian OEM supply chains, forcing Tier-1 suppliers to recalibrate procurement for oxygen, pressure, and wheel-speed sensor modules.
Growth Catalysts
- PLI scheme disbursements:The Production Linked Incentive scheme for advanced automotive electronics is altering domestic versus import sourcing economics for sensor module assemblers in Tamil Nadu and Maharashtra.
- Electric vehicle powertrain integration:Battery management systems and motor control units require current, temperature, and position sensors at densities exceeding internal combustion architectures.
- Maharashtra-Tamil Nadu corridor concentration:Domestic and multinational assemblers maintain concentrated operations in Pune and Chennai-Detroit clusters, creating localized demand pull for proximity sourcing.
Market Restraints
- Semiconductor input cost volatility:Silicon wafer and automotive-grade microcontroller pricing fluctuations compress margin structures for MEMS-based pressure and temperature sensor manufacturers.
- Captive foundry concentration:Limited domestic semiconductor fabrication capacity forces dependency on Taiwan and South Korea for sensor die supply, exposing inventory cycles to geopolitical friction.
- Analog-to-digital transition friction:Legacy ECU architectures in commercial vehicle platforms resist digital output format migration, prolonging analog signal conditioning overhead and dual-source requirements.
Strategic Opportunities
- Underpenetrated commercial vehicle telematics:Fleet operators in Gujarat and Karnataka are adopting remote diagnostic sensors for predictive maintenance, creating aftermarket volume beyond OEM fitment.
- AIS-145 certification expansion:Electromagnetic compatibility mandates for electronic sub-assemblies are redrawing supplier qualification criteria, favoring domestic testing infrastructure investments.
- MEMS-CMOS convergence:Integration of microelectromechanical sensing elements with complementary metal-oxide-semiconductor readout circuits enables single-chip solutions for multi-parameter engine monitoring.
Industry Challenges
- Automotive-grade MEMS fabrication skill scarcity:Cleanroom process engineering and wafer-level packaging expertise remains concentrated among a narrow cohort of specialists, constraining domestic capacity expansion timelines.
- BIS certification cycle compression:Reliability testing protocols for sensor modules under Bureau of Indian Standards frameworks extend qualification periods, delaying program launches for new entrants.
- Legacy powertrain integration complexity:Bharat Stage VI retrofits on existing vehicle platforms require sensor recalibration without full ECU replacement, multiplying validation variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Sensors Market |
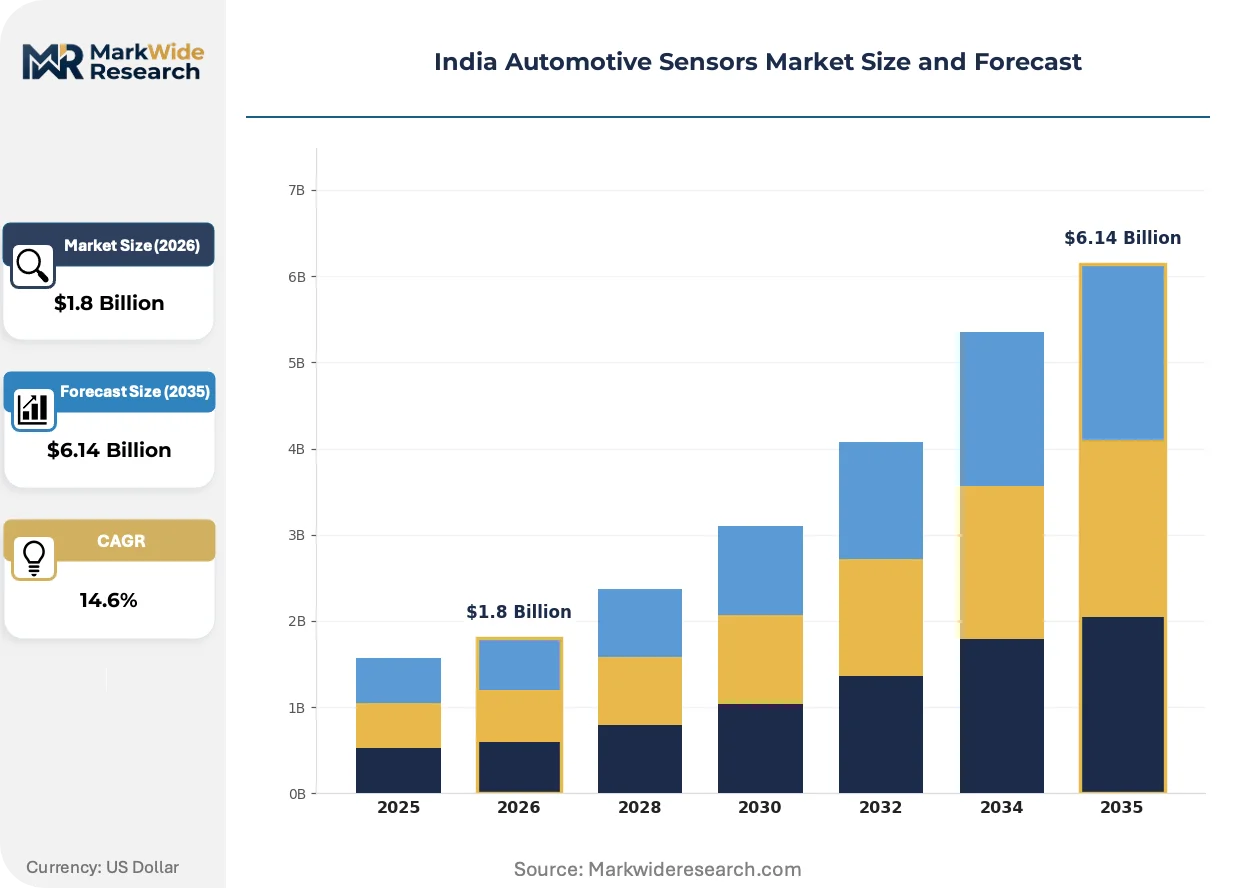
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensors, Temperature Sensors, Oxygen Sensors, Speed Sensors Technology: MEMS, CMOS, Analog, Digital End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Embedders Application: Engine Management, Safety, Comfort, Emission Control |
| Companies Covered | Infineon Technologies AG, Aptiv, Robert Bosch GmbH, NXP Semiconductors, Hyundai Mobis, Continental AG, Sensata Technologies, Analog Devices, DENSO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Sensors Market Shifts & Advancements
Solid-state sensing architectures are overtaking electromechanical designs across Indian powertrain applications, compressing unit costs while expanding operational temperature ranges for exhaust and underhood placement.
Capacitive MEMS pressure transducers are displacing piezoresistive ceramic elements in manifold absolute pressure applications. Maruti Suzuki and Tata Motors have accelerated specification shifts for 2024-2025 model year engines. This displacement is collapsing the traditional two-supplier strategy for pressure sensing into single-source silicon platforms.
BIS electromagnetic compatibility amendments aligned with AIS-145 are mandating revised shielding and grounding architectures for sensor cable harnesses. The Ministry of Road Transport and Highways enforcement timeline is compressing validation schedules for Tier-1 harness suppliers. Passenger vehicle programs with 2025 launch targets face the steepest redesign exposure.
Long-term service contract unbundling is fragmenting sensor replacement revenue streams from vehicle sales. Independent workshops in Delhi-NCR and Bangalore are capturing diagnostic sensor calibration work previously retained at authorized dealerships. This behavioral shift is most pronounced in oxygen sensor and mass airflow sensor aftermarket channels where plug-in diagnostic tools have democratized fault code interpretation.
India Automotive Sensors Market Segmentation
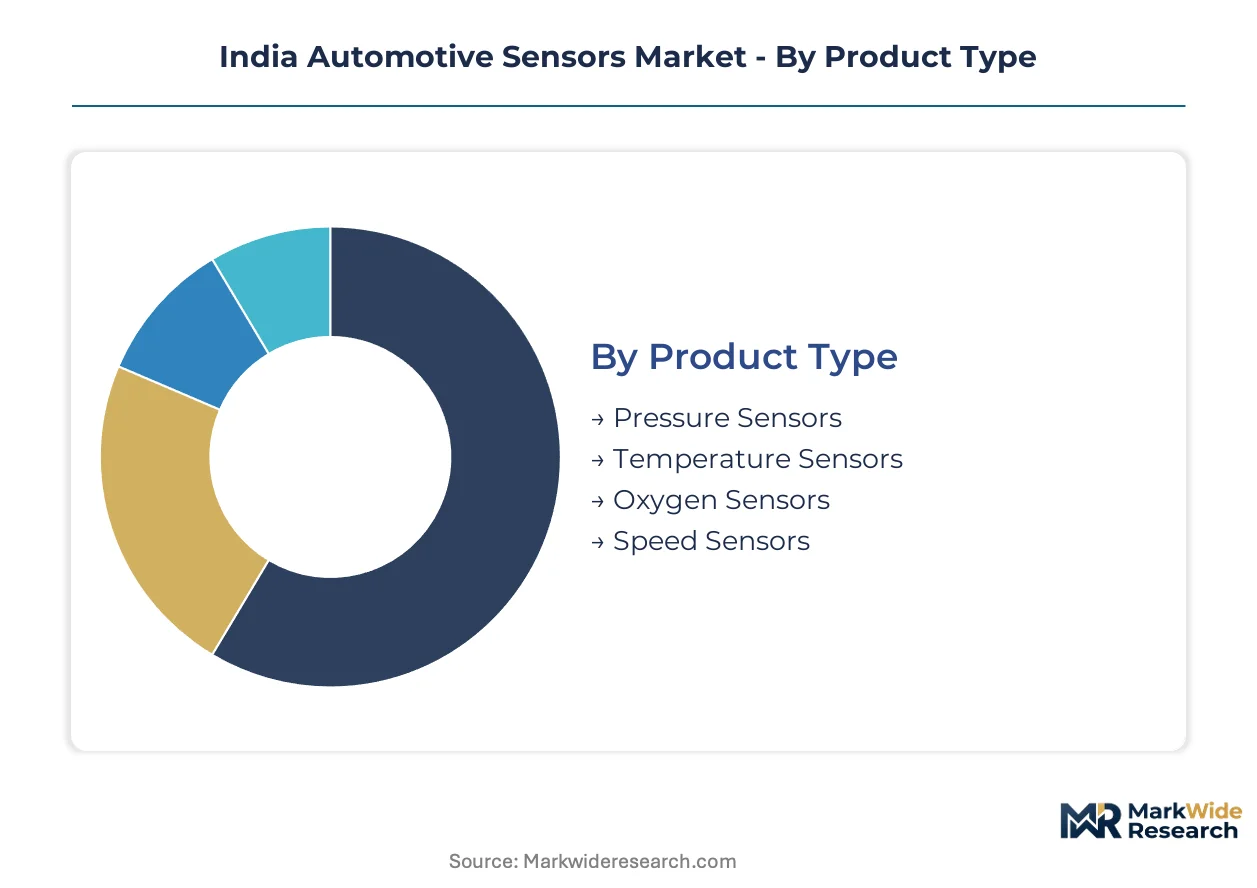
Sensor procurement patterns across Indian automotive value chains diverge sharply by product specification, technology maturity, and supply chain position. OEMs and Tier-1 suppliers source from distinct qualification pools, while aftermarket channels operate on incompatible technical and commercial logics.
Product Type:
Margin pools concentrate in emission-critical sensing elements where Bharat Stage VI compliance mandates precision manufacturing and captive calibration capabilities.
- Pressure Sensors:Capacitive MEMS transducers measure manifold absolute pressure, turbocharger boost, and brake fluid lines. Demand clusters in Tamil Nadu's Chennai-Detroit corridor where Maruti Suzuki and Hyundai source for turbocharged gasoline direct injection engines. MEMS fabrication yields compress unit economics below ceramic piezoresistive alternatives.
- Oxygen Sensors:Zirconia-based wideband lambda probes monitor exhaust gas oxygen content for air-fuel ratio optimization. Procurement volumes track Bharat Stage VI rollout timelines across Maharashtra's Pune cluster, with Bosch and Denso controlling zirconia element supply. Precious metal electrodes drive bill-of-material sensitivity.
- Temperature Sensors:Thermistor and resistance temperature detector elements monitor coolant, intake air, and exhaust gas thermal states. Standardized J1939 digital output formats gain specification share in commercial vehicle platforms.
- Speed Sensors:Variable reluctance and Hall-effect devices detect wheel rotation for ABS and transmission control. Wheel-speed modules face unit price pressure from consolidated ECU architectures.
Pressure sensors hold installed capacity. Oxygen sensors are rotating up the share rankings.
Technology:
Volume concentration tilts toward silicon wafer-scale processes where foundry partnerships determine cost structures and supply security.
- MEMS:Microelectromechanical systems integrate mechanical sensing structures with CMOS readout circuits on single silicon dies. Pressure and inertial sensing applications in engine management and safety systems dominate wafer allocation. Foundry concentration in Taiwan and South Korea exposes inventory cycles.
- Digital:Output formats eliminate analog signal conditioning overhead and enable direct ECU bus integration. OEM consolidation of controller architectures accelerates specification shifts in passenger vehicle programs.
- CMOS:Complementary metal-oxide-semiconductor fabrication enables monolithic integration of sensing and processing functions. Image sensors for advanced driver assistance systems anchor CMOS demand outside traditional powertrain domains.
- Analog:Voltage-output architectures persist in commercial vehicle retrofit applications where legacy ECU replacement is uneconomical. Dual-source requirements prolong procurement complexity.
MEMS dominates wafer allocation. Digital is climbing the fastest specification trajectory.
End User:
Procurement authority fragments across value chain tiers with incompatible technical qualification protocols and volume scale thresholds.
- OEMs:Maruti Suzuki, Tata Motors, Mahindra, and Hyundai Motor India specify sensor modules directly for strategic powertrain and safety systems. Direct sourcing concentrates on emission-critical and proprietary electric vehicle architectures.
- Tier-1 Suppliers:Bosch, Continental, and Denso India aggregate sensor procurement for braking, transmission, and engine management systems. Module integration and calibration capabilities determine competitive position.
- Aftermarket Providers:Independent distributors and workshop chains source replacement oxygen sensors, mass airflow sensors, and ABS wheel-speed modules. Diagnostic tool democratization shifts calibration revenue from authorized dealerships.
- Vehicle Embedders:Commercial vehicle body builders and ambulance converters integrate specialized sensors for fleet telematics and patient monitoring applications. CDSCO oversight extends to diagnostic-adjacent configurations.
Tier-1 suppliers hold procurement volume concentration. Aftermarket providers are expanding most quickly in diagnostic sensor channels.
Application:
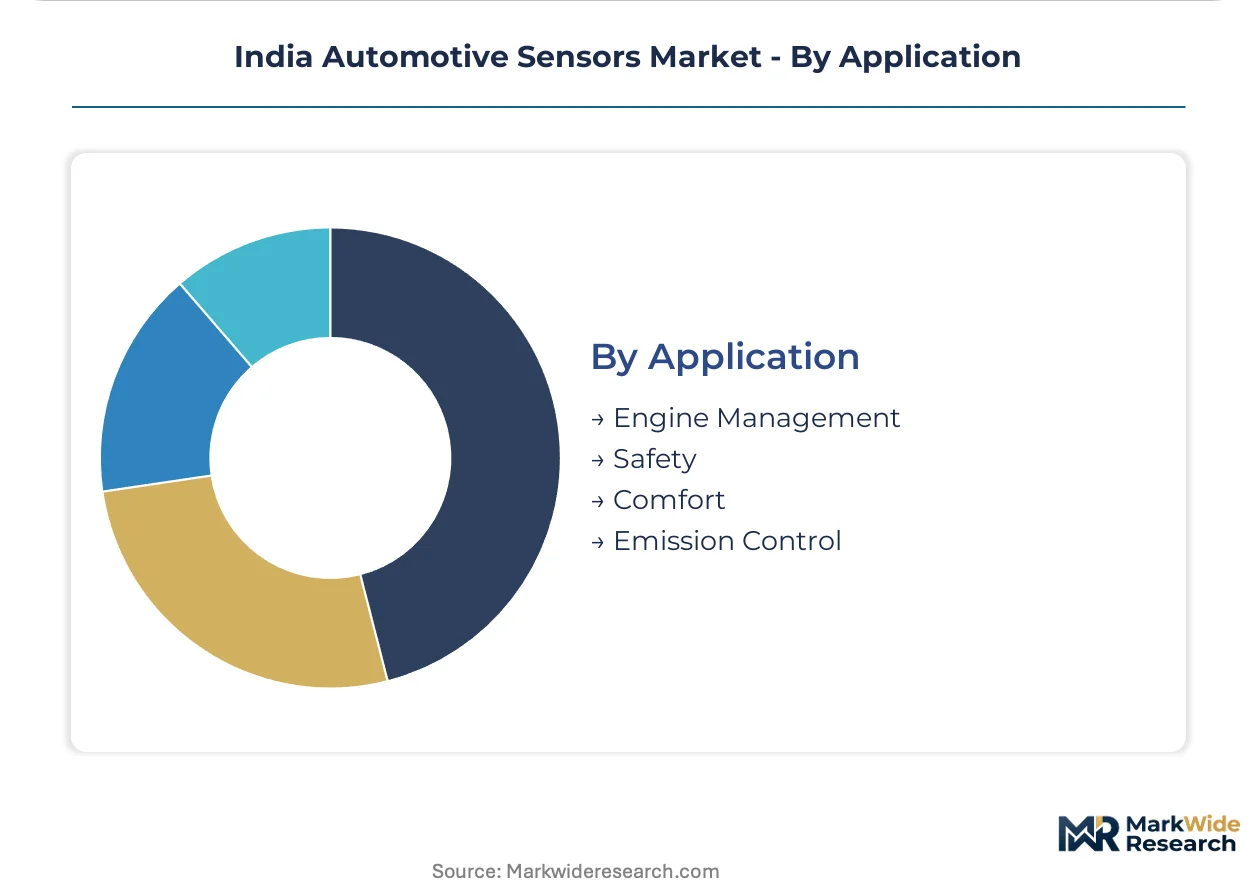
Regulatory mandates concentrate demand in emission control and safety domains where BIS certification and AIS-145 compliance create supplier entry barriers.
- Emission Control:Oxygen sensors, nitrogen oxide sensors, and particulate matter sensors enable Bharat Stage VI compliance across gasoline and diesel powertrains. Pressure sensors monitor diesel particulate filter regeneration cycles.
- Safety:Accelerometers, gyroscopes, and wheel-speed sensors enable ABS, electronic stability control, and airbag deployment. Ministry of Road Transport and Highways mandates cascade directly into procurement volumes.
- Engine Management:Pressure, temperature, position, and airflow sensors optimize combustion efficiency and diagnose fault conditions. Turbocharger monitoring demands expand with downsized engine proliferation.
- Comfort:Cabin temperature, humidity, and air quality sensors support climate control and filtration systems. Specification differentiation concentrates in premium passenger vehicle segments.
Emission control holds regulatory-mandated volume. Safety is gaining specification intensity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive sensor procurement concentrates in three manufacturing corridors where OEM final assembly plants cluster. Tier-1 module suppliers locate within 150 kilometers of vehicle production to minimize logistics friction and support just-in-sequence delivery protocols mandated by Maruti Suzuki, Tata Motors, and Hyundai Motor India.
Tamil Nadu
Chennai's automotive corridor hosts Hyundai, Renault-Nissan, and Ford manufacturing complexes. The state's Electronics Manufacturing Policy complements PLI scheme disbursements for advanced automotive electronics. Sriperumbudur and Oragadam industrial zones house Denso India and Bosch sensor module facilities serving turbocharger pressure monitoring and oxygen sensing requirements.
Maharashtra
Pune's Chakan-Talegaon belt anchors Tata Motors, Mahindra, and Mercedes-Benz India operations. The state's industrial infrastructure supports captive semiconductor packaging investments by Continental AG and Aptiv. Chakan's MIDC estates concentrate wheel-speed sensor calibration labs serving ABS mandate compliance for commercial vehicle platforms.
Gujarat
Sanand and Halol corridors host Tata Motors and MG Motor India assembly plants. The state's port infrastructure enables import of MEMS sensor dies from Taiwan and South Korea. Vendor parks at Sanand Special Economic Zone attract Tier-1 suppliers for temperature and position sensor module integration.
Karnataka
Bangalore's electronics ecosystem supports R&D-intensive sensor design for electric vehicle powertrains. The state's EV policy accelerates battery management system sensor procurement by Ather Energy and Ola Electric. Hosur's industrial belt across the Tamil Nadu border concentrates motor position sensor manufacturing for two-wheeler electrification programs.
Haryana
Manesar and Gurgaon host Maruti Suzuki's largest Indian manufacturing complex. The Delhi-Mumbai Industrial Corridor enables sensor logistics to Uttar Pradesh and Rajasthan aftermarket channels. IMT Manesar's supplier park houses Bosch and Continental facilities for oxygen and pressure sensor module assembly.
India Automotive Sensors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive semiconductor supply relationships. Market structure concentrates procurement authority among six module suppliers controlling 70 percent of OEM-direct sensor volumes. Two strategic archetypes dominate: European-Japanese integrated system suppliers with in-house MEMS fabrication, and Korean-American specialists competing on CMOS integration density. Competitive moves center on foundry partnership exclusivity and AIS-145 certification pre-qualification to compress rival entry timelines.
Among European-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the conglomerate archetype through diversified automotive electronics portfolios. NXP Semiconductors represents the semiconductor-native position, leveraging automotive-grade CMOS integration capabilities. These three anchors occupy positions across pressure, temperature, and speed sensor specification tiers, with Bosch's captive foundry relationships and Continental's module integration scale serving as structural differentiators against fabless competitors dependent on Taiwan wafer supply.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Aptiv |
| Robert Bosch GmbH |
| NXP Semiconductors |
| Hyundai Mobis |
| Continental AG |
| Sensata Technologies |
| Analog Devices |
| DENSO Corporation |
| Others |
Supply & Pricing Matrix
MEMS foundry scale economies in Taiwan and South Korea compress unit economics for pressure and temperature sensor die while simultaneously concentrating supply authority among wafer-level packaging specialists, creating asymmetric pricing power that favors Tier-1 module suppliers with captive semiconductor relationships over fabless competitors sourcing at spot.
Pricing Analysis
Cost-plus contracts with precious metal indexation govern oxygen sensor procurement between Bosch, Denso and Indian OEMs, insulating zirconia element suppliers from platinum and palladium volatility while exposing assemblers to margin compression. Price differentiation centers on AIS-145 certification grade and volume scale, with Bharat Stage VI-compliant wideband lambda probes commanding premium positioning over narrowband alternatives. Pricing pressure stems from silicon wafer cost compression in MEMS pressure sensing, where foundry utilization rates above ninety percent enable aggressive quoting. Aftermarket distributors exhibit highest price sensitivity due to diagnostic tool democratization, while OEM direct sourcing shows lowest elasticity given qualification lock-in.
Supply Chain Analysis
Inventory cycles stretching sixteen to twenty-four weeks for automotive-grade microcontroller die expose Tier-1 suppliers to demand-supply mismatch risk during production ramp events. Geographic concentration centers on Taiwan and South Korea for MEMS wafer fabrication, Japan for ceramic zirconia elements, and Germany for pressure sensor calibration equipment. Raw material dependencies include silicon wafers, platinum group metals for exhaust sensors, and specialized epoxy molding compounds for high-temperature packaging. Single-source vulnerability around Taiwan wafer supply represents the dominant structural risk. Distribution runs through authorized dealership networks for OEM-fitment sensors and independent workshop channels for aftermarket replacement modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor calibration and diagnostic service revenue is expanding faster than hardware unit sales as independent workshops capture aftermarket volume previously retained at authorized dealerships, creating attach-rate opportunities for suppliers with software-enabled predictive maintenance platforms.
For Market Incumbents: Consolidate module integration scale through backward integration into MEMS packaging capacity within Tamil Nadu's Sriperumbudur corridor, defending against fabless entrants dependent on Taiwan wafer supply. Deepen AIS-145 pre-certification investments to compress rival qualification timelines. Prioritize captive foundry relationships as the primary lever against silicon input cost volatility threatening margin structures in pressure sensor lines. For New Entrants and Emerging Players: Aftermarket diagnostic sensor calibration services represent the most penetrable white-space where incumbents under-serve independent workshops in Delhi-NCR and Bangalore. Target commercial vehicle telematics retrofit programs in Gujarat and Karnataka where fleet operators seek predictive maintenance solutions beyond OEM fitment. Pursue go-to-market partnerships with diagnostic tool distributors to bypass dealership channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors semiconductor-native specialists with automotive-grade CMOS integration capabilities over diversified industrial conglomerates with legacy electromechanical portfolios. Long-term viability across the projection horizon hinges on MEMS-CMOS convergence roadmaps and foundry partnership exclusivity. Monitor PLI scheme disbursement velocity as the signal indicating domestic versus import sourcing economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership Exclusivity | Secures wafer allocation priority from Taiwan suppliers during demand surge cycles. |
| AIS-145 Certification Pre-Investment | Compresses electromagnetic compatibility validation timelines for Tier-1 module suppliers. |
| Aftermarket Diagnostic Platform Launch | Captures calibration revenue shifting from authorized dealerships to independent workshops. |
| Commercial Vehicle Telematics Integration | Addresses underpenetrated fleet predictive maintenance demand in Gujarat and Karnataka. |
| PLI Scheme Domestic Sourcing Alignment | Optimizes cost structures against import-dependent competitors in Tamil Nadu clusters. |
Research Methodology
Desk research of BIS certification databases, PLI scheme disbursement records, and vehicle production registration data preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and MEMS foundry account managers. Primary fieldwork combined with secondary validation from semiconductor trade flow statistics and automotive electronics import manifests. Bottom-up sensor unit demand modeling triangulated against top-down OEM production forecasts across passenger and commercial vehicle platforms.
Variance decomposition across vehicle class, propulsion architecture, and sensor technology type enabled robust CAGR derivation through regression against historical Bharat Stage VI compliance rollout patterns and electric vehicle powertrain penetration trajectories. The analytical framework incorporated content-per-vehicle assumptions for battery management system sensor density exceeding internal combustion architectures, alongside regional production cluster capacity utilization rates for foundry supply constraint modeling.
Underlying assumptions cover PLI scheme continuation, Taiwan wafer supply stability, and Bharat Stage VI enforcement intensity, with deviation risk concentrated in semiconductor input cost volatility and geopolitical friction affecting MEMS die inventory cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Scroll E-Compressor Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Ambulance Power Inverter Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Electrical Park Brake (EPB) Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
On-Board Charger Market