
 Automotive Thermoelectric Generator Market | 2026-2036
Automotive Thermoelectric Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Thermoelectric Generator Market Analysis
German automotive supplier clusters is recalibrating production footprints to serve thermoelectric module demand from European OEM electrification programs. Valeo leverages its thermal management integration expertise to bundle generator systems with existing HVAC architectures. Gentherm Incorporated anchors North American supply through its seat comfort and thermal technology divisions.
An automotive thermoelectric generator converts exhaust waste heat into electrical energy through the Seebeck effect, typically employing bismuth telluride or skutterudite compounds arranged in p-type and n-type junctions to produce continuous DC output for auxiliary loads and battery charging. Waste heat recovery applications dominate current deployment, while vehicle electrification segments show the fastest structural expansion as 48-volt mild-hybrid architectures proliferate. Bi-metallic technology occupies the mature cost-optimized tier, whereas integrated multi-layer designs command premium positioning for next-generation platforms.
The EPA tailpipe emission rules and EU F-Gas Regulation shape product standards by mandating thermal efficiency gains that thermoelectric systems help satisfy. Japan's METI energy efficiency directives and NHTSA fuel economy enforcement in the United States create parallel compliance pull across three major automotive markets. Stakeholders must monitor how battery-electric platform adoption rates alter the addressable waste heat pool and reposition R&D portfolios accordingly.
Market Dynamics
The 48-volt mild-hybrid architecture proliferation is compressing thermoelectric generator integration timelines as passenger vehicle OEMs race to capture exhaust waste heat for auxiliary electrical loads before battery-electric platforms erode the addressable thermal pool.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:US automakers face tightening fleet efficiency mandates that thermoelectric waste heat recovery directly addresses. The regulation creates compliance pull across Detroit engineering centers.
- Skutterudite compound advances:Next-generation thermoelectric materials are raising conversion efficiency above bismuth telluride baselines. Module suppliers in Japan's automotive corridor are scaling pilot production lines.
- German automotive engineering concentration:Stuttgart-to-Munich supplier clusters enable rapid prototyping cycles for integrated thermal management systems. Proximity to BMW and Mercedes-Benz electrification programs accelerates validation timelines.
Market Restraints
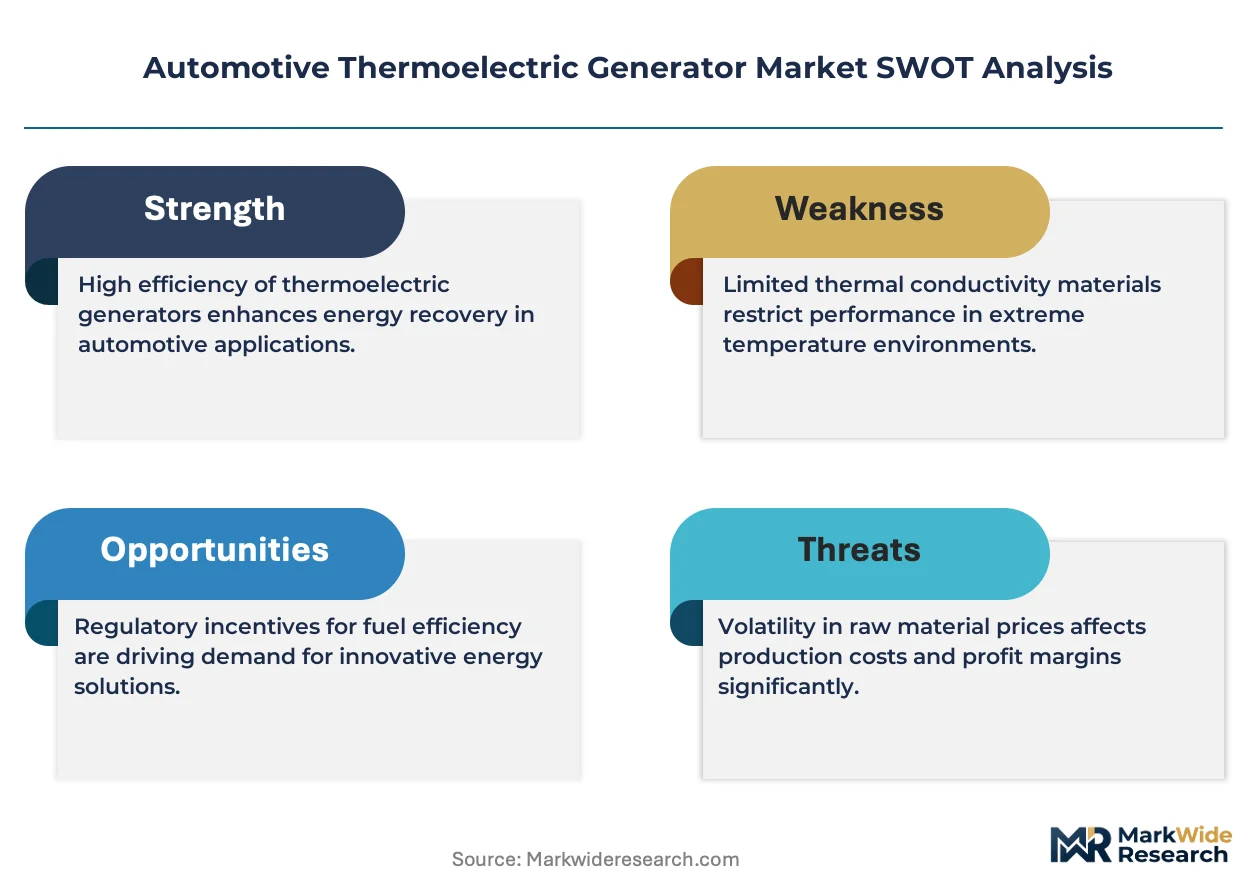
- Tellurium supply concentration:Bismuth telluride feedstock depends on copper refining byproduct streams concentrated in Chinese smelter operations. Price volatility in minor metal markets compresses module margins.
- EU F-Gas Regulation compliance costs:Thermal system integration requirements add certification overhead for European market entry. Testing protocols for refrigerant-sealed generator-HVAC bundles extend development cycles.
- Solid-state battery substitution threat:Next-generation cell chemistries promise reduced auxiliary load demands that would shrink the economic case for exhaust heat recovery. Toyota and QuantumScape development trajectories bear monitoring.
Strategic Opportunities
- India commercial vehicle segment:Bharat Stage VI emission norms and severe thermal cycling conditions create unmet demand for robust waste heat recovery. Domestic truck OEMs lack integrated thermal partners.
- Japan METI energy efficiency directives:Subsidy frameworks for industrial heat recovery are extending to automotive applications. Toyota and Honda supplier qualification programs offer fast-track certification pathways.
- Multi-physics simulation convergence:Coupled thermal-electric-mechanical modeling is collapsing prototype iteration counts. Ansys and COMSOL platform adoption among tier-one suppliers is compressing design-to-test intervals.
Industry Challenges
- Thermoelectric materials science talent scarcity:PhD-level expertise in solid-state physics and semiconductor processing concentrates in national laboratories and elite university departments. Automotive suppliers compete with defense and aerospace for limited hiring pools.
- 48-volt electrical architecture integration complexity:Legacy 12-volt vehicle networks require substantial rewiring to accommodate generator output. OEM electrical system teams face compressed platform development timelines.
- ISO 26262 functional safety certification:Thermoelectric modules feeding safety-critical loads must demonstrate fail-operational behavior. Validation testing for automotive safety integrity levels extends qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Thermoelectric Generator Market |
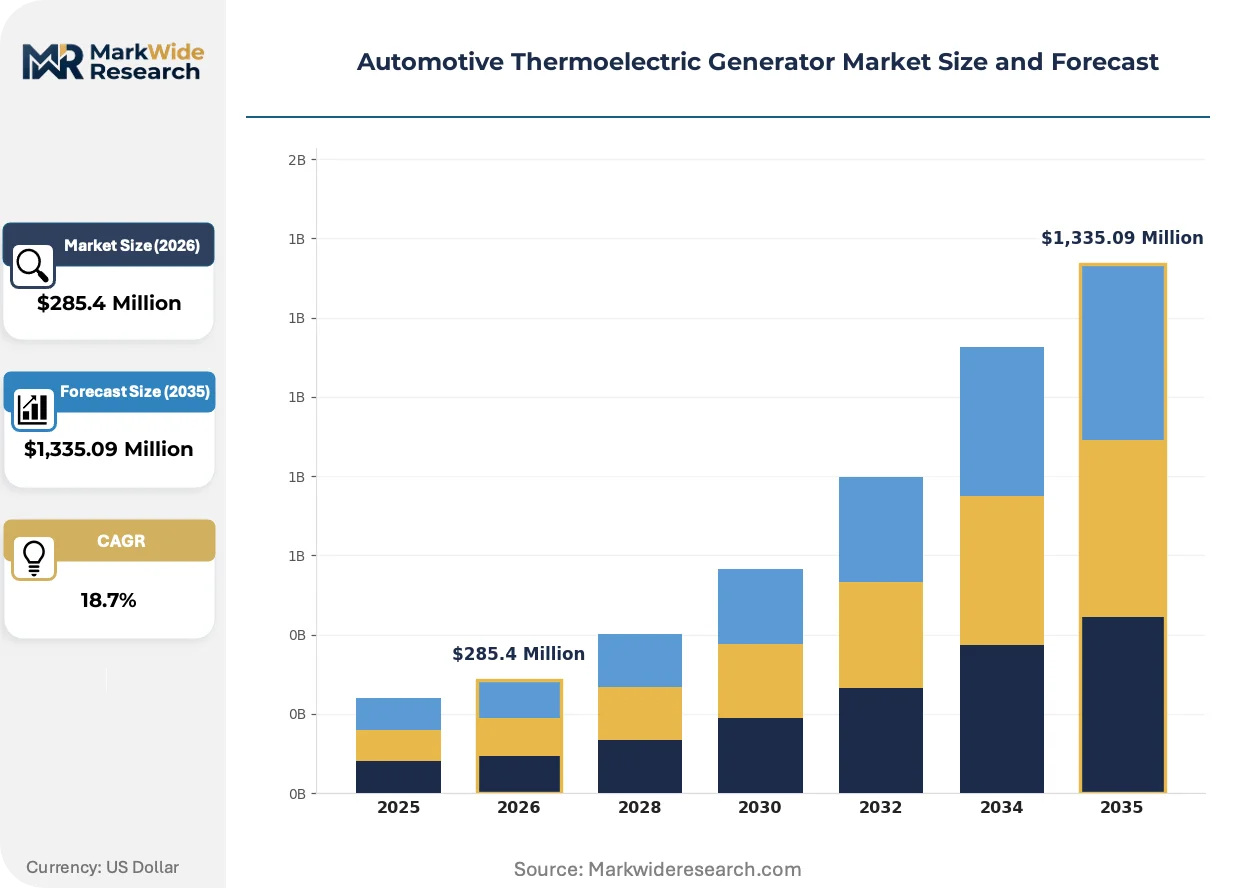
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive, Active, Hybrid, Advanced End User: OEMs, Aftermarket Providers, Fleet Operators, Dealers Application: Waste Heat Recovery, Vehicle Electrification, Power Generation, Cooling Systems Technology: Bi-Metallic, Single Material, Multi-Layer, Integrated |
| Companies Covered | Valeo, KELK Ltd., Gentherm Incorporated, Tenneco, Laird Thermal Systems, European Thermodynamics, II-VI Marlow, Yamaha Corporation, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Thermoelectric Generator Market Emerging Trajectories
Active thermal management integration is redefining competitive positioning as waste heat recovery systems migrate from standalone components to embedded subsystems within broader vehicle energy architectures.
Segmented thermoelectric generator architectures are automating the transition from uniform-temperature designs to spatially graded configurations that match exhaust stream thermal profiles. BMW and Volkswagen engineering teams are validating multi-zone modules for 2027 platform introductions. This topology optimization is automating the compression of generator footprint requirements while maintaining power output density.
The EU F-Gas Regulation is mandating refrigerant phase-down schedules that force HVAC-thermal system suppliers to redesign integration architectures. Thermoelectric generators bundled with climate control systems must now demonstrate compatibility with low-global-warming-potential working fluids. German tier-one suppliers are responding with sealed-generator prototypes that eliminate refrigerant permeation pathways.
Fleet procurement departments are consolidating thermal system sourcing decisions under centralized sustainability officers who evaluate lifecycle carbon impact alongside unit economics. Traditional component-by-component purchasing is yielding to bundled energy-management contracts. This concentration of buying authority is most visible in California and Germany where corporate fleet electrification mandates accelerate vendor consolidation.
Automotive Thermoelectric Generator Market Segmentation
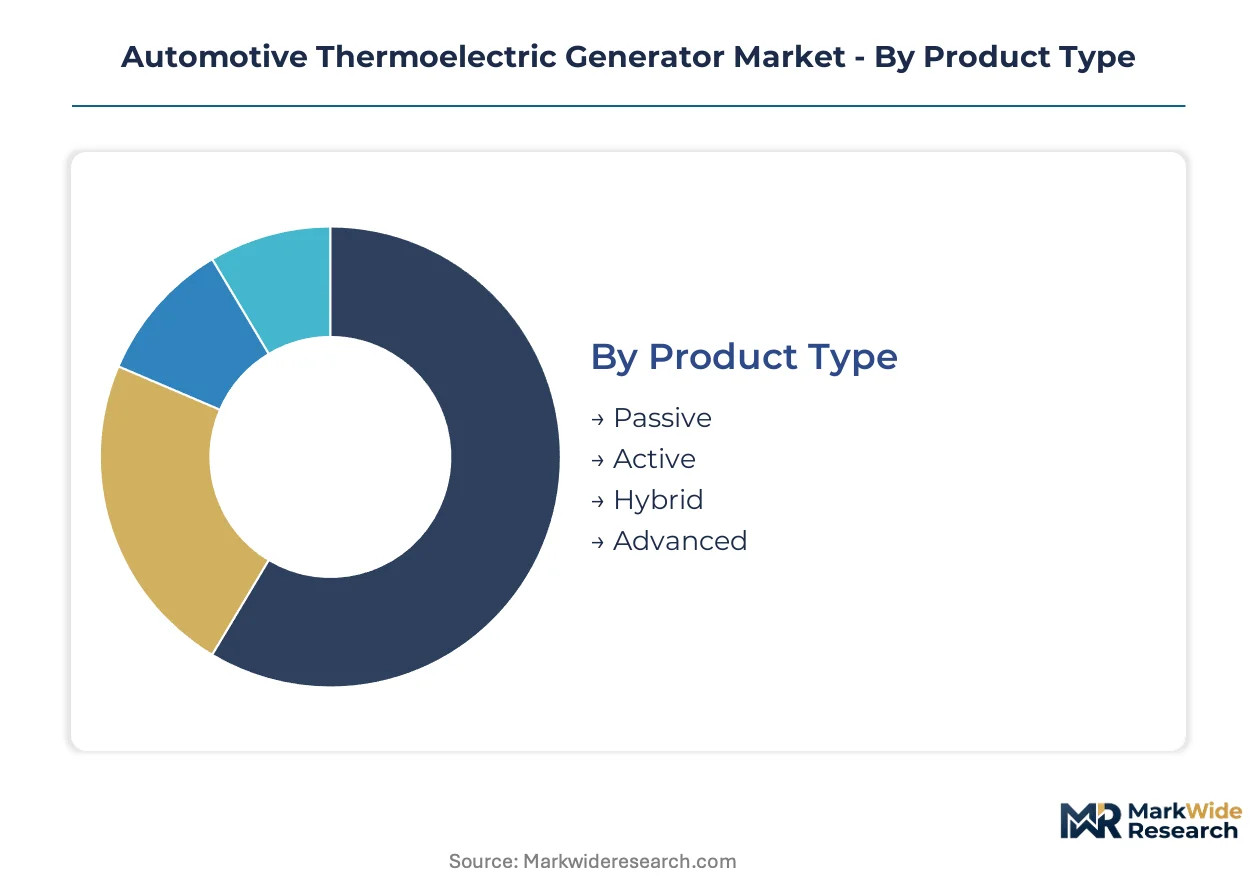
Thermoelectric generator architectures vary dramatically in thermal integration depth, electrical output management, and cost structure. Segmentation reveals which configurations align with 48-volt mild-hybrid timelines versus long-range battery-electric platforms.
Product Type:
Standardization dominates at the passive end of this spectrum, while active and hybrid systems demand bespoke thermal-electrical calibration for each vehicle platform.
- Passive:Fixed-geometry modules without active thermal switching rely on static Seebeck junction arrangements. BMW and Mercedes-Benz procurement teams specify these for cost-sensitive 48-volt auxiliary loads in high-volume sedan platforms where thermal profiles remain predictable.
- Active:Microcontroller-governed thermal switching enables real-time optimization of heat flux across p-n junction arrays. Volkswagen engineering centers in Wolfsburg prioritize active architectures for next-generation SUV platforms where exhaust temperature swings exceed 200°C during drive cycles.
- Hybrid:Combines passive baseline generation with active bypass circuits for peak load shaving.
- Advanced:Incorporates phase-change materials and variable-geometry heat exchangers for extreme thermal cycling environments.
Leading the category by volume: Passive. Growing fastest: Active.
End User:
Volume concentration sits with direct OEM procurement, though fleet operator specifications are rewriting integration requirements through lifecycle cost frameworks.
- OEMs:Passenger vehicle manufacturers account for the dominant share of thermoelectric generator offtake. Stuttgart engineering corridors validate modules against BMW and Mercedes-Benz electrification roadmaps where waste heat recovery supports 48-volt belt-driven starter-generator architectures.
- Fleet Operators:Commercial vehicle procurement departments in California and Germany now mandate thermal efficiency disclosures in RFP documentation. Daimler Truck and Volvo Group fleet divisions specify generator durability guarantees exceeding 300,000 kilometers for long-haul applications.
- Aftermarket Providers:Retrofit specialists serve aging commercial vehicle populations in India and Southeast Asia.
- Dealers:Authorized service networks handle warranty replacements and platform upgrade installations.
Dominant procurement channel: OEMs. Expanding most quickly: Fleet Operators.
Application:
Application selection tracks the diminishing thermal budget across electrification pathways, with waste heat recovery yielding ground to power generation as combustion architectures contract.
- Waste Heat Recovery:Exhaust stream energy capture constitutes the mature revenue base. German tier-one suppliers bundle these systems with catalytic converter assemblies for EU F-Gas Regulation compliance.
- Vehicle Electrification:48-volt mild-hybrid architectures create new demand for generator-fed battery management systems. Toyota and Honda engineering centers in Aichi Prefecture validate thermoelectric modules for supplemental charging of lithium-ion packs during deceleration events.
- Power Generation:Standalone auxiliary power units for commercial vehicle sleeper cabs and emergency service vehicles.
- Cooling Systems:Thermoelectric refrigeration for electric vehicle battery thermal management.
Maturest installed base: Waste Heat Recovery. Steepest expansion trajectory: Vehicle Electrification.
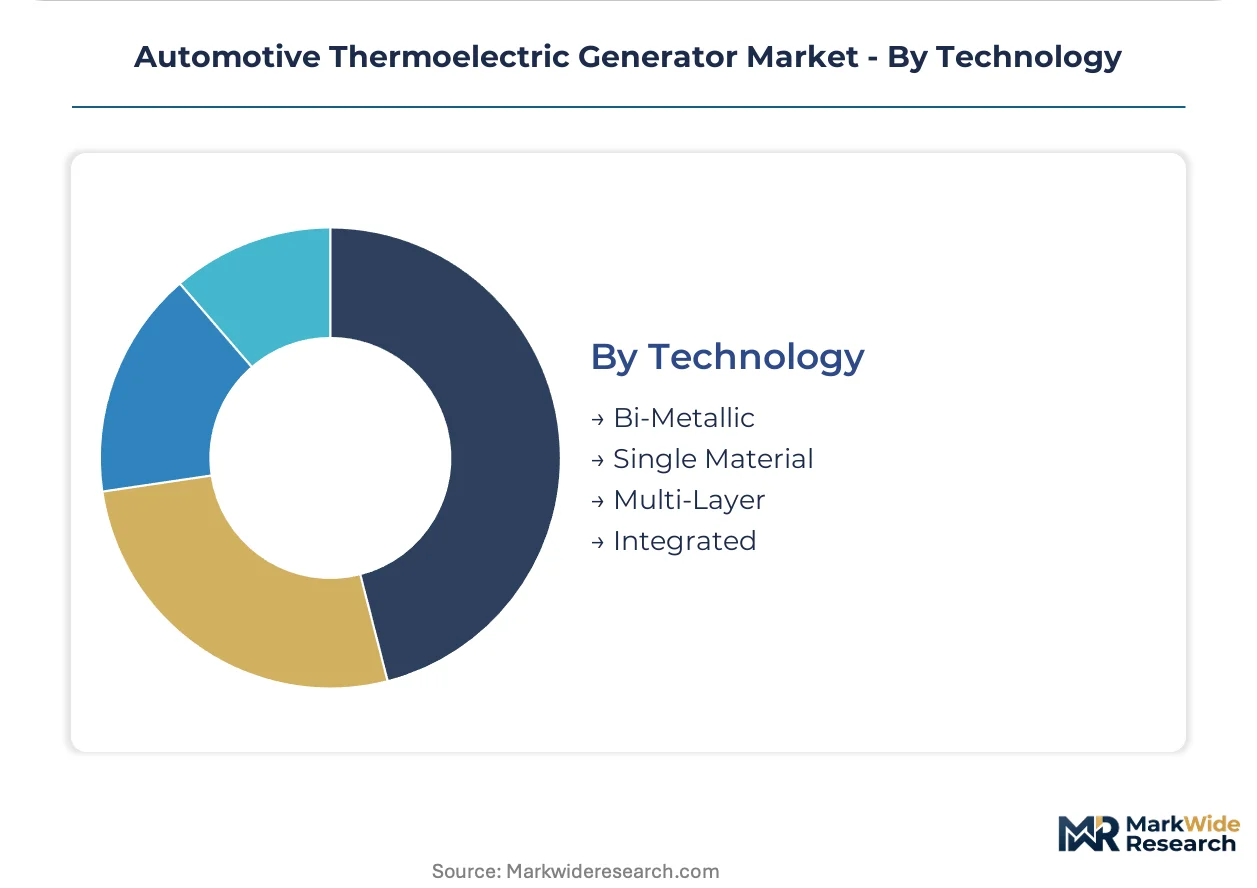
Technology:
Technology tiers separate by materials science sophistication and manufacturing complexity, with bi-metallic systems facing displacement from multi-layer architectures.
- Bi-Metallic:Bismuth telluride junctions on ceramic substrates represent the cost-optimized baseline. Chinese module assemblers dominate volume production for 12-volt legacy vehicle applications where conversion efficiency targets remain below 5%.
- Multi-Layer:Stacked p-n junction configurations with graded thermal interfaces achieve higher power density. Japanese national laboratory partnerships with automotive suppliers advance skutterudite-filled variants for next-generation platforms.
- Single Material:Homogeneous semiconductor compositions simplify manufacturing but limit temperature operating windows.
- Integrated:Monolithic generator-HVAC assemblies sealed against refrigerant permeation for EU F-Gas Regulation compliance.
Highest shipment volumes: Bi-Metallic. Gaining share fastest: Multi-Layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tellurium refining byproduct streams from Chinese copper smelters feed bismuth telluride module production, anchoring raw material flows to East Asian processing capacity. German automotive engineering corridors convert these inputs into integrated thermal management systems. Japanese national laboratory partnerships advance skutterudite alternatives.
United States
NHTSA fuel economy enforcement and EPA Corporate Average Fuel Economy standards drive Detroit engineering centers toward waste heat recovery integration. The Inflation Reduction Act extends clean vehicle tax credits that encompass thermal efficiency improvements. Michigan and Ohio supplier clusters validate thermoelectric modules against 48-volt mild-hybrid timelines.
Germany
BMW and Mercedes-Benz electrification roadmaps concentrate demand for exhaust heat recovery systems in the Stuttgart-to-Munich corridor. EU F-Gas Regulation mandates refrigerant phase-down schedules that reshape HVAC-generator integration architectures. Bavarian tier-one suppliers prototype sealed-generator designs for low-global-warming-potential compatibility.
Japan
METI energy efficiency directives extend industrial heat recovery subsidies into automotive applications, accelerating Toyota and Honda supplier qualification programs. Aichi Prefecture engineering centers validate thermoelectric modules for supplemental lithium-ion charging during deceleration events. National laboratory partnerships with automotive suppliers advance skutterudite-filled multi-layer architectures.
China
Domestic copper smelter operations concentrate tellurium byproduct supply for bismuth telluride feedstock, shaping module cost structures globally. The country's dual carbon goals push commercial vehicle OEMs toward thermal efficiency solutions. Yangtze River Delta module assemblers dominate volume production for 12-volt legacy vehicle applications.
India
Bharat Stage VI emission norms and severe thermal cycling conditions create unmet demand for robust waste heat recovery in commercial vehicles. Domestic truck OEMs lack integrated thermal partners, opening procurement opportunities. Maharashtra and Gujarat manufacturing corridors attract module suppliers seeking localization advantages.
Automotive Thermoelectric Generator Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue active thermal management integration and next-generation materials science. The supplier base stratifies across three maturity tiers: legacy thermal specialists with HVAC integration expertise, semiconductor materials laboratories transitioning toward automotive qualification, and Chinese volume assemblers serving cost-sensitive 12-volt applications. Consolidation pressures intensify as 48-volt platform timelines compress development cycles. Dominant competitive moves include strategic partnerships for refrigerant-sealed system bundling and backward integration into tellurium sourcing channels.
Within the integrated thermal management tier, Valeo and Gentherm Incorporated exemplify archetypes of HVAC-bundled generator deployment. Valeo leverages its thermal management integration expertise to bundle generator systems with existing climate control architectures. Gentherm Incorporated anchors North American supply through its seat comfort and thermal technology divisions. Japanese industrial conglomerates represented by Yamaha Corporation occupy positions bridging materials science and automotive component supply. These three entities collectively illustrate the geographic and capability segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Valeo |
| KELK Ltd. |
| Gentherm Incorporated |
| Tenneco |
| Laird Thermal Systems |
| European Thermodynamics |
| II-VI Marlow |
| Yamaha Corporation |
| Faurecia |
| Others |
Supply Flow & Price Mechanics
Bi-metallic versus multi-layer technology divergence separates cost-optimized 12-volt modules from premium 48-volt architectures, with warranty bundling and qualification overhead driving price spreads that reflect tellurium feedstock concentration and ISO 26262 certification tiers. German tier-one suppliers capture margin through sealed-generator HVAC integration, while Chinese assemblers compete on spot-market bismuth telluride sourcing for legacy vehicle retrofits.
Pricing Analysis
Warranty and service bundling separates OEM procurement contracts from aftermarket spot purchases, with multi-year durability guarantees commanding substantial premiums over unbundled module supply. Pricing stratifies across premium, standard, and economy tiers based on ISO 26262 certification grade and active thermal management capability. Cost compression in the bi-metallic segment is intensifying because Yangtze River Delta module assemblers are absorbing tellurium price volatility to maintain volume share. Fleet operators in California and Germany exhibit lowest price sensitivity due to lifecycle carbon accounting mandates, whereas Indian commercial vehicle retrofitters prioritize unit economics over performance guarantees.
Supply Chain Analysis
ISO 26262 functional safety certification gates tier-one supplier qualification, creating bottleneck conditions that favor incumbent thermal specialists with existing automotive safety integrity level validation. Raw material supply draws from Chinese copper smelter tellurium byproduct streams, Japanese skutterudite research partnerships, and German precision ceramics processing. Single-source vulnerability concentrates in bismuth telluride feedstock channels anchored to East Asian refining capacity. Distribution runs through Stuttgart-to-Munich engineering corridors for European OEM integration, Michigan-Ohio clusters for Detroit platform validation, and Aichi Prefecture supplier networks for Toyota-Honda qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive thermoelectric generator market functions as a cost-of-compliance arena where EPA Corporate Average Fuel Economy standards and EU F-Gas Regulation create regulatory moats that reward pre-qualified incumbents while raising capital barriers for unproven entrants.
For Market Incumbents: Lock in tellurium sourcing channels through backward integration or long-term offtake agreements with Chinese copper smelters to defend against raw material price volatility. Expand sealed-generator HVAC bundling capabilities to capture EU F-Gas Regulation-driven retrofit demand from European fleet operators. Solid-state battery substitution trajectories at Toyota and QuantumScape represent the primary demand destruction threat requiring R&D portfolio repositioning.
For New Entrants and Emerging Players: Launch via aftermarket retrofit distribution partnerships targeting India's Bharat Stage VI commercial vehicle segment, where domestic truck OEMs lack integrated thermal partners and severe thermal cycling conditions favor robust waste heat recovery solutions. Multi-physics simulation service offerings present a white-space entry path alongside hardware supply. Japan METI subsidy frameworks offer fast-track certification pathways for qualified suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to HVAC-thermal consolidation platforms and automotive tier-one diversification strategies. Long-term viability hinges on 48-volt mild-hybrid architecture proliferation rates relative to battery-electric platform displacement timelines. Acquisition targets should demonstrate active thermal management integration expertise and existing OEM qualification relationships. The signal to watch is BMW-Volkswagen multi-zone segmented generator validation outcomes for 2027 platform introductions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Sourcing | Captive supply of bismuth telluride feedstock insulates margins from Chinese smelter price volatility. |
| Sealed-Generator HVAC Bundling | EU F-Gas Regulation compliance positions Valeo and Gentherm for low-global-warming-potential refrigerant integration. |
| Multi-Physics Simulation Platform Adoption | Ansys and COMSOL deployment collapses prototype iteration counts for Japanese national laboratory partnerships. |
| India Commercial Vehicle Localization | Maharashtra and Gujarat manufacturing corridors address Bharat Stage VI retrofit demand from domestic truck OEMs. |
| Skutterudite Materials Science Partnerships | Japanese automotive suppliers advance conversion efficiency beyond bismuth telluride baselines through METI-funded research. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, thermal management R&D leads, and fleet sustainability officers. EPA enforcement documentation, NHTSA fuel economy compliance databases, EU F-Gas Regulation implementation reports, and METI subsidy program disclosures provided regulatory validation. Vehicle production databases and IHS Markit registration data enabled demand-side triangulation against bottom-up module shipment estimates and top-down waste heat recovery penetration assumptions.
Segment-level granularity modeled propulsion architecture splits between 48-volt mild-hybrid and battery-electric platforms, content-per-vehicle variations across passenger and commercial segments, OEM tier positioning, and regional production cluster concentrations. CAGRs derived from exponential growth curve fitting against technology adoption S-cycles, with skutterudite material readiness timelines and solid-state battery commercialization trajectories serving as scenario-weighting inputs. The analytical framework applied Monte Carlo simulation across tellurium price volatility and regulatory enforcement intensity distributions.
Battery-electric platform adoption acceleration, tellurium supply disruption events, and EPA fuel economy standard relaxation are the dominant revision risks warranting forecast reassessment. Model outputs reflect documented assumptions regarding 48-volt architecture proliferation rates and thermoelectric conversion efficiency improvement trajectories. A model refresh is warranted upon material change in Toyota-Honda electrification roadmap disclosures or QuantumScape solid-state battery production timeline confirmations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Jump Starter Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive Electric Actuator Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market