
 Automotive Power Modules Market | 2026-2036
Automotive Power Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Modules Market Analysis
Aftermarket service revenue for legacy internal-combustion powertrain components is reconfiguring toward module diagnostics, thermal interface refurbishment, and predictive replacement scheduling for electrified fleets. Infineon Technologies leverages captive silicon carbide wafer capacity to anchor premium module supply contracts with German OEMs. Mitsubishi Electric Corporation dominates high-voltage IGBT assembly for Japanese and Southeast Asian commercial vehicle platforms. Denso Corporation specializes in integrated thermal-management subsystems that embed power modules within compact cooling architectures.
Automotive power modules are packaged semiconductor assemblies—typically rated between 400V and 800V—that switch and condition electrical energy between battery packs and traction motors through controlled gate-drive interfaces. Their primary purpose is to minimize switching losses and thermal dissipation while maximizing power density within constrained vehicle chassis envelopes. SiC Modules command the fastest expansion trajectory as OEMs trade silicon substrates for wide-bandgap materials that sustain higher junction temperatures and faster switching frequencies. IGBT Modules retain volume leadership in cost-sensitive hybrid vehicle applications where established supply chains and mature packaging economics preserve incumbent positioning. MOSFET Modules occupy a narrowing mid-range niche in low-voltage auxiliary systems and light electrification architectures.
The EPA tailpipe emissions framework and the EU Green Deal carbon-neutrality pathway are tightening fleet-average CO2 mandates that compel OEMs to electrify powertrains and source higher-efficiency power conversion components. China's GB standards for new energy vehicle safety and the NMPA certification regime for automotive semiconductor reliability are raising technical barriers that favor domestic module suppliers with in-country testing infrastructure. Stakeholders must monitor how substrate material transitions, thermal packaging roadmaps, and regional content requirements redistribute manufacturing footprint and qualification timelines across competing supply bases.
Market Dynamics
The transition from silicon IGBT to silicon carbide MOSFET architectures is compressing module form factors while multiplying thermal management complexity, forcing suppliers to redesign packaging roadmaps around 800V drivetrain electrification timelines.
Growth Catalysts
- EU Green Deal carbon-neutrality pathway:Fleet-average CO2 mandates compel OEMs to electrify powertrains and source higher-efficiency power conversion components, accelerating module procurement cycles.
- Silicon carbide substrate adoption:Wide-bandgap materials sustain higher junction temperatures and faster switching frequencies, enabling traction inverters to shrink cooling system mass by 40-50%.
- China's module localization policies:Domestic EV production volumes and NMPA certification requirements favor suppliers with in-country testing infrastructure, reshaping competitive dynamics.
Market Restraints
- Silicon carbide wafer supply concentration:Captive substrate capacity remains concentrated among integrated semiconductor manufacturers, constraining independent module assemblers.
- Technical qualification barriers:Automotive AEC-Q101 and AQG-324 standards require 2,000+ hour thermal cycling validation, extending new entrant time-to-revenue.
- Copper and aluminum thermal interface cost volatility:Base metal price swings compress module gross margins during contract renegotiation windows.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced cell chemistry and power electronics attract module packaging investments to Tamil Nadu and Gujarat manufacturing corridors.
- Vehicle-to-grid bidirectional charging:Traction inverters with reversible power flow capability open stationary energy storage revenue streams for fleet operators.
- Integrated thermal-management subsystems:Convergence of power modules with compact cooling architectures enables tier-one suppliers to capture value from thermal stack integration.
Industry Challenges
- Packaging engineer scarcity:Specialized expertise in direct copper bonding and silver sintering die-attach processes commands premium compensation, constraining R&D throughput.
- Legacy 400V platform coexistence:Simultaneous engineering of 400V IGBT and 800V SiC module variants fragments validation resources across divergent thermal and electrical interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Modules Market |
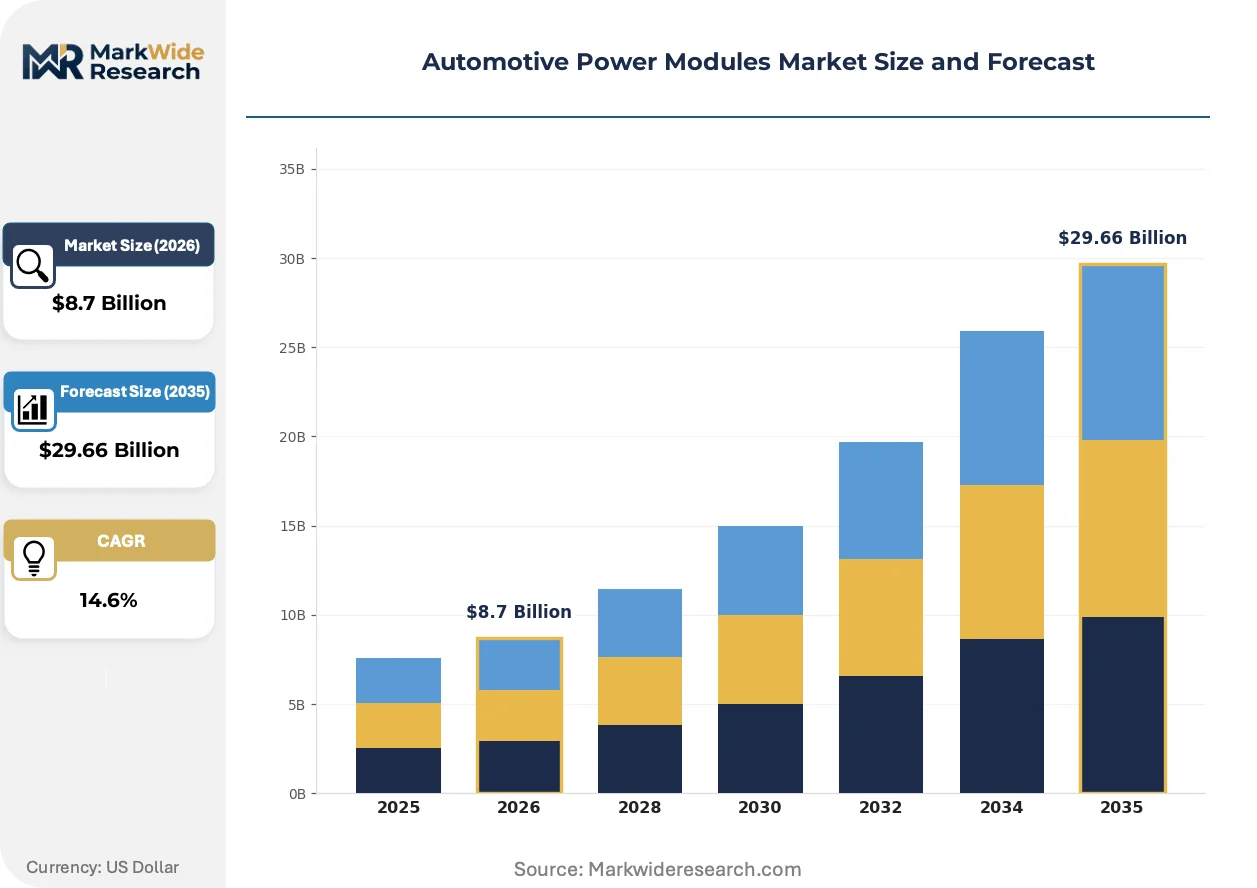
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IGBT Modules, SiC Modules, MOSFET Modules, Hybrid Modules Technology: Thermal Management, Power Density, Conversion Efficiency, Integration Technology End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Specialty Vehicle Manufacturers Application: Electric Vehicles, Hybrid Vehicles, Commercial Vehicles, Automotive Electronics |
| Companies Covered | Infineon Technologies, Continental AG, Robert Bosch GmbH, Mitsubishi Electric Corporation, Denso Corporation, STMicroelectronics, Fuji Electric, ON Semiconductor, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Modules Market Emerging Trajectories
Module architectures are converging around substrate-agnostic packaging platforms that accommodate both silicon and wide-bandgap die without full redesign, compressing development cycles for multi-voltage product portfolios.
Silicon carbide MOSFET technology is collapsing the thermal management burden in 800V traction inverters. European and Chinese OEMs are adopting these modules at accelerated pace for premium EV platforms. The structural consequence is collapsing the competitive advantage of legacy silicon suppliers who lack captive SiC crystal growth capacity.
The EPA tailpipe emissions framework is tightening fleet-average CO2 mandates that compel powertrain electrification. Industrial consequence includes mandatory procurement of higher-efficiency power conversion components across light-duty and medium-duty vehicle categories. Heavy-duty commercial platforms face the steepest compliance cost escalation and are responding with accelerated pilot deployments of SiC-based drivetrains.
Fleet procurement patterns are consolidating around long-term supply agreements with module suppliers who guarantee substrate traceability and second-source qualification. Direct OEM-supplier contracting is displacing tier-one distributor intermediation in high-volume EV programs. This concentration is most visible in Germany and China, where domestic OEMs negotiate multi-year wafer allocation commitments.
Automotive Power Modules Market Segmentation
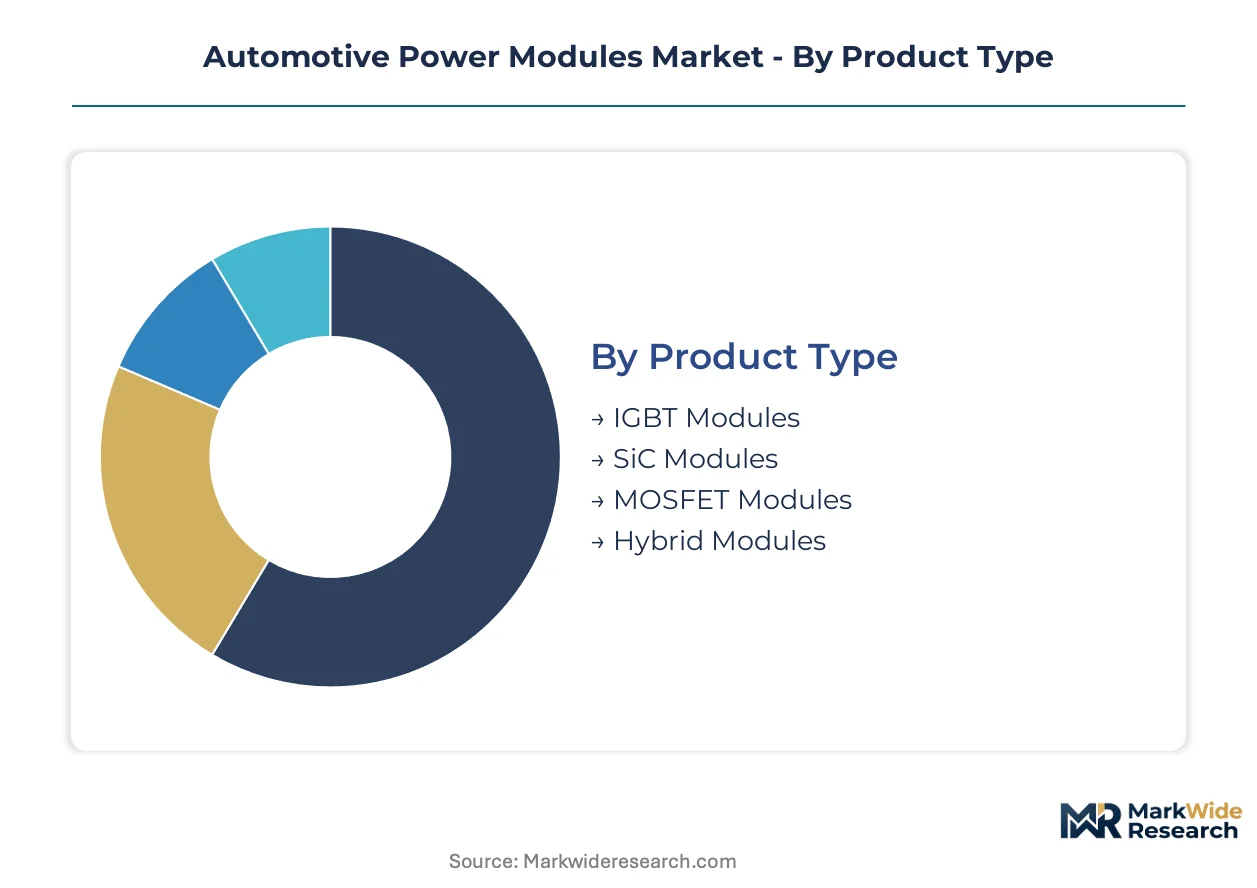
Power module procurement patterns diverge sharply across voltage classes and thermal architectures. OEM sourcing strategies now prioritize substrate material flexibility and regional qualification pathways over legacy packaging formats.
Product Type:
Cost tier determines procurement volume and margin structure across semiconductor substrate technologies.
- IGBT Modules:Silicon-based insulated-gate bipolar transistor assemblies dominate 400V hybrid drivetrains with mature supply chains and established AEC-Q101 qualification databases. Procurement concentrates among Japanese and German OEMs maintaining parallel IGBT and SiC sourcing for platform flexibility.
- SiC Modules:Silicon carbide MOSFET architectures sustain junction temperatures above 175°C while switching at frequencies above 50kHz, enabling traction inverter mass reduction of 40-50%. Demand clusters in China and Germany where 800V premium EV platforms require the highest conversion efficiency.
- MOSFET Modules:Silicon MOSFETs occupy auxiliary power applications below 100V including DC-DC converters and thermal management pumps.
- Hybrid Modules:Co-packaged silicon and SiC die combinations address cost-sensitive electrified platforms seeking partial efficiency gains.
IGBT Modules command the established base. The steepest expansion runs through SiC Modules.
Technology:
Application requirements across traction inverters and onboard chargers dictate which performance dimension drives supplier selection.
- Thermal Management:Direct liquid cooling and double-sided cooling architectures manage heat flux densities exceeding 250W/cm² in 800V systems. Chinese module suppliers integrate cooling subsystems to meet NMPA thermal cycling requirements.
- Power Density:Kilowatt-per-liter metrics determine packaging form factor constraints within crowded vehicle chassis envelopes. European OEMs specify 30-50kW/liter targets for next-generation inverter designs.
- Conversion Efficiency:Efficiency above 99% at partial load conditions minimizes battery pack sizing requirements.
- Integration Technology:Embedded gate drivers and current sensors reduce external component counts.
Thermal Management anchors qualification timelines. Power Density is climbing the fastest as OEMs compress chassis packaging volumes.
End User:
Customer type shapes contract structures, volume commitments, and technical collaboration depth.
- OEMs:Direct procurement from Volkswagen, BYD, and Tesla drives multi-year wafer allocation agreements with captive SiC substrate suppliers. OEMs specify module-level reliability requirements and second-source mandates.
- Tier-1 Suppliers:Denso, Bosch, and Vitesco intermediate module sourcing for OEMs lacking internal power electronics capabilities. These suppliers capture value through thermal stack integration and system-level qualification.
- Aftermarket Providers:Service networks for electrified fleets require diagnostic tooling and refurbished module exchanges.
- Specialty Vehicle Manufacturers:Low-volume producers of electric buses and construction equipment source customized module configurations.
OEMs dominate volume concentration. Tier-1 Suppliers are expanding fastest as outsourcing of inverter assembly accelerates.
Application:
Vehicle electrification depth determines voltage class, thermal budget, and reliability requirements.
- Electric Vehicles:Battery-electric platforms at 400V and 800V represent the primary demand sink, with SiC module penetration highest in premium segments above 100kWh battery capacity. Chinese EV production volumes exceed 50% of global module consumption.
- Commercial Vehicles:Heavy-duty electric trucks and buses impose 1.2 million kilometer lifetime requirements and severe thermal cycling profiles. European and North American fleet operators pilot SiC-based drivetrains for total cost of ownership advantages.
- Hybrid Vehicles:PHEV and HEV applications balance cost and efficiency with mixed IGBT-SiC architectures.
- Automotive Electronics:Low-voltage power modules support steer-by-wire, brake-by-wire, and thermal management systems.
Electric Vehicles anchor procurement volume. Commercial Vehicles are gaining share fastest as regulatory compliance costs force electrification of heavy-duty platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes automotive power modules at volumes exceeding half of global procurement, yet Germany and the United States deploy them at substantially higher power densities per vehicle as 800V architectures penetrate premium EV segments.
China
Domestic EV production exceeding global module consumption drives localization mandates under NMPA certification requirements. GB standards for new energy vehicle safety elevate technical barriers that favor suppliers with in-country testing infrastructure. Yangtze River Delta manufacturing corridors concentrate module packaging investments as BYD and CATL scale vertical integration into power electronics.
Germany
Volkswagen and BMW procurement of SiC-based traction inverters accelerates under EU Green Deal fleet-average CO2 mandates. KBA type-approval processes enforce AEC-Q101 reliability standards that extend qualification timelines for non-European entrants. Bavaria's semiconductor cluster anchors captive silicon carbide wafer capacity agreements between Infineon and domestic OEMs.
United States
Tesla and Ford drive 800V platform development for light-duty and commercial vehicle electrification. EPA tailpipe emissions frameworks tighten compliance costs for heavy-duty platforms, forcing pilot SiC drivetrain deployments. Michigan and Texas manufacturing corridors concentrate inverter assembly investments as the IRA production tax credits reshape domestic sourcing economics.
Japan
Toyota and Honda maintain parallel IGBT and SiC sourcing strategies for hybrid platform flexibility. METI technology roadmaps prioritize wide-bandgap semiconductor commercialization through public-private partnerships. Nagoya and Kyushu industrial clusters host Mitsubishi Electric's high-voltage IGBT assembly capacity for Southeast Asian commercial vehicle export markets.
India
Tata Motors and Mahindra scale EV platform investments under PLI scheme incentives for advanced power electronics. CEA grid integration standards create technical specifications for vehicle-to-grid bidirectional charging capabilities. Tamil Nadu and Gujarat manufacturing corridors attract module packaging investments as domestic cell chemistry production scales.
Automotive Power Modules Market Vendor Landscape
Capability concentration sits with integrated semiconductor manufacturers commanding captive silicon carbide substrate growth; scale advantage sits with diversified industrial conglomerates leveraging established automotive tier-one relationships. The market structures around three tiers: substrate-integrated specialists, diversified electronics conglomerates, and regional packaging specialists. Dominant competitive moves include backward integration into wafer supply and multi-year OEM allocation agreements locking substrate traceability.
Among diversified electronics conglomerates, Infineon Technologies and STMicroelectronics exemplify the substrate-integrated archetype, while Denso Corporation occupies a position bridging module packaging with thermal subsystem integration. Continental AG and Robert Bosch GmbH represent diversified industrial groups leveraging established powertrain engineering relationships across European and Asian OEM portfolios.
| Leading Market Players |
|---|
| Infineon Technologies |
| Continental AG |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| STMicroelectronics |
| Fuji Electric |
| ON Semiconductor |
| Valeo |
| Others |
Supply Flow & Price Mechanics
Captive silicon carbide wafer capacity concentrated among integrated semiconductor manufacturers in Germany and Japan anchors margin pools with module assemblers who lack upstream substrate control. Long-term offtake contracts between OEMs and wafer suppliers now dictate downstream pricing power across 800V traction inverter programs.
Pricing Analysis
Long-term offtake agreements spanning three to five years dominate procurement for high-volume EV platforms, while spot-market transactions persist for prototype and low-volume specialty vehicle builds. Price differentiation rests on AEC-Q101 certification tier and captive SiC crystal growth capability, with qualified suppliers commanding substantial premiums over independent assemblers. Cost compression in IGBT modules is intensifying because Chinese domestic suppliers are scaling 400V platform output under localization mandates. Fleet operators and commercial vehicle OEMs exhibit the highest price sensitivity, whereas premium passenger EV manufacturers prioritize efficiency metrics over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for module suppliers serving North American OEMs. Manufacturing concentrates in China, Germany, and Japan, with raw material dependencies spanning silicon carbide substrates from Japan, copper thermal interface materials from Chile, and aluminum baseplates from domestic smelters. Single-source vulnerability around 150mm SiC wafer supply constrains independent module assemblers who lack backward integration into crystal growth. Distribution runs through direct OEM contracting for high-volume programs, with tier-one suppliers like Denso and Bosch intermediate for outsourced inverter assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive power modules are approaching a platform-economics inflection as 800V architectures standardize around substrate-agnostic packaging and bidirectional charging protocols reshape inverter design requirements. Ecosystem interoperability between charging infrastructure, grid standards, and vehicle power electronics is consolidating procurement around suppliers who control both module and thermal subsystem integration.
For Market Incumbents: Insulate margin pools by locking multi-year wafer allocation commitments with German and Japanese substrate suppliers before independent assemblers qualify alternative sources. Accelerate in-house production of silicon carbide crystals to neutralize the threat of Chinese domestic suppliers capturing 800V platform share under NMPA localization requirements. Expand thermal stack integration capabilities to capture value from cooling subsystem convergence.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing corridors for 400V commercial vehicle modules before incumbent qualification databases solidify. Target aftermarket refurbishment and predictive replacement scheduling for electrified fleets as the most penetrable segment, where diagnostic tooling requirements create service revenue stickiness. Pursue joint development agreements with European tier-one suppliers seeking second-source qualification for SiC module programs.
For Investors and Strategic Acquirers: Capital is best deployed toward substrate-integrated specialists with captive wafer capacity and established AEC-Q101 qualification databases, as these assets compound defensive positioning across the analysis window. Acquisition target archetypes include regional packaging specialists in China and India with NMPA or PLI certification infrastructure. Watch for inflection signals in 200mm SiC wafer qualification timelines, which would collapse cost structures and redistribute competitive advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Wafer Supply | Infineon and STMicroelectronics anchor premium module contracts through captive substrate capacity. |
| Long-term OEM Allocation Agreements | Volkswagen and BYD lock multi-year wafer commitments that freeze out independent assemblers. |
| Thermal Stack Integration Expansion | Denso captures value from converging power modules with compact liquid cooling architectures. |
| Regional Certification Infrastructure Investment | Domestic suppliers with NMPA testing facilities capture share under China's localization mandates. |
| Bidirectional Charging Capability Development | Traction inverter reversibility opens stationary energy storage revenue streams for fleet operators. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket service network managers, and semiconductor packaging specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, vehicle production databases from IHS Markit, customs and trade data, and NMPA certification registries. Bottom-up module shipment estimates triangulated against top-down EV production forecasts across voltage class and propulsion architecture segments.
Scenario-bracketing around silicon carbide substrate availability, copper and aluminum price volatility, and regional content requirement enforcement shaped the analytical framework. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, semiconductor substrate technology, thermal management configuration, and regional production cluster. CAGRs derived from unit shipment trajectories and average selling price evolution across the projection horizon, with specific inputs including GB standards compliance timelines and EU Green Deal fleet-average CO2 mandate trajectories.
Stress conditions across SiC wafer supply concentration, base metal price volatility, and NMPA qualification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding substrate technology transition rates and OEM platform electrification schedules. Material shifts in Chinese domestic supplier qualification timelines or 200mm SiC wafer commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Tappet Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
Japan Electro Hydraulic Power Steering Market
Powertrain
Car Active Purge Pump Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Automotive Transmission Fluid Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Oil Sump Market
Powertrain
North America Precision Gearbox Market
Powertrain
Engine Rocker Arm Market
Powertrain
Car Drive System Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Automotive Brake Booster Market
Powertrain
Automotive Fluid Reservoir Market