
 Automotive Esim Market | 2026-2036
Automotive Esim Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Esim Market Analysis
Automotive eSIM distribution through carrier-direct channels is fragmenting as OEMs pursue embedded connectivity strategies. Thales Group leverages its secure element manufacturing base to anchor supply relationships with European automakers. Giesecke+Devrient competes through specialized subscription management platforms that simplify multi-carrier provisioning. Deutsche Telekom controls a significant share of operational MNO partnerships, extending its position through integrated automotive service bundles.
An automotive eSIM is a remotely provisionable subscriber identity module soldered directly into vehicle control units, typically conforming to M2M form factors with enhanced temperature tolerance from minus forty to one hundred five degrees Celsius, enabling persistent cellular connectivity for safety and convenience services. Embedded eSIM variants dominate current production volumes due to their tamper resistance and space efficiency in densely packed electronic architectures. Telematics applications lead deployment rates as regulatory mandates for emergency call systems expand across multiple jurisdictions, while remote diagnostics represents the fastest-growing application segment as predictive maintenance contracts reshape aftermarket revenue models.
The European Telecommunications Standards Institute defines M2M eSIM architecture specifications that constrain hardware interoperability across the supply base. In the United States, FCC equipment authorization requirements govern radio frequency emissions from automotive connectivity modules, directly shaping product certification timelines. Japan's Ministry of Economy, Trade and Industry promotes connected vehicle standards through national ITS initiatives. Stakeholders must monitor divergence between regional cybersecurity certification regimes when planning multi-market eSIM platform rollouts.
Market Dynamics
Automotive eSIM deployment is accelerating as vehicle architectures consolidate around zonal compute platforms, forcing connectivity modules to migrate from discrete telematics boxes into domain controllers where soldered eSIMs replace removable SIM trays.
Growth Catalysts
- Emergency call mandates:The EU's eCall regulation and equivalent requirements in Russia and Kazakhstan mandate automatic crash notification systems, embedding cellular connectivity as a baseline safety feature across vehicle classes.
- Over-the-air software updates:OEMs are expanding remote firmware management for powertrain and infotainment systems, creating persistent bandwidth requirements that eSIMs provision automatically across carrier networks.
- Predictive maintenance contracts:Fleet operators and leasing companies are monetizing vehicle health monitoring, driving demand for continuous telemetry streams that embedded eSIMs enable without driver intervention.
Market Restraints
- Semiconductor supply concentration:Secure element fabrication for automotive-grade eSIMs concentrates among a limited set of European and East Asian foundries, exposing OEMs to allocation risk during capacity constraints.
- Subscription management complexity:Multi-carrier provisioning platforms require sustained interoperability investment, fragmenting operational expenditure across incompatible carrier backends.
- Long vehicle lifecycles:Automotive electronics must function for fifteen to twenty years, yet cellular network technology refreshes on five-to-seven-year cycles, creating obsolescence risk for embedded modules.
Strategic Opportunities
- Software-defined vehicle platforms:Centralized compute architectures in premium electric vehicles are creating demand for multi-profile eSIMs that separate consumer, fleet, and manufacturer data streams on single hardware.
- India's Bharat NCAP expansion:The country's vehicle safety rating program is incorporating connected safety features, opening a volume market where embedded connectivity transitions from luxury to mass-market equipment.
- Blockchain-anchored identity:Integration of distributed ledger verification with eSIM authentication is emerging as a technical pathway for secure vehicle-to-infrastructure payment and access credentialing.
Industry Challenges
- Cybersecurity certification timelines:The EU Cyber Resilience Act and UN ECE R155 type approval require extensive penetration testing and documentation, extending product development cycles by twelve to eighteen months.
- Multi-stakeholder data governance:OEMs, tier-one suppliers, MNOs, and cloud service providers must negotiate liability frameworks for connectivity failures that span organizational boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Esim Market |
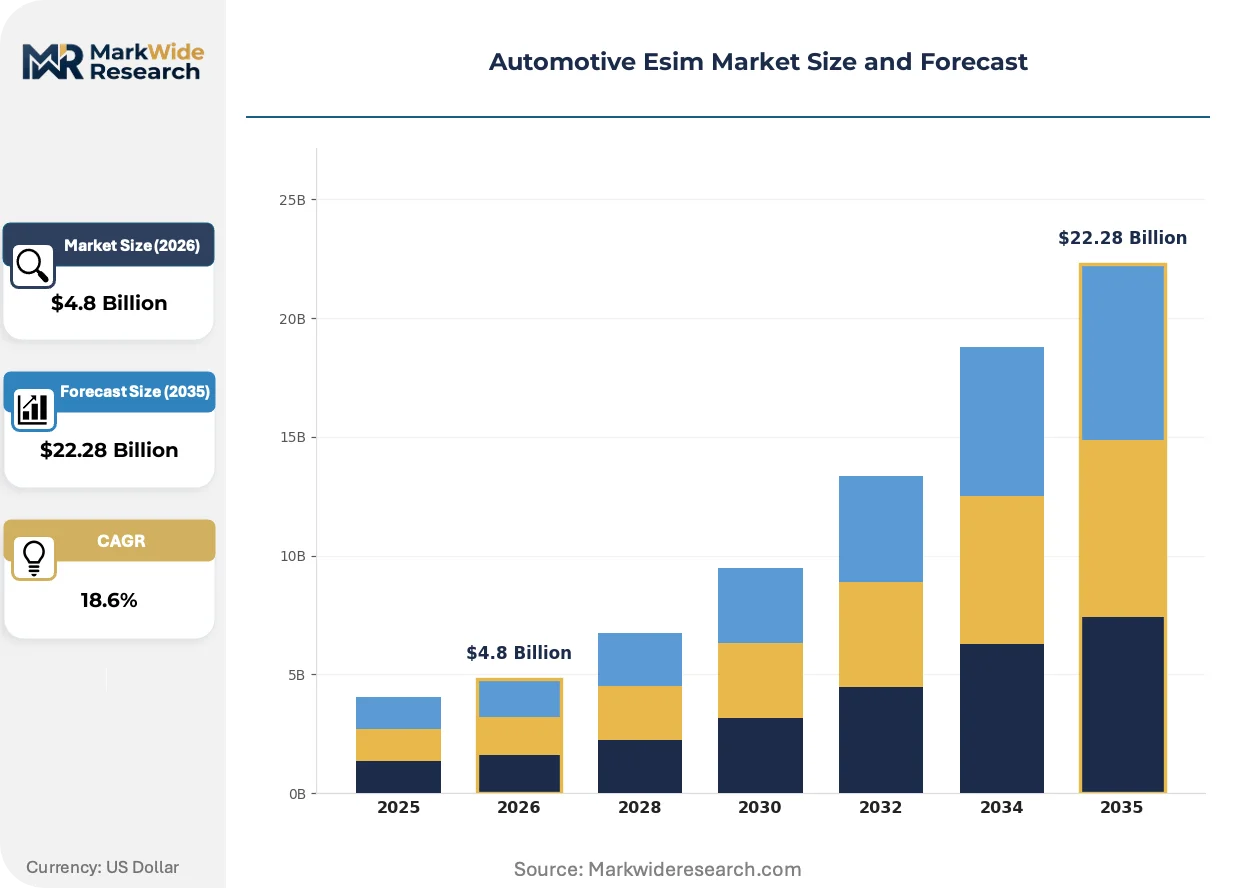
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.28 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Removable eSIM, Embedded eSIM, Integrated eSIM, SIM Manager End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Technology: Cellular, GNSS, V2X, IoT Connectivity Application: Telematics, Fleet Management, Infotainment, Remote Diagnostics |
| Companies Covered | IDEMIA, Thales Group, Giesecke+Devrient, Deutsche Telekom, STMicroelectronics, NXP Semiconductors, Infineon Technologies, AT&T, Telefónica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Esim Market Emerging Trajectories
Automotive connectivity is undergoing architectural transformation as software-defined vehicle platforms dissolve traditional boundaries between telematics, infotainment, and powertrain domains. Three developments are restructuring how cellular modules are specified, provisioned, and monetized.
Integrated eSIM functionality is virtualizing the traditional SIM supply chain by embedding subscription management directly into vehicle operating systems. Premium electric vehicle platforms from German and Korean manufacturers are adopting this approach first, eliminating physical card slots to reclaim interior space and reduce assembly complexity. This virtualization is compressing procurement relationships from hardware vendors toward software-centric platform providers.
Japan's METI has issued updated connected vehicle guidelines that mandate local data processing for sensitive telemetry, reshaping how eSIM routing policies are configured. The regulation requires domestic network termination for location and biometric data, forcing OEMs to implement region-specific subscription profiles. Powertrain monitoring systems are most affected, as they must now maintain separate data paths for domestic and cross-border transmission.
Fleet procurement departments are consolidating connectivity purchasing away from vehicle acquisition teams, creating direct relationships with MNOs that bypass traditional OEM-bundled services. This channel disintermediation is most visible in North American commercial vehicle operations, where large logistics operators negotiate enterprise-wide data plans that override factory-installed carrier agreements. The shift is fragmenting aftermarket revenue pools that manufacturers had treated as captive.
Automotive Esim Market Segmentation
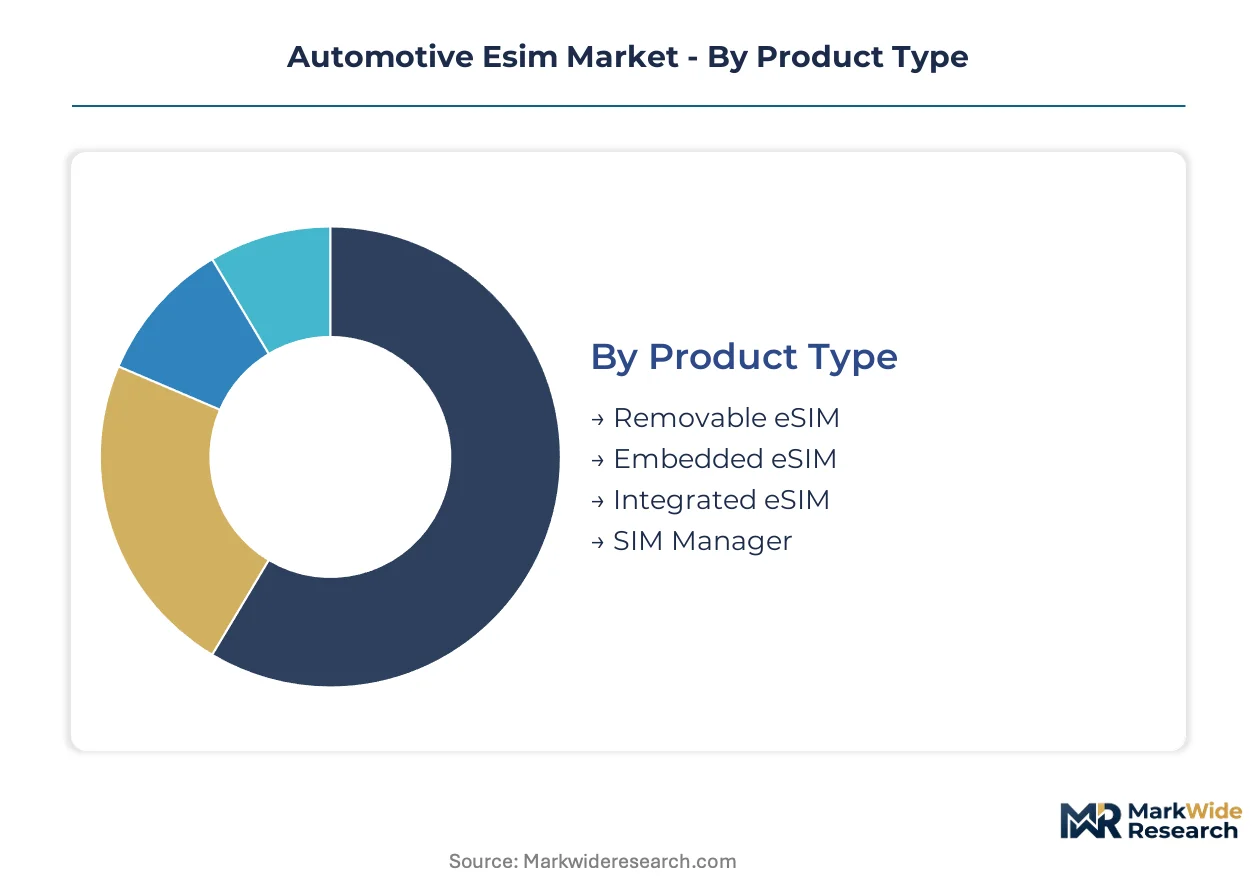
Automotive eSIM segmentation reflects divergent service intensity across vehicle lifecycle stages. Embedded variants demand minimal dealer intervention while integrated solutions require continuous software orchestration.
Product Type:
After-sales-service intensity varies sharply across form factors, with soldered modules demanding zero physical maintenance while management platforms require perpetual subscription oversight.
- Embedded eSIM:Soldered M2M modules with temperature tolerance from minus forty to one hundred five degrees Celsius serve as the default architecture for telematics control units. German and Japanese OEMs specify these for emergency call systems where physical tamper resistance outweighs carrier flexibility.
- Integrated eSIM:Virtualized subscription management embedded directly into vehicle operating systems eliminates physical card slots entirely. Korean manufacturers deploy these in premium electric vehicle platforms where interior space reclamation and assembly simplification justify higher upfront engineering investment.
- Removable eSIM:M2M form factor cards in carrier-configurable sockets serve legacy fleet retrofit applications.
- SIM Manager:Software platforms handling multi-profile provisioning and carrier switching address fleet operator demands for rate arbitrage.
By volume, Embedded eSIM leads. By growth pace, Integrated eSIM is climbing the fastest.
End User:
Cost tier stratification separates factory-installed systems from post-sale service revenue pools.
- OEMs:Vehicle manufacturers specify eSIM hardware during platform development, capturing connectivity revenue through bundled service contracts. Direct procurement relationships with Thales Group and Giesecke+Devrient secure supply allocation during semiconductor constraints.
- Tier-1 Suppliers:Continental and Bosch integrate eSIMs into domain controllers for zonal architectures, positioning connectivity as a bundled electronics component rather than discrete module.
- Aftermarket Providers:Retrofit telematics boxes serve commercial vehicle operators extending fleet connectivity to legacy assets.
- Dealerships:Franchise networks activate consumer-facing subscription tiers during vehicle handover.
OEMs dominate procurement volume. Aftermarket Providers are expanding most quickly as fleet operators decouple connectivity from vehicle acquisition.
Technology:
Application requirements dictate radio technology stacking in multi-protocol modules.
- Cellular:LTE-M and 5G NR modules provide persistent wide-area connectivity for over-the-air updates and emergency services.
- V2X:C-V2X and DSRC radios enable direct vehicle-to-infrastructure communication for cooperative awareness.
- GNSS:Multi-constellation positioning engines integrate with eSIM data links for stolen vehicle tracking and usage-based insurance.
- IoT Connectivity:Low-power WAN protocols serve battery-operated asset trackers in trailer and container applications.
Cellular anchors installed base. V2X shows steepest expansion trajectory as regulatory mandates for cooperative intelligent transport systems advance.
Application:
Customer type fragmentation separates consumer convenience services from commercial operational imperatives.
- Telematics:Emergency call systems and stolen vehicle tracking represent regulatory-mandated baseline connectivity. EU eCall and equivalent mandates in Russia and Kazakhstan embed cellular hardware as standard safety equipment.
- Remote Diagnostics:Continuous powertrain telemetry enables predictive maintenance contracts reshaping aftermarket revenue models. Fleet operators in North America monetize vehicle health monitoring through direct MNO relationships.
- Fleet Management:Asset tracking and driver behavior analytics serve logistics operators with enterprise-wide data plans.
- Infotainment:Consumer streaming and Wi-Fi hotspot services generate recurring subscription revenue.
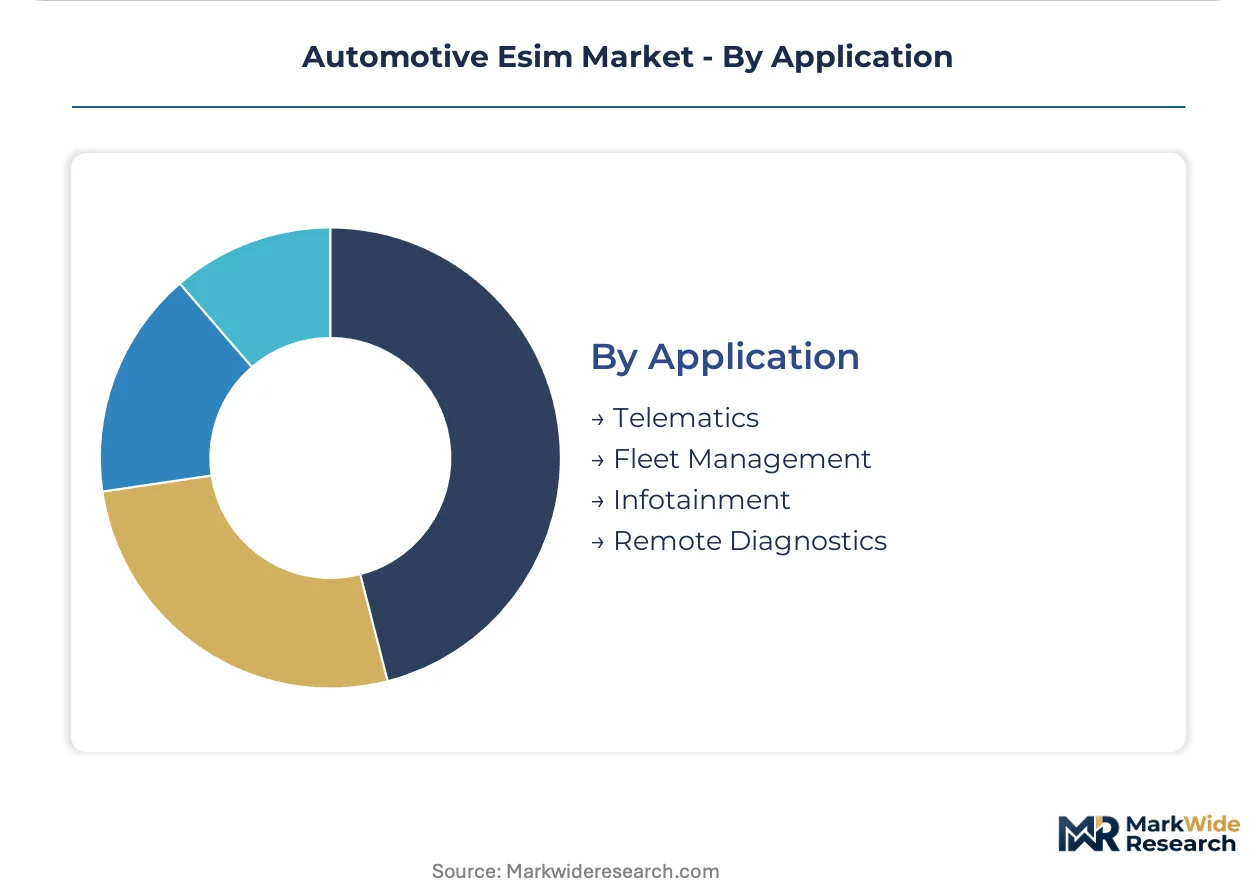
Telematics leads by unit volume. Remote Diagnostics is gaining share fastest as predictive maintenance contracts displace traditional service intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for connected vehicle safety systems are accelerating eSIM deployment across major automotive manufacturing centers. Regulatory frameworks in the European Union, Japan, and North America establish baseline connectivity requirements that shape procurement patterns. OEM supply chain decisions concentrate hardware sourcing in jurisdictions with integrated electronics ecosystems.
Germany
Emergency call system mandates from KBA drive factory-installed eSIM specifications across premium and mass-market vehicle lines. The EU Cyber Resilience Act imposes hardware authentication standards that extend product development timelines for connected components. Stuttgart and Munich anchor concentrated electronics supply chains where Thales Group and Giesecke+Devrient maintain secure element fabrication relationships with domestic OEMs.
Japan
METI connected vehicle guidelines mandate local data processing for sensitive telemetry, forcing region-specific subscription profile implementations. The ministry's ITS initiatives promote domestic network termination requirements for location and biometric data flows. Nagoya and Tokyo metropolitan areas host integrated semiconductor packaging facilities where automotive-grade eSIM modules undergo final qualification for export markets.
United States
FCC equipment authorization requirements govern radio frequency emissions from automotive connectivity modules, directly shaping product certification timelines for telematics control units. Fleet operators in commercial vehicle segments negotiate enterprise-wide data plans that bypass factory-installed carrier agreements. Michigan and California concentrate domain controller manufacturing where zonal architectures embed soldered eSIMs into consolidated compute platforms.
South Korea
Premium electric vehicle platforms from domestic manufacturers adopt integrated eSIM virtualization to eliminate physical card slots and reclaim interior space. MFDS cybersecurity frameworks for connected medical and automotive devices establish penetration testing protocols that overlap with vehicle type approval processes. Seoul metropolitan area hosts software-centric platform providers compressing procurement relationships away from discrete hardware vendors.
India
Bharat NCAP expansion incorporates connected safety features, transitioning embedded connectivity from luxury to mass-market equipment specifications. TRAI spectrum allocation policies for IoT and M2M applications shape carrier provisioning economics for telematics services. Tamil Nadu and Gujarat manufacturing corridors attract electronics component suppliers establishing localized secure element assembly capacity for domestic OEM integration.
Automotive Esim Market Vendor Landscape
On the supply side, the industry is consolidating around secure element manufacturers with automotive qualification credentials and subscription management platform operators. Component fabrication concentrates among European and East Asian foundries with temperature tolerance certification for M2M form factors. Three strategic archetypes dominate: secure element specialists, integrated connectivity platform providers, and carrier-affiliated provisioning services. Competitive moves center on multi-profile software development and direct OEM supply relationships that bypass traditional distribution channels.
Among secure element manufacturers, Thales Group, Giesecke+Devrient, and NXP Semiconductors exemplify the hardware-authentication tier where automotive-grade qualification creates supply allocation leverage. Deutsche Telekom occupies a position representing carrier-integrated service bundling. These named entities anchor archetype boundaries without exhausting the competitive set, as STMicroelectronics and Infineon Technologies sit within adjacent semiconductor specialization tiers, while IDEMIA and Telefónica represent provisioning and network operation segments respectively.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| Giesecke+Devrient |
| Deutsche Telekom |
| STMicroelectronics |
| NXP Semiconductors |
| Infineon Technologies |
| AT&T |
| Telefónica |
| Others |
Supply Flow & Price Mechanics
Undercapacity in automotive-grade secure element foundries across Germany and South Korea is tightening allocation leverage for qualified suppliers and compressing pricing flexibility for OEMs negotiating multi-year connectivity contracts. This utilization squeeze feeds directly into tier-one supplier procurement posture, where domain controller integrators pass through semiconductor scarcity premiums while extracting volume commitments.
Pricing Analysis
Volume-discount tiering structures separate emergency call system baselines from premium multi-profile configurations, with German OEMs capturing steepest reductions through consolidated platform sourcing across vehicle lines. Price differentiation hinges on EAL4+ certification grade and after-sales subscription bundling, where integrated eSIM virtualization commands substantial engineering premiums over soldered M2M alternatives. Cost compression in mass-market telematics modules is intensifying as Indian and Chinese OEMs qualify second-source secure element vendors. Fleet operators exhibit highest price sensitivity due to direct MNO negotiation leverage, while premium electric vehicle manufacturers prioritize space efficiency over unit cost.
Supply Chain Analysis
Export-control regimes restricting advanced semiconductor manufacturing equipment to Chinese foundries are constraining regional supply diversification for automotive eSIM secure elements. Fabrication concentrates in Germany, South Korea, and Taiwan, with final module assembly drawing from specialized packaging facilities in Japan and Malaysia. Raw material dependencies span silicon wafers, gold bonding wire, and high-reliability epoxy molding compounds. Single-source vulnerability around ETSI-certified subscription management platforms represents the dominant structural risk. Distribution runs through direct OEM procurement channels that bypass traditional electronics distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
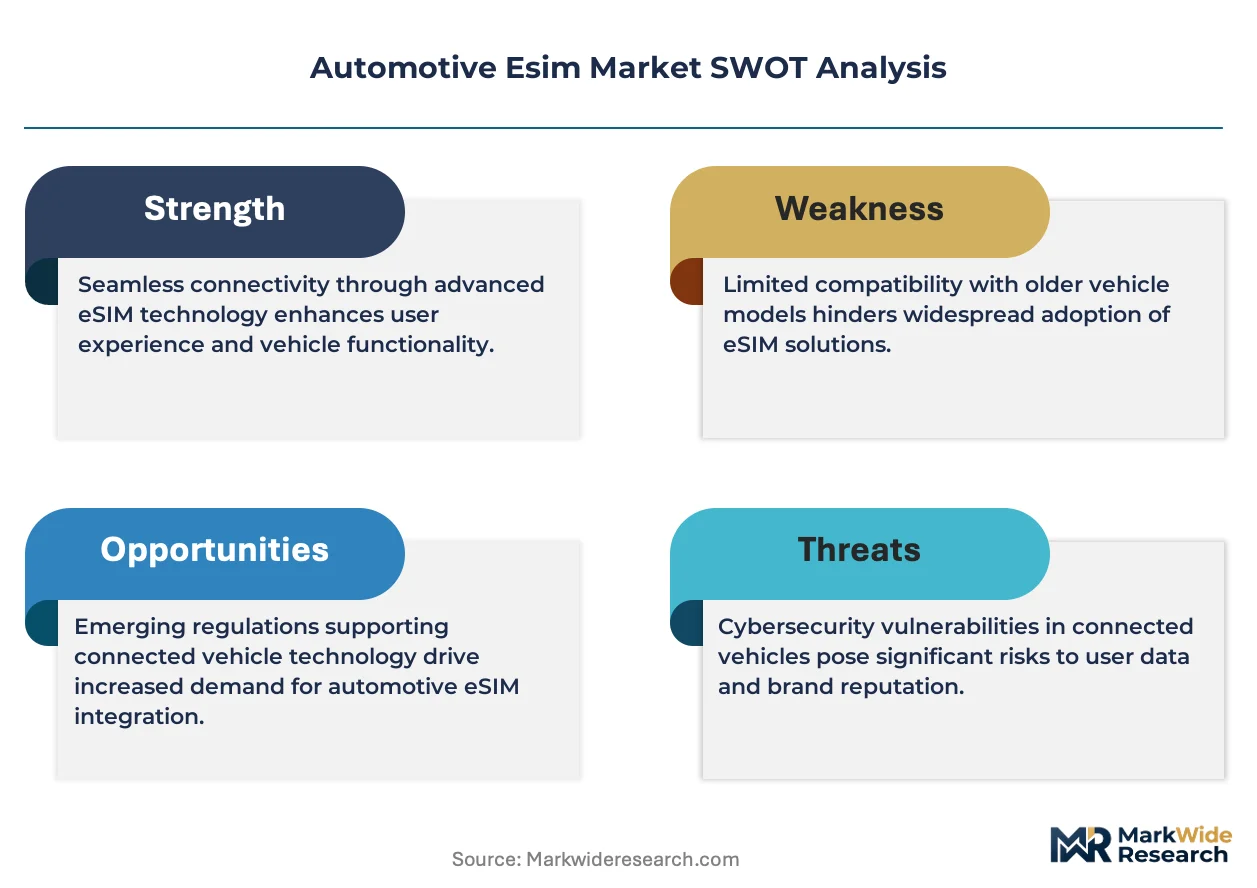
This market functions as a defensive-moat story where regulatory entrenchment around cybersecurity certification creates substantial switching costs for OEMs qualifying alternative suppliers.
For Market Incumbents: Entrench platform-level integration by embedding subscription management directly into zonal domain controllers, foreclosing modular replacement by aftermarket competitors. Secure allocation priority at Thales Group and Giesecke+Devrient foundries through multi-year offtake agreements, countering emerging fabless entrants from Taiwan. Deepen certification investment under EU Cyber Resilience Act and UN ECE R155 frameworks to extend approval timelines that protect installed base. For New Entrants and Emerging Players: India's Bharat NCAP expansion represents the most penetrable volume opportunity, where mass-market connectivity specifications remain unsettled and domestic OEMs seek cost-optimized alternatives to European secure element pricing. Target commercial vehicle fleet operators with SIM Manager platforms that enable rate arbitrage across carrier networks, bypassing OEM-bundled services entirely. Pursue direct MNO partnerships as the primary go-to-market angle, leveraging enterprise data plan relationships that override factory-installed connectivity agreements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated connectivity platform providers with software-defined vehicle deployments, where virtualization eliminates hardware replacement cycles and locks in perpetual subscription management fees. Long-term viability favors acquisition targets possessing dual automotive qualification credentials and active MNO provisioning relationships. Monitor India's TRAI spectrum allocation rulings for IoT and M2M applications as the critical inflection signal, where favorable carrier economics would accelerate embedded connectivity penetration in mass-market vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidated zonal architectures embed eSIM functionality directly into domain controllers, eliminating discrete telematics modules. |
| Software-Defined Vehicle Investment | Virtualized subscription management in Korean premium EV platforms compresses procurement toward software-centric providers. |
| Geographic Manufacturing Footprint | Localized secure element assembly in Tamil Nadu and Gujarat corridors addresses India's Bharat NCAP connectivity mandates. |
| Battery Supply Agreement | Electric vehicle platform scale creates bundled connectivity procurement leverage for integrated eSIM specification. |
| Charging Infrastructure Partnership | Vehicle-to-grid authentication requirements drive blockchain-anchored eSIM identity verification for payment credentialing. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings from semiconductor manufacturers, and ETSI technical specifications. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, MNO automotive service directors, and aftermarket telematics distributors. Bottom-up triangulation across component shipment volumes and top-down validation against vehicle connectivity penetration rates ensure cross-verified market sizing.
Forecast inputs incorporate vehicle class stratification, propulsion architecture differentiation, eSIM content per vehicle by platform generation, OEM tier segmentation, and regional production cluster dynamics. CAGRs derive from segmented growth trajectory modeling across the projection horizon, with specific weighting applied to regulatory mandate implementation schedules and carrier provisioning economics. Industry-specific inputs include semiconductor foundry capacity utilization signals and cybersecurity certification pipeline visibility.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese fabless secure element vendors or hyperscaler-backed connectivity platforms would shift outcomes. Material shifts in EU Cyber Resilience Act enforcement timelines or India's TRAI spectrum allocation rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
High Voltage DC Relay for Vehicle Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
TPMS Battery Market
Automotive Electrical & Electronics
Automotive Alternator Market
Automotive Electrical & Electronics
Automotive E-Compressor Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Automotive Camera Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive PCB Market
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
Stair Lift Motors Market
Automotive Electrical & Electronics
Global Automotive on Board Power Inverter Market