
 Car Satellite Antenna Market | 2026-2036
Car Satellite Antenna Market Size, Share, and Industry Trends Forecast 2026-2036
Car Satellite Antenna Market Analysis
Market Context
LCP resin is decoupling car satellite antenna housings from traditional thermoplastic assemblies, cutting part weight while maintaining RF transparency across Ku and Ka bands. Kathrein leverages its European manufacturing footprint to supply phased-array modules directly to German premium OEMs. Harada sustains dominance in shark-fin multi-function antennas through captive die-casting operations in Japan and Thailand. Molex competes on connector-integrated antenna platforms that merge FAKRA and HSD interfaces into single roofline modules.
Technical Definition and Segment Structure
A car satellite antenna is a vehicle-mounted RF transducer designed to capture and transmit signals from geostationary and low-earth-orbit constellations, typically operating at 1.5–30 GHz with circular polarization and gain specifications exceeding 3 dBiC for mobile applications. Its primary commercial purpose is to enable uninterrupted navigation, emergency calling, and broadband data services in vehicles traversing terrestrial cellular dead zones. The active antenna segment leads unit volume as OEMs specify low-noise amplifier integration to compensate for coaxial cable losses in large SUVs and commercial vans. Phased-array technology represents the fastest-growing architecture, with electronically steerable beams eliminating mechanical azimuth tracking and reducing roofline protrusion height. Aftermarket installers occupy a mature margin pool concentrated on retrofitting legacy fleets with single-band GPS units, though this channel faces compression as factory-installed telematics penetration deepens.
Regulatory Framework and Outlook
The EU's Radio Equipment Directive and ETSI EN 303 413 shape antenna emission masks and spurious radiation limits for connected vehicles sold across member states, while the FCC in the United States governs Part 25 licensing for mobile earth station terminals operating near Inmarsat and Starlink frequencies. Japan's MIC enforces stringent antenna efficiency benchmarks under Radio Law Article 38, compelling suppliers like Harada and Yokowa to maintain dedicated Tokyo testing laboratories. Stakeholders must monitor spectrum reallocation proceedings in major automotive markets, as terrestrial 5G expansion threatens to encroach on satellite downlink bands and force antenna redesign cycles.
Market Dynamics
Phased-array beam steering is decoupling antenna performance from mechanical positioning hardware, compressing roofline packaging requirements while expanding Ku-band throughput for broadband mobility services.
Growth Catalysts
- Emergency calling mandates:The EU's eCall regulation compels automakers to embed satellite redundancy for automatic crash notification across all new vehicle types sold in member states.
- Low-Earth orbit proliferation:Constellation densification by Starlink and OneWeb is creating signal availability in previously unserved rural corridors, pulling OEM specification upgrades.
- Die-casting automation:Thai and Japanese manufacturing clusters are achieving 40-second cycle times on multi-cavity aluminum housings, compressing unit economics for shark-fin assemblies.
Market Restraints
- LCP resin supply concentration:Polymer feedstock for RF-transparent housings concentrates among three Japanese chemical conglomerates, exposing antenna assemblers to force majeure risk.
- Spectrum reallocation friction:FCC proceedings on 12 GHz band sharing between terrestrial 5G and satellite downlinks are freezing antenna architecture commitments until rulings finalize.
- Coaxial cable loss physics:Signal attenuation in copper runs exceeding four meters necessitates distributed low-noise amplifiers, adding BOM complexity for commercial van platforms.
Strategic Opportunities
- India fleet retrofit:Commercial vehicle telematics penetration remains below 15 percent, creating aftermarket pull for single-band GPS units with BS-VI compliance logging.
- Cyber Resilience Act certification:Antenna authentication protocols mandated for European market entry create first-mover margin pools for suppliers achieving ETSI EN 303 413 compliance ahead of enforcement.
- Phased-array plus 5G convergence:Hybrid modules combining electronically steerable satellite beams with cellular MIMO are enabling seamless handoff architectures for autonomous highway corridors.
Industry Challenges
- RF simulation talent scarcity:Electromagnetic modeling expertise for multi-band array optimization concentrates among legacy defense contractors, forcing antenna specialists into bidding wars for finite engineering capacity.
- Homologation timeline compression:Simultaneous FCC Part 25, EU RED, and Japan MIC approval cycles for multi-constellation terminals are extending product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Satellite Antenna Market |
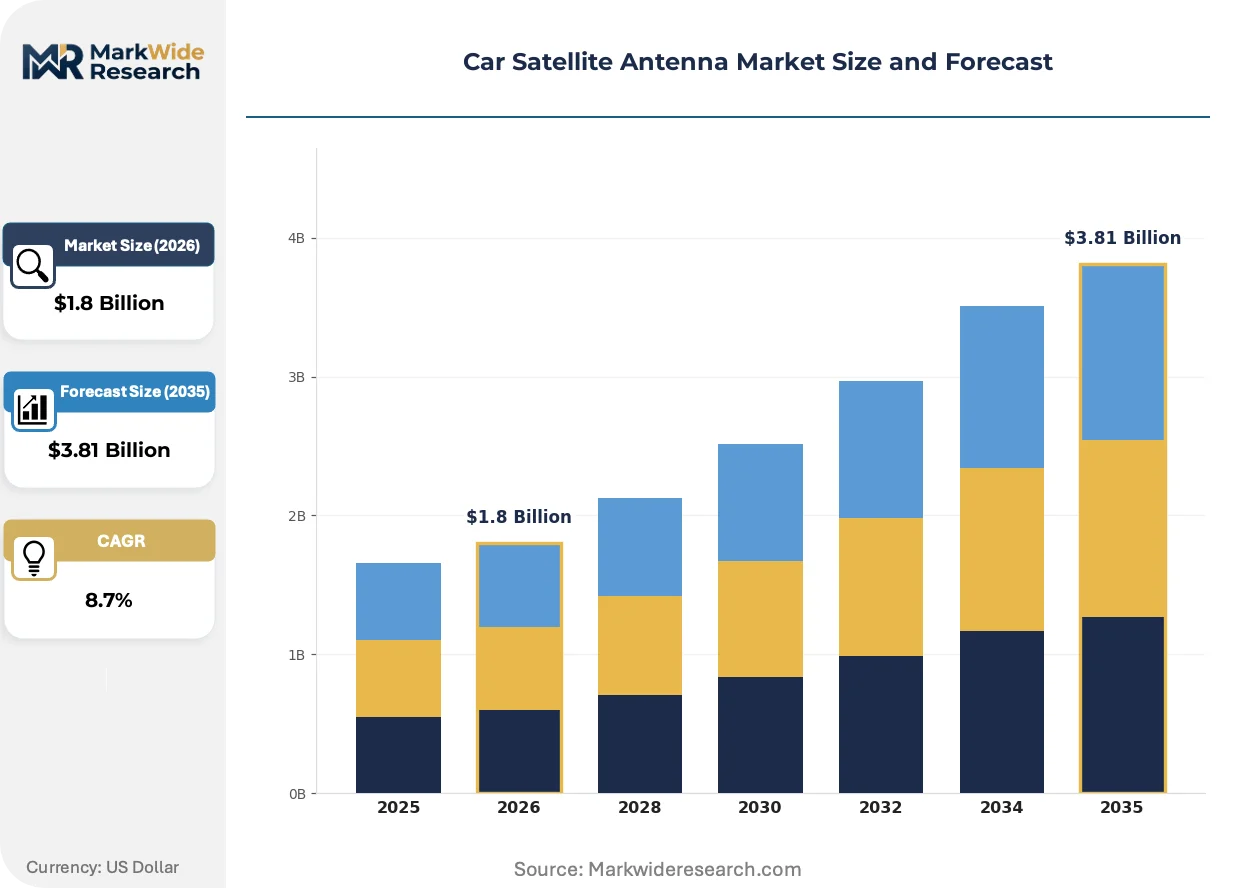
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Antenna, Passive Antenna, Amplified Antenna, Digital Antenna Application: GPS Navigation, Entertainment System, Communication System, Telematics Technology: Microstrip, Reflective, Array, Phased-Array End User: OEMs, Aftermarket Installers, Fleet Management, Ride-Sharing Companies |
| Companies Covered | Kathrein, ASK Industries, Molex, Inzi Controls, Northeast Industries, Harada, Hirschmann, Suzhong Antenna Group, Yokowa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Satellite Antenna Market Emerging Trajectories
Antenna architecture is pivoting from passive reception toward software-defined beam management, with hardware-software co-design becoming the primary locus of competitive differentiation.
Metamaterial surfaces are integrating into low-profile apertures, replacing parabolic dishes with flat panels that achieve comparable gain across L-band through Ka-band. German premium OEMs are specifying these assemblies for flagship electric vehicle rooflines where drag coefficient targets prohibit protruding mechanical trackers. The structural consequence is that RF frontend design is integrating with vehicle aerodynamics workflows, compressing traditional supplier tier boundaries.
Japan's MIC is tightening antenna efficiency benchmarks under revised Radio Law Article 38 enforcement guidelines, compelling suppliers to maintain dedicated Tokyo testing laboratories for pre-certification validation. The industrial consequence is a bifurcation between suppliers with captive Japanese facilities and those dependent on third-party lab queues. Tier 1 antenna integrators serving Toyota and Honda platforms are most affected, accelerating backward integration into electromagnetic simulation capabilities.
Fleet procurement is consolidating specification authority from individual vehicle operators toward telematics platform providers, compressing vendor counts and elevating volume-scale pricing power. Samsara and Geotab are displacing fragmented aftermarket distributors as the primary antenna specification gatekeepers for North American commercial vehicle deployments. This concentration is most visible in long-haul trucking corridors where unified connectivity contracts now bundle satellite backup with primary cellular service.
Car Satellite Antenna Market Segmentation
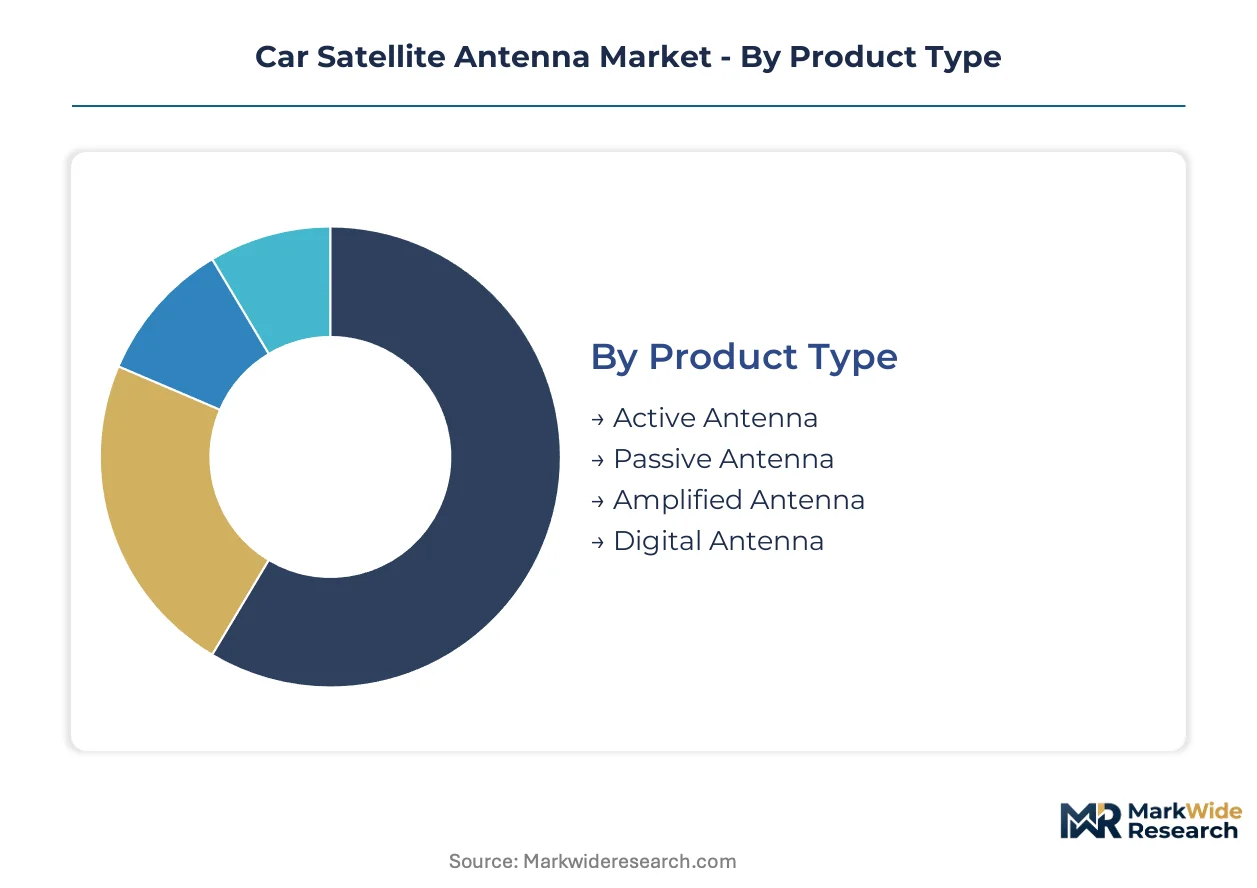
Antenna segmentation in automotive applications tracks the divergence between factory-integrated connectivity architectures and retrofit solutions for legacy vehicle pools. Specification authority concentrates with OEM platform engineers for new vehicle programs, while fragmented procurement patterns persist in commercial fleet retrofit channels.
Product Type:
Standardization dominates at the low end with passive assemblies, while active configurations command customization premiums for multi-band RF frontends.
- Active Antenna:Integrates low-noise amplifiers and filtering circuits directly at the aperture to compensate for coaxial losses in large commercial vans and luxury SUVs. German premium OEMs specify these for flagship electric vehicle lineups requiring uninterrupted connectivity across Ku and Ka bands.
- Passive Antenna:Simple conductive elements without onboard amplification, specified primarily for cost-sensitive compact car segments where cable runs remain under two meters. Volume concentration in emerging market vehicle platforms where telematics penetration lags factory-installed rates.
- Amplified Antenna:External amplifier modules bridge passive elements with head units, common in mid-range crossover retrofit applications.
- Digital Antenna:Software-defined RF processing enables constellation switching without hardware swaps, gaining traction in autonomous vehicle test fleets.
Leading the category by volume: Passive Antenna. Growing fastest: Active Antenna.
Application:
Functional requirements split between safety-mandated services and discretionary infotainment, with regulatory pressure elevating certain segments above pure commercial logic.
- GPS Navigation:Multi-constellation reception capability now baseline across all vehicle tiers, with L1/L2/L5 band support becoming standard in mid-range platforms. Japanese suppliers maintain dedicated Tokyo testing laboratories under MIC Radio Law Article 38 enforcement for pre-certification validation.
- Telematics:Emergency calling mandates including EU eCall compel satellite redundancy for automatic crash notification, embedding hardware regardless of consumer preference. Fleet procurement consolidation toward Samsara and Geotab specifications is compressing vendor counts in North American commercial vehicle corridors.
- Entertainment System:Broadband mobility services via Starlink and OneWeb integration, specified for rear-seat streaming in premium three-row SUVs.
- Communication System:Voice and data connectivity for commercial fleet dispatch, concentrated in long-haul trucking applications.
Telematics claims the largest installed base. Entertainment System climbs the fastest as LEO constellation density expands.
Technology:
Architecture selection trades physical packaging constraints against beam agility requirements, with aerodynamic priorities in electric vehicles accelerating flat-panel adoption.
- Phased-Array:Electronically steerable beams eliminate mechanical azimuth tracking, reducing roofline protrusion height critical for drag coefficient targets. German premium OEMs specify metamaterial-enhanced flat panels for flagship electric vehicle rooflines where traditional parabolic dishes violate aerodynamic workflows.
- Microstrip:Low-profile printed circuit implementations dominate shark-fin multi-function assemblies, with LCP resin housings decoupling weight from RF transparency performance.
- Reflective:Parabolic and horn configurations persist in aftermarket satellite TV retrofit for recreational vehicles.
- Array:Fixed-beam multi-element configurations serve GPS-dominant applications with limited spatial coverage requirements.
Microstrip holds volume leadership. Phased-Array expands most quickly as beam steering decouples performance from mechanical hardware.
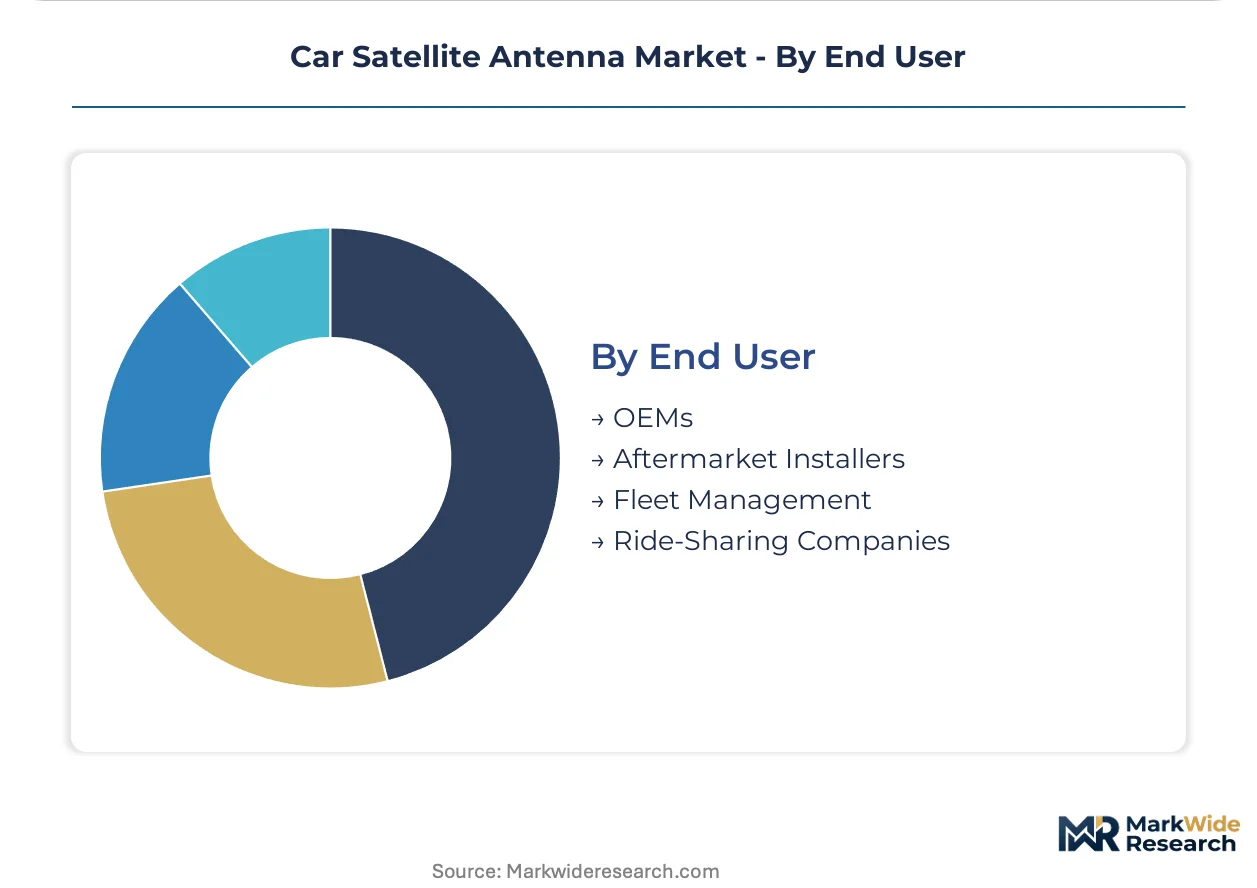
End User:
Procurement authority concentrates upstream as telematics platform providers displace fragmented vehicle operators, reshaping vendor engagement models.
- OEMs:Integrated platform engineering teams specify antennas during vehicle development cycles, with multi-band satellite functionality now embedded in next-generation electric vehicle architectures. Kathrein supplies phased-array modules directly to German premium manufacturers from European manufacturing footprints.
- Fleet Management:Unified connectivity contracts now bundle satellite backup with primary cellular service, consolidating specification authority with telematics providers. Samsara and Geotab displace aftermarket distributors as primary antenna gatekeepers in North American long-haul corridors.
- Aftermarket Installers:Mature margin pool concentrated on single-band GPS retrofit for legacy fleets, facing compression as factory-installed telematics penetration deepens.
- Ride-Sharing Companies:Driver safety and asset tracking requirements pull multi-constellation specifications in urban vehicle pools.
OEMs dominate unit volume. Fleet Management gains share fastest as procurement centralizes on platform providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German premium OEMs anchor demand concentration through multi-band satellite antenna specifications for flagship electric vehicle lineups, while regulatory pressure across multiple jurisdictions accelerates authentication protocol adoption.
Germany
Bavaria-based automakers specify phased-array modules with metamaterial-enhanced flat panels for aerodynamic roofline integration. The EU's Cyber Resilience Act mandates stricter antenna authentication protocols for connected cars entering European markets. Stuttgart and Munich manufacturing clusters concentrate die-casting automation for aluminum shark-fin housings.
United States
Fleet procurement consolidation toward Samsara and Geotab specifications compresses vendor counts in long-haul trucking corridors. The FCC governs Part 25 licensing for mobile earth station terminals operating near Inmarsat and Starlink frequencies. Detroit-area engineering centers integrate RF frontend design with vehicle platform development cycles.
Japan
Toyota and Honda platforms drive specification authority for multi-constellation terminals with dedicated pre-certification requirements. The Ministry of Internal Affairs and Communications enforces stringent antenna efficiency benchmarks under Radio Law Article 38. Tokyo testing laboratories concentrate electromagnetic simulation capabilities for tier 1 antenna integrators.
China
Domestic electric vehicle platforms embed satellite functionality into next-generation architectures with localized supply chain preferences. The Ministry of Industry and Information Technology shapes equipment certification timelines for multi-band RF assemblies. Yangtze River Delta manufacturing bases concentrate LCP resin processing for RF-transparent housings.
Thailand
Japanese supplier captive operations achieve compressed cycle times on multi-cavity aluminum housings for shark-fin assemblies. The country's Board of Investment incentives support automotive electronics clustering for regional export markets. Bangkok-area industrial zones concentrate die-casting automation serving Asia-Pacific OEM supply chains.
Car Satellite Antenna Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform suppliers commanding OEM specification authority while component specialists capture aftermarket retrofit volumes. The vendor base organizes around three archetypes: European-headquartered phased-array module suppliers, Japanese multi-function antenna integrators with captive Asian manufacturing, and connector-centric platform providers merging RF and data interfaces. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as participants seek to compress homologation timelines and secure polymer feedstock security.
Among European-headquartered suppliers, Kathrein and Hirschmann occupy positions within the premium-tier phased-array segment, representing the archetype of direct OEM platform supply from regional manufacturing footprints. Harada and Yokowa anchor the Japanese specialist tier, exemplifying multi-function antenna integration with captive die-casting operations. Molex sits within the connector-integrated platform vector, merging FAKRA and HSD interfaces into consolidated roofline modules.
| Leading Market Players |
|---|
| Kathrein |
| ASK Industries |
| Molex |
| Inzi Controls |
| Northeast Industries |
| Harada |
| Hirschmann |
| Suzhong Antenna Group |
| Yokowa |
| Others |
Supply Flow & Price Mechanics
German premium OEM procurement teams concentrate specification authority for flagship electric vehicle platforms, anchoring a contract-based long-term offtake model that rewards multi-band certification and captive die-casting capacity.
Pricing Analysis
Volume-massive passive antennas for emerging market compact cars trade on thin margins, while active configurations with integrated low-noise amplifiers command customization premiums. Pricing stratifies across premium phased-array modules, standard shark-fin multi-function assemblies, and economy single-band GPS units. Cost compression in the passive tier intensifies as Thai manufacturing clusters achieve sub-minute cycle times on aluminum housings. Fleet management providers exhibit lowest price sensitivity due to unified connectivity contract bundling, whereas aftermarket installers face acute margin pressure from deepening factory-installed telematics penetration.
Supply Chain Analysis
China's MIIT domestic-content benchmarks for multi-band RF assemblies are reshaping sourcing patterns for LCP resin processing and phased-array module integration. Manufacturing gravity centers on Germany for premium OEM direct supply, Japan and Thailand for captive die-casting operations, and China for RF-transparent housing feedstock. The supply chain draws from Japanese chemical conglomerates for LCP resin, German engineering centers for metamaterial design, and Thai industrial zones for aluminum housing production. Single-source vulnerability concentrates in LCP polymer feedstock among three Japanese suppliers. Distribution runs through Tier 1 antenna integrators to OEM platform engineering teams, with fleet procurement consolidating toward telematics platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phased-array beam steering is displacing mechanical positioning hardware as the dominant antenna architecture, compressing roofline packaging requirements while expanding Ku-band throughput for broadband mobility services.
For Market Incumbents: Lock in backward integration into LCP resin supply through long-term offtake agreements with Japanese chemical conglomerates, insulating against force majeure risk while competitors queue for feedstock allocation. Expand captive electromagnetic simulation capabilities to compress homologation timelines for simultaneous FCC Part 25, EU RED, and Japan MIC approval cycles. Priority lever rests on securing ETSI EN 303 413 certification ahead of Cyber Resilience Act enforcement to capture first-mover margin pools in European market entry. For New Entrants and Emerging Players: Direct-to-fleet digital channels bypass fragmented aftermarket distributor networks, enabling specification capture with Samsara and Geotab as consolidated procurement gatekeepers in North American long-haul corridors. White-space concentration sits in India's commercial vehicle telematics retrofit below 15 percent penetration, where BS-VI compliance logging creates pull for single-band GPS units. Target aftermarket installers serving legacy fleet pools with amplified antenna bridge solutions for mid-range crossover applications. For Investors and Strategic Acquirers: The window for entry favors phased-array module specialists with metamaterial-enhanced flat panel capabilities and captive European manufacturing footprints. Long-term viability hinges on software-defined RF processing competence enabling constellation switching without hardware swaps. Acquisition target archetype: Tier 2 antenna integrators with electromagnetic simulation talent and pending multi-constellation homologation. Signal to watch: FCC rulings on 12 GHz band sharing between terrestrial 5G and satellite downlinks as inflection indicator for antenna architecture commitment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LCP Resin Supply | Secures RF-transparent polymer feedstock against Japanese chemical conglomerate concentration risk. |
| Phased-Array Platform Standardization | Enables German premium OEMs to specify metamaterial flat panels across multiple flagship electric vehicle lineups. |
| Cyber Resilience Act Certification Investment | Creates first-mover margin pools for ETSI EN 303 413 compliant antenna authentication protocols. |
| Fleet Telematics Platform Partnership | Consolidates specification authority with Samsara and Geotab as aftermarket distributor displacement accelerates. |
| Electromagnetic Simulation Capability Acquisition | Compresses homologation timelines for simultaneous FCC, EU RED, and Japan MIC multi-constellation approvals. |
Methodological Framework
Document review covered regulatory filings with the FCC, EU Radio Equipment Directive implementation guidance, and Japan MIC Radio Law Article 38 enforcement guidelines, complemented by interviews with OEM platform engineers, Tier 1 antenna integrator procurement leads, aftermarket distributor operations heads, and fleet telematics provider specification managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs trade records for LCP resin and aluminum housing flows, and SEC filings of listed automotive electronics suppliers. Bottom-up unit volume modeling triangulated against top-down market value estimates across the analysis window.
Historical shipment patterns for active, passive, amplified, and digital antenna configurations were cross-referenced against panel input from platform engineering teams at German premium OEMs and Japanese multi-function antenna integrators. Segmentation dimensions modeled included product type, application function, technology architecture, and end-user procurement authority, with vehicle class and propulsion architecture as automotive-specific overlays. CAGRs were derived from fitted growth curves anchored to disclosed OEM platform telematics penetration targets and LEO constellation densification timelines. Industry-specific forecast inputs incorporated die-casting automation cycle time improvements and spectrum reallocation proceeding status.
The model holds under stable regulatory enforcement timelines for Cyber Resilience Act and Radio Law Article 38 compliance; deviation in FCC 12 GHz band sharing rulings or LCP resin force majeure events would shift antenna architecture commitment cycles and feedstock availability assumptions. Forecasts reflect documented assumptions regarding phased-array cost curves and fleet procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
Motor Vehicle Sensor Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Electric Vehicle High-Voltage Cables Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Japan Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electronic Logging Device (ELD/E-Log) Market
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market