

Switchrack Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Switchrack Assemblies Market Insights
Project finance tied to data center infrastructure rollouts is tilting competitive access toward capitalized electrical equipment suppliers. Eaton leverages its integrated power distribution portfolio to bundle switchrack assemblies with upstream switchgear, reducing procurement friction for large facility operators. Schneider Electric anchors its position through factory-automated enclosure production that compresses lead times for modular configurations. Powell Industries competes on custom-engineered switchracks for harsh-environment utility and industrial substations where standard catalog products fail.
Switchrack assemblies are structural mounting frameworks that organize electrical switches, circuit breakers, and cabling termination points within standardized enclosure footprints, typically fabricated from cold-rolled steel or aluminum with powder-coated finishes rated for NEMA 4X or IP65 ingress protection. These assemblies serve the primary purpose of consolidating power distribution and network interconnection hardware into serviceable, thermally managed layouts for mission-critical facilities. Horizontal switchracks dominate data center deployments where low-profile overhead clearance favors lateral equipment arrangement, while modular switchracks represent the fastest-expanding category as operators adopt disaggregated infrastructure that permits incremental capacity additions without full rack replacement. Copper cabling technology sustains the largest installed base despite fiber optic penetration in hyperscale backbone applications, since hybrid cabling configurations capture growing preference among enterprises balancing cost and bandwidth headroom.
The National Electrical Manufacturers Association publishes enclosure and wiring standards that directly dictate switchrack dimensional tolerances, material gauges, and busbar ampacity ratings across North American installations. IEC 61439 series standards govern low-voltage switchgear assemblies in Europe and Asia-Pacific export markets, creating dual-certification burdens for multinational suppliers. OSHA electrical safety regulations and the EU's RoHS substance restrictions further constrain component sourcing and surface treatment processes. Stakeholders must monitor evolving efficiency mandates from the EPA and EU Ecodesign frameworks that will likely embed standby-loss limits into switchrack-integrated power distribution specifications.
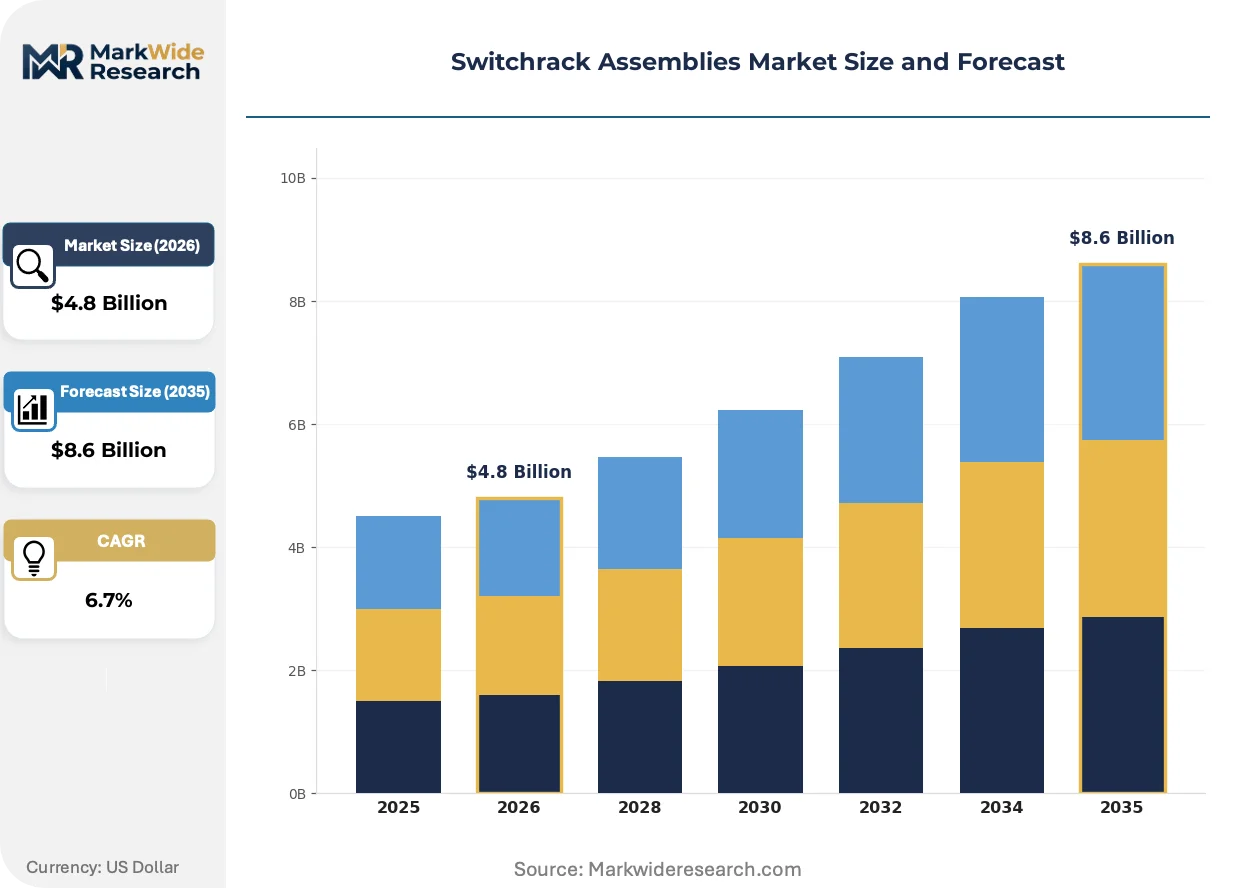
Market Dynamics
Hyperscale cloud operators are consolidating procurement power around modular, disaggregated infrastructure architectures, forcing switchrack manufacturers to abandon fixed-configuration catalog products in favor of incrementally scalable platforms that align with edge computing deployment cycles.
Growth Catalysts
- Edge Computing Infrastructure:Data hosting facilities are expanding procurement of modular switchrack configurations to support distributed computing nodes closer to end-users, reducing latency for real-time applications.
- Seismic Load Standards:NEMA and IEC standards tightening fire-resistance and seismic-load requirements are forcing design upgrades that favor engineered switchrack assemblies over commodity electrical enclosures.
- Copper Hybrid Cabling:Enterprise data centers balancing cost and bandwidth headroom are driving specification intensity for switchracks supporting hybrid copper-fiber termination architectures.
Market Restraints
- Cold-Rolled Steel Input Volatility:Fluctuations in steel pricing and mill capacity constrain margin predictability for powder-coated enclosure fabrication.
- Dual-Certification Burden:Manufacturers serving multinational operators face redundant testing costs from simultaneous NEMA enclosure standards and IEC 61439 low-voltage switchgear compliance requirements.
- Prefabricated Modular Substations:Utility-scale buyers are substituting traditional switchrack assemblies with fully integrated power modules that compress on-site installation labor.
Strategic Opportunities
- India Data Center Buildout:The country's national electrical regulator CEA is streamlining power infrastructure approvals, creating procurement windows for IEC-certified modular switchrack suppliers.
- AI Training Clusters:Liquid-cooled switchrack configurations converging with thermal management systems capture specification opportunities in high-density GPU server deployments.
- Direct-to-Site Distribution:Bypassing traditional electrical distributor channels through factory-direct logistics reduces lead times for hyperscale operators with consolidated purchasing functions.
Industry Challenges
- Busbar Ampacity Engineering Talent:Shortages of designers fluent in both thermal modeling and short-circuit withstand ratings delay custom switchrack development cycles.
- RoHS Surface Treatment Conversion:EU substance restrictions on hexavalent chromium coatings force capital-intensive retooling of powder-coating and plating lines without immediate pricing recovery mechanisms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
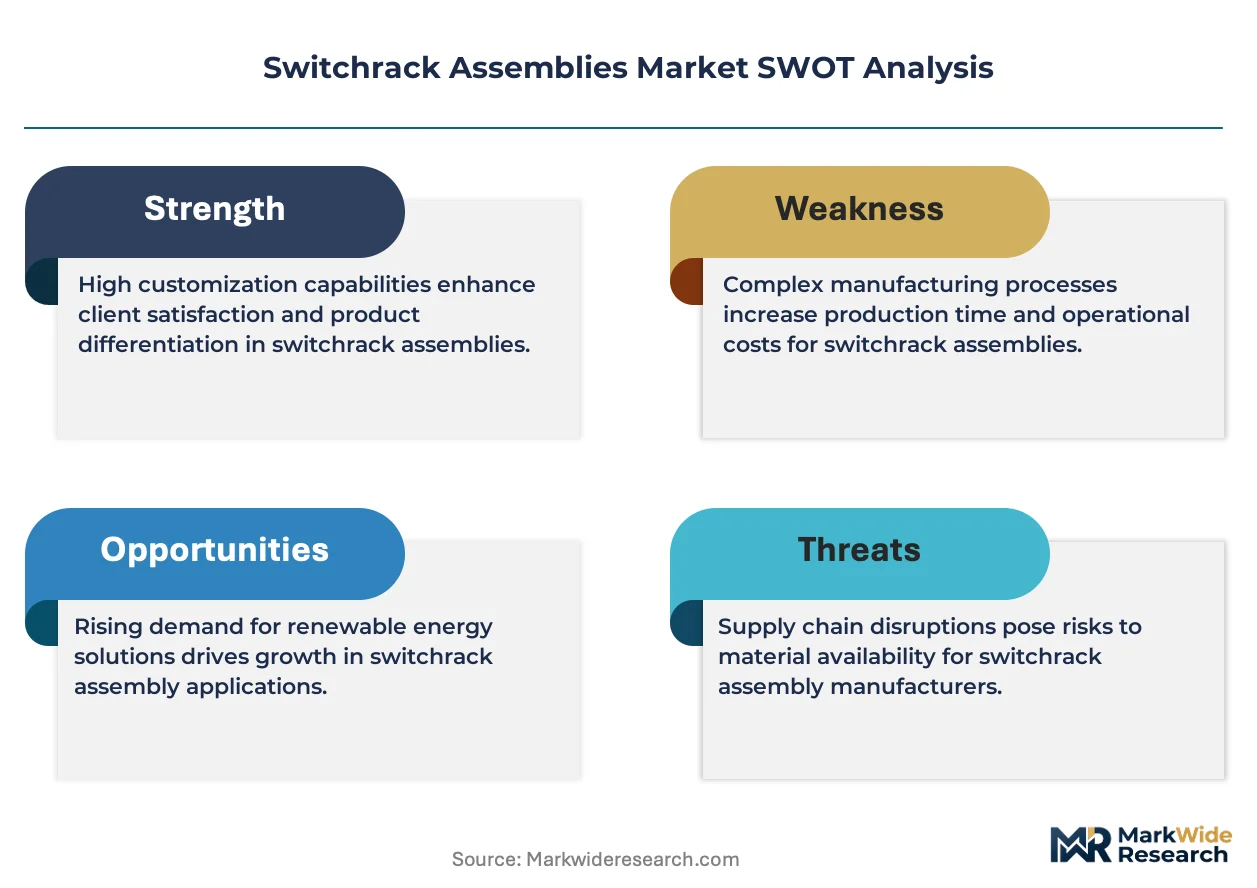
Switchrack Assemblies Market Trends and Innovations
Active cooling integration and intelligent power monitoring are compressing the traditional separation between structural mounting hardware and electrical distribution intelligence, collapsing procurement categories that buyers previously sourced independently.
Busbar-based power distribution modules with integrated current monitoring are rendering obsolete conventional cable-and-lug termination methods in hyperscale facilities. Cloud operators in the United States are specifying these assemblies for rapid deployment phases. The technology is rendering obsolete the practice of field-terminating individual feeder cables to rack-mounted breakers.
REACH substance restrictions and the EU Ecodesign framework are embedding standby-loss limits into switchgear specifications, forcing enclosure manufacturers to validate thermal performance under loaded conditions. Suppliers serving European data center operators are redesigning airflow pathways to meet efficiency mandates. The regulations most affect aluminum enclosure fabricators substituting steel to reduce weight.
Consolidated specification authority among hyperscale engineering teams is collapsing the traditional distributor-specifier relationship in electrical infrastructure procurement. Large facility operators now issue direct factory contracts for modular switchrack platforms, bypassing regional electrical distributors. This pattern concentrates most visibly in the United States where cloud provider capital expenditure cycles dominate demand timing.
Switchrack Assemblies Market Segmentation
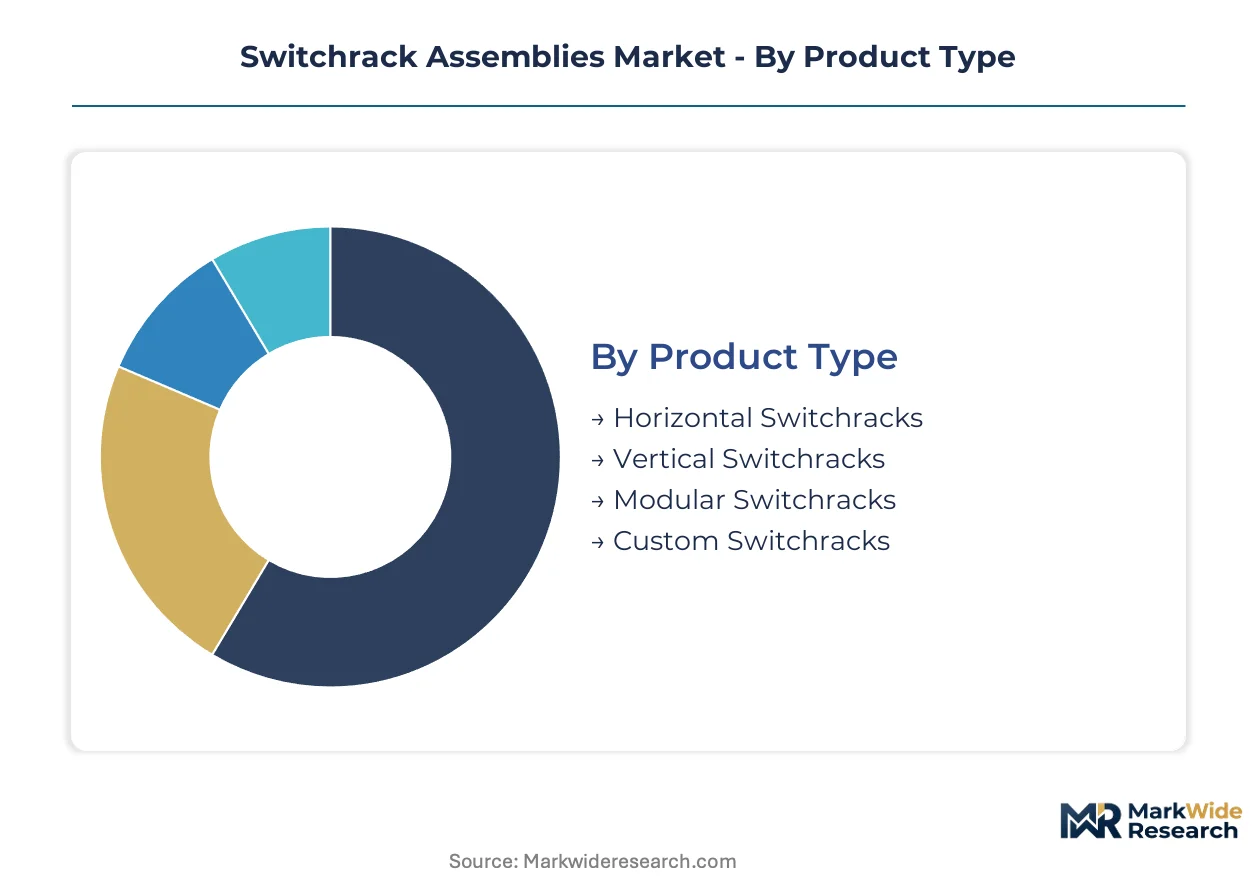
Switchrack assembly configurations fragment across mounting orientation, connectivity technology, facility application, and buyer industry vertical. Procurement patterns diverge sharply between hyperscale cloud operators seeking standardized modular platforms and industrial substation engineers demanding custom-engineered seismic-rated enclosures.
Product Type:
Mature horizontal formats dominate legacy data center footprints while emerging modular architectures capture specification intensity from edge computing rollouts.
- Horizontal Switchracks:Low-profile lateral mounting frameworks optimize for constrained overhead clearance in raised-floor environments. Hyperscale cloud operators in the United States specify these for rapid deployment phases where standardized aisle widths predominate.
- Modular Switchracks:Disaggregated structural platforms permit incremental capacity additions without full rack replacement. Data hosting facilities expanding edge computing nodes favor these configurations for distributed infrastructure closer to end-users.
- Vertical Switchracks:Floor-to-ceiling mounting density serves telecommunication central offices with limited horizontal footprint.
- Custom Switchracks:Engineer-to-order enclosures address harsh-environment utility substations where NEMA 4X and seismic-load requirements exceed catalog specifications.
Horizontal switchracks handle the majority of throughput; modular switchracks are the fastest mover on share.
Technology:
Cost tier stratification separates premium fiber deployments from copper-dominant enterprise budgets, with hybrid configurations bridging the gap.
- Copper Cabling:Twisted-pair and coaxial termination hardware sustains the largest installed base despite fiber penetration. IT enterprises balancing cost and bandwidth headroom drive specification intensity for copper-compatible busbar configurations.
- Hybrid Cabling:Integrated copper-fiber termination architectures capture preference among data center operators managing mixed infrastructure generations. Cloud infrastructure buildouts in the United States specify these for transitional backbone deployments.
- Fiber Optic:Single-mode and multimode termination panels serve hyperscale backbone applications demanding terabit-scale throughput.
- Wireless Connectivity:Integrated antenna mounting and power-over-ethernet backhaul supports telecommunication network densification.
Copper cabling handles the majority of throughput; hybrid cabling is climbing the fastest on specification intensity.
Application:
Volume concentration tracks capital expenditure cycles among facility types with divergent redundancy and density requirements.
- Data Centers:Enterprise and colocation facilities deploy standardized switchrack configurations for power distribution and network interconnection. Data hosting facilities expanding procurement drive specification intensity for thermally managed, serviceable layouts.
- Cloud Infrastructure:Hyperscale operator direct procurement favors modular platforms aligned with disaggregated server deployment cycles. United States-based cloud providers concentrate demand timing through consolidated factory contracts.
- Telecommunication Networks:Central office and cell site upgrades specify switchracks for legacy copper-to-fiber transition.
- Network Security Systems:Segmented power zones and physical access controls govern specialized enclosure requirements.
Data centers handle the majority of throughput; cloud infrastructure is gaining share fastest from direct procurement consolidation.
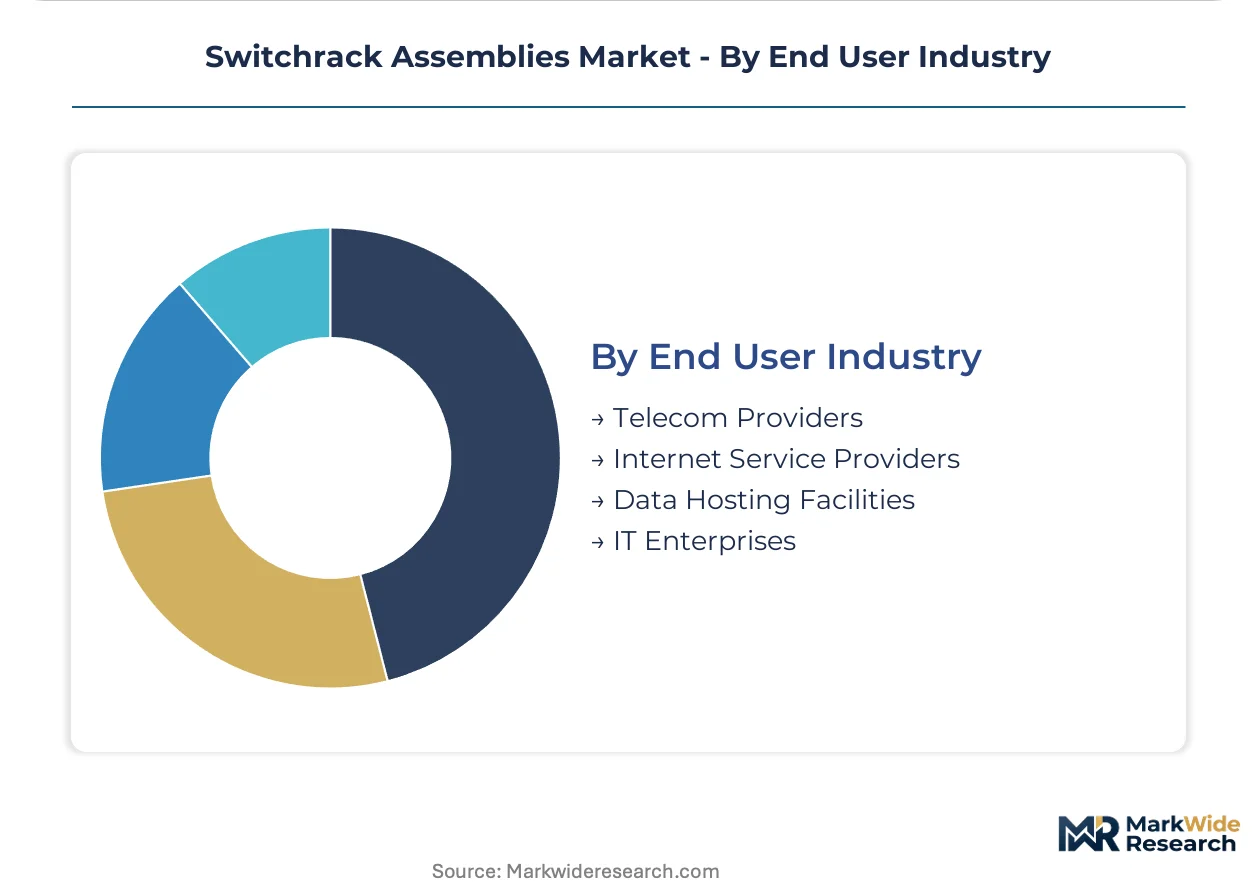
End User Industry:
Customer type determines specification authority, with consolidated engineering teams bypassing traditional distributor channels.
- Data Hosting Facilities:Colocation and cloud operators exercise direct factory contracting for modular switchrack platforms. These buyers issue consolidated specifications spanning multiple facility locations, compressing procurement cycles.
- Telecom Providers:Incumbent carriers and mobile network operators mandate dual NEMA-IEC certification for multinational infrastructure consistency. These procurement patterns face redundant testing costs from simultaneous compliance requirements.
- Internet Service Providers:Regional fiber overbuilders specify cost-optimized configurations for metro network expansion.
- IT Enterprises:Corporate data center operators balance legacy copper infrastructure with selective fiber upgrades.
Data hosting facilities handle the majority of throughput; telecom providers are expanding specification fastest from edge infrastructure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Germany and Japan supply switchrack assemblies to data center operators across North America and Asia-Pacific, while the United States runs a structural import deficit in specialized enclosure fabrication. Trade flows concentrate around IEC-certified production hubs serving multinational cloud infrastructure contracts.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth drive specification intensity for high-density busbar configurations. OSHA electrical safety regulations and NEMA enclosure standards govern procurement requirements for mission-critical facilities. Direct factory contracting is displacing traditional electrical distributor channels among consolidated engineering teams.
Germany
Industrial machinery OEMs and automotive battery gigafactories demand seismic-rated custom switchracks for harsh-environment substations. REACH substance restrictions and the EU Ecodesign framework mandate thermal performance validation under loaded conditions. Factory-automated enclosure production in Baden-Württemberg compresses lead times for modular configurations.
China
Domestic cloud providers and state-owned telecom operators are expanding procurement of IEC-certified modular platforms for edge computing nodes. MIIT standards and GB certification requirements create compliance thresholds for low-voltage switchgear assemblies. Yangtze River Delta fabricators serve both domestic demand and export markets across Southeast Asia.
India
Data center buildouts in Mumbai and Chennai are accelerating procurement of copper-hybrid cabling switchracks for transitional backbone deployments. The Central Electricity Authority is streamlining power infrastructure approvals, creating procurement windows for IEC-certified suppliers. Domestic manufacturers in Gujarat and Karnataka are scaling powder-coated enclosure production to capture import substitution opportunities.
Japan
Telecom central office upgrades and semiconductor fabrication facilities specify vertical switchracks for constrained horizontal footprints. METI efficiency mandates and JIS enclosure standards dictate material gauges and busbar ampacity ratings. Kanto region engineering firms integrate thermal modeling with short-circuit withstand ratings for custom-engineered configurations.
Switchrack Assemblies Market Competitive Landscape
On the supply side, the industry is consolidating around integrated power distribution portfolios that bundle switchrack assemblies with upstream electrical infrastructure. Tiered competitive positioning separates capitalized multinational suppliers from regional specialists focused on custom-engineered seismic-rated enclosures. Three archetypes dominate: diversified electrical equipment conglomerates with factory-direct logistics capabilities, modular enclosure specialists serving hyperscale procurement cycles, and harsh-environment engineering firms addressing utility substation requirements. Dominant competitive moves include backward integration into cold-rolled steel fabrication and strategic partnerships with thermal management system providers for liquid-cooled configurations.
Within the diversified electrical equipment tier, Eaton and Schneider Electric exemplify capitalized suppliers leveraging integrated power distribution portfolios to reduce procurement friction for large facility operators. Powell Industries occupies a position among custom-engineered specialists, representing the archetype of firms addressing utility and industrial substations where standard catalog products fail seismic-load and fire-resistance requirements.
| Leading Market Players |
|---|
| Eaton |
| Schneider Electric |
| ABB |
| Siemens |
| Powell Industries |
| Rockwell Automation |
| Legrand |
| Hubbell |
| Emerson |
| Others |
Pricing and Supply Chain Analysis
Cold-rolled steel mill concentration in China and India dictates margin distribution across switchrack assembly tiers, with powder-coating and busbar fabrication capturing value downstream from commodity metal inputs. Buyers with consolidated hyperscale procurement functions extract pricing concessions through volume commitments and factory-direct logistics, while custom-engineered seismic-rated configurations retain premium positioning through engineer-to-order scarcity.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with hyperscale cloud operators commanding the deepest volume discounts through consolidated factory contracts. Price differentiation rests on certification tier (NEMA 4X versus IP65 baselines) and customization depth for seismic-load engineering. Cost compression in standard catalog products is intensifying because of prefabricated modular substation substitution. Regional electrical distributors exhibit highest price sensitivity as direct procurement channels displace their intermediary role.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for enclosure fabricators serving North American data center operators. Manufacturing concentrates in China's Yangtze River Delta, Germany's Baden-Württemberg, and India's Gujarat for IEC-certified production. Cold-rolled steel, copper busbar, and powder-coat chemicals constitute critical input dependencies. Distribution runs through factory-direct logistics for hyperscale buyers and regional electrical distributors for fragmented enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switchrack assembly demand tracks data center capital expenditure cycles, with edge computing infrastructure buildouts signaling cyclical recovery momentum across the analysis window.
For Market Incumbents: Entrench factory-automated enclosure production capabilities to compress lead times for modular configurations against emerging regional specialists. Capture backward integration into cold-rolled steel fabrication to insulate margin pools from commodity volatility. Prioritize IEC-NEMA dual-certification investment to defend multinational cloud infrastructure contracts from compliance-weak competitors. For New Entrants and Emerging Players: Establish a beachhead in India's data center buildout corridor by securing CEA streamlined approval pathways for IEC-certified modular platforms. Target copper-hybrid cabling switchracks for transitional backbone deployments where incumbent catalog products lack specification flexibility. Pursue direct-to-site distribution partnerships with regional fiber overbuilders bypassing traditional electrical distributor channels. For Investors and Strategic Acquirers: Capital is best deployed toward custom-engineered specialists with seismic-rated enclosure capabilities and utility substation relationships, as hyperscale standardization squeezes commodity switchrack margins. Monitor liquid-cooled switchrack specification intensity in AI training clusters as the inflection signal for thermal-converged platform viability. Long-term viability favors suppliers integrating active cooling and intelligent power monitoring into structural hardware.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Fabrication | Captive cold-rolled steel supply insulates margin pools from Yangtze River Delta mill volatility. |
| Dual-Certification Investment | Simultaneous NEMA and IEC compliance unlocks multinational cloud operator procurement consolidation. |
| Liquid-Cooled Configuration Development | Thermal convergence with GPU server deployments captures specification in AI training clusters. |
| Direct-to-Site Logistics Expansion | Factory-direct distribution bypasses electrical distributor channels for hyperscale buyers. |
| Edge Computing Modular Platform Launch | Disaggregated architectures align with distributed infrastructure deployment cycles closer to end-users. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center engineering directors, electrical contractor procurement leads, enclosure fabrication plant managers, and utility substation specification engineers. Secondary validation drew from NEMA standards documentation, IEC 61439 certification registries, OSHA electrical safety filings, and hyperscaler capital expenditure disclosures. Bottom-up shipment data triangulated against top-down facility construction permits across the analysis window.
Calibration against historical capacity utilization rates and order backlog trends anchored the projection framework across product type, connectivity technology, facility application, and end-user industry verticals. CAGRs were derived from segmented growth rate reconciliation with aggregate market expansion. Edge computing deployment timelines, seismic standard upgrade cycles, and copper-fiber transition patterns served as industry-specific forecast inputs throughout the modeling period.
Stress conditions across steel input volatility, dual-certification cost inflation, and prefabricated substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscale procurement consolidation and regulatory efficiency mandate trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.