
 Africa and Middle East Automotive Tpms Market | 2026-2036
Africa and Middle East Automotive Tpms Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Automotive Tpms Market Outlook
Tire sensor manufacturing capacity across North Africa and the Levant is restructuring as regional assemblers localize procurement to avoid currency volatility and import duties. Continental AG leverages its integrated sensor-to-software pipeline to dominate OEM supply contracts with European-brand plants in Morocco and South Africa. Sensata Technologies anchors aftermarket channels through distributor partnerships spanning Nigeria, Kenya, and Egypt. Schrader Electronics competes on Bluetooth-enabled direct TPMS modules designed for GCC heat tolerance.
Automotive TPMS comprises pressure monitoring sensors, receiver units, and dashboard indicators that transmit real-time tire inflation data to drivers, typically operating at 433 MHz radio frequency with lithium coin-cell power sources lasting five to ten years. The system's primary purpose is preventing blowouts, extending tire life, and optimizing fuel consumption across commercial and passenger vehicle fleets. Direct TPMS leads unit shipments due to regulatory mandates requiring absolute pressure readings, while IoT Integration represents the fastest-expanding technology segment as telematics providers embed tire data into fleet management platforms. Sensor-Based systems retain the largest installed base but face margin compression from commoditized hardware.
Gulf Standardization Organization (GSO) regulations and Saudi Standards, Metrology and Quality Organization (SASO) technical requirements mandate TPMS fitment on new vehicle categories, directly expanding addressable volume for OEM and fleet channels. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces UN ECE R64-aligned tire safety standards that shape product certification costs and market entry timelines. Stakeholders must monitor evolving type-approval harmonization between GCC states and sub-Saharan African economic communities to anticipate procurement specification divergence or convergence.
Market Dynamics
Fleet digitization across the Gulf Cooperation Council is compressing replacement cycles for tire pressure monitoring hardware as logistics operators integrate real-time tire data into centralized telematics dashboards. This structural pull is overriding traditional aftermarket purchasing patterns rooted in passive maintenance schedules.
Growth Catalysts
- SASO Technical Requirements:Saudi Arabia's mandated TPMS fitment on new commercial vehicle categories is forcing OEMs to pre-install direct sensor systems at factory gates, eliminating retrofit lag and expanding first-fit volume.
- Heat-Tolerant Materials:Advancements in ceramic-coated pressure transducers and high-temperature lithium thionyl chloride cells are extending sensor operational life beyond 150°C ambient thresholds common in Gulf summer conditions.
- Fleet Consolidation:Large logistics operators across the UAE and Saudi Arabia are centralizing procurement under enterprise maintenance contracts that specify TPMS as standard equipment across tractor-trailer combinations.
Market Restraints
- Currency Volatility:Egyptian and Nigerian importers face working capital strain as tire sensor procurement denominated in euros or dollars encounters local currency depreciation against import payment obligations.
- Receiver Unit Concentration:Dashboard-integrated receiver manufacturing concentrates in East Asian electronics clusters, exposing regional assemblers to semiconductor lead-time volatility and freight cost spikes.
- Indirect TPMS Substitution:Wheel-speed-based indirect systems continue to satisfy minimum regulatory thresholds in price-sensitive North African passenger vehicle segments, limiting direct sensor penetration.
Strategic Opportunities
- Kenyan Logistics Corridor:The Northern Corridor transit route connecting Mombasa to Kampala and Kigali offers untapped aftermarket potential as regional freight operators modernize tire maintenance protocols for long-haul efficiency.
- Telematics Convergence:Integration of tire pressure data with GPS tracking and predictive maintenance algorithms is creating new subscription revenue streams for fleet software providers serving Saudi petrochemical transport fleets.
- GSO Harmonization:Pending Gulf Standardization Organization alignment on TPMS type-approval testing protocols would streamline cross-border certification and reduce duplicate compliance costs for suppliers serving multiple GCC markets.
Industry Challenges
- RF Calibration Expertise:Shortage of technicians trained in 433 MHz radio frequency pairing procedures and sensor ID reprogramming is extending service bay times at independent garages across Morocco and Tunisia.
- Legacy Fleet Integration:Retrofitting direct TPMS onto commercial vehicles with analog dashboard architectures requires custom wiring harness fabrication, complicating deployment at scale for older Saudi and Egyptian truck populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Automotive Tpms Market |
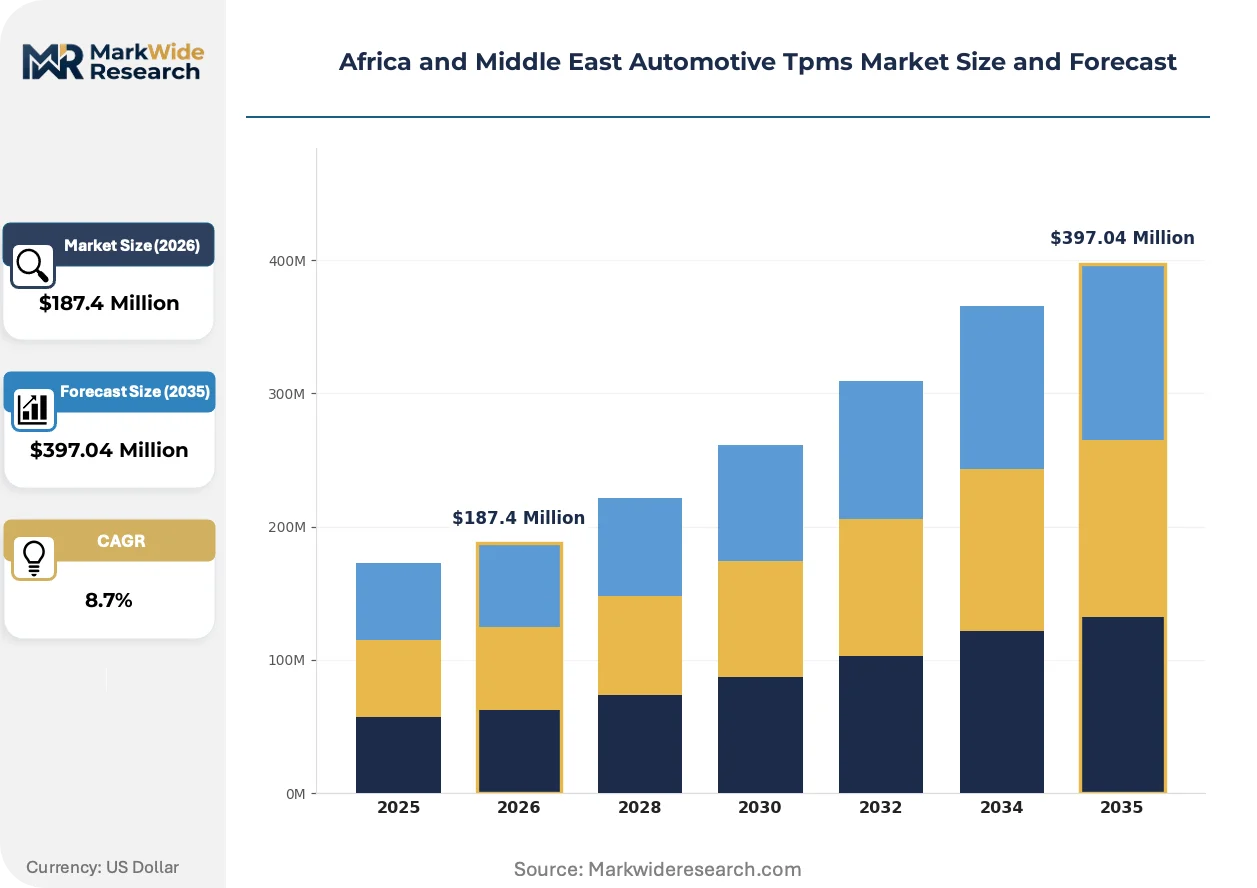
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct TPMS, Indirect TPMS, Hybrid TPMS, Wireless TPMS Technology: Sensor-Based, Advanced Driver Assistance Systems, Bluetooth Connectivity, IoT Integration End User: OEMs, Aftermarket, Fleet Operators, Vehicle Manufacturers Distribution Channel: Online Retail, Specialty Stores, Dealerships, Distributors |
| Companies Covered | Continental AG, Sensata Technologies, Schrader Electronics, ZF Friedrichshafen AG, Pacific Industrial, DENSO Corporation, Huf Hülsbeck & Fürst GmbH & Co. KG, PressurePro, Valeo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Automotive Tpms Market Strategic Shifts
Hardware commoditization is forcing suppliers to differentiate through embedded software capabilities and predictive analytics rather than sensor precision alone. This shift is elevating data platform vendors alongside traditional component manufacturers in customer purchasing decisions.
Bluetooth Low Energy direct TPMS modules are expanding into heavy-duty commercial applications previously reserved for proprietary RF protocols. Mining operators in South Africa and quarry fleets in the UAE are piloting these sensors for their simplified smartphone-based diagnostics and reduced infrastructure requirements. The technology is expanding into fleet management ecosystems by enabling tire pressure alerts to flow directly into driver mobile applications without dedicated receiver hardware.
Gulf Standardization Organization technical committees are tightening electromagnetic compatibility testing requirements for TPMS units operating in dense RF environments typical of Dubai and Riyadh urban corridors. This regulatory pressure is filtering out lower-tier suppliers lacking in-house EMC validation capabilities while accelerating certification investments from established manufacturers. Aftermarket distributors serving Kuwait and Qatar are adjusting procurement specifications to preempt compliance gaps.
Logistics buyers are consolidating tire maintenance spend under outcome-based contracts that penalize suppliers for pressure-related downtime rather than purchasing sensors as capital items. This purchasing model is displacing traditional distributor relationships in Saudi long-haul and UAE last-mile segments. The shift is most visible among temperature-controlled freight operators where tire failure carries cargo spoilage liability beyond direct vehicle recovery costs.
Africa and Middle East Automotive Tpms Market Segmentation
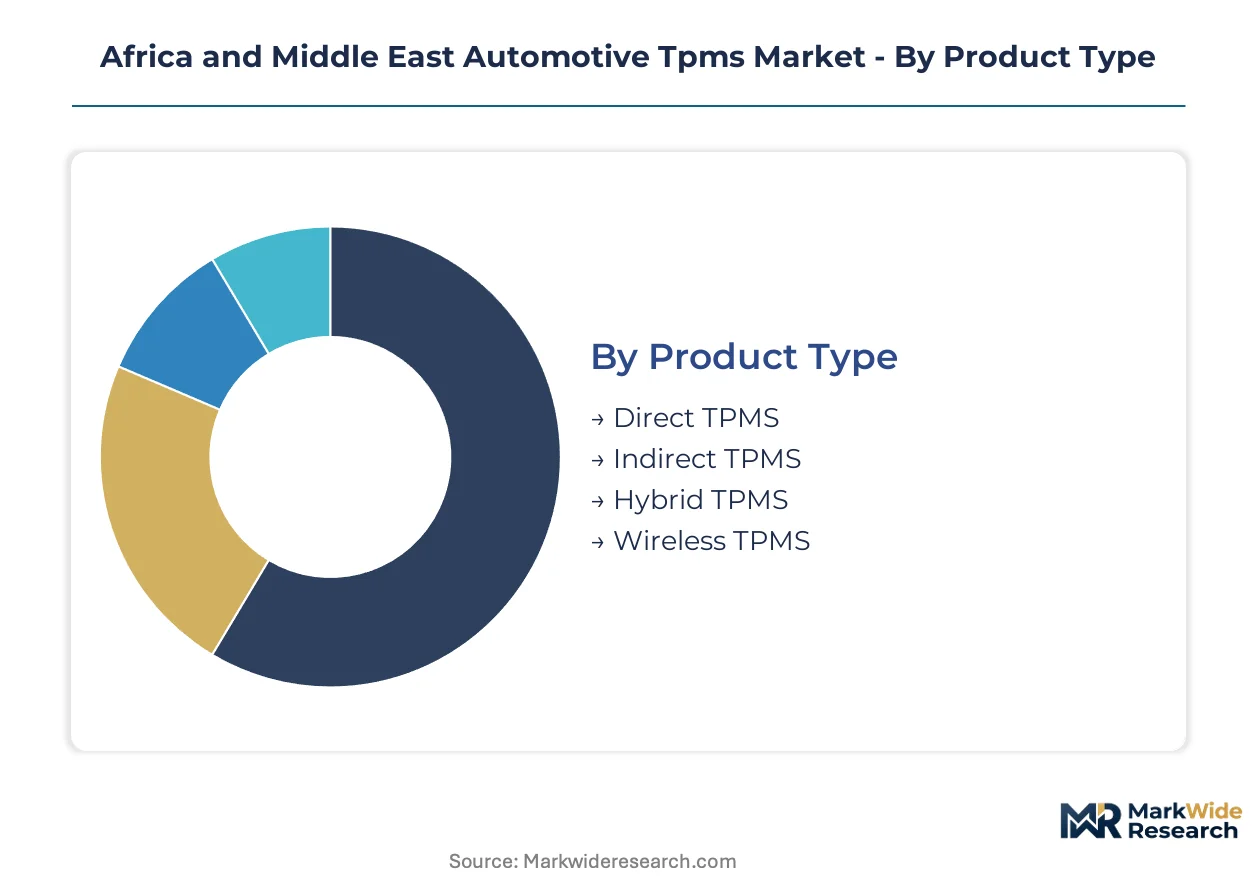
Segmentation in the Africa and Middle East Automotive TPMS Market reveals distinct procurement patterns across regulatory environments and fleet maturity levels. Product architecture choices diver sharply between Gulf Cooperation Council mandates and North African price sensitivity. Technology adoption curves separate telematics-integrated operators from passive maintenance cultures.
Product Type:
Standardization dominates at the regulatory floor while customization proliferates in fleet-specific deployments across this category.
- Direct TPMS:Pressure sensors mounted inside each wheel transmit absolute inflation readings via 433 MHz radio frequency to dashboard receivers. Saudi petrochemical transport fleets and UAE cold-chain operators mandate these systems under enterprise maintenance contracts that penalize pressure-related downtime. Leading the category by volume: Direct TPMS. Growing fastest: Hybrid TPMS.
- Indirect TPMS:Wheel-speed differential algorithms estimate pressure loss through ABS sensor data without dedicated hardware. Moroccan and Tunisian passenger vehicle assemblers specify these systems to meet minimum UN ECE R64-aligned thresholds while preserving bill-of-material cost positions.
- Hybrid TPMS:Combines wheel-speed monitoring with simplified pressure reference sensors to bridge cost and compliance requirements. Nigerian commercial vehicle retrofitters favor this architecture for legacy fleet upgrades facing currency-constrained procurement budgets.
- Wireless TPMS:Eliminates wired receiver connections through integrated RF transceiver modules. South African mining operators pilot these units for reduced installation complexity in severe-service environments.
Direct TPMS commands the largest installed base. Hybrid architectures are climbing the fastest as fleet operators balance compliance depth against total cost of ownership.
Technology:
Cost tier stratification separates commoditized hardware from software-enabled premium positioning in this dimension.
- Sensor-Based:Discrete pressure transducers with lithium thionyl chloride power cells dominate unit economics but face margin compression from Asian component suppliers. Egyptian and Kenyan distributors stock these modules in volume for independent garage channels serving price-sensitive passenger vehicle owners.
- Advanced Driver Assistance Systems:Tire pressure data feeds into centralized vehicle safety computers for automated braking and stability interventions. European-brand assembly plants in Morocco and South Africa specify ADS-integrated TPMS to maintain platform commonality with parent company architectures.
- Bluetooth Connectivity:Low-energy protocols enable smartphone-based diagnostics without dedicated dashboard hardware. UAE last-mile delivery fleets and South African quarry operators deploy these sensors to reduce infrastructure requirements and accelerate driver-level alert response.
- IoT Integration:Real-time pressure streams feed predictive maintenance algorithms within fleet telematics platforms. Saudi long-haul logistics operators and UAE temperature-controlled freight carriers generate subscription revenue from tire data embedded in centralized dashboards. Volume concentration rests with Sensor-Based systems. IoT Integration is gaining share fastest.
Sensor-Based systems retain volume leadership. IoT Integration exhibits the steepest expansion trajectory as fleet digitization compresses replacement cycles.
End User:
Customer type determines specification authority and purchasing rhythm across this segmentation dimension.
- OEMs:Factory-fit mandates from SASO and GSO regulations eliminate retrofit lag for new commercial vehicle categories. European-brand plants in Morocco and South Africa source through integrated sensor-to-software pipelines to maintain platform consistency.
- Aftermarket:Independent distributors serve replacement demand from vehicle owners outside warranty coverage. Sensata Technologies anchors this channel through partnerships spanning Nigeria, Kenya, and Egypt.
- Fleet Operators:Enterprise procurement centralizes tire maintenance spend under outcome-based contracts. Large logistics operators across Saudi Arabia and the UAE specify TPMS as standard equipment across tractor-trailer combinations. Aftermarket channels move the most units. Fleet Operators are expanding most quickly.
- Vehicle Manufacturers:Regional assemblers localize procurement to avoid currency volatility and import duties, restructuring North African and Levant manufacturing capacity.
Aftermarket dominates transaction volume. Fleet Operators are expanding most quickly as enterprise maintenance contracts displace traditional distributor relationships.
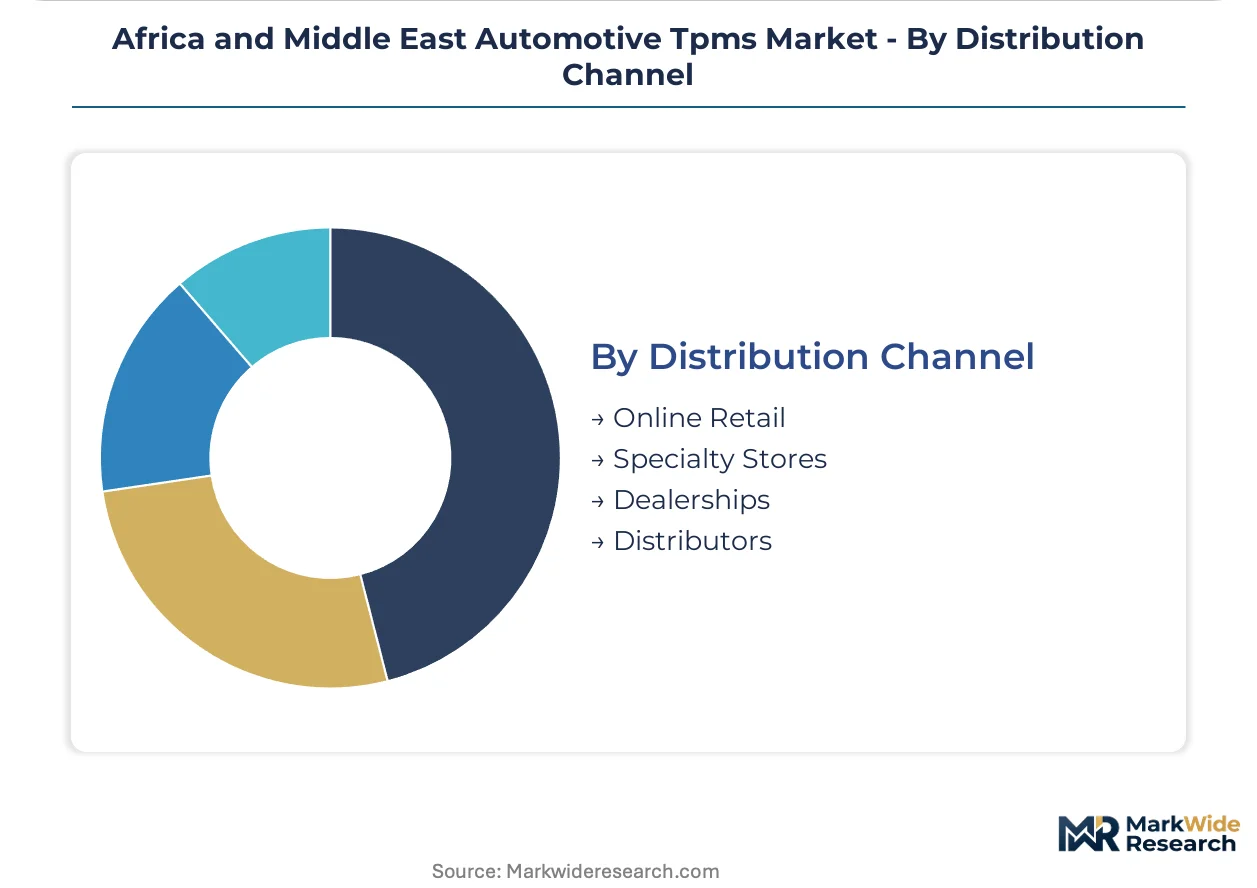
Distribution Channel:
Geography and customer scale determine channel preference across this final segmentation layer.
- Online Retail:E-commerce platforms serve dispersed independent garages and owner-operators with standardized sensor SKUs. Kenyan and Nigerian buyers leverage digital channels to bypass import duty stacking through traditional distributor tiers.
- Specialty Stores:Focused tire and automotive electronics retailers provide RF calibration expertise and sensor ID reprogramming services. Shortage of 433 MHz-trained technicians extends service bay times at independent garages across Morocco and Tunisia.
- Dealerships:Authorized service networks handle warranty-compliant replacements for OEM-installed systems. European-brand dealership channels in South Africa and Morocco maintain proprietary diagnostic tool compatibility.
- Distributors:Regional wholesalers aggregate procurement for multi-site fleet operators and independent repair networks. Kuwait and Qatar distributors are adjusting specifications to preempt GSO electromagnetic compatibility compliance gaps. Distributors command the largest volume. Online Retail is climbing the fastest.
Distributors maintain volume leadership. Online Retail channels are expanding most quickly as procurement digitization penetrates price-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
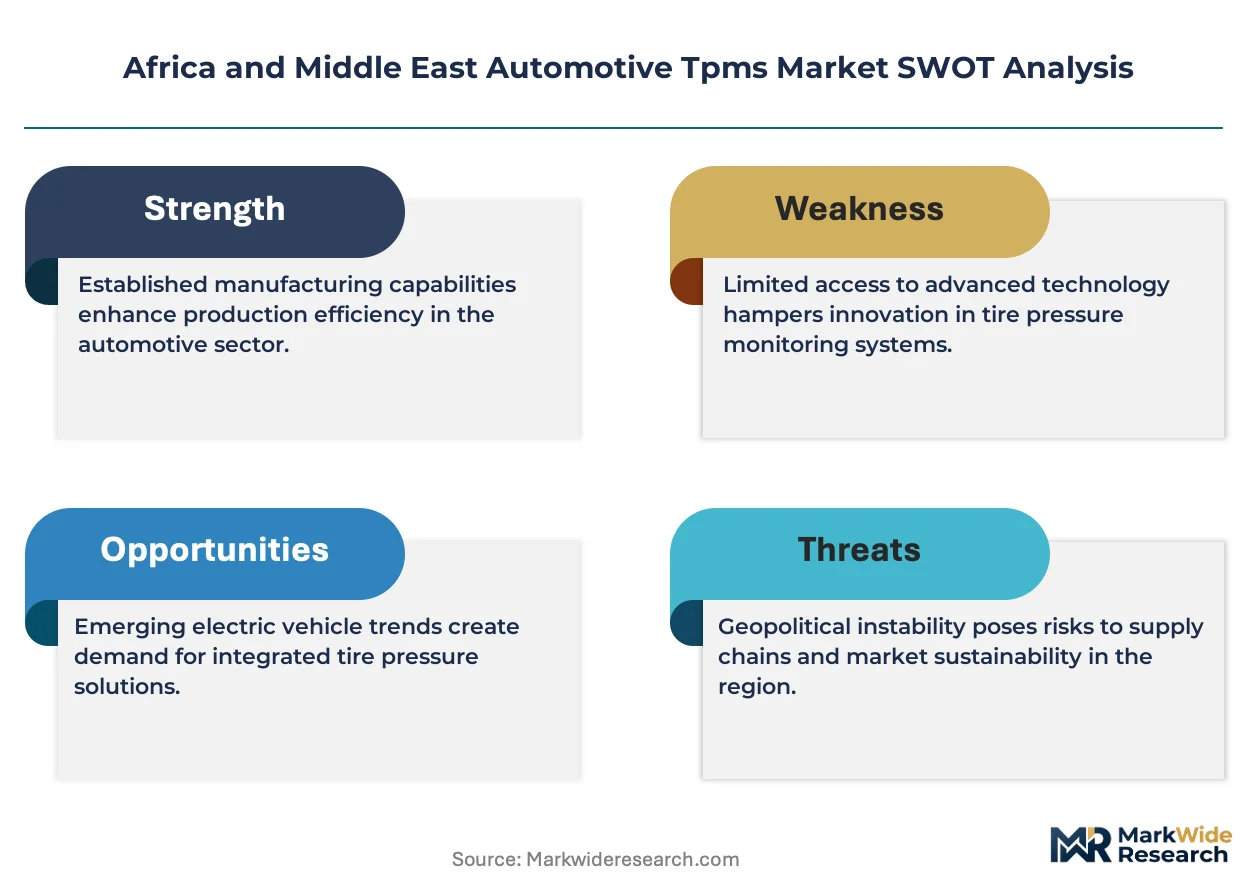
Lithium thionyl chloride cell production concentrates in East Asian chemical clusters, yet Gulf-based logistics operators and North African assemblers anchor regional TPMS demand through fleet digitization mandates and localized procurement restructuring.
Saudi Arabia
Petrochemical transport fleets and long-haul logistics operators generate concentrated demand for heat-tolerant direct TPMS hardware. SASO technical requirements mandate factory-fit systems on new commercial vehicle categories, eliminating retrofit lag for OEM channels. Riyadh-based fleet operators centralize tire maintenance spend under outcome-based contracts that penalize pressure-related downtime.
United Arab Emirates
Temperature-controlled freight carriers and last-mile delivery fleets drive adoption of Bluetooth-enabled sensors for smartphone-based diagnostics. Dubai's dense RF environment pushes GSO electromagnetic compatibility testing requirements tighter, filtering suppliers lacking in-house validation capabilities. Jebel Ali logistics corridors anchor enterprise procurement centralization across tractor-trailer combinations.
South Africa
European-brand assembly plants in the Eastern Cape and Gauteng source through integrated sensor-to-software pipelines to maintain platform consistency with parent company architectures. NRCS enforces UN ECE R64-aligned tire safety standards that shape product certification costs. Mining operators in the platinum belt pilot wireless TPMS units for reduced installation complexity in severe-service environments.
Morocco
Passenger vehicle assemblers specify indirect TPMS systems to meet minimum regulatory thresholds while preserving bill-of-material cost positions. Tangier Med automotive export platforms drive localization of tire sensor procurement to avoid currency volatility and EU import duty exposure. Casablanca-based distributors face technician shortages trained in 433 MHz radio frequency pairing procedures.
Nigeria
Commercial vehicle retrofitters favor hybrid TPMS architectures for legacy fleet upgrades facing currency-constrained procurement budgets. Lagos port corridors anchor aftermarket distributor networks serving Northern Corridor transit routes. Central Bank foreign exchange rationing strains working capital for euro-denominated sensor imports.
Africa and Middle East Automotive Tpms Market Competitive Environment
Global majors compete with regional champions across technology integration and distribution reach, producing a tiered structure where sensor-to-software pipelines dominate OEM supply while aftermarket channels fragment across national distributors. Three archetypes anchor positioning: integrated system suppliers with captive semiconductor fabrication, telematics-embedded platform vendors, and heat-tolerance specialists serving Gulf thermal environments. Competitive moves concentrate on strategic partnerships with fleet telematics providers and backward integration into lithium cell supply.
Within the integrated system tier, Continental AG exemplifies the sensor-to-software pipeline archetype through its OEM supply relationships with European-brand assembly plants. Sensata Technologies occupies a position anchoring aftermarket distribution across Anglophone East and West African markets. Schrader Electronics sits within the thermal specialization segment, representing Bluetooth-enabled module design oriented toward Gulf climate tolerance. These three patterns illustrate how geographic coverage, technology integration depth, and environmental hardening differentiate competitive positioning across the regional landscape.
| Leading Market Players |
|---|
| Continental AG |
| Sensata Technologies |
| Schrader Electronics |
| ZF Friedrichshafen AG |
| Pacific Industrial |
| DENSO Corporation |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| PressurePro |
| Valeo |
| Others |
Value Chain & Pricing Dynamics
RF calibration technician shortages across Morocco and Tunisia widen pricing spreads between bundled service packages and bare sensor transactions. Labor-cost differentials between Gulf electronics clusters and North African service bays feed into three-tier pricing structures that separate premium telematics-integrated systems from economy-grade hardware.
Pricing Analysis
Warranty bundling separates OEM channel pricing from aftermarket unbundled transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between GSO-compliant Gulf units and UN ECE R64-aligned North African systems. Price differentiation hinges on electromagnetic compatibility validation depth and Bluetooth connectivity inclusion. Cost compression in the sensor-based tier is intensifying because Asian component suppliers are flooding Egyptian and Kenyan distributor channels with commoditized hardware. Fleet operators show the least price sensitivity due to outcome-based contract structures, while independent garages in Nigeria and Tunisia face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with East Asian lithium thionyl chloride cell manufacturers that feed sensor production across the entire region. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while final sensor assembly clusters in China and Vietnam. Raw material dependencies span rare-earth magnets for RF transceivers, ceramic substrates for pressure transducers, and specialty polymers for heat-shielding housings. Tariff exposure runs through EU import duties hitting Moroccan re-export platforms. Distribution runs through Kuwaiti and Qatari wholesalers that aggregate procurement for multi-site fleet operators spanning the GCC.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa and Middle East Automotive TPMS Market sits in a technology-transition phase where IoT-integrated platforms are displacing passive sensor-based systems. Bluetooth Low Energy protocols are replacing proprietary 433 MHz RF architectures in fleet management ecosystems.
For Market Incumbents: Deepen backward integration into lithium cell supply to defend margin positions against Asian component commoditization. Secure captive semiconductor sourcing through long-term offtake agreements with Taiwanese foundries to mitigate lead-time volatility. Invest in GSO electromagnetic compatibility certification ahead of pending harmonization to preempt competitor compliance gaps. For New Entrants and Emerging Players: Launch via online retail channels targeting Kenyan and Nigerian independent garages bypassing traditional distributor markup tiers. Target the Northern Corridor transit route with hybrid TPMS retrofit kits designed for currency-constrained East African commercial vehicle operators. Anchor go-to-market strategy through telematics platform partnerships that embed tire data into existing fleet management dashboards. For Investors and Strategic Acquirers: Re-rating potential sits with telematics-embedded platform vendors given fleet digitization mandates across Saudi petrochemical transport and UAE cold-chain logistics. Long-term viability favors suppliers with software-defined revenue streams over pure hardware manufacturers. Monitor GSO type-approval harmonization progress as the signal indicating cross-border certification cost compression and market consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Software Pipeline Integration | Continental AG leverages integrated architectures to dominate OEM supply contracts with European-brand plants in Morocco and South Africa. |
| Bluetooth Low Energy Module Development | Schrader Electronics targets UAE last-mile and South African mining applications with smartphone-diagnostic capabilities. |
| East African Distributor Partnership Expansion | Sensata Technologies anchors aftermarket channels through relationships spanning Nigeria, Kenya, and Egypt. |
| Heat-Tolerant Materials R&D Investment | Ceramic-coated pressure transducers extend operational life beyond 150°C thresholds common in Gulf summer conditions. |
| Fleet Telematics Platform Convergence | Saudi long-haul operators generate subscription revenue from tire data embedded in centralized predictive maintenance algorithms. |
Study Parameters
Document review covered GSO technical regulations, SASO fitment mandates, NRCS certification requirements, and UN ECE R64 alignment protocols, complemented by interviews with TPMS procurement leads at Saudi logistics fleets, UAE temperature-controlled freight operators, Moroccan passenger vehicle assemblers, and Egyptian aftermarket distributors. Secondary validation drew from customs trade databases, vehicle production registries, and semiconductor supply disclosures. Bottom-up sensor shipment modeling and top-down fleet penetration estimates were triangulated against regulatory mandate timelines.
Cross-referencing historical fitment rates against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, technology integration depth, end-user procurement authority, and distribution channel structure. CAGRs were derived from regression analysis of fleet digitization adoption curves and regulatory compliance lag patterns. Industry-specific inputs incorporated lithium cell supply constraints and RF spectrum allocation stability in dense urban corridors.
Currency volatility in Egypt and Nigeria, GSO electromagnetic compatibility testing requirement changes, and lithium thionyl chloride supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding fleet consolidation trajectories and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive Zonal Gateway ECU Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Automotive Ultracapacitor Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Europe Automotive Camera Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Automotive Magnetic Sensor Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market