
 Automotive Films Market | 2026-2036
Automotive Films Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Films Market Intelligence
The performance gap between premium ceramic-based films and commodity dyed polyester films is broadening, impacting installer margins and brand perception. Eastman Chemical Company leverages its chemical engineering expertise to lead in high-performance paint protection films. In parallel, 3M Company sustains a strong position through its global distribution network and brand recognition in both aftermarket and OEM channels. Saint-Gobain competes by offering specialized glazing solutions that integrate film technologies directly at the manufacturing stage.
Automotive films are thin, multi-layered polymer laminates, typically made from polyester or polyurethane, designed for application to vehicle glass or painted surfaces. Their primary purpose is to enhance aesthetics, provide surface protection, improve safety, or control solar energy transmission and UV radiation. Paint Protection Films are a high-growth product category, driven by demand from luxury and electric vehicle owners. Within applications, the passenger vehicles segment remains dominant, while commercial vehicles present steady demand for functional films like safety and anti-glare.
Regulatory frameworks significantly influence market specifications. In the United States, state-level regulations govern visible light transmission (VLT) for window tints, while in Europe, ECE regulations dictate standards for safety glazing films. The ISO 9001 standard is also critical for ensuring manufacturing quality control across global supply chains. Navigating these varied regional compliance requirements is a central challenge for manufacturers seeking to maintain broad market access.
Market Dynamics
The central dynamic shaping the automotive films market is the performance bifurcation between advanced, multi-layer polyurethane films and traditional dyed polyester products. This division is driven by intense demand from the electric vehicle segment for paint protection and solar control films that preserve battery life and protect sensitive electronics.
Growth Catalysts
- Regulatory Mandates:Stricter vehicle safety standards, such as Europe's General Safety Regulation, and environmental policies like China's dual carbon goals promote advanced vehicle technologies, which in turn require sophisticated protective and functional films.
- Material Innovation:The development of paint protection films with self-healing properties and enhanced durability is attracting significant interest from luxury and electric vehicle owners seeking to preserve vehicle aesthetics and resale value.
- Concentrated OEM Demand:Demand is heavily focused within China's original equipment manufacturer (OEM) and aftermarket sectors, where a massive passenger vehicle market creates substantial volume for all film types.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of petroleum-derived raw materials, specifically polyurethane and polyester resins, create margin pressure for manufacturers and price instability for installers.
- Fragmented Compliance:A patchwork of state-level regulations in the United States governing visible light transmission (VLT) complicates product development and inventory management for window tint manufacturers.
- Substitution from Glazing:The integration of solar control and UV filtering properties directly into automotive glass by glazing manufacturers presents a long-term substitution threat to aftermarket window films.
Strategic Opportunities
- Functional Film Integration:There is a significant opportunity in developing films with integrated electronic functions, such as switchable privacy glass or films that enhance the performance of heads-up displays (HUDs).
- Commercial Fleet Penetration:The commercial vehicle segment remains an underserved market for functional films that offer anti-glare, safety, and security benefits, particularly for logistics and public transport fleets.
- Aftermarket Expansion in Emerging Economies:Markets in Southeast Asia and Latin America, characterized by a growing middle class and increased vehicle ownership, represent new growth frontiers for aftermarket film suppliers.
Industry Challenges
- Installer Skill Gap:A persistent shortage of highly skilled and certified technicians capable of flawlessly applying premium paint protection and ceramic films limits the growth of the high-margin segment.
- Quality Control and Counterfeiting:Ensuring consistent quality control compliant with ISO 9001 and combating the proliferation of low-quality, counterfeit films that erode brand trust are major operational hurdles.
- OEM Certification Cycles:The lengthy and resource-intensive process of qualifying new film products to meet the specific performance and durability standards of each automotive OEM delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Films Market |
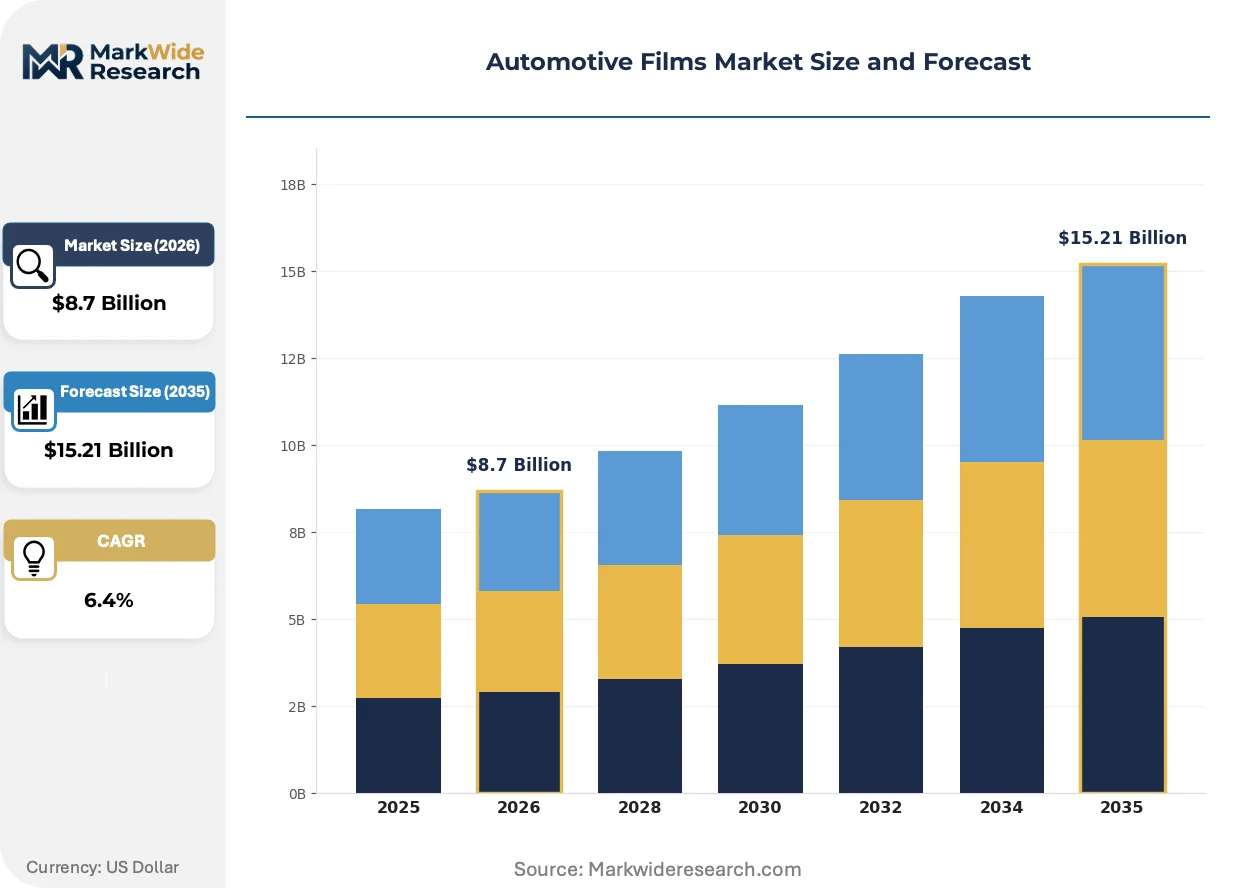
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Window Tint Films, Paint Protection Films, Decorative Films, Safety & Security Films, Anti-Glare Films Technology: Polyester, Polyurethane, Ceramic, Metalized, Dyed Application: Passenger Vehicles, Commercial Vehicles, Specialty Vehicles, Two-Wheelers, Public Transport End User: Vehicle Manufacturers, Aftermarket Installers, Automotive Dealerships, Fleet Operators, Customization Shops |
| Companies Covered | 3M Company, Eastman Chemical Company, Saint-Gobain, Avery Dennison Corporation, TORAY INDUSTRIES, INC., Johnson Window Films, Inc., Lintec Corporation, Garware Hi-Tech Films Limited, Hexis S.A.S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Films Market Strategic Shifts & Innovations
Product innovation is shifting from aesthetic enhancements to functional performance, driven by the technical requirements of electric and autonomous vehicles. This evolution prioritizes material science, focusing on films that offer measurable benefits in energy efficiency, surface protection, and sensor compatibility, reshaping competitive positioning around technical capability.
Advanced film constructions utilizing multi-layer sputtering technology enable precise filtering of specific wavelengths of light. This technology is increasingly adopted by owners of premium electric vehicles and commercial fleets to reduce solar heat gain, lessening the load on HVAC systems and preserving battery range. This manufacturing capability is decentralizing performance away from simple dyed films, creating a distinct premium tier defined by material science.
Regulatory frameworks are directly influencing material specifications. China's GB standards for vehicle manufacturing, for example, indirectly encourage the use of films that contribute to overall vehicle efficiency and safety. This policy environment accelerates demand for solar control films in EVs to manage battery thermal load and for safety films on side glass. The passenger EV segment is most affected, with manufacturers specifying high-performance films as a key value-add feature.
Consumer purchasing behavior is evolving from a transactional model to a specialized, service-oriented one. Buyers are increasingly seeking certified installation centers that specialize in high-end paint protection and ceramic films, disrupting the traditional, generalist auto accessory channel. This shift is most pronounced in North America and Europe, where a strong enthusiast culture and high vehicle values justify the investment in professional-grade surface protection services.
Automotive Films Market Segmentation
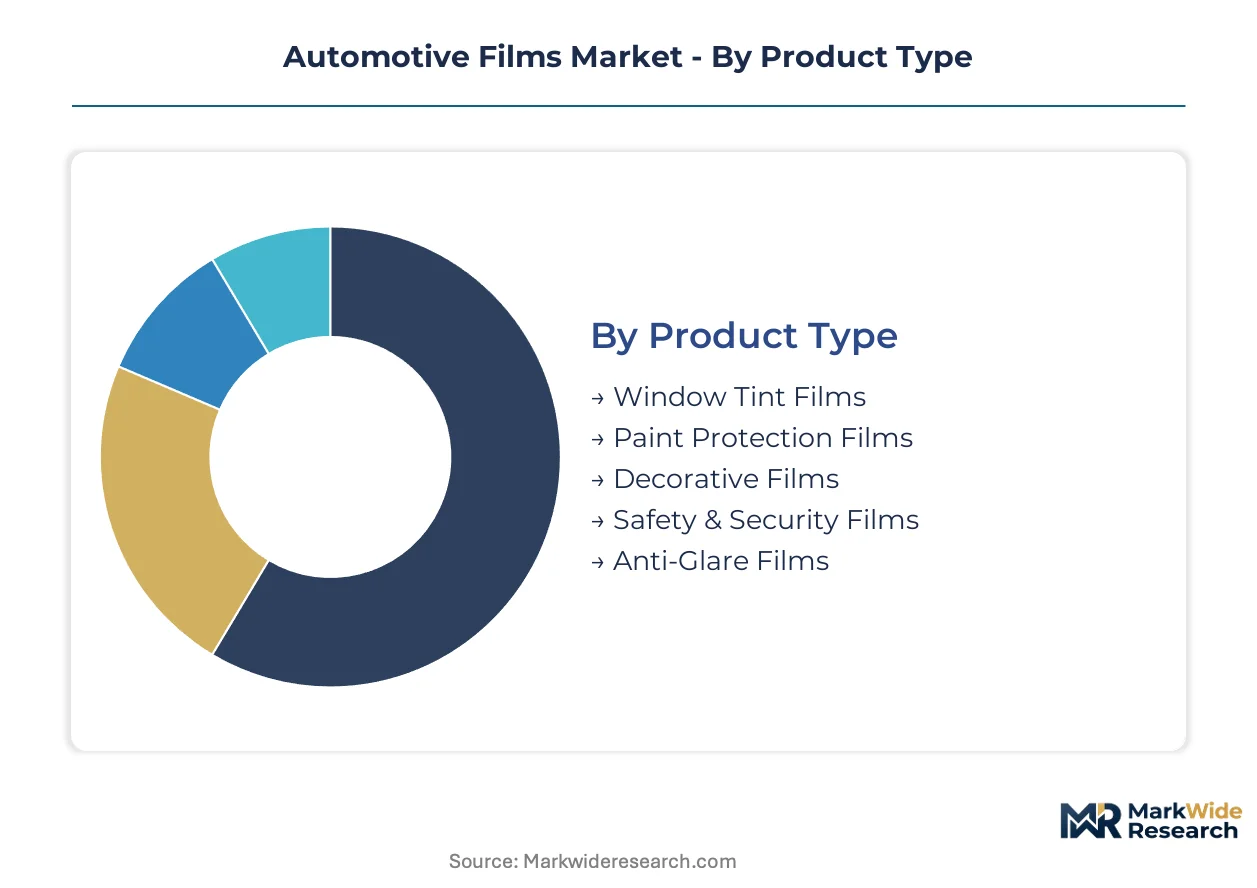
The automotive films market segmentation reveals distinct demand patterns and technological preferences across various product types, technologies, applications, and end-users. Understanding these divisions allows manufacturers to tailor product development and distribution strategies, addressing specific vehicle owner needs and regulatory requirements. Each segment reflects unique value propositions, from aesthetic enhancements to critical safety and performance improvements.
Product Type:
The automotive films market navigates a spectrum from highly customized, performance-driven solutions to standardized, widely accessible products across various film types.
- Window Tint Films:These films are primarily designed for solar energy control, reducing heat and glare inside the vehicle while blocking harmful UV radiation. Demand is concentrated in regions with intense sunlight, such as the Southern United States and Australia, driven by comfort and interior preservation.
- Paint Protection Films:Transparent, self-healing polyurethane films applied to exterior painted surfaces, offering superior protection against stone chips, scratches, and environmental contaminants. Demand is particularly strong among luxury and electric vehicle owners in North America and Western Europe, preserving vehicle aesthetics and resale value.
- Decorative Films:Aesthetic films that customize vehicle appearance through color changes, graphic wraps, or textured finishes. These products find demand in customization shops and among younger demographics seeking personalized vehicle aesthetics.
- Safety & Security Films:Thicker, multi-layered films designed to hold shattered glass together upon impact, enhancing occupant safety and deterring smash-and-grab theft. Commercial vehicles and public transport fleets in Europe prioritize these films due to stricter safety regulations.
- Anti-Glare Films:Specialized films applied to instrument clusters or infotainment screens to reduce reflections and improve visibility for the driver. These films are gaining traction in newer vehicles with large digital displays to enhance driver experience.
Most installed capacity flows through Window Tint Films. Expansion is steepest in Paint Protection Films.
Technology:
Supply concentration within film technologies reflects varied manufacturing complexities and material availability.
- Polyester:A versatile and cost-effective polymer widely used as a base material for various film types, offering good dimensional stability and clarity. Its broad availability makes it a foundational component across many automotive film products.
- Polyurethane:Highly durable and flexible polymer, specifically engineered for paint protection films due to its self-healing properties and resistance to abrasion. This technology commands premium pricing in the high-performance segment.
- Ceramic:Films infused with ceramic particles that excel at blocking infrared (IR) heat and UV radiation without interfering with electronic signals. Demand is high in electric vehicles within China, preserving battery life and cabin comfort.
- Metalized:Films incorporating thin layers of metal, which provide excellent heat rejection and privacy through reflection. These films often offer a distinct metallic appearance and are popular in cost-sensitive markets.
- Dyed:Basic films where the color is integrated into the adhesive or film layer, primarily offering aesthetic tinting and some glare reduction. These products represent the entry-level segment due to their simple construction.
Polyurethane films command premium pricing. Polyester products maintain broad market accessibility.
Application:
Customer type significantly influences film selection, with distinct requirements emerging from individual vehicle owners versus large fleet operators.
- Passenger Vehicles:The largest application segment, encompassing sedans, SUVs, and hatchbacks, where films are used for aesthetics, paint protection, and solar control. Demand from electric vehicle owners in Germany and the United States is particularly strong for high-performance films.
- Commercial Vehicles:Trucks, vans, and buses utilize films primarily for functional benefits such as safety, anti-glare, and branding. Fleet operators prioritize durability and cost-effectiveness for their extensive vehicle populations.
- Specialty Vehicles:Includes luxury cars, sports cars, and custom builds, where high-end paint protection and unique aesthetic films are frequently applied. This niche segment often demands specialized installation services.
- Two-Wheelers:Motorcycles and scooters use films for windshield protection, headlight tinting, and aesthetic customization. The focus here is often on scratch resistance and UV protection for plastic components.
- Public Transport:Buses, trains, and trams incorporate films for safety glazing, vandal resistance, and solar control to enhance passenger comfort and security. Durability and ease of maintenance are critical considerations.
Passenger vehicles generate the largest film volume. Commercial fleets exhibit consistent demand for functional solutions.
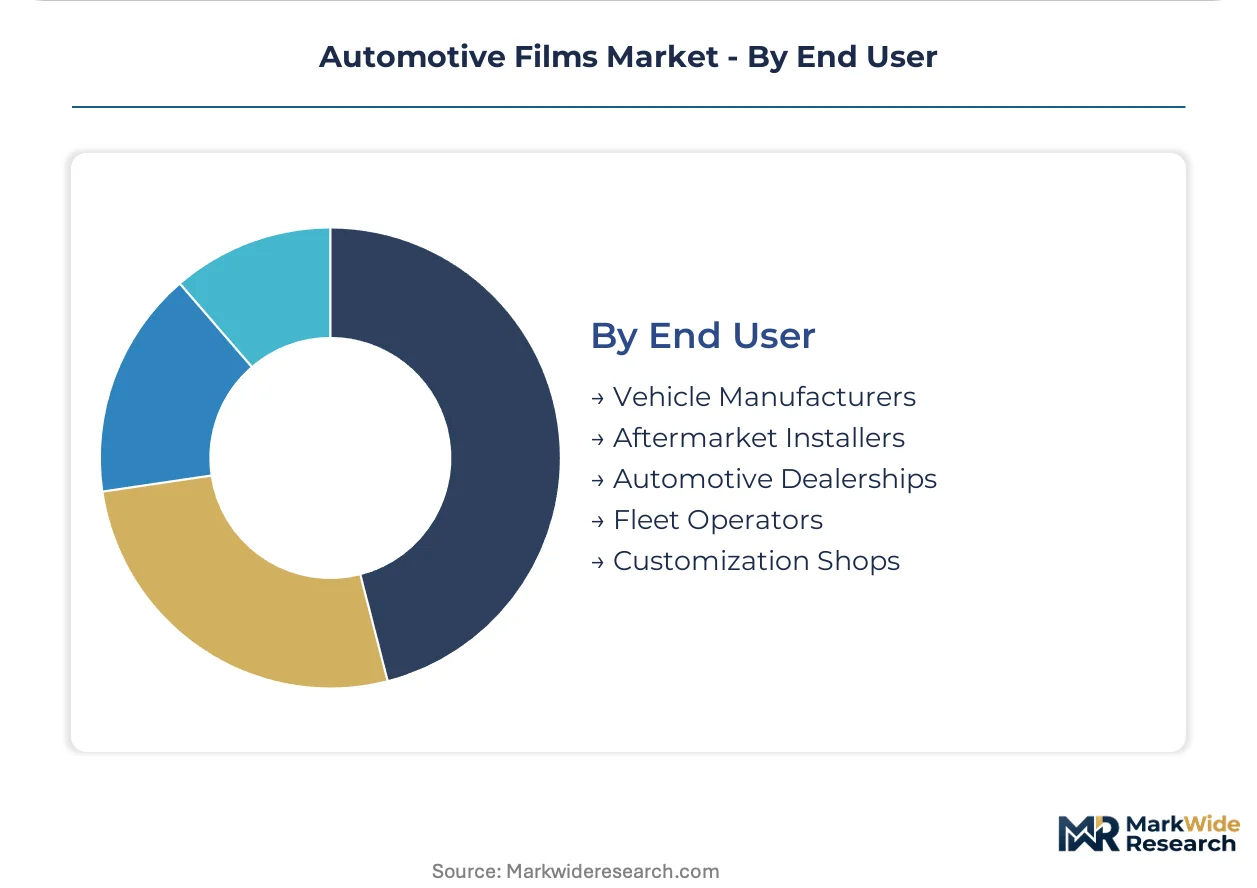
End User:
Market maturity among end-users defines procurement channels, ranging from established factory integration to dynamic aftermarket services.
- Vehicle Manufacturers:Original Equipment Manufacturers (OEMs) integrate films directly into the vehicle production process, ensuring factory-level quality and warranty coverage. Long certification cycles are a significant barrier to entry for new film products.
- Aftermarket Installers:Independent businesses and service centers specializing in film application, catering to vehicle owners seeking customization, protection, or upgrades post-purchase. This segment drives innovation in specialized application techniques and premium film offerings.
- Automotive Dealerships:Dealerships offer film products as add-ons or bundled packages during vehicle sales, providing convenience for new car buyers. Their offerings often include both OEM-approved and aftermarket options.
- Fleet Operators:Companies managing large vehicle fleets, such as rental agencies or logistics firms, purchase films in bulk for their operational vehicles. Their focus is on functional benefits, durability, and cost efficiency.
- Customization Shops:Specialized outlets focusing on high-end vehicle modifications and aesthetic enhancements, frequently employing advanced decorative and paint protection films. These shops cater to a discerning clientele with unique requirements.
Aftermarket installers drive innovation in service delivery. Vehicle manufacturers integrate films at the production stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in advanced material science and automotive engineering anchor significant demand for automotive films across key global markets. This expertise drives innovation in high-performance films, particularly for electric and luxury vehicles. Regional regulations and consumer preferences further shape specific product adoption.
China
Demand from China's massive passenger vehicle market, coupled with strong electric vehicle adoption, drives significant volume in both aftermarket and OEM sectors. China's dual carbon goals promote advanced vehicle technologies, including solar control films for EVs to manage battery thermal load. The Yangtze River Delta region, with its dense automotive manufacturing base, concentrates OEM demand for integrated film solutions.
Germany
Luxury and performance vehicle segments in Germany drive demand for premium paint protection films and specialized glazing solutions. Europe's General Safety Regulation influences the adoption of safety glazing films in new vehicles, enhancing occupant protection. The Stuttgart automotive cluster drives material innovation and specialized film applications for high-end vehicle manufacturers.
United States
Large aftermarket for vehicle customization and a growing electric vehicle ownership base fuel demand for aesthetic and protective films in the United States. State-level visible light transmission (VLT) regulations for window tints create a complex compliance landscape for manufacturers. Southern California's strong enthusiast culture and high vehicle values support specialized installation centers for premium films.
Japan
High quality standards and advanced vehicle technologies characterize the Japanese market, driving demand for functional films like anti-glare and UV protection. JIS standards ensure manufacturing quality and performance specifications for automotive films within the domestic market. The Kanto region, home to major automotive OEMs, focuses on integrating advanced film technologies during vehicle production.
South Korea
Rapid electric vehicle market expansion and consumer interest in advanced electronics protection contribute to demand for solar control films in South Korea. The country's national automotive safety standards encourage the use of films that enhance occupant protection. The Seoul Capital Area, a hub for automotive R&D and manufacturing, sees significant adoption of ceramic-based films for new vehicles.
Automotive Films Market Key Industry Players
Top-tier vendors anchor the premium segment, while a broader base of regional specialists addresses specific aftermarket needs. The market structure exhibits a tiered consolidation, with global chemical companies and diversified industrial conglomerates competing for high-performance applications. Two strategic archetypes dominate: integrated material science providers focusing on R&D, and specialized film converters emphasizing application expertise. Companies are pursuing portfolio diversification and strategic partnerships to expand their market reach and secure supply chains.
On the premium-tier vector, Eastman Chemical Company and 3M Company exemplify the integrated material science approach, leveraging extensive R&D capabilities and global distribution networks. Saint-Gobain, a French industrial group, represents a specialized glazing solution provider, integrating film technologies directly into automotive glass. These entities anchor the high-value segments, influencing product specifications and performance benchmarks across the industry, particularly in OEM channels and advanced aftermarket applications.
| Leading Market Players |
|---|
| 3M Company |
| Eastman Chemical Company |
| Saint-Gobain |
| Avery Dennison Corporation |
| TORAY INDUSTRIES, INC. |
| Johnson Window Films, Inc. |
| Lintec Corporation |
| Garware Hi-Tech Films Limited |
| Hexis S.A.S |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals, promoting advanced vehicle technologies, gate both qualified film supply and premium-tier pricing access for specialized solar control and safety products. This mandate drives material science investments and influences global supply dynamics for high-performance automotive films.
Pricing Analysis
Bundled installation services versus unbundled film sales define the pricing landscape, particularly in the aftermarket. Pricing stratifies across premium, standard, and economy tiers, driven by quality grade, brand premium, and after-sales service guarantees. Input cost volatility, specifically for polyurethane and polyester resins, causes pricing pressure for manufacturers and installers. Luxury and electric vehicle owners exhibit the least price sensitivity, prioritizing performance and aesthetics, while commercial fleets remain highly sensitive to overall cost-effectiveness.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand, integrating films into vehicle production lines. Supply concentration for advanced film materials draws from key chemical manufacturing hubs in China, Germany, and the United States. Polyurethane and polyester resins form critical raw material dependencies. Commodity price volatility presents a structural risk across the supply chain. Aftermarket distribution primarily runs through a fragmented network of independent installers and automotive dealerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This automotive films market presents a late-cycle quality story, driven by a pronounced demand-shift toward premium, high-performance film specifications for electric and luxury vehicles.
For Market Incumbents: Deepen chemical engineering expertise to maintain leadership in high-performance film development. Focus on securing OEM certifications in key markets like Germany and Japan to counter the threat of fragmented compliance. Expand global distribution networks to leverage brand recognition, particularly in emerging aftermarket segments. Invest in R&D for next-generation materials that enhance battery life and sensor compatibility.
For New Entrants and Emerging Players: A price-point gap exists between premium ceramic-based films and commodity dyed polyester products, offering entry opportunities. Target underserved commercial fleets with functional films like anti-glare and safety solutions. Penetrate growing aftermarket segments in Southeast Asia and Latin America through localized distribution and certified installer programs. Focus on niche aesthetic films and specialized customization shops as a distinct go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized aftermarket installer networks because of the fragmented service landscape and high demand for certified application. Long-term viability hinges on the continued electrification of the automotive fleet and stricter safety regulations. Target regional film converters or specialized material science startups with proprietary technology. The signal to watch is the OEM adoption rate of advanced integrated film solutions as standard features.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand R&D in self-healing polymers | This initiative enhances film durability, appealing to luxury and EV owners who prioritize vehicle preservation. |
| Secure OEM certifications in China | Achieving these certifications unlocks significant volume from the world's largest automotive production base. |
| Develop integrated electronic films | This innovation positions companies for future smart vehicle applications like switchable privacy glass. |
| Establish certified installer training programs | Such programs address the installer skill gap, ensuring quality application for high-margin premium films. |
| Form strategic alliances with glazing manufacturers | These partnerships mitigate substitution threats by integrating film technologies directly into automotive glass. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a robust market analysis. This process involved extensive discussions with industry stakeholders, including OEM procurement managers, film manufacturers, aftermarket installers, and regulatory bodies. Secondary validation drew from automotive production databases, trade association reports, regulatory filings, and financial disclosures, triangulating data points from bottom-up and top-down perspectives.
Historical data was cross-referenced with expert panel input to calibrate the analytical framework across the analysis window. The modeling period incorporated segmentation dimensions including product type, technology, application, end-user, and regional demand patterns. Compound annual growth rates were derived through a weighted average of historical trends and projected market drivers, utilizing forecast inputs such as electric vehicle production forecasts and raw material price trends.
Caveats apply where raw material price volatility, significant regulatory changes, or the widespread adoption of new glazing technologies could materially shift the outlook. Forecasts reflect assumptions regarding economic stability and technological progression throughout the projection horizon. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Automotive Air Purifier Market