
 L4 Autonomous Driving Market | 2026-2036
L4 Autonomous Driving Market Size, Share, and Industry Trends Forecast 2026-2036
L4 Autonomous Driving Market Outlook
ISO 26262 functional safety certification is redrawing competitive boundaries in the L4 autonomous driving sector, forcing substantial capital commitments before commercial deployment. Waymo leverages its extensive real-world mileage database to sustain testing leadership across multiple urban environments. Tesla competes through vertical integration of its Full Self-Driving compute stack, while Pony.ai anchors its position in robotaxi operations with geographic concentration in California and Guangzhou.
L4 autonomous driving denotes vehicles capable of performing all driving functions within defined operational design domains without human intervention, relying on sensor fusion architectures that process lidar point clouds, radar returns, and camera feeds at sub-100-millisecond latencies to execute path planning decisions. Camera systems dominate current bill-of-materials profiles due to cost scalability, though lidar retains margin concentration in premium passenger car and dense urban robotaxi applications where centimeter-level ranging accuracy proves essential. Fleet management deployments generate recurring revenue streams that attract logistics-focused capital, contrasting with the capital-intensive private ownership segment where consumer liability frameworks remain unresolved.
NHTSA in the United States, Germany's KBA, and China's MIIT each enforce distinct homologation pathways that fragment development roadmaps and inflate engineering overhead for multi-territory operators. The EU AI Act adds algorithmic transparency requirements that reshape how L4 perception systems document decision logic for regulatory audit. Stakeholders must monitor which jurisdiction first achieves functional equivalence agreements for cross-border autonomous vehicle certification, as this will determine where deployment capital concentrates and which sensor-software architectures achieve standardization.
Market Dynamics
ISO 26262 functional safety certification is compressing development timelines and forcing capital concentration toward pre-commercial validation infrastructure, reshaping how L4 autonomous driving ventures sequence their technical roadmaps.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:Germany's KBA and France's CNIL are accelerating documentation standards that reward early compliance investments, creating first-mover advantages for perception-stack developers.
- Logistics corridor densification:Freight operators across the United States and China are consolidating freight volumes onto designated autonomous routes, generating predictable operational design domains for fleet deployment.
- Lidar cost-down curves:Solid-state ranging modules are penetrating robotaxi specifications previously reserved for camera-dominant architectures, expanding addressable deployment scenarios.
Market Restraints
- Compute substrate supply concentration:Advanced driver-assistance system-on-chip fabrication concentrates among Taiwan-based foundries, exposing development schedules to geopolitical disruption.
- Sensor fusion validation burden:Sub-100-millisecond latency requirements across lidar-radar-camera architectures inflate software verification cycles before homologation.
- Cross-border certification fragmentation:NHTSA, Germany's KBA, and China's MIIT enforce non-equivalent testing protocols, forcing redundant engineering tracks for multi-territory operators.
Strategic Opportunities
- India's logistics automation corridor:The country's national highway infrastructure investment is creating greenfield autonomous freight deployment zones without legacy traffic management system conflicts.
- Occupant monitoring convergence:Integration of driver-state detection with L4 fallback protocols opens new cabin-interior sensor procurement channels.
- Japan's METI mobility-as-a-service subsidies:Regional robotaxi pilot funding is concentrating fleet operator partnerships around Osaka and Tokyo metropolitan zones.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise concentrates among Tier-1 automotive suppliers, constraining startup hiring pipelines.
- Sensor calibration infrastructure capex:Factory-grade lidar-camera-radar alignment systems require dedicated cleanroom facilities that compress operating margins during pre-revenue phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L4 Autonomous Driving Market |
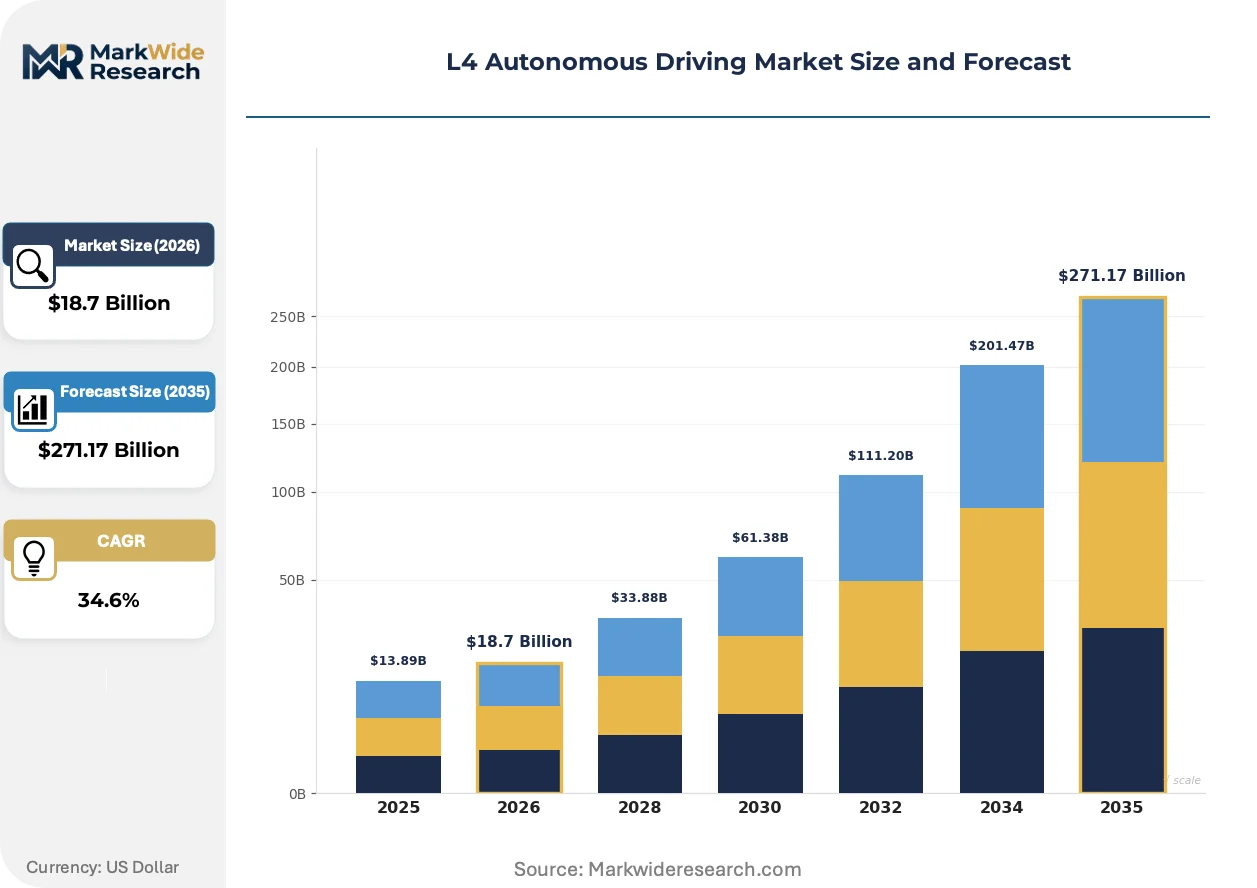
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $271.17 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lidar, Radar, Camera Systems, Ultrasonic Sensors Vehicle Type: Passenger Cars, Buses, Trucks, Delivery Vans Deployment Model: On-Demand Services, Fleet Management, Private Ownership, Research Applications End User: OEMs, Logistics Companies, Public Transport Authorities, Research Institutions |
| Companies Covered | Lucid Motors, Nuro, Tesla, Audi, BMW, Waymo, Ford Motor Company, Pony.ai, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L4 Autonomous Driving Market Strategic Shifts
Software-defined vehicle architectures are dissolving traditional hardware-software boundaries in L4 development, enabling over-the-air perception model updates that compress validation cycles and reshape supplier relationships.
End-to-end neural perception stacks are fragmenting the established modular pipeline of separate detection, tracking, and prediction components. Robotaxi operators in California and Guangzhou are piloting these consolidated architectures for urban dense-traffic scenarios. The compression of intermediate interpretable representations is forcing regulators to develop new audit methodologies for algorithmic decision documentation.
China's MIIT is mandating data localization for autonomous vehicle training datasets, requiring foreign operators to establish domestic cloud infrastructure partnerships. This policy is segmenting global development roadmaps between China-accessible and China-excluded perception model versions. Fleet operators are responding by licensing bifurcated software stacks that share only upstream sensor hardware specifications.
Logistics buyers are unbundling vehicle procurement from fleet management services, contracting directly with autonomous driving software providers while sourcing chassis from traditional commercial vehicle manufacturers. This disintermediation is visible most acutely in the United States, where freight operators negotiate separate agreements with perception-stack vendors and truck OEMs. The shift is compressing traditional dealer network margins and redirecting service revenue toward software subscription models.
L4 Autonomous Driving Market Segmentation
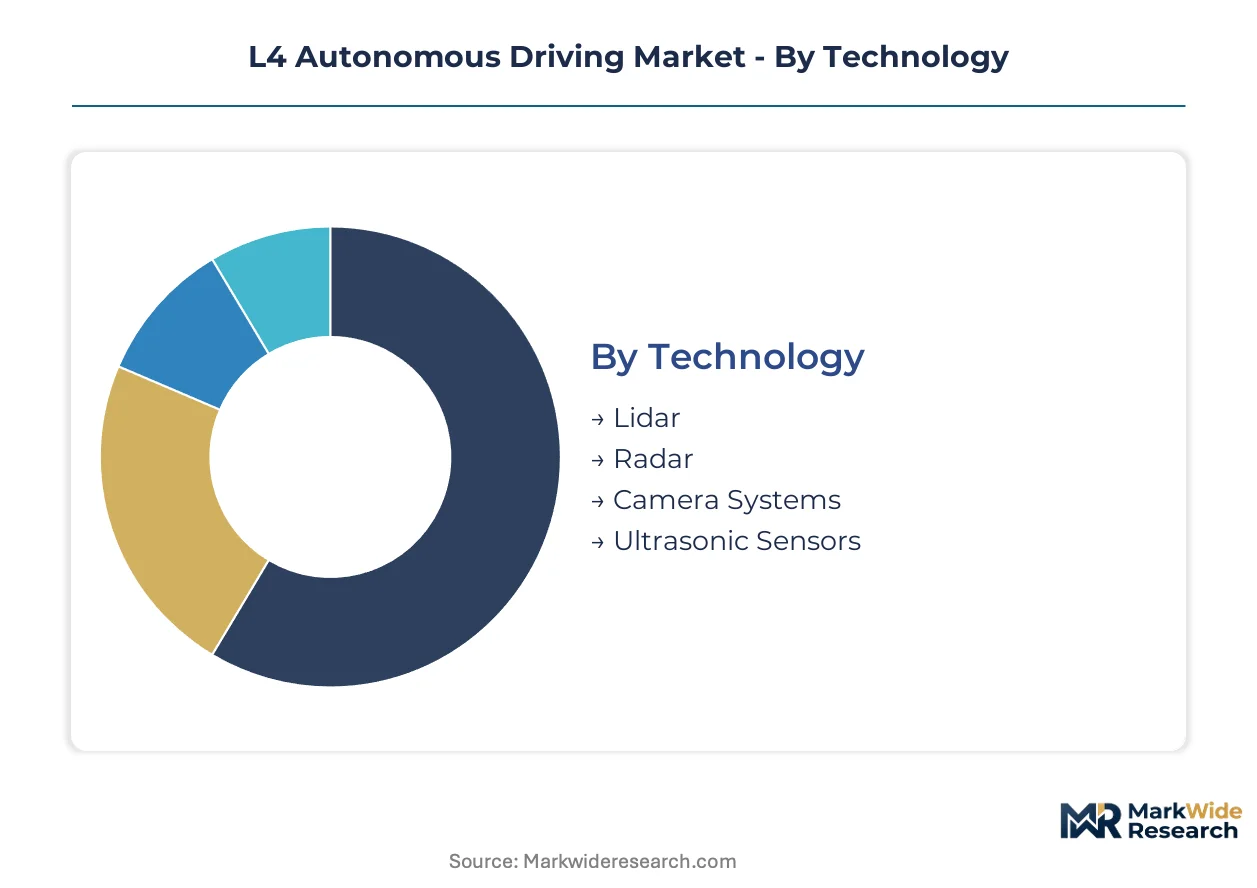
Technology choices in L4 autonomous driving determine homologation pathways and capital intensity before any commercial deployment. Segment boundaries shift as solid-state sensors displace mechanical assemblies and fleet operators unbundle software from chassis procurement.
Technology:
Lidar faces acute substitution pressure from camera-dominant architectures as neural perception stacks compress ranging requirements into vision-only pipelines.
- Lidar:Solid-state ranging modules emit pulsed laser arrays to generate dense point clouds for centimeter-level spatial mapping. Dense urban robotaxi fleets in California and Guangzhou specify mechanical and MEMS-based units despite unit cost premiums, driven by regulatory documentation requirements for interpretable obstacle detection.
- Camera Systems:CMOS image sensors capture visible-spectrum and near-infrared data for lane detection, traffic sign recognition, and end-to-end neural driving policies. Passenger car OEMs in Germany and the United States concentrate procurement here to preserve bill-of-materials scalability, though low-light performance constraints limit operational design domains.
- Radar:Frequency-modulated continuous-wave units penetrate weather obscurants to deliver velocity and range data for adaptive cruise control handoffs.
- Ultrasonic Sensors:Short-range acoustic modules handle parking maneuvers and low-speed proximity alerts where millimeter precision exceeds cost thresholds.
Camera Systems anchors the volume base while Lidar gains share at the steepest rate.
Vehicle Type:
Cost tier stratification separates capital-light passenger deployments from heavy-duty freight applications requiring redundant braking and steering actuators.
- Passenger Cars:Sedans and SUVs integrate L4 stacks for robotaxi and private ownership use cases, with sensor pods roof-mounted to preserve cabin packaging. California's DMV permit holders and China's Baidu Apollo partners concentrate development here, constrained by unresolved occupant liability frameworks in multi-territory deployments.
- Trucks:Class 8 tractors and regional haulers deploy hub-to-hub autonomous corridors across Texas, Arizona, and China's Yangtze River Delta logistics belts. Fleet operators negotiate directly with perception-stack vendors, bypassing traditional dealer networks to capture fuel and labor savings.
- Buses:Fixed-route shuttles serve airport loops and central business district circulators with geofenced operational design domains.
- Delivery Vans:Last-mile parcel vehicles navigate curb-side loading zones and residential street hierarchies at sub-25-mph velocities.
Trucks anchors the volume base while Passenger Cars gains share at the steepest rate.
Deployment Model:
Application maturity divides revenue-recurring fleet services from pre-commercial research phases dependent on grant funding and partnership subsidies.
- Fleet Management:Centralized vehicle oversight with predictive maintenance, remote assistance fallback, and dynamic route optimization generates subscription revenue from logistics buyers. Operators across the United States and China consolidate freight onto designated autonomous corridors, creating predictable operational design domains that accelerate homologation timelines.
- On-Demand Services:Robotaxi networks match ride requests with available autonomous vehicles through mobile applications, capturing urban mobility spend previously directed toward human-driven taxis. Waymo and Pony.ai anchor operations in Phoenix, San Francisco, and Guangzhou, constrained by local regulations governing empty-vehicle miles and geofenced service boundaries.
- Private Ownership:Individual purchasers acquire L4-capable vehicles for personal use, though residual value uncertainty and insurance pricing fragmentation suppress near-term volume.
- Research Applications:University and corporate testbeds validate perception algorithms and safety frameworks before commercial deployment.
On-Demand Services anchors the volume base while Fleet Management climbs the fastest.
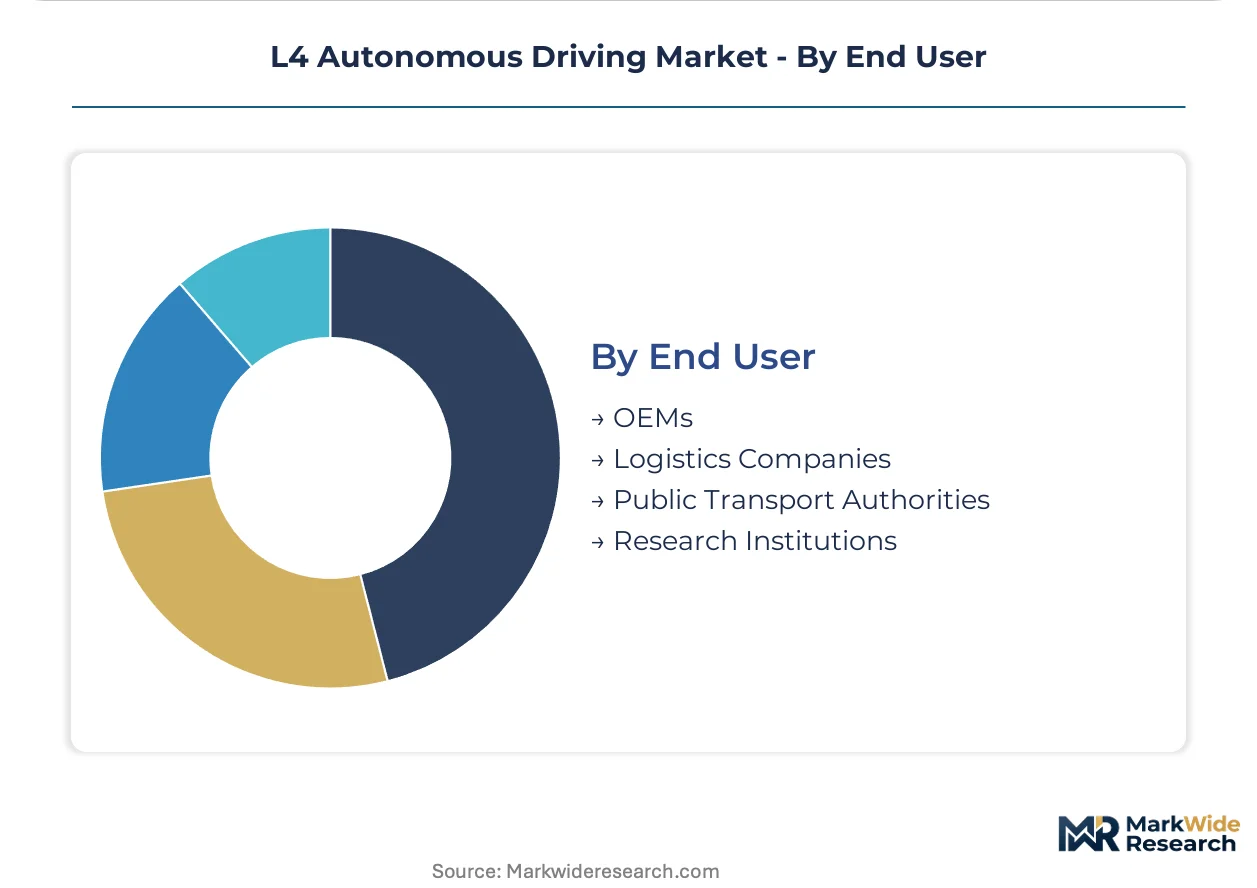
End User:
Customer type concentration shapes procurement authority, with OEMs retaining integration control while logistics buyers disintermediate traditional supply chains.
- Logistics Companies:Freight operators source autonomous chassis and perception software through separate contracting streams, redirecting service revenue from dealers toward software subscriptions. United States-based truckload carriers and Chinese e-commerce fulfillment networks drive specification requirements for long-haul corridor compatibility.
- OEMs:Vehicle manufacturers integrate L4 stacks into production lines, managing sensor calibration infrastructure and warranty exposure. Germany's KBA and the United States' NHTSA homologation timelines force early ISO 26262 compliance investments that concentrate development among capitalized tier-one suppliers.
- Public Transport Authorities:Municipal and regional agencies procure autonomous shuttles for first-mile-last-mile connectivity and fixed-route replacement.
- Research Institutions:Academic and government laboratories validate safety frameworks and generate training datasets for algorithmic development.
OEMs anchors the volume base while Logistics Companies expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 freight corridor underwrites United States primacy in autonomous trucking deployment, connecting California ports to Texas distribution hubs with minimal terrain variation.
United States
Arizona and Texas host the densest hub-to-hub autonomous freight trials, with NHTSA accelerating rulemaking timelines for commercial deployment permits. California's DMV maintains separate testing protocols that fragment development roadmaps for multi-state operators. Waymo anchors robotaxi operations across Phoenix and San Francisco, while logistics buyers consolidate freight volumes onto designated I-10 and I-45 corridors.
China
The Yangtze River Delta logistics belt generates predictable operational design domains for fleet deployment across Shanghai, Suzhou, and Hangzhou. MIIT mandates data localization for autonomous vehicle training datasets, forcing foreign operators to establish domestic cloud infrastructure partnerships. Baidu Apollo and Pony.ai concentrate robotaxi pilots in Guangzhou and Beijing, navigating bifurcated software stack requirements.
Germany
Bavaria's automotive engineering cluster supports KBA homologation pathways for passenger car L4 integration, with Munich anchoring Tier-1 supplier development. The EU AI Act imposes algorithmic transparency requirements that reshape perception system documentation for regulatory audit. Audi and BMW pursue divergent sensor fusion architectures across Ingolstadt and Munich development centers.
Japan
Osaka and Tokyo metropolitan zones concentrate METI mobility-as-a-service subsidies for regional robotaxi pilot funding. The Kansai region's dense urban fabric provides validation environments for end-to-end neural perception stacks. Toyota and Honda suppliers navigate JIS standards convergence with ISO 26262 functional safety certification timelines.
India
The Delhi-Mumbai Industrial Corridor creates greenfield autonomous freight deployment zones without legacy traffic management system conflicts. National highway infrastructure investment accelerates logistics automation corridor development across Gujarat and Maharashtra. State transport authorities in Karnataka and Telangana pilot fixed-route shuttle services for airport connectivity.
L4 Autonomous Driving Market Competitive Environment
Listed leaders compete with private specialists across capital access and regulatory navigation, producing a tiered structure where public automotive OEMs face venture-backed perception-stack developers. The vendor base segments into integrated vehicle manufacturers, pure-play software providers, and fleet operators unbundling procurement from chassis sourcing. Three archetypes dominate: vertically integrated OEMs controlling sensor calibration infrastructure; robotaxi specialists amassing real-world mileage databases; and logistics-focused stack vendors licensing perception software to freight carriers. Competitive moves concentrate on strategic partnerships with fleet buyers and geographic licensing agreements that secure operational design domain exclusivity.
Within the venture-backed specialist tier, Waymo and Pony.ai exemplify divergent geographic concentration strategies, with the former spanning multiple United States urban environments and the latter anchoring operations across California and Guangzhou. Tesla occupies a position as the listed OEM pursuing vertical integration of compute stack and vehicle production. Among diversified automotive manufacturers, BMW and Ford Motor Company represent incumbents navigating ISO 26262 compliance investments while managing legacy dealer network relationships. Lucid Motors and Nuro sit within the premium passenger and last-mile delivery archetypes respectively, each facing distinct homologation pathway pressures.
| Leading Market Players |
|---|
| Lucid Motors |
| Nuro |
| Tesla |
| Audi |
| BMW |
| Waymo |
| Ford Motor Company |
| Pony.ai |
| General Motors |
| Others |
Value Chain & Pricing Dynamics
Long-term fleet service contracts lock in both sensor module supply access and predictable unit economics for logistics operators negotiating multi-year autonomous freight deployments across Arizona and Texas corridors.
Pricing Analysis
Certification level (ISO 26262 ASIL-D vs ASIL-B) creates the primary spread between premium lidar-camera fusion stacks and standard camera-dominant architectures. Three-tier pricing structure across premium, standard, and economy levels reflects sensor count, compute substrate performance, and after-sales remote assistance bundling. Cost compression in mid-tier perception modules is intensifying because solid-state lidar vendors are displacing mechanical assemblies at 40% lower bill-of-materials. Logistics companies exhibit highest price sensitivity due to fleet-scale procurement volumes, while robotaxi operators prioritize redundancy premiums over unit cost.
Supply Chain Analysis
Strategic stockpiling of advanced driver-assistance system-on-chips dominates procurement behavior as Taiwan-based foundry concentration exposes development schedules to geopolitical disruption. Supply concentrates in Taiwan, South Korea, and the United States for compute substrates, with China and Germany anchoring lidar mechanical assembly and precision optics respectively. Raw material dependencies span silicon wafers, rare-earth magnet components for MEMS mirrors, and automotive-grade photodiodes. Single-source vulnerability in 7nm automotive chip fabrication represents the dominant structural risk. Distribution runs through Tier-1 automotive suppliers holding ISO 26262 calibration infrastructure, though direct procurement from perception-stack vendors is accelerating among freight operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet management software subscriptions and remote assistance service layers are expanding faster than hardware procurement, transforming L4 autonomous driving into a service-attach revenue architecture where recurring income streams outweigh one-time vehicle sales.
For Market Incumbents: Shield market position through captive control over sensor calibration infrastructure and accelerated ISO 26262 certification investments before NHTSA rulemaking hardens compliance timelines. Defensive consolidation around end-to-end neural perception stacks counters the threat from venture-backed software specialists unbundling hardware from fleet services. Vertical integration into cleanroom-grade alignment facilities preserves margin concentration against price erosion from modular component suppliers. For New Entrants and Emerging Players: Anchor in India's greenfield logistics corridors where national highway infrastructure investment creates autonomous freight deployment zones without legacy traffic management conflicts. White-space targets include last-mile delivery van specifications below 25-mph operational design domains and fixed-route airport shuttle services in secondary metropolitan zones. A direct-to-freight-operator go-to-market angle bypasses entrenched Tier-1 supplier relationships that dominate OEM procurement channels. For Investors and Strategic Acquirers: Pure-play perception-stack developers with established real-world mileage databases in multiple urban environments represent the highest-conviction acquisition archetype for long-term viability across the 5-10 year commercialization window. These assets command premium positioning because data moats compound faster than hardware cost curves. The signal to watch is functional equivalence agreements for cross-border autonomous vehicle certification, which will concentrate deployment capital and trigger consolidation among multi-territory operators. Revision becomes warranted when regulatory harmonization timelines extend beyond modeled assumptions or when compute substrate supply disruptions exceed six-month durations.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Standardization | Reduces homologation overhead for multi-territory operators navigating NHTSA, KBA, and MIIT fragmentation. |
| Fleet Management Software Licensing | Captures recurring revenue from logistics buyers disintermediating traditional dealer networks. |
| Data Localization Infrastructure Partnership | Enables China market access under MIIT mandates without bifurcating global development roadmaps. |
| Solid-State Lidar Supply Agreement | Secures centimeter-level ranging modules as mechanical lidar faces substitution pressure from camera-dominant stacks. |
| Remote Assistance Fallback Service Buildout | Generates subscription income from robotaxi operators managing edge-case disengagements in dense urban environments. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with autonomous vehicle program directors, Tier-1 supplier procurement leads, fleet operations managers, and regulatory affairs specialists at NHTSA and Germany's KBA; and secondary validation against SEC 10-K filings, NHTSA autonomous vehicle disengagement reports, MIIT industry bulletins, and vehicle production databases from IHS Markit. Bottom-up triangulation across sensor module bill-of-materials and top-down reconciliation against fleet deployment announcements anchored volume estimates.
Across the analysis window, the forecasting framework modeled technology substitution curves, vehicle type penetration by operational design domain complexity, deployment model revenue recognition patterns, and end-user procurement authority shifts. CAGRs derived from logistic diffusion curves fitted to pilot program expansion rates and homologation timeline acceleration signals. Industry-specific inputs included lidar cost-down trajectories, compute substrate foundry capacity allocation, and EU AI Act algorithmic transparency compliance burden estimates.
Material uncertainties — geopolitical disruption in Taiwan-based semiconductor fabrication, regulatory fragmentation persistence, and end-to-end neural perception stack validation cycle extensions — sit outside the modeled envelope. Forecasts reflect assumptions about functional safety engineer availability and cross-border certification harmonization progress. Revision becomes warranted when compute substrate lead times or multi-territory homologation redundancy costs cross thresholds that alter capital deployment sequencing for fleet operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Self-Driving Bus Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Vehicle Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
US Autonomous Car Market