
 Automotive Anti-Pinch Power Window System Market | 2026-2036
Automotive Anti-Pinch Power Window System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Anti-Pinch Power Window System Market Analysis
Software-defined window calibration services is consolidating around embedded motor-control firmware that automakers monetize through over-the-air update subscriptions. Robert Bosch GmbH leverages its semiconductor division to anchor intelligent actuator production in-house. Continental AG competes through integrated body-electronics platforms that bundle anti-pinch with central gateway modules. Brose Fahrzeugteile SE and Co. KG specializes in door-system mechatronics, sustaining premium supply relationships with German OEMs.
An automotive anti-pinch power window system employs Hall-effect sensors and current-sensing algorithms to detect obstructions during window closure, reversing motor direction within milliseconds when pinch-force thresholds are exceeded. The assembly typically combines a DC motor, control module, and rubber-sealed regulator mechanism to prevent occupant injury in passenger vehicles. Smart product variants are capturing margin pools as OEMs specify predictive maintenance integration and smartphone-linked diagnostics. Electrical technology leads volume deployment, though hybrid electromechanical architectures are gaining share in cost-sensitive segments where mechanical redundancy satisfies baseline regulatory requirements. Factory-fitted installation dominates value capture, while retrofitted channels face margin compression from certification complexity.
NHTSA's FMVSS 118 and UNECE R21 establish maximum permissible pinch forces, compelling Tier-1 suppliers to validate sensor accuracy across temperature extremes. China's GB standards and Japan's JIS frameworks add regional test protocols that fragment homologation requirements for multinational component manufacturers. Stakeholders must monitor convergence between anti-pinch systems and broader vehicle-access electronics, including biometric entry and frameless door architectures that alter obstruction-detection geometries.
Market Dynamics
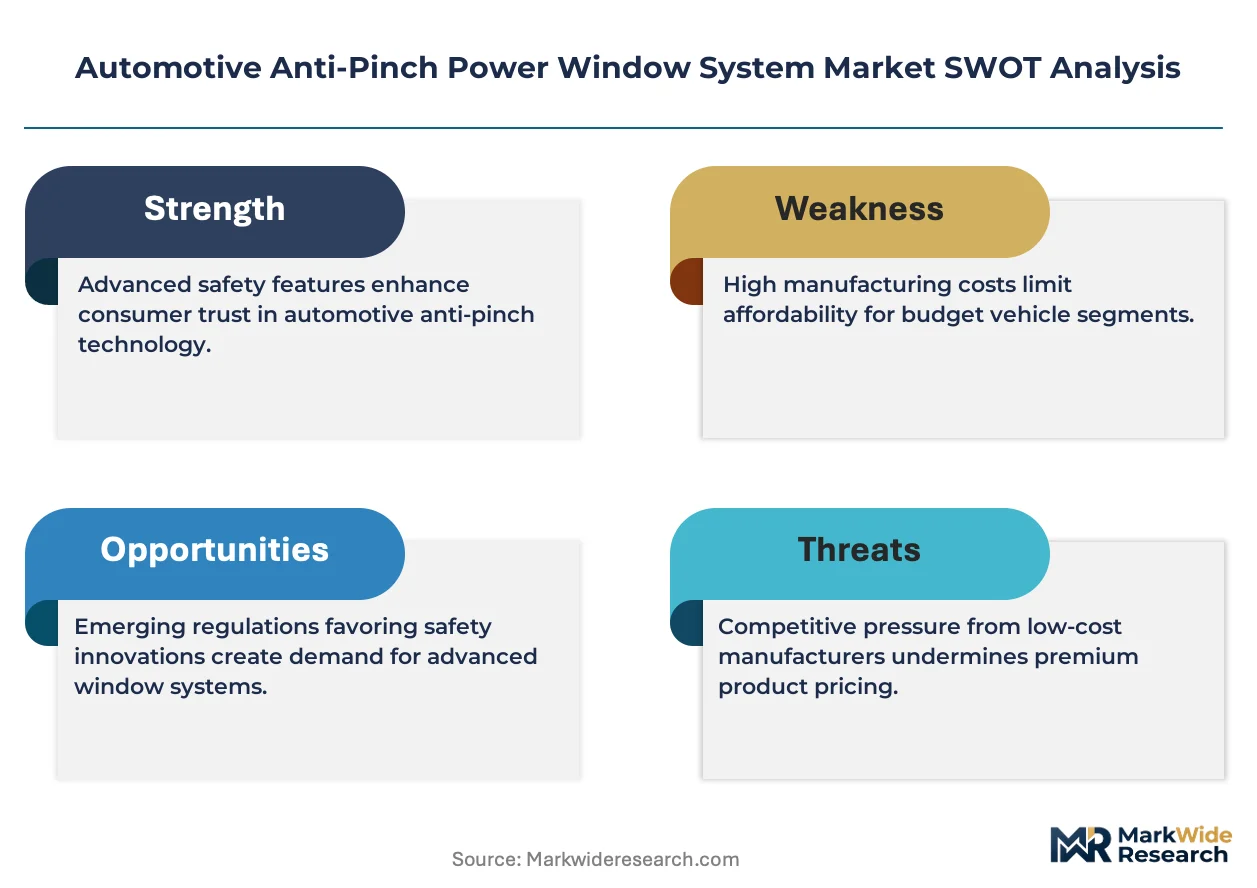
Software-defined calibration is compressing hardware margins as automakers capture recurring revenue through firmware subscriptions, forcing Tier-1 suppliers to restructure their value proposition around embedded motor-control intellectual property.
Growth Catalysts
- FMVSS 118 mandates:NHTSA's pinch-force thresholds in the United States compel OEMs to factory-fit compliant systems across all passenger vehicle classes, eliminating non-compliant mechanical alternatives from new car production.
- Frameless door proliferation:Premium German and Japanese OEMs are specifying obstruction-detection geometries for frameless architectures that require more sophisticated sensor fusion and algorithmic calibration.
- Hall-effect sensor cost curves:Semiconductor manufacturing scale in East Asia is driving down per-unit sensor costs, enabling electromechanical system deployment in mid-market vehicle segments previously served by pure mechanical regulators.
Market Restraints
- Rare earth magnet volatility:Neodymium and dysprosium price swings from Chinese export quotas destabilize DC motor cost structures, squeezing margins for suppliers without long-term offtake agreements.
- Homologation fragmentation:Divergent test protocols between UNECE R21, China's GB standards, and Japan's JIS frameworks force redundant validation cycles that extend development timelines and inflate certification budgets.
- Mechanical redundancy substitution:Cost-sensitive vehicle segments in India and Southeast Asia continue specifying mechanical anti-pinch designs that satisfy baseline regulatory requirements without electrical system premiums.
Strategic Opportunities
- Aftermarket smartphone integration:Bluetooth-linked diagnostic modules enable independent service channels to compete with dealer networks through predictive maintenance alerts and remote calibration updates.
- Biometric entry convergence:Fingerprint and facial recognition systems are creating demand for window control modules that communicate with vehicle-access electronics through centralized body-computer architectures.
- India domestic production scaling:Maruti Suzuki and Tata Motors' capacity expansion is generating localized demand for anti-pinch systems that bypass import duties and qualify for PLI scheme incentives.
Industry Challenges
- Embedded firmware talent scarcity:Motor-control algorithm development requires specialized expertise in real-time systems and functional safety standards that automotive suppliers struggle to recruit against semiconductor and aerospace competitors.
- Legacy gateway integration:New anti-pinch modules must communicate with decade-old central body electronics through protocol translation layers that introduce latency and complicate warranty attribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Anti-Pinch Power Window System Market |
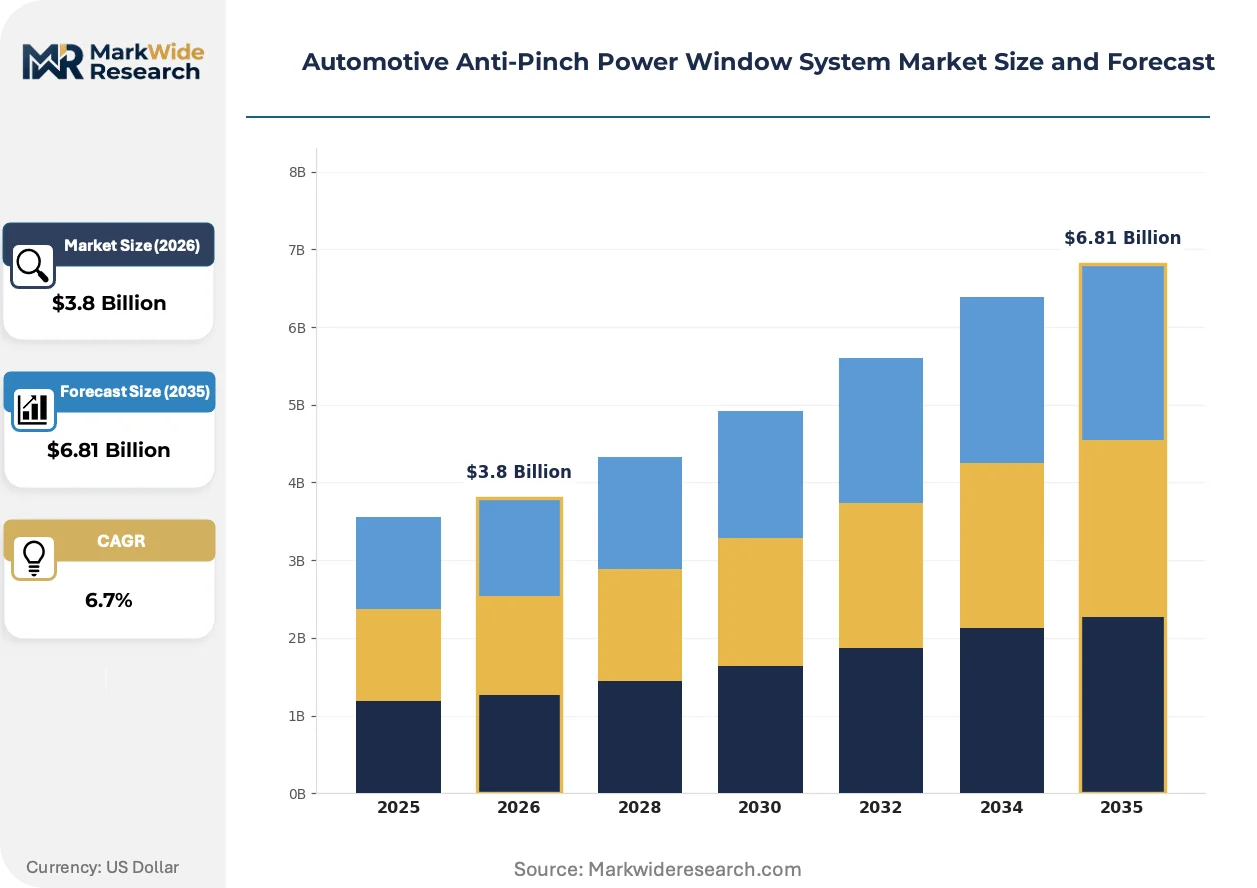
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Smart, Manual, Automatic Technology: Mechanical, Electrical, Hybrid, Pneumatic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation Type: Factory-Fitted, Retrofitted, Dealer-Fitted, DIY |
| Companies Covered | Aisin, Robert Bosch GmbH, Continental AG, Denso Corporation, Mitsuba Corp., Inteva Products LLC, Leopold Kostal GmbH, Brose Fahrzeugteile SE and Co. KG, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Anti-Pinch Power Window System Market Emerging Trajectories
Intelligent actuator architectures are displacing discrete component assemblies as automakers specify integrated door-system modules that bundle sensing, control, and motor functions into single supplier relationships.
Capacitive sensing arrays are electrifying obstruction detection by replacing mechanical Hall-effect configurations with electrode patterns embedded in window seals, enabling detection of non-conductive objects like limbs and fabric that resist magnetic field disruption. Korean and Chinese OEMs are specifying these arrays for premium electric vehicle programs where minimal moving parts align with reliability targets. This electrification is compressing the addressable market for standalone Hall-effect sensor suppliers and consolidating value capture within seal-integrated system providers.
UNECE R21's 2023 technical amendments tightened pinch-force measurement protocols and expanded temperature validation ranges, compelling suppliers to redesign test fixtures and recalibrate production-line quality systems. The regulation's industrial consequence is a bifurcation between multinational Tier-1s with existing climatic test chambers and mid-tier suppliers facing six-figure capital commitments to maintain homologation eligibility. European premium OEMs are responding by consolidating supplier panels around vertically integrated door-system specialists capable of self-certifying across the expanded protocol matrix.
Fleet procurement departments are unbundling window system service contracts from comprehensive maintenance agreements, creating standalone aftermarket revenue pools for diagnostic software subscriptions and predictive replacement scheduling. Commercial vehicle operators in North America are driving this disintermediation through telematics platforms that aggregate component-level failure data to negotiate direct relationships with module manufacturers. The behavior is most visible in rental fleet verticals where vehicle utilization metrics justify premium pricing for guaranteed uptime clauses tied to real-time window system health monitoring.
Automotive Anti-Pinch Power Window System Market Segmentation
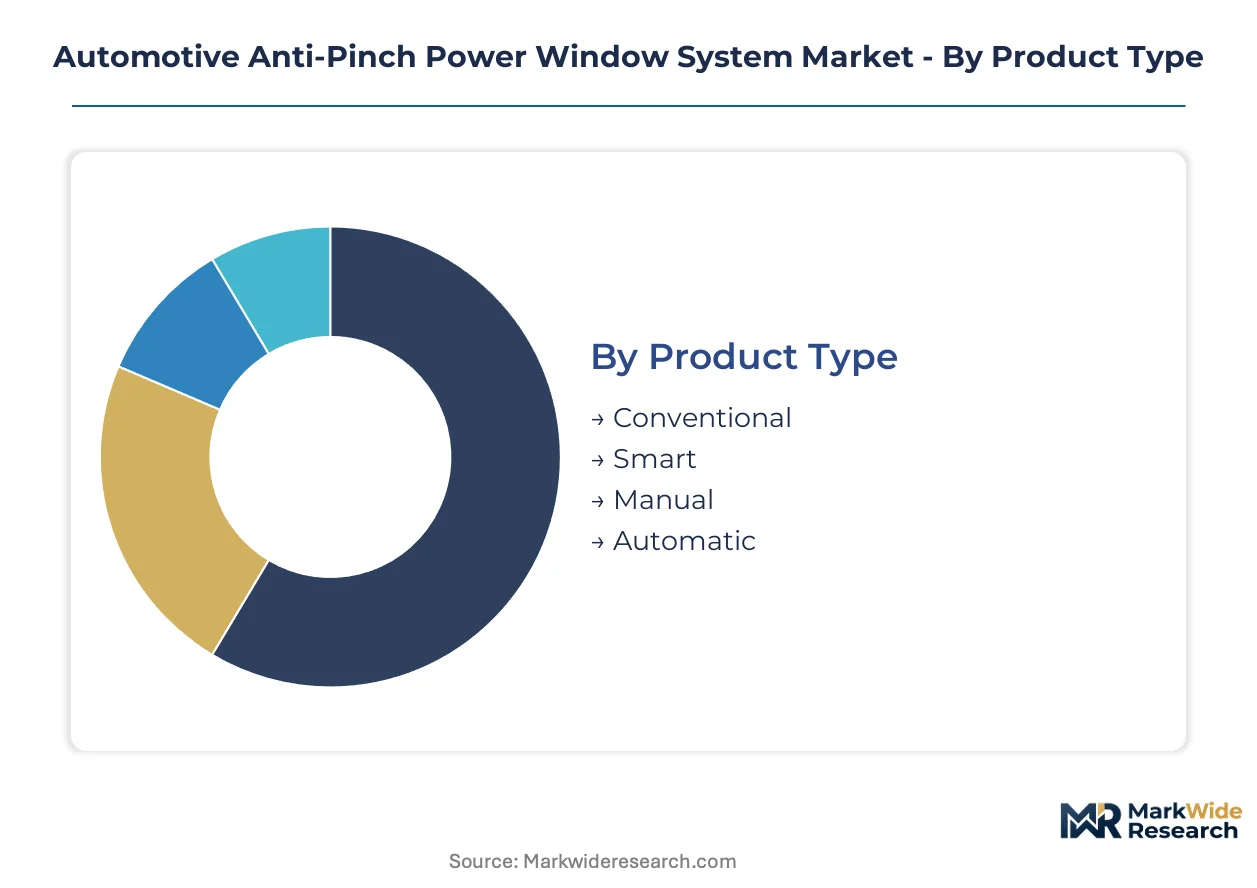
Anti-pinch power window systems fragment across four distinct dimensions that shape procurement economics and supplier relationships. Product type and technology determine hardware margins and firmware monetization potential. End-user and installation channels dictate certification burdens and geographic concentration of demand.
Product Type:
Buyers differentiate primarily by intelligence tier and connectivity requirements, with premium OEMs prioritizing predictive maintenance integration while cost-sensitive segments accept baseline functionality.
- Smart:Embedded motor-control firmware enables over-the-air calibration updates and smartphone-linked diagnostics. German luxury OEMs specify these variants for frameless door architectures requiring sophisticated sensor fusion.
- Automatic:Hall-effect sensor arrays with current-sensing algorithms detect obstructions and reverse motor direction within milliseconds. Demand concentrates in mid-market passenger vehicles across China and India where semiconductor cost curves enable electromechanical deployment.
- Conventional:Basic obstruction detection without predictive capabilities serves mechanical redundancy requirements in cost-sensitive segments.
- Manual:Pure mechanical regulators satisfy baseline regulatory thresholds in emerging market entry-level vehicles.
Volume sits with Automatic; growth tilts toward Smart.
Technology:
Technology selection tracks regulatory stringency and thermal validation requirements, with electrical architectures commanding premium pricing where UNECE R21 and FMVSS 118 enforcement is strictest.
- Electrical:DC motors with Hall-effect sensors and rubber-sealed regulator mechanisms dominate factory-fitted installations. NHTSA's pinch-force thresholds compel OEM adoption across all US passenger vehicle classes.
- Hybrid:Electromechanical architectures blend sensor accuracy with mechanical backup for cost-sensitive segments in Southeast Asia where certification complexity favors redundant designs.
- Mechanical:Pure mechanical anti-pinch satisfies baseline requirements in India's domestic production scaling without electrical system premiums.
- Pneumatic:Compressed-air actuation serves specialized commercial vehicle applications with extreme temperature cycling requirements.
Electrical systems capture the dominant revenue share; hybrid configurations are expanding most quickly in emerging markets.
End User:
End-user category determines contract structure, with OEMs demanding integrated body-electronics platforms while aftermarket channels compete through diagnostic software subscriptions.
- OEMs:Factory-fitted specifications bundle anti-pinch with central gateway modules, consolidating supplier relationships around vertically integrated door-system specialists capable of self-certification.
- Tier-1 Suppliers:Robert Bosch GmbH and Continental AG anchor intelligent actuator production through captive semiconductor divisions and integrated firmware development.
- Aftermarket Providers:Bluetooth-linked diagnostic modules enable independent service channels to compete with dealer networks through predictive maintenance alerts.
- Vehicle Assemblers:Maruti Suzuki and Tata Motors in India generate localized demand for systems qualifying under PLI scheme incentives.
OEMs command the value pool; aftermarket channels are gaining share fastest through fleet procurement disintermediation.
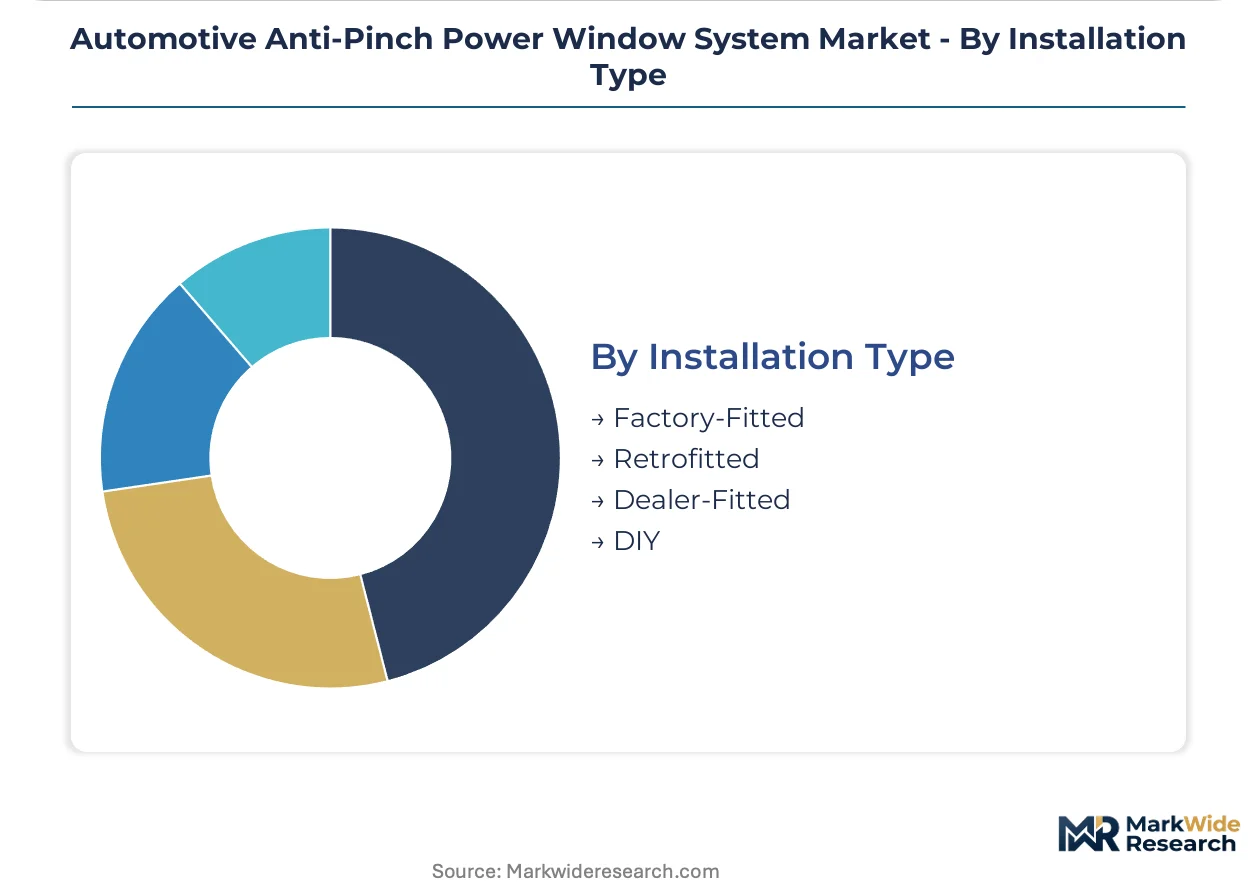
Installation Type:
Installation channel shapes margin structure, with factory-fitted capturing recurring firmware revenue while retrofitted channels face compression from homologation fragmentation.
- Factory-Fitted:Embedded at vehicle assembly with full climatic validation and regulatory compliance. Premium German and Japanese OEMs specify these for smart window deployments.
- Dealer-Fitted:Authorized service channels maintain warranty attribution and protocol translation compatibility with legacy gateway architectures.
- Retrofitted:Post-vehicle-sale installation faces margin pressure from redundant validation cycles across UNECE R21, China's GB standards, and Japan's JIS frameworks.
- DIY:Consumer self-installation remains minimal due to safety-critical functional requirements and liability exposure.
Factory-Fitted dominates absolute volume; Dealer-Fitted shows the steepest expansion trajectory as fleet operators unbundle service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and Japan where luxury OEMs factory-fit smart window systems, while consumption tilts toward China and India as domestic vehicle assembly scales. Regulatory divergence between NHTSA's FMVSS 118, UNECE R21, and China's GB standards fragments homologation requirements across major markets.
United States
NHTSA's FMVSS 118 mandates pinch-force thresholds across all passenger vehicle classes, compelling OEM adoption of compliant electromechanical systems. Fleet procurement departments in North America unbundle window system service contracts through telematics platforms that aggregate component-level failure data. Michigan's automotive corridor anchors intelligent actuator development for premium domestic OEMs.
Germany
Luxury passenger vehicle OEMs expand factory-fitted smart window deployments requiring sophisticated sensor fusion for frameless door architectures. UNECE R21's 2023 technical amendments tightened pinch-force measurement protocols and expanded temperature validation ranges. Stuttgart and Munich host vertically integrated door-system specialists capable of self-certifying across the expanded protocol matrix.
China
Domestic vehicle production scaling generates localized demand for anti-pinch systems that bypass import duties and align with GB standards test protocols. Semiconductor manufacturing scale in East Asia drives down per-unit Hall-effect sensor costs, enabling electromechanical deployment in mid-market segments. Shanghai and Guangzhou anchor captive production for state-owned OEMs and emerging EV brands.
India
Maruti Suzuki and Tata Motors' capacity expansion generates demand for systems qualifying under PLI scheme incentives with localized sourcing requirements. Cost-sensitive segments continue specifying mechanical anti-pinch designs that satisfy baseline regulatory requirements without electrical system premiums. Tamil Nadu and Gujarat host vehicle assembly clusters where domestic Tier-1 suppliers compete on import substitution.
Japan
JIS frameworks add regional test protocols that complement UNECE R21 requirements for multinational component manufacturers serving export markets. Hall-effect sensor cost curves enable electromechanical system deployment across kei-car and compact segments previously served by mechanical regulators. Aichi Prefecture's Toyota City and Yokohama corridor concentrate motor-control firmware development for integrated body-electronics platforms.
Automotive Anti-Pinch Power Window System Market Vendor Landscape
Top-tier vendors anchor integrated door-system supply, while mid-tier specialists compete on regional certification speed and cost-optimized mechanical architectures. The supplier base stratifies between semiconductor-anchored conglomerates with captive motor-control divisions and mechatronics specialists focused on door-system integration. Three archetypes dominate: vertically integrated electronics platforms, door-system mechatronics purists, and regional cost-optimized fabricators. Competitive moves center on firmware intellectual property accumulation and climatic validation capacity expansion.
Among German-based diversified suppliers, Robert Bosch GmbH and Continental AG occupy positions representing semiconductor-anchored and integrated body-electronics archetypes respectively. Brose Fahrzeugteile SE and Co. KG exemplifies the door-system mechatronics specialist model with concentrated relationships in premium European OEM supply chains.
| Leading Market Players |
|---|
| Aisin |
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Mitsuba Corp. |
| Inteva Products LLC |
| Leopold Kostal GmbH |
| Brose Fahrzeugteile SE and Co. KG |
| Valeo SA |
| Others |
Supply Flow & Price Mechanics
Fleet procurement unbundling of window system service contracts forces suppliers to restructure revenue models around firmware subscriptions rather than per-unit hardware margins, compressing transactional pricing while elevating recurring revenue capture.
Pricing Analysis
Margin tightening in mid-market electromechanical systems reflects Hall-effect sensor cost curves from East Asian semiconductor scale. Three-tier pricing structure across smart, automatic, and conventional levels separates predictive maintenance-enabled variants from baseline obstruction-detection modules. Cost-down pressure on hybrid architectures accelerates because mechanical redundancy satisfies India's PLI scheme requirements without electrical premiums. Aftermarket channels exhibit highest price sensitivity due to homologation fragmentation across UNECE R21, China's GB standards, and Japan's JIS frameworks.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese export quota administration for neodymium and dysprosium essential to DC motor production. Captive semiconductor fabrication in Germany and Japan feeds intelligent actuator development, while rubber-sealed regulator mechanisms source from Thailand and Mexico assembly clusters. Single-source vulnerability concentrates in East Asian Hall-effect sensor wafer processing. Distribution runs through vertically integrated door-system specialists capable of self-certifying across expanded UNECE R21 temperature validation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Climatic validation capacity scarcity props pricing for suppliers with existing test chambers, constraining mid-tier competitors from UNECE R21 compliance and consolidating procurement around self-certifying specialists.
For Market Incumbents: Deepen captive motor-control firmware development to defend against software-defined calibration subscriptions eroding hardware margins. Expand climatic test chamber capacity in Germany to maintain homologation eligibility under UNECE R21's 2023 technical amendments. Prioritize backward integration into Hall-effect sensor supply through long-term offtake agreements insulating against rare earth volatility.
For New Entrants and Emerging Players: Bluetooth-linked diagnostic modules offer a service-channel route to bypass dealer network warranty attribution and capture fleet procurement disintermediation in North America. Target India's domestic production scaling under PLI scheme incentives where import substitution creates white-space for localized Tier-1 suppliers. Pursue biometric entry convergence partnerships requiring window control modules communicating with centralized body-computer architectures.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated door-system specialists with self-certification capacity across UNECE R21, FMVSS 118, and JIS protocol matrices. Long-term viability hinges on firmware intellectual property accumulation and real-time systems talent retention against semiconductor competitor poaching. Watch for fleet telematics platform aggregation of component-level failure data as signal of direct manufacturer relationship normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Firmware Monetization | Over-the-air calibration subscriptions capture recurring revenue from German luxury OEM smart window deployments. |
| Climatic Validation Capacity Expansion | Self-certifying test chambers maintain UNECE R21 eligibility as 2023 amendments tighten temperature protocols. |
| Rare Earth Supply Securement | Long-term offtake agreements insulate DC motor cost structures from Chinese export quota volatility. |
| Biometric Entry Integration | Window control modules communicating with fingerprint systems address European premium OEM frameless door architectures. |
| India PLI Localization | Maruti Suzuki and Tata Motors capacity expansion generates import-substituting demand for domestic Tier-1 suppliers. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combined with primary interviews across Tier-1 supplier procurement, OEM platform engineers, aftermarket distributors, and dealership operations. NHTSA FMVSS 118 documentation, UNECE R21 technical amendments, China's GB standards publications, and Japan's JIS frameworks provided regulatory validation. Vehicle production databases and IHS Markit registration data supplied demand-side calibration. Bottom-up component cost modeling and top-down OEM specification analysis triangulated market sizing.
Segment-level modeling addressed product type intelligence tiers, technology architecture selection, end-user contract structures, and installation channel margin profiles across the projection horizon. Propulsion architecture, vehicle class content per vehicle, and regional production cluster concentration shaped analytical granularity. CAGRs derived from installed base rollover rates and specification penetration curves. Forecast inputs incorporated semiconductor cost curve trajectories and regulatory amendment implementation timelines.
The model holds under stable rare earth supply and continued UNECE R21 enforcement; deviation in Chinese export quota administration or FMVSS 118 threshold revision would shift supplier competitive positioning. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automatic Emergency Braking Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
China Airbag Systems Market
Automotive Safety and Security Systems
Biometric in the Automotive Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Automotive Battery Pack Fire Barrier Pad Market
Automotive Safety and Security Systems
Active Spoiler Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Asia-Pacific Airbag Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market
Automotive Safety and Security Systems
Automotive Active Health Monitoring System Market
Automotive Safety and Security Systems
Automotive Personal Assistance System Market
Automotive Safety and Security Systems
Global Automotive Mirror Replacement System Market