
 Automotive Keyless Entry System Market | 2026-2036
Automotive Keyless Entry System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Keyless Entry System Market Analysis
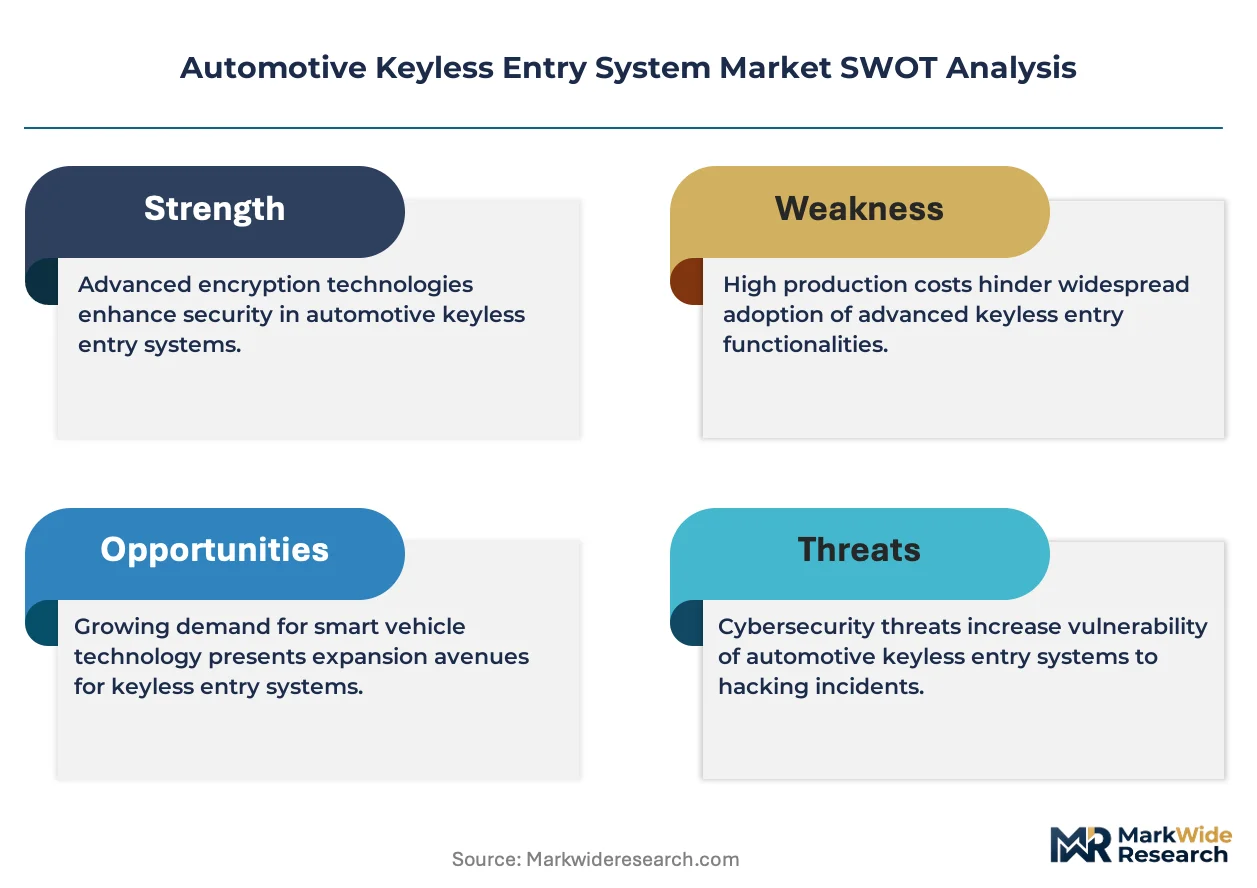
Modular bundling of keyless entry with digital key and smartphone integration is hardening as the default product configuration. Valeo SA leverages its electronics portfolio to anchor factory-installed passive entry systems across European OEM programs. Robert Bosch GmbH competes through R&D intensity in ultra-wideband positioning for centimeter-level accuracy. Denso Corporation specializes in thermal-stable transceivers for extreme climate deployment.
An automotive keyless entry system comprises a radio-frequency transceiver, encrypted controller unit, and actuator array that authenticates proximity or command signals to unlock doors and enable ignition without physical key insertion. These systems operate at low-frequency bands for wake-up and ultra-high-frequency for data exchange, with AES-128 encryption now standard for relay-attack prevention. Smart Key and Passive Entry categories dominate value capture due to semiconductor content and software licensing, while Mobile App integration represents the fastest-expanding installation pathway as OEMs seek subscription revenue. Bluetooth Key and RFID segments occupy mature margin pools where component commoditization pressures pricing.
NHTSA cybersecurity guidelines, ECE R116 vehicle alarm standards, and China's GB/T automotive encryption protocols collectively mandate relay-attack countermeasures and secure element architecture. EMA and EU AI Act adjacent compliance for biometric vehicle access is tightening certification timelines for suppliers targeting European OEMs. Stakeholders must monitor regulatory divergence between NHTSA software-bill-of-materials requirements and China's SAMR data-localization rules for connected key systems.
Market Dynamics
Ultra-wideband positioning is compressing authentication latency from seconds to milliseconds, forcing incumbent suppliers to redesign transceiver architectures around centimeter-level accuracy requirements.
Growth Catalysts
- NHTSA Cybersecurity Guidelines:Mandatory secure-element architecture for relay-attack prevention is accelerating hardware refresh cycles across US OEM supply chains.
- Luxury Vehicle Segment:Passive entry bundling with digital key platforms is driving semiconductor content expansion in Germany's premium manufacturing corridor.
- Bluetooth Low Energy 5.3:Extended range and directional finding capabilities are enabling smartphone-as-key deployment without dedicated fob hardware.
Market Restraints
- Semiconductor Supply Concentration:Advanced secure-element fabrication clusters in Taiwan create single-source vulnerability for AES-128 encryption modules.
- ECE R116 Certification Burden:Extended vehicle alarm standard validation timelines stretch product development cycles by eight to fourteen months.
- RFID Commoditization:Mature 125 kHz proximity technology faces margin compression from unlicensed Asian module suppliers.
Strategic Opportunities
- Subscription Revenue Models:Mobile app key provisioning enables recurring licensing fees from fleet operators and mobility-as-a-service platforms.
- EU AI Act Adjacent Compliance:Biometric vehicle access integration creates certification moats for suppliers with facial recognition firmware capabilities.
- India Automotive Corridor:Underpenetrated passive entry installation rates in domestic OEM programs offer first-mover positioning for localized transceiver sourcing.
Industry Challenges
- UWB Talent Scarcity:Radio-frequency engineering specialization for centimeter-level positioning exceeds available workforce supply in European automotive electronics hubs.
- Legacy Controller Integration:Encrypted controller unit retrofitting with 2018-2022 vehicle platforms demands costly gateway hardware redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Keyless Entry System Market |
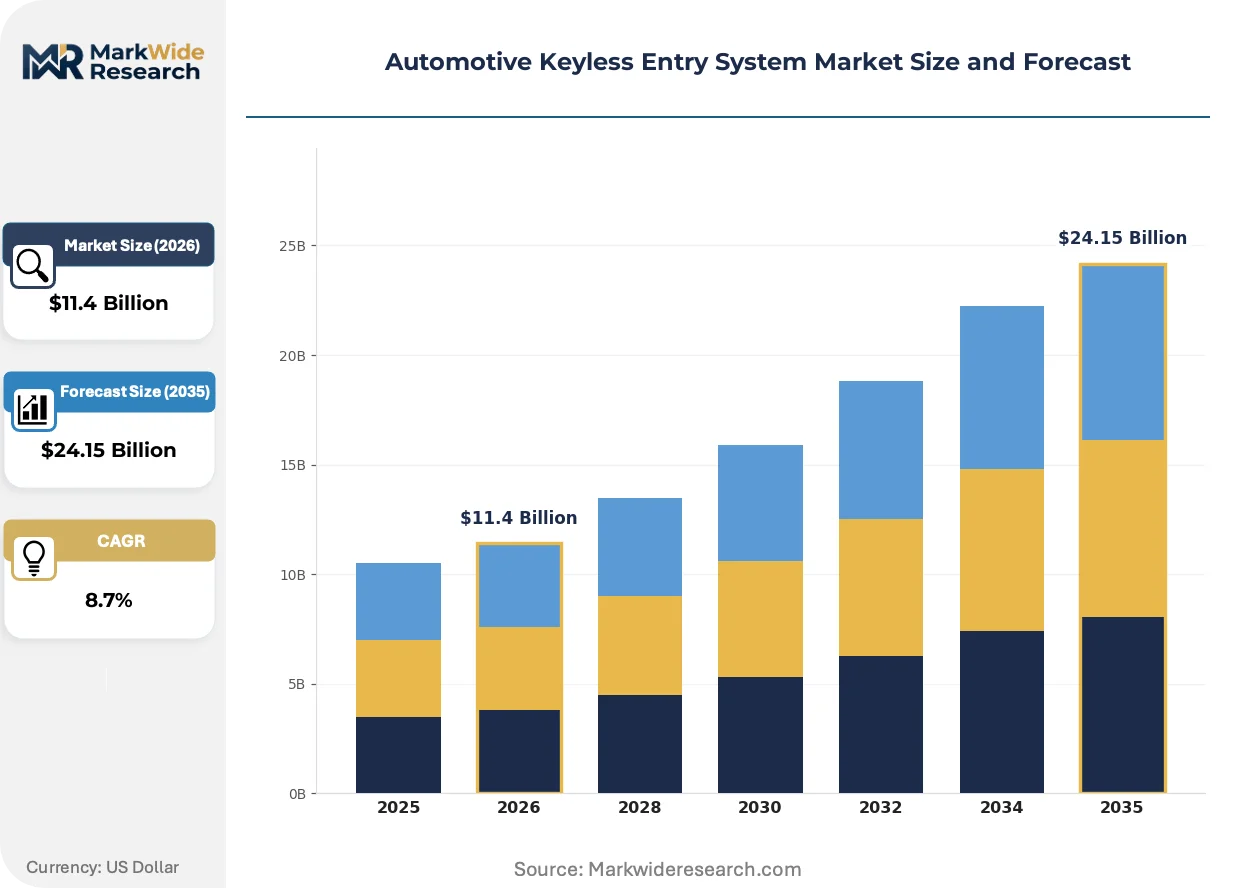
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Key, Remote Key, Key Fob, Bluetooth Key Technology: Passive Entry, Active Entry, RFID, Mobile App End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Factory-installed, Dealer-installed, DIY, Retrofit |
| Companies Covered | Valeo SA, Hyundai Mobis Co. Ltd., Robert Bosch GmbH, HELLA GmbH & Co. KGaA, Mitsubishi Electric Corporation, Denso Corporation, ZF Friedrichshafen AG, Huf Hülsbeck & Fürst GmbH & Co. KG, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Keyless Entry System Market Emerging Trajectories
Authentication protocols are migrating from radio-frequency identification toward software-defined access credentials, compressing hardware bill-of-materials while expanding attack surface management requirements.
Ultra-wideband ranging is automating proximity detection for passive entry activation, eliminating false unlock events from relay attacks. German luxury OEMs are mandating UWB inclusion in 2026 model year architectures. This shift is automating the displacement of legacy Bluetooth-only positioning in premium vehicle segments.
EU AI Act framework classification for biometric vehicle access is mandating algorithmic transparency documentation and human oversight protocols. Tier-1 suppliers must embed explainability modules in facial recognition firmware. European premium OEM programs face the tightest compliance deadlines, with certification submissions required eighteen months ahead of production ramp.
Fleet procurement departments are consolidating keyless entry specification authority from individual dealership networks to centralized mobility platform operators. Bulk digital key licensing is replacing per-vehicle fob procurement in corporate fleet channels. This concentration is most visible in Germany's commercial vehicle leasing market, where single contracts now cover ten thousand-plus vehicle access credentials.
Automotive Keyless Entry System Market Segmentation
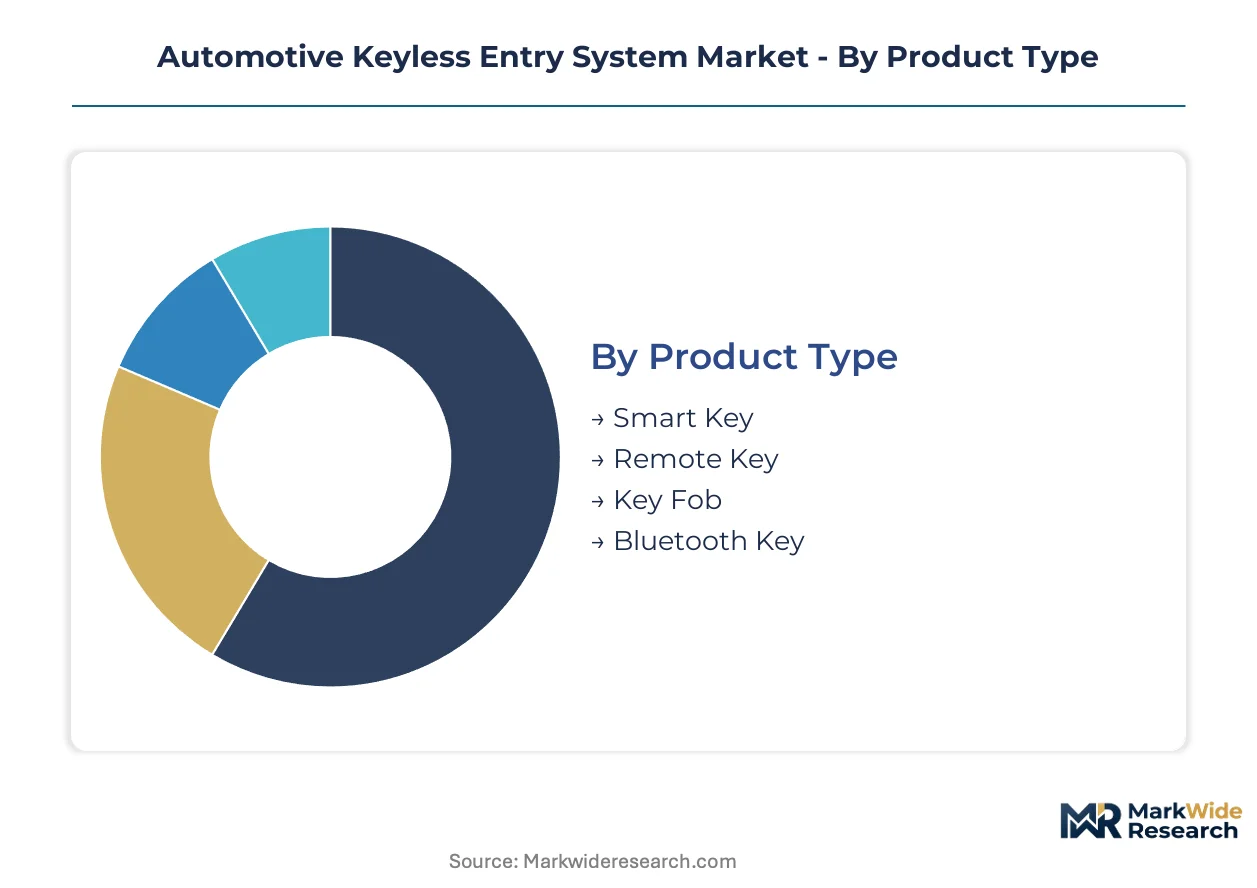
Segmentation in automotive keyless entry reveals how certification requirements, semiconductor content, and installation pathways split value capture across supplier tiers. Each dimension carries distinct regulatory burdens and margin structures that shape competitive positioning.
Product Type:
Certification intensity varies sharply by product type, with NHTSA cybersecurity guidelines and ECE R116 alarm standards imposing tiered validation requirements on encrypted versus non-encrypted variants.
- Smart Key:Combines passive entry transceivers with encrypted controller units and directional antenna arrays for proximity detection. Demand concentrates in Germany's premium manufacturing corridor where OEMs bundle digital key platforms with factory-installed systems. NHTSA secure-element mandates accelerate hardware refresh cycles for AES-128 modules.
- Bluetooth Key:Leverages BLE 5.3 extended range and directional finding to enable smartphone-as-key deployment without dedicated fob hardware. Germany's commercial vehicle leasing market drives bulk digital key licensing contracts covering ten thousand-plus credentials. Relay-attack countermeasures require continuous firmware updates.
- Remote Key:Active radio-frequency transceivers operating at ultra-high-frequency bands for command-based door unlock. Mature installation base in economy vehicle segments.
- Key Fob:Physical housing for transponder chips with mechanical key backup. Faces margin compression from unlicensed Asian module suppliers.
Smart Key sits at the top of the volume ranking, with Bluetooth Key climbing the fastest.
Technology:
Cost tiering separates semiconductor-intensive positioning technologies from mature radio-frequency implementations with commoditized component sourcing.
- Passive Entry:Ultra-wideband and low-frequency wake-up circuits enable hands-free door unlock when authorized devices enter proximity zones. Germany, Japan, and the United States drive luxury vehicle segment adoption where centimeter-level accuracy commands premium pricing. UWB talent scarcity in European automotive electronics hubs constrains supplier expansion.
- Mobile App:Software-defined credentials provisioned through OEM cloud platforms enable subscription revenue from fleet operators and mobility-as-a-service providers. India's underpenetrated domestic OEM programs offer first-mover positioning for localized transceiver sourcing. EU AI Act biometric compliance creates certification moats for facial recognition integration.
- Active Entry:Button-activated radio-frequency transmission requiring deliberate user action. Dominates mid-market vehicle configurations.
- RFID:Legacy 125 kHz proximity technology for basic access control. Mature margin pools face pricing pressure from component commoditization.
Passive Entry dominates value capture, while Mobile App gains share fastest through recurring licensing models.
End User:
Customer type determines procurement authority concentration, with fleet operators and platform managers displacing individual dealership networks in specification control.
- OEMs:Factory integration of keyless entry with connected vehicle platforms and digital key ecosystems. Germany's automotive manufacturing corridor anchors demand for modular bundling with cybersecurity-compliant architectures.
- Tier-1 Suppliers:Subsystem provision to OEM assembly lines with validated ECE R116 certification documentation. Extended validation timelines stretch product development cycles.
- Aftermarket Providers:Retrofit installation for vehicle parc outside factory warranty coverage. Price-sensitive channel with compressed margins.
- Vehicle Assemblers:Contract manufacturing arrangements for regional market adaptation. Localized sourcing requirements in India's automotive corridor.
OEMs command the highest procurement volumes, with Tier-1 Suppliers expanding most quickly through platform consolidation.
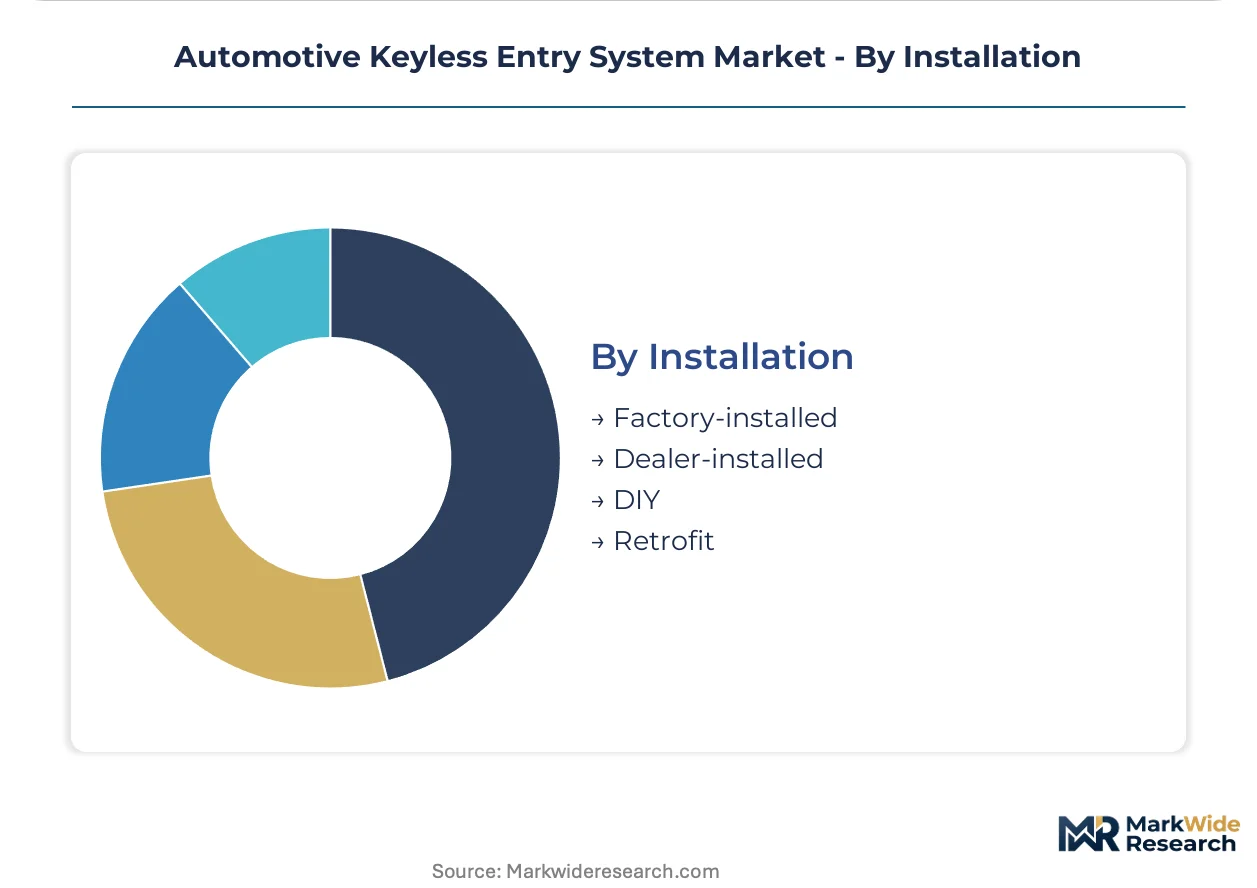
Installation:
Margin structure inverts between factory-integrated architectures with embedded secure elements and retrofit pathways requiring gateway hardware redesigns.
- Factory-installed:Embedded controller units with AES-128 encryption and ultra-wideband positioning specified at vehicle design phase. German luxury OEMs mandate UWB inclusion in 2026 model year architectures.
- Retrofit:Aftermarket controller integration with legacy 2018-2022 vehicle platforms demanding costly gateway hardware modifications. Cybersecurity validation adds certification burden.
- Dealer-installed:Authorized service center programming of OEM-approved modules. Intermediate pricing tier with warranty coverage.
- DIY:Consumer self-installation of basic radio-frequency modules. Lowest certification requirements and highest security vulnerability exposure.
Factory-installed leads installation volumes, with Retrofit climbing fastest as vehicle parc renewal accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor birthed modern passive entry technology during the 1990s premium vehicle wave. Today, supplier ecosystems in Stuttgart and Munich continue defining certification standards for encrypted controller architectures. Three additional national markets now shape deployment trajectories through distinct regulatory and procurement channels.
United States
NHTSA cybersecurity guidelines mandate secure-element architecture for relay-attack prevention across Detroit's OEM supply chains. The agency's software-bill-of-materials requirements compress hardware refresh cycles for AES-128 encryption modules. Michigan's automotive electronics corridor anchors factory-installed passive entry integration with connected vehicle platforms.
Germany
KBA vehicle type approval processes enforce ECE R116 alarm standard validation stretching product development timelines. The EU AI Act's biometric vehicle access classification tightens certification deadlines for Tier-1 suppliers targeting premium OEM programs. Bavaria's manufacturing belt concentrates UWB transceiver R&D for 2026 model year architectures.
Japan
METI industrial standards coordinate thermal-stable transceiver specifications for extreme climate deployment across domestic OEM programs. JIS encryption protocols align with global AES-128 mandates while preserving proprietary wake-up circuit architectures. Nagoya's automotive electronics cluster specializes in low-frequency band optimization for hands-free activation systems.
China
MIIT GB/T automotive encryption protocols mandate data-localization rules for connected key systems distinct from NHTSA frameworks. SAMR cybersecurity certification creates dual compliance burdens for multinational suppliers serving joint-venture OEMs. Yangtze River Delta manufacturing hubs concentrate secure-element fabrication for domestic passive entry module production.
India
BIS automotive electronics standards phase in passive entry requirements for domestic OEM programs previously limited to manual key systems. PLI scheme incentives attract localized transceiver sourcing for Tier-1 suppliers avoiding import duty compression. Tamil Nadu's automotive corridor hosts first-mover positioning for factory-installed keyless entry in compact vehicle segments.
Automotive Keyless Entry System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity and semiconductor content dimensions. The vendor base stratifies between full-system integrators owning encrypted controller architectures and module suppliers facing commoditization pressure in legacy RFID implementations. Three archetypes dominate: diversified automotive electronics conglomerates, specialized transceiver technology houses, and diversified Tier-1 chassis-electronics suppliers. Competitive moves concentrate on strategic partnerships for UWB talent access and portfolio diversification into biometric authentication firmware.
Within the diversified electronics tier, Valeo SA, Robert Bosch GmbH, and Denso Corporation exemplify distinct geographic anchoring strategies. The Paris-based conglomerate represents European factory-installed system integration. The Stuttgart-based GmbH occupies German precision-positioning specialization. The Aichi-based Corporation anchors Japanese thermal-engineering capabilities for climate-extreme deployment. Each exemplifies how regional automotive corridors shape competitive positioning without converging on identical technology vectors.
| Leading Market Players |
|---|
| Valeo SA |
| Hyundai Mobis Co. Ltd. |
| Robert Bosch GmbH |
| HELLA GmbH & Co. KGaA |
| Mitsubishi Electric Corporation |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
NHTSA cybersecurity guidelines for secure-element architecture gate qualified supply access and premium-tier pricing power, compressing hardware refresh cycles for AES-128 encryption modules while OEMs absorb certification costs into factory-installed system bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UWB-enabled passive entry from BLE-only configurations and legacy RFID implementations. Certification grade under ECE R116 and NHTSA cybersecurity tiers drives price differentiation, with AES-128 secure-element modules commanding substantial premiums over basic transceiver assemblies. Cost compression in RFID proximity technology is intensifying because unlicensed Asian module suppliers flood aftermarket channels. Fleet operators and mobility-as-a-service platforms exhibit lowest price sensitivity due to subscription revenue models, while DIY retrofit consumers face highest sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from German and US OEMs mandate multi-supplier qualification for AES-128 encryption modules and UWB transceiver chipsets. Geographic supply concentration centers on Taiwan for advanced secure-element fabrication, Germany for precision-positioning R&D, and Japan for thermal-stable transceiver engineering. Raw material dependencies include silicon wafers, rare-earth magnets for antenna arrays, and specialized RF substrate materials. Single-source vulnerability in Taiwan-based fabrication creates structural risk exposure. Distribution runs through Tier-1 supplier consolidation into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive keyless entry system market reads as a late-cycle quality story, with demand shifting decisively toward UWB-enabled passive entry specifications that bundle cybersecurity compliance with centimeter-level accuracy.
For Market Incumbents: Anticipate margin compression in legacy Bluetooth-only positioning as German luxury OEMs mandate UWB inclusion in 2026 model year architectures. Defensive consolidation moves require backward integration into secure-element sourcing and captive UWB talent acquisition in European automotive electronics hubs. Certification investment in EU AI Act biometric compliance creates moats against emerging firmware specialists. For New Entrants and Emerging Players: BIS automotive electronics standards in India open a window for localized transceiver sourcing partnerships with domestic OEM programs previously limited to manual key systems. White-space targets include factory-installed passive entry for compact vehicle segments and facial recognition firmware for EU AI Act adjacent compliance. Go-to-market positioning through PLI scheme incentives attracts first-mover manufacturing footprint in Tamil Nadu's automotive corridor. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized UWB transceiver technology houses lacking OEM platform scale. Long-term viability over a five-to-ten year window hinges on secure-element architecture ownership and biometric authentication firmware capabilities. Acquisition target archetype: mid-cap suppliers with validated ECE R116 documentation and European premium OEM program relationships. Signal to watch: fleet procurement consolidation toward centralized mobility platform operators.| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-Wideband Transceiver Development | Centimeter-level positioning accuracy meets German luxury OEM 2026 architecture mandates. |
| Secure-Element Architecture Investment | AES-128 encryption modules satisfy NHTSA cybersecurity guidelines across Detroit supply chains. |
| Biometric Authentication Firmware Integration | EU AI Act compliance creates certification barriers for Tier-1 suppliers targeting premium programs. |
| Localized Transceiver Sourcing in India | BIS standards and PLI incentives enable cost-competitive factory-installed systems for domestic OEMs. |
| Subscription Revenue Platform Development | Mobile app key provisioning captures recurring licensing from fleet operators and mobility-as-a-service providers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from automotive electronics conglomerates, and regulatory submission documents from NHTSA and KBA. Bottom-up volume modeling and top-down value triangulation anchored segmentation outputs.
Comparable-period anchoring linked historical passive entry installation rates through 2025 against projected technology transition curves across the modeling period. Segmentation dimensions modeled include product type, technology architecture, installation pathway, and regional production cluster. CAGRs derived from semiconductor content expansion trajectories and OEM platform bundling trends, with UWB adoption curves and subscription revenue penetration serving as automotive-specific forecast inputs.
Revisions become necessary when semiconductor supply concentration triggers materialize, regulatory divergence between NHTSA software-bill-of-materials requirements and China's SAMR data-localization rules intensifies, or UWB talent scarcity in European automotive electronics hubs constrains supplier expansion capacity. Deviation in secure-element fabrication capacity or EU AI Act certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Engine Braking System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Acoustic Vehicle Alerting System Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
Automotive Radar Market
Automotive Safety and Security Systems
Africa Vehicle Tracking System Market
Automotive Safety and Security Systems
Automotive Fusion Sensors Market
Automotive Safety and Security Systems
Global Automotive Terrain Response System Market
Automotive Safety and Security Systems
Automotive Active Safety System Market
Automotive Safety and Security Systems
Latin America Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market