
 Global Vehicle Camera Market | 2026-2036
Global Vehicle Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vehicle Camera Market Outlook
Market Context
Fleet management is expanding as the fastest-growing end-use vertical for vehicle cameras, driven by telematics integration and driver behavior monitoring requirements across logistics and ride-hailing operators. Continental AG leverages its integrated sensor portfolio to dominate OEM supply relationships for surround view systems. Robert Bosch GmbH sustains R&D intensity in digital camera signal processing, anchoring its position in European and Asian automotive electronics. Mobileye Global Inc. differentiates through computer vision silicon and software stacks that compete directly with tier-1 hardware suppliers for advanced driver-assistance platforms.
Technical Definition and Segment Structure
A vehicle camera is an electro-optical imaging device engineered to automotive-grade specifications, typically operating across temperature ranges from minus forty to eighty-five degrees Celsius with IP6K9K ingress protection, designed to capture real-time visual data for driver assistance, parking maneuvering, and autonomous navigation systems. Surround view systems command premium positioning within product type segments due to multi-camera fusion complexity and higher ASPs, while digital camera technology leads over analog formats as OEMs mandate higher resolution and night-vision compatibility. The installation type segment shows structural bifurcation: OEM channels capture volume scale through platform-standard designs, whereas aftermarket and retrofit categories serve aging vehicle parc demand with lower entry barriers and compressed margins.
Regulatory Framework
NHTSA mandates rear visibility standards for light vehicles in the United States, while Euro NCAP protocols in Europe incentivize front camera and autonomous emergency braking integration through star-rating linkages. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces specific field-of-view requirements for commercial vehicle camera systems. Stakeholders must monitor divergence between regional certification timelines and sensor fusion standards as regulatory fragmentation threatens platform economies of scale.
Market Dynamics
Multi-camera fusion architectures are compressing development timelines for surround view systems as OEMs consolidate supplier relationships around integrated platform providers capable of delivering thermal-tested, IP6K9K-rated modules at automotive-grade scale.
Growth Catalysts
- Euro NCAP safety mandates:Front camera integration requirements tied to star-rating protocols are forcing OEM platform redesigns across European passenger vehicle lines.
- Fleet telematics convergence:Logistics operators are mandating driver behavior monitoring systems that fuse camera data with GPS and accelerometer inputs for insurance compliance.
- Japan MLIT commercial requirements:Specific field-of-view standards for truck and bus camera systems are creating dedicated procurement channels for heavy-duty vehicle electronics.
Market Restraints
- Automotive-grade sensor supply concentration:High-temperature CMOS image sensor fabrication capacity clusters in Taiwan and South Korea, creating single-source vulnerability for tier-1 module assemblers.
- Multi-camera calibration complexity:Surround view systems require sub-millimeter alignment tolerances that inflate warranty costs and service bay time.
- Regulatory timeline divergence:NHTSA rear visibility deadlines, Euro NCAP front camera protocols, and Japan MLIT commercial mandates operate on non-synchronized certification cycles that fragment platform engineering resources.
Strategic Opportunities
- India commercial vehicle retrofit:Aging truck parc and new central motor vehicle rules create aftermarket demand for compliance-grade camera systems in logistics corridors.
- Camera-LiDAR sensor fusion:Convergence of optical imaging and laser ranging hardware is opening architecture slots for integrated perception modules in Level 2+ automation platforms.
- Direct OEM software licensing:Computer vision algorithm providers are bypassing tier-1 hardware channels to sell perception stacks directly to vehicle manufacturers seeking in-house integration control.
Industry Challenges
- Automotive vision software talent scarcity:Embedded systems engineers with ISO 26262 functional safety expertise command premium compensation that strains mid-tier supplier R&D budgets.
- Legacy vehicle electrical architecture incompatibility:Retrofit camera installations in pre-2015 vehicle parc require CAN bus gateway adaptations that multiply installation time and error rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vehicle Camera Market |
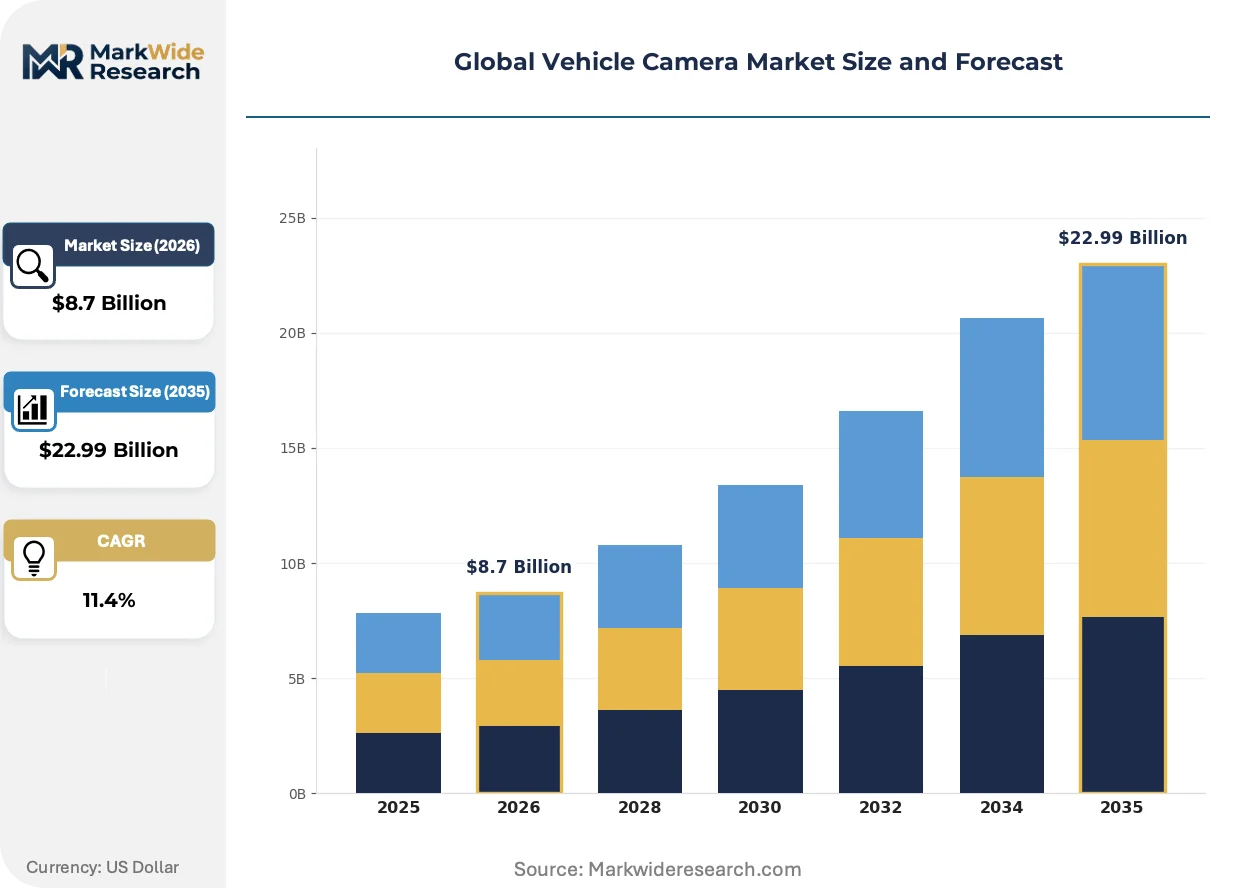
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rearview Cameras, Front Cameras, Surround View Systems, Dash Cameras Technology: Analog Cameras, Digital Cameras, Infrared Cameras, 360-Degree Cameras End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Fleet Management Installation Type: OEM, Aftermarket, Retrofit, Integrated Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Magna International Inc., Valeo SA, Denso Corporation, ZF Friedrichshafen AG, Aptiv PLC, Panasonic Holdings Corporation, Mobileye Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vehicle Camera Market Strategic Shifts
Edge-based neural inference is migrating from centralized domain controllers into camera module housings, redistributing computational load and altering supplier value capture across the perception stack.
Deep learning-based image signal processors are automating real-time scene understanding for pedestrian and cyclist detection without cloud connectivity dependency. Tier-1 suppliers in Germany and Japan are embedding these accelerators directly into camera housing electronics to reduce wiring harness complexity. This architecture shift is automating the displacement of discrete ECU-based processing nodes in favor of intelligent edge sensors.
NHTSA rear visibility regulations are mandating standardized field-of-view coverage and response time thresholds for all light vehicles under 10,000 pounds. The rule forces redesign of liftgate-mounted camera modules to withstand repeated mechanical stress and temperature cycling. OEMs serving the United States market are responding by consolidating surround view system suppliers to platforms pre-certified to FMVSS 111 test protocols.
Fleet procurement departments are unbundling camera hardware from telematics service contracts, creating direct purchasing relationships with module manufacturers previously accessed through system integrators. Logistics operators in North American and European freight corridors are driving this disintermediation to reduce per-unit costs across thousand-vehicle deployments. The practice is most visible in long-haul trucking where camera data feeds directly into driver scorecard platforms operated by insurance underwriters.
Global Vehicle Camera Market Segmentation
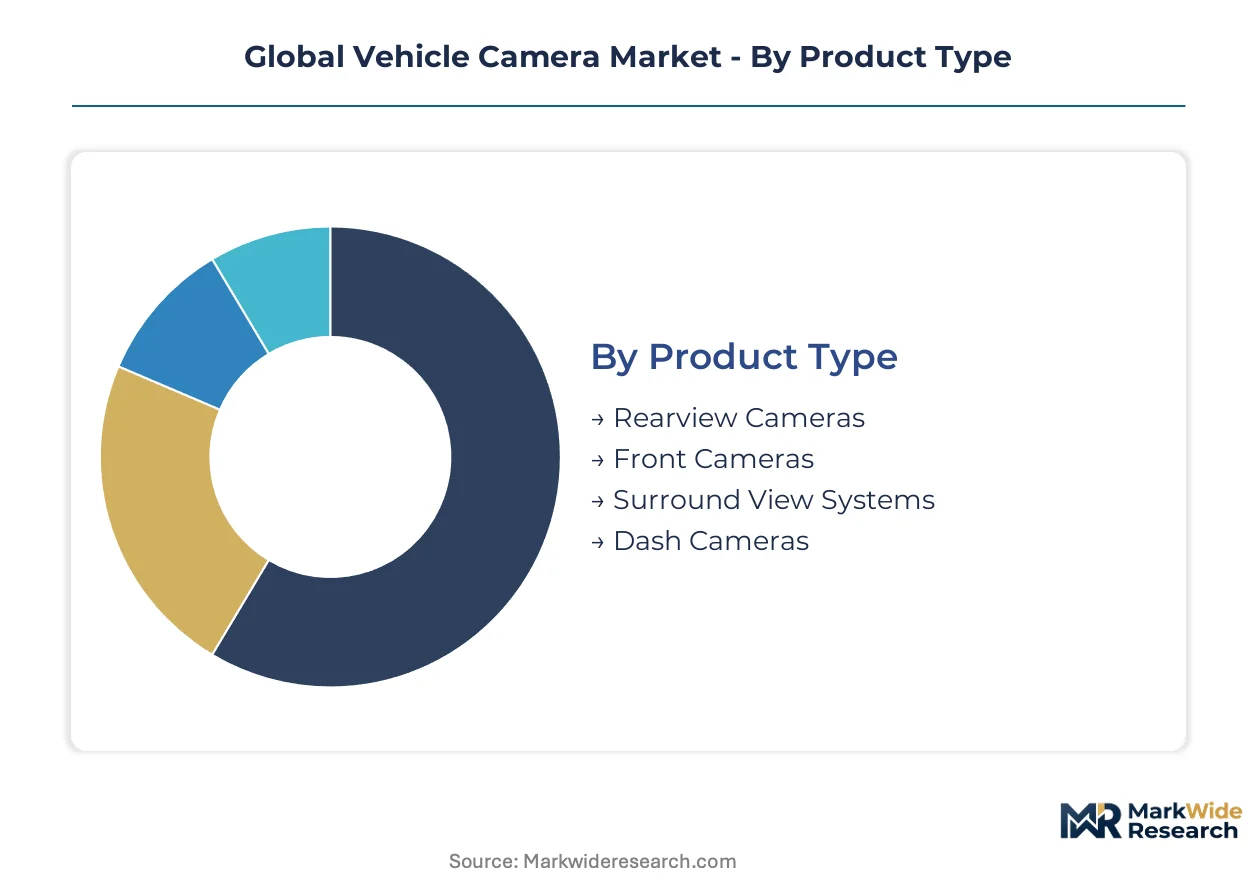
Vehicle camera procurement decisions follow distinct technical and commercial logics across automotive OEMs, fleet operators, and aftermarket installers. Upgrade cycles vary sharply between safety-mandated rearview retrofits and optional surround view premium features.
Product Type:
Replacement intensity differs dramatically across camera positions, with rearview units facing mandated refresh timelines while surround view systems ride platform redesign cycles.
- Rearview Cameras:Single-lens modules mounted at license plate or liftgate positions, engineered to NHTSA FMVSS 111 field-of-view and latency specifications. Demand concentrates in United States light vehicle lines where federal compliance deadlines force annual volume placements exceeding other positions.
- Surround View Systems:Multi-camera fusion architectures stitching four to six feeds into unified bird's-eye displays, requiring sub-millimeter calibration and IP6K9K sealing. Germany's premium OEM platforms anchor current revenue concentration, though Japan's compact vehicle segment is expanding adoption fastest.
- Front Cameras:Forward-facing units supporting autonomous emergency braking and lane-keeping assistance.
- Dash Cameras:Windshield-mounted recording devices serving insurance documentation and fleet liability management.
Volume placements concentrate in Rearview Cameras; the faster expansion belongs to Surround View Systems.
Technology:
Cost tiers separate legacy analog infrastructure from digital migration paths, with thermal imaging commanding specialized procurement channels.
- Digital Cameras:CMOS-based imaging with 1080p to 4K resolution, HDR processing, and night-vision enhancement. OEM platforms in Japan and Germany mandate digital exclusively for new vehicle introductions, displacing analog at fastest rate.
- 360-Degree Cameras:Omnidirectional lens systems capturing spherical video for immersive parking assistance. Fleet management operators in United States logistics corridors are adopting these for comprehensive incident reconstruction.
- Analog Cameras:CVBS signal format prevalent in pre-2020 vehicle parc and economy aftermarket replacements.
- Infrared Cameras:Thermal imaging sensors detecting pedestrian heat signatures beyond visible spectrum range.
Procurement scale tilts toward Digital Cameras; Infrared Cameras are climbing the fastest as night-vision requirements spread.
End User:
Customer type determines specification rigor, with commercial duty cycles demanding enhanced vibration tolerance and warranty terms.
- Fleet Management:Telematics-integrated camera systems supporting driver behavior scoring, insurance compliance, and cargo security. Logistics operators across Germany, Japan, and United States are unbundling hardware from service contracts to drive per-unit costs down.
- Electric Vehicles:Camera architectures optimized for high-voltage electrical environments and extended software update horizons. China's NEV platforms and Tesla's vertical integration are expanding specification influence.
- Passenger Vehicles:Consumer-grade safety and convenience features across mass-market and premium segments.
- Commercial Vehicles:Heavy-duty truck and bus applications subject to Japan MLIT field-of-view mandates.
Passenger Vehicles dominate unit placements; Fleet Management is gaining share fastest as telematics convergence accelerates.
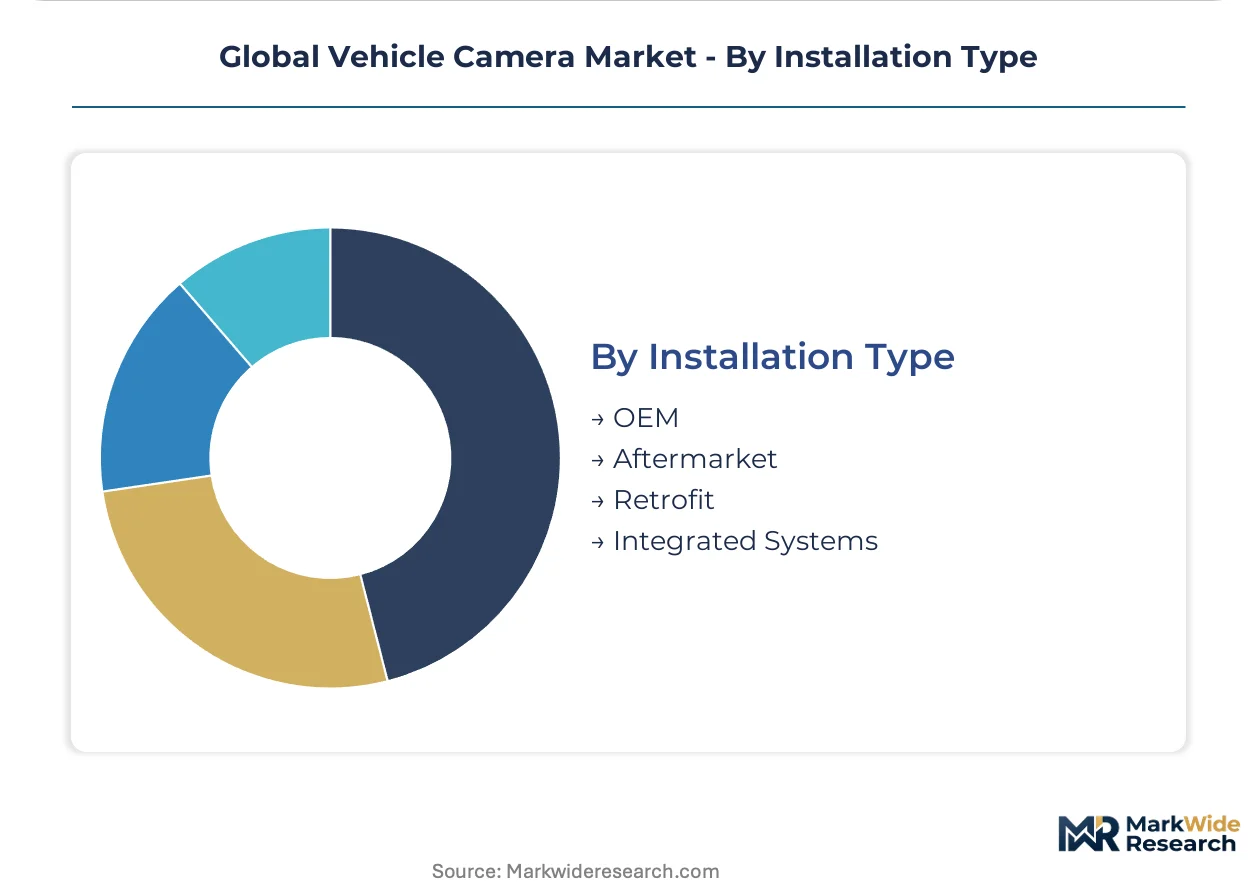
Installation Type:
Channel structure reflects vehicle age distribution and regulatory enforcement intensity across national markets.
- OEM:Factory-integrated modules specified at platform design phase with automotive-grade validation and multi-year supply agreements. Germany's tier-1 supplier ecosystems and Japan's keiretsu relationships concentrate procurement power.
- Aftermarket:Dealer and independent installer channels serving warranty expiration replacements and feature upgrades. India's aging truck parc and new central motor vehicle rules are creating compliance-driven demand corridors.
- Retrofit:Post-manufacture additions to pre-2015 vehicle parc requiring CAN bus gateway adaptations.
- Integrated Systems:Camera modules bundled with domain controllers and software stacks.
OEM captures highest volume scale; Aftermarket is expanding most quickly as regulatory retrofit mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electronics special economic zones in Bavaria, Stuttgart, and Aichi Prefecture concentrate tier-1 supplier ecosystems and drive regional procurement gravity for vehicle camera modules.
United States
NHTSA FMVSS 111 rear visibility mandates force annual platform redesigns across Detroit Three light vehicle lines. The regulation specifies field-of-view coverage and response latency thresholds that OEMs must certify before model year deployment. Michigan's automotive corridor anchors surround view system integration programs, with suppliers clustering around Ann Arbor and Detroit for proximity to OEM engineering centers.
Germany
Euro NCAP star-rating protocols tie front camera integration to safety scores, compelling premium OEM platform refreshes. KBA type-approval requirements enforce harmonized electromagnetic compatibility standards for camera modules entering European vehicle parc. Baden-Württemberg's Stuttgart region hosts Continental AG and Robert Bosch GmbH engineering campuses that dominate surround view system architecture development.
Japan
MLIT commercial vehicle field-of-view mandates create dedicated procurement channels for heavy-duty truck and bus camera systems. METI automotive technology roadmaps prioritize sensor fusion standardization to reduce platform fragmentation. Aichi Prefecture's Toyota City-Nagoya corridor concentrates Denso Corporation and Panasonic Holdings Corporation manufacturing capacity for OEM-grade camera module supply.
China
MIIT new energy vehicle safety regulations mandate camera-based driver monitoring for Level 2 automation platforms. GB standards for automotive electromagnetic compatibility constrain module design specifications for domestic and export-bound production. Yangtze River Delta electronics clusters in Shanghai-Suzhou supply CMOS image sensor packaging and lens assembly capacity for regional OEMs.
South Korea
MFDS automotive component quality certification requirements align with international functional safety standards for camera module exports. Government-funded autonomous vehicle testbeds in Pangyo and Sejong City validate multi-camera perception stacks for domestic OEM deployment. Seoul Capital Area fabs supply high-temperature CMOS image sensor capacity that feeds tier-1 module assemblers across Asia-Pacific.
Global Vehicle Camera Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with tier-1 automotive suppliers capturing OEM volume through platform-standard designs while aftermarket channels fragment across regional distributors. The structure concentrates around integrated sensor portfolio providers capable of delivering automotive-grade validation at scale. Three archetypes dominate: diversified automotive electronics conglomerates with full-stack perception capabilities, specialized camera module fabricators focused on thermal-tested IP6K9K sealing, and computer vision software licensors bypassing hardware channels. Competitive moves center on supplier consolidation around pre-certified platform providers and direct OEM software licensing agreements that disintermediate traditional tier-1 relationships.
Within the diversified automotive electronics tier, Continental AG and Robert Bosch GmbH occupy positions exemplifying integrated sensor portfolio strategies that span surround view hardware and signal processing domains. Mobileye Global Inc. represents the software-centric archetype, anchoring computer vision silicon and perception stack licensing approaches that compete with traditional hardware suppliers for advanced driver-assistance platform slots. These three entities illustrate the competitive tension between hardware-integrated and software-disaggregated market development paths.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Magna International Inc. |
| Valeo SA |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| Panasonic Holdings Corporation |
| Mobileye Global Inc. |
| Others |
Value Chain & Pricing Dynamics
Embedded systems engineers with ISO 26262 functional safety expertise concentrate in Stuttgart, Aichi Prefecture, and Seoul Capital Area, creating labor-cost differentials that widen spreads between premium automotive-grade modules and economy aftermarket replacements.
Pricing Analysis
Lead-time-driven pricing premiums apply to short-cycle surround view system orders for platform redesigns, while spot inventory of analog rearview modules trades at compressed margins. The dominant structure is contract-based long-term offtake with tiered pricing separating IP6K9K-certified OEM-grade units from dealer-channel aftermarket equivalents. Price differentiation hinges on certification level (ISO 26262 ASIL-B versus non-functional-safety tiers) and volume scale. Cost compression in economy retrofit channels is intensifying because India's compliance-driven truck parc renewal floods spot markets with undifferentiated hardware. Fleet procurement departments exhibit highest price sensitivity; premium OEM platform engineering centers show lowest.
Supply Chain Analysis
Domestic-content mandates in China's MIIT new energy vehicle regulations and India's phased manufacturing programs are reshaping sourcing patterns for CMOS image sensor packaging and lens assembly operations. High-temperature CMOS image sensor fabrication concentrates in Taiwan, South Korea, and Japan. Module assembly draws from automotive-grade PCB substrates, IP6K9K-rated sealing compounds, and HDR-capable image signal processors. Single-source vulnerability in Taiwan-based wafer-level optics capacity threatens tier-1 module assemblers. Distribution runs through keiretsu-aligned OEM supply agreements in Japan, consolidated tier-1 platforms in Germany, and fragmented regional distributors serving India's aftermarket retrofit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA FMVSS 111 rear visibility mandates erect a cost-of-compliance barrier that cedes pricing power to pre-certified platform providers while squeezing undifferentiated aftermarket entrants.
For Market Incumbents: Hedge against software-disaggregation threats by anchoring surround view hardware contracts with integrated signal processing IP. Secure captive supply of high-temperature CMOS capacity through foundry partnerships in Taiwan and South Korea. Deepen backward integration into automotive-grade lens molding to defend margin position against modular component commoditization. For New Entrants and Emerging Players: Enter via India's commercial vehicle retrofit corridor where new central motor vehicle rules create compliance-driven demand without entrenched tier-1 relationships. Target fleet telematics unbundling trends in North American logistics corridors where direct procurement relationships bypass established system integrators. Pursue white-label manufacturing partnerships with domestic assemblers serving price-sensitive aftermarket channels. For Investors and Strategic Acquirers: The window for entry favors computer vision software licensors with automotive-grade functional safety credentials. Long-term viability centers on perception-stack providers capable of bypassing tier-1 hardware channels for direct OEM relationships. Watch for inflection signals in Level 2+ automation platform awards where software-centric architectures displace integrated hardware suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation around pre-certified surround view architectures reduces supplier qualification overhead across model lines. |
| Software-Defined Vehicle Investment | Edge-based neural inference migration redistributes value capture from domain controllers to intelligent camera modules. |
| Geographic Manufacturing Footprint | Proximity to Aichi Prefecture and Stuttgart engineering corridors accelerates platform development cycle times. |
| Sensor Fusion Partnership | Camera-LiDAR integration opens architecture slots for unified perception modules in Level 2+ automation platforms. |
| Direct OEM Software Licensing | Perception stack providers bypass tier-1 channels to capture recurring revenue from autonomous emergency braking platforms. |
Study Parameters
Vehicle production databases, IHS Markit registration data, and SEC filings from tier-1 automotive electronics suppliers formed the secondary backbone. Primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and fleet telematics operators combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated segment-level unit economics across product type, technology, end user, and installation type dimensions; top-down cross-checks validated aggregate market scale against vehicle production forecasts and content-per-vehicle trajectories. CAGRs were derived from regression analysis of historical placement rates and forward projections of regulatory mandate timelines. Forecast inputs included Euro NCAP star-rating protocol evolution and NHTSA FMVSS 111 compliance penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timeline divergence or automotive-grade sensor supply disruption scenarios. Forecasts reflect assumptions on platform redesign cycles and fleet telematics adoption curves without claiming predictive certainty. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Instrument Cluster Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Drive by Wire Market
Automotive Electronics & Wiring
Electric Vehicle High Voltage Wire Harness Market
Automotive Electronics & Wiring
Automotive Fuse Boxes Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Smart Camera Market
Automotive Electronics & Wiring
China Automotive Camera Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive Wireless Charger Market
Automotive Electronics & Wiring
Vehicle Control Unit (VCU) Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market