
 Automotive Expanded Polypropylene (EPP) Foam Market | 2026-2036
Automotive Expanded Polypropylene (EPP) Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Expanded Polypropylene (EPP) Foam Market Analytics
Electric vehicle OEMs is redrawing procurement priorities away from conventional internal-combustion platforms. JSP Corporation leverages its bead foam expertise to anchor Japanese EV supply chains. BASF SE competes through backward integration into propylene feedstocks and specialized catalyst systems. Kaneka Corporation differentiates via high-performance grades targeting battery thermal management applications.
Automotive Expanded Polypropylene (EPP) Foam comprises closed-cell, bead-molded polypropylene structures with densities typically ranging from 20 to 200 grams per liter, produced through steam-chest molding of expanded beads to achieve energy absorption and weight reduction in vehicle systems. Its primary industrial purpose centers on impact protection, acoustic dampening, and thermal insulation across passenger and commercial vehicle architectures. Molded Parts commands the dominant share of value as complex geometries replace multi-piece assemblies in bumper cores and seat structures. Crash Management represents the fastest-expanding application segment as safety cell designs integrate thicker EPP layers around battery enclosures. Tier-1 Suppliers occupy critical margin pools by controlling tool design and just-in-sequence delivery to vehicle assemblers.
NHTSA crashworthiness standards and EPA fuel economy mandates collectively elevate lightweight material penetration across US vehicle programs. ECHA REACH restrictions on flame retardant chemistries are forcing reformulation of additive packages in European-sourced grades. OEMs and compounders must monitor evolving battery safety protocols from China's MIIT and SAMR as those specifications diffuse into export requirements.
Market Dynamics
Battery enclosure protection requirements are compressing design cycles across EV platforms, forcing Tier-1 foam molders to co-develop crash structures with cell manufacturers rather than traditional sequential sourcing.
Growth Catalysts
- EU Green Deal vehicle weight mandates:OEMs must shed mass to meet fleet CO2 targets, expanding EPP substitution for metal and denser polymer components in seat pans and bumper systems.
- Steam-chest molding automation:Robotic bead handling and predictive cavity control are shortening mold-change intervals, enabling just-in-sequence supply to Stuttgart-area assembly plants.
- China:MIIT battery safety protocols are mandating thicker thermal insulation layers around prismatic cells, directly expanding molded foam volumes for NEV export programs.
Market Restraints
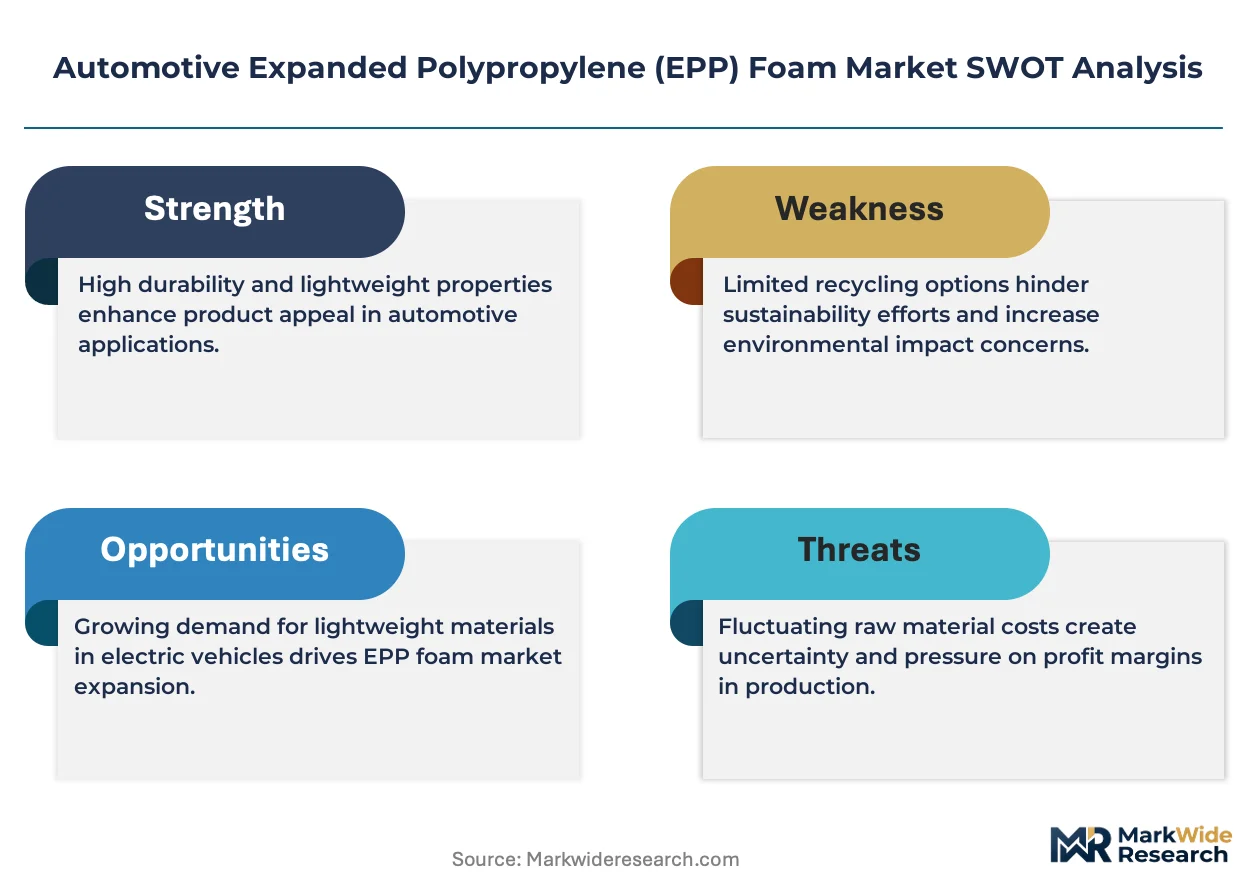
- Propylene feedstock volatility:Naphtha-cracking economics tie EPP resin costs to petrochemical spreads, compressing compounder margins during upstream price spikes.
- Tooling concentration in Germany:Complex aluminum mold fabrication for large battery tray geometries relies on a narrow supplier base around Wolfsburg, creating single-source vulnerability.
- ECHA REACH additive restrictions:Reformulation of legacy flame-retardant packages is extending qualification timelines by 8-14 months for European-sourced grades.
Strategic Opportunities
- India:PLI scheme subsidies for domestic EV manufacturing are attracting foam compounders to establish localized bead-molding capacity near Chennai and Pune assembly corridors.
- Autonomous vehicle sensor integration:EPP bumper cores with embedded routing channels for lidar and radar cabling represent an unserved design space between acoustic and structural functions.
- Closed-loop bead recycling:Pyrolysis-to-monomer recovery systems are converging with virgin propylene streams, enabling circular material claims for sustainability-scored OEM tenders.
Industry Challenges
- Multi-physics simulation talent:Crash-validated finite element modeling for anisotropic bead foam requires rare expertise combining polymer rheology and explicit dynamics, constraining Tier-2 tool development.
- Dual-chemistry certification:Battery pack suppliers must simultaneously qualify EPP grades under UN 38.3 thermal runaway protocols and OEM-specific odor-emission standards, fragmenting testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Expanded Polypropylene (EPP) Foam Market |
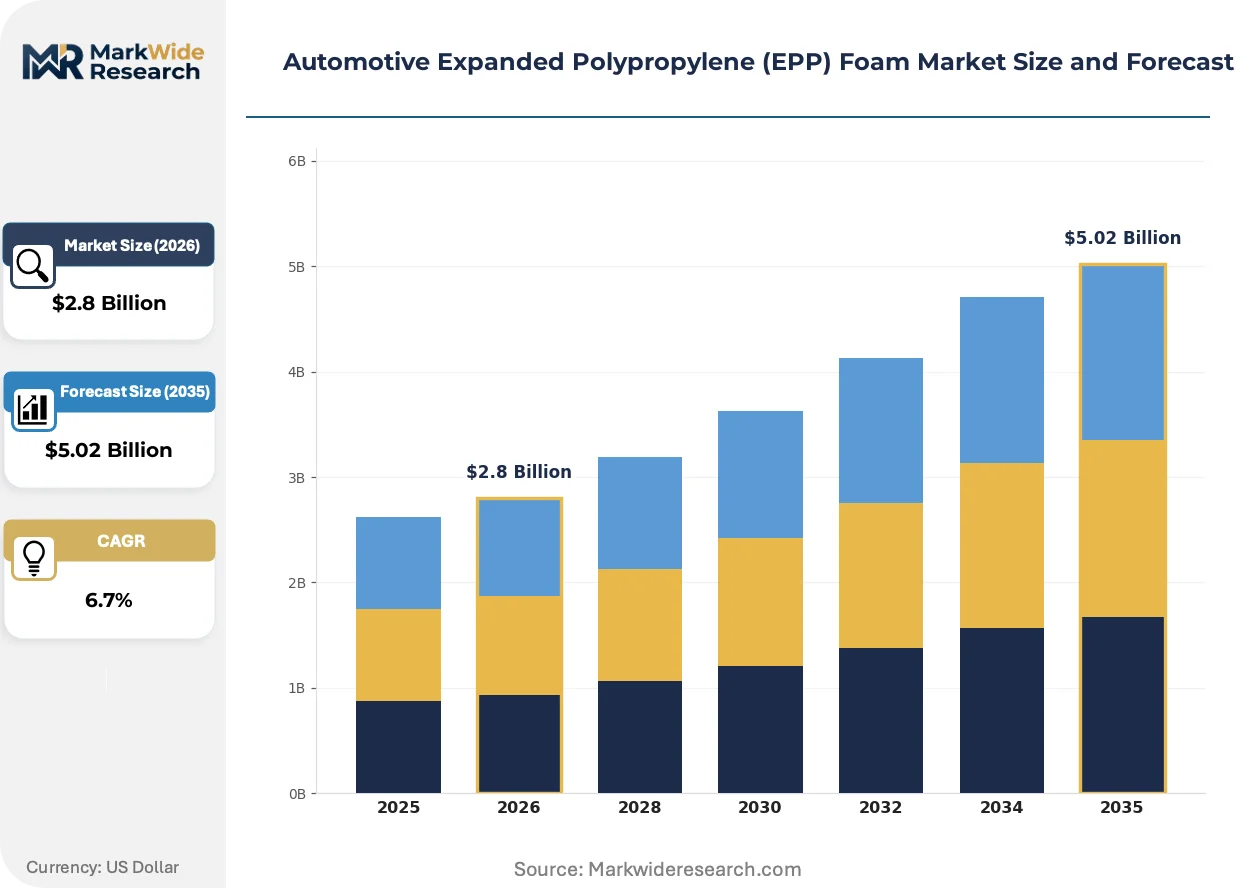
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
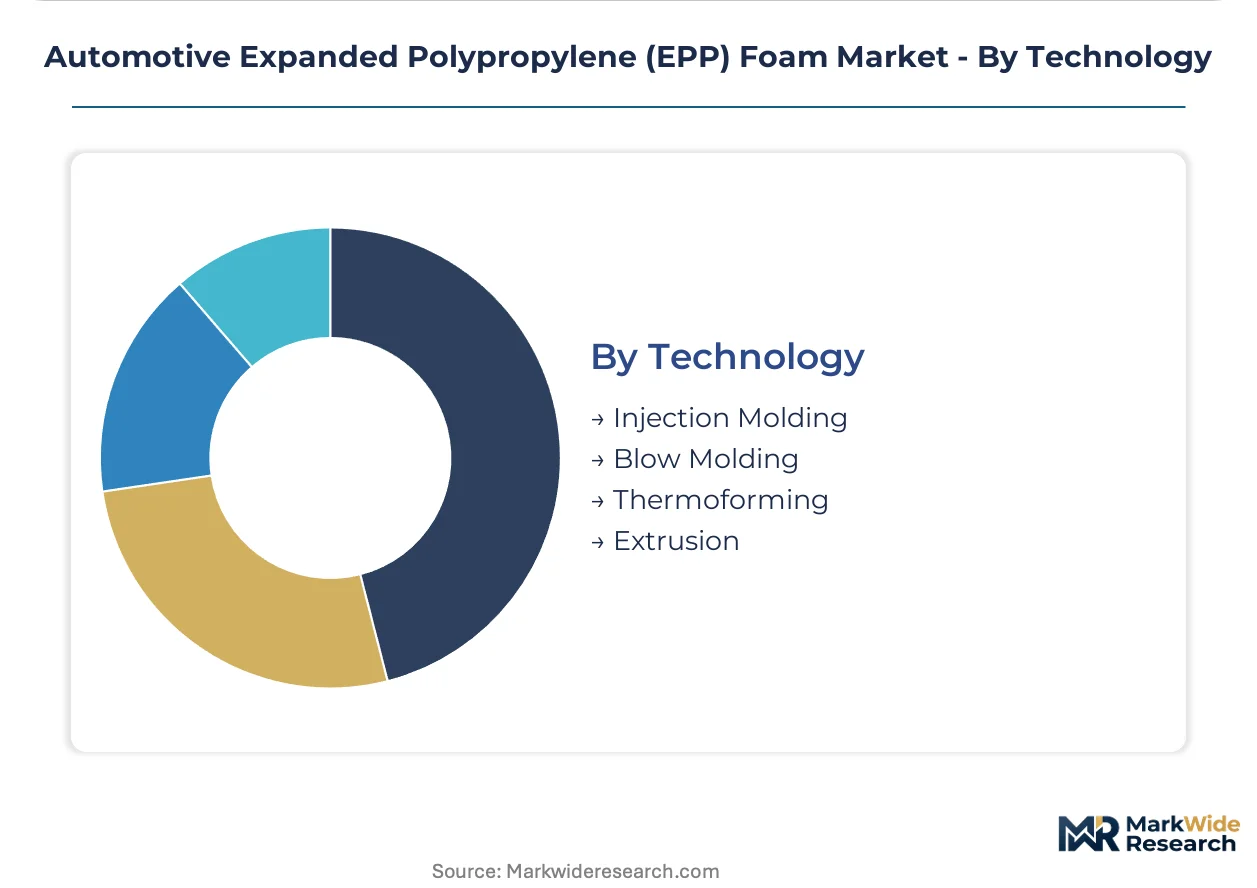
| Segmentation | Product Type: Sheets, Blocks, Molded Parts, Custom Shapes Application: Interior, Exterior, Packaging, Crash Management End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | Hanwha Corporation, DS Smith plc, JSP Corporation, Knauf Industries, Sonoco Products Company, BASF SE, Furukawa Electric Co., Ltd., The Woodbridge Group, Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Expanded Polypropylene (EPP) Foam Market Evolving Landscape
Material-grade stratification and processing automation are bifurcating the supply base between commodity bead molders and specialists serving thermal-management specifications.
High-performance expanded polypropylene grades with engineered cell structures for anisotropic thermal conductivity are supplanting conventional cross-linked polyethylene in battery module interstitial layers. Korean cell manufacturers are specifying these grades for 800V architectures. The shift is compressing qualification timelines for legacy foam suppliers without catalyst-controlled bead expansion capabilities.
EPA fuel economy standards and NHTSA crashworthiness mandates are tightening in parallel, creating compound compliance pressure for US vehicle programs. OEMs must simultaneously reduce mass and maintain intrusion resistance in frontal offset tests. EPP bumper cores and seat structures are absorbing expanded engineering attention as multi-functional solutions.
Direct-to-OEM contracting is displacing traditional Tier-1 foam supply arrangements for battery enclosure programs. Cell manufacturers are specifying material grades and mold designs, bypassing conventional automotive interior suppliers. This pattern is most visible in Germany, where CATL and BYD co-located plants are sourcing crash-absorbing foam layers through dedicated supply agreements rather than established seating or bumper module integrators.
Automotive Expanded Polypropylene (EPP) Foam Market Segmentation
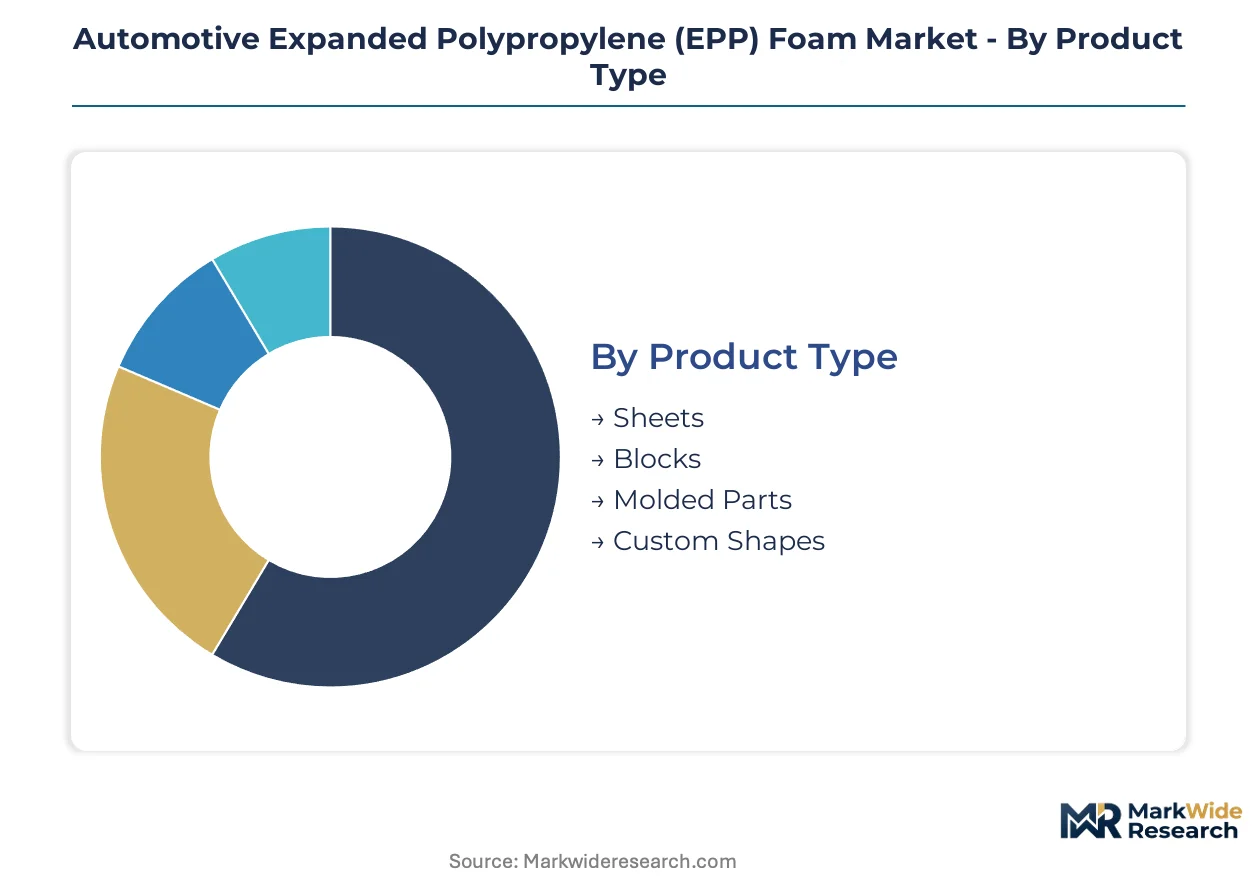
Automotive EPP foam procurement patterns diverge sharply between mass-market vehicle platforms and specialized EV architectures. Segment boundaries are blurring as battery enclosure specifications force material grades to serve multiple functional roles simultaneously.
Product Type:
Domestic consumption dominates molded parts and blocks serving Germany's Stuttgart corridor assembly plants, while sheets and custom shapes feed export-oriented tool-and-die operations across multiple jurisdictions.
- Molded Parts:Complex bead-molded geometries achieve energy absorption in bumper cores and seat structures through steam-chest processing. German OEMs around Wolfsburg concentrate procurement for EV platform crash management systems where EPP replaces multi-piece metal assemblies.
- Blocks:Solid expanded polypropylene masses undergo CNC machining or hot-wire cutting for prototype validation and low-volume tooling. Indian PLI scheme beneficiaries near Chennai source blocks for domestic NEV battery tray development programs.
- Sheets:Continuous extruded panels serve acoustic insulation layers in passenger compartment floors.
- Custom Shapes:Application-specific geometries address autonomous vehicle sensor housing requirements with embedded cable routing channels.
Molded Parts holds the largest share; momentum sits with Custom Shapes as lidar integration specifications proliferate.
Application:
Cost tier stratification separates commodity interior applications from premium crash management specifications commanding specialized thermal-runaway certification.
- Crash Management:Thick EPP layers surround battery enclosures to manage thermal runaway propagation and frontal offset intrusion. Korean cell manufacturers specify these grades for 800V architectures, compressing qualification timelines for suppliers lacking catalyst-controlled bead expansion.
- Interior:Acoustic dampening and tactile surfaces in seat pans, door panels, and headliners reduce NVH while trimming mass from vehicle structures. EU Green Deal CO2 mandates accelerate EPP substitution for denser polymer and metal components.
- Exterior:Bumper cores and fender liners combine impact recovery with paint-line thermal stability.
- Packaging:Returnable dunnage and component shipping containers serve tiered supply chain logistics.
Crash Management is climbing the fastest as battery safety protocols mandate thicker protective layers; Interior maintains volume leadership across legacy ICE and hybrid platforms.
End User:
Customer-type concentration is reshaping traditional tier structures as cell manufacturers bypass established automotive suppliers for direct material specification.
- Tier-1 Suppliers:Module integrators control aluminum tool design and just-in-sequence delivery to vehicle assemblers, capturing critical margin pools through mold fabrication expertise concentrated around Wolfsburg.
- OEMs:Direct contracting for battery enclosure foam is displacing conventional sourcing arrangements, with CATL and BYD co-located German plants negotiating dedicated supply agreements.
- Vehicle Assemblers:Final production facilities specify material grades for seat and interior modules.
- Aftermarket Suppliers:Replacement components and repair segments serve collision repair networks.
Tier-1 Suppliers retain the largest share; momentum sits with OEMs as direct material specification accelerates across EV platforms.
Technology:
Supply concentration in German toolmaking favors steam-chest molding derivatives, while alternative processes address specialized geometries and prototyping velocity.
- Injection Molding:Bead fusion in precision aluminum tools produces complex hollow sections with variable wall thickness for structural crash elements. Robotic bead handling and predictive cavity control enable just-in-sequence supply.
- Thermoforming:Heated sheet processing creates shallow-draw acoustic panels and packaging trays for component logistics.
- Blow Molding:Limited application for hollow profile sections in fluid reservoir protection.
- Extrusion:Continuous profile production feeds sheet stock and simple geometric sections for secondary fabrication.
Injection Molding holds the largest share; momentum sits with Thermoforming as interior acoustic specifications proliferate across mass-market EV architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German EPP compounders dominate European supply flows into Stuttgart and Wolfsburg assembly corridors, while Japanese bead-foam specialists anchor Pacific Rim exports to Korean battery manufacturers.
United States
NHTSA crashworthiness standards and EPA fuel economy mandates elevate lightweight material penetration across Detroit and Southern automotive clusters. Michigan and Tennessee assembly plants source EPP bumper cores and seat structures to satisfy dual compliance pressure. The Southeast corridor around Georgia and South Carolina attracts molded foam capacity to serve BMW and Mercedes-Benz US operations.
Germany
EU Green Deal CO2 fleet targets force mass reduction through EPP substitution for metal components in Wolfsburg and Stuttgart manufacturing zones. ECHA REACH additive restrictions extend qualification timelines for flame-retardant reformulations. Tooling concentration around Lower Saxony creates single-source vulnerability for complex aluminum mold fabrication serving battery tray geometries.
China
MIIT battery safety protocols mandate thicker thermal insulation layers around prismatic cells for NEV export programs. Yangtze River Delta and Pearl River Delta clusters concentrate bead-molding capacity near CATL and BYD co-located plants. SAMR evolving specifications diffuse into tender requirements for European-bound vehicle platforms.
Japan
METI industrial standards and domestic OEM lightweighting roadmaps sustain specialized EPP demand for hybrid and fuel-cell vehicle programs. Nagoya and Tokyo corridor manufacturers supply high-performance grades to Korean 800V battery architectures. JIS certification requirements maintain quality differentiation against commodity Asian imports.
India
PLI scheme subsidies for domestic EV manufacturing attract foam compounders to establish localized bead-molding capacity. Tamil Nadu and Maharashtra assembly corridors near Chennai and Pune concentrate procurement for indigenous NEV battery tray development. BIS standards alignment with UN 38.3 protocols enables export qualification for Southeast Asian markets.
Automotive Expanded Polypropylene (EPP) Foam Market Competitive Landscape
Player mix skews toward integrated petrochemical conglomerates with captive propylene supply and specialized bead-foam molders with tool design expertise. Structure concentrates margin pools in aluminum mold fabrication and just-in-sequence logistics rather than raw bead production. Two archetypes dominate: backward-integrated resin producers controlling feedstock economics, and Tier-1 system integrators commanding vehicle assembler relationships. Competitive moves center on co-development partnerships with cell manufacturers and geographic expansion into PLI-subsidized Indian manufacturing zones.
Among Japanese specialists, JSP Corporation and Kaneka Corporation exemplify the catalyst-controlled bead expansion tier serving thermal management specifications. BASF SE anchors the European integrated producer archetype with upstream propylene positioning. Hanwha Corporation represents Korean conglomerate diversification into battery enclosure materials. DS Smith plc and Sonoco Products Company occupy packaging-to-automotive crossover positions. Knauf Industries and The Woodbridge Group sit within the mold-fabrication and system-integration tier concentrated around German automotive clusters. Furukawa Electric Co., Ltd. diversifies from cable and electronics materials into vehicle lightweighting applications.
| Leading Market Players |
|---|
| Hanwha Corporation |
| DS Smith plc |
| JSP Corporation |
| Knauf Industries |
| Sonoco Products Company |
| BASF SE |
| Furukawa Electric Co., Ltd. |
| The Woodbridge Group |
| Kaneka Corporation |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German OEMs and Wolfsburg-area compounders lock in propylene feedstock access while freezing price visibility for standard-grade EPP across the analysis window. These contracts insulate Tier-1 molders from naphtha-cracking volatility but expose buyers to rigidity when battery enclosure specifications demand rapid grade switches.
Pricing Analysis
High-performance thermal-management grades command substantial premiums over conventional bead foam used in interior acoustic applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification complexity: UN 38.3 thermal-runaway qualified grades sit at the top, followed by OEM-specific odor-emission compliant mid-tier, with undifferentiated commodity bead foam at the base. Cost compression in standard interior grades is intensifying because Indian PLI scheme beneficiaries are adding bead-molding capacity near Chennai. Tier-1 seat module integrators exhibit highest price sensitivity due to fixed OEM price-down schedules, while cell manufacturers sourcing crash-management foam directly show lowest sensitivity given battery safety liability exposure.
Supply Chain Analysis
Inventory buffers for complex aluminum molds stretch lead times to 14-18 weeks, constraining just-in-sequence responsiveness for Stuttgart-area EV platforms. Supply concentrates in Germany, China, and Japan, with Wolfsburg tooling shops fabricating precision molds, Yangtze River Delta compounders serving CATL co-located plants, and Nagoya specialists exporting to Korean 800V architectures. Raw material flows draw from naphtha-cracking complexes, specialized catalyst systems, and flame-retardant additive packages. Single-source vulnerability runs through Lower Saxony mold fabrication for large battery tray geometries. Distribution runs through dedicated logistics corridors linking compounders to final assembly plants rather than traditional tiered warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT battery safety protocol diffusion is accelerating grade stratification faster than legacy qualification timelines permit, compressing competitive windows for unprepared suppliers.
For Market Incumbents: Consolidate mold-fabrication expertise around Wolfsburg through selective acquisition of specialized aluminum tool shops facing succession gaps. Deepen captive propylene positioning via backward integration into naphtha-cracking economics to defend margin pressure from Korean conglomerate entrants. Prioritize co-development partnerships with CATL and BYD before direct OEM contracting displaces traditional Tier-1 relationships entirely. For New Entrants and Emerging Players: UN 38.3 fast-track certification programs offer entry path into battery enclosure specifications where incumbent qualification backlogs create temporary supply gaps. Target India's PLI-subsidized manufacturing zones near Pune and Chennai for greenfield bead-molding capacity serving indigenous NEV export programs. Lead with pyrolysis-to-monomer recycling credentials to differentiate in sustainability-scored OEM tenders where circular material claims command premium positioning. For Investors and Strategic Acquirers: Capital is best deployed toward catalyst-controlled bead expansion specialists with existing thermal-management grade portfolios rather than commodity molders facing margin compression. The 5-10 year viability window favors suppliers with demonstrated 800V architecture qualification and established relationships with Korean cell manufacturers. Monitor ECHA REACH additive restriction enforcement intensity as signal for qualification timeline disruption and subsequent M&A opportunity creation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstocks | BASF SE's captive supply anchors cost position against naphtha volatility. |
| Co-Development Partnership with Cell Manufacturers | CATL direct contracting bypasses traditional Tier-1 foam supply arrangements. |
| Pyrolysis-to-Monomer Recycling Infrastructure | Circular material claims unlock sustainability-scored OEM tender participation. |
| Aluminum Mold Fabrication Capacity Expansion | Wolfsburg tooling concentration creates acquisition targets for supply security. |
| 800V Architecture Grade Qualification | Korean cell manufacturer specifications compress legacy supplier competitive windows. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, cell manufacturer material specification leads, and aluminum mold fabrication shop owners provided ongoing calibration across primary fieldwork phases. Secondary validation drew from MIIT battery safety protocol filings, ECHA REACH restriction updates, customs data tracking propylene derivative trade flows, and vehicle production databases. Bottom-up bead-molding capacity estimates triangulated against top-down OEM lightweighting program announcements to anchor volume assumptions.
Consistency checks against external benchmarks validated model outputs across the projection horizon. The analytical framework segmented by vehicle propulsion architecture, content per vehicle, performance grade tier, and regional production cluster. CAGRs derived from explicit modeling of EV platform rollout schedules and EPP substitution rates in legacy ICE programs. Forecast inputs incorporated steam-chest molding automation adoption curves and ECHA reformulation timeline assumptions.
Underlying assumptions cover MIIT protocol diffusion rates, propylene spread stability, and REACH enforcement intensity, with deviation risk concentrated in battery safety standard harmonization between Chinese and European regulators. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market