
 Automotive Telescopic Mirror Market | 2026-2036
Automotive Telescopic Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Telescopic Mirror Market Analytics
Electromechanical engineering talent is bifurcating the competitive landscape, separating suppliers with in-house servo-motor expertise from assembly-dependent rivals. Magna International leverages captive manufacturing scale across North American and European plants. Gentex Corporation differentiates through proprietary electrochromic technology leadership in dimming applications. Samvardhana Motherson Reflectec anchors cost-competitive volume production for mass-market OEM programs.
An automotive telescopic mirror extends and retracts from a vehicle body through manual, electric, or hydraulic actuation mechanisms, typically incorporating glass substrates with anti-glare coatings and heating elements to maintain visibility across temperature ranges; its primary purpose eliminates forward blind spots in commercial trucks, buses, and specialized utility vehicles where fixed mirror geometry fails clearance or aerodynamic requirements. Electric product types now command the dominant margin pool as OEMs spec power-adjustable units with memory positioning. Smart mirror technology within the Advanced Driver Assistance Systems category represents the fastest-growing segment, integrating camera feeds and blind-spot monitoring displays directly into mirror housings. Aftermarket providers occupy a mature, price-sensitive channel concentrated in collision repair and fleet retrofit demand.
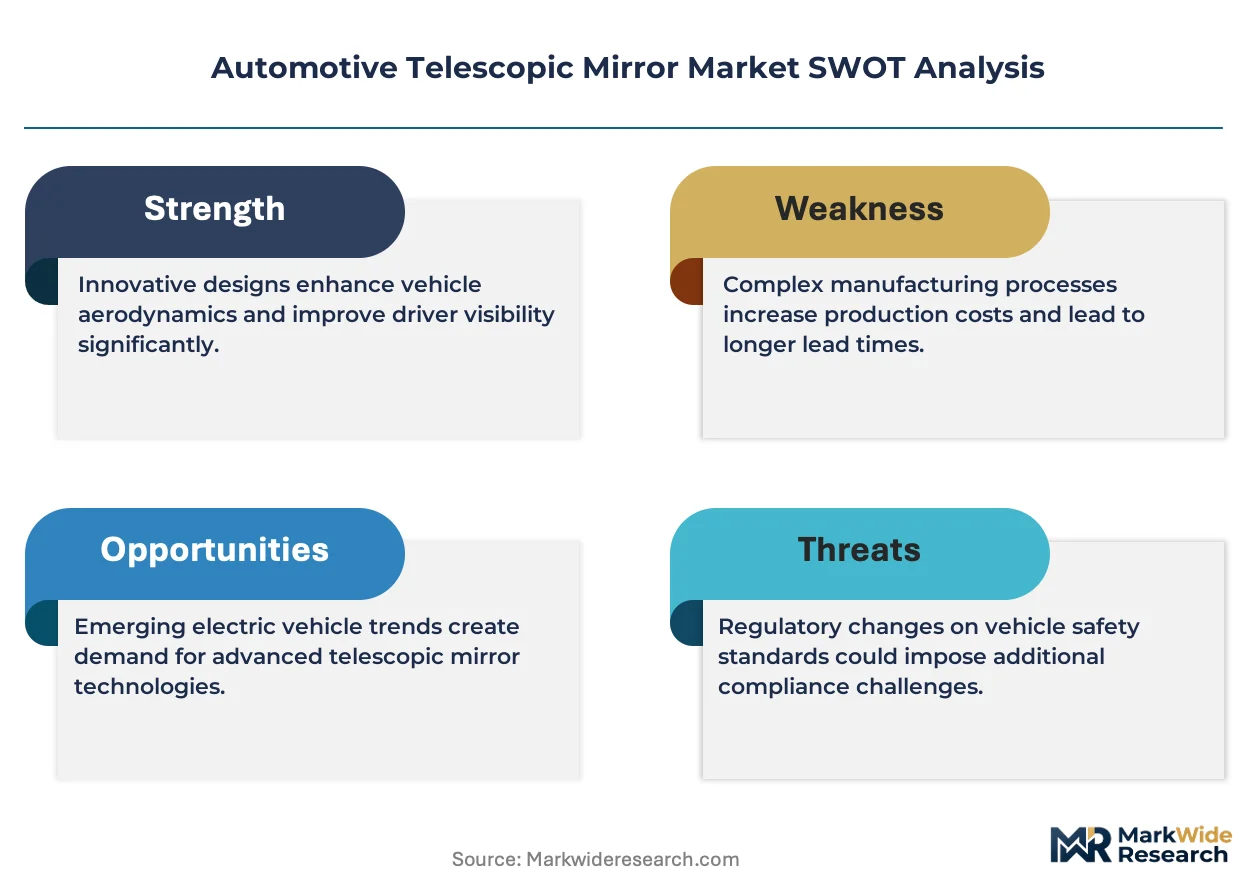
NHTSA's Federal Motor Vehicle Safety Standard 111 governs rear-visibility field of view and mirror durability testing in the United States, while China's MIIT enforces GB standards for exterior mirror performance under varying load and vibration conditions. ECE Regulation 46 in Europe mandates specific mounting strength and deflection criteria that directly shape housing material selection and actuator torque specifications. Stakeholders must monitor regulatory divergence between camera-replacement permissibility and traditional mirror retention requirements as jurisdictions evaluate alternative visibility systems.
Market Dynamics
Mirror actuator servo-motor supply is concentrating among electromechanical specialists with captive winding and magnet fabrication capabilities, creating procurement bottlenecks for assembly-dependent tier suppliers serving German and Chinese OEM programs.
Growth Catalysts
- NHTSA rear-visibility mandates:Federal Motor Vehicle Safety Standard 111 field-of-view requirements are forcing commercial truck and bus fleet upgrades across the United States, expanding replacement demand for power-adjustable telescopic units.
- Camera-to-mirror integration:Blind-spot monitoring display fusion into mirror housings is accelerating specification upgrades in premium SUV and electric vehicle platforms.
- China MIIT safety equipment rules:GB standards enforcement on exterior mirror performance under vibration and thermal load is disqualifying low-cost fixed-mirror suppliers from state-owned OEM procurement lists.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings in Chinese spot markets are compressing servo-motor gross margins for European actuator manufacturers.
- Camera-replacement substitution:NHTSA and ECE regulatory divergence on digital mirror permissibility is creating platform engineering uncertainty for mirror-dependent vehicle architectures.
- Housing polymer supply concentration:Polyamide 66 and PBT compounding capacity is geographically concentrated in German and Korean chemical clusters, exposing mirror housing molders to force majeure risk.
Strategic Opportunities
- India commercial vehicle retrofit:Underpenetrated power-mirror adoption in domestic truck and bus fleets creates aftermarket volume potential as BIS safety norms tighten.
- Smart mirror ADAS convergence:Integration of lane-departure warning displays and 360-degree camera feeds into mirror assemblies opens premium pricing tiers for electro-optics suppliers.
- Brazil ANVISA fleet safety incentives:Federal tax credits for commercial vehicle visibility equipment are stimulating telescopic mirror demand in agricultural and mining truck segments.
Industry Challenges
- Electromechanical engineering talent scarcity:Servo-motor design and precision geartrain expertise is concentrating at mid-cap specialists, forcing tier suppliers into costly recruitment or licensing arrangements.
- ECE 46 homologation timeline compression:European mounting strength and deflection testing cycles are extending by four to six months as notified bodies face certification backlog.
- Legacy vehicle electrical architecture integration:Smart mirror power and data requirements are straining 12V harness capacity in commercial truck platforms designed for passive mirror loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Telescopic Mirror Market |
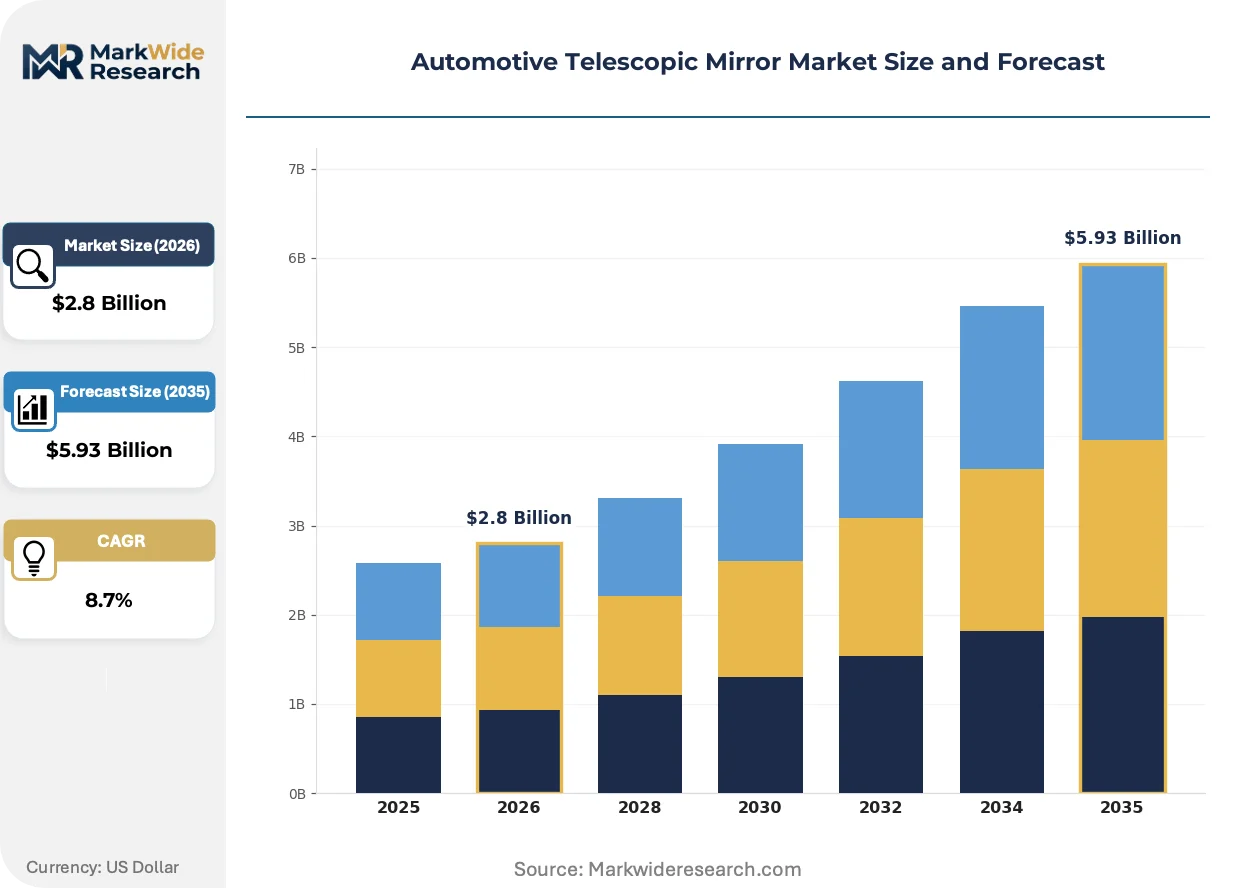
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Hydraulic, Automatic End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Distributors Material: Plastic, Aluminum, Glass, Composite Technology: Conventional, Advanced Driver Assistance Systems, Smart Mirrors, Others |
| Companies Covered | Magna International Inc., Gentex Corporation, SL Corporation, Ficosa Internacional SA, Burco Inc., Samvardhana Motherson Reflectec, Murakami Corporation, Ichikoh Industries Ltd., Milenco Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Telescopic Mirror Market Evolving Landscape
Actuator mechanisms and optical subsystems are undergoing simultaneous compression and functional expansion, with miniaturization pressures reshaping supplier capability requirements across electromechanical and electrochromic domains.
Brushless DC servo motors with integrated position feedback encoders are miniaturizing mirror actuator packages while maintaining torque output for heavy-duty commercial vehicle vibration environments. European and Chinese OEMs are specifying these compact units for door-mount mirror applications where packaging space is constrained. The technology is miniaturizing housing form factors and enabling aerodynamic drag reductions previously unattainable with brushed-motor architectures.
ECE Regulation 46 revision discussions in Brussels are evaluating camera-based visibility system permissibility alongside traditional mirror retention requirements. This regulatory uncertainty is forcing European OEM engineering teams to develop dual-architecture platform strategies. Premium electric vehicle programs in Germany and Sweden are most affected, accelerating investment in reversible mirror-to-camera mounting systems.
Fleet procurement managers are consolidating supplier relationships around vertically integrated electromechanical specialists capable of delivering complete mirror assemblies rather than discrete actuator modules. This behavior shift is compressing tier-two component supplier margins and channel volume. The pattern is most visible in North American heavy-duty truck manufacturing, where OEMs are reducing approved vendor lists from twelve to four mirror system suppliers.
Automotive Telescopic Mirror Market Segmentation
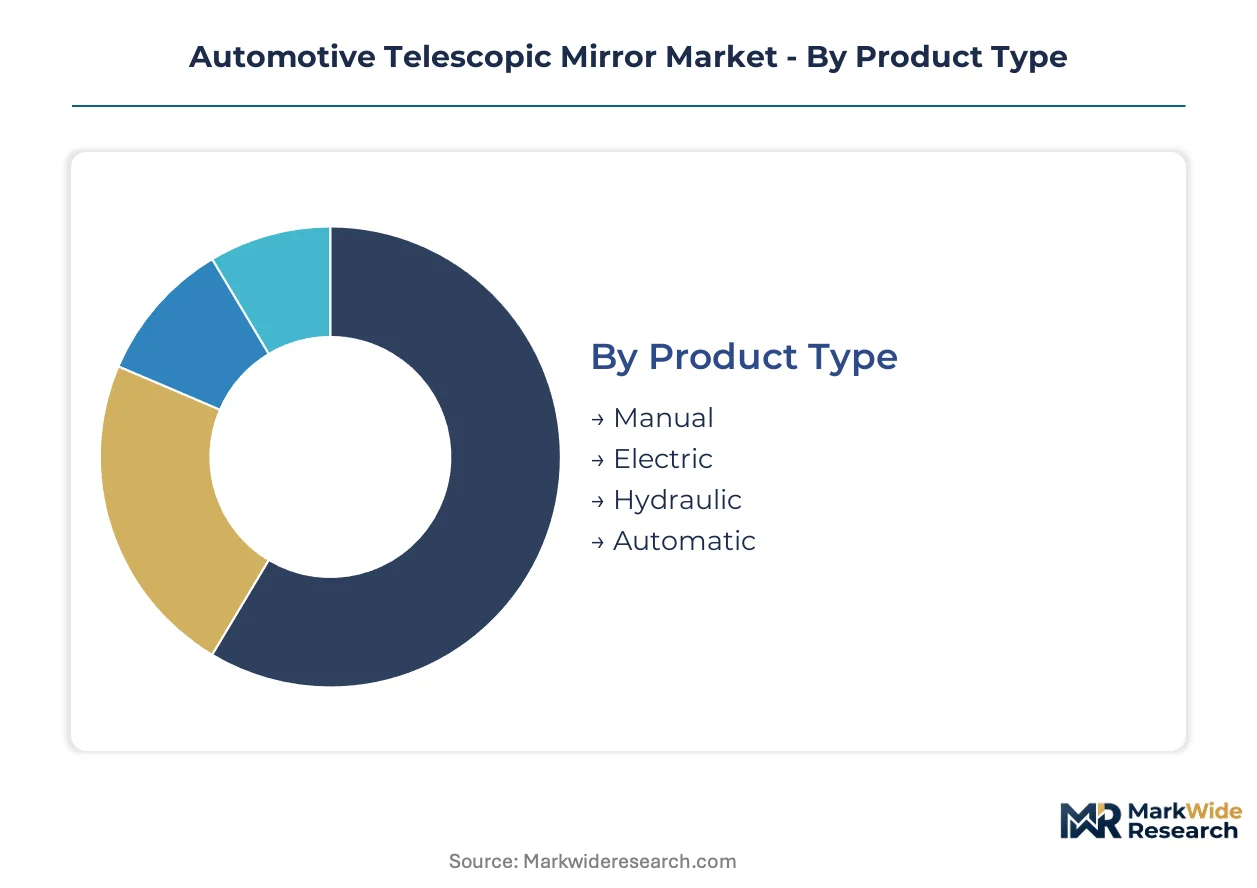
Telescopic mirror segmentation reveals divergent vulnerability to camera-based substitution across actuation methods and optical technologies. Product and technology categories face the most acute displacement pressure as regulators evaluate digital visibility alternatives.
Product Type:
Electric and automatic variants confront the strongest substitution threat from camera-replacement systems, while manual and hydraulic units serve residual fleet segments where electrification costs prove prohibitive.
- Electric:Brushless DC servo motors with integrated position feedback encoders power these units, enabling memory positioning and heated glass integration. OEM specification concentrates in German premium SUV and Swedish electric vehicle platforms where ADAS convergence commands specification upgrades.
- Manual:Cable-actuated mechanical linkages without electrical harness dependency persist in emerging-market commercial truck retrofits and cost-constrained fleet procurement. India's BIS safety norm tightening is stimulating aftermarket volume even as OEM adoption contracts.
- Hydraulic:Fluid-pressure actuation serves heavy-duty mining and agricultural equipment where environmental sealing against dust ingress takes priority over precision positioning.
- Automatic:Sensor-triggered extension and retraction mechanisms integrate with vehicle speed and steering angle data, finding application in luxury coach and specialized utility vehicle platforms.
Electric retains volume leadership; automatic holds the steepest expansion curve.
End User:
Procurement authority is consolidating around vertically integrated system suppliers, compressing tier-two component margins across all customer channels.
- OEMs:Direct vehicle manufacturer specification drives power-adjustable and smart mirror adoption, with German and Chinese state-owned OEMs leading technology integration mandates.
- Aftermarket Providers:Collision repair and fleet retrofit demand concentrates in price-sensitive channels, with North American heavy-duty truck approved vendor lists contracting from twelve to four mirror system suppliers.
- Vehicle Assemblers:Contract manufacturing arrangements for commercial bus and specialty vehicle production in Brazil and India create specification intermediation complexity.
- Distributors:Regional logistics networks serving independent repair shops face margin compression as fleet procurement managers consolidate supplier relationships.
OEMs command specification authority; aftermarket providers deliver residual volume stability.
Material:
Housing polymer supply concentration in German and Korean chemical clusters shapes material selection risk profiles across all mirror categories.
- Plastic:Polyamide 66 and PBT compounds dominate volume production, with compounding capacity geographic concentration exposing molders to force majeure disruption.
- Aluminum:Die-cast housings serve premium applications requiring ECE 46 mounting strength compliance without polymer deflection under thermal load.
- Glass:Anti-glare coated substrates with integrated heating elements maintain visibility across temperature ranges, with electrochromic dimming technology differentiating premium tier offerings.
- Composite:Carbon-fiber-reinforced polymers enable aerodynamic drag reduction in electric vehicle platforms where range optimization overrides cost considerations.
Plastic sustains cost-position dominance; composite gains share fastest in electrified platforms.
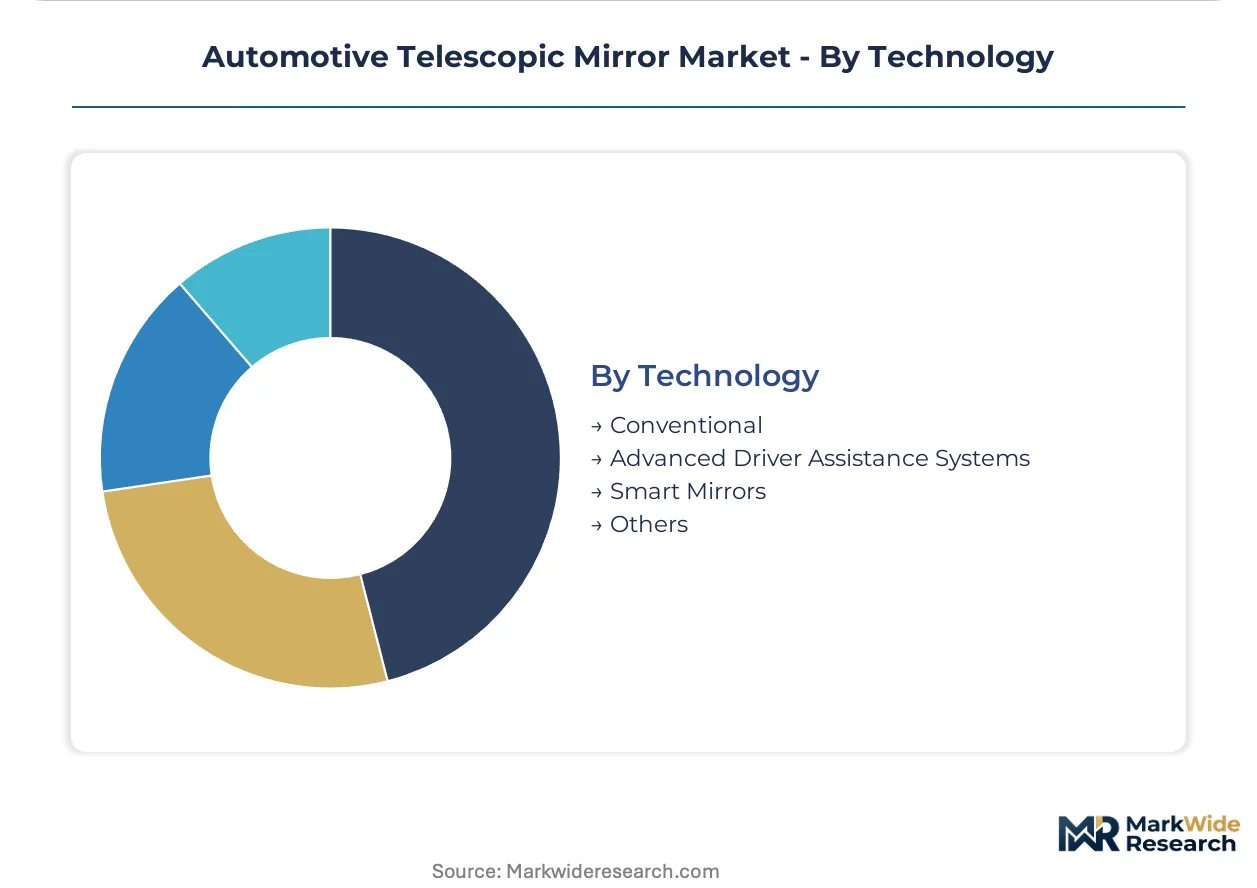
Technology:
Regulatory divergence between camera-replacement permissibility and traditional mirror retention requirements creates platform engineering uncertainty across all technology tiers.
- Advanced Driver Assistance Systems:Blind-spot monitoring display fusion into mirror housings accelerates specification upgrades, with lane-departure warning integration and 360-degree camera feed aggregation opening premium pricing tiers for electro-optics suppliers.
- Smart Mirrors:Camera-fed displays replacing optical glass face regulatory headwinds as NHTSA and ECE evaluate permissibility, forcing European OEM engineering teams toward dual-architecture platform strategies.
- Conventional:Passive optical mirrors without electronic integration serve legacy vehicle electrical architectures where 12V harness capacity cannot support smart mirror power and data requirements.
- Others:Emerging electro-optic technologies including self-dimming liquid crystal arrays occupy pre-commercial development status.
Conventional retains installed-base dominance; ADAS integration climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA rear-visibility mandates anchor the United States as the regulatory driver for commercial fleet mirror upgrades, while China's MIIT enforcement reshapes supplier qualification across Asia-Pacific manufacturing corridors.
United States
Federal Motor Vehicle Safety Standard 111 field-of-view requirements are compelling heavy-duty truck and bus fleet retrofits with power-adjustable telescopic units. NHTSA durability testing protocols disqualify fixed-mirror configurations from interstate commerce certification. Manufacturing concentrates in Michigan and Ohio automotive supplier belts where tier-one mirror system integrators serve Detroit-based OEM programs.
Germany
Premium SUV and electric vehicle production in Bavaria and Baden-Württemberg drives specification upgrades toward smart mirror ADAS integration. ECE Regulation 46 mounting strength criteria directly shape housing material selection for Stuttgart and Munich engineering centers. The KBA homologation backlog is extending certification timelines for new actuator designs by four to six months.
China
State-owned OEM procurement lists are excluding low-cost fixed-mirror suppliers under MIIT GB standards enforcement on vibration and thermal load performance. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province concentrate electromechanical actuator production for domestic and export programs. MIIT mandates on vehicle safety equipment are accelerating power-mirror adoption in commercial bus platforms.
India
BIS safety norm tightening in commercial vehicle segments is stimulating aftermarket volume for power-mirror retrofits in underpenetrated truck and bus fleets. Domestic manufacturing corridors in Maharashtra and Tamil Nadu are attracting component suppliers for cost-competitive actuator sourcing. Fleet procurement managers in Gujarat logistics hubs are consolidating supplier relationships around complete mirror assembly providers.
Brazil
ANVISA federal tax credits for commercial vehicle visibility equipment are stimulating telescopic mirror demand in agricultural and mining truck segments. São Paulo state manufacturing complexes serve as the assembly anchor for South American export programs. Mining corridor fleet operators in Minas Gerais are specifying heavy-duty hydraulic actuation variants for dust-sealed environmental requirements.
Automotive Telescopic Mirror Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive electromechanical capability separating full-system suppliers from assembly-dependent competitors. The vendor base compresses around vertically integrated mirror system providers capable of delivering complete actuator-glass-housing assemblies rather than discrete component modules. Three archetypes dominate: North American multi-product automotive suppliers with captive manufacturing scale, Asian specialists in cost-competitive volume production, and precision electro-optics developers with proprietary dimming technology. Competitive moves concentrate on approved vendor list consolidation by OEMs and backward integration into servo-motor winding capabilities.
Within the integrated tier, Magna International and Gentex Corporation exemplify divergent specialization strategies, while Samvardhana Motherson Reflectec occupies a position in cost-optimized volume manufacturing. Magna International represents the captive-scale archetype with manufacturing presence across multiple continents. Gentex Corporation exemplifies technology-led positioning through electrochromic capability development. Samvardhana Motherson Reflectec anchors the emerging-market volume tier with mass-market OEM program execution.
| Leading Market Players |
|---|
| Magna International Inc. |
| Gentex Corporation |
| SL Corporation |
| Ficosa Internacional SA |
| Burco Inc. |
| Samvardhana Motherson Reflectec |
| Murakami Corporation |
| Ichikoh Industries Ltd. |
| Milenco Limited |
| Others |
Value Network & Pricing Analysis
Captive servo-motor winding capacity in German and Chinese tier-one plants creates scale advantages that simultaneously compress component costs for integrated suppliers and erect margin floors for assembly-dependent rivals serving North American heavy-duty truck programs.
Pricing Analysis
North American fleet procurement contracts trade at 15-25 percent premiums above Indian aftermarket retrofits for equivalent actuator specifications. Three-tier pricing structure across premium, standard, and economy levels separates ADAS-integrated smart mirrors from power-adjustable units and manual cable-actuated configurations. Cost compression in economy tiers is intensifying because Chinese MIIT compliance investments are disqualifying low-cost fixed-mirror suppliers. Fleet procurement managers in commercial truck segments demonstrate highest price sensitivity; German premium SUV OEMs exhibit lowest.
Supply Chain Analysis
Germany and China anchor electromechanical actuator production for OEM programs, while South Korea concentrates polyamide 66 and PBT compounding for mirror housings. The supply chain draws from rare-earth magnet feedstock concentrated in Chinese spot markets, precision geartrain components from Japanese specialists, and glass substrates with anti-glare coatings from European optical manufacturers. Single-source vulnerability in neodymium and dysprosium procurement exposes servo-motor manufacturers to commodity price volatility. Distribution runs through tier-one system integrators delivering complete mirror assemblies directly to vehicle manufacturer plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house servo-motor design expertise has become the scarcest capability in mirror system supply, separating full-system suppliers from assembly-dependent competitors and determining long-term contract viability with German and Chinese OEMs.
For Market Incumbents: Consolidate approved vendor list positions by backward integration into brushless DC servo-motor winding capabilities and captive magnet fabrication. Defend against camera-replacement substitution by accelerating dual-architecture platform investments that preserve mirror-to-camera mounting reversibility. Prioritize ECE 46 homologation pre-certification to compress timeline disadvantages from KBA backlog. For New Entrants and Emerging Players: Lead with cost-competitive electric actuator sourcing for India's underpenetrated commercial vehicle aftermarket as BIS safety norms tighten fleet retrofit requirements. Target Brazilian agricultural and mining truck segments where ANVISA tax credits stimulate demand and hydraulic actuation specialization creates defensible positioning. Pursue white-label manufacturing arrangements with tier-one system integrators seeking geographic capacity diversification. For Investors and Strategic Acquirers: Electromechanical specialists with captive winding and encoder integration capabilities represent the highest-conviction acquisition archetype for portfolio exposure to ADAS convergence trends. Long-term viability hinges on regulatory permanence of physical mirror requirements against camera-replacement permissibility debates in Brussels and Washington. Monitor NHTSA and ECE regulatory divergence announcements as the primary inflection signal for platform engineering commitment levels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo-Motor Production | Captive winding and magnet fabrication capabilities secure OEM approved vendor list positions against assembly-dependent rivals. |
| Dual-Architecture Platform Development | Reversible mirror-to-camera mounting systems preserve optionality amid ECE 46 revision uncertainty in European regulatory forums. |
| Smart Mirror ADAS Convergence Investment | Integration of blind-spot displays and 360-degree camera feeds opens premium pricing tiers with Stuttgart and Munich engineering centers. |
| Geographic Manufacturing Footprint Expansion | Maharashtra and Tamil Nadu production corridors capture India aftermarket volume as BIS norms stimulate fleet retrofit demand. |
| Long-Term Supply Agreement with Rare-Earth Processors | Fixed-price neodymium and dysprosium contracts hedge Chinese spot market volatility compressing European actuator margins. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aftermarket fleet managers, and electromechanical R&D specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 111 filings, MIIT GB standards documentation, ECE Regulation 46 technical appendices, and vehicle production databases. Bottom-up actuator shipment modeling triangulated against top-down OEM content-per-vehicle estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including actuation method, end-user procurement channel, housing material composition, and technology integration tier. CAGRs were derived from regression analysis of historical shipment trajectories and OEM specification trend projections. Industry-specific forecast inputs incorporated regulatory mandate implementation timelines and fleet replacement cycle patterns.
The analysis sits within stated boundaries; outcomes outside sustained physical mirror retention requirements or accelerated camera-replacement permissibility would require recalibration. Forecasts reflect assumptions regarding MIIT enforcement continuity, rare-earth price band stability, and KBA homologation throughput recovery. Recalibration cycles align with material shifts in regulatory divergence announcements and electromechanical engineering labor market conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market