
 Automotive Display Market | 2026-2036
Automotive Display Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Display Market Analysis
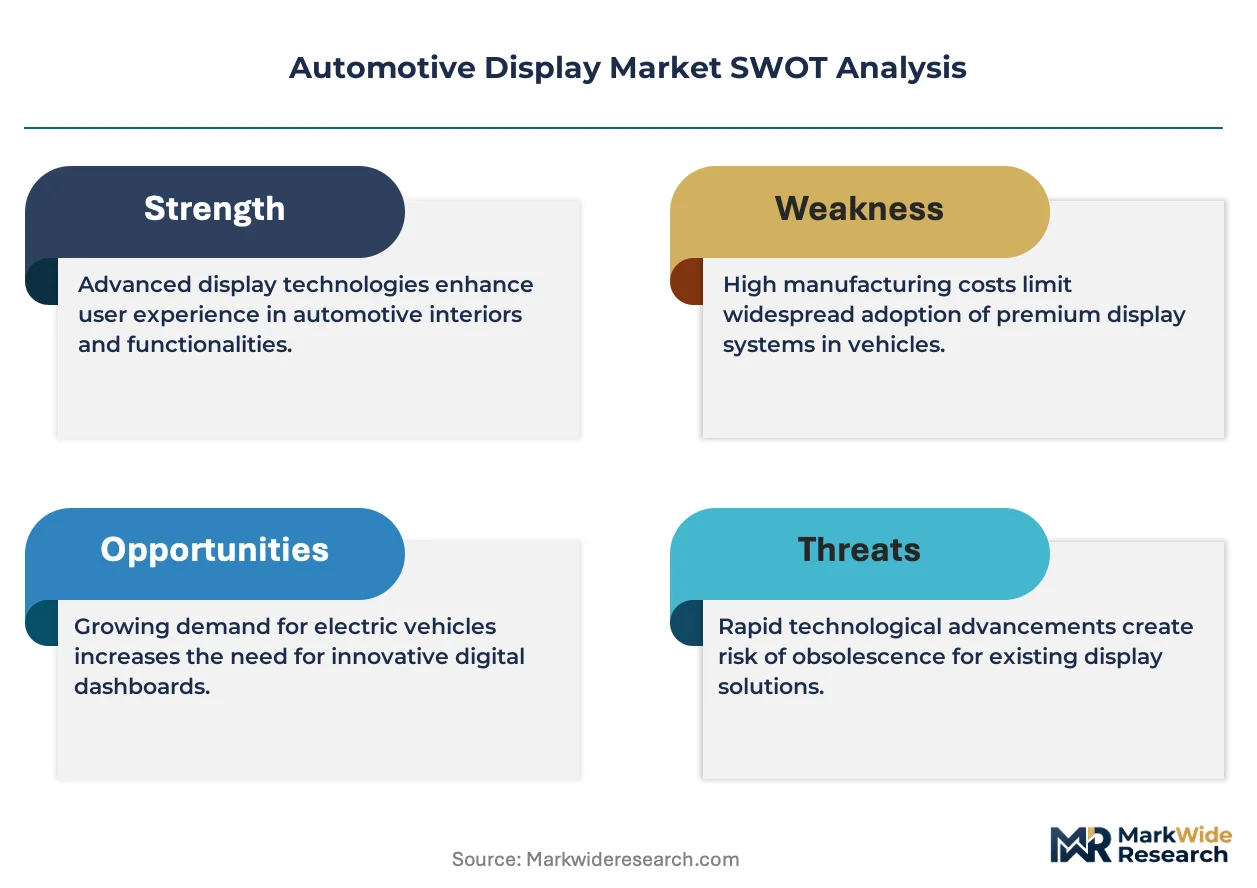
High-resolution OLED specification tiers is collapsing into mid-range vehicle trims faster than supplier roadmaps anticipated. Continental AG leverages captive semiconductor partnerships to secure display driver supply. Robert Bosch GmbH anchors European OEM relationships through integrated cockpit domain controllers. Samsung Display dominates premium OLED panel shipments to luxury marques.
Automotive displays encompass electro-optical panels engineered for operation across temperature extremes from negative forty to positive eighty-five degrees Celsius, with luminance exceeding one thousand candela per square meter for sunlight readability, serving as the primary human-machine interface between vehicle systems and occupants. Center stack monitors generate the largest revenue pool among product types due to their ubiquity across trim levels and expanding screen diagonal trends. OLED technology captures the fastest expansion trajectory as AMOLED burn-in mitigation and flexible substrate manufacturing mature for curved instrument cluster applications. TFT LCD sustains volume leadership in economy and fleet segments where cost sensitivity outweighs contrast ratio demands.
NHTSA guidelines on driver distraction limit manual task completion time during vehicle motion, directly shaping menu architecture and touch target sizing requirements. EU safety ratings through Euro NCAP incorporate human-machine interface assessment criteria that penalize complex multi-layer menu structures. REACH substance restrictions and RoHS compliance constrain backlight phosphor and solder material selection across the supply base. Stakeholders must monitor divergence between regional distraction protocols and emerging augmented reality head-up display field-of-view standards to align R&D allocation with enforceable compliance timelines.
Market Dynamics
Automotive display procurement is concentrating around cockpit domain consolidation, where single silicon platforms now drive instrument clusters, center stacks, and passenger entertainment screens through unified software layers.
Growth Catalysts
- NHTSA Distraction Protocols:Strict manual-task time limits during vehicle motion are forcing OEMs to redesign human-machine interfaces with simplified menu architectures and larger touch targets. This regulatory pressure accelerates hardware refresh cycles.
- OLED Flexible Substrates:Curved instrument cluster applications now deploy bendable AMOLED panels that conform to dashboard topography, enabling differentiated cabin aesthetics across premium marques.
- Electric Vehicle Cabin Differentiation:Battery-electric OEMs exploit expanded screen real estate as a primary competitive vector against legacy powertrain architectures, prioritizing digital experience over mechanical heritage.
Market Restraints
- Driver IC Supply Concentration:Display driver semiconductor fabrication concentrates in Taiwan and South Korea, creating single-source vulnerability for tier-1 module integrators during foundry allocation constraints.
- RoHS Phosphor Restrictions:REACH substance limitations constrain backlight phosphor chemistry selection, forcing reformulation of quantum dot enhancement films and raising qualification timelines.
- TFT LCD Substitution Pressure:Economy and fleet segments resist OLED migration due to cost sensitivity, locking volume share in mature liquid crystal technology with inferior contrast ratios.
Strategic Opportunities
- Augmented Reality HUD Field-of-View:Windshield-projected navigation and hazard alerts represent underexploited display surface area, with optics miniaturization enabling larger virtual image sizes without dashboard intrusion.
- Rear-Seat Entertainment Integration:Ceiling-mounted and seatback OLED deployments in luxury electric SUVs create incremental panel demand per vehicle beyond front-cockpit configurations.
- Euro NCAP HMI Scoring:Safety rating incentives for intuitive interface design reward early compliance investment, creating competitive advantage for suppliers with pre-certified menu architectures.
Industry Challenges
- Automotive-Grade Software Talent Scarcity:Embedded graphics pipeline engineering for safety-critical operating systems commands premium compensation, constraining tier-1 hiring velocity.
- Multi-Modal Input Integration:Synchronizing touch, voice, and gesture recognition across heterogeneous sensor fusion stacks demands systems integration capabilities absent from traditional display panel vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Display Market |
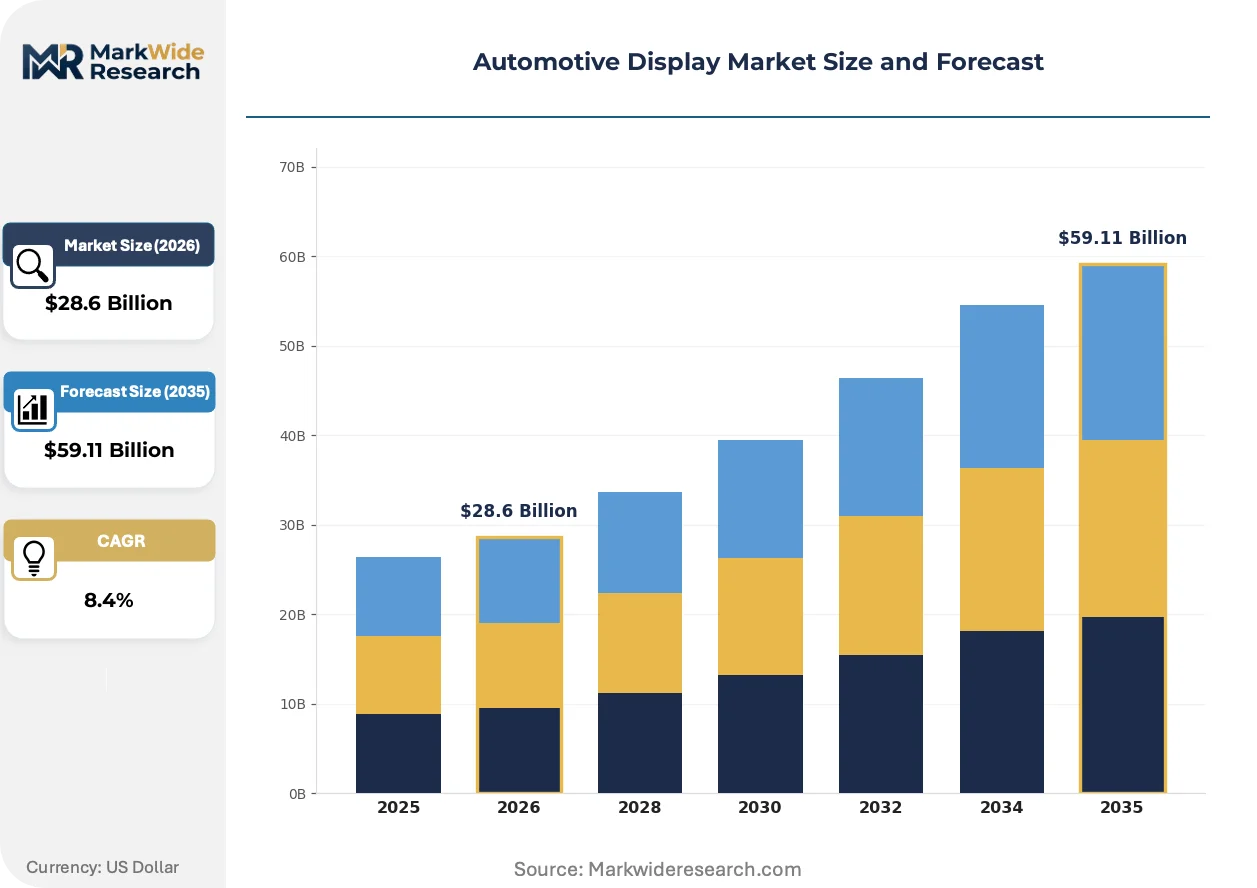
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instrument Cluster, Head-Up Display, Center Stack Monitor, Rear-Seat Entertainment Technology: LCD, OLED, AMOLED, TFT End User: OEMs, Tier-1 Suppliers, Dealerships, Aftermarket Providers Installation: In-Vehicle, Aftermarket, Integrated, Standalone |
| Companies Covered | Continental AG, Visteon Corporation, Samsung Display, AUO Corporation, Robert Bosch GmbH, LG Display, Denso Corporation, Tianma, BOE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Display Market Emerging Trajectories
Display technology trajectories in automotive are compressing specification tiers downward while expanding functional integration upward, collapsing the historical boundary between premium and mass-market feature availability.
Local dimming mini-LED backlights are displacing conventional edge-lit TFT LCD modules in upper-mid vehicle trims. Tier-1 suppliers now specify thousands of dimming zones for high dynamic range video playback. This backlight architecture is displacing full-array LED designs that previously anchored premium segment differentiation.
REACH substance restrictions and RoHS compliance directives from ECHA are reshaping solder alloy selection and phosphor chemistry across European-bound production. Module assemblers must maintain dual material sets for EU versus non-EU vehicle programs. Display driver PCB fabrication for Germany-destined clusters now segregates tin-bismuth formulations from legacy tin-lead alternatives.
Electric vehicle startups are compressing supplier qualification timelines from 36 months toward 18 months through parallel validation protocols. Traditional tier-1 relationships with Stuttgart and Wolfsburg incumbents face disruption from direct procurement by California and Shanghai OEMs. This procurement velocity shift concentrates engineering resources in China, Germany, and the United States.
Automotive Display Market Segmentation
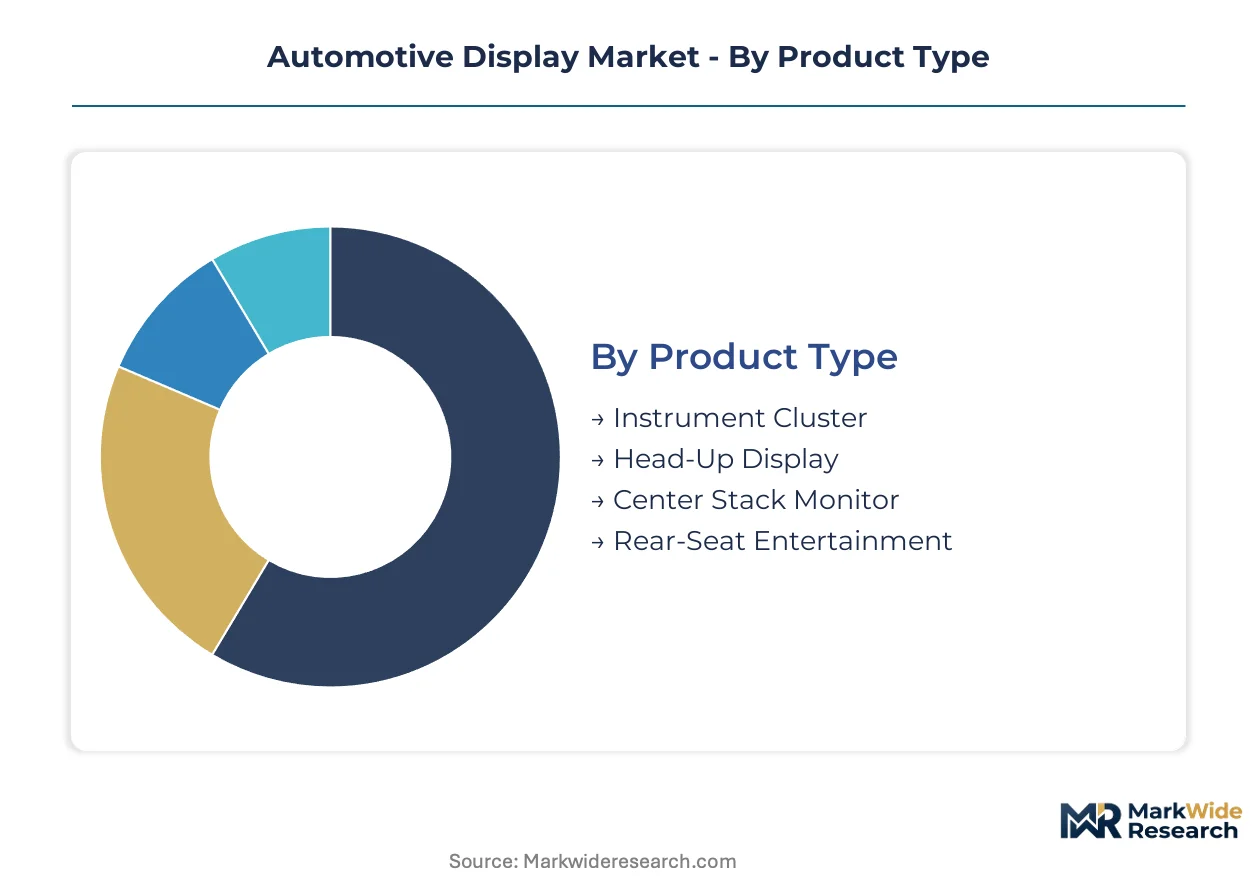
Automotive display procurement decisions cascade across four distinct segmentation axes, each carrying different margin profiles and technical qualification barriers. Tier-1 module integrators must align inventory strategies with the diverging lifecycle rhythms of infotainment hardware versus safety-critical cluster systems.
Product Type:
Substitution pressure from smartphone mirroring and voice interfaces threatens standalone display categories most exposed to consumer electronics convergence.
- Center Stack Monitor:These touch-enabled panels dominate cockpit surface area with diagonal expansions exceeding fifteen inches in electric vehicle architectures. Demand concentrates in China and Germany where NIO, BYD, and BMW prioritize screen-centric cabin differentiation over traditional control surfaces.
- Instrument Cluster:Digital gauge replacements for analog dials require ASIL-B functional safety certification and negative forty-degree Celsius cold-start reliability. European OEMs in Stuttgart and Wolfsburg drive specification tightening through integrated cockpit domain consolidation.
- Head-Up Display:Windshield projection systems with augmented reality navigation overlays.
- Rear-Seat Entertainment:Ceiling-mounted and seatback OLED deployments in luxury electric SUVs.
Center Stack Monitor retains volume leadership; Instrument Cluster holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium vehicle programs willing to absorb OLED panel premiums from fleet operators demanding TFT LCD economics.
- OLED:Self-emissive organic compounds eliminate backlight assemblies, enabling sub-millimeter thickness and true black states. Samsung Display anchors supply to luxury marques in Germany and California, with burn-in mitigation algorithms now qualifying for ten-year automotive lifecycles.
- AMOLED:Active-matrix addressing enables flexible substrate bending for curved instrument cluster topography. Korean panel fabs concentrate capacity expansion here as Chinese OEMs accelerate adoption into mid-range electric vehicle trims faster than supplier roadmaps projected.
- LCD:Mature liquid crystal volume production with edge-lit LED backlights.
- TFT:Thin-film transistor active addressing for economy segment cost floors.
TFT sustains volume leadership across fleet and economy segments; AMOLED climbs the fastest as flexible substrate manufacturing scales.
End User:
Customer type determines qualification timeline intensity, with direct OEM procurement compressing traditional tier-1 validation windows.
- OEMs:Volkswagen, General Motors, and Tesla increasingly bypass tier-1 integrators for direct panel procurement, forcing module suppliers to defend value-add through software integration and thermal management expertise.
- Tier-1 Suppliers:Continental AG and Robert Bosch GmbH anchor European relationships through cockpit domain controller integration.
- Dealerships:Retrofit upgrade programs for infotainment system refreshes.
- Aftermarket Providers:Third-party head unit replacements and accessory displays.
OEM direct procurement is gaining share fastest; Tier-1 Suppliers retain the deepest technical integration relationships.
Installation:
Application architecture separates factory-integrated systems with vehicle-network dependency from standalone units with independent compute.
- In-Vehicle:Factory-installed displays hardwired to CAN and Ethernet backbone networks with cybersecurity authentication.
- Integrated:Multi-screen domain controller architectures sharing silicon and software layers across cluster, center stack, and passenger screens.
- Aftermarket:Dealer or third-party retrofit installations requiring compatibility with legacy vehicle electrical systems.
- Standalone:Portable or accessory displays with independent power and processing.
Integrated installations are expanding most quickly with cockpit domain consolidation; In-Vehicle factory fitment retains absolute volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panel fabrication and module integration concentrate in East Asian foundry clusters and German automotive engineering corridors. Display driver semiconductor output dominates Taiwan and South Korea. Final assembly of cockpit systems clusters around Stuttgart, Wolfsburg, and Shanghai-OEM technical centers.
China
NIO, BYD, and XPeng compress supplier qualification timelines from 36 months toward 18 months through parallel validation protocols. MIIT mandates cybersecurity authentication for in-vehicle displays under GB standards. The Yangtze River Delta around Shanghai anchors panel procurement volume for domestic electric vehicle OEMs expanding screen real estate across instrument clusters.
Germany
Volkswagen, BMW, and Mercedes-Benz drive specification tightening for integrated cockpit domain controllers. KBA enforces type approval for human-machine interface designs under EU safety rating frameworks. Stuttgart and Wolfsburg engineering centers concentrate tier-1 supplier relationships for ASIL-B certified instrument cluster systems.
United States
Tesla and Rivian prioritize direct panel procurement, bypassing traditional tier-1 integrators for center stack and instrument cluster displays. NHTSA distraction guidelines limit manual task completion time during vehicle motion, shaping menu architecture requirements. California and Michigan technical centers concentrate EV startup engineering activity for curved AMOLED cluster applications.
South Korea
Samsung Display and LG Display anchor premium OLED panel shipments to luxury marques in Germany and California. MFDS oversight applies to automotive-grade component exports under bilateral trade frameworks. Korean panel fabs concentrate capacity expansion for flexible substrate manufacturing serving curved instrument cluster topography.
Japan
Denso Corporation and other tier-1 suppliers maintain deep technical integration relationships with Toyota and Honda for integrated cockpit architectures. METI promotes domestic semiconductor supply chain resilience through subsidy programs for display driver fabrication. Nagoya and Tokyo engineering corridors concentrate embedded graphics pipeline engineering talent for safety-critical operating systems.
Automotive Display Market Vendor Landscape
Concentration sits with diversified automotive electronics conglomerates and specialized display panel manufacturers. The vendor base separates into tier-1 module integrators with cockpit domain expertise and pure-play panel suppliers with captive semiconductor partnerships. Three archetypes dominate: integrated cockpit system providers, OLED panel specialists with automotive qualification, and diversified electronics conglomerates with backward integration into display drivers. Competitive moves center on cockpit domain consolidation through unified software layers and strategic partnerships to secure foundry allocation.
Among diversified automotive electronics conglomerates, Continental AG and Robert Bosch GmbH exemplify integrated cockpit system providers anchoring European OEM relationships. Samsung Display occupies a position within the OLED panel specialist tier, representing premium display supply to luxury marques. These three companies sit within distinct competitive vectors—module integration, domain controller software, and panel manufacturing—each defending value-add through different technical barriers.
| Leading Market Players |
|---|
| Continental AG |
| Visteon Corporation |
| Samsung Display |
| AUO Corporation |
| Robert Bosch GmbH |
| LG Display |
| Denso Corporation |
| Tianma |
| BOE |
| Others |
Supply Flow & Price Mechanics
Mini-LED backlight substitution for conventional edge-lit TFT LCD modules is redrawing procurement geography toward Taiwan and South Korea while compressing margin structures across upper-mid vehicle trims. This technology displacement simultaneously concentrates premium panel sourcing in Korean fabs and forces European tier-1 integrators to absorb qualification cost premiums for dual material sets under REACH substance restrictions.
Pricing Analysis
EU REACH and RoHS substance restrictions dictate the pricing tier structure across European-bound production, segregating compliant solder alloys and phosphor chemistries into premium-qualified brackets. Three-tier pricing structure across premium OLED, standard mini-LED, and economy TFT LCD levels separates luxury marques from fleet operators, with certification-grade differentiation commanding substantial premiums. Pricing pressure stems from Chinese OEM procurement velocity compressing traditional 36-month qualification windows toward 18 months, forcing accelerated amortization of validation investments. Fleet and economy segments exhibit highest price sensitivity, locking volume share in mature liquid crystal technology despite inferior contrast performance.
Supply Chain Analysis
Inventory lead times for display driver integrated circuits now stretch substantially beyond historical automotive norms, creating allocation vulnerability for tier-1 module integrators. Semiconductor fabrication concentrates in Taiwan and South Korea, with foundry output feeding module assembly clusters in Germany, China, and the United States. Raw material dependencies span indium tin oxide for transparent electrodes, rare-earth phosphors for backlight enhancement, and specialized glass substrates for thermal stability. Single-source vulnerability in driver IC supply represents the dominant structural risk, with downstream distribution running through cockpit domain controller integrators anchoring OEM relationships in Stuttgart, Wolfsburg, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive display procurement is experiencing high-growth disruption as electric vehicle OEMs exploit expanded screen real estate for cabin differentiation, with NHTSA distraction protocols and EU safety ratings tightening compliance requirements that accelerate hardware refresh cycles.
For Market Incumbents: Shield established European OEM relationships through accelerated cockpit domain controller integration and preemptive ASIL-B certification investment for instrument cluster systems. Defensive consolidation around captive semiconductor partnerships mitigates foundry allocation vulnerability from Taiwan and South Korea concentration. Vertical integration into display driver supply secures allocation priority during capacity constraints. For New Entrants and Emerging Players: Anchor in rear-seat entertainment integration for luxury electric SUVs, where ceiling-mounted and seatback OLED deployments create incremental panel demand beyond front-cockpit saturation. The augmented reality head-up display segment offers penetrable white-space with optics miniaturization enabling larger virtual image sizes. Direct procurement relationships with California and Shanghai EV startups bypass entrenched tier-1 gatekeeping. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors panel specialists with automotive-grade burn-in mitigation and flexible substrate capabilities. Long-term viability over the next decade rests on differentiation through software-defined cockpit architectures rather than commodity panel supply. Watch Euro NCAP HMI scoring adoption as the signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cockpit Domain Consolidation | Unified silicon platforms reduce hardware complexity for Stuttgart and Wolfsburg OEMs. |
| Flexible Substrate Capacity Expansion | Korean fabs scale bendable AMOLED output for curved instrument cluster topography. |
| Display Driver Supply Agreement | Captive semiconductor partnerships secure allocation priority during foundry constraints. |
| Software-Defined Vehicle Investment | Integrated graphics pipelines differentiate tier-1 suppliers beyond commodity panel supply. |
| Rear-Seat Entertainment Integration | Ceiling-mounted OLED deployments capture incremental content-per-vehicle expansion. |
Methodological Framework
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement leads, display panel manufacturing executives, and automotive semiconductor specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from diversified electronics conglomerates, and regulatory submission records from NHTSA and KBA. Bottom-up triangulation across panel shipment volumes and top-down reconciliation against OEM platform deployment schedules anchored the analytical framework.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against electric vehicle adoption curves and regulatory compliance timelines. Industry-specific forecast inputs incorporate NHTSA distraction protocol implementation schedules and Euro NCAP HMI scoring adoption trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained electric vehicle penetration and stable foundry allocation for automotive-grade semiconductors; material deviation in battery-electric adoption rates or trade policy shifts would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Floor Carpet Market